
 Stair Lift Motors Market | 2026-2036
Stair Lift Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Stair Lift Motors Market Analytics
European motor suppliers is realigning production footprints to serve stair lift OEMs with shorter lead times. Stannah Lifts Holdings Ltd. leverages its British manufacturing heritage to dominate premium residential channels across Western Europe. Bruno Independent Living Aids Inc. anchors its competitive position through deep vertical integration in DC motor assembly for straight-rail systems. TK Elevator GmbH competes on industrial-scale output, supplying gear motor platforms to both in-house lift divisions and third-party assemblers.
Stair lift motors are electromechanical drive units engineered to deliver controlled torque output between 0.25 kW and 1.5 kW, typically incorporating permanent magnet DC or brushless AC architectures with integrated planetary gear reduction for low-speed high-torque operation. These motors power rack-and-pinion or worm-drive traction systems that move seated platforms along inclined rail profiles at speeds regulated to 0.15 m/s for passenger safety. DC motors lead the type category due to their superior variable-speed control and battery-backup compatibility in residential settings, while gear motors capture the margin pool through integrated encoder feedback systems that reduce installation complexity. Electric technology dominates the technology split, though digital motor controls with CAN bus diagnostics represent the fastest-expanding subsegment as facility managers demand predictive maintenance capabilities.
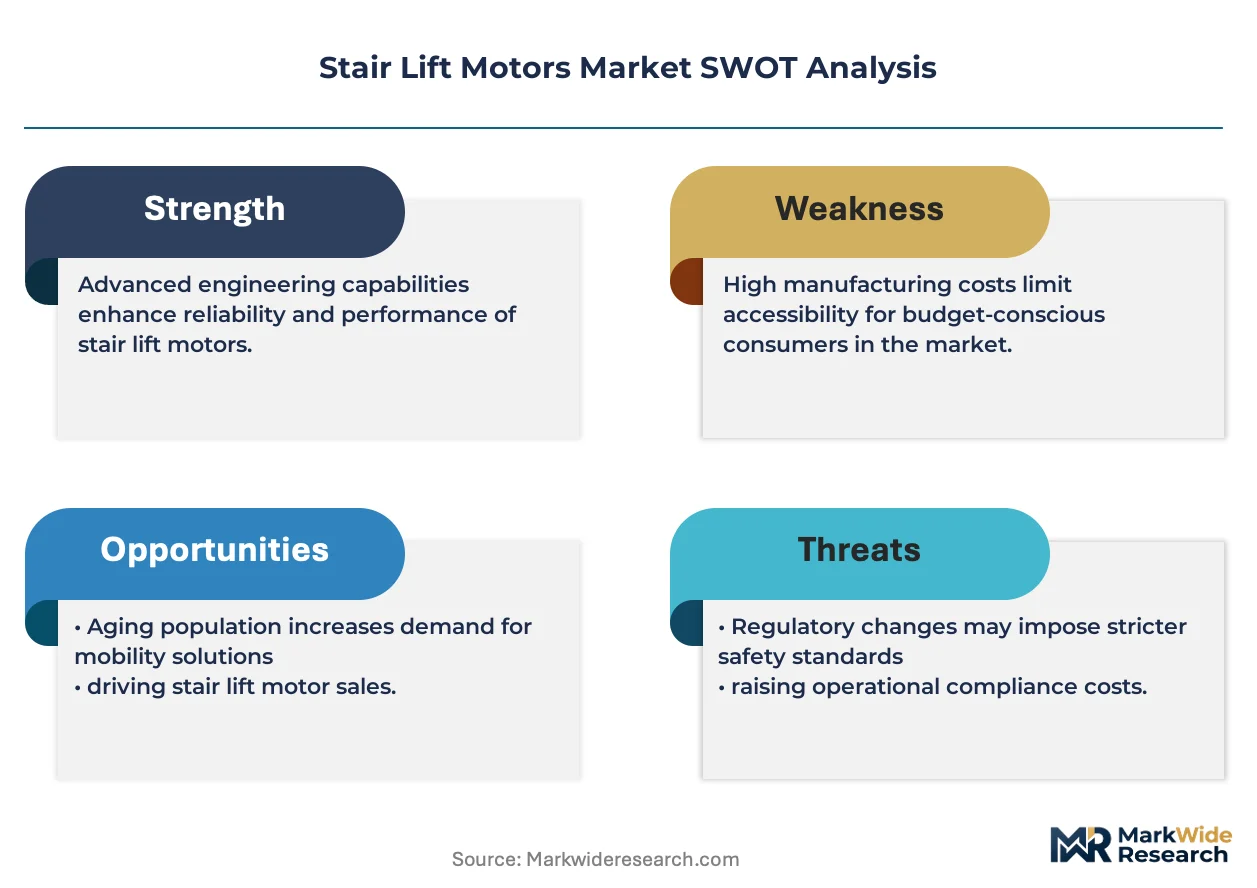
The EU Machinery Directive and CE marking framework mandate redundant braking systems and electromagnetic compatibility testing for stair lift motors sold across member states, effectively raising engineering barriers for non-compliant suppliers. The US FDA classifies certain clinical stair lift installations as medical devices, requiring 510(k) clearance for motors used in healthcare facility transfers and shaping procurement protocols among hospital contractors. Stakeholders must monitor evolving accessibility mandates from national building regulators and decide whether to certify motor platforms for multi-jurisdiction deployment or specialize in single-market compliance architectures.
Market Dynamics
Permanent magnet DC motor architectures are displacing brushed alternatives as stair lift OEMs prioritize battery-backup compatibility and regenerative braking efficiency in residential installations. This technology transition concentrates procurement power among suppliers with captive rare-earth magnet sourcing.
Growth Catalysts
- Aging-in-place infrastructure mandates:Germany's federal states are expanding accessibility retrofit subsidies for multi-generational housing, directly stimulating motor demand from domestic stair lift assemblers.
- EU Machinery Directive compliance:CE marking requirements for redundant braking and electromagnetic compatibility are filtering out non-compliant motor suppliers, consolidating volume with certified manufacturers.
- Brushless AC platform adoption:Healthcare facility operators in Japan are specifying maintenance-free motor architectures for high-cycle institutional installations, accelerating technology substitution.
Market Restraints
- Neodymium price volatility:Permanent magnet supply concentration in Chinese processing facilities exposes motor cost structures to rare-earth export quota fluctuations.
- Precision gear manufacturing bottleneck:Planetary gear reduction components rely on a concentrated supplier base in Baden-Württemberg, creating single-source vulnerability for torque-dense motor assemblies.
- FDA 510(k) clearance timelines:Clinical stair lift motor classifications in the US impose 12-18 month certification delays that deter rapid product iteration.
Strategic Opportunities
- India accessibility retrofit wave:Urban metro systems and aging housing stock in Mumbai and Delhi present untapped demand for cost-optimized DC motor platforms.
- Predictive maintenance convergence:CAN bus diagnostic integration with IoT telemetry platforms enables service-contract revenue migration for motor suppliers.
- Japan's metropolitan elderly care clusters:Tokyo and Osaka prefecture density supports shared-service stair lift models with standardized motor specifications.
Industry Challenges
- Electromagnetic compatibility testing capacity:Third-party certification laboratory queues in the EU extend product launch timelines for multi-jurisdiction motor platforms.
- Legacy rack-and-pinion integration:Existing installed rail infrastructure constrains motor form-factor innovation, forcing backward-compatible design compromises.
- Encoder calibration skill scarcity:Precision gear motor assembly requires specialized technician training that outpaces vocational program output in Eastern European manufacturing zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stair Lift Motors Market |
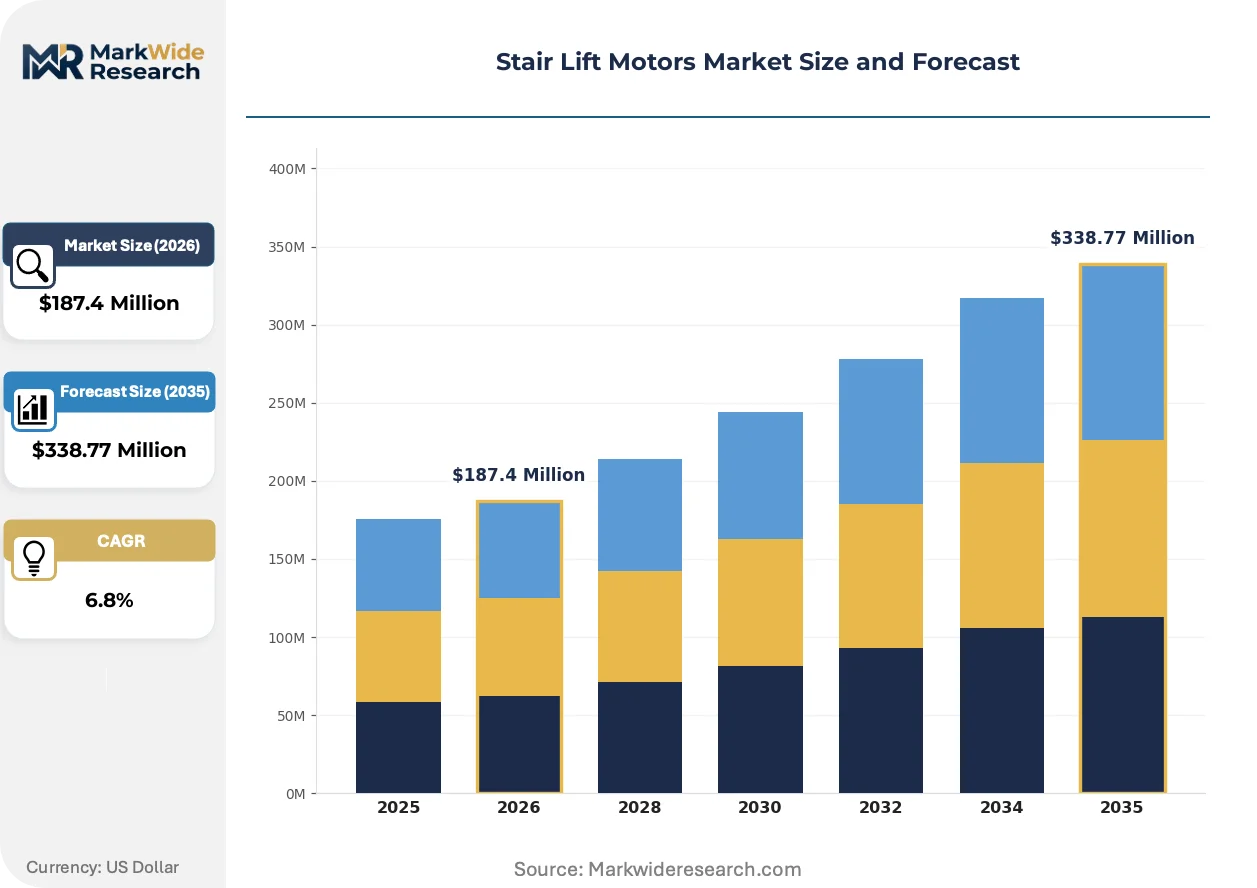
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: AC Motors, DC Motors, Gear Motors, Linear Motors Technology: Hydraulic, Electric, Mechanical, Digital Application: Residential, Commercial, Healthcare, Public Transit End User: Homeowners, Facility Managers, Contractors, Caregivers |
| Companies Covered | Stannah Lifts Holdings Ltd., Lifeway Mobility, Bruno Independent Living Aids Inc., Leaf Home Stair Lifts, Handicare, Acorn Stairlifts Inc., Savaria Corp., TK Elevator GmbH, Harmar Mobility LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stair Lift Motors Market Evolving Landscape
Digital motor control architectures are compressing the traditional divide between electromechanical hardware and predictive software systems. This convergence is redefining supplier value capture and installation economics across residential and institutional channels.
Sensorless vector control technology is integrating real-time torque estimation algorithms that eliminate physical encoder hardware. Facility management contractors in German hospital networks are specifying these platforms for reduced maintenance intervals. The technology is integrating predictive failure analytics that compress warranty reserve requirements for motor OEMs.
REACH substance restrictions on hexavalent chromium coatings are forcing gear motor suppliers to migrate toward trivalent alternatives or physical vapor deposition finishes. Surface treatment requalification extends engineering validation cycles by 6-9 months. European stair lift assemblers are responding by consolidating procurement with suppliers that completed REACH-compliant process transitions early.
After-sales service unbundling is separating motor hardware procurement from long-term maintenance contracting. Residential dealers in North American markets are migrating toward third-party diagnostic subscriptions rather than manufacturer-captive service agreements. This pattern is most visible in Florida and Arizona retirement communities where dealer concentration supports independent service network economics.
Stair Lift Motors Market Segmentation
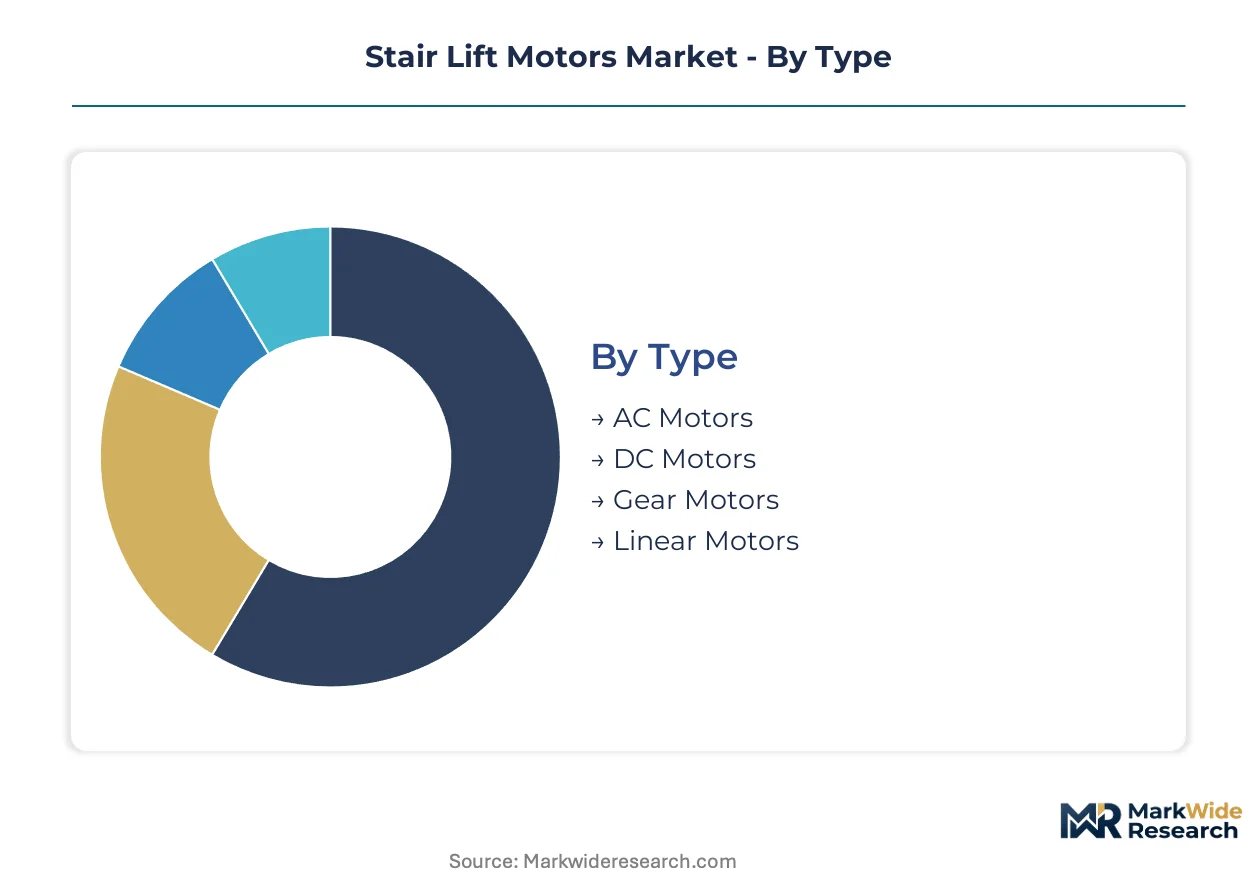
Stair lift motor procurement patterns diverge sharply across installation environments, power architectures, and buyer sophistication levels. Understanding these fault lines reveals where engineering investment concentrates and which customer segments command premium pricing.
Type:
Buyers differentiate primarily by backup power requirements and speed control precision rather than upfront hardware cost.
- DC Motors:Permanent magnet architectures deliver superior variable-speed control and seamless battery-backup integration for residential installations. Demand concentrates among German stair lift OEMs serving multi-generational housing retrofits where grid-independent operation is mandatory.
- Gear Motors:Integrated planetary reduction units with encoder feedback systems reduce field installation complexity and calibration time. Japanese metropolitan elderly care facilities specify these platforms for high-cycle institutional deployments requiring predictive maintenance telemetry.
- AC Motors:Brushless designs offer maintenance-free operation for commercial environments with dedicated maintenance staff.
- Linear Motors:Direct-drive configurations eliminate mechanical transmission components for ultra-quiet residential applications.
DC motors lead volumes today; gear motors are gaining share fastest.
Technology:
Facility operators now prioritize diagnostic connectivity over raw power density when specifying drive platforms.
- Electric:Mains-powered and battery-backed electromechanical systems dominate installed base across all application tiers. REACH compliance for surface coatings and CE marking for electromagnetic compatibility have consolidated procurement with certified European suppliers.
- Digital:CAN bus-enabled motor controllers with real-time torque estimation and predictive failure analytics represent the steepest expansion trajectory. German hospital network contractors specify these platforms to compress warranty reserve requirements and enable outcome-based service contracting.
- Hydraulic:Fluid power systems persist in heavy-duty commercial installations requiring sustained high-torque output.
- Mechanical:Spring and counterweight assist mechanisms serve cost-optimized retrofit markets with limited electrical infrastructure.
Electric platforms anchor current revenue; digital architectures are climbing the fastest.
Application:
Regulatory exposure and cycle frequency separate margin profiles across installation environments.
- Residential:Aging-in-place retrofits in owner-occupied housing demand compact, quiet motors with aesthetic rail integration. North American homeowners drive volume through accessibility tax credit programs and multi-generational living trends.
- Healthcare:Clinical transfer installations in hospitals and rehabilitation centers require FDA 510(k) cleared motors with redundant braking. Procurement concentrates among US hospital contractors facing strict liability protocols and extended certification timelines.
- Commercial:Office buildings and retail environments prioritize uptime guarantees and rapid service response.
- Public Transit:Metro and rail station accessibility retrofits specify heavy-duty gear motors for continuous-duty operation.
Residential applications dominate unit shipments; healthcare represents the fastest-growing value pool.
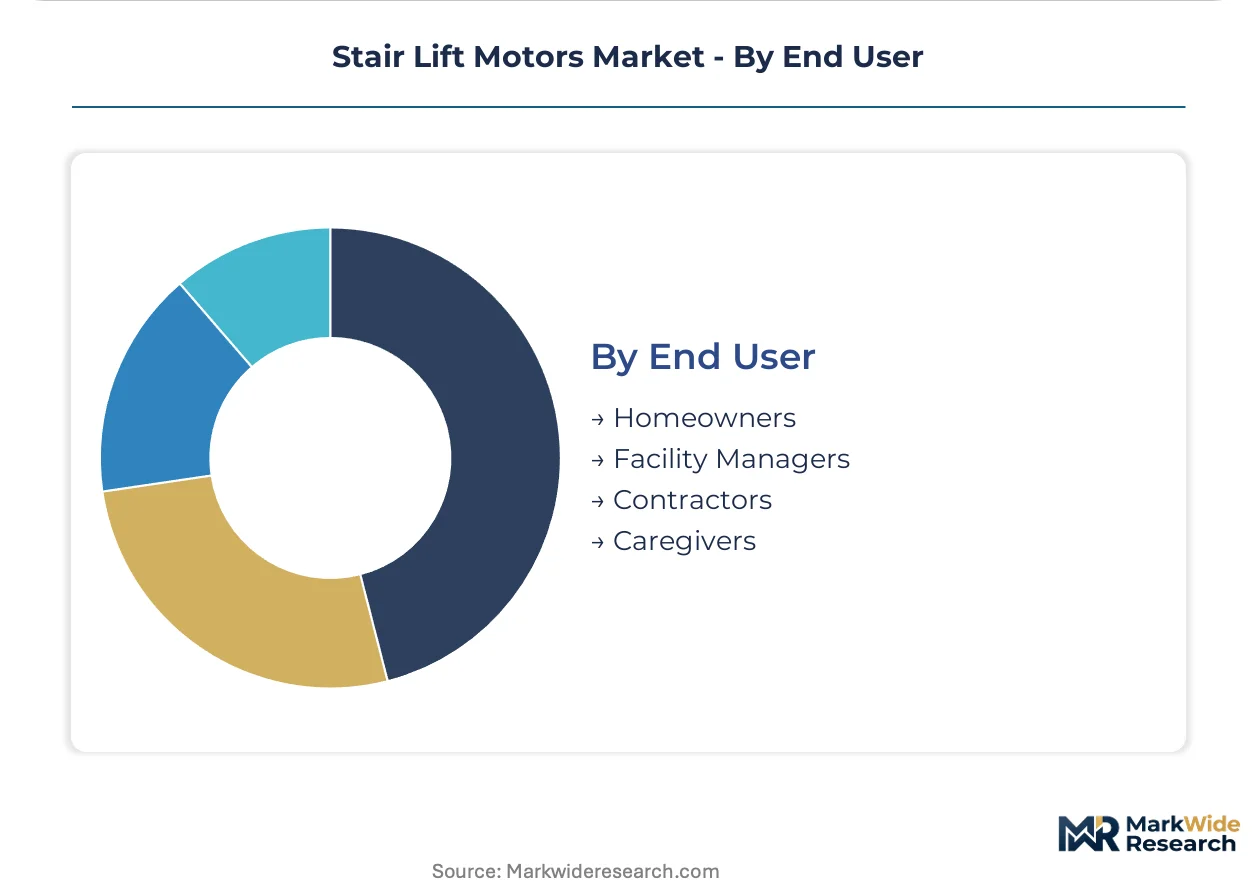
End User:
Technical sophistication and purchasing authority determine whether buyers specify integrated platforms or modular components.
- Facility Managers:Institutional procurement professionals in Japanese prefecture elderly care clusters demand standardized motor specifications across shared-service stair lift fleets. These buyers specify CAN bus diagnostics to enable centralized fleet monitoring and predictive maintenance.
- Contractors:Hospital construction and renovation specialists in the US navigate FDA 510(k) clearance requirements for clinical installations. Their procurement protocols favor motor suppliers with pre-cleared platforms to avoid project delays.
- Homeowners:Direct residential purchasers prioritize aesthetic integration and local dealer support networks.
- Caregivers:Family members and professional aides influence retrofit decisions through safety feature requirements.
Facility managers control the largest contract values; contractors are expanding procurement influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping motor production footprints. CE marking compliance costs in Western Europe push some assembly toward Eastern European facilities. Meanwhile, FDA 510(k) clearance timelines in the United States create captive demand for pre-certified suppliers.
Germany
Baden-Württemberg's precision manufacturing corridor hosts concentrated planetary gear production for torque-dense motor assemblies. The federal states' accessibility retrofit subsidies for multi-generational housing directly stimulate domestic stair lift assembler demand. REACH substance restrictions on hexavalent chromium coatings force surface treatment requalification cycles extending 6-9 months.
United States
Florida and Arizona retirement communities drive residential dealer concentration supporting independent service network economics. FDA classifies certain clinical stair lift installations as medical devices, requiring 510(k) clearance for motors used in healthcare facility transfers. Hospital contractors in these states favor pre-cleared motor platforms to avoid project delays.
Japan
Tokyo and Osaka prefecture density supports shared-service stair lift models with standardized motor specifications. METI-backed elderly care infrastructure mandates accelerate brushless AC platform adoption for maintenance-free institutional installations. Healthcare facility operators specify CAN bus diagnostics to enable centralized fleet monitoring.
India
Urban metro systems and aging housing stock in Mumbai and Delhi present untapped demand for cost-optimized DC motor platforms. The country's national accessibility regulator is expanding retrofit mandates for public infrastructure. Domestic stair lift assemblers in Maharashtra and Gujarat are localizing procurement to reduce import dependency.
United Kingdom
Stannah Lifts Holdings Ltd. leverages British manufacturing heritage to dominate premium residential channels across Western Europe. The UK's building accessibility regulations tighten compliance requirements for electromagnetic compatibility testing. Precision motor suppliers in the Midlands realign production footprints to serve stair lift OEMs with shorter lead times.
Stair Lift Motors Market Competitive Landscape
German producers anchor the precision-tier; British specialists hold premium residential positioning. The vendor base splits between consolidated industrial-scale suppliers and fragmented regional assemblers. Three archetypes dominate: vertically integrated motor manufacturers, stair lift OEMs with captive drive production, and component specialists supplying planetary gear systems. Competitive moves concentrate on REACH-compliant process transitions and predictive maintenance service-contract migration.
Within the premium-tier residential segment, Stannah Lifts Holdings Ltd. exemplifies heritage-based market positioning. Among vertically integrated fabricators, Bruno Independent Living Aids Inc. and TK Elevator GmbH occupy distinct competitive spaces—Bruno representing North American DC motor assembly specialization, TK Elevator anchoring industrial-scale gear motor platform supply to both in-house divisions and third-party assemblers.
| Leading Market Players |
|---|
| Stannah Lifts Holdings Ltd. |
| Lifeway Mobility |
| Bruno Independent Living Aids Inc. |
| Leaf Home Stair Lifts |
| Handicare |
| Acorn Stairlifts Inc. |
| Savaria Corp. |
| TK Elevator GmbH |
| Harmar Mobility LLC |
| Others |
Value Network & Pricing Analysis
Neodymium price index volatility cascades through permanent magnet DC motor cost structures, compressing margins for tier-two assemblers while concentrating pricing power with suppliers holding captive rare-earth sourcing. REACH-compliant surface treatment transitions add six to nine months to supplier qualification cycles, forcing stair lift OEMs toward early-adopter certification partners.
Pricing Analysis
Distributor margin layers absorb roughly one-third of final installed cost in residential channels, while direct-to-OEM procurement secures volume discounts for institutional fleet buyers. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked precision gear motors from basic DC platforms and unbranded Asian imports. Cost compression in economy tiers intensifies because of neodymium supply concentration and REACH requalification overhead. Homeowners in North American retirement communities exhibit highest price sensitivity, whereas Japanese prefecture facility managers prioritize predictive maintenance telemetry over upfront hardware cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from TK Elevator and Stannah, while specialized distributors serve fragmented regional assemblers. Manufacturing gravity centers on Germany's Baden-Württemberg precision corridor for planetary gear reduction, China's rare-earth processing belt for permanent magnet feedstock, and Japan's Nagoya industrial zone for brushless AC controller integration. Planetary gear housings, neodymium-iron-boron magnets, and encoder sensor modules constitute critical input dependencies. Single-source vulnerability in Baden-Württemberg precision machining capacity exposes torque-dense motor assemblies to regional supply disruption. Distribution runs through authorized dealer networks for residential retrofit and GPO-contracted channels for healthcare institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stair lift motors market functions as a regulatory compounder where EU Machinery Directive enforcement and FDA 510(k) clearance requirements continuously raise engineering barriers and consolidate procurement with certified suppliers.
For Market Incumbents: Extend predictive maintenance service-contract coverage to capture recurring revenue streams as hardware margins compress. Deepen backward integration into rare-earth magnet sourcing to insulate cost structures from Chinese export quota fluctuations. Prioritize REACH-compliant surface treatment process transitions ahead of competitor requalification cycles to lock in OEM procurement relationships. For New Entrants and Emerging Players: The mid-tier price-point gap between premium German gear motors and economy DC platforms offers viable entry space for cost-optimized brushless architectures. India's urban metro accessibility retrofit wave presents the most penetrable geography, with Mumbai and Delhi housing stock generating unserved demand for battery-backup compatible systems. Pursue white-label supply partnerships with domestic Indian assemblers to bypass import duty exposure and establish local manufacturing credibility. For Investors and Strategic Acquirers: Asymmetric upside sits with sensorless vector control technology specialists possessing predictive analytics software stacks. Long-term viability over the next decade hinges on regulatory certification moats rather than manufacturing scale alone. Acquisition targets should demonstrate completed CE marking and FDA 510(k) clearance for multi-jurisdiction deployment. Monitor encoder calibration technician training program expansion in Eastern European manufacturing zones as an inflection indicator for supply-constrained gear motor assembly capacity.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Surface Treatment Transition | Early process requalification locks in OEM procurement ahead of competitor compliance cycles. |
| CAN Bus Diagnostic Platform Integration | Predictive maintenance telemetry enables outcome-based service contracting with Japanese prefecture facilities. |
| Rare-Earth Magnet Backward Integration | Captive neodymium sourcing insulates margin structures from Chinese export quota volatility. |
| India Localized Assembly Partnership | Domestic manufacturing access reduces import dependency for Mumbai and Delhi metro retrofit demand. |
| FDA 510(k) Pre-Clearance Investment | Pre-cleared motor platforms accelerate procurement cycles with US hospital construction contractors. |
Research Methodology
Direct dialogue with stair lift OEM procurement directors, planetary gear manufacturing engineers, facility management contractors in German hospital networks, and encoder calibration technicians anchored qualitative insight development. Secondary validation drew from EU Machinery Directive compliance databases, FDA 510(k) clearance filings, REACH substance restriction updates, and Japanese METI elderly care infrastructure mandate documentation. Bottom-up motor shipment estimates triangulated against top-down stair lift installation forecasts across residential, healthcare, and commercial application tiers.
Segmented projections by motor type, technology architecture, installation environment, and end-user sophistication generated volume and value trajectories across the analysis window. Modeled dimensions included DC versus AC versus gear motor platform splits, electric versus digital control technology adoption curves, and residential versus healthcare versus commercial application penetration rates. CAGRs emerged from installed base growth assumptions, replacement cycle dynamics, and regulatory-driven retrofit acceleration in multi-generational housing markets.
Caveats apply where neodymium price shocks, REACH enforcement delays, or FDA clearance timeline extensions could materially shift the outlook for supplier consolidation and technology substitution patterns. Periodic stress-testing of base assumptions against rare-earth export policy developments and electromagnetic compatibility laboratory capacity constraints is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Europe Electric Power Steering Market
Automotive Electrical & Electronics
Car Satellite Antenna Market
Automotive Electrical & Electronics
X-By-Wire Systems Market
Automotive Electrical & Electronics
Commercial Vehicle Switches and Relays Market
Automotive Electrical & Electronics
Automotive Pressure Sensors Market
Automotive Electrical & Electronics
Automotive Inverter Busbar Laminates Market
Automotive Electrical & Electronics
Automotive Emission Sensors Market
Automotive Electrical & Electronics
Japan X by Wire Systems Market
Automotive Electrical & Electronics
EPS Motors Market
Automotive Electrical & Electronics
Global Automotive on Board AC-DC Power Inverters Market
Automotive Electrical & Electronics
Automotive Electronics Control Unit Management (ECU/ECM) Market
Automotive Electrical & Electronics
Automotive Alternator and Starter Motor Market
Automotive Electrical & Electronics
Wire Harness Market
Automotive Electrical & Electronics
Automotive E-Compressor Market
Automotive Electrical & Electronics
Automotive PCB Market
Automotive Electrical & Electronics
Automotive Electronic Expansion Valve Market