
 Automotive Airbag Electronic Control Unit Market | 2026-2036
Automotive Airbag Electronic Control Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Airbag Electronic Control Unit Market Insights
Over-the-air calibration subscriptions for airbag ECUs is recalibrating what suppliers monetize beyond hardware shipments. Robert Bosch leverages its semiconductor division to anchor in-house sensor-to-ECU integration. Continental AG competes through electromechanical platform standardization across multiple OEM programs. Autoliv differentiates by controlling crash-test data loops that feed adaptive algorithm development.
An automotive airbag electronic control unit is a microprocessor-based module that processes collision signals from accelerometers and pressure sensors within milliseconds to trigger pyrotechnic inflators, typically operating on 12-volt vehicle architecture with ASIL-D functional safety ratings. Its primary purpose is to discriminate crash severity and deploy restraint stages with occupant-position awareness. Dual-stage and multi-stage product types lead volume shipments while advanced adaptive systems capture expanding margin pools as OEMs bundle pedestrian protection and rollover detection. Smart sensors technology is displacing mechanical triggering methods in premium vehicle programs, though electromechanical architectures still dominate mid-range production lines.
NHTSA Federal Motor Vehicle Safety Standard 208, Euro NCAP assessment protocols, and China's GB/T vehicle safety standards collectively mandate multi-point crash sensing and fault-tolerant ECU architectures. These frameworks force suppliers to maintain redundant data pathways and diagnostic traceability across production batches. Stakeholders must monitor how software-defined safety features reshape procurement contracts and long-term service revenue models.
Market Dynamics
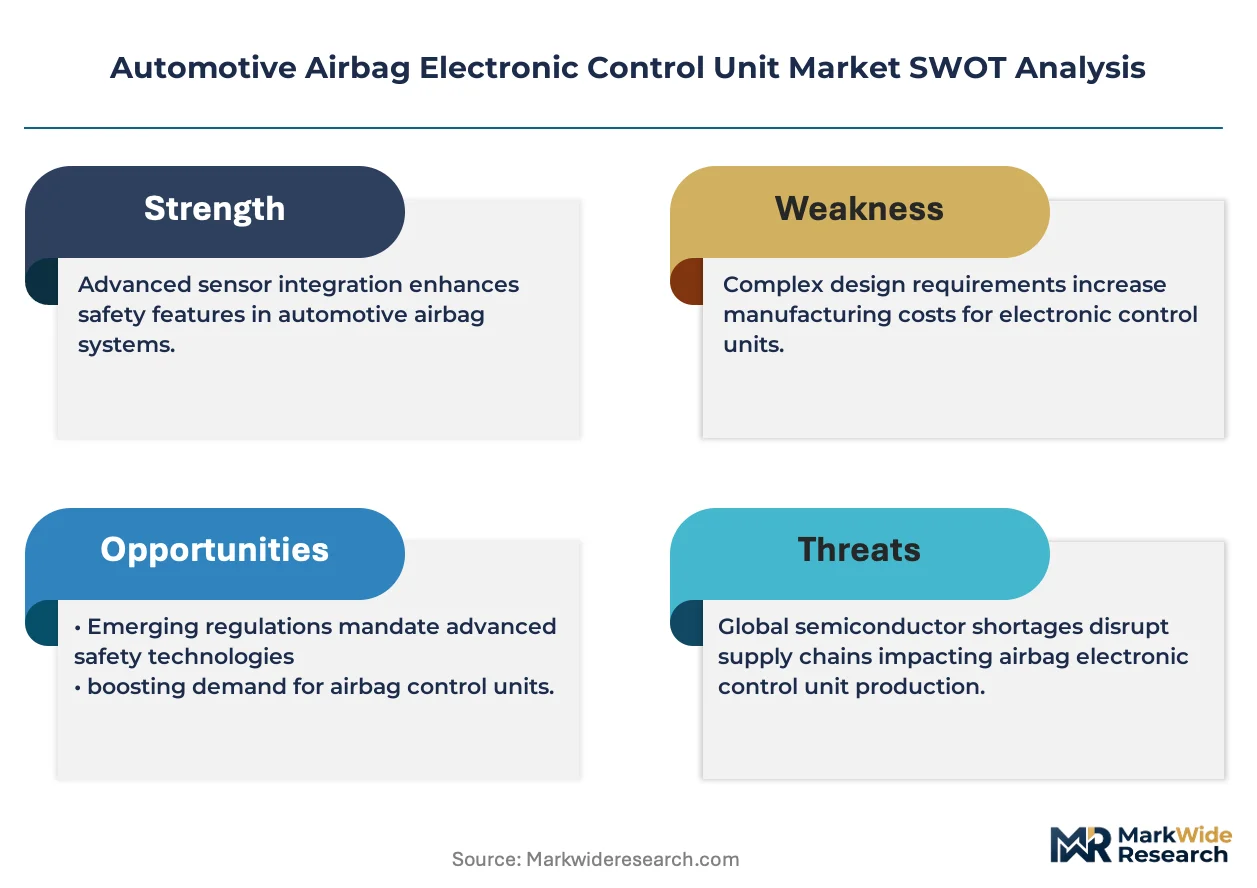
Over-the-air calibration subscriptions are restructuring supplier revenue models beyond hardware shipments, while NHTSA and Euro NCAP protocol tightening forces multi-stage system adoption across OEM portfolios.
Growth Catalysts
- Federal Motor Vehicle Safety Standard 208:NHTSA mandates for advanced frontal airbag systems require sophisticated multi-point crash sensing architectures that expand ECU functionality requirements.
- Smart sensor technology:Solid-state MEMS accelerometers and pressure transducers enable faster signal processing with improved discrimination between crash severities.
- China's GB/T vehicle safety standards:Domestic OEM compliance requirements are accelerating module localization programs and ECU integration facility investments.
Market Restraints
- Semiconductor supply concentration:Wafer fabrication for automotive-grade ASIL-D microcontrollers concentrates in Taiwan and South Korea, exposing ECU suppliers to allocation volatility.
- Pyrotechnic inflator input costs:Sodium azide and guanidine nitrate propellant chemistry faces raw material price instability and hazardous substance handling compliance burdens.
- Functional safety certification timelines:ISO 26262 ASIL-D validation protocols extend development cycles by 18-24 months, compressing program launch windows.
Strategic Opportunities
- Pedestrian protection mandates:Euro NCAP external airbag and hood-lift actuator requirements create new ECU output channel demand for premium vehicle platforms.
- Software-defined safety features:Subscription-based algorithm updates enable recurring revenue streams from deployed vehicle fleets.
- Rollover detection convergence:Integration of gyroscopic sensing with traditional accelerometer architectures opens margin expansion in SUV and light truck segments.
Industry Challenges
- Embedded systems cybersecurity:UN R155 and ISO/SAE 21434 compliance requires hardware security module integration and penetration testing protocols that strain engineering bandwidth.
- Legacy vehicle architecture integration:12-volt electrical systems with controller area network limitations complicate retrofit of advanced multi-stage deployment logic.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Airbag Electronic Control Unit Market |
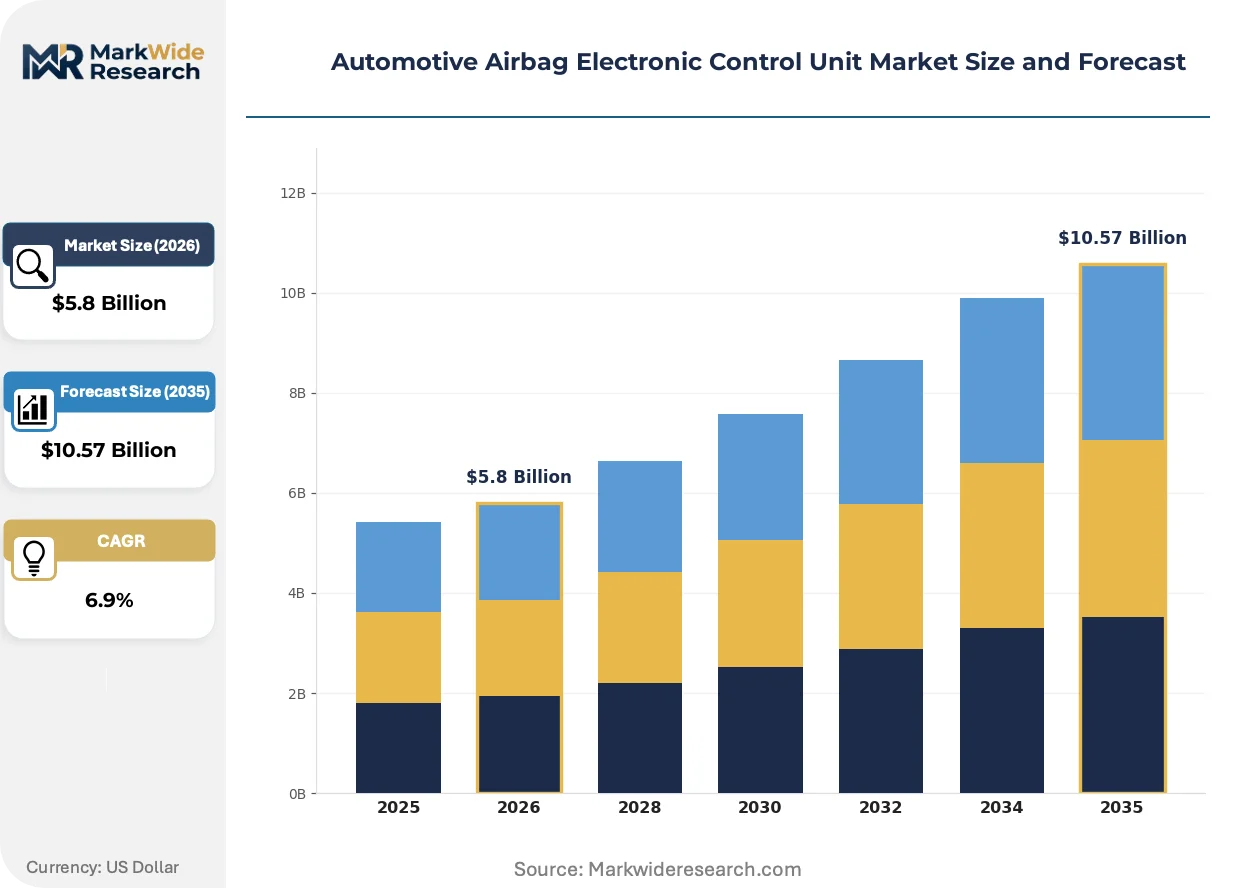
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.57 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Stage, Dual Stage, Multi-Stage, Advanced Adaptive Technology: Mechanical, Electromechanical, Electronic, Smart Sensors End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Installation: Front, Side, Curtain, Knee |
| Companies Covered | Robert Bosch, Aptiv, Continental AG, Autoliv, ZF Friedrichshafen AG, DENSO Corporation, Hyundai Mobis, Mitsubishi Electric Corporation, Infineon Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Airbag Electronic Control Unit Market Trends and Innovations
Sensor fusion architectures and edge computing capabilities are redefining crash discrimination speed and accuracy thresholds across vehicle safety systems.
Domain controller consolidation is decentralizing standalone airbag ECU functions into zonal compute platforms. Premium OEMs at BMW and Mercedes-Benz are piloting integrated restraint control modules that share silicon with ADAS processing units. This topology compression reduces wiring harness complexity while forcing suppliers to defend module value through software differentiation.
REACH substance restrictions are phasing traditional inflator initiator compounds from European supply chains. ECHA candidate list scrutiny of heavy metal stabilizers is accelerating transition to non-azide gas generant formulations. Module suppliers serving Volkswagen Group and Stellantis programs are reformulating propellant chemistry to maintain type approval continuity.
Fleet operators and leasing companies are unbundling post-warranty calibration services from dealer networks. Direct supplier relationships for over-the-air parameter updates are emerging in commercial vehicle segments where downtime costs dominate procurement criteria. This channel disintermediation is most pronounced in North American heavy-duty truck configurations.
Automotive Airbag Electronic Control Unit Market Segmentation
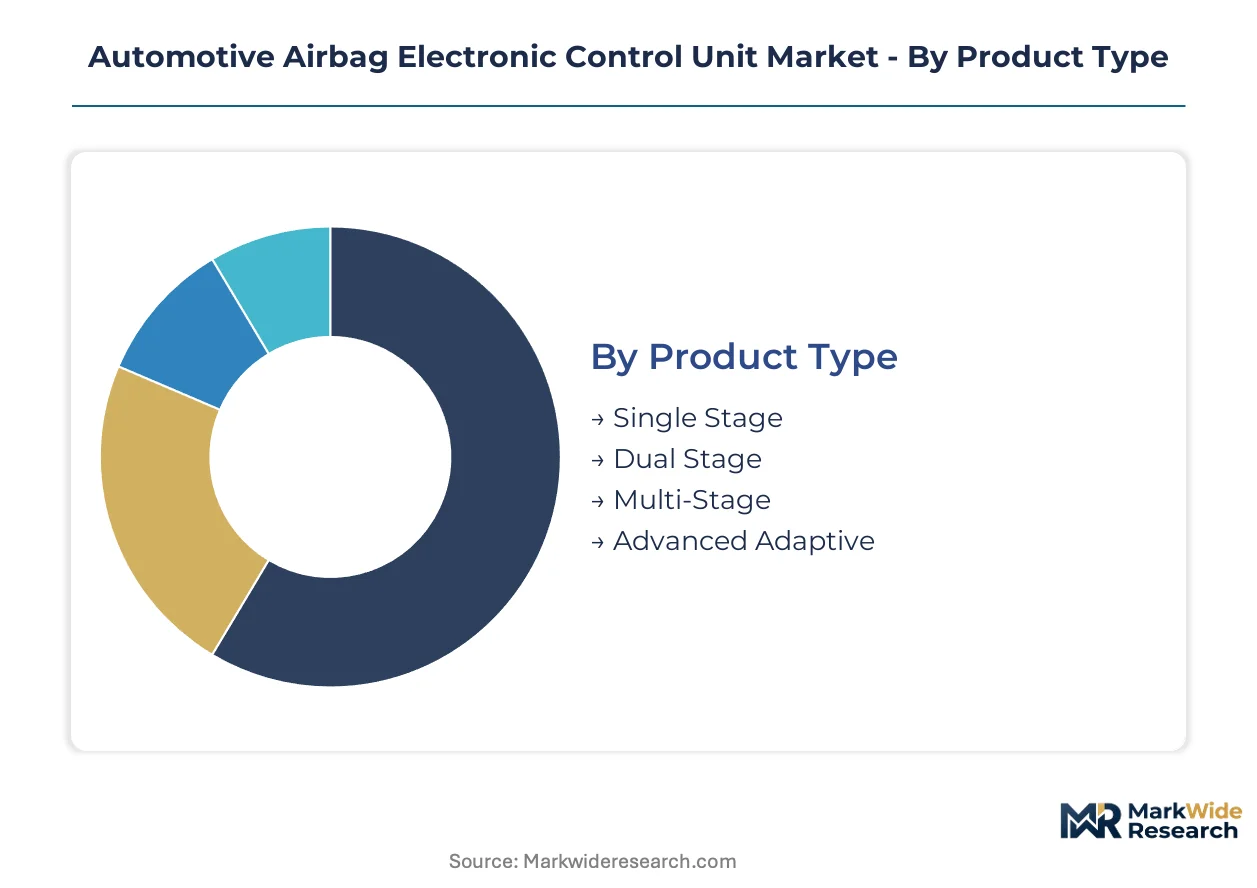
ECU procurement contracts diverge sharply across product tiers and installation positions, with crash severity discrimination requirements dictating microcontroller specifications and sensor fusion complexity. Tier-1 suppliers and OEMs negotiate volume commitments differently depending on whether systems serve mainstream sedan platforms or premium adaptive architectures with pedestrian protection channels.
Product Type:
Cost tier determines microcontroller grade and pyrotechnic channel count, with OEMs calibrating safety ratings against target vehicle price positioning.
- Multi-Stage:Deploys sequential inflator ignition with variable delay intervals matched to occupant mass and crash pulse severity. Passenger car programs in Germany and the United States concentrate procurement for mid-luxury segments where NHTSA and Euro NCAP five-star thresholds require discriminating deployment force.
- Advanced Adaptive:Integrates occupant position sensing, belt tension feedback, and external collision prediction into unified deployment algorithms. Premium SUV and electric vehicle architectures in China absorb expanding volumes as domestic OEMs pursue NCAP-equivalent ratings for export qualification.
- Single Stage:Fixed-threshold deployment logic with minimal sensor input, serving emerging market compact vehicles where cost floors dominate specification.
- Dual Stage:Two-level force modulation for frontal impact scenarios, retaining volume leadership in mass-market sedan platforms across multiple geographies.
Multi-stage leads on scale; advanced adaptive leads on momentum.
Technology:
Volume concentration shifts toward solid-state architectures as mechanical triggering methods face elimination from European supply chains under REACH substance restrictions.
- Smart Sensors:MEMS accelerometers with integrated digital signal processing enable sub-millisecond crash classification through edge computing. Premium vehicle programs at BMW and Mercedes-Benz anchor demand as domain controller consolidation mandates silicon-level integration with ADAS compute.
- Electromechanical:Hybrid architectures combining mechanical safing sensors with electronic deployment logic retain cost advantages in high-volume compact and subcompact production. Assembly plants in Mexico and Thailand source these modules for regional vehicle exports.
- Mechanical:Ball-in-tube and roller-type sensors with discrete electrical contacts, now restricted to legacy platform maintenance and specific commercial vehicle configurations.
- Electronic:Pure solid-state sensing without mechanical redundancy, occupying intermediate positioning between smart sensors and electromechanical hybrids.
Electromechanical retains volume dominance; smart sensors command the steepest expansion trajectory.
End User:
Customer type shapes contract structure, with OEM direct procurement favoring long-term algorithm licensing and tier-1 sourcing emphasizing module price-per-channel metrics.
- OEMs:Direct specification of ECU architectures with embedded software ownership and over-the-air update infrastructure. Volkswagen Group and Stellantis negotiate multi-year supply agreements with algorithm performance guarantees.
- Tier-1 Suppliers:Integration of purchased ECU modules into complete restraint system assemblies for resale to vehicle assemblers.
- Vehicle Assemblers:Contract manufacturing arrangements where brand owners specify ECU requirements but outsource final integration.
- Aftermarket Providers:Replacement module distribution for collision repair and warranty claims, constrained by diagnostic tool compatibility and VIN-specific calibration data access.
OEMs lead on scale; tier-1 suppliers lead on momentum.
Installation:
Application position dictates sensor fusion requirements and pyrotechnic channel allocation, with side and curtain installations demanding faster signal processing than frontal systems.
- Curtain:Roof-rail mounted inflators with rollover deployment logic requiring gyroscopic sensing integration. Light truck and SUV platforms in the United States generate concentrated demand as rollover resistance ratings influence fleet purchase decisions.
- Side:Door-mounted or seat-integrated modules with near-side and far-side discrimination algorithms. Euro NCAP side pole and mobile barrier test protocols force multi-point pressure sensing architectures.
- Front:Steering wheel and instrument panel installations with the longest development heritage and highest unit volumes.
- Knee:Lower dashboard modules preventing submarining injuries, increasingly bundled with advanced adaptive frontal systems.
Front leads on scale; curtain leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates more ECU integration engineering than the United States, yet China's module localization programs are expanding faster than either market as domestic OEMs pursue export certification.
United States
NHTSA Federal Motor Vehicle Safety Standard 208 mandates multi-stage frontal airbag systems for all new passenger vehicles. The regulation forces OEMs to source ECUs with redundant crash sensing architectures. Detroit's automotive corridor anchors module assembly operations serving Ford, General Motors, and Stellantis production lines.
Germany
Euro NCAP five-star thresholds require discriminating deployment force algorithms that only advanced adaptive ECUs deliver. REACH substance restrictions are phasing traditional inflator initiator compounds from German supply chains. Stuttgart and Munich host engineering centers where Robert Bosch and Continental AG develop sensor-to-ECU integration platforms.
China
Domestic OEM compliance with GB/T vehicle safety standards is accelerating module localization programs. The country's dual carbon goals are pushing electric vehicle architectures that bundle pedestrian protection and rollover detection into unified ECU platforms. Shanghai and Beijing concentrate ECU integration facility investments from BYD, NIO, and Li Auto supply chains.
Japan
METI industrial policy supports automotive semiconductor supply chain resilience through domestic ASIL-D microcontroller production. JIS standards alignment with ISO 26262 functional safety protocols streamlines ECU export qualification. Toyota City and Hiroshima anchor DENSO Corporation and Mitsubishi Electric manufacturing clusters.
South Korea
Wafer fabrication for automotive-grade microcontrollers concentrates in Hsinchu and Seoul metropolitan area foundries, exposing ECU suppliers to allocation volatility. MFDS hazardous substance handling regulations govern sodium azide propellant chemistry imports. Hyundai Mobis anchors domestic ECU production for Hyundai-Kia Automotive Group vehicle programs.
Automotive Airbag Electronic Control Unit Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-stack system integrators capturing premium-tier contracts while component-focused suppliers serve high-volume platform programs. The vendor base concentrates around three strategic archetypes: semiconductor-to-module integrators with captive silicon supply, electromechanical platform standardizers with multi-OEM program scale, and crash-data-loop controllers with proprietary algorithm development. M&A activity targets sensor fusion capabilities and cybersecurity certification assets, while capacity expansion focuses on ASIL-D qualified assembly lines in Mexico and Thailand.
Within the semiconductor-integrated tier, Robert Bosch and Infineon Technologies AG exemplify the archetype of suppliers controlling upstream silicon production. Continental AG and Autoliv occupy positions as full-system integrators with standardized platform architectures spanning multiple OEM programs. These three companies represent the competitive spectrum from component supply through complete restraint system delivery.
| Leading Market Players |
|---|
| Robert Bosch |
| Aptiv |
| Continental AG |
| Autoliv |
| ZF Friedrichshafen AG |
| DENSO Corporation |
| Hyundai Mobis |
| Mitsubishi Electric Corporation |
| Infineon Technologies AG |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up specialists in automotive electronics have consolidated module assembly capacity across Mexico and Thailand, tightening pricing discipline through volume commitments while squeezing mid-tier suppliers on ASIL-D certification costs.
Pricing Analysis
Capacity additions in Mexico and Thailand are reshaping price floors for mid-range electromechanical ECU tiers. Three-tier pricing structure across premium adaptive, standard multi-stage, and economy single-stage levels stratifies around microcontroller grade and pyrotechnic channel count. Pricing pressure stems from semiconductor allocation volatility as wafer fabrication concentrates in Taiwan and South Korea. Fleet operators show highest price sensitivity due to volume procurement leverage, while premium OEMs prioritize algorithm performance guarantees over unit cost.
Supply Chain Analysis
Reverse-logistics flows for collision-replacement modules channel through certified refurbishment centers in Germany and the United States before secondary distribution. Geographic supply concentrates in Taiwan for ASIL-D microcontrollers, South Korea for wafer fabrication, and China for module integration and testing. Raw material dependencies include sodium azide and guanidine nitrate propellant chemistry, MEMS accelerometer silicon substrates, and copper-alloy connector housings. Single-source vulnerability in Taiwan semiconductor foundries poses structural risk. Distribution runs through Tier-1 system integrators with direct OEM contracting for algorithm-licensed architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on software-defined safety features displacing hardware-only procurement, as subscription-based calibration services capture recurring revenue from deployed fleets.
For Market Incumbents: Extend algorithm ownership through embedded software licensing structures that lock OEMs into multi-year update agreements. Consolidate sensor fusion capabilities through targeted acquisition of MEMS design houses in Japan and South Korea. Domain controller consolidation at BMW and Mercedes-Benz threatens standalone ECU value capture; defend through zonal compute integration partnerships. For New Entrants and Emerging Players: Direct-to-fleet calibration subscriptions offer the most penetrable route for aftermarket-focused entrants, bypassing entrenched Tier-1 relationships. Target commercial vehicle segments in North America where downtime costs dominate procurement criteria over upfront module pricing. White-space exists in cybersecurity certification services for UN R155 compliance, with hardware security module integration as the go-to-market anchor. For Investors and Strategic Acquirers: Valuations sit cheapest among component-focused suppliers serving high-volume compact vehicle programs without adaptive algorithm portfolios. Long-term viability favors full-stack integrators controlling crash-test data loops and proprietary deployment algorithms. Watch for NHTSA protocol amendments on pedestrian protection mandates as the inflection signal for advanced adaptive system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Continental AG leverages electromechanical architectures across Stellantis and Volkswagen Group programs to amortize development costs. |
| Semiconductor Supply Agreement | Robert Bosch anchors in-house sensor-to-ECU integration through captive wafer supply from its semiconductor division. |
| Software-Defined Vehicle Investment | Autoliv monetizes crash-test data loops through subscription-based algorithm updates for adaptive deployment logic. |
| Geographic Manufacturing Footprint | Capacity expansion in Thailand and Mexico serves regional export demand while hedging against Taiwan foundry concentration. |
| Cybersecurity Certification Program | UN R155 and ISO/SAE 21434 compliance creates defensive moats through hardware security module integration mandates. |
Research Methodology
Multiple input streams — OEM platform engineering disclosures, Tier-1 supplier procurement patterns, and semiconductor foundry allocation data — were reconciled through bottom-up and top-down triangulation. Primary interviews with ECU program managers, restraint system procurement leads, and aftermarket distribution specialists informed volume assumptions. Secondary validation drew from NHTSA FMVSS 208 dockets, Euro NCAP technical bulletins, vehicle production databases, and SEC filings from listed automotive suppliers.
Historical shipment trajectories were cross-referenced against panel input from industry participants to construct the analytical framework across the analysis window. Segmentation dimensions modeled include product type tier, sensor technology architecture, end-user contracting structure, and installation position. CAGRs were derived from elasticity-adjusted volume projections incorporating electric vehicle content-per-vehicle escalations and pedestrian protection mandate adoption curves.
The model assumes a particular technology adoption path; alternative pathways for solid-state MEMS displacement of electromechanical architectures would alter the outlook. Forecasts reflect assumptions on GB/T standard alignment with Euro NCAP protocols and REACH substance restriction timelines. Practitioners should monitor foundry capacity announcements in Taiwan and South Korea, NHTSA rulemaking on external airbag requirements, and fleet operator direct-supplier contracting trends for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Car Satellite Antenna Market
Automotive Electrical & Electronics
Electric Motor Horn Market
Automotive Electrical & Electronics
Automotive Ultracapacitor Market
Automotive Electrical & Electronics
Automotive Alternator Market
Automotive Electrical & Electronics
Argentina Automotive EPS Market
Automotive Electrical & Electronics
South Korea Electric Power Steering (EPS) Sensor Market
Automotive Electrical & Electronics
Automotive Camera Market
Automotive Electrical & Electronics
Europe Electric Power Steering Market
Automotive Electrical & Electronics
South Korea Automotive Camera Market
Automotive Electrical & Electronics
Global Automotive on Board Power Inverter Market
Automotive Electrical & Electronics
Africa and Middle East Automotive Tpms Market
Automotive Electrical & Electronics
Electric Vehicle Shielded HV Cables Market
Automotive Electrical & Electronics
Automotive Zonal Gateway ECU Market
Automotive Electrical & Electronics
Electric Vehicle High-Voltage Cables Market
Automotive Electrical & Electronics
Automotive Temperature Sensor Market
Automotive Electrical & Electronics
Mexico Automotive EPS Market