
 Animal Diagnostics Market | 2026-2036
Animal Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Diagnostics Market Analysis
Consolidation among companion animal hospital chains is repositioning procurement power toward centralized laboratory networks. IDEXX Laboratories, Inc. leverages its integrated in-house and reference lab platform to capture recurring diagnostic volumes. Zoetis anchors its position through pharmaceutical-diagnostic bundling across livestock and companion animal channels. Thermo Fisher Scientific, Inc. competes by extending its human diagnostics manufacturing scale into veterinary PCR and sequencing workflows.
Animal diagnostics encompasses the detection, identification, and monitoring of disease states, genetic markers, and metabolic conditions in livestock and companion animals through assays requiring sensitivity thresholds typically below nanogram-per-milliliter concentrations. These systems serve commercial purposes spanning herd health management, zoonotic disease surveillance, and personalized veterinary treatment protocols. Molecular diagnostics leads in revenue contribution due to premium pricing on PCR and next-generation sequencing panels, while rapid tests occupy the highest volume tier in field-deployed livestock screening. Immunoassays sustain margin pools through chronic disease monitoring in aging companion animal populations.
The FDA Center for Veterinary Medicine regulates diagnostic test kit accuracy claims, while USDA APHIS governs interstate movement testing for reportable diseases such as avian influenza and bovine tuberculosis. ISO 17025 accreditation requirements for veterinary reference laboratories shape capital deployment toward automated platforms. Stakeholders must weigh the pace of CLIA-waived veterinary test expansion against the regulatory burden of full laboratory certification.
Market Dynamics
Companion animal hospital chains are consolidating procurement power toward centralized laboratory networks, compressing margins for standalone reference labs while rewarding integrated platform providers with recurring diagnostic volumes.
Growth Catalysts
- FDA Center for Veterinary Medicine oversight:Regulatory clarity on diagnostic test kit accuracy claims accelerates product development pathways and reduces commercialization risk for assay developers targeting companion animal channels.
- PCR and next-generation sequencing panels:Molecular diagnostics command premium pricing due to sensitivity thresholds below nanogram-per-milliliter concentrations, sustaining revenue pools in chronic disease monitoring applications.
- United States pet insurance penetration:Specialty veterinary consolidation in this geography drives uptake of premium diagnostic protocols previously constrained by out-of-pocket cost sensitivity.
Market Restraints
- ISO 17025 capital intensity:Automated platform accreditation requirements for veterinary reference laboratories strain mid-tier operators with limited balance sheet capacity.
- CLIA-waived expansion friction:The regulatory burden of full laboratory certification slows point-of-care test deployment in rural livestock screening networks.
- Avian influenza surveillance mandates:USDA APHIS interstate movement testing requirements create compliance cost concentration in poultry-dense supply regions without offsetting revenue mechanisms.
Strategic Opportunities
- India livestock health networks:Underpenetrated dairy and poultry operations present white space for affordable rapid test formats adapted to field-deployed screening workflows.
- Pharmaceutical-diagnostic bundling:Convergence of therapeutic and assay platforms enables integrated disease management contracts across livestock channel customers.
- Telemedicine-enabled remote interpretation:Digital distribution innovation extends specialist veterinary pathology access to fragmented companion animal practices lacking in-house expertise.
Industry Challenges
- Veterinary clinical pathologist scarcity:Specialized diagnostic interpretation skills concentrate in academic medical centers and large reference networks, constraining quality assurance scaling.
- Legacy immunoassay platform integration:Chronic disease monitoring workflows depend on established chemiluminescence infrastructure resistant to full molecular platform replacement.
- Multiplex assay validation timelines:Simultaneous detection claim substantiation across pathogen panels extends regulatory submission preparation and strains development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Diagnostics Market |
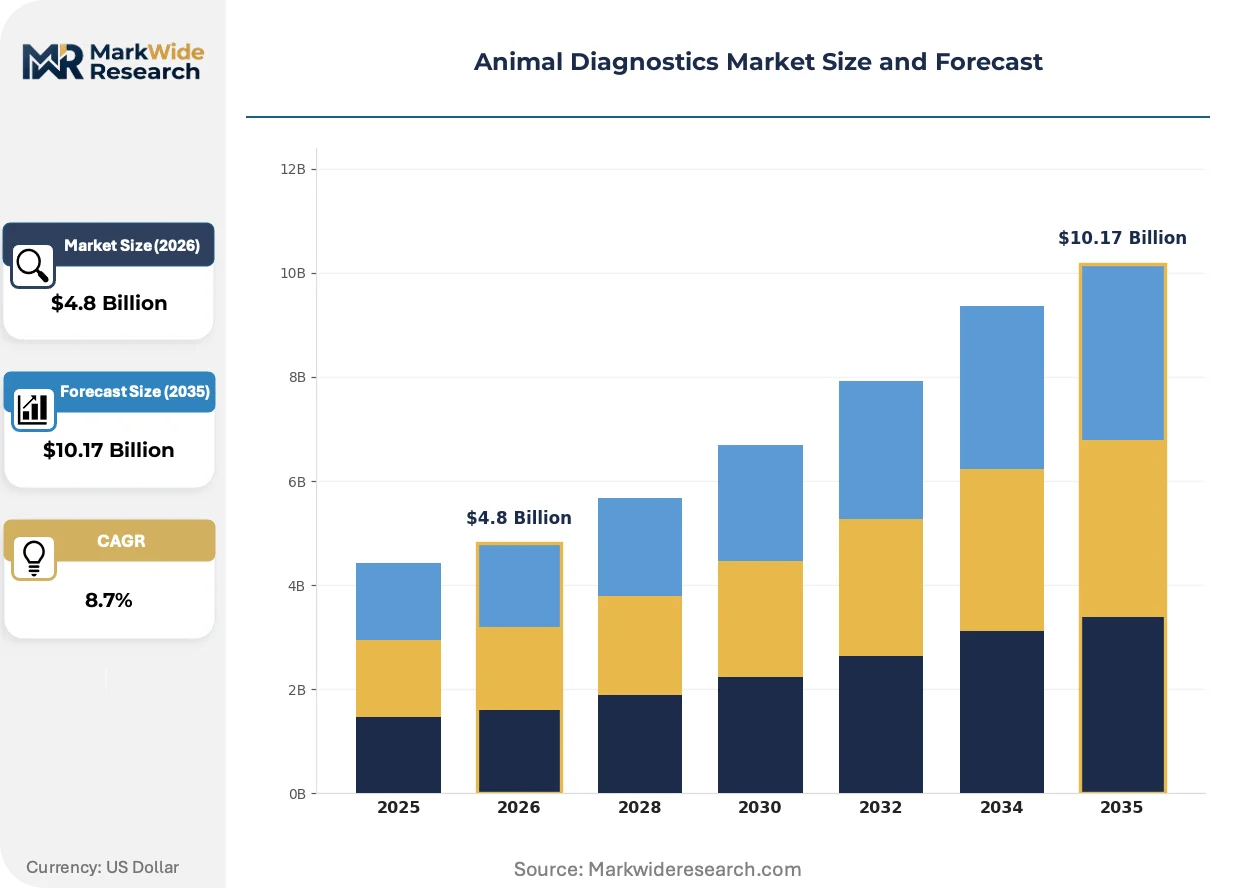
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biochemicals, Immunoassays, Molecular Diagnostics, Rapid Tests Technology: Enzyme-Linked Immunosorbent Assay, Polymerase Chain Reaction, Microfluidics, Next-Generation Sequencing End User: Veterinary Clinics, Research Laboratories, Animal Hospitals, Livestock Farms Application: Infectious Disease, Genetic Testing, Nutritional Health, Preventive Care |
| Companies Covered | IDEXX Laboratories, Inc., Zoetis, Antech Diagnostics, Inc., Thermo Fisher Scientific, Inc., Virbac, bioMérieux, Neogen Corporation, FUJIFILM Corporation, Heska Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Diagnostics Market Emerging Trajectories
Automation of sample-to-answer workflows is compressing turnaround times while artificial intelligence-assisted image analysis is reshaping cytology and histopathology interpretation economics.
Digital PCR platforms are automating absolute quantification of viral load and genetic markers without standard curve dependency. Companion animal hospitals with in-house molecular capabilities are adopting these systems to retain revenue previously referred to external laboratories. The technology is automating technician workflow efficiency while reducing batch failure rates in low-volume practice settings.
EU MDR-equivalent veterinary diagnostic device classification discussions are creating preemptive compliance investments among manufacturers with European commercial interests. The regulatory trajectory is pressuring legacy product portfolios toward design dossier documentation standards. In vitro diagnostic reagent producers are restructuring quality management systems to accommodate anticipated notified body involvement.
Subscription-based reagent access models are displacing capital-intensive instrument ownership in independent companion animal practices. Equipment-as-a-service arrangements bundle maintenance, software updates, and consumable supply into predictable monthly expenditures. This financing restructuring is most visible in United States metropolitan markets where practice ownership demographics skew toward debt-averse younger veterinarians.
Animal Diagnostics Market Segmentation
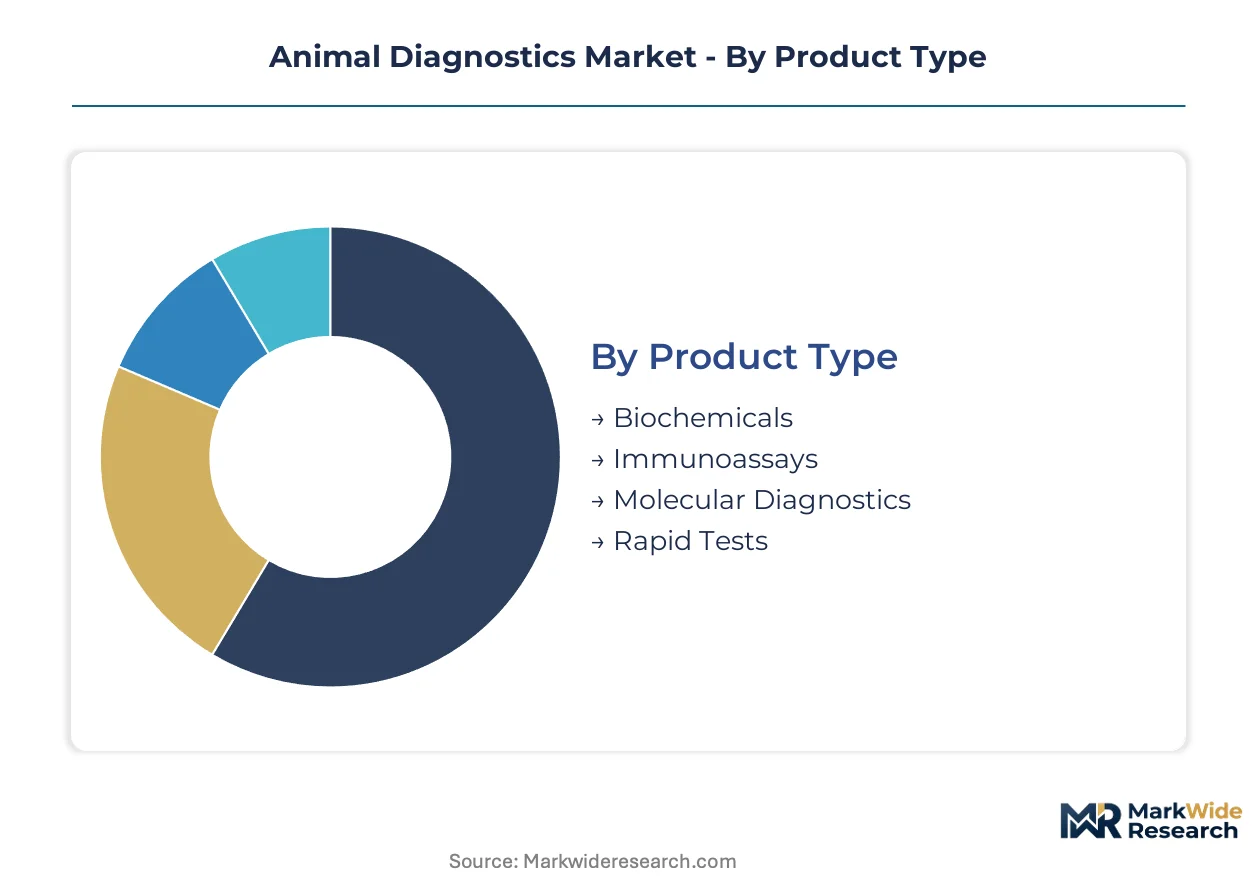
Diagnostic modality selection in animal health hinges on sensitivity requirements, throughput economics, and regulatory pathway complexity. Segmentation reveals how technology tiers map to distinct buyer budgets and clinical workflows across companion and production animal settings.
Product Type:
Procurement budgets stratify sharply between reference laboratory capital investments and point-of-care disposable economics.
- Molecular Diagnostics:PCR and sequencing platforms detect pathogen nucleic acid at picogram sensitivity thresholds. Companion animal specialty hospitals in the United States deploy these systems in-house to retain revenue from complex oncology and infectious disease cases.
- Immunoassays:Chemiluminescence and ELISA systems monitor chronic conditions in aging pet populations through biomarker quantification. Reference laboratory networks achieve scale economies through automated batch processing of endocrine and metabolic panels.
- Rapid Tests:Lateral flow cassettes enable field-deployed screening without cold chain logistics. Livestock veterinarians in remote dairy regions prioritize these formats for immediate herd management decisions.
- Biochemicals:Reagent kits for hematology and clinical chemistry analyzers constitute recurring consumable revenue streams. Animal hospitals with in-house laboratory infrastructure lock in multi-year supply contracts.
Molecular diagnostics leads on scale; rapid tests lead on momentum.
Technology:
Workflow automation intensity separates high-throughput reference laboratories from resource-constrained practice settings.
- Polymerase Chain Reaction:Thermal cycling amplification enables pathogen detection below clinical threshold concentrations. Digital PCR platforms now automate absolute quantification without standard curve dependency, compressing turnaround times for veterinary oncology panels.
- Next-Generation Sequencing:Massively parallel readouts identify novel pathogen variants and antimicrobial resistance markers. Academic veterinary medical centers deploy these systems for outbreak investigation and genomic surveillance.
- Enzyme-Linked Immunosorbent Assay:Colorimetric antibody detection sustains high-volume screening economics in livestock export certification programs.
- Microfluidics:Lab-on-chip architectures miniaturize reagent volumes for point-of-care deployment in mobile veterinary units.
PCR anchors current revenue pools; next-generation sequencing climbs the fastest.
End User:
Testing volume concentration and reimbursement access determine platform procurement authority.
- Animal Hospitals:Consolidated companion animal chains centralize reference laboratory contracts while expanding in-house rapid test menus. Specialty oncology and internal medicine departments drive molecular diagnostics adoption.
- Veterinary Clinics:Independent practices favor CLIA-waived point-of-care instruments with subscription reagent financing. Equipment-as-a-service arrangements reduce capital barriers for younger practice owners.
- Livestock Farms:Integrated poultry and swine operations mandate continuous surveillance testing under USDA APHIS interstate movement regulations.
- Research Laboratories:Contract research organizations and academic institutions validate novel assay formats for commercial licensing.
Animal hospitals command procurement volume; veterinary clinics expand most quickly.
Application:
Clinical utility and payment model maturity shape segment investment prioritization.
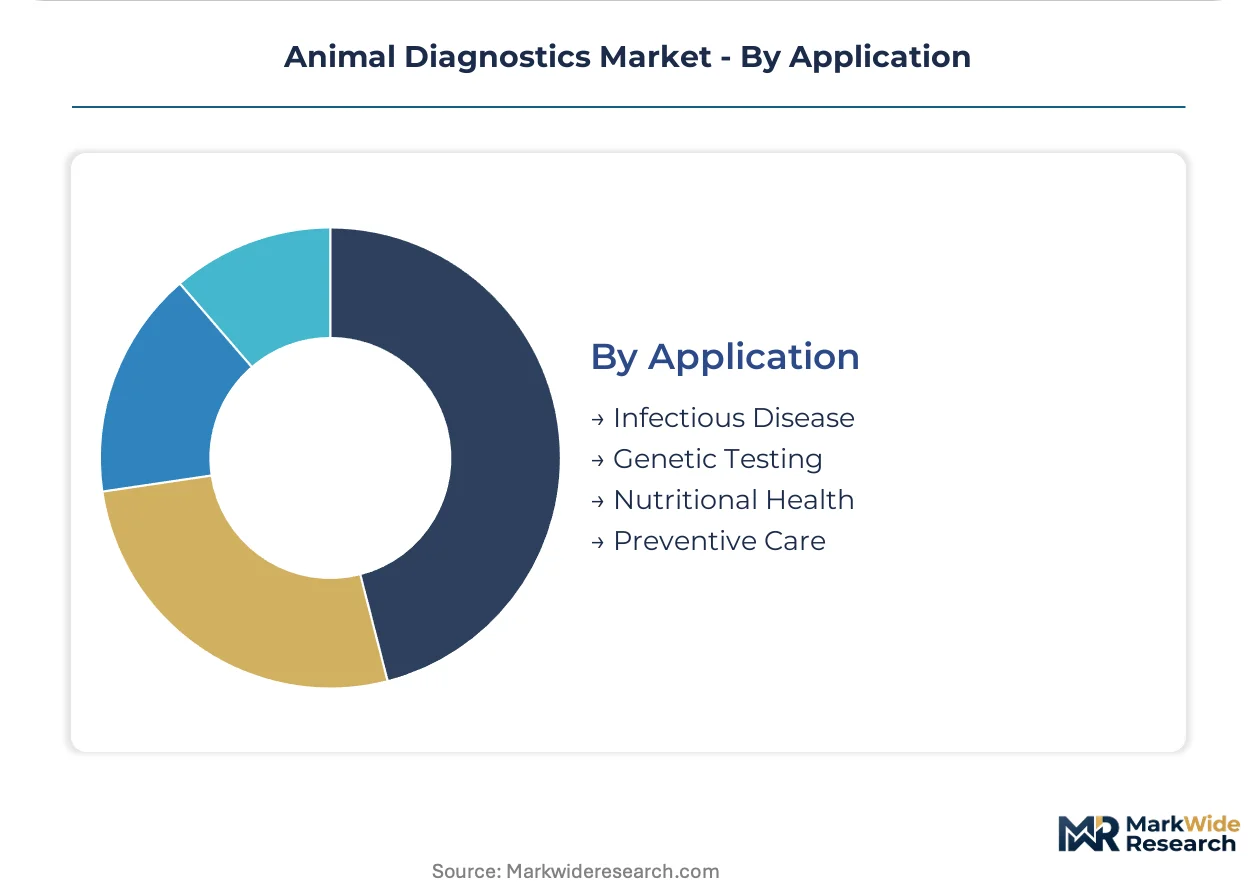
- Infectious Disease:Pathogen detection panels address zoonotic surveillance mandates and companion animal vaccine protocol validation. USDA APHIS reporting requirements sustain demand for validated assay formats in avian influenza and brucellosis screening.
- Genetic Testing:Breed-specific disease marker screening and parentage verification drive premium pricing in purebred companion animal markets.
- Preventive Care:Wellness screening panels expand diagnostic penetration among insured pet populations with reduced cost sensitivity.
- Nutritional Health:Metabolic profiling supports customized diet formulation in high-value performance animals and exotic species.
Infectious disease dominates current testing volumes; genetic testing shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands premium diagnostic volumes through pet insurance penetration, while Germany anchors European livestock testing through stringent veterinary surveillance mandates. Country-specific regulatory frameworks and veterinary infrastructure maturity create divergent growth trajectories across major markets.
United States
Companion animal hospital chains consolidate procurement power toward centralized laboratory networks, compressing margins for standalone reference labs. FDA Center for Veterinary Medicine oversight shapes diagnostic test kit accuracy claims and commercialization pathways. Specialty oncology practices in Greater Boston and the Pacific Northwest deploy in-house molecular platforms to retain complex case revenue.
Germany
Livestock export certification programs sustain high-volume immunoassay screening economics across dairy and swine operations. EU MDR-equivalent veterinary diagnostic device classification discussions pressure legacy product portfolios toward design dossier documentation standards. Industrial clusters in North Rhine-Westphalia and Bavaria host automated reference laboratory networks serving centralized procurement contracts.
China
Dairy and poultry operation expansion drives demand for affordable rapid test formats adapted to field-deployed screening workflows. NMPA regulatory pathways for veterinary diagnostic devices accelerate product registration timelines for domestic manufacturers. Yangtze River Delta veterinary medical centers deploy next-generation sequencing platforms for outbreak investigation and genomic surveillance.
India
Underpenetrated dairy and poultry operations present white space for rapid test formats in field-deployed screening workflows. CDSCO veterinary product registration requirements shape import substitution strategies for diagnostic reagent manufacturers. Maharashtra and Gujarat industrial corridors concentrate contract research organizations validating novel assay formats for commercial licensing.
Brazil
Integrated poultry and swine operations mandate continuous surveillance testing under ANVISA-aligned federal veterinary health regulations. Export certification requirements for European and Asian markets sustain reference laboratory capacity investments. São Paulo state anchors diagnostic platform distribution networks serving the Mercosur veterinary market.
Animal Diagnostics Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated market structure. Consolidation among companion animal hospital chains concentrates procurement authority toward integrated platform providers with recurring diagnostic volumes. Three strategic archetypes dominate: pharmaceutical-diagnostic bundlers, reference laboratory network operators, and human diagnostics scale extenders. M&A activity targets point-of-care technology assets, while equipment-as-a-service financing models reduce capital barriers for independent practice acquisition.
Among diversified life science conglomerates, Thermo Fisher Scientific, Inc. and FUJIFILM Corporation occupy positions extending human diagnostics manufacturing scale into veterinary workflows. IDEXX Laboratories, Inc. anchors the integrated reference laboratory and in-house platform tier, exemplifying the recurring revenue model that hospital chain consolidation rewards. These three entities represent distinct competitive positioning vectors: manufacturing scale leverage, integrated service-platform bundling, and point-of-care technology specialization.
| Leading Market Players |
|---|
| IDEXX Laboratories, Inc. |
| Zoetis |
| Antech Diagnostics, Inc. |
| Thermo Fisher Scientific, Inc. |
| Virbac |
| bioMérieux |
| Neogen Corporation |
| FUJIFILM Corporation |
| Heska Corporation |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between ISO 17025-accredited reference laboratories and CLIA-waived point-of-care operators manifests in divergent pricing architectures and supply chain configurations across the animal diagnostics value chain. Premium-tier molecular platforms command instrument-plus-reagent bundling contracts with multi-year lock-ins, while economy rapid-test segments flow through distributor networks optimized for cold-chain-agnostic logistics.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for lateral flow rapid tests, compressing margins for legacy manufacturers in established markets. Three-tier pricing structure across premium, standard, and economy levels separates digital PCR oncology panels from automated chemiluminescence immunoassays and disposable field-screening cassettes. Pricing pressure stems from consolidated companion animal hospital chains centralizing procurement toward integrated platform providers with recurring diagnostic volumes. Independent veterinary clinics in United States metropolitan markets exhibit highest price sensitivity, driving subscription-based reagent access models that displace capital-intensive instrument ownership.
Supply Chain Analysis
Instrument refurbishment and trade-in programs for hematology and clinical chemistry analyzers create reverse-logistics flows from veterinary clinics back to original equipment manufacturers and certified remanufacturing facilities. Manufacturing concentration in the United States, Germany, and China shapes upstream dependencies for thermal cycling components, optical detection modules, and microfluidic cartridges. Raw material sourcing draws from specialized polymer suppliers for consumable housings, rare-earth elements for magnetic bead separation systems, and recombinant protein production for antibody reagents. Single-source vulnerability concentrates in semiconductor components for digital PCR platforms. Distribution runs through veterinary distribution cooperatives and direct-to-hospital sales forces serving consolidated chain accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in animal diagnostics hinge on automation-driven cost compression in reference laboratory networks and premium-tier uptake of molecular oncology panels in insured companion animal populations.
For Market Incumbents: Anchor defensive positioning through backward integration into reagent manufacturing and captive control of veterinary reference laboratory networks serving consolidated hospital chains. Invest in ISO 17025 accreditation automation to offset clinical pathologist scarcity constraints. Counter emerging point-of-care molecular platform entrants by locking multi-year consumable supply contracts with specialty oncology practices. For New Entrants and Emerging Players: Launch via equipment-as-a-service financing models targeting debt-averse younger veterinarians in United States metropolitan markets. Target underpenetrated dairy and poultry operations in India with affordable rapid test formats adapted to field-deployed screening workflows without cold chain logistics. Pursue telemedicine-enabled remote interpretation partnerships to extend specialist pathology access to fragmented companion animal practices lacking in-house expertise. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier reference laboratory operators face ISO 17025 capital intensity strains without balance sheet capacity for automated platform deployment. Long-term viability favors integrated platform providers with recurring diagnostic volumes and pharmaceutical-diagnostic bundling capabilities across livestock channels. Monitor FDA Center for Veterinary Medicine CLIA-waived expansion decisions as inflection indicator for point-of-care test deployment economics in rural livestock screening networks.| Strategic Initiative | Industry Significance |
|---|---|
| Reference Laboratory Network Consolidation | Centralized procurement contracts with companion animal hospital chains lock in recurring diagnostic volumes and compress standalone competitor margins. |
| Digital PCR Platform Launch | Absolute quantification capabilities without standard curve dependency automate technician workflows and reduce batch failure rates in low-volume practice settings. |
| Equipment-as-a-Service Financing Model | Subscription-based reagent access bundles maintenance and consumable supply into predictable monthly expenditures for independent veterinary clinics. |
| EU MDR-Equivalent Compliance Investment | Preemptive design dossier documentation for veterinary diagnostic devices pressures legacy product portfolios toward notified body involvement standards. |
| Telemedicine-Enabled Pathology Partnership | Digital distribution innovation extends specialist veterinary cytology and histopathology interpretation to fragmented practices lacking in-house expertise. |
Methodological Framework
Bottom-up companion animal hospital and livestock farm modeling reconciled against top-down diagnostic platform manufacturer shipment tracking forms the analytical core of this study. Primary interviews with veterinary practice owners, reference laboratory operations directors, diagnostic reagent procurement managers, and regulatory affairs specialists at FDA Center for Veterinary Medicine intersect with secondary validation from USDA APHIS surveillance reports, FDA 510(k) veterinary diagnostic filings, ISO 17025 accreditation databases, and pet insurance penetration statistics from North American and European markets.
Input-output matrices map diagnostic modality adoption rates against end-user procurement authority concentration, technology lifecycle positioning, and regional regulatory pathway complexity across the projection horizon. Segmentation dimensions span product type, technology tier, end-user category, and application area, with cross-cutting analysis of veterinary infrastructure maturity and reimbursement access patterns. CAGRs derive from weighted scenario modeling incorporating instrument placement forecasts, consumable pull-through assumptions, and pricing trajectory sensitivity to consolidated buyer power.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt shifts in FDA CLIA-waiver expansion timelines or USDA APHIS interstate movement testing mandate modifications. Practitioners should monitor companion animal hospital chain consolidation velocity and NMPA regulatory pathway acceleration in China for early signals of procurement power redistribution and import substitution momentum.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Semen Analysis Systems Market
Diagnostics
Johne's Disease Diagnostics Market
Diagnostics
Global Predictive Genetic Testing and Consumer/Wellness Genomics Market
Diagnostics
Autoimmunity Immunoassay Market
Diagnostics
Asia-Pacific Molecular Diagnostics Market
Diagnostics
Tuberculosis (TB) Diagnostics Market
Diagnostics
Argentina in Vitro Diagnostics Market
Diagnostics
Diagnostic Enzymes Market
Diagnostics
Veterinary Diagnostic Services Market
Diagnostics
BRIC in-Vitro Diagnostics (IVD) Market
Diagnostics
GCC in-Vitro Diagnostics Market
Diagnostics
Cervical Cancer Diagnostic Tests Market
Diagnostics
Asia-Pacific Ovarian Cancer Diagnostics Market
Diagnostics
Global RSV Diagnostics Market
Diagnostics
Remote Diagnosis of Electric Vehicle Market
Diagnostics
Neuro-Auto-Immune Disease Diagnostics Market