
 Meat Emulsions Market | 2026-2036
Meat Emulsions Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Emulsions Market Foresight
Multi-source procurement of hydrocolloids and emulsifiers is shifting toward vertically integrated supply arrangements among large meat processors. Cargill, Incorporated leverages its grain-to-protein pipeline to secure captive supplies of modified starches for emulsion stabilization. Kerry Group plc sustains formulation leadership through its integrated taste and nutrition platforms across European and North American meat accounts. ADM competes on oilseed-derived lecithin and specialty lipid portfolios that anchor emulsion functionality in reduced-fat meat systems.
Meat emulsions are colloidal dispersions of finely comminuted fat within a continuous protein matrix, typically achieving particle sizes below 50 microns through high-shear chopping or bowl-cutter processing to ensure thermal stability and sliceability in cooked products. Emulsion sausages occupy the largest volume position within product type categories, though spreadable products command premium positioning in European retail channels. Food manufacturers represent the most concentrated end-user segment, with procurement patterns favoring ingredient suppliers capable of delivering integrated emulsifier-stabilizer-flavor systems rather than single-component offerings.
USDA inspection protocols and FSIS labeling standards govern emulsion composition and allergen declaration in the United States, while EFSA evaluates novel emulsifier additives under EU food improvement agent regulations. The EU Green Deal's Farm to Fork strategy pressures reduction of synthetic phosphate usage in meat emulsions, redirecting R&D toward natural phosphate alternatives and clean-label binding systems. Stakeholders must monitor evolving additive authorization pathways and regional clean-label thresholds to align formulation portfolios with divergent regulatory timelines.
Market Dynamics
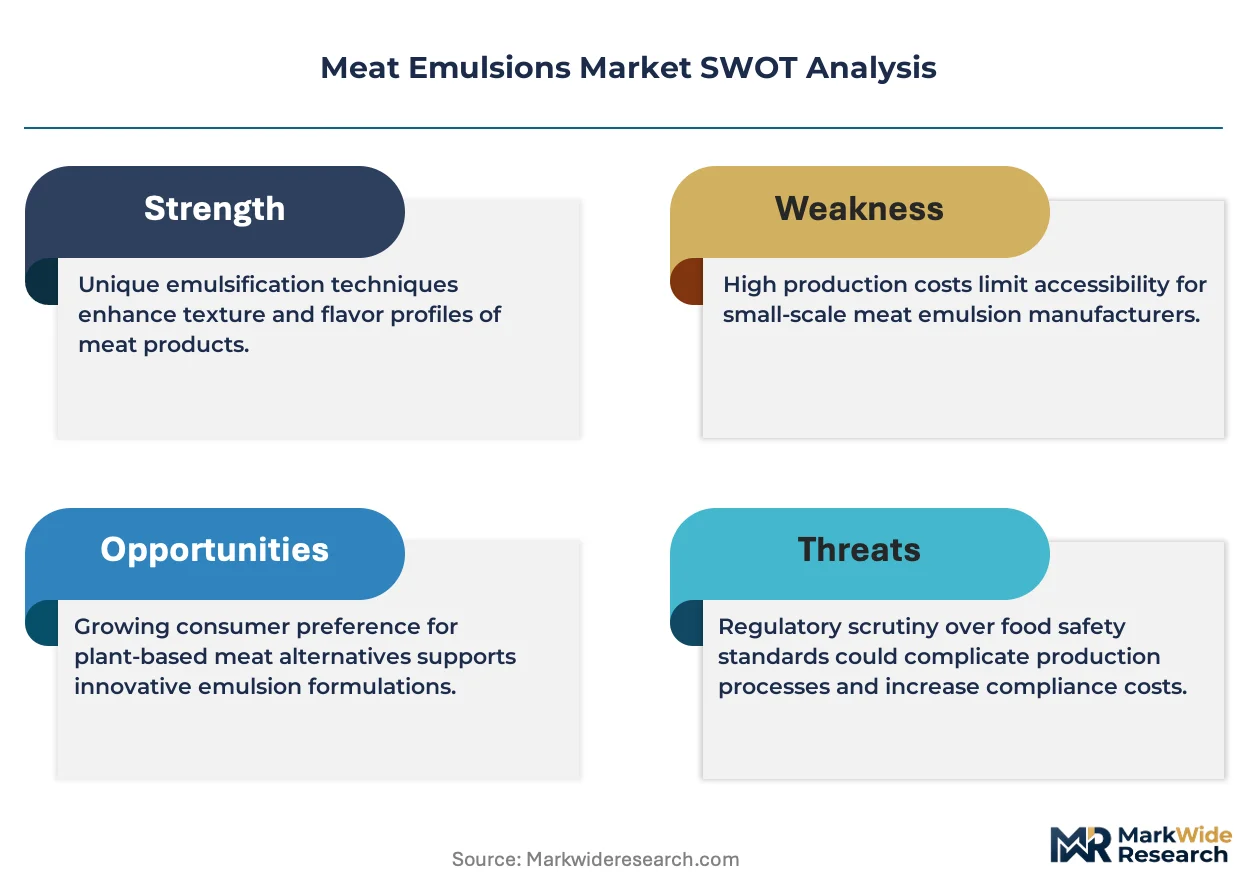
Clean-label reformulation mandates across the European Union and North America are forcing meat processors to abandon synthetic phosphate binders in favor of natural hydrocolloid systems, reshaping supplier relationships and ingredient procurement specifications throughout the value chain.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Binding targets for synthetic additive reduction in processed foods accelerate demand for phosphate-free emulsion stabilizers in German and French sausage manufacturing.
- High-shear bowl-cutter processing:Equipment upgrades in industrial meat facilities enable sub-50 micron fat dispersion, improving thermal stability and expanding clean-label product portfolios.
- German sausage tradition density:Concentrated industrial meat processing infrastructure in Bavaria and Lower Saxony generates sustained procurement volume for specialized emulsion ingredient systems.
Market Restraints
- Modified starch supply concentration:Grain processing consolidation in North American Midwest limits alternative sourcing for critical emulsion stabilizers during harvest volatility periods.
- Clean-label cost premium:Natural hydrocolloid binders command 15-40% price elevation over synthetic phosphates, compressing margins in private-label processed meat segments.
- EFSA novel food additive pathways:Extended safety evaluation timelines for emerging plant-based emulsifiers delay product launches by 18-36 months versus legacy ingredient approvals.
Strategic Opportunities
- Cell-cultured fat integration:Precision fermentation-derived lipids offer emulsion functionality without conventional slaughter supply chain dependencies, attracting sustainability-focused retail channels.
- Integrated taste-nutrition platforms:Formulation suppliers bundling emulsifiers, stabilizers, and flavor masking systems capture higher share of wallet from R&D-constrained mid-tier processors.
- Reduced-fat meat system expansion:Oilseed-derived lecithin and specialty lipid portfolios address structural integrity challenges in sub-10% fat emulsion products for health-positioned retail lines.
Industry Challenges
- Reformulation technical expertise scarcity:Meat processors lack in-house capability to balance clean-label binder substitution with shelf-life and texture specifications, creating dependency on supplier technical service.
- Dual regulatory compliance burden:Simultaneous USDA FSIS label standards and EFSA food improvement agent requirements force parallel formulation tracks for transatlantic product lines.
- Legacy equipment retrofit costs:High-shear processing upgrades require capital deployment incompatible with depreciation schedules at family-owned European sausage operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat Emulsions Market |
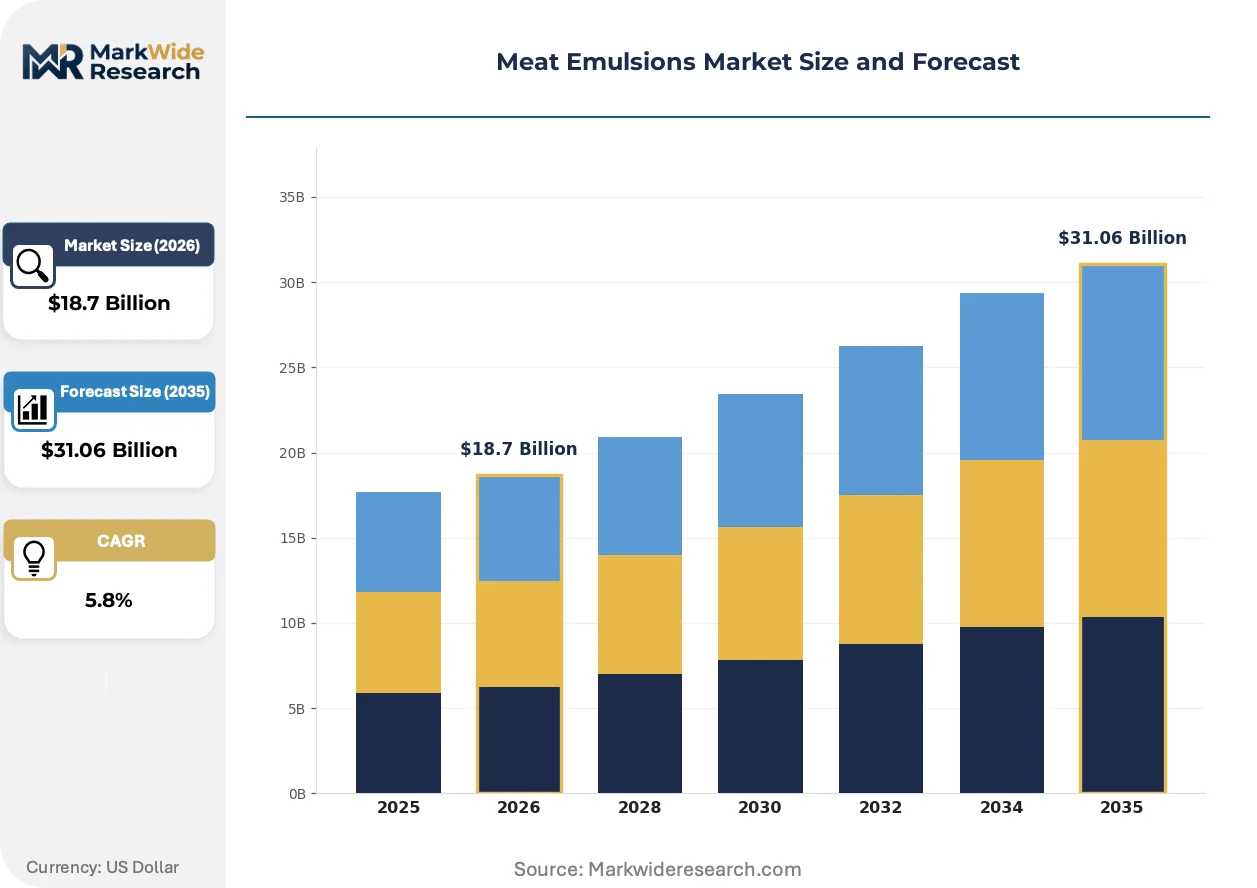
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion Sausages, Spreadable Products, Coatings, Fillings Application: Food Services, Retail, Processed Meats, Confectionery End User: Restaurants, Supermarkets, Food Manufacturers, Caterers Ingredient Type: Meat, Fats, Emulsifiers, Flavorings |
| Companies Covered | Cargill, Incorporated, ADM, Ingredion Incorporated, Kerry Group plc, Corbion, DuPont, BASF SE, Palsgaard, International Flavors & Fragrances Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Emulsions Market Shifts & Advancements
Electromechanical processing advances and regulatory chemistry restrictions are converging to transform how fat-protein matrices achieve stability, with equipment manufacturers and ingredient suppliers racing to deliver integrated solutions.
High-pressure processing technology is decentralizing emulsion stabilization away from chemical additive dependence by deploying isostatic pressure to achieve microbial reduction and protein denaturation simultaneously. Mid-sized European sausage manufacturers are adopting HPP retrofit units at accelerating rates. This shift is decentralizing formulation control from centralized R&D laboratories toward plant-floor process engineering decisions.
REACH authorization restrictions on synthetic phosphate variants are compelling reformulation investments across EU-based meat processing operations. The industrial consequence is accelerated R&D allocation toward seaweed-derived alginate and citrus fiber binding systems. Spreadable meat product categories in Benelux retail channels are most affected, with manufacturers accelerating natural phosphate alternative trials ahead of 2026 regulatory review deadlines.
Ingredient bundling contracts are consolidating procurement decisions around suppliers capable of delivering emulsifier-stabilizer-flavor integrated systems rather than discrete component sourcing. Large food manufacturers are displacing multi-vendor arrangements with single-source formulation partnerships. This concentration is most visible in North American prepared foods segments, where procurement teams prioritize technical service bandwidth over unit cost minimization.
Meat Emulsions Market Segmentation
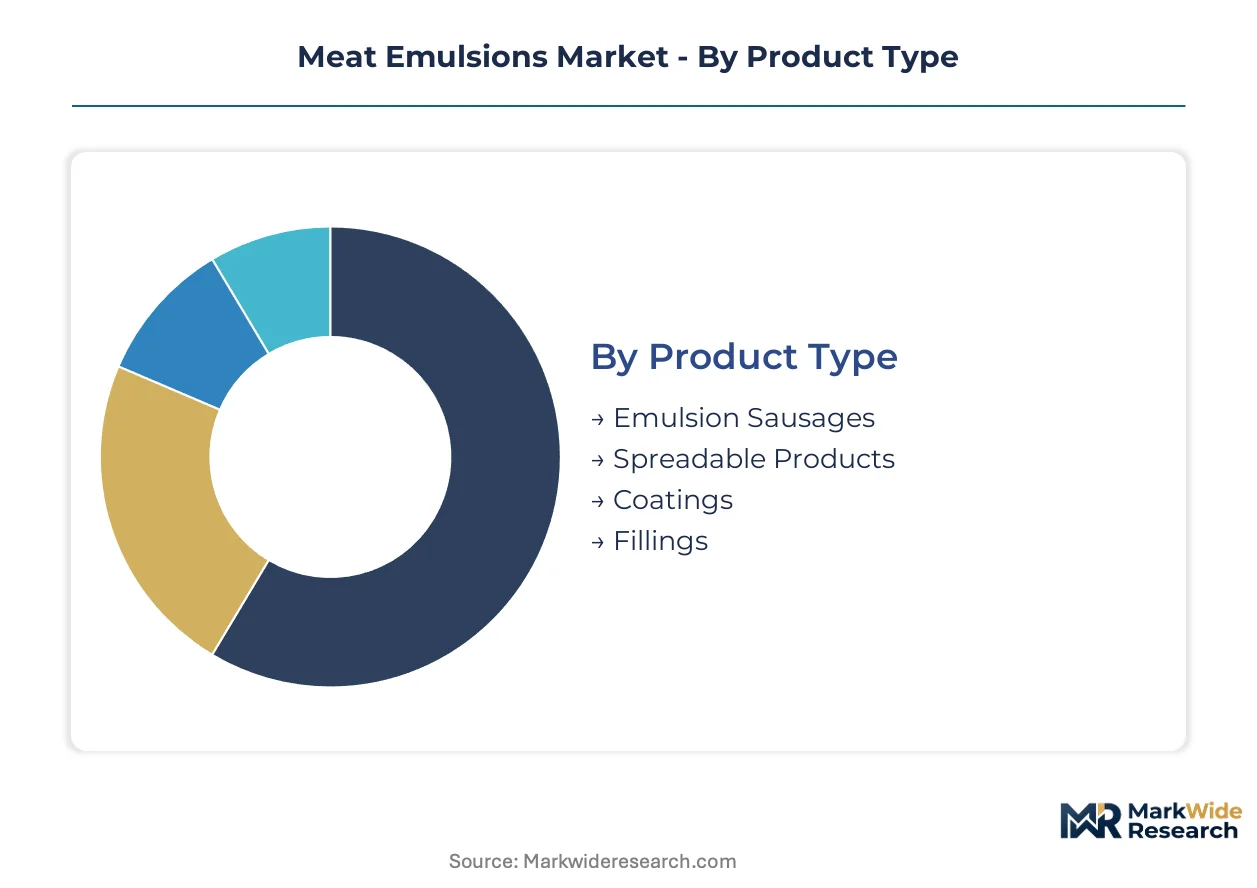
Meat emulsions demand fragments across formulation complexity tiers, from single-ingredient commodity blends to multi-component stabilized systems. Procurement patterns diverge sharply between industrial manufacturers seeking integrated ingredient platforms and food service operators purchasing finished emulsion bases.
Product Type:
Standalone emulsion formats dominate high-volume manufacturing, while embedded emulsion systems integrate into broader ingredient portfolios for specialized applications.
- Emulsion Sausages:These products achieve colloidal stability through finely comminuted fat dispersed below 50 microns within a continuous protein matrix, ensuring thermal integrity and sliceability after cooking. German sausage manufacturers in Bavaria and Lower Saxony anchor procurement volume, driven by traditional consumption patterns and dense industrial processing infrastructure.
- Spreadable Products:Higher fat-phase ratios and reduced protein content characterize these emulsions, requiring specialized stabilizer systems to prevent syneresis during shelf life. Benelux retail channels command premium positioning here, with clean-label reformulations accelerating ahead of EU Green Deal synthetic phosphate reduction targets.
- Coatings:Functional batters and breading adhesives employing emulsion chemistry for substrate binding.
- Fillings:Pumpable emulsion matrices for stuffed meat products and prepared food applications.
Volume placements concentrate in Emulsion Sausages; the faster expansion belongs to Spreadable Products.
Application:
Cost-tier stratification separates commodity-scale industrial buyers from premium-positioned retail and food service channels with divergent technical service requirements.
- Processed Meats:Industrial-scale emulsion production for sausage, pâté, and restructured meat categories demands high-throughput stabilizer systems with consistent functional performance. Food manufacturers in Germany and France drive specification development, pressured by EFSA additive authorization pathways and Farm to Fork synthetic reduction mandates.
- Food Services:Prepared emulsion bases and portion-controlled formats reduce labor and equipment requirements for commercial kitchens. North American contract catering and institutional feeding operations favor phosphate-free clean-label options despite 15-40% cost premiums over conventional systems.
- Retail:Branded consumer packaged goods with extended shelf-life requirements.
- Confectionery:Specialized fat-based emulsions for meat-adjacent savory applications.
Processed Meats captures the dominant procurement volume; Food Services is climbing the fastest as labor constraints reshape commercial kitchen operations.
End User:
Customer-type concentration favors large-scale manufacturing accounts with technical integration capabilities over fragmented food service operators.
- Food Manufacturers:These integrated processors specify emulsion ingredient systems rather than discrete components, bundling emulsifiers, stabilizers, and flavor masking into single-source procurement contracts. North American prepared foods segments prioritize supplier technical service bandwidth over unit cost minimization, consolidating vendor relationships around formulation partnerships.
- Supermarkets:Private-label processed meat programs require emulsion systems balancing clean-label positioning with margin constraints. European retail chains face compressed economics from natural hydrocolloid cost premiums, forcing trade-offs between phosphate-free claims and price competitiveness.
- Restaurants:Independent and chain food service operations purchasing finished emulsion products.
- Caterers:Event and institutional feeding services with batch-scale requirements.
Food Manufacturers command the deepest procurement relationships; Supermarkets are gaining share fastest as private-label clean-label programs expand.
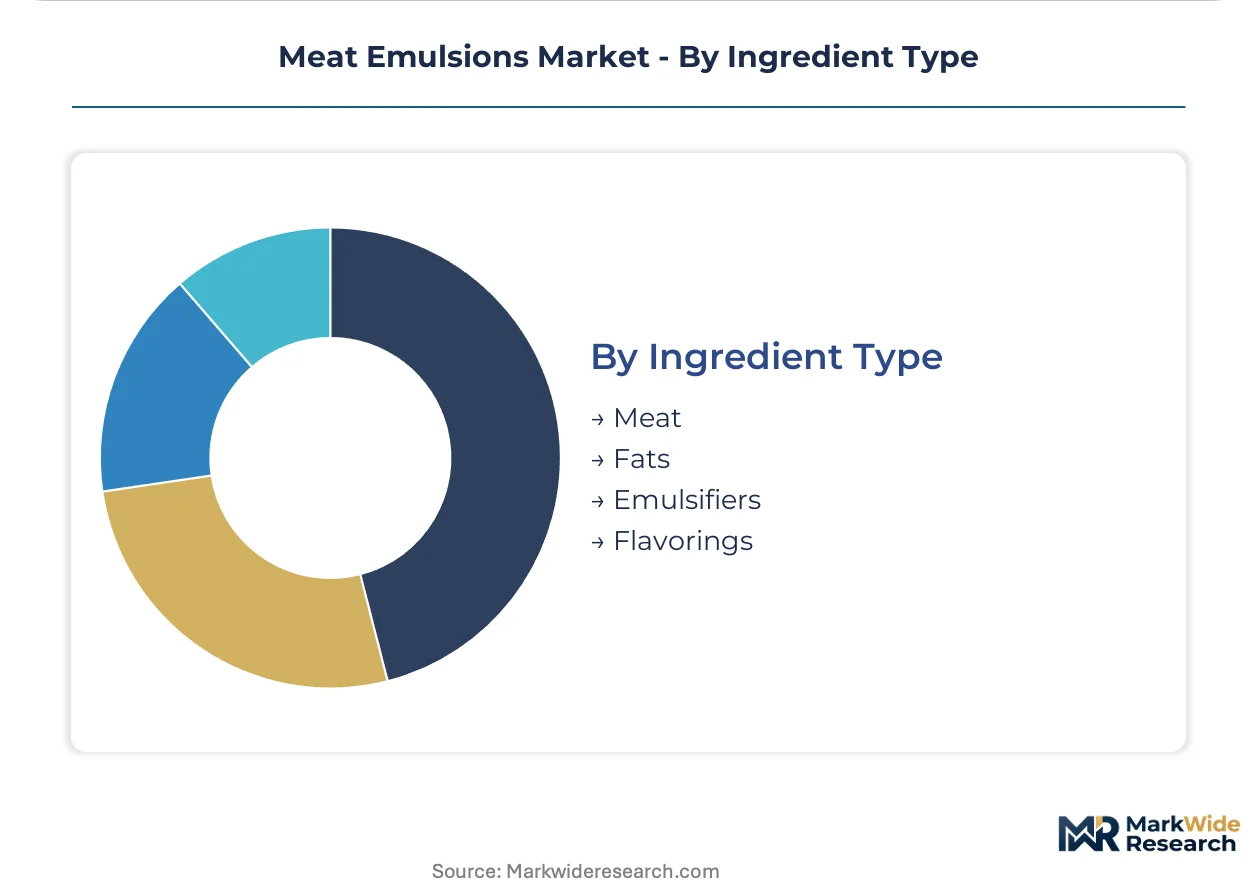
Ingredient Type:
Supply-side concentration in grain and oilseed processing shapes availability and pricing dynamics for critical functional components.
- Emulsifiers:Modified starches, lecithin derivatives, and specialty lipids anchor emulsion stability across reduced-fat and clean-label formulations. Oilseed-derived lecithin portfolios from major processors address structural integrity in sub-10% fat systems for health-positioned retail lines.
- Fats:Animal-derived and vegetable lipid sources provide the dispersed phase for protein matrix entrapment, with precision fermentation alternatives emerging for sustainability-positioned channels.
- Meat:Muscle protein fractions supplying the continuous phase emulsion structure.
- Flavorings:Taste and aroma systems integrated into emulsion stabilizer platforms.
Emulsifiers attract the most intensive R&D investment; Fats sees the steepest expansion trajectory from cell-cultured lipid integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest grain belts anchor global emulsifier supply chains, while European meat processing clusters drive formulation demand. Procurement patterns concentrate in three distinct geographies defined by feedstock access, regulatory pressure, and industrial meat traditions.
Germany
Bavarian sausage manufacturers and Lower Saxony processing plants sustain the densest emulsion ingredient procurement in Europe. EFSA food improvement agent regulations and EU Green Deal Farm to Fork mandates accelerate phosphate-free reformulation trials ahead of 2026 deadlines. Frankfurt-Rhine-Main logistics corridors concentrate distribution infrastructure for hydrocolloid stabilizers.
United States
USDA FSIS inspection protocols govern emulsion composition standards across industrial meatpacking corridors in Iowa, Nebraska, and Illinois. Modified starch supply concentration in the Midwest grain belt limits alternative sourcing during harvest volatility periods. Chicago-based procurement teams prioritize integrated emulsifier-stabilizer-flavor systems from suppliers with captive grain processing assets.
France
Charcuterie traditions in the Massif Central and Brittany sustain demand for premium spreadable emulsion products. REACH authorization restrictions on synthetic phosphate variants compel R&D investment in alginate and citrus fiber binding systems. Lyon and Paris basin food technology clusters host reformulation technical service centers serving pan-European accounts.
Netherlands
Benelux retail channels command premium positioning for clean-label spreadable meat emulsions with extended shelf-life requirements. EFSA novel food additive evaluation timelines delay plant-based emulsifier launches by 18-36 months versus legacy approvals. Wageningen food research corridors anchor ingredient innovation partnerships between suppliers and mid-sized processors.
China
Domestic meat processing expansion in Shandong and Henan provinces generates procurement volume for cost-optimized emulsion stabilizers. SAMR food additive standards and GB quality benchmarks govern import substitution strategies for modified starch and lecithin derivatives. Yangtze River Delta distribution hubs concentrate foreign ingredient supplier technical service operations.
Meat Emulsions Market Competitive Landscape
Global majors compete with regional champions across integrated formulation platforms versus discrete component supply. The vendor base structures around three tiers: grain-to-protein pipeline operators with captive starch assets, integrated taste-nutrition platforms bundling multi-functional systems, and oilseed processors leveraging lecithin and specialty lipid portfolios. Dominant competitive moves include backward integration into grain processing and single-source formulation partnerships displacing multi-vendor arrangements.
Within the integrated platform tier, Cargill, Incorporated and Kerry Group plc exemplify divergent paths to formulation leadership. Cargill leverages Midwest grain belt concentration for captive modified starch supply to meat processing accounts. Kerry Group plc occupies a position across European and North American meat accounts through bundled emulsifier-stabilizer-flavor systems. ADM represents the oilseed-derived specialist archetype, anchoring reduced-fat emulsion functionality through lecithin and specialty lipid portfolios.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| ADM |
| Ingredion Incorporated |
| Kerry Group plc |
| Corbion |
| DuPont |
| BASF SE |
| Palsgaard |
| International Flavors & Fragrances Inc. |
| Others |
Supply & Pricing Matrix
Captive grain-to-starch processing in the North American Midwest anchors both supply security and pricing leverage for major emulsion stabilizer suppliers. This backward integration into corn and wheat processing assets allows Cargill and Ingredion to buffer procurement costs for meat processors while commanding premium positioning on technical service-bundled contracts.
Pricing Analysis
Technical service bundling separates integrated formulation partnerships from commodity component transactions, with the former commanding 15-40% premiums over discrete ingredient sourcing. Price differentiation hinges on clean-label certification tiers and volume scale, with private-label supermarket programs facing acute cost compression from natural hydrocolloid premiums. Pricing pressure intensifies in spreadable product categories as EU Green Deal phosphate reduction deadlines approach. Food manufacturers with captive R&D capabilities exhibit lowest price sensitivity; family-owned sausage operations in Bavaria show highest sensitivity due to legacy equipment depreciation constraints.
Supply Chain Analysis
Freight costs from Midwest grain belt processing centers to European meat clusters constitute a structural cost layer that regional suppliers exploit. Supply concentrates in the United States, Germany, and the Netherlands for hydrocolloid stabilizers and modified starches. Raw material dependencies rest on corn and wheat feedstocks, oilseed lecithin derivatives, and seaweed-derived alginates. Single-source vulnerability runs through Midwest grain processing consolidation during harvest volatility periods. Distribution runs through Frankfurt-Rhine-Main logistics corridors for European accounts and Chicago-based procurement hubs for North American meatpacking corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label reformulation mandates and extended EFSA additive approval timelines are forcing consolidation among mid-tier ingredient suppliers lacking integrated technical service platforms.
For Market Incumbents: Lock in formulation partnerships with mid-sized European sausage manufacturers before REACH authorization restrictions on synthetic phosphates fully phase in. Prioritize captive supply investments in alginate and citrus fiber binding systems to offset grain belt harvest volatility. Defend margin position through exclusive bundling contracts that displace multi-vendor arrangements in North American prepared foods segments. For New Entrants and Emerging Players: Mid-tier French charcuterie processors represent the most penetrable buyer archetype, as these operators lack in-house reformulation expertise for phosphate-free binding systems. White-space opportunities concentrate in precision fermentation-derived lipid emulsifiers for sustainability-positioned retail channels and HPP-compatible clean-label stabilizers. A technical service-heavy go-to-market approach targeting Lyon food technology clusters bypasses direct competition with grain-belt majors. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated taste-nutrition platforms seeking alginate and citrus fiber R&D capabilities. Long-term viability favors suppliers with demonstrated EFSA novel food additive navigation and established relationships with German sausage manufacturers. Watch for inflection when EU Green Deal synthetic phosphate reduction targets accelerate ahead of stated deadlines, compressing margins for non-compliant ingredient portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alginate Sourcing | Seaweed supply agreements with Norwegian and French coastal processors secure phosphate-free binding capacity ahead of EU regulatory deadlines. |
| Integrated Taste-Nutrition Platform Expansion | Bundled emulsifier-stabilizer-flavor systems capture higher share of wallet from R&D-constrained mid-tier meat processors. |
| High-Pressure Processing Equipment Partnership | Collaboration with HPP unit manufacturers decentralizes formulation control toward plant-floor engineering decisions in European sausage operations. |
| Cell-Cultured Lipid Emulsifier Development | Precision fermentation-derived fats attract sustainability-focused retail channels seeking slaughter-independent supply chains. |
| EFSA Regulatory Affairs Capability Buildout | Dedicated novel food additive submission teams compress 18-36 month approval timelines for plant-based emulsifier launches. |
Research Methodology
Independent corroboration across primary interviews with meat processing R&D directors, ingredient procurement managers, and EFSA regulatory consultants underwrites the qualitative findings. Secondary validation draws from USDA FSIS labeling guidance documents, EFSA food improvement agent registers, EU Green Deal Farm to Fork strategy publications, and trade data from German meat industry associations. Bottom-up demand modeling triangulates against top-down supply-side capacity assessments across Midwest grain processing and European hydrocolloid extraction facilities.
Comparable-period anchoring to historical emulsion stabilizer demand patterns across the analysis window informs projection elasticity assumptions. The analytical framework segments by product type, application tier, end-user scale, and ingredient technology platform. CAGRs derive from regression-adjusted trend extrapolation incorporating regulatory timeline acceleration risks and clean-label adoption curve inflections. Industry-specific inputs include EFSA novel food additive pipeline status and HPP equipment installation rates at mid-sized European processors.
Revisions become necessary when EU Green Deal implementation timelines accelerate, EFSA approves disruptive plant-based emulsifiers ahead of schedule, or Midwest grain belt harvest volatility disrupts modified starch supply. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Lab-Grown Meat Market
Meat Products
Grass-Fed Meat Market
Meat Products
Vegan Meatball Market
Meat Products
Meat Products Market
Meat Products
Bahrain Poultry Meat Market
Meat Products
Sausage Premixes Market
Meat Products
Beef Fat Market
Meat Products
Pepperoni Foods Market
Meat Products
Pork Meat Market
Meat Products
Europe Canned Meat Market
Meat Products
Beef Jerky Market
Meat Products
Organic Eggs Market
Meat Products
Hams Market
Meat Products
Saudi Arabia Red Meat Market
Meat Products
Middle East Edible Meat Market
Meat Products
Organic Meat Products Market