
 Grassfed Jerky Market | 2026-2036
Grassfed Jerky Market Size, Share, and Industry Trends Forecast 2026-2036
Grassfed Jerky Market Analytics
Single-serve portion packs and protein-bundle assortments is restructuring how consumers evaluate grassfed jerky at point of purchase. Chomps leverages direct-to-consumer subscription models to sustain recurring revenue from paleo and Whole30 adherents. KRAVE anchors its presence through premium placement in specialty retail channels with curated flavor rotations. Pearson Ranch competes on heritage ranching credentials and transparent sourcing narratives that resonate with ethically motivated buyers.
Grassfed jerky comprises dried, cured meat strips derived from cattle raised on pasture-based diets without grain finishing, typically processed through low-temperature dehydration or smoke curing to preserve protein integrity while minimizing synthetic preservatives. The product serves commercial purposes across convenience snacking, sports nutrition, and clean-label retail segments where protein density and minimal ingredient lists drive purchasing decisions. Beef dominates product type revenue due to established consumer familiarity and scalable ranching infrastructure, while bison captures premium margin pools through scarcity positioning and perceived nutritional superiority. Online retail represents the fastest-growing distribution channel as digitally native brands bypass traditional slotting fees and capture first-party consumer data.
USDA Organic certification and FSIS labeling standards govern product claims and facility inspection protocols for domestic manufacturers, while FDA nutrition labeling rules shape front-of-package communication strategies. The EU Green Deal's Farm to Fork strategy and EFSA novel food assessments create compliance complexity for export-oriented producers seeking European market access. Stakeholders must monitor evolving definitions of grassfed claims across jurisdictions as litigation risk around labeling accuracy intensifies and consumer protection agencies scrutinize sustainability assertions.
Market Dynamics
Clean-label certification requirements and pasture-based supply chain constraints are forcing manufacturers to consolidate ranching partnerships while reformulating around minimal-ingredient protocols that satisfy both USDA Organic standards and paleo-dietary adherents.
Growth Catalysts
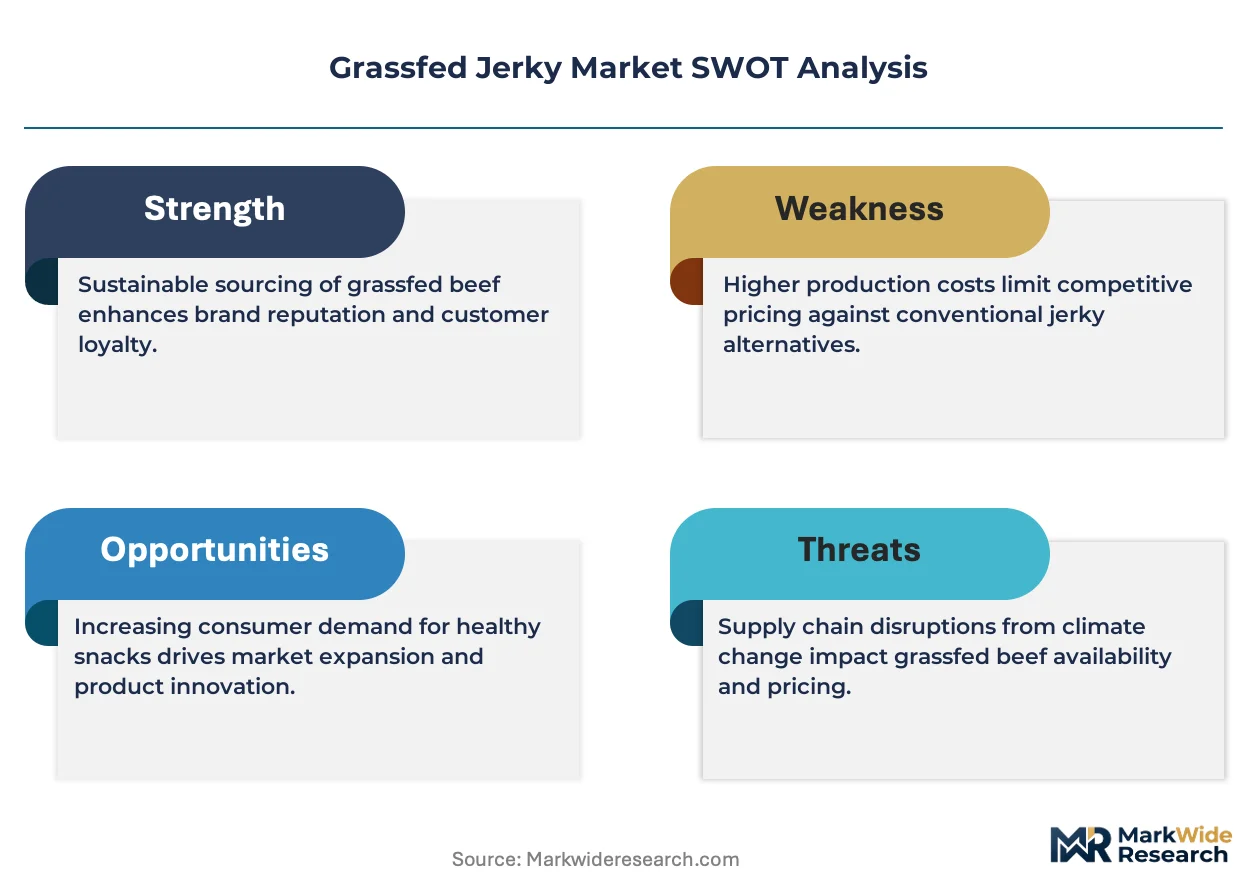
- USDA Organic certification mandates:Federal labeling standards for grassfed claims create competitive moats for compliant processors while filtering out unsubstantiated marketing assertions.
- Sports nutrition segment expansion:Fitness enthusiasts seeking portable protein sources with minimal processing drive repeat purchase velocity in specialty retail and direct-to-consumer channels.
- Pasture-raised cattle supply concentration:Texas and Colorado ranching corridors provide scalable, traceable raw material inputs that anchor domestic production capacity.
Market Restraints
- Input cost volatility:Drought cycles and hay price fluctuations in Great Plains grazing regions compress processor margins during climate-stressed growing seasons.
- Supply concentration risk:Dependence on limited certified-grassfed slaughterhouse capacity creates processing bottlenecks during peak harvest windows.
- Regulatory friction:EFSA novel food assessments and EU Green Deal Farm to Fork compliance complexity block export expansion into European retail channels.
Strategic Opportunities
- Underpenetrated European markets:German and Dutch clean-label retail channels present first-mover openings for certified exporters navigating EFSA registration pathways.
- Functional ingredient convergence:Collagen-fortified and adaptogen-infused jerky formats capture wellness-oriented consumers seeking beyond-protein benefits.
- Subscription commerce channels:Direct-to-consumer replenishment models bypass slotting fee structures while capturing first-party consumption data.
Industry Challenges
- Certification timeline compression:USDA Organic and American Grassfed Association dual-certification processes extend product development cycles by 8-14 months.
- Smoke point control expertise gap:Low-temperature dehydration specialists command premium wages as traditional meat processors retool for minimal-thermal-damage protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grassfed Jerky Market |
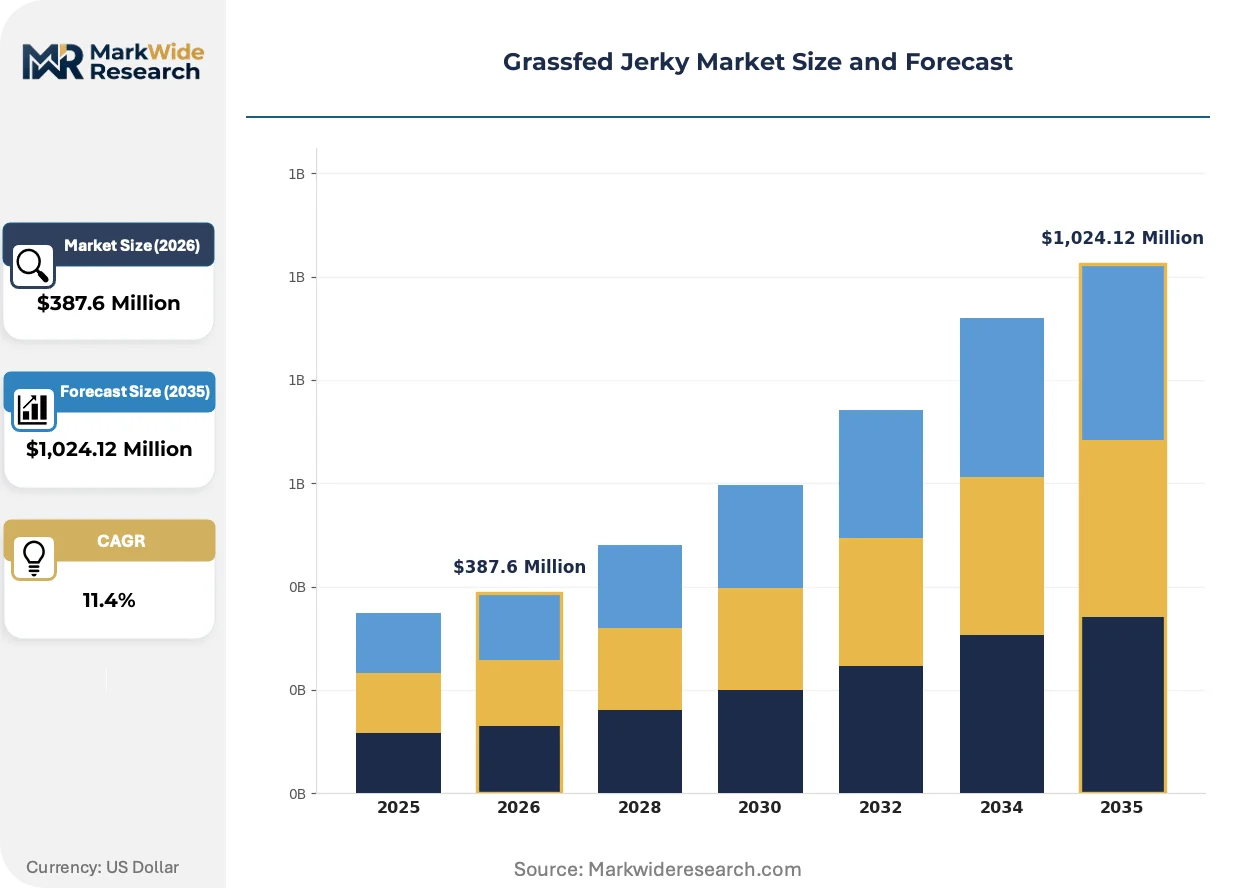
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Turkey, Bison, Pork Flavor Profile: Original, Teriyaki, Spicy, BBQ Packaging Type: Resealable Bags, Vacuum-Sealed Packs, Canisters, Singles Distribution Channel: Online Retail, Grocery Stores, Convenience Stores, Specialty Shops |
| Companies Covered | Archer Provisions, Chomps, KRAVE, Think Jerky, Jerky’s Gourmet, Cattaneo Bros., Pearson Ranch, Ripped Jerky, Starwalker Organic Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grassfed Jerky Market Evolving Landscape
Refrigerated supply chain compression and digital-native brand building are dismantling traditional wholesale-retail gatekeeping structures while enabling transparent sourcing narratives that command price premiums.
Precision low-temperature dehydration technology is decentralizing protein preservation capabilities away from centralized smokehouse infrastructure. Regional processors in Montana and Wyoming are adopting vacuum-assisted drying systems that preserve amino acid profiles while reducing synthetic preservative dependence. This equipment diffusion is compressing minimum viable scale thresholds and enabling ranch-direct processing models.
EU Green Deal Farm to Fork strategy implementation is tightening residue monitoring protocols for imported meat products. European retailers now require third-party carbon footprint verification alongside traditional safety certifications. American exporters targeting Dutch and German channels are retrofitting supply chain documentation systems to satisfy CSRD-aligned disclosure requirements.
Paleo and Whole30 adherents are bypassing conventional grocery placement through curated subscription assortments. Direct-to-consumer platforms now bundle jerky with complementary clean-label snacks, displacing single-category impulse purchases. This behavioral pivot concentrates highest lifetime-value customers in digitally native channels rather than mass retail.
Grassfed Jerky Market Segmentation
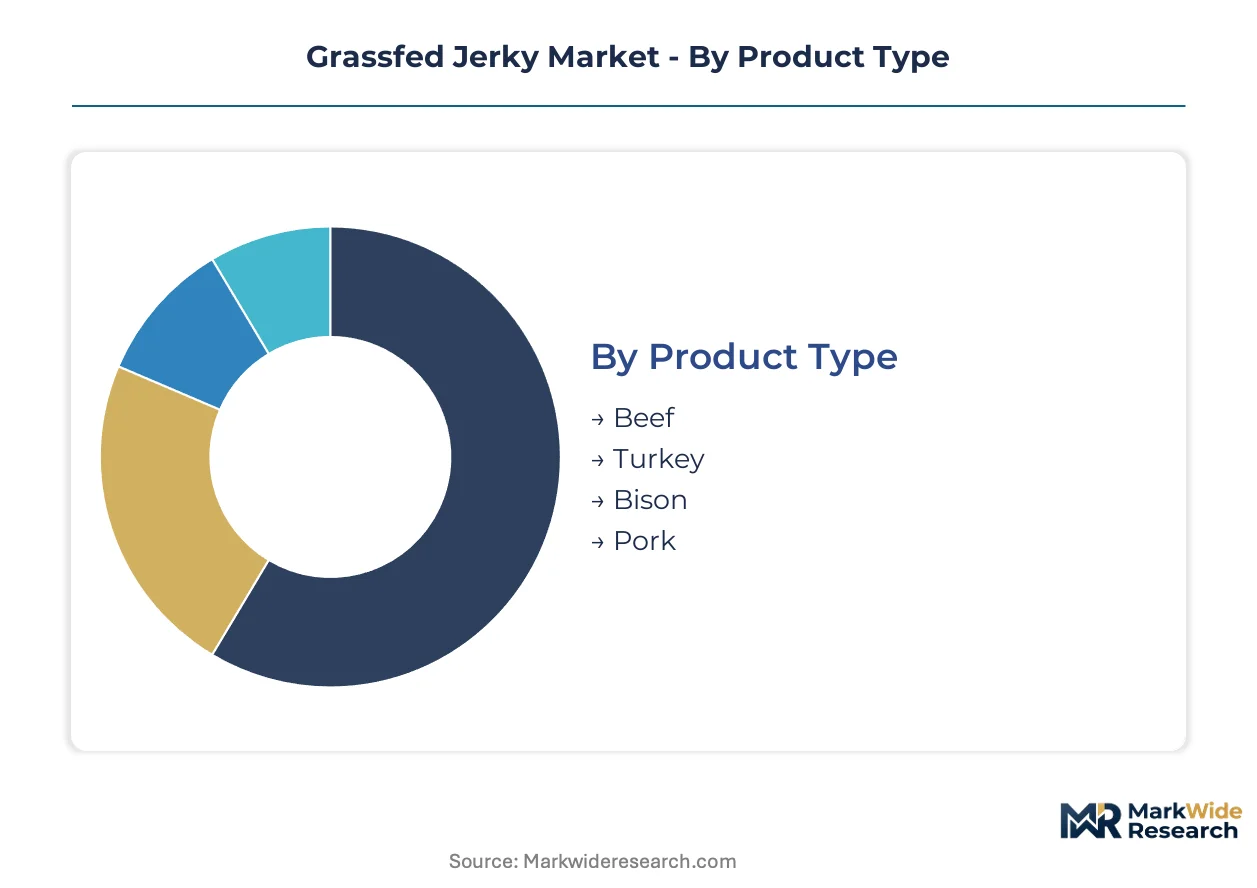
Grassfed jerky segmentation reveals how protein sourcing, flavor innovation, and channel strategy create distinct competitive battlegrounds. Manufacturers optimize formulations and packaging formats against specific consumption occasions and retail environments.
Product Type:
Upgrade cycles in grassfed jerky track shifting protein preferences as consumers rotate between familiar beef formats and emerging alternatives seeking nutritional differentiation or novelty.
- Beef:Derived from pasture-raised cattle finished without grain supplementation, delivering complete amino acid profiles and established consumer recognition. Demand concentrates in Texas and Colorado ranching corridors where certified-grassfed slaughterhouse capacity anchors scalable supply chains constrained by drought-cycle hay price volatility.
- Bison:Sourced from free-range herds on native prairie grasses, offering lower fat content and higher iron density than conventional beef. Scarcity positioning commands premium shelf placement in specialty retail channels across the Mountain West where tribal and private ranching operations maintain genetic stock isolation.
- Turkey:Lean white meat alternative processed with lower sodium protocols for health-conscious snackers seeking reduced red meat consumption.
- Pork:Pasture-raised heritage breed options capturing niche demand in Appalachian and Midwestern markets with established small-scale hog operations.
Beef sits at the top of the volume ranking, with bison climbing the fastest as scarcity positioning and nutritional density narratives penetrate premium retail channels.
Flavor Profile:
Flavor innovation cycles accelerate as manufacturers test limited-batch releases to capture social media-driven discovery behavior without diluting core SKU productivity.
- Original:Unseasoned or minimally salted formulations highlighting meat quality transparency for paleo and Whole30 adherents prioritizing ingredient list simplicity over taste complexity.
- Teriyaki:Soy-glazed profiles with ginger and garlic notes appealing to Asian-American consumer segments and cross-cultural snack experimentation in West Coast urban markets.
- Spicy:Capsicum-forward heat levels calibrated through habanero, ghost pepper, or cayenne inclusions targeting younger male demographics and craft beer pairing occasions.
- BBQ:Smoked tomato and molasses-based coatings resonating with Midwestern and Southern regional taste preferences anchored in traditional jerky consumption heritage.
Original formulations retain the highest baseline velocity, though spicy variants are gaining share fastest through social media amplification and hot sauce culture crossover.
Packaging Type:
Packaging selection directly shapes margin structure through material cost tiers and inventory velocity implications across temperature-controlled and ambient supply chains.
- Resealable Bags:Multi-serve flexible pouches with zip-lock closures extending shelf life after opening for household pantry storage and portion-controlled consumption.
- Vacuum-Sealed Packs:Oxygen-barrier film eliminating headspace to preserve texture integrity and color stability during extended distribution timelines for export-oriented production.
- Canisters:Rigid container formats with moisture-absorbing inserts supporting countertop merchandising in convenience stores and gas station impulse purchase environments.
- Singles:Individually wrapped one-ounce portions enabling grab-and-go placement at point-of-sale locations and corporate breakroom micro-market penetration.
Resealable bags dominate absolute unit movement, while singles demonstrate the steepest expansion trajectory through micro-market and direct-to-consumer subscription bundle integration.
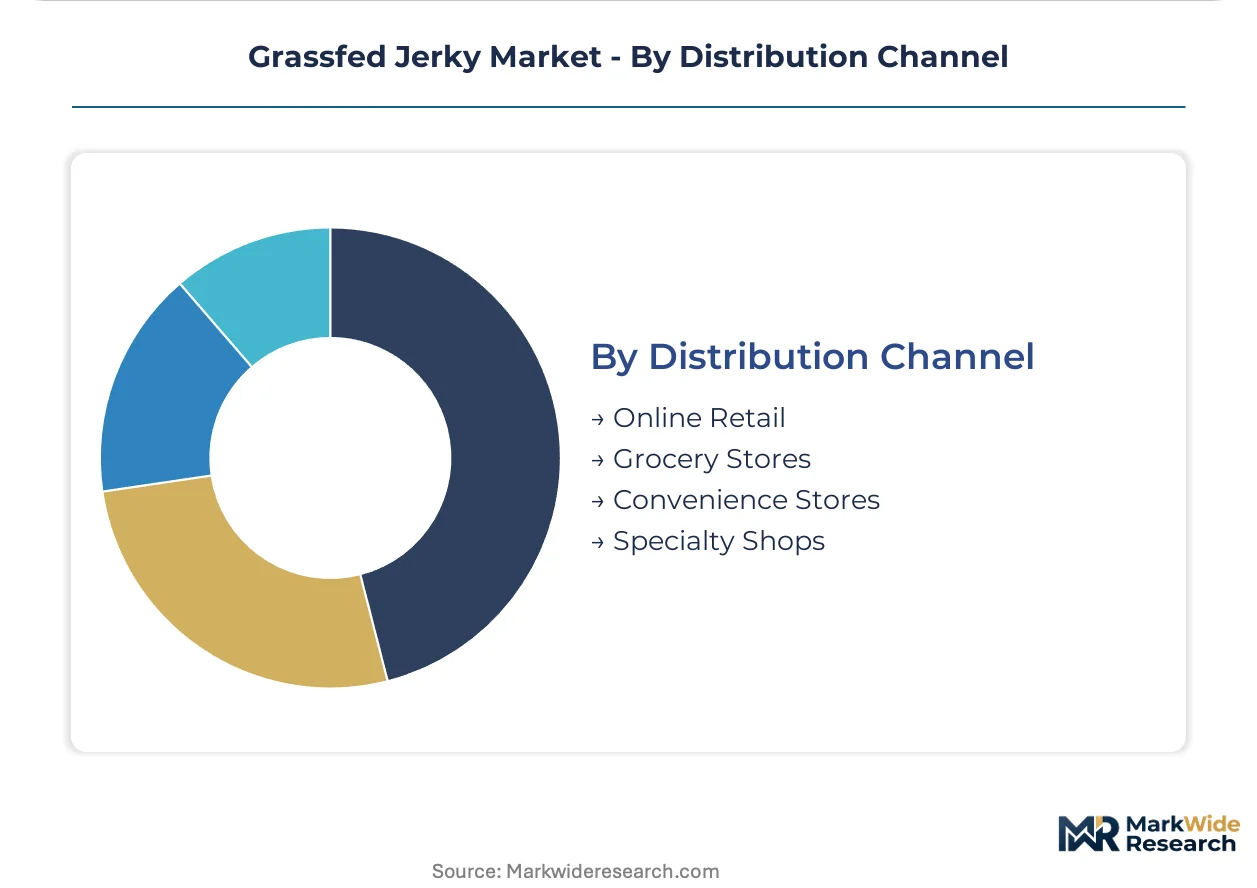
Distribution Channel:
Channel strategy determines pricing architecture and consumer data capture potential as digitally native brands bypass traditional wholesale margin stacking.
- Online Retail:Direct-to-consumer platforms and marketplace listings enabling subscription replenishment models, first-party data harvesting, and flavor customization without slotting fee burdens.
- Grocery Stores:Conventional supermarket placement requiring trade promotion investment and facing competition from private label alternatives in protein snack aisles.
- Convenience Stores:Immediate consumption positioning at fuel retail locations with high foot traffic but limited SKU depth and compressed margin structures.
- Specialty Shops:Curated independent retailers and outdoor recreation outfitters targeting enthusiast segments with premium placement and educated staff recommendation.
Grocery stores maintain the largest revenue footprint, yet online retail is expanding most quickly as subscription mechanics and influencer-driven discovery displace traditional aisle browsing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grassfed jerky production traces its commercial lineage to the American West, where cattle ranching heritage and preservation traditions converged during the late twentieth century to establish the first certified-grassfed supply chains. Texas and Colorado ranching corridors anchored this foundation, with artisanal processors later expanding into adjacent markets seeking premium protein alternatives.
United States
Health-conscious millennials and fitness enthusiasts in metropolitan markets drive sustained demand for portable protein with clean-label credentials. USDA Organic certification and FSIS labeling standards govern domestic manufacturing claims, creating compliance moats for verified processors. Texas and Colorado ranching corridors concentrate certified-grassfed slaughterhouse capacity, though drought cycles periodically compress hay availability and processor margins.
Germany
Clean-label retail channels in Berlin and Hamburg exhibit appetite for American-style protein snacks with verified pasture-raised sourcing. EU Green Deal Farm to Fork strategy implementation tightens residue monitoring and carbon footprint disclosure requirements for imported meat products. Third-party logistics providers in the Netherlands retrofit documentation systems to satisfy CSRD-aligned supply chain transparency mandates for German distribution.
Canada
Paleo and Whole30 adherents in Vancouver and Toronto accelerate adoption of minimal-ingredient jerky formats through direct-to-consumer channels. Health Canada and PMRA establish parallel certification pathways for organic livestock claims that recognize American Grassfed Association standards. Alberta ranching operations explore cross-border processing partnerships to access USDA-inspected facilities and circumvent domestic certified-slaughterhouse bottlenecks.
Australia
Outdoor recreation enthusiasts and sports nutrition consumers in Sydney and Melbourne sustain demand for bison and beef jerky with transparent sourcing narratives. TGA oversight of therapeutic claims and FSANZ food standards shape labeling protocols for functional protein products. Queensland pasture-raised cattle operations develop export-oriented dehydration capacity targeting Asian markets seeking Australian-origin grassfed credentials.
United Kingdom
Specialty retail channels in London and Manchester curate premium jerky assortments for ethically motivated buyers prioritizing heritage ranching narratives. Post-Brexit UKCA marking requirements and retained EU food safety regulations create dual compliance obligations for imported American products. Scottish Highland cattle producers experiment with small-batch jerky processing to capture domestic premium positioning distinct from mass-market alternatives.
Grassfed Jerky Market Competitive Landscape
The competitive structure tilts toward digitally native specialists with direct-to-consumer subscription mechanics. Ranch-direct heritage brands and venture-backed clean-label entrants occupy distinct positioning tiers, with minimal overlap in distribution architecture. Three archetypes dominate: vertically integrated ranch-to-retail operations, subscription-commerce pure-plays, and specialty retail gatekeepers with curated flavor rotations. Consolidation pressure concentrates among mid-scale processors seeking certified-slaughterhouse capacity access, while geographic expansion into European markets demands EFSA registration expertise that few domestic players possess.
Within the subscription-commerce tier, Chomps anchors recurring revenue mechanics for paleo and Whole30 adherents through replenishment models that bypass traditional slotting structures. KRAVE exemplifies specialty retail gatekeeper positioning with premium placement and curated flavor rotations in outdoor recreation channels. Pearson Ranch occupies the heritage ranching archetype, leveraging transparent sourcing narratives that resonate with ethically motivated buyers seeking verified pasture-raised credentials. These three entities collectively illustrate how channel strategy and certification architecture determine competitive moat durability.
| Leading Market Players |
|---|
| Archer Provisions |
| Chomps |
| KRAVE |
| Think Jerky |
| Jerky's Gourmet |
| Cattaneo Bros. |
| Pearson Ranch |
| Ripped Jerky |
| Starwalker Organic Farms |
| Others |
Value Network & Pricing Analysis
Low-temperature dehydration specialists in Montana and Wyoming command premium wages that compress processor margins and widen spreads between artisanal and commodity tiers. Labor-cost differentials between certified-grassfed smokehouse operators and conventional meat processors feed directly into pricing-tier stratification across the market.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates heritage ranch-direct SKUs from regional processor lines and private-label alternatives. Certification grade—USDA Organic and American Grassfed Association dual credentials—drives the widest price spreads, followed by volume scale discounts for subscription replenishment commitments. Pricing pressure stems from drought-cycle hay price volatility in Great Plains grazing regions that squeezes processor margins without full pass-through elasticity. Paleo and Whole30 adherents in direct-to-consumer channels exhibit lowest price sensitivity, while convenience store impulse buyers face highest elasticity.
Supply Chain Analysis
Refrigerated freight costs from Texas and Colorado ranching corridors to coastal distribution centers absorb disproportionate margin share for export-oriented processors. Raw material supply concentrates in United States pasture-based cattle operations, with Alberta ranching partnerships and Queensland export capacity serving secondary sourcing roles. The supply chain rests on certified-grassfed slaughterhouse capacity that bottlenecks during peak harvest windows. Tariff exposure from EU Green Deal carbon footprint verification requirements threatens European market penetration. Distribution runs through direct-to-consumer subscription platforms, specialty retail gatekeepers, and conventional grocery wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grassfed jerky production arbitrages lower pasture-raising costs in Texas and Colorado against premium pricing in German clean-label retail channels where EU regulatory compliance creates import friction. Cost differentials between American ranch-direct processing and European certified-slaughterhouse scarcity support margin capture for compliant exporters.
For Market Incumbents: Cement ranch-direct supply agreements in Montana and Wyoming to lock in low-temperature dehydration capacity before wage inflation spreads. Acquire American Grassfed Association dual-certification expertise to defend against digitally native entrants bypassing traditional slotting structures. Channel control through curated specialty retail placements remains essential as grocery private-label alternatives erode mass-market share.
For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for paleo and Whole30 adherents seeking curated protein bundles. Target German clean-label retail channels through Dutch third-party logistics providers already retrofitting CSRD-aligned documentation systems. Launch with collagen-fortified or adaptogen-infused formats to differentiate beyond commodity protein positioning.
For Investors and Strategic Acquirers: Vertically integrated protein snack conglomerates are the most active acquirer in this space, seeking certified-slaughterhouse access and subscription-commerce mechanics. Mid-scale processors with dual USDA Organic and American Grassfed Association credentials represent the highest-probability acquisition archetype over the coming decade. Watch EFSA novel food registration approval velocity as the critical inflection signal for European market viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ranch-Direct Supply | Captures margin from Texas and Colorado grazing operations while ensuring traceability compliance. |
| Subscription Commerce Platform Launch | Bypasses grocery slotting fees and harvests first-party data from paleo adherents. |
| EFSA Novel Food Registration Pathway | Unlocks German and Dutch retail channels blocked by EU Green Deal residue protocols. |
| Functional Ingredient Format Extension | Collagen and adaptogen infusions capture wellness-oriented consumers beyond protein seekers. |
| Precision Low-Temperature Dehydration Adoption | Vacuum-assisted drying systems in Montana and Wyoming reduce synthetic preservative dependence. |
Research Methodology
Direct dialogue with ranch operations managers, certified-slaughterhouse facility directors, specialty retail category buyers, and direct-to-consumer brand founders grounded qualitative findings in operational reality. Secondary validation drew from USDA FSIS inspection records, FDA nutrition labeling guidance, EU Green Deal Farm to Fork strategy documents, and American Grassfed Association certification databases. Bottom-up ranch capacity assessments and top-down protein snack category sizing were triangulated against trade flow data.
Bottom-up modeling segmented volume and value across product type, flavor profile, packaging format, and distribution channel dimensions, with certification tier as an additional industry-specific stratification. CAGRs were derived from trajectory fitting across the projection horizon. Forecast inputs incorporated drought-cycle hay price volatility patterns and EFSA registration pipeline velocity for European market access scenarios.
The model assumes a particular technology adoption path; alternative pathways for vacuum-assisted precision dehydration would alter the outlook if equipment diffusion accelerates beyond ranch-direct processing economics. Forecasts reflect assumptions about pasture-raised cattle supply stability and EU regulatory friction persistence that drought severity or trade negotiation shifts could revise. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
GCC Edible Meat Market
Meat Products
Hot Dog and Sausages Market
Meat Products
Chicken Fat Market
Meat Products
Saudi Arabia Edible Meat Market
Meat Products
Chicken Buckets Market
Meat Products
Shark Meat Market
Meat Products
Vegan Meatball Market
Meat Products
North America Edible Meat Market
Meat Products
Meat, Poultry and Seafood Market
Meat Products
Animal Protein Market
Meat Products
Middle East Red Meat Market
Meat Products
Low Fat Beef Market
Meat Products
3D Printed Meat Market
Meat Products
Asia-Pacific Red Meat Market
Meat Products
Organic Chicken Market
Meat Products
Meat-Based FPP Market