
 Europe Processed Meat Market | 2026-2036
Europe Processed Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Processed Meat Market Foresight
Foodservice operators are unwinding legacy procurement patterns tied to commodity-grade processed meats. Danish Crown AmbA leverages cooperative sourcing structures to anchor supply across Nordic institutional kitchens. WH Group Ltd sustains vertical integration from European hog farming through branded sausage manufacturing. JBS S.A. competes through scale advantages in fresh-to-processed conversion capacity across Iberian and Benelux plants.
Processed meat comprises muscle tissue subjected to curing, smoking, fermentation, thermal processing, or mechanical restructuring to extend shelf life, enhance flavor, and ensure microbiological safety, with water activity typically controlled below 0.95 for ambient-stable products. Its primary commercial purpose is to deliver standardized protein formats with predictable portioning, preservation, and sensory profiles for retail and foodservice channels. Sausages and bacon occupy the largest volume positions due to breakfast and quick-meal applications across European households, while salami commands premium shelf space in Mediterranean markets where Protected Designation of Origin certifications support price architecture. Modified atmosphere packaging and vacuum packs are displacing conventional tray formats as retailers prioritize extended case-life and reduced shrink in fresh deli counters.
EFSA nitrite exposure assessments and EU Green Deal methane benchmarks are forcing reformulation investments and supplier audit intensification across the value chain. ECHA REACH compliance for processing aids and packaging migrants adds secondary compliance layers for imported casings and barrier films. Stakeholders must monitor whether the EU AI Act's forthcoming food-chain traceability mandates will require retrofitting legacy batch-tracking systems before enforcement timelines crystallize.
Market Dynamics
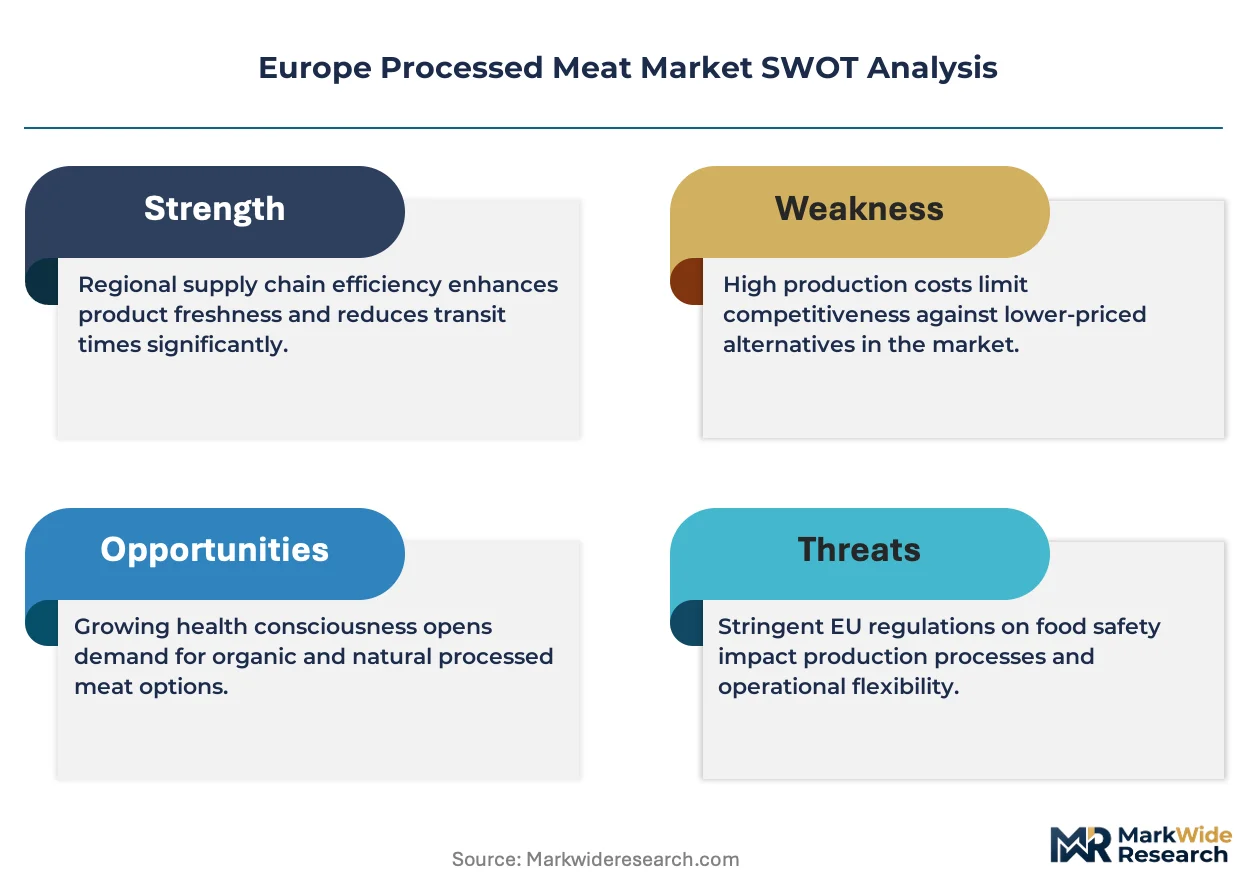
EFSA nitrite exposure limits and EU Green Deal methane benchmarks are forcing simultaneous reformulation of curing protocols and carbon accounting across European processing plants. This dual compliance pressure is compressing margins while accelerating supplier consolidation around audited cold-chain networks.
Growth Catalysts
- Foodservice premiumization:Institutional kitchens across Germany, France, and Italy are expanding procurement of Protected Designation of Origin charcuterie and artisanal smoked varieties for menu differentiation.
- REACH compliance infrastructure:ECHA mandates for processing aids and packaging migrants are creating competitive moats for processors with in-house analytical laboratories and regulatory affairs capabilities.
- Modified atmosphere packaging:Retailers in northern Italy's charcuterie corridor are adopting vacuum and gas-flushed formats to extend case-life and reduce deli-counter shrink.
Market Restraints
- Feed grain price volatility:Hog farming input costs fluctuate with Ukrainian grain export disruptions, compressing processor margins on fresh-to-processed conversion.
- Nordic supply concentration:Danish Crown AmbA's cooperative sourcing dominance creates procurement bottlenecks for foodservice operators seeking supply diversification.
- Nitrite reduction technical ceiling:EFSA exposure assessments are approaching microbiological safety thresholds that limit further clean-label reformulation without shelf-life trade-offs.
Strategic Opportunities
- Eastern European cold-chain expansion:Poland and Romania present underpenetrated retail and foodservice channels for premium cured meat distribution.
- EU AI Act traceability mandates:Early compliance with forthcoming batch-tracking requirements will differentiate processors in tender processes for institutional procurement.
- Plant-protein hybrid convergence:Blended meat-vegetable formulations using fermentation-derived binders address flexitarian demand without full substitution.
Industry Challenges
- Legacy ERP integration:Retrofitting batch-tracking systems for EU AI Act compliance creates data migration friction and downtime risk during enforcement windows.
- Specialized smokehouse engineering:Traditional curing facilities face capex intensity for emission controls and energy efficiency upgrades under CSRD reporting requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Processed Meat Market |
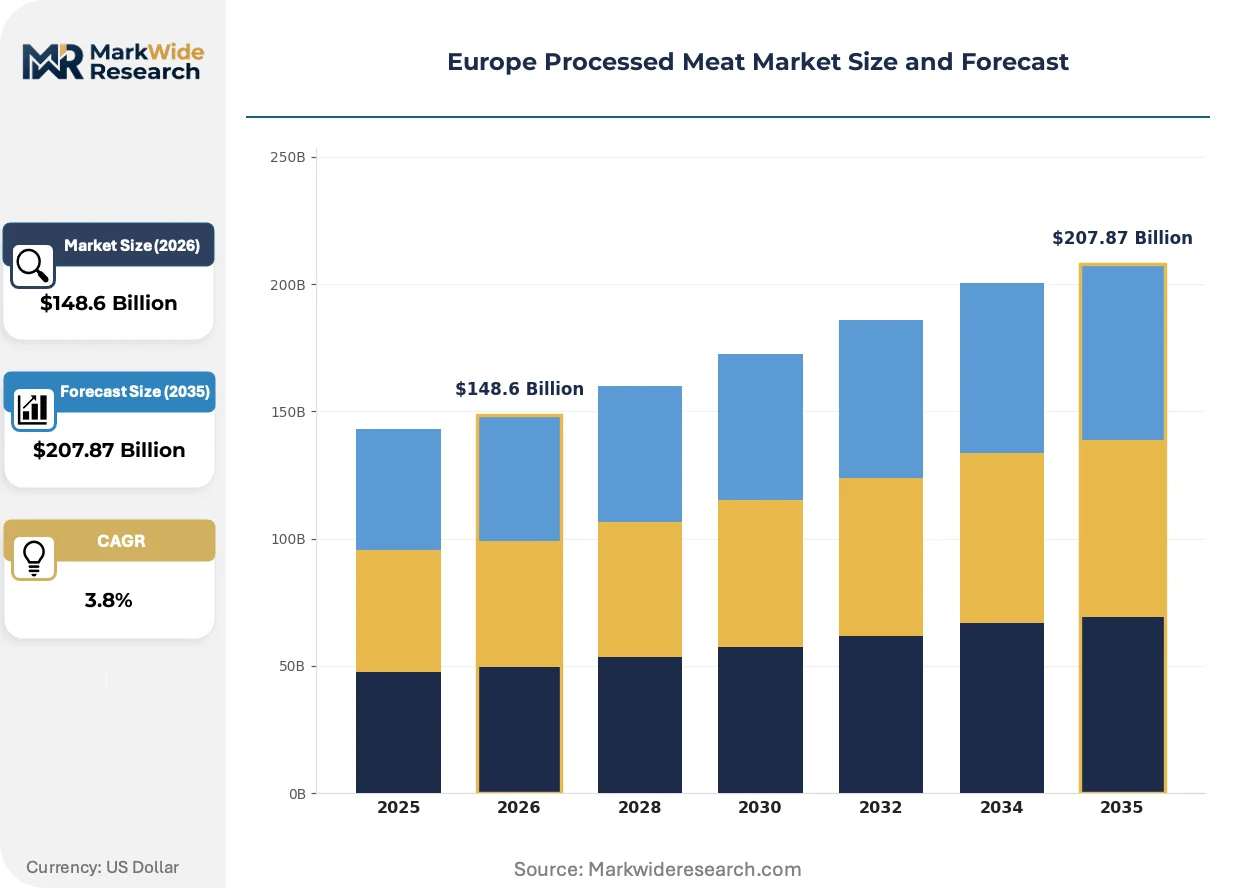
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $207.87 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
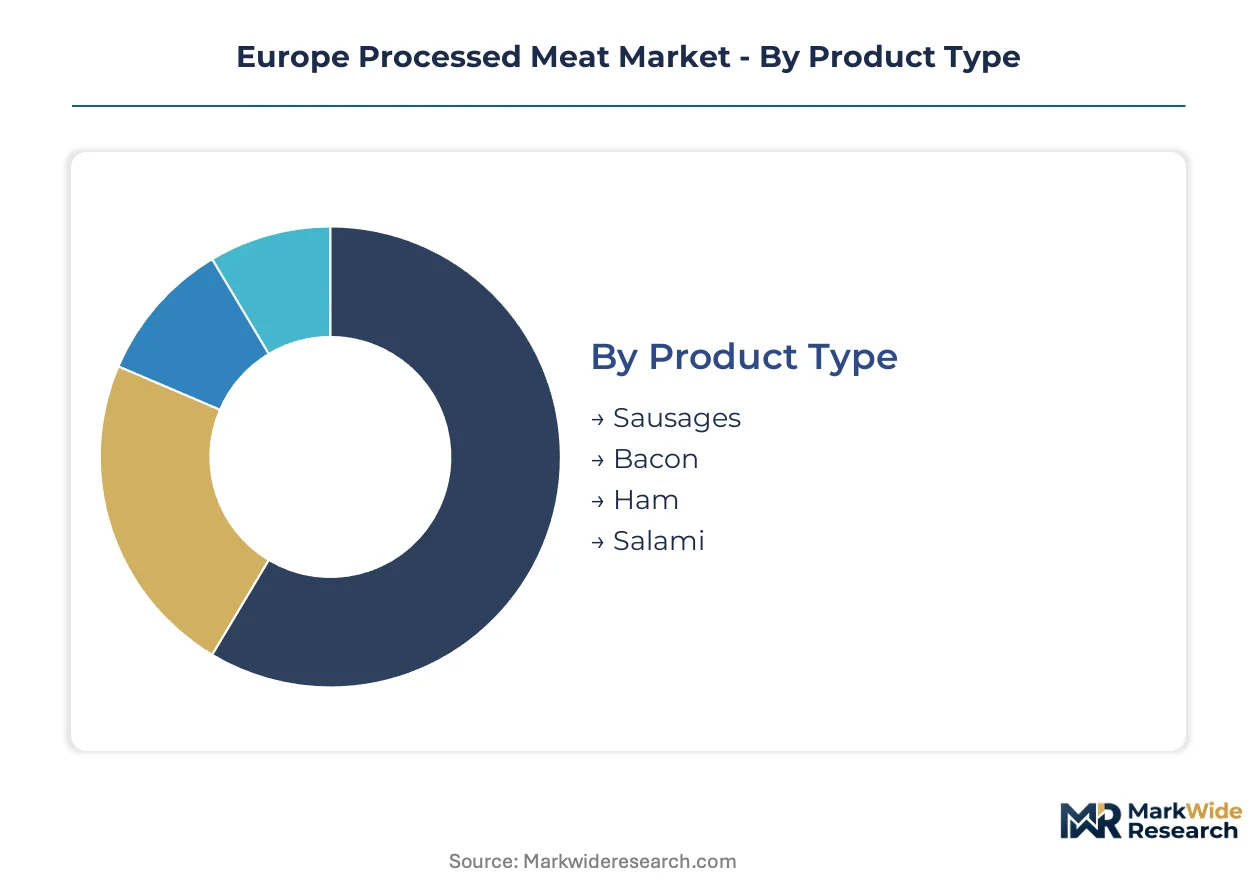
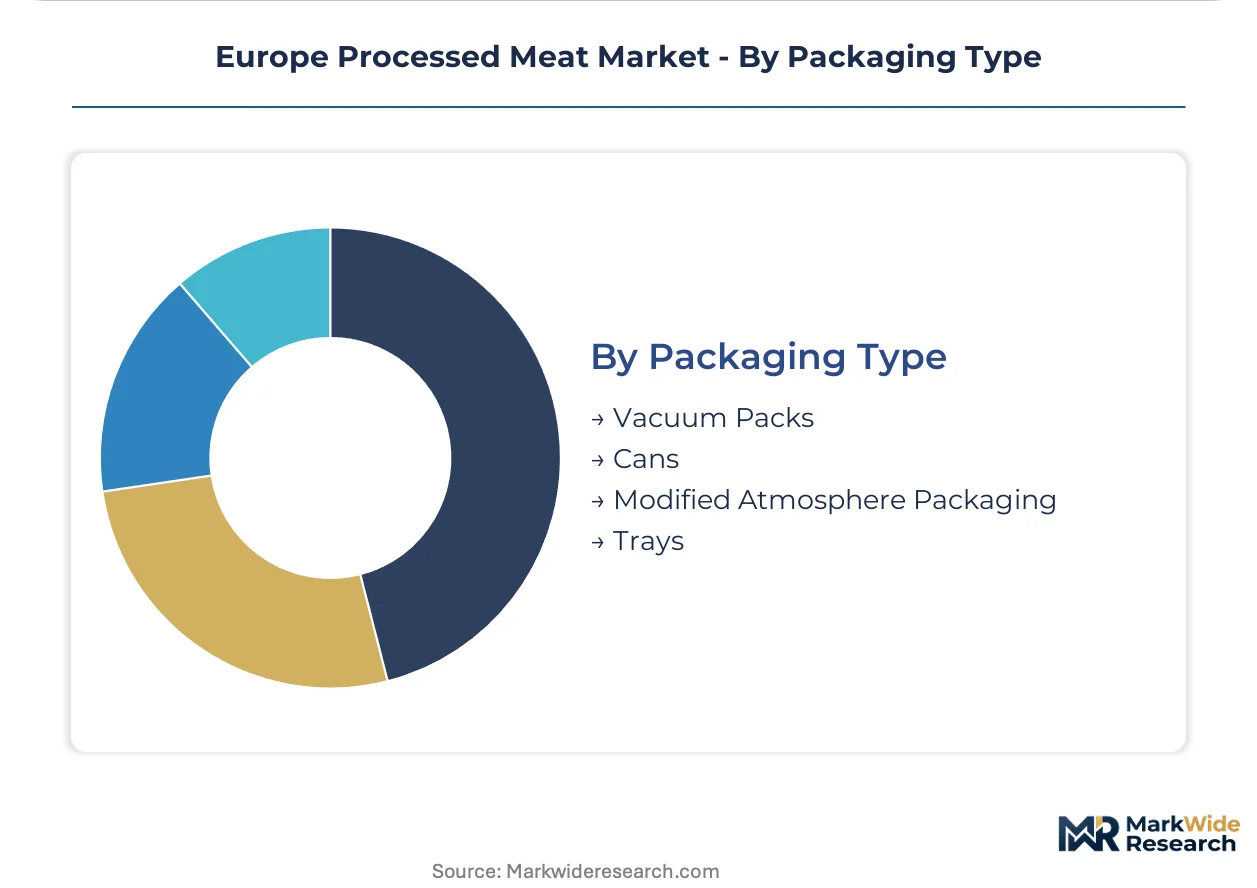
| Segmentation | Product Type: Sausages, Bacon, Ham, Salami Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Foodservice End User: Households, Restaurants, Food Processors, Cafés Packaging Type: Vacuum Packs, Cans, Modified Atmosphere Packaging, Trays |
| Companies Covered | Groupe Bigard SA, WH Group Ltd, Danish Crown AmbA, Cargill, Inc., JBS S.A., Vion Food Group, Bell Food Group, Cranswick PLC, Premium Food Group ApS & Co. KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Processed Meat Market Shifts & Advancements
Clean-label preservation and carbon-transparent sourcing are rewiring competitive advantage across European processing. Technology investments now prioritize traceability infrastructure and emission reduction over conventional capacity expansion.
High-pressure processing is supplanting thermal pasteurization in premium sausage and sliced deli categories. German and Dutch retail chains are adopting cold-pasteurized formats for extended shelf-life without preservative labeling. This shift is compressing the advantage of conventional processors dependent on nitrite-based safety margins.
CSRD scope-three emission reporting is mandating supplier-tier carbon disclosure across the value chain. Processors must now audit feed, energy, and transport inputs for consolidated sustainability statements. Iberian and Benelux plants face the steepest compliance curves due to fragmented upstream hog farming structures.
Centralized procurement desks at pan-European foodservice groups are consolidating supplier panels around multi-site contract frameworks. Legacy regional distributor relationships are yielding to direct processor agreements with volume-commitment pricing. This concentration is most visible in Germany's Rhineland meat processing cluster, where institutional buyers now negotiate continental coverage from single-source agreements.
Europe Processed Meat Market Segmentation
Channel configuration dictates margin capture across European processed meat value chains. Retail format selection determines packaging specifications, shelf-life requirements, and price positioning for each product category.
Product Type:
Supermarkets anchor volume for ambient-stable formats while foodservice channels concentrate demand for premium cured varieties requiring shorter rotation cycles.
- Sausages:Ground meat emulsions stuffed into natural or synthetic casings, then smoked, cooked, or fermented to achieve target water activity and texture. German households drive volume through breakfast and grilling applications, though EFSA nitrite limits are forcing reformulation of traditional curing protocols. By volume, sausages lead. By growth pace, salami is expanding most quickly.
- Bacon:Pork belly cured with salt and nitrites, then smoked and sliced for retail or foodservice portioning. British and Irish households sustain the largest per-capita consumption, with rashers dominating quick-meal preparation and sandwich assembly.
- Ham:Whole-muscle curing of pork leg through brine injection or dry-salt equilibration, with Parma and Serrano designations commanding premium positioning in Mediterranean retail.
- Salami:Fermented and dried sausages relying on lactic acid bacteria for pH reduction and shelf stability, with northern Italy's charcuterie corridor supplying Protected Designation of Origin volumes to specialty retailers.
Premium designation concentration in salami and ham segments generates margin offsets against commodity sausage pricing pressure.
Distribution Channel:
Cost-to-serve economics stratify channel profitability, with direct-to-foodservice bypassing retail margin stacking but requiring specialized cold-chain infrastructure.
- Supermarkets:Multi-temperature retail environments with dedicated deli counters and pre-packaged sections. German and French chains are consolidating procurement around pan-European suppliers with REACH-compliant processing aids documentation.
- Online Retail:Direct-to-consumer fulfillment requiring insulated packaging and controlled last-mile delivery. Dutch and Nordic markets show steepest adoption curves for subscription-based charcuterie boxes.
- Convenience Stores:Limited assortment focused on grab-and-go formats with extended shelf-life requirements. Iberian networks prioritize single-serve cured meat snacks for commuter traffic patterns.
- Foodservice:Institutional kitchens, restaurants, and catering operations sourcing in case quantities with specification-grade consistency. German Rhineland processors are securing multi-site contracts with pan-European hospitality groups.
Supermarkets maintain volume leadership. Online retail is gaining share fastest among emerging channels.
End User:
Application-specific requirements differentiate procurement specifications across household and commercial segments.
- Households:Retail-packaged portions prioritized for convenience, with breakfast and quick-meal occasions driving repeat purchase frequency in northern European markets.
- Restaurants:Foodservice operators in France and Italy are expanding Protected Designation of Origin charcuterie procurement for menu differentiation against commodity alternatives.
- Food Processors:Ingredient-grade supplies for pizza toppings, ready-meal components, and sandwich manufacturing requiring standardized dimensional specifications and predictable yield rates.
- Cafés:Smaller-format operators emphasizing artisanal presentation and local provenance claims in urban premium locations across Benelux and Scandinavian cities.
Households dominate absolute consumption. Restaurants are climbing the fastest as foodservice premiumization accelerates.
Packaging Type:
Barrier performance and shelf-life extension capabilities determine format selection across retail and foodservice channels.
- Vacuum Packs:Oxygen exclusion through flexible film barriers, extending refrigerated shelf-life for sliced deli meats and whole-muscle cuts. Northern Italian retailers are adopting this format aggressively to reduce deli-counter shrink.
- Cans:Thermal sterilization in rigid metal containers for ambient-stable products including luncheon meats and shelf-stable sausages, with Eastern European markets maintaining higher per-capita consumption.
- Modified Atmosphere Packaging:Gas-flushed barrier trays replacing conventional formats in German and Dutch retail chains, enabling extended case-life without preservative labeling.
- Trays:Overwrapped foam or rigid plastic containers with permeable films, remaining cost-competitive for high-velocity commodity segments with rapid turnover expectations.
Modified atmosphere packaging leads investment flows. Vacuum packs are scaling fastest as retailers prioritize waste reduction metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German processors dominate intra-European trade flows, exporting premium cured varieties to Benelux and Scandinavian buyers while sourcing hog supplies from Danish and Dutch farming cooperatives.
Germany
Foodservice operators in the Rhineland meat processing cluster are expanding procurement of artisanal smoked sausages for institutional kitchen differentiation. EFSA nitrite exposure limits are forcing reformulation of traditional curing protocols without shelf-life trade-offs. Cologne and Düsseldorf anchor distribution networks serving pan-European hospitality groups with multi-site contract frameworks.
Italy
Restaurants across Lombardy and Emilia-Romagna are elevating Protected Designation of Origin charcuterie procurement for menu premiumization against commodity alternatives. EU Green Deal methane benchmarks are accelerating carbon accounting investments across Parma and Modena processing facilities. Northern Italy's charcuterie corridor supplies specialty retailers with vacuum-packed salami formats to reduce deli-counter shrink.
France
Institutional kitchens in Paris and Lyon are unwinding legacy distributor relationships for direct processor agreements with volume-commitment pricing. REACH compliance mandates for processing aids are creating competitive moats for operators with in-house analytical laboratories. Brittany's pork processing belt is consolidating around audited cold-chain networks for export-grade ham production.
Spain
JBS S.A. leverages Iberian plant scale advantages in fresh-to-processed conversion capacity for foodservice export channels. CSRD scope-three emission reporting is mandating supplier-tier carbon disclosure across fragmented upstream hog farming structures. Barcelona and Valencia anchor modified atmosphere packaging adoption for extended case-life in retail deli counters.
Netherlands
Dutch retail chains are adopting high-pressure processed cold-pasteurized formats for extended shelf-life without preservative labeling. ECHA compliance infrastructure requirements favor processors with regulatory affairs capabilities and documented barrier film migrants testing. Eindhoven and Utrecht distribution hubs facilitate cross-border fulfillment to German and Belgian convenience store networks.
Europe Processed Meat Market Competitive Landscape
Player mix skews toward cooperative structures and vertically integrated agribusiness conglomerates with captive hog supply. Market structure concentrates around three to five pan-European processors controlling fresh-to-processed conversion capacity. Strategic archetypes include cooperative sourcing alliances, integrated farming-to-branded manufacturing operations, and scale-driven fresh processing specialists. Competitive moves center on multi-site foodservice contract consolidation and cold-chain infrastructure expansion into Eastern European retail channels.
Among cooperative-structured operators, Danish Crown AmbA anchors Nordic institutional supply through member-farmer sourcing networks. WH Group Ltd exemplifies integrated agribusiness architecture with backward integration into European hog farming and branded sausage manufacturing. JBS S.A. occupies the scale-driven position with Iberian and Benelux plant networks optimized for fresh-to-processed throughput. These three entities represent distinct competitive archetypes: cooperative governance, vertical integration, and continental scale.
| Leading Market Players |
|---|
| Groupe Bigard SA |
| WH Group Ltd |
| Danish Crown AmbA |
| Cargill, Inc. |
| JBS S.A. |
| Vion Food Group |
| Bell Food Group |
| Cranswick PLC |
| Premium Food Group ApS & Co. KG |
| Others |
Supply & Pricing Matrix
EU Green Deal methane benchmarks and EFSA nitrite exposure limits gate both supplier qualification and price differentiation simultaneously, forcing processors to invest in audited cold-chain infrastructure and reformulation capabilities that separate premium-tier operators from commodity competitors unable to absorb compliance costs.
Pricing Analysis
Prior-generation nitrite-dependent curing commands economy-tier positioning as EFSA limits tighten, while current-generation high-pressure processed formats capture standard-tier margins through extended shelf-life claims, and next-generation fermentation-derived preservation systems anchor premium pricing for clean-label positioning. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in economy-tier commodity sausage is intensifying because feed grain price volatility from Ukrainian export disruptions compresses fresh-to-processed conversion margins. Food processors demonstrate highest price sensitivity due to standardized yield requirements, while institutional kitchens in Germany and Italy show lowest sensitivity when sourcing Protected Designation of Origin charcuterie.
Supply Chain Analysis
Strategic stockpiling of hog supplies dominates processor procurement strategy, with Danish cooperative sourcing networks and Dutch farming operations anchoring live animal flows into Rhineland and Benelux plants. Geographic supply concentration centers on Denmark, Germany, and the Netherlands for hog farming, with northern Italy's charcuterie corridor supplying premium cured varieties. Raw material dependencies rest on feed grains, natural casings, and barrier film packaging migrants. Single-source vulnerability runs through Danish Crown AmbA's cooperative dominance in Nordic institutional supply. Distribution runs through pan-European foodservice procurement desks consolidating around direct processor agreements with multi-site contract frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-pressure processing and fermentation-derived preservation systems are disrupting competitive positioning in European processed meat, with EFSA nitrite limits and EU AI Act traceability mandates creating simultaneous technological and regulatory inflection points that reward early compliance investment.
For Market Incumbents: Consolidate cold-chain audit capabilities and in-house analytical laboratories to defend against emerging clean-label specialists capturing premium shelf space. Threats from plant-protein hybrid convergence and carbon-transparent sourcing requirements demand backward integration into feed and energy inputs for CSRD scope-three compliance. Priority lever sits with multi-site foodservice contract consolidation across Germany's Rhineland cluster and northern Italy's charcuterie corridor. For New Entrants and Emerging Players: Foodservice procurement desk consolidation gaps in Eastern European retail channels present white-space entry points for premium cured meat distribution. Poland and Romania offer most penetrable geographies with underpenetrated cold-chain infrastructure. Go-to-market angle should emphasize EU AI Act batch-tracking compliance ahead of enforcement timelines to differentiate in institutional tender processes. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across smokehouse emission control and high-pressure processing equipment installations. Long-term viability over the coming decade favors processors with documented REACH compliance infrastructure and captive hog supply arrangements. Acquisition target archetype includes mid-tier operators with regulatory affairs capabilities but fragmented upstream sourcing. Signal to watch is carbon accounting audit completion rates across Iberian and Benelux plant networks.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Adoption | Cold-pasteurized formats extend shelf-life without EFSA-scrutinized nitrite labeling in German retail. |
| Backward Integration into Hog Farming | Captive supply secures margin control against Ukrainian grain export volatility in fresh-to-processed conversion. |
| EU AI Act Traceability Compliance | Batch-tracking infrastructure differentiates processors in pan-European foodservice procurement tenders. |
| Eastern European Cold-Chain Expansion | Poland and Romania distribution networks unlock underpenetrated premium cured meat retail channels. |
| CSRD Scope-Three Carbon Disclosure | Supplier-tier auditing satisfies consolidated sustainability reporting for Benelux and Iberian plant operations. |
Research Methodology
A standing panel of plant operations directors, foodservice procurement managers, regulatory affairs specialists, and retail category buyers provided ongoing calibration throughout data collection. Primary interviews combined with secondary validation against EFSA exposure assessments, ECHA REACH substance databases, EU Green Deal policy documents, and customs trade flow records. Bottom-up segment modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Consistency checks validated outputs against external benchmarks including pan-European foodservice procurement volumes and retail scanner data from Nielsen and Circana audits across German, Italian, and French markets. The analytical framework segmented by product type, distribution channel, packaging format, and end-use application across the projection horizon. CAGRs derived from regression analysis of historical consumption patterns and elasticity-adjusted demand projections. Industry-specific inputs included hog supply forecasts from cooperative sourcing networks and reformulation cost curves for nitrite-reduced curing protocols.
Forecasts assume regulatory continuity in EFSA exposure limits and EU Green Deal methane benchmarks; material policy shifts would require re-modeling. Specific risk factors include Ukrainian grain export disruption persistence, REACH substance restriction expansion, and EU AI Act enforcement timeline acceleration. Revision becomes warranted when carbon accounting audit failure rates cross thresholds that trigger foodservice procurement desk supplier panel restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Global Edible Meat Market
Meat Products
China Processed Meat Market
Meat Products
Blended Meat Market
Meat Products
Grassfed Jerky Market
Meat Products
Grass Fed Beef Market
Meat Products
United States Processed Pork Meat Market
Meat Products
Raw Chicken Feet Market
Meat Products
Canned Chicken Market
Meat Products
Meat Paste Market
Meat Products
Western Europe Ready-To-Eat Meat Market
Meat Products
US Meat Market
Meat Products
Germany Meat Products Market
Meat Products
Bacon Slicers Market
Meat Products
Asia-Pacific Processed Meat Market
Meat Products
Saudi Arabia Red Meat Market
Meat Products
North America Processed Poultry Meat Market