
 South Africa Processed Meat Market | 2026-2036
South Africa Processed Meat Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Processed Meat Market Analytics
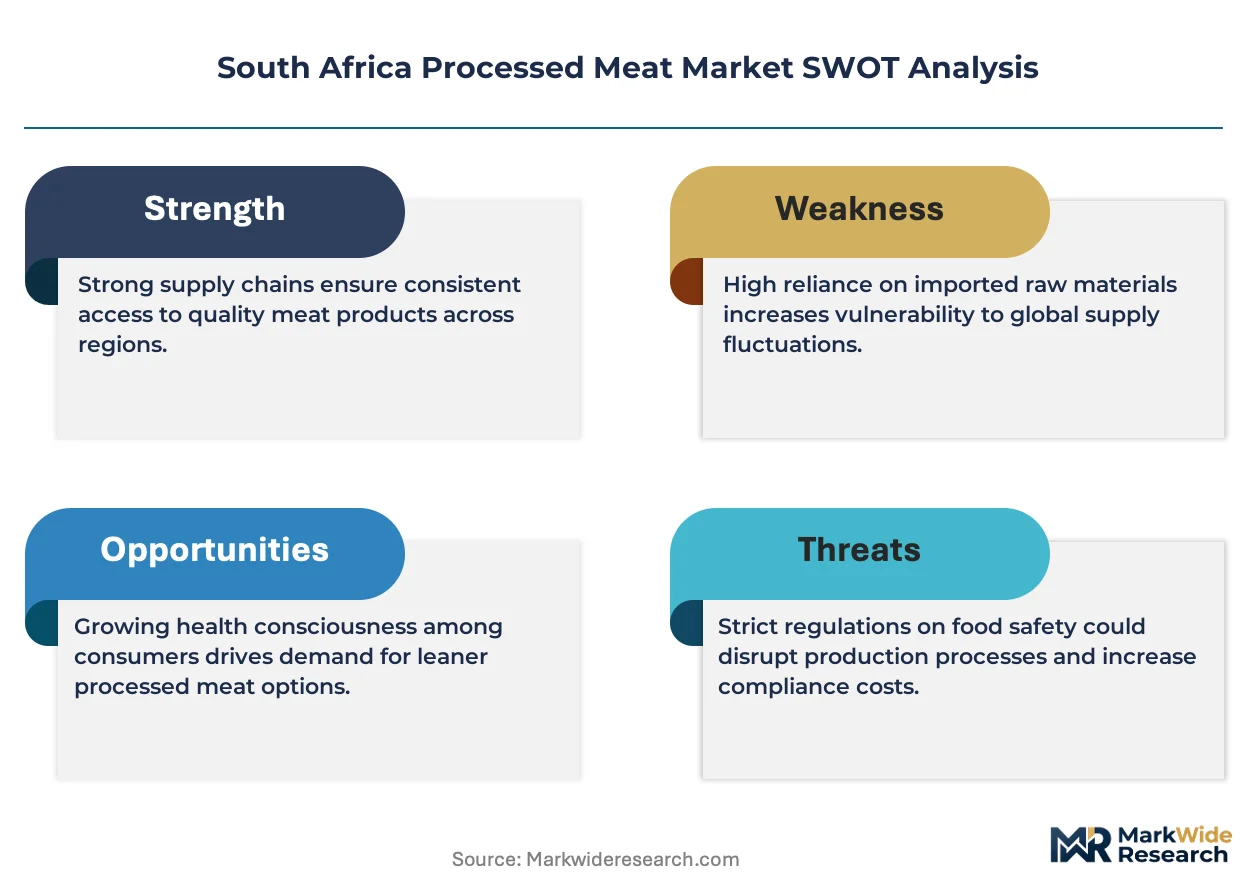
Subscription-based cold-chain monitoring is pivoting how value gets captured beyond the physical product. Tiger Brands Limited leverages its national distribution network to sustain shelf presence across multiple retail tiers. RCL Foods Limited anchors protein supply through integrated poultry and processed meat operations. Eskort Co-operative differentiates via cooperative sourcing structures that control input costs for member farmers.
Processed meat comprises animal protein subjected to curing, smoking, fermentation, thermal processing, or mechanical restructuring to extend shelf stability, enhance flavor profiles, and ensure food safety compliance through controlled water activity and pH reduction. Its primary commercial purpose centers on delivering convenient, standardized protein formats for retail and foodservice channels with minimal preparation requirements. Sausages and deli meats lead volume throughput in South African retail, while vacuum-sealed packaging commands margin premiums through extended freshness claims and reduced spoilage rates. Online retail channels represent the fastest-growing distribution pathway as logistics networks improve last-mile cold-chain reliability.
The Department of Agriculture, Land Reform and Rural Development enforces meat safety standards through regular facility inspections and pathogen testing protocols, while the National Regulator for Compulsory Specifications mandates labeling accuracy for processed meat composition claims. FSSAI-aligned importers face additional scrutiny at ports, shaping competitive access for foreign suppliers. Stakeholders must monitor evolving sodium-reduction targets and antibiotic-residue thresholds that will reshape formulation requirements and sourcing qualifications across the value chain.
Market Dynamics
The Department of Agriculture, Land Reform and Rural Development's updated labeling standards are compressing formulation flexibility while quick-service restaurant chains across Gauteng and the Western Cape accelerate procurement of ready-to-cook processed cuts. This regulatory tightening against foodservice expansion defines the market's central tension.
Growth Catalysts
- Quick-service restaurant procurement:Chains across Johannesburg's foodservice corridor are expanding volume commitments for ready-to-cook processed cuts, pulling throughput from traditional retail channels.
- Labeling standard enforcement:The Department of Agriculture, Land Reform and Rural Development's disclosure requirements are forcing ingredient transparency that builds consumer trust and retail shelf access.
- Vacuum-sealed packaging adoption:Extended freshness claims through modified atmosphere packaging are capturing margin premiums in Cape Town's retail-distribution hub.
Market Restraints
- Feed input cost volatility:Maize and soy prices fluctuate with rainfall patterns across the Free State and Mpumalanga, compressing processor margins unpredictably.
- Cold-chain infrastructure gaps:Last-mile refrigeration reliability remains inconsistent in Eastern Cape and Limpopo townships, limiting distribution reach.
- Plant-based protein substitution:Flexitarian diets in urban Gauteng are displacing some processed meat occasions, particularly among younger demographics.
Strategic Opportunities
- Online retail channel expansion:E-commerce platforms with dedicated cold-chain logistics are penetrating under-served Northern Cape and North West markets.
- Subscription-based monitoring services:Temperature-tracking technology bundled with delivery contracts creates recurring revenue beyond product sales.
- Sodium-reduction formulation:Anticipated targets from the Department of Health offer first-mover advantage for processors with compliant product lines.
Industry Challenges
- Antibiotic-residue testing capacity:Laboratory bottlenecks at port-of-entry facilities delay clearance for imported inputs, stretching working capital cycles.
- Skilled meat technologist shortage:Formulation expertise for clean-label product development concentrates in Johannesburg and Cape Town, leaving regional processors dependent on external consultants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Processed Meat Market |
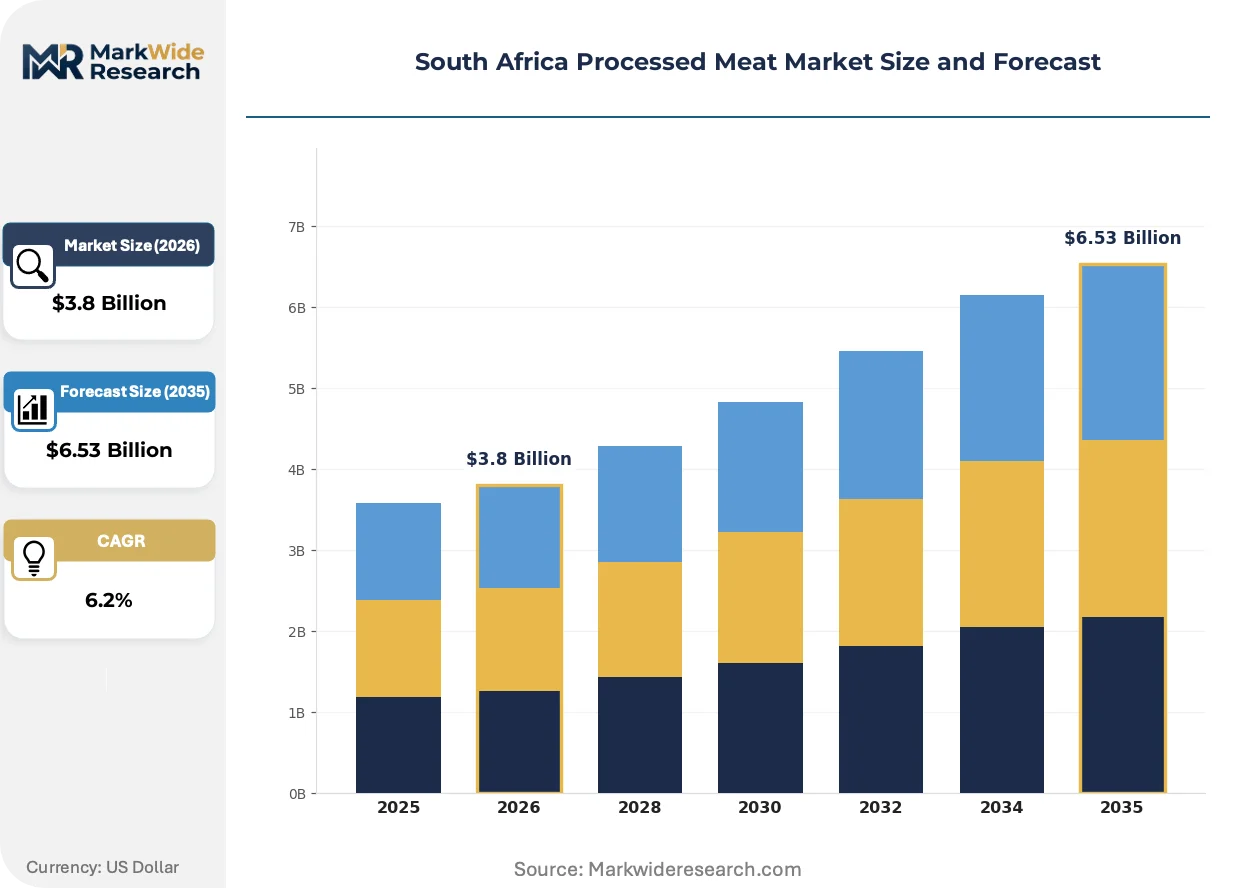
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sausages, Bacon, Deli Meats, Canned Meats Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Butcher Shops Consumer Type: Households, Restaurants, Cafes, Catering Services Packaging Type: Vacuum Sealed, Tray Pack, Flexible Pouches, Canned |
| Companies Covered | Astral Foods Limited, Famous Brands Limited, Tiger Brands Limited, Rainbow Farms (Pty) Ltd, Tyson Foods, RCL Foods Limited, Eskort Co-operative, Irvin & Johnson Ltd, BRF SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Processed Meat Market Evolving Landscape
Digital traceability systems and modified atmosphere packaging are compressing traditional quality assurance timelines. Regulatory pressure on ingredient disclosure is reshaping formulation priorities. Channel diversification beyond conventional retail is redrawing competitive access patterns.
Modified atmosphere packaging with embedded time-temperature indicators is absorbing quality assurance functions previously handled by retailer inspection protocols. Gauteng-based quick-service restaurant chains are adopting these formats at pace for centralized kitchen delivery. The technology is absorbing margin pressure from spoilage claims while enabling longer distribution radii from Western Cape processing hubs.
The Department of Agriculture, Land Reform and Rural Development's updated labeling standards mandate ingredient percentage disclosure and allergen highlighting for all processed meat products. This regulatory tightening is forcing reformulation of legacy recipes that relied on undeclared binders and extenders. Deli meat categories face the steepest compliance costs, with processors in Johannesburg's industrial corridor accelerating label redesign cycles.
Direct-to-hospitality procurement models are bypassing traditional wholesale intermediaries for volume accounts. Quick-service restaurant chains in Gauteng and the Western Cape are consolidating supplier relationships around processors with dedicated foodservice specifications. This channel compression is most visible in Cape Town's retail-distribution hub, where national chain procurement teams now negotiate directly with cooperative sourcing structures.
South Africa Processed Meat Market Segmentation
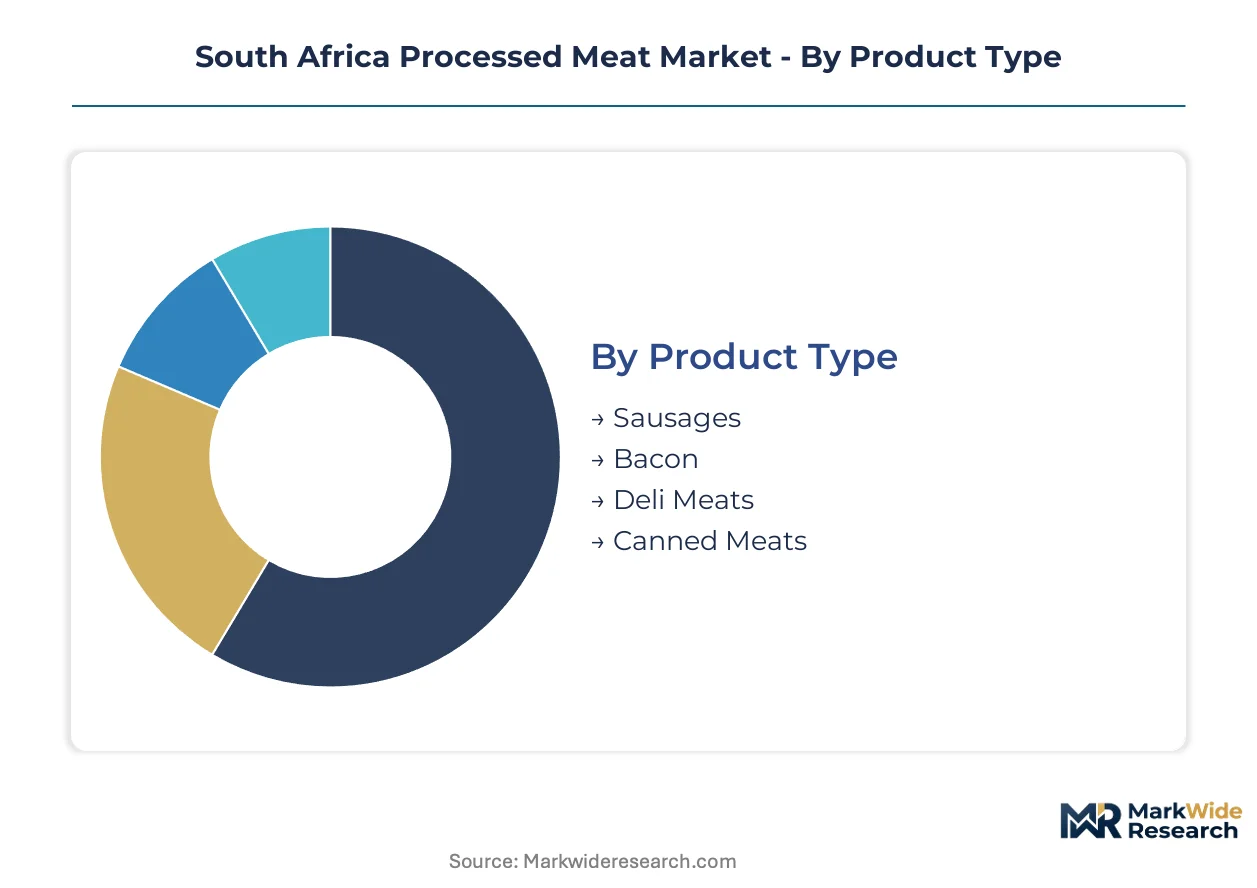
Processed meat purchasing in South Africa fragments across four distinct decision hierarchies. Product format determines preparation convenience and price positioning. Distribution channel selection reflects cold-chain reliability and last-mile access. Packaging technology governs shelf-life claims and margin capture.
Product Type:
Buyer choice pivots on preparation time and meal occasion compatibility.
- Sausages:Ground meat emulsions stuffed into casings, spanning fresh, smoked, and dried variants. Demand concentrates in Gauteng townships and Cape Town informal settlements where single-meal affordability drives volume. Price sensitivity here exceeds national averages by significant margins.
- Deli Meats:Sliced cured products including ham, salami, and pastrami for sandwich and platter applications. Johannesburg's corporate catering corridor and Sandton office complexes sustain premium throughput for convenience-oriented protein formats. Modified atmosphere packaging enables extended distribution from Western Cape processing hubs.
- Bacon:Cured and smoked pork belly strips for breakfast and recipe applications. Retail penetration remains strongest in suburban supermarket chains.
- Canned Meats:Thermally processed products in shelf-stable containers for emergency provisioning and rural distribution. Limpopo and Eastern Cape townships depend on this format where refrigeration is intermittent.
Sausages lead on scale; deli meats lead on momentum.
Distribution Channel:
Channel selection tracks infrastructure maturity and purchase frequency patterns.
- Supermarkets:Full-format retail with dedicated cold-chain infrastructure and private-label processed meat programs. Shoprite Holdings and Pick n Pay control shelf access through centralized procurement in Johannesburg's distribution corridor. Volume commitments here determine processor production scheduling.
- Online Retail:E-commerce platforms with temperature-controlled fulfillment networks penetrating under-served provinces. Northern Cape and North West markets show steepest expansion trajectory as last-mile cold-chain reliability improves. Subscription models are capturing recurring revenue beyond transactional sales.
- Convenience Stores:Small-format retail in fuel stations and township high streets for immediate consumption. Spar Group franchises dominate this tier in KwaZulu-Natal.
- Butcher Shops:Independent meat retailers with on-site processing and custom cutting. Traditional trade persists in Eastern Cape and Free State rural communities.
Supermarkets anchor volume throughput; online retail is gaining share fastest.
Consumer Type:
End-use application dictates specification requirements and delivery scheduling.
- Restaurants:Quick-service chains and casual dining operations across Gauteng and Western Cape demanding consistent portion control and food safety documentation. Nando's and Steers procurement teams negotiate directly with processors for dedicated foodservice specifications. Centralized kitchen models are compressing supplier relationships.
- Households:Individual consumers purchasing for domestic meal preparation through retail channels. Cape Town's Atlantic Seaboard and Johannesburg's northern suburbs show strongest demand for premium deli and bacon categories.
- Cafes:Coffee shop and light meal operations requiring ready-to-serve protein formats for sandwich and breakfast applications.
- Catering Services:Event and institutional food providers with bulk volume requirements and seasonal demand spikes.
Restaurants command specification discipline; households provide volume baseline.
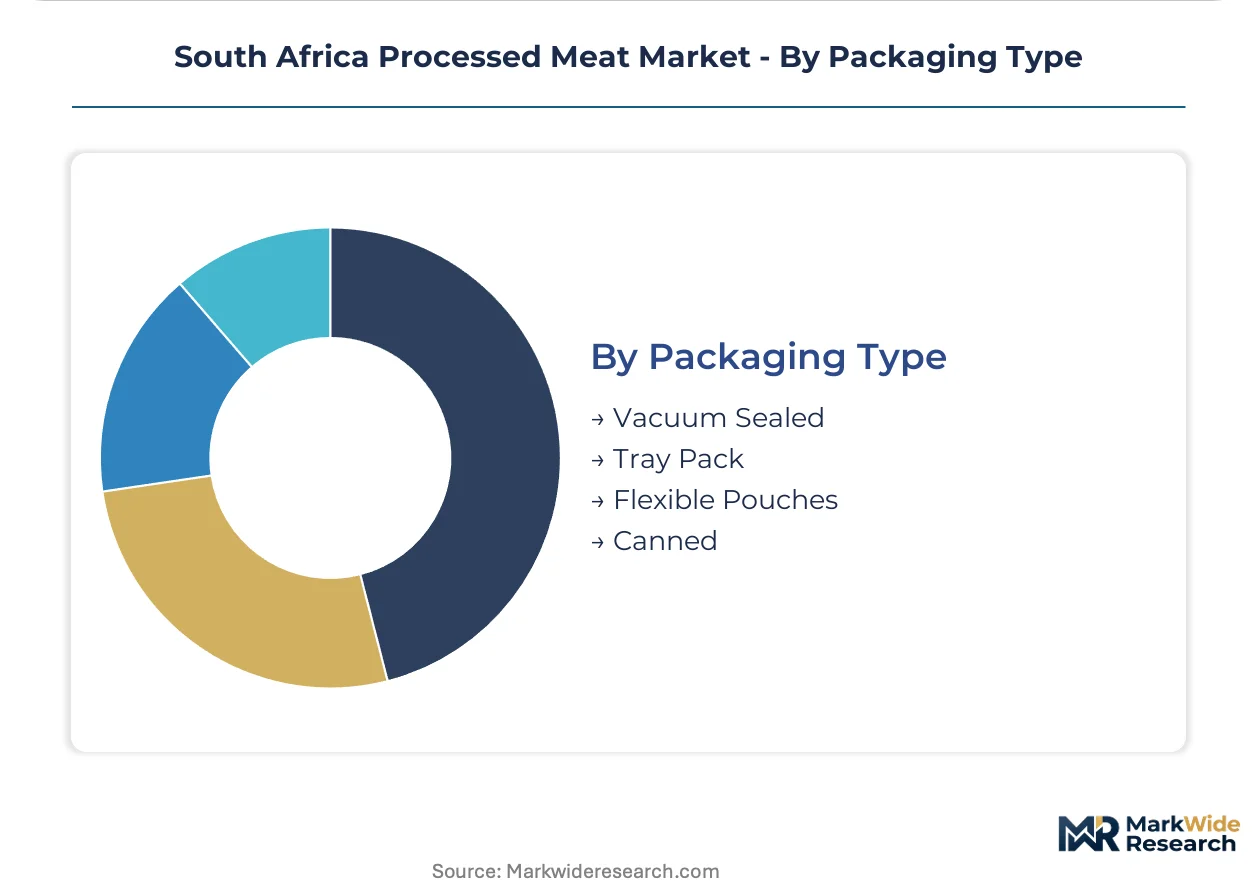
Packaging Type:
Packaging technology determines shelf-life extension and spoilage risk allocation.
- Vacuum Sealed:Oxygen-exclusion packaging with modified atmosphere for extended freshness claims. Cape Town's retail-distribution hub processors capture margin premiums through reduced spoilage rates and longer distribution radii. Time-temperature indicators are absorbing quality assurance functions.
- Flexible Pouches:Lightweight polymer packaging for sliced deli meats and portion-controlled formats. Adoption accelerates in Johannesburg's quick-service restaurant supply chains where space efficiency matters.
- Tray Pack:Expanded polystyrene or cardboard trays with overwrap film for fresh sausage and bacon display. Supermarket delis favor this format for visual merchandising.
- Canned:Metal container thermal processing for ambient shelf stability. Rural Eastern Cape and Limpopo distribution depends on this format.
Vacuum sealed dominates margin capture; flexible pouches show steepest adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redistributing processing capacity toward provinces with lower compliance costs and established cold-chain infrastructure. The Department of Agriculture, Land Reform and Rural Development's enforcement intensity varies across provinces, creating migration incentives for mid-scale processors.
Gauteng
Johannesburg's foodservice corridor commands the highest procurement volumes for ready-to-cook processed cuts. The Department of Health's sodium-reduction consultation targets processors here first due to concentration of quick-service restaurant chains. Midrand industrial parks host formulation laboratories serving national retail private-label programs.
Western Cape
Cape Town's retail-distribution hub captures margin premiums through vacuum-sealed packaging adoption and modified atmosphere technology. Provincial environmental regulations on wastewater discharge from rendering operations exceed national baselines, elevating compliance costs for coastal processors. Paarl and Stellenbosch processing clusters supply deli meat formats to Atlantic Seaboard supermarkets.
KwaZulu-Natal
Durban's port infrastructure shapes competitive access for imported meat inputs and equipment. The Department of Agriculture's facility inspection frequency intensified following 2017 listeriosis outbreak tracing, compressing operational flexibility. Pietermaritzburg industrial zones concentrate canned meat production for rural Eastern Cape distribution.
Eastern Cape
Cold-chain infrastructure gaps in township markets sustain demand for shelf-stable canned meat formats. Provincial agricultural development programs subsidize small-scale processor equipment upgrades in former homeland territories. Gqeberha's abattoir capacity supports limited processed meat value-addition for local retail.
Free State
Feed input cost volatility from maize production fluctuations directly compresses processor margins in this grain-surplus province. The Department of Agriculture's pathogen testing protocols for export-oriented facilities exceed domestic-market requirements. Bloemfontein processing plants primarily supply raw material to Gauteng and Western Cape value-addition facilities.
South Africa Processed Meat Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with national brand owners commanding supermarket shelf access while cooperative structures dominate foodservice procurement. The market presents a three-tier structure: integrated agribusiness conglomerates with captive protein supply, branded consumer goods specialists with national distribution networks, and regional cooperatives with cost-controlled sourcing. Dominant competitive moves include backward integration into poultry farming and direct-to-hospitality channel compression bypassing wholesale intermediaries.
Among integrated agribusiness conglomerates, Astral Foods Limited and RCL Foods Limited exemplify the protein-supply anchoring archetype through captive farming operations. Tiger Brands Limited occupies the branded consumer goods specialist position with national retail network penetration. Eskort Co-operative represents the cooperative sourcing structure that controls input costs for member farmers while serving foodservice accounts directly.
| Leading Market Players |
|---|
| Astral Foods Limited |
| Famous Brands Limited |
| Tiger Brands Limited |
| Rainbow Farms (Pty) Ltd |
| Tyson Foods |
| RCL Foods Limited |
| Eskort Co-operative |
| Irvin & Johnson Ltd |
| BRF SA |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between vacuum-sealed premium deli formats and commodity tray-pack sausages manifests in divergent margin structures and sourcing radii across South African processing corridors. This tier divergence concentrates procurement power in Cape Town's retail-distribution hub for extended-shelf-life formats while compressing logistics costs for Johannesburg's quick-service restaurant supply chains through localized production.
Pricing Analysis
Distributor margin stacking absorbs margin compression from feed input volatility, with retailer markup tiers separating vacuum-sealed deli premiums from commodity sausage formats. Price differentiation rests on cold-chain certification grade and volume scale commitments, with foodservice accounts commanding direct-to-processor discounts bypassing wholesale layers. Pricing pressure stems from maize and soy cost fluctuations across the Free State, with Gauteng township retailers showing highest price sensitivity and Atlantic Seaboard supermarkets least.
Supply Chain Analysis
Dual-sourcing requirements from quick-service restaurant chains mandate multi-processor qualification for raw material security, with geographic supply concentration anchoring in South Africa's domestic poultry and pork farming belts, supplemented by Brazilian and EU import corridors for specialized curing inputs. Raw material dependencies center on maize feed, soy protein, and casings. Supply chain risk concentrates in single-source vulnerability for modified atmosphere packaging films. Distribution runs through Johannesburg's foodservice corridor and Cape Town's retail-distribution hub with cold-chain reliability gaps in Eastern Cape and Limpopo townships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Western Cape environmental compliance costs and Gauteng's sodium-reduction regulatory intensity, with processors migrating formulation capacity toward provinces with lower wastewater discharge standards.
For Market Incumbents: Anticipate Department of Health sodium-reduction mandates by accelerating clean-label reformulation in Midrand laboratories. Secure backward integration into poultry farming to offset feed cost volatility from Free State maize fluctuations. Defend shelf access against private-label expansion by embedding time-temperature indicator technology in vacuum-sealed formats.
For New Entrants and Emerging Players: Launch via direct-to-hospitality procurement models bypassing wholesale intermediaries for Gauteng quick-service restaurant chains. Target under-served Northern Cape and North West online retail corridors where cold-chain infrastructure gaps persist. Penetrate through subscription-based temperature-monitoring services bundled with delivery contracts.
For Investors and Strategic Acquirers: Consolidation pressure builds where cooperative sourcing structures control input costs but lack national distribution reach. Long-term viability favors processors with integrated protein supply and foodservice specification expertise. Watch for antibiotic-residue testing capacity bottlenecks at port-of-entry facilities as inflection signal for import-dependent input strategies.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Poultry Farming | Captive protein supply insulates margins from Free State feed cost volatility. |
| Direct-to-Hospitality Channel Compression | Bypassing wholesale intermediaries secures volume commitments from Nando's and Steers procurement teams. |
| Modified Atmosphere Packaging Scale-Up | Extended freshness claims capture premium positioning in Cape Town's Atlantic Seaboard retail corridor. |
| Sodium-Reduction Formulation Investment | First-mover compliance with Department of Health targets secures Gauteng quick-service restaurant access. |
| Online Retail Cold-Chain Expansion | Temperature-controlled fulfillment networks penetrate Northern Cape and North West under-served markets. |
Research Methodology
Direct dialogue with processed meat plant managers, quick-service restaurant procurement directors, retail category buyers, and cold-chain logistics operators grounded qualitative insights in operational realities. Secondary validation drew from Department of Agriculture inspection records, National Regulator for Compulsory Specifications labeling databases, customs trade data for imported meat inputs, and SEC filings of listed protein processors. Bottom-up volume modeling triangulated against top-down value estimates across product format, distribution channel, and packaging technology segments.
Segment-level projections across the analysis window incorporated product type splits, channel penetration trajectories, and consumer application hierarchies. CAGRs derived from regression analysis of historical throughput patterns and forward-looking regulatory enforcement schedules. Industry-specific inputs included pathogen testing protocol changes, sodium-reduction consultation timelines, and cold-chain infrastructure investment pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under feed input price spikes or accelerated antibiotic-residue threshold enforcement. Deviation in Department of Health sodium-reduction implementation speed would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Europe Poultry Meat Market
Meat Products
Blended Meat Market
Meat Products
North America Poultry Meat Market
Meat Products
India Poultry Meat Market
Meat Products
India Animal Protein Market
Meat Products
Animal Protein Market
Meat Products
Beef Fat Powder Market
Meat Products
United States Edible Meat Market
Meat Products
Global Processed Pork Meat Market
Meat Products
Pepperoni Foods Market
Meat Products
Emulsified Meat Market
Meat Products
Mexico Meat Products Market
Meat Products
Europe Meat Products Market
Meat Products
Shark Meat Market
Meat Products
Organic Eggs Market
Meat Products
Beef Liver Market