
 Global Beef Market | 2026-2036
Global Beef Market Size, Share, and Industry Trends Forecast 2026-2036
Global Beef Market Analysis
Aftermarket value-added processing is tilting toward branded portion-cut programs that capture higher margins than commodity carcass sales. JBS leverages its North American feedlot network to control cattle supply flows from ranch to packing plant. Tyson Foods anchors its competitive stance through scale advantages in boxed beef fabrication. Marfrig Global Foods specializes in grass-fed and organic certifications that differentiate its South American exports into European retail channels.
Bef refers to the meat derived from cattle (Bos taurus and Bos indicus), typically graded by marbling score, age at harvest, and pH decline post-mortem, with primal cuts separated during breaking to supply fresh, frozen, or further-processed formats for human consumption. Chilled beef commands premium positioning in supermarket and butcher shop channels where cold-chain integrity signals freshness and supports shorter shelf-life logistics. Frozen beef sustains volume leadership in food services and hotels that prioritize inventory flexibility and extended storage. Processed beef occupies stable demand from the pet food industry, where rendered trimmings and mechanically separated material convert into shelf-stable protein inputs.
The USDA enforces pathogen reduction and hazard analysis standards through FSIS inspection mandates that determine market access for domestic and imported beef. Brazil's MAPA and the EU Commission coordinate equivalence agreements that shape export eligibility for South American packers. China's SAMR and GB standards govern label claims and residue limits that incoming suppliers must satisfy. Stakeholders must monitor how carbon border adjustments and methane accounting protocols reshape cost structures and sourcing geography across the value chain.
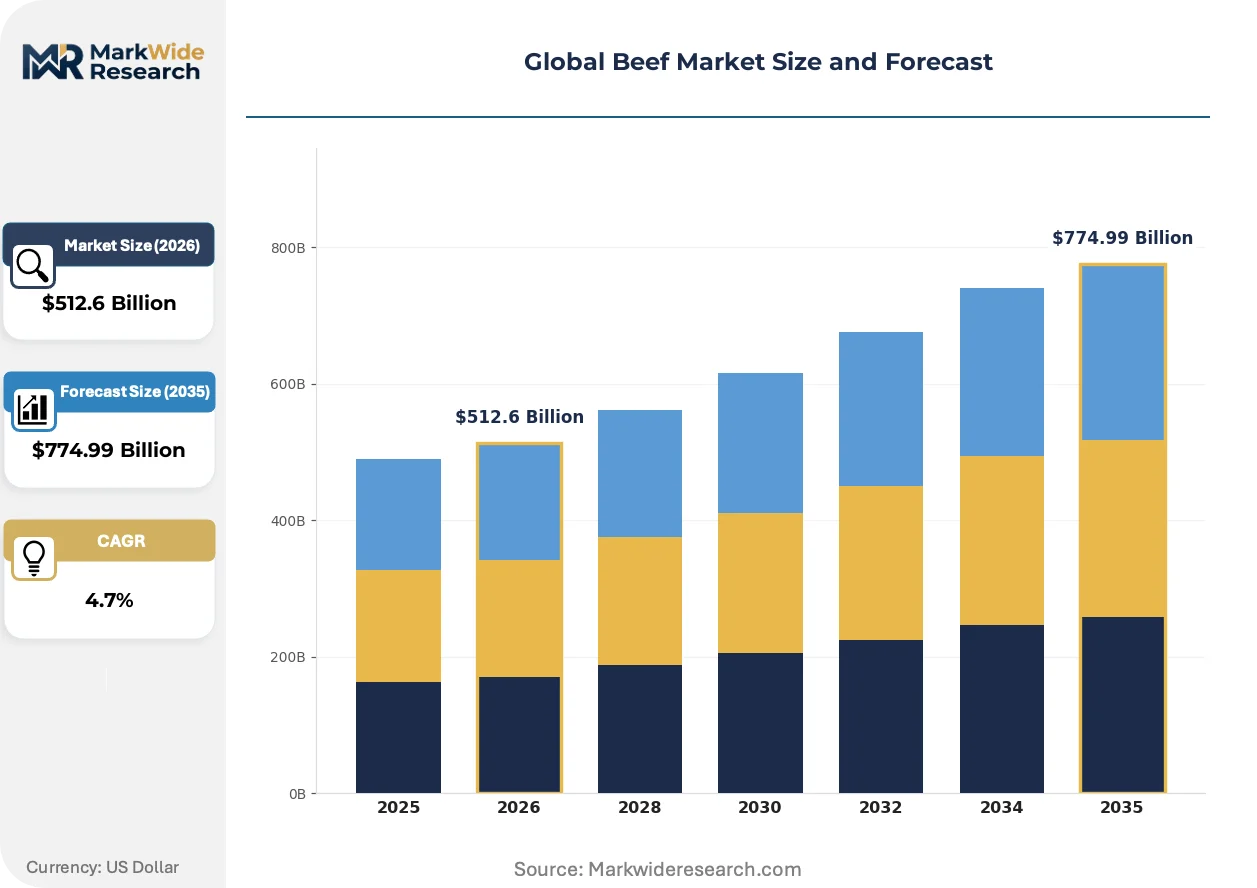
Market Dynamics
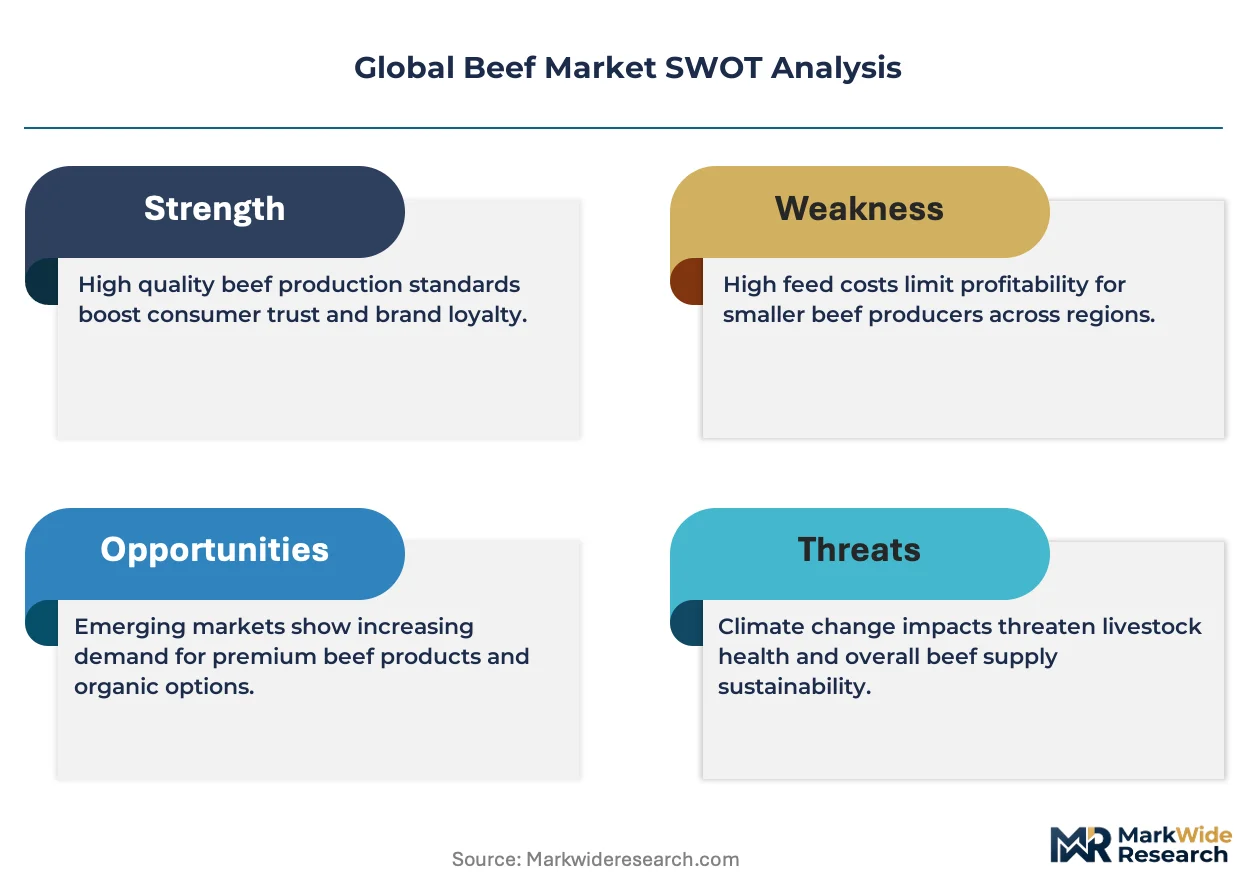
Carbon border adjustments and methane accounting protocols are restructuring sourcing economics across the beef value chain, forcing packers to reconfigure feedlot-to-retail pathways and redirect procurement toward lower-emission production zones.
Growth Catalysts
- EU Green Deal methane mandates:European retail chains are rewarding verified low-methane suppliers with preferential shelf placement and long-term contracts, accelerating investment in feed additives and manure management systems across exporting regions.
- Urban supermarket expansion in China:SAMR-certified cold-chain infrastructure is enabling grain-fed beef penetration into tier-two cities, where disposable income growth supports premium chilled product adoption.
- Blockchain traceability integration:Food service operators in Brazil are deploying distributed ledger systems to document herd origin and welfare compliance, satisfying procurement officers at multinational hotel chains.
Market Restraints
- Feed grain price volatility:Corn and soybean meal input costs swing with drought cycles in the US Midwest and Argentine Pampas, compressing feedlot margins and triggering destocking decisions.
- Processing concentration in Brazil:Three states account for over two-thirds of federally inspected slaughter capacity, creating bottlenecks when labor disputes or sanitary suspensions interrupt operations.
- Cell-cultured protein substitution:Singapore and Israel have approved novel meat production for food service channels, diverting R&D investment and pilot procurement away from conventional beef.
Strategic Opportunities
- Underpenetrated Indonesian market:Halal certification alignment with MUI standards opens access to a Muslim-majority population of 270 million with rising protein consumption.
- Regenerative grazing incentives:Australia's carbon credit framework rewards rotational grazing practices, allowing exporters to capture premium positioning in climate-conscious European retail.
- Direct-to-butcher digital platforms:Specialized software is connecting small-scale US ranchers with independent meat shops, bypassing traditional auction-yard and packer intermediaries.
Industry Challenges
- Veterinary pharmaceutical residue compliance:Meeting China's GB 31650 maximum residue limits requires extended withdrawal periods and documentation systems that many South American producers lack.
- Cold-chain infrastructure capex:Building export-compliant chilling and freezing capacity demands capital outlays that exceed balance sheet capacity for mid-sized Brazilian cooperatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Beef Market |
| Market Size in 2026 | $512.6 Billion |
| Market Size in 2035 | $774.99 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chilled Beef, Frozen Beef, Canned Beef, Processed Beef Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Butcher Shops Customer Type: Households, Restaurants, Food Services, Hotels End Use Industry: Food Industry, Pet Food Industry, Retail Industry, Culinary Sector |
| Companies Covered | Marfrig Global Foods, Minerva Foods, JBS, Hormel Foods, BRF, Tyson Foods, National Beef Packing, Smithfield Foods, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Beef Market Emerging Trajectories
Precision livestock technologies and alternative protein competition are forcing conventional beef operations to differentiate through verified sustainability credentials and supply chain transparency tools that command price premiums in selective retail channels.
Sensor-enabled ear tags and automated weighing systems is hybridizing traditional ranch management with data-driven decision support, allowing Australian and Uruguayan producers to optimize feed conversion and reduce finishing days. Mid-sized feedlots in the US Plains are adopting these platforms fastest, compressing the information advantage previously held by integrated packers with captive research divisions.
The EU F-Gas Regulation and CSRD reporting requirements are mandating granular Scope 3 emissions disclosure from food retailers, compelling importers to demand methane intensity documentation from South American suppliers. German and Dutch supermarket chains are now excluding non-compliant packers from tender processes, reshaping eligibility criteria for European market access.
Urban Chinese households are rotating protein purchases toward imported grain-fed beef through membership-based supermarket channels, displacing wet-market pork and poultry transactions. This behavioral pivot concentrates demand among SAMR-licensed importers with established cold-chain partnerships, marginalizing traders reliant on traditional wholesale distribution.
Global Beef Market Segmentation
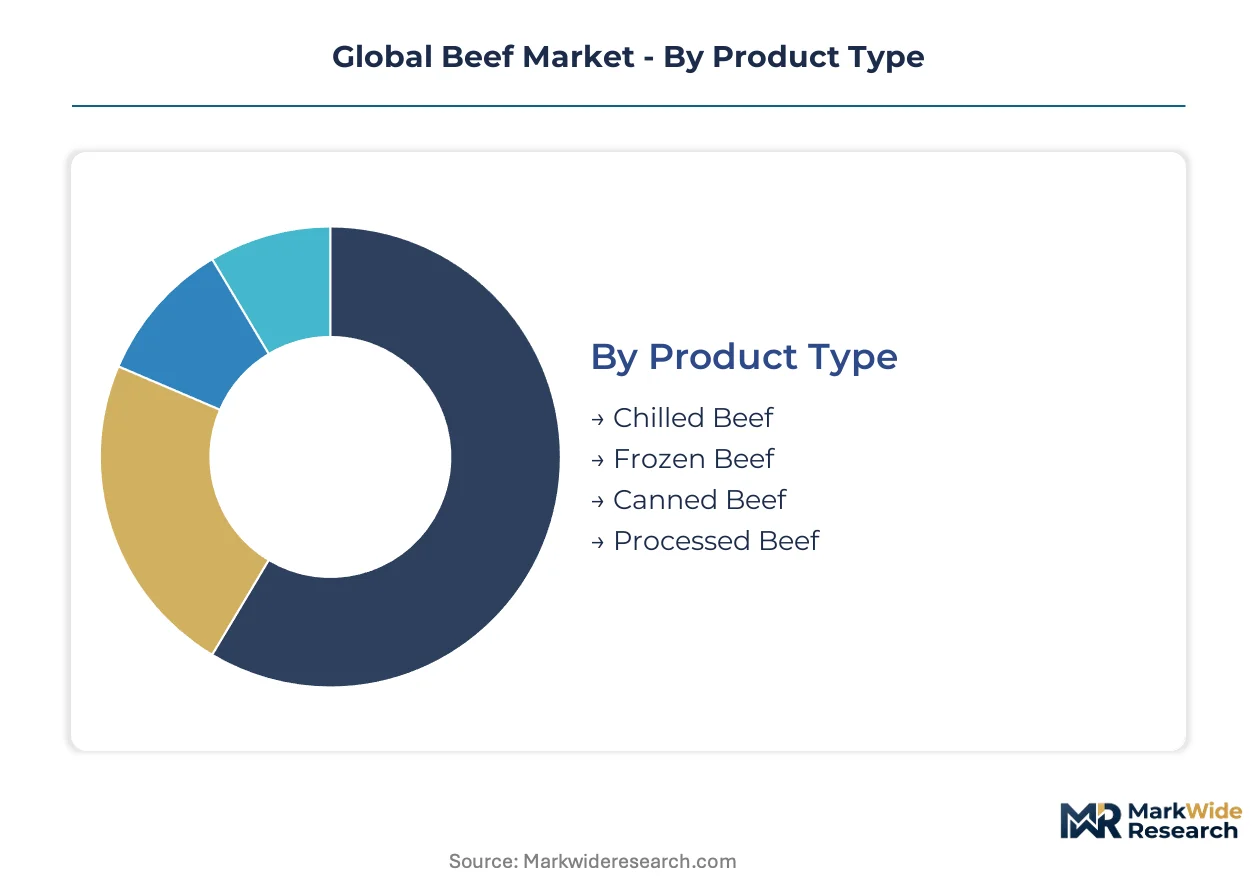
Beef market segmentation reveals how cold-chain capabilities, procurement scale, and end-use specifications fragment demand across incompatible logistics systems. Each dimension carries distinct margin structures and regulatory exposure that reshape competitive positioning.
Product Type:
Mature formats dominate volume flows while emerging preservation technologies capture premium positioning in climate-sensitive channels.
- Chilled Beef:Refrigerated carcasses and primal cuts maintained at 0°C to 4°C preserve enzymatic aging and color stability for 21-35 days. Supermarket chains in Germany and France reward verified cold-chain integrity with preferential shelf placement and long-term supply agreements.
- Frozen Beef:Blast-frozen at -18°C or below, this format extends storage to 12+ months while sacrificing some textural quality. Food service operators across Brazil and US hotel chains prioritize inventory flexibility and extended storage over fresh characteristics.
- Canned Beef:Heat-sterilized products in retort pouches or metal containers serve emergency stockpiling and military procurement with shelf-stable protein.
- Processed Beef:Rendered trimmings and mechanically separated material convert into shelf-stable inputs for pet food manufacturers.
Frozen beef retains volume leadership; chilled beef holds the steepest expansion curve.
Distribution Channel:
Channel selection determines margin capture, with direct retail commanding price premiums while wholesale intermediaries absorb logistics risk.
- Supermarkets:Large-format retailers with dedicated meat counters and cold-chain infrastructure. SAMR-licensed importers in China are penetrating tier-two cities through membership-based supermarket channels as urban households rotate protein purchases.
- Butcher Shops:Independent meat shops source from direct-to-butcher digital platforms that bypass traditional auction-yard intermediaries. These outlets capture consumers seeking custom fabrication and provenance verification.
- Convenience Stores:Limited cold-space formats stock pre-packaged cuts for immediate consumption in dense urban zones.
- Online Retail:E-commerce platforms with last-mile cold delivery serve time-constrained urban households seeking subscription-based protein procurement.
Supermarkets dominate absolute volume; online retail is gaining share fastest.
Customer Type:
Procurement scale separates institutional buyers from fragmented household demand, with each segment imposing incompatible specification and payment terms.
- Restaurants:Full-service establishments demand consistent portion-cut specifications and just-in-time delivery windows. Brazilian food services are expanding chilled beef procurement as consumer preferences shift toward premium cuts.
- Hotels:Multinational chains deploy blockchain traceability systems to document herd origin and welfare compliance, satisfying procurement officers with documented supply chain transparency.
- Households:Individual consumers purchase through retail channels with variable cut preferences and price sensitivity.
- Food Services:Contract catering and institutional feeding operations prioritize cost stability and volume security over product differentiation.
Food services retain volume leadership; hotels hold the steepest expansion curve.
End Use Industry:
Application requirements fragment beef utilization across human consumption, animal nutrition, and industrial processing with divergent specification standards.
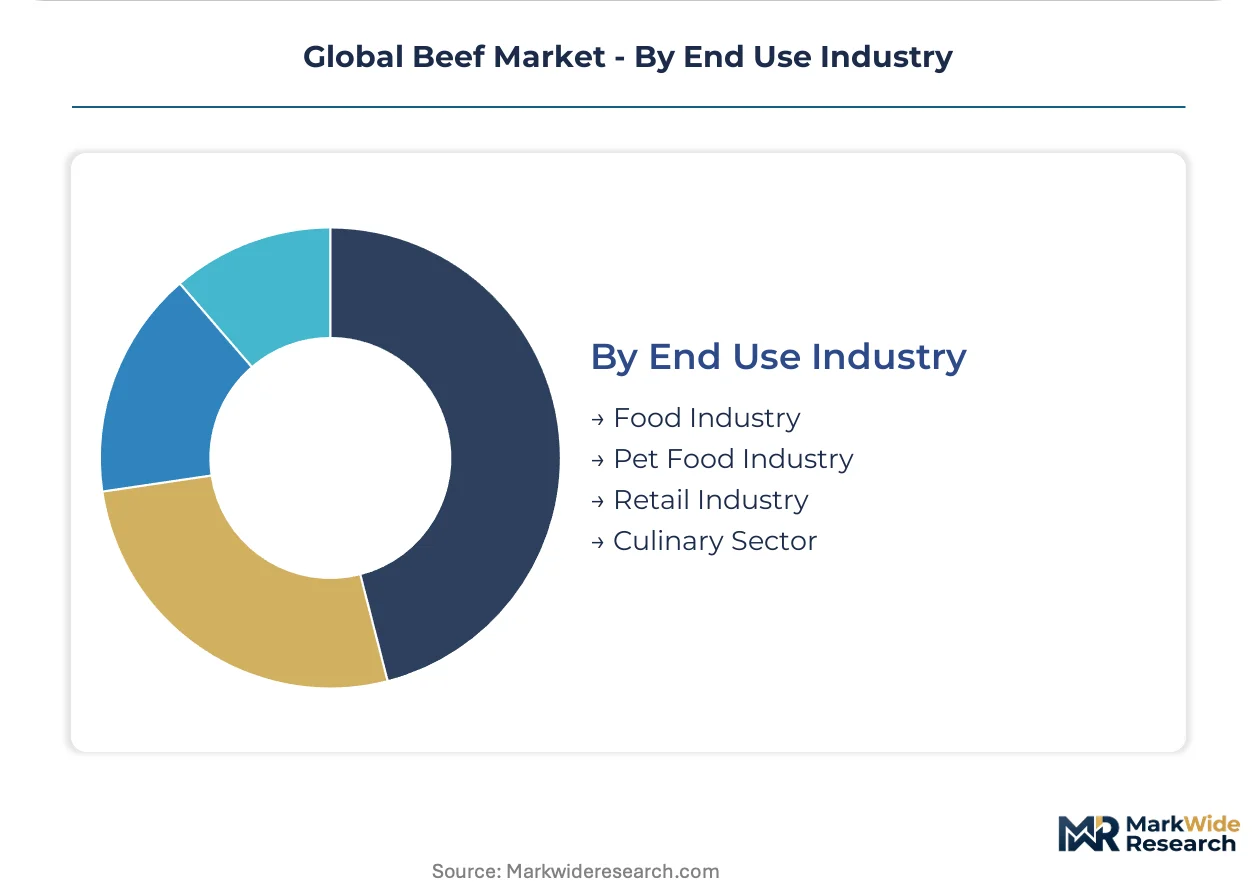
- Food Industry:Human consumption spans fresh retail, food service, and further processing into value-added products. EU Green Deal methane mandates are rewarding verified low-methane suppliers with preferential access.
- Pet Food Industry:Rendered byproducts and mechanically separated material supply shelf-stable protein inputs with stable demand.
- Retail Industry:Merchandising operations encompassing supermarkets, butcher shops, and e-commerce platforms that manage cold-chain presentation.
- Culinary Sector:Chef-driven establishments emphasizing origin stories, aging protocols, and breed-specific characteristics for menu differentiation.
The food industry retains volume leadership; the culinary sector holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers demonstrate the lowest price elasticity as urban households absorb premium grain-fed imports, while Brazilian food services exhibit higher sensitivity to feed cost swings. European procurement officers now weight methane intensity above landed price in supplier scorecards. Australian exporters capture climate premiums through regenerative grazing certification.
United States
Feedlot operators in the Texas Panhandle and Kansas are consolidating under packer-owned supply agreements that guarantee throughput volumes. USDA FSIS inspection mandates determine market access eligibility for both domestic production and imported carcasses. The Nebraska-Iowa corridor anchors the largest concentration of federally inspected slaughter capacity, where Tyson Foods and Cargill operate integrated fabrication facilities.
Brazil
Food service operators across São Paulo and Rio de Janeiro are expanding chilled beef procurement as consumer preferences shift toward premium cuts. MAPA coordinates equivalence agreements with the EU Commission that shape export eligibility for South American packers. Mato Grosso, Goiás, and São Paulo states account for over two-thirds of federally inspected slaughter capacity, creating operational bottlenecks during labor disputes.
China
Urban households in Shanghai and Beijing are consuming more imported grain-fed beef through membership-based supermarket channels, displacing wet-market pork transactions. SAMR GB standards govern label claims and residue limits that incoming suppliers must satisfy. Cold-chain infrastructure expansion into tier-two cities like Chengdu and Hangzhou is enabling premium chilled product penetration beyond coastal metros.
Australia
European retail chains are rewarding Australian exporters with verified low-methane supply chains through preferential shelf placement and long-term contracts. The national carbon credit framework rewards rotational grazing practices that reduce enteric fermentation emissions. Queensland and New South Wales grazing regions are capturing premium positioning in climate-conscious German and Dutch supermarket tenders.
Germany
Supermarket chains in Bavaria and North Rhine-Westphalia are excluding non-compliant packers from tender processes based on CSRD-mandated Scope 3 emissions disclosure. The EU F-Gas Regulation and Green Deal methane mandates are compelling importers to demand documentation from South American suppliers. The Hamburg-Bremen port cluster is reshaping import flows toward verified low-intensity supply origins.
Global Beef Market Vendor Landscape
Capability concentration sits with integrated packers controlling captive feedlot networks; scale advantage sits with diversified protein conglomerates spanning multiple species. The market structures around three tiers: multinational integrators with continental processing footprints, regional specialists commanding origin-specific certifications, and commodity traders arbitraging price differentials across ocean freight lanes. Dominant competitive moves include backward integration into cattle supply and geographic diversification of slaughter capacity to mitigate regulatory disruption.
Within the multinational integrator tier, JBS anchors Brazilian-origin supply flows through its North American feedlot network, while Tyson Foods exemplifies scale-driven boxed beef fabrication. Marfrig Global Foods occupies a position specializing in grass-fed and organic certifications that differentiate South American exports into European retail channels. These three entities represent the archetype spectrum from geographic diversification to premium certification capture.
| Leading Market Players |
|---|
| Marfrig Global Foods |
| Minerva Foods |
| JBS |
| Hormel Foods |
| BRF |
| Tyson Foods |
| National Beef Packing |
| Smithfield Foods |
| Cargill |
| Others |
Supply Flow & Price Mechanics
Feed grain price volatility determines both the spread between commodity chilled beef and premium grain-fed tiers and the geographic shape of procurement flows toward lower-cost grazing regions. Corn and soybean meal input swings compress feedlot margins and trigger destocking decisions that reshape supply availability across export channels.
Pricing Analysis
After-sales revenue from value-added processing and branded portion-cut programs drives lifetime value capture beyond carcass sales. Three-tier pricing structure across premium certified, standard commercial, and economy commodity levels separates chilled grain-fed exports from frozen grass-fed and rendered processing inputs. Pricing pressure stems from cell-cultured protein substitution diverting R&D investment and pilot procurement in Singapore and Israel. Food service operators exhibit highest price sensitivity due to feed cost pass-through volatility, while Chinese urban households demonstrate lowest elasticity for verified grain-fed imports.
Supply Chain Analysis
Supplier-financing through extended payment terms and supply-chain credit facilities anchors working capital flows between Brazilian cooperatives and European importers. Geographic concentration centers on Brazil, Australia, and the United States as dominant export origins. Raw material dependencies rest on corn and soybean meal feed inputs, breeding stock genetics, and veterinary pharmaceutical inventories. Single-source vulnerability concentrates in Mato Grosso, Goiás, and São Paulo states where labor disputes or sanitary suspensions interrupt federally inspected slaughter capacity. Distribution runs through cold-chain integrated packers with captive feedlot networks controlling ranch-to-retail pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Beef Market functions as a defensive-moat industry where regulatory entrenchment through equivalence agreements and residue compliance protocols creates durable barriers to new supply origins.
For Market Incumbents: Build regulatory moats through backward integration into certified low-methane feedlot networks and manure management systems. Secure long-term equivalence agreements with the EU Commission and SAMR ahead of carbon border adjustment implementation. Invest in blockchain traceability infrastructure to satisfy multinational hotel chain procurement requirements and exclude non-compliant competitors from tender processes.
For New Entrants and Emerging Players: Establish a beachhead in Indonesia's halal-certified segment where MUI alignment opens access to 270 million consumers with rising protein consumption. Target Australia's carbon credit framework for rotational grazing certification that commands premium positioning in German and Dutch supermarket channels. Deploy direct-to-butcher digital platforms connecting small-scale ranchers with independent meat shops to bypass established auction-yard intermediaries.
For Investors and Strategic Acquirers: EU Green Deal methane mandates reshaping the acquisition landscape toward verified low-intensity supply origins with documented Scope 3 emissions profiles. Long-term viability favors integrated packers with continental processing footprints and captive feedlot networks over commodity traders exposed to tariff and logistics volatility. Monitor carbon border adjustment implementation timelines as the critical inflection signal for asset repricing across South American export operations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Feedlots | JBS leverages North American feedlot networks to control cattle supply flows from ranch to packing plant. |
| Blockchain Traceability Deployment | Brazilian food service operators document herd origin and welfare compliance for multinational hotel chain procurement officers. |
| Halal Certification Alignment | MUI-standard compliance opens access to Indonesia's 270 million Muslim-majority population with rising protein consumption. |
| Carbon Credit Framework Participation | Australian exporters capture premium positioning in climate-conscious European retail through regenerative grazing certification. |
| Cold-Chain Infrastructure Expansion | SAMR-licensed importers penetrate Chinese tier-two cities through membership-based supermarket channel partnerships. |
Methodological Framework
Operator-level perspectives from feedlot managers, meat procurement officers at multinational hotel chains, cold-chain logistics directors, and regulatory affairs specialists at exporting cooperatives anchored the qualitative base. Primary interview insights combined with secondary validation from USDA FSIS inspection records, MAPA equivalence agreement documentation, SAMR GB standard filings, and EU Commission F-Gas Regulation implementation reports. Bottom-up volume modeling across product type, distribution channel, and customer type segments triangulated with top-down trade flow analysis.
Scenario-bracketing across feed grain price volatility bands, regulatory implementation timelines, and substitution elasticity assumptions framed the analytical envelope throughout the projection horizon. Segmentation dimensions modeled include preservation format, channel cold-chain capability, procurement scale tier, and end-use specification intensity. CAGRs derived from trend extrapolation of historical trade volumes adjusted for structural shifts in Chinese urban consumption patterns and European methane accounting protocol adoption. Industry-specific inputs encompassed feed conversion ratios, chilling capacity utilization rates, and equivalence agreement renewal probabilities.
Stress conditions across corn and soybean meal price spikes, EU carbon border adjustment enforcement intensity, and cell-cultured protein approval acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation pacing and consumer preference evolution. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Brisket Market
Meat Products
Grassfed Jerky Market
Meat Products
Lab-Grown Meat Market
Meat Products
Organic Halal Meat Market
Meat Products
Pork Meat Market
Meat Products
Europe Edible Meat Market
Meat Products
United States Edible Meat Market
Meat Products
North America Low Fat Sausage Market
Meat Products
Oman Poultry Meat Market
Meat Products
Bacon Flavors Market
Meat Products
Europe Bacon Market
Meat Products
Meat Market
Meat Products
Canned Chicken Market
Meat Products
Meat Paste Market
Meat Products
Middle East Edible Meat Market
Meat Products
3D Printed Meat Market