
 Brazil Meat Products Market | 2026-2036
Brazil Meat Products Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Meat Products Market Insights
Commodity trading margins is narrowing as processors invest in branded, value-added product lines. JBS leverages its vertically integrated cattle sourcing across the Amazon-Cerrado frontier to secure feedlot supply. BRF differentiates through antibiotic-free poultry certification and ready-to-cook portfolio depth. Marfrig anchors its position in premium beef exports to Middle Eastern and Asian markets.
Brazil meat products encompass fresh and processed animal proteins derived from cattle, swine, and poultry, subject to cold-chain preservation from slaughter through retail and graded by fat content, marbling, and pH levels for commercial trade. Poultry dominates volume throughput due to feed conversion efficiency and short production cycles, while processed meats command higher margin pools through seasoning, curing, and packaging value addition. Prime and Choice beef grades concentrate in southern Brazil's grass-fed systems and command export premiums, whereas Standard grade supplies domestic price-sensitive segments through supermarket and wholesale channels.
ANVISA governs additive limits and labeling standards, MAPA enforces sanitary inspection and SIF facility certification, and the EU Green Deal's deforestation-free supply chain requirements shape export market access protocols for Brazilian processors. These frameworks elevate compliance costs but create competitive filtration that rewards certified, traceable operations. Stakeholders must monitor evolving traceability mandates and carbon accounting rules that will redefine procurement qualifications and market eligibility.
Market Dynamics
MAPA's updated sanitary inspection protocols and SISBI certification requirements are compressing processing capacity toward certified facilities, filtering out informal operators and elevating compliance costs across Brazil's slaughtering corridor.
Growth Catalysts
- EU Green Deal deforestation-free mandates:Brazilian exporters with traceable Amazon-Cerrado supply chains secure preferential European market access, rewarding certified ranchers and integrated processors.
- Foodservice premium procurement:Brazilian steakhouse chains and hotel operators are expanding contracts for Prime-grade beef and antibiotic-free poultry cuts, pulling volume toward value-added processing lines.
- Paraná's integrated poultry cluster:Feed mill-to-slaughter coordination within this region achieves sub-40-day production cycles, driving cost efficiency that exports compete on.
Market Restraints
- Feed grain price volatility:Corn and soybean meal costs in Mato Grosso fluctuate with international commodity futures, compressing processor margins during El Niño harvest disruptions.
- Amazon basin supply concentration:Cattle sourcing dependence on the Amazon-Cerrado frontier exposes processors to deforestation monitoring scrutiny and export market exclusion risks.
- Technical cold-chain gaps:Last-mile refrigeration failures in Brazil's northern states limit shelf-life extension for fresh cuts, constraining distribution radius for unprocessed product.
Strategic Opportunities
- Ready-to-cook portfolio expansion:Marinated and pre-seasoned poultry products command margin premiums in São Paulo's urban retail channels, capturing time-constrained household demand.
- Carbon accounting integration:Early adoption of livestock emissions measurement protocols positions certified operators for forthcoming EU carbon border adjustment mechanisms.
- Halal certification depth:Dedicated slaughter lines for Middle Eastern markets unlock export volume pools that standard Brazilian facilities cannot access.
Industry Challenges
- Veterinary inspector certification backlog:MAPA's SIF facility approval queues extend 14-18 months, freezing capacity expansion timelines for mid-scale processors.
- Legacy traceability system integration:Ranch-level electronic ear-tagging mandates require IT infrastructure upgrades that smaller cooperatives struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Meat Products Market |
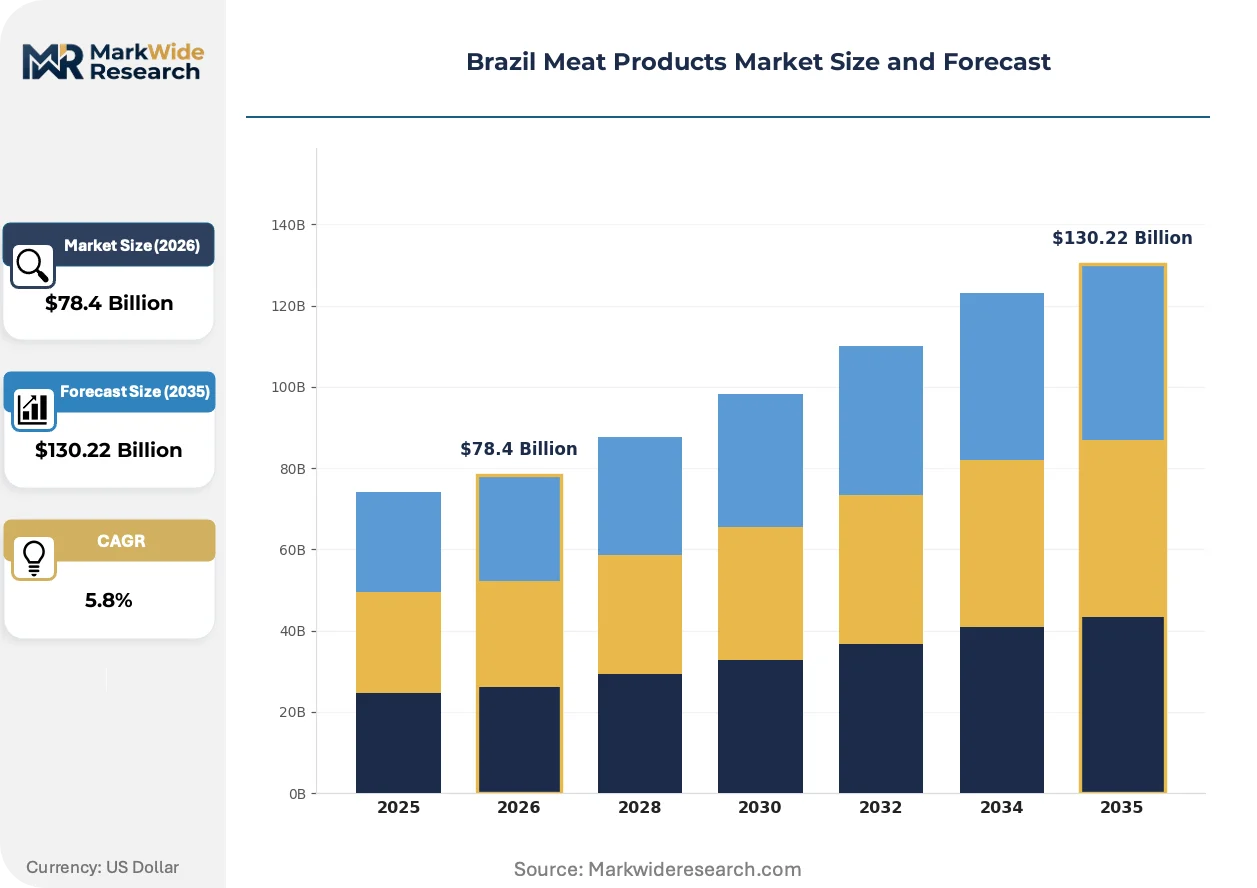
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $130.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Poultry, Processed Meats Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesale Quality Grade: Prime, Choice, Select, Standard Consumer Type: Households, Restaurants, Catering Services, Institutions |
| Companies Covered | BRF, Aurora Alimentos, JBS, Frigorífico Jundiá, Frigorífico Borusã, Minerva, Pilgrim's Brasil, Masterboi, Marfrig, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Meat Products Market Trends and Innovations
Digital infrastructure is penetrating Brazil's meat supply chain at the ranch gate, compressing information asymmetries between producers and processors while enabling new verification and trading mechanisms.
Blockchain-based cattle provenance tracking is virtualizing the documentation of animal movement from birth through slaughter. Large export-oriented processors are deploying these systems to satisfy EU and Chinese import documentation requirements. The technology is virtualizing compliance costs into competitive filtration, advantaging capitalized operators over informal competitors.
ANVISA's updated additive limits and labeling standards are tightening formulation constraints for processed meat categories. Manufacturers must reformulate cured products to meet reduced nitrite ceilings, elevating R&D expenditure. The regulatory pressure concentrates most intensely on São Paulo state's sausage and deli meat producers, who are accelerating natural preservative substitution programs.
Direct procurement contracts between supermarket banners and certified ranchers are displacing traditional livestock auction channels in southern Brazil. Retailers including Carrefour and GPA are securing volume commitments with traceability guarantees, compressing the spot market's role in price discovery. This pattern is most visible in Rio Grande do Sul's grass-fed beef corridor, where branded origin programs now capture shelf space previously held by generic cuts.
Brazil Meat Products Market Segmentation
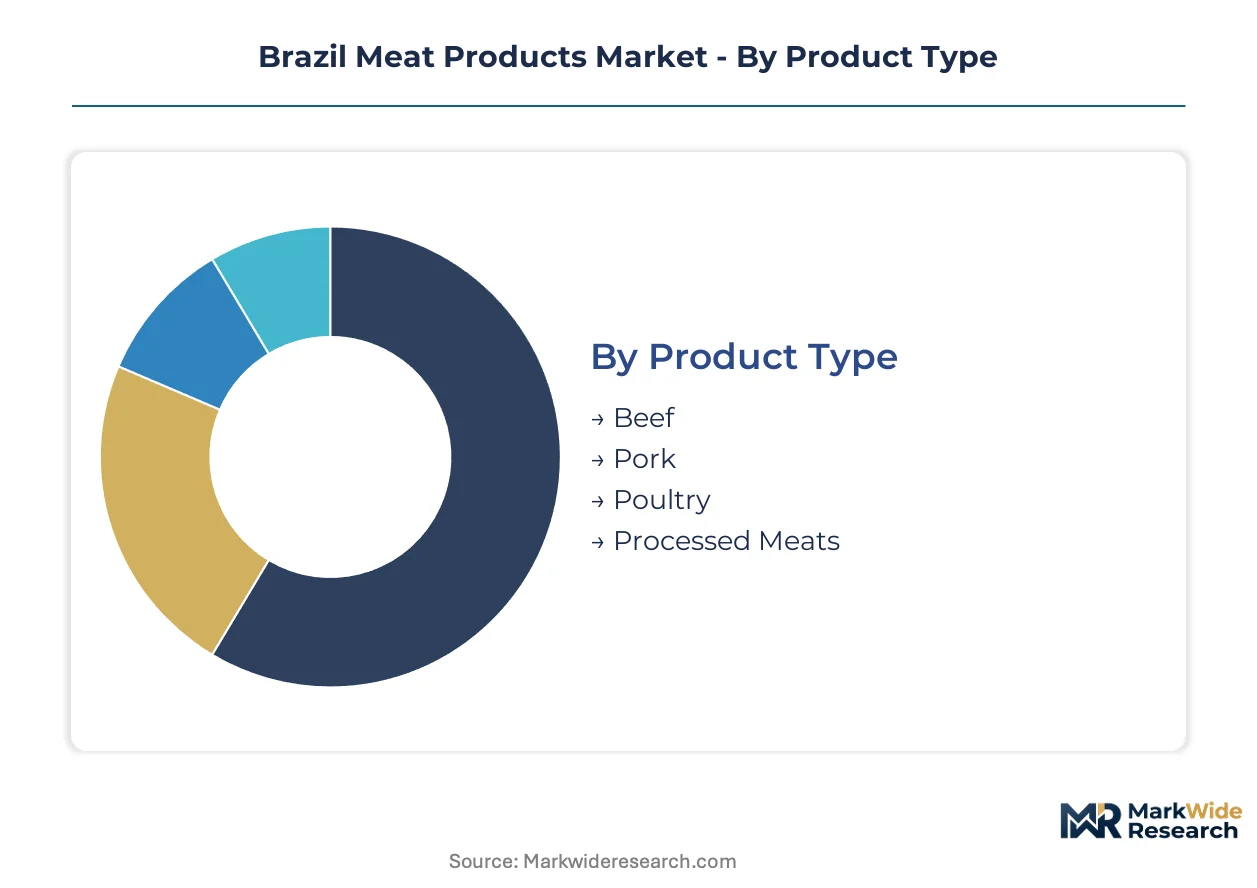
Brazil's meat products market fragments across production cycles, distribution economics, and certification tiers that reshape procurement patterns. Each segmentation axis reveals distinct margin pools and compliance thresholds that processors must navigate.
Product Type:
Poultry cycles through production in under 40 days, while cattle require 24-30 months from breeding to slaughter weight, creating divergent capital intensity and price volatility profiles.
- Poultry:Short production cycles and superior feed conversion efficiency concentrate volume throughput in Paraná's integrated cluster. São Paulo foodservice operators pull antibiotic-free certified cuts into premium ready-to-cook lines.
- Beef:Grass-fed systems in Rio Grande do Sul and Mato Grosso supply graded carcasses with traceable Amazon-Cerrado documentation for EU export eligibility. Marfrig and JBS anchor procurement networks across the frontier.
- Pork:Southern Brazil's grain-proximate operations supply domestic processing and limited export channels, constrained by MAPA sanitary protocols and regional disease monitoring zones.
- Processed Meats:Cured and seasoned products face ANVISA reformulation mandates on nitrite ceilings, elevating R&D spend for São Paulo sausage and deli manufacturers.
Poultry anchors the volume base while processed meats gain share at the steepest rate through margin expansion in urban retail.
Distribution Channel:
Channel selection determines cold-chain investment requirements and traceability documentation burdens that filter processor participation.
- Supermarkets:Carrefour and GPA banners in São Paulo and Rio de Janeiro secure direct rancher contracts with blockchain-verified origin claims, displacing traditional auction price discovery.
- Wholesale:São Paulo's CEAGESP and Porto Alegre terminals handle ungraded volume for price-sensitive institutional buyers, requiring minimal certification documentation.
- Convenience Stores:Frozen and chilled grab-and-go formats in urban corridors demand compact packaging and extended shelf-life solutions from mid-scale processors.
- Online Retail:Delivery platforms in Belo Horizonte and Curitiba test subscription meat boxes with temperature-tracked logistics, though last-mile refrigeration gaps constrain northern expansion.
Wholesale channels dominate volume throughput while supermarket direct procurement climbs fastest as retailers consolidate supply control.
Quality Grade:
Grade differentiation separates export-accessible premium pools from domestic commodity segments with divergent traceability and certification requirements.
- Prime:Intramuscular fat deposition and pH specifications command Middle Eastern and Asian export premiums. Southern Brazil grass-fed systems supply this tier through Marfrig's dedicated processing lines.
- Choice:Moderate marbling grades concentrate in domestic steakhouse chains and hotel foodservice contracts with origin-labeling requirements.
- Select:Leaner specifications serve supermarket private-label programs and quick-service restaurant grinding operations with cost-focused procurement.
- Standard:Ungraded commodity volume fills northern domestic wholesale channels where cold-chain limitations prevent fresh-cut distribution radius extension.
Standard grade carries the volume base while Prime certification expands most quickly through export market access rewards.
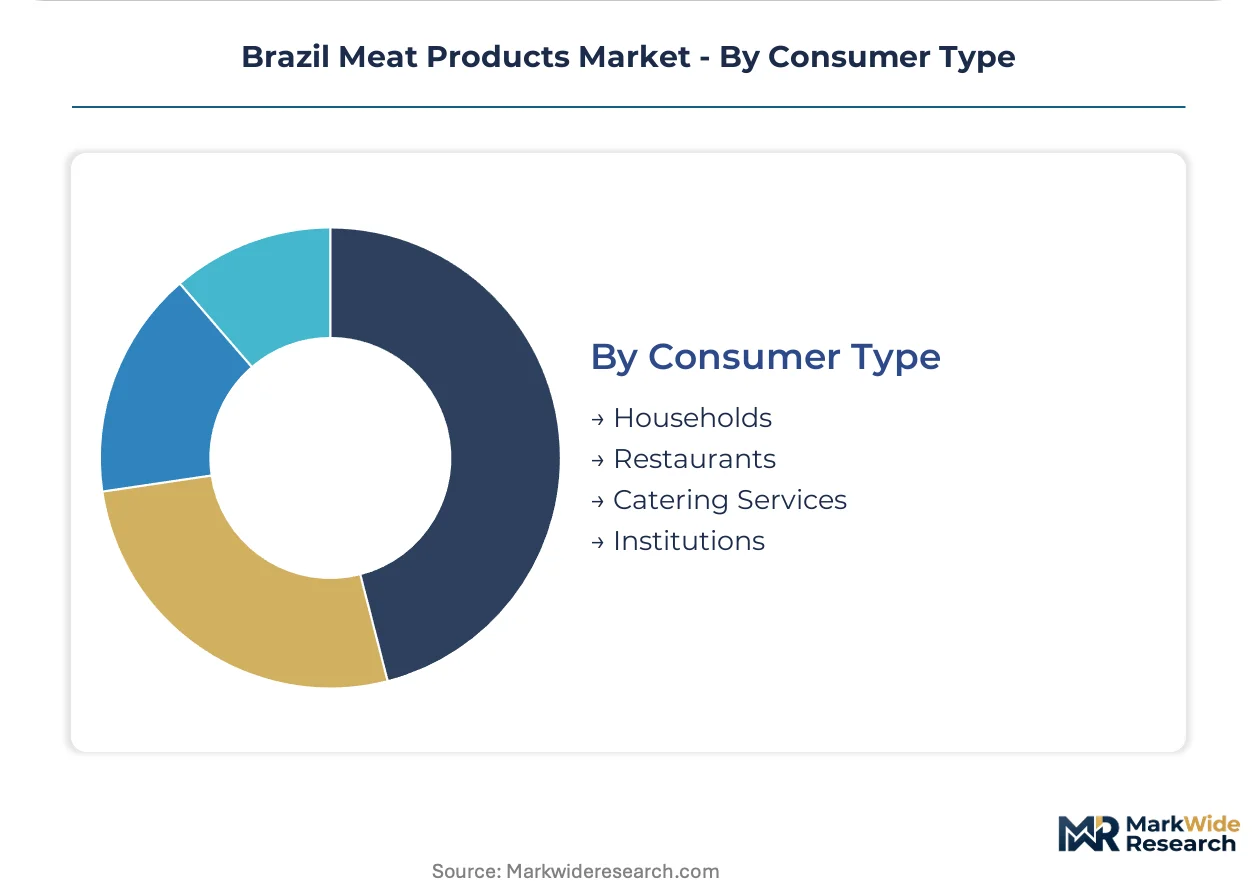
Consumer Type:
End-use segmentation reveals diverging service requirements from traceability documentation to portion specifications and delivery scheduling.
- Restaurants:Brazilian steakhouse chains and hotel operators specify Prime beef and antibiotic-free poultry with volume commitments that pull supply toward value-added processing.
- Households:Time-constrained urban demand in São Paulo and Curitiba drives marinated and pre-seasoned poultry product uptake through retail freezer sections.
- Catering Services:Event and institutional feeders require consistent portion control and scheduled delivery windows that favor large-processor contract relationships.
- Institutions:School and hospital nutrition programs operate under rigid cost ceilings and MAPA procurement compliance that limit supplier pools to SIF-certified facilities.
Household retail absorbs the volume base while restaurant premium procurement accelerates fastest as foodservice operators upgrade protein specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across Brazilian states, with southern regions prioritizing premium graded beef for export channels while northern states concentrate on unprocessed commodity volume constrained by cold-chain limitations.
São Paulo
Foodservice operators in São Paulo's metropolitan corridor drive demand for antibiotic-free poultry and Prime-grade beef cuts. ANVISA's additive limits and labeling standards impose reformulation costs on local sausage and deli manufacturers. The state's industrial slaughtering corridor hosts integrated processing facilities serving both domestic retail and export documentation requirements.
Paraná
Feed mill-to-slaughter coordination achieves sub-40-day poultry production cycles that supply cost-competitive export volume. MAPA's SISBI certification requirements filter processing capacity toward certified facilities within the integrated cluster. Maringá and Londrina anchor feed conversion efficiency gains that processors leverage for Middle Eastern and Asian market access.
Rio Grande do Sul
Grass-fed beef systems supply Prime and Choice grades with traceable origin claims for European and Middle Eastern export premiums. Carrefour and GPA banners secure direct rancher contracts with blockchain-verified documentation, displacing traditional livestock auction channels. The state's branded origin programs capture supermarket shelf space previously held by generic cuts.
Mato Grosso
Cattle sourcing dependence on the Amazon-Cerrado frontier exposes processors to deforestation monitoring scrutiny and EU Green Deal supply chain exclusion risks. Corn and soybean meal cost fluctuations compress margins during El Niño harvest disruptions. Sinop and Rondonópolis feedlots supply the volume base for JBS's vertically integrated procurement networks.
Minas Gerais
Dairy-beef crossbreeding systems and poultry integration supply domestic processing channels with lower certification documentation burdens. Technical cold-chain gaps in northern municipalities limit fresh-cut distribution radius extension. Belo Horizonte's urban retail channels test subscription meat boxes with temperature-tracked logistics platforms.
Brazil Meat Products Market Competitive Landscape
Capability concentration sits with integrated processors commanding traceable supply chains; scale advantage sits with diversified protein houses spanning multiple species and geographies. The market structures around three tiers: multinational exporters with SIF-certified facility networks, mid-scale regional processors serving domestic wholesale channels, and cooperative aggregators supplying spot-market volume. Strategic moves center on backward integration into feedlot and ranch operations, plus portfolio diversification into ready-to-cook and marinated product lines.
Within the multinational exporter tier, JBS, Marfrig, and BRF occupy positions that exemplify divergent specialization vectors. JBS anchors cattle sourcing breadth across the Amazon-Cerrado frontier. Marfrig concentrates premium beef export access to Middle Eastern and Asian markets. BRF represents poultry-centric diversification with antibiotic-free certification depth and ready-to-cook portfolio breadth. Aurora Alimentos and Minerva sit within the mid-scale regional tier, supplying domestic channels with lower documentation burdens.
| Leading Market Players |
|---|
| BRF |
| Aurora Alimentos |
| JBS |
| Frigorífico Jundiá |
| Frigorífico Borusã |
| Minerva |
| Pilgrim's Brasil |
| Masterboi |
| Marfrig |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in São Paulo state's industrial slaughtering corridor compresses processor margins and forces selective facility closures, while undercapacity in Paraná's integrated poultry cluster sustains pricing power for certified operators. This utilization divergence reshapes procurement negotiations and capital allocation across Brazil's protein processing landscape.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between large processors and supermarket banners, though spot market volume persists in wholesale channels serving price-sensitive institutional buyers. Price differentiation stems from quality grade certification and ANVISA compliance tier, with Prime beef and antibiotic-free poultry commanding substantial premiums over Standard grade commodity cuts. Pricing pressure intensifies in the Standard tier as feed grain cost volatility in Mato Grosso compresses processor margins during El Niño disruptions. Foodservice operators exhibit the least price sensitivity, while northern wholesale buyers demonstrate acute cost consciousness that limits branded product penetration.
Supply Chain Analysis
EU Green Deal deforestation-free supply chain requirements restrict market access for Brazilian exporters lacking traceable Amazon-Cerrado documentation, filtering eligible volume toward certified ranchers and integrated processors. Geographic supply concentration centers on Brazil's southern states—Paraná for poultry, Rio Grande do Sul for grass-fed beef, and São Paulo for processed meat manufacturing—while Mato Grosso anchors cattle feedlot operations. Raw material dependencies include corn and soybean meal for feed formulation, veterinary pharmaceuticals for herd health, and packaging materials for shelf-life extension. Single-source vulnerability runs through Amazon basin cattle sourcing exposed to deforestation monitoring scrutiny. Distribution runs through cold-chain networks reaching supermarket direct procurement, wholesale terminals, and emerging subscription delivery platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in Brazil's meat products market center on temperature-tracked logistics and blockchain-verified traceability subscriptions, recurring-revenue layers expanding faster than base commodity processing as retailers and exporters demand documentation depth.
For Market Incumbents: Entrench defensible positions by deepening backward integration into feedlot operations across the Amazon-Cerrado frontier to secure supply amid deforestation scrutiny, and accelerate SISBI certification investment to filter out mid-scale competitors facing MAPA approval backlogs. Threats concentrate in emerging plant-based substitutes and EU carbon border adjustment mechanisms that could reshape export eligibility. Channel control through direct supermarket contracts represents the critical lever for margin protection. For New Entrants and Emerging Players: Establish a beachhead in ready-to-cook marinated poultry products for São Paulo's time-constrained urban households, where incumbent portfolio gaps and premium pricing tolerance create penetrable whitespace. Halal-certified processing for Middle Eastern export channels offers a second viable entry vector given dedicated slaughter line requirements that standard facilities cannot satisfy. Go-to-market execution should prioritize partnerships with established cold-chain logistics operators rather than greenfield infrastructure buildout. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among processors with integrated traceability platforms and long-term supermarket contracts, positioning these archetypes for superior cash flow quality across extended holding periods. Acquisition targets should display SIF-certified facility networks with underutilized capacity in Paraná or Rio Grande do Sul. The signal to watch is MAPA regulatory acceleration that could compress approval timelines and unlock stranded capacity value.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedlot Operations | JBS-style captive cattle supply secures volume through Amazon-Cerrado sourcing networks. |
| Blockchain Traceability Platform Deployment | EU Green Deal compliance documentation unlocks preferential European market access. |
| Halal Certification Line Investment | Dedicated Middle Eastern slaughter capacity accesses export pools standard facilities cannot reach. |
| Ready-to-Cook Portfolio Expansion | Marinated poultry products capture São Paulo urban retail premium pricing. |
| Carbon Accounting Protocol Adoption | Early livestock emissions measurement positions operators for forthcoming EU border adjustments. |
Research Methodology
Cross-validation between processor procurement executives and supermarket category buyers anchors the qualitative findings, supplemented by regulatory affairs specialists at MAPA and ANVISA, veterinary inspectors, and cold-chain logistics operators. Secondary sources include MAPA slaughter and inspection databases, ANVISA additive regulation filings, EU Green Deal technical documentation, and customs export records. Bottom-up facility capacity assessments and top-down consumption modeling triangulate volume estimates across the analysis window.
Calibration against historical price series and production cycle data refines the analytical framework. Segmentation dimensions span product type, distribution channel, quality grade, and consumer type, with regional regulatory cluster as an additional meat-specific dimension. CAGRs derive from trend extrapolation moderated by capacity constraint analysis and certification penetration assumptions. Feed conversion efficiency trajectories and cold-chain infrastructure deployment schedules constitute key forecast inputs.
Sensitivities concentrate around EU deforestation enforcement stringency, El Niño recurrence patterns affecting feed costs, and MAPA inspector certification throughput. Forecasts reflect documented assumptions about regulatory continuity and trade agreement stability. Material shifts in Amazon monitoring protocols or carbon border implementation timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
France Meat Products Market
Meat Products
Qatar Poultry Meat Market
Meat Products
India Edible Meat Market
Meat Products
Raw Chicken Feet Market
Meat Products
Middle East Red Meat Market
Meat Products
Poultry Processing Meat Market
Meat Products
South Africa Processed Meat Market
Meat Products
Global Duck Meats Market
Meat Products
North America Red Meat Market
Meat Products
Meat Products Market
Meat Products
Pork Flavors Market
Meat Products
Organic Eggs Market
Meat Products
United Arab Emirates Red Meat Market
Meat Products
Emulsified Meat Market
Meat Products
Meat Mincers Market
Meat Products
Bacon Flavors Market