
 Middle East Edible Meat Market | 2026-2036
Middle East Edible Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Edible Meat Market Foresight
Consolidation among Gulf-based food service buyers is rebalancing bargaining power toward large catering groups and chain restaurants. Almarai Company leverages its integrated dairy-to-meat supply infrastructure to control cold-chain distribution across Saudi Arabia. BRF S.A. competes through frozen poultry exports that anchor Brazilian supply into UAE and Kuwait ports. Tanmiah Food Company specializes in fresh chilled chicken, differentiating against commodity frozen imports with shorter shelf-life guarantees.
Edible meat encompasses muscle tissue from slaughtered livestock and poultry, processed under halal protocols requiring complete blood drainage and avoidance of prohibited additives, then chilled or frozen to maintain microbiological safety below 4 degrees Celsius for commercial distribution. The primary purpose spans direct household consumption, institutional catering, and further processing into value-added products such as sausages and breaded portions. Poultry dominates volume due to lower feed conversion ratios and faster breeding cycles that compress production economics versus beef and lamb. Frozen packaging leads in wholesale trade, while vacuum-sealed fresh formats capture premium margins in supermarket channels serving upscale households.
Saudi Food and Drug Authority and UAE Ministry of Climate Change and Environment enforce halal slaughter standards and import residue limits that shape product eligibility for domestic sale. Gulf Standardization Organization harmonization efforts are reducing cross-border compliance costs for suppliers operating in multiple member states. Stakeholders must monitor evolving antibiotic-free certification requirements and local capacity buildouts that could redirect import dependency patterns.
Market Dynamics
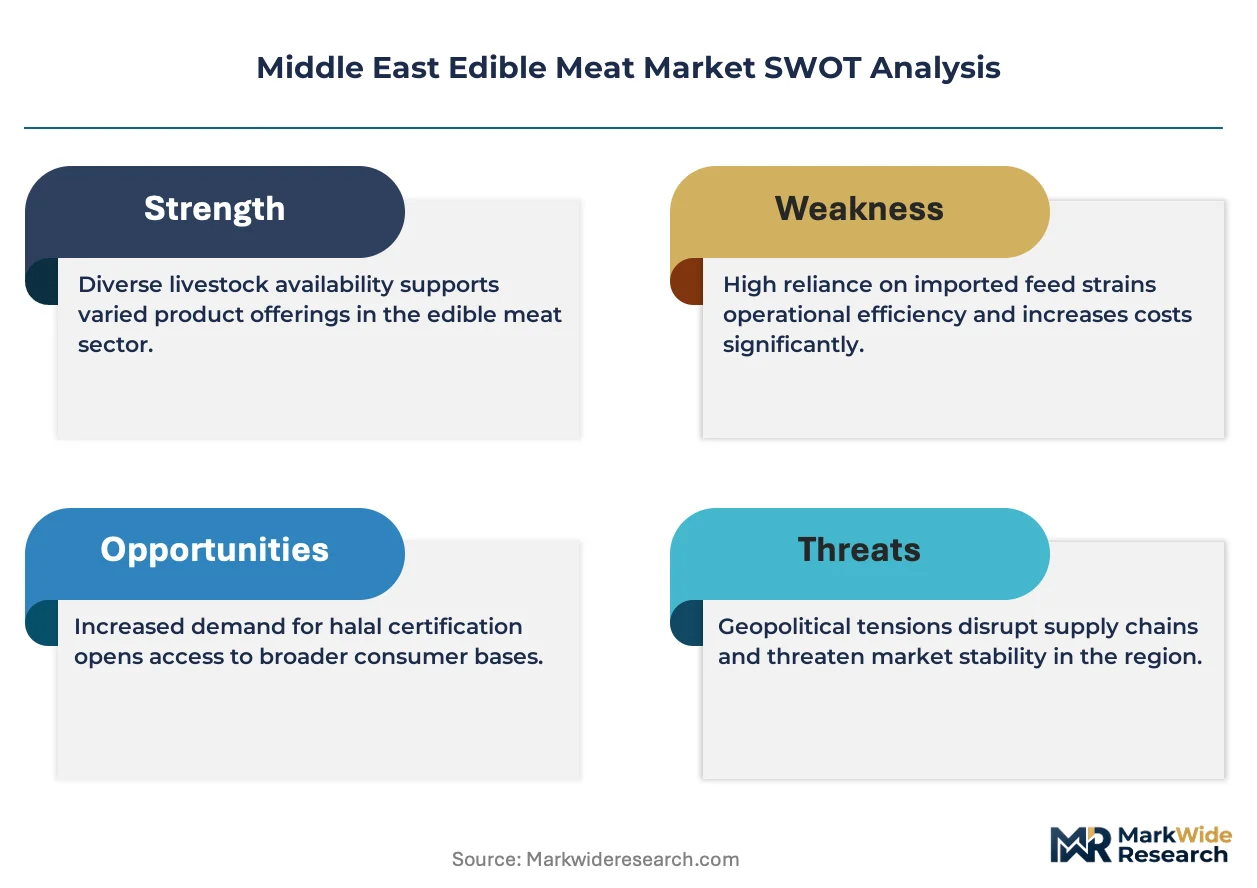
Halal traceability mandates from Saudi Food and Drug Authority and UAE Ministry of Climate Change and Environment are forcing cold-chain infrastructure upgrades across the Gulf, compressing margins for importers while rewarding integrated domestic producers with compliance-ready systems.
Growth Catalysts
- Gulf Standardization Organization harmonization:Unified halal certification protocols reduce cross-border compliance duplication for suppliers operating across Saudi Arabia, UAE, Kuwait, and Oman.
- Quick-service restaurant expansion:Chained food service buyers in Riyadh and Dubai are consolidating procurement volumes, creating dedicated supply agreements that lock in chilled poultry volumes.
- Poultry integration projects:Saudi government food security initiatives are funding large-scale breeding-to-processing facilities that compress feed-to-retail timelines.
Market Restraints
- Feed input volatility:Corn and soybean meal price swings transmit directly into broiler production economics, squeezing integrated operators with captive breeding operations.
- Import concentration risk:Brazilian frozen poultry dominates UAE and Kuwait port volumes, exposing buyers to currency fluctuation and shipping disruption at Santos and Paranaguá terminals.
- Antibiotic residue limits:SFDA and MOHAP enforcement of maximum residue levels for tetracyclines and fluoroquinolones blocks entry for non-compliant South American and Asian suppliers.
Strategic Opportunities
- Kuwait and Bahrain penetration:Underdeveloped chilled meat distribution networks in these markets create first-mover advantages for vacuum-sealed fresh poultry specialists.
- Antibiotic-free certification:Premium positioning aligned with EU Green Deal export standards opens high-margin supermarket channels serving health-conscious households in Jeddah and Abu Dhabi.
- Direct-to-hotel procurement platforms:Digital tendering systems are bypassing traditional importer-wholesaler layers, connecting Qatari hospitality groups directly to Saudi processing plants.
Industry Challenges
- Halal auditor scarcity:Certified slaughter supervisors and supply chain traceability specialists command premium wages, constraining expansion timelines for new processing facilities.
- Cold-chain capex intensity:Blast freezing and controlled-atmosphere storage requirements demand substantial upfront investment, favoring incumbent players with existing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Edible Meat Market |
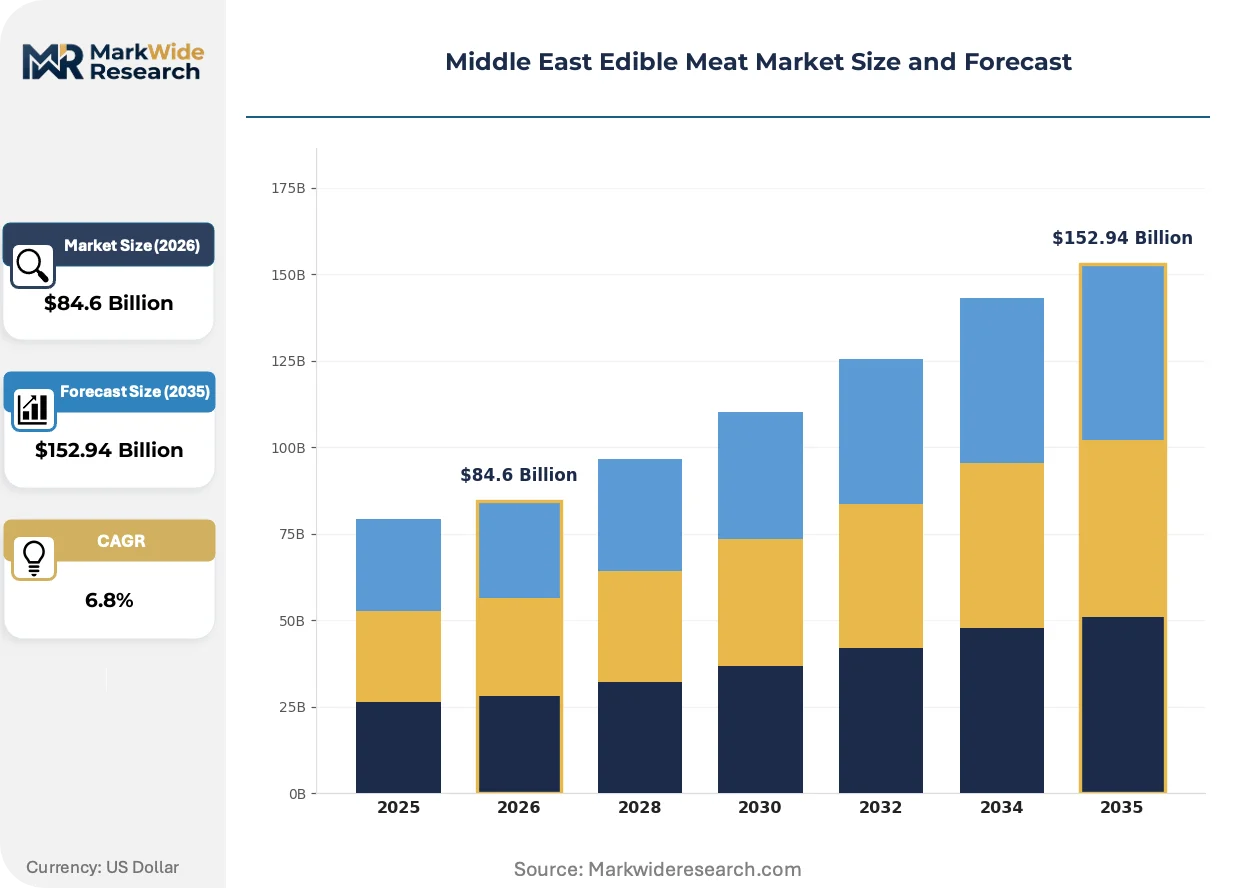
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $152.94 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry, Beef, Lamb, Goat Distribution Channel: Retail Stores, Online Stores, Wholesale Markets, Supermarkets End User: Restaurants, Households, Caterers, Food Processors Packaging Type: Vacuum Packaged, Canned, Fresh, Frozen |
| Companies Covered | Al Ain Farms, BRF S.A., Siniora Food Industries Company, Tanmiah Food Company, The Savola Group, Almarai Company, Al Islami Foods, Americana Group, Al-Watania Poultry, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Edible Meat Market Shifts & Advancements
Automation in slaughter and portioning lines is compressing labor dependency while vacuum-skin packaging formats are capturing shelf-space from traditional MAP trays in premium retail channels.
Controlled-atmosphere stunning systems that replace electrical water-bath methods are overtaking conventional halal slaughter configurations in Saudi processing plants. Jeddah-based facilities are retrofitting gas-stunning tunnels to meet EU export eligibility while maintaining religious compliance. This technology is overtaking legacy setups by enabling simultaneous access to domestic supermarkets and high-value European halal markets.
SFDA implementation of blockchain-enabled traceability mandates requires real-time temperature and origin data submission for all imported chilled meat. The regulation forces importers to deploy IoT-enabled container monitoring or face port detention. Brazilian and Australian exporters are responding by pre-certifying supply chains through approved third-party auditors before shipment departure.
Central kitchen consolidation among UAE-based hospitality groups is compressing supplier rosters from fragmented local butchers to single-source national distributors. Hotel chains in Dubai and Abu Dhabi are mandating quarterly microbiological audits and fixed-price annual contracts. This pattern is most visible in the four-star and five-star segment, where procurement directors prioritize liability reduction over unit cost minimization.
Middle East Edible Meat Market Segmentation
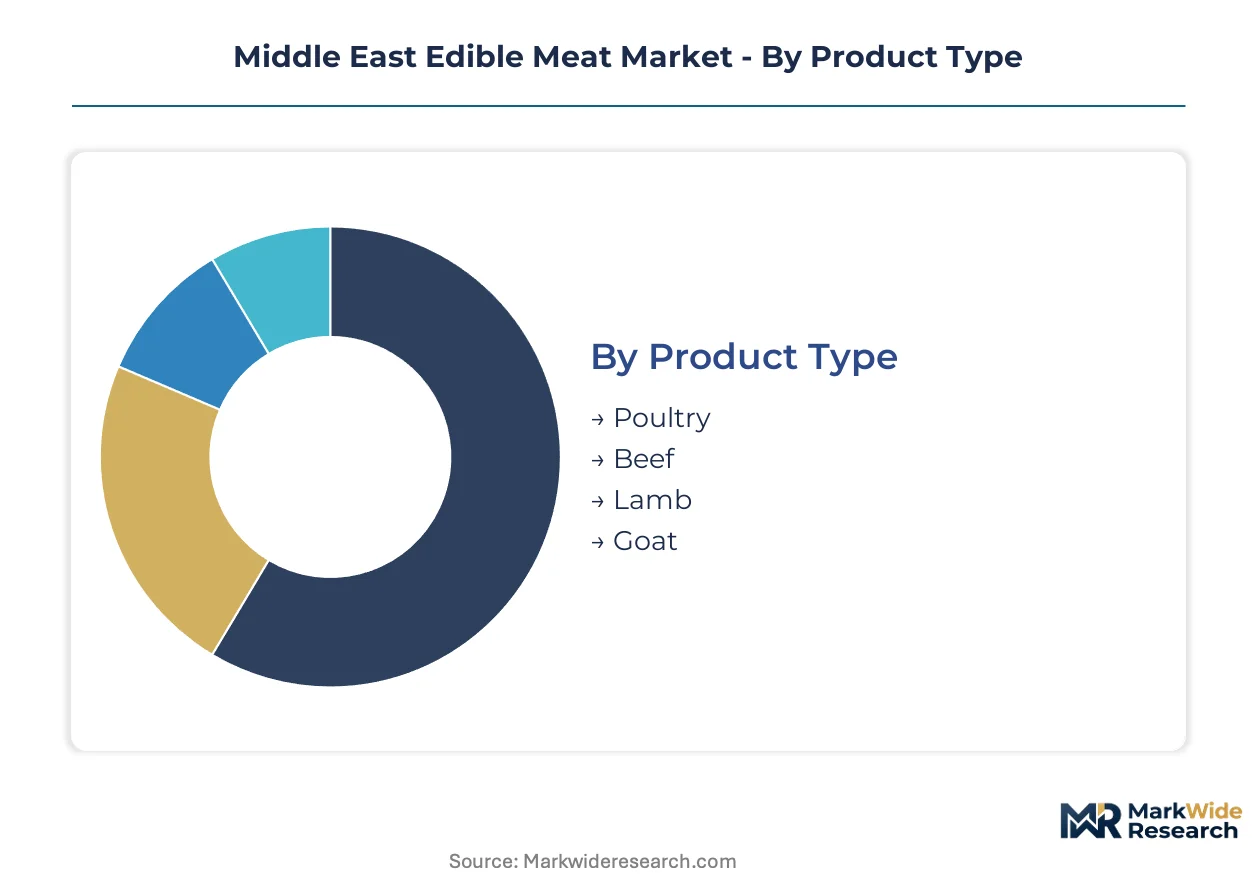
Segmentation reveals how capital deployment and regulatory compliance vary sharply across product and channel dimensions. Each category carries distinct infrastructure requirements that reshape competitive entry barriers and margin structures.
Product Type:
Poultry and beef operations demand the heaviest upfront investment in breeding facilities, feed mills, and controlled-atmosphere stunning systems that satisfy both halal protocols and export eligibility standards.
- Poultry:Broiler production compresses feed-to-slaughter timelines through vertically integrated breeding-to-processing facilities. Saudi government food security initiatives concentrate procurement volumes in Riyadh and Jeddah, where integrated operators capture economies of scale that commodity importers cannot replicate.
- Beef:Cattle finishing requires extended holding periods and specialized abattoir infrastructure for complete blood drainage compliance. UAE Ministry of Climate Change and Environment residue testing blocks entry for South American suppliers with tetracycline violations, tightening eligible supply pools for Dubai hospitality buyers.
- Lamb:Seasonal demand spikes around religious observances strain cold-storage capacity across Gulf ports.
- Goat:Niche volumes serve traditional household preparation methods with minimal processing value-add.
Poultry absorbs the bulk of installed capacity; beef is expanding most quickly as hotel chains consolidate procurement around audited national distributors.
Distribution Channel:
Channel selection determines working capital intensity and halal traceability compliance burdens, with direct-to-institutional routes demanding the most sophisticated cold-chain documentation.
- Retail Stores:Neighborhood butcher counters rely on daily fresh deliveries with minimal inventory carry, limiting margin capture to commodity spreads. Neighborhood networks in Kuwait and Bahrain remain fragmented, creating consolidation opportunities for vacuum-sealed specialists with shorter shelf-life guarantees.
- Supermarkets:Hypermarket chains in Riyadh and Dubai mandate fixed-price annual contracts with quarterly microbiological audits. Vacuum-skin packaging formats displace traditional MAP trays as retailers compete for premium household positioning.
- Wholesale Markets:Centralized port-side trading concentrates Brazilian frozen poultry volumes at Santos-originated price benchmarks.
- Online Stores:Digital tendering platforms bypass importer-wholesaler layers, connecting Qatari hospitality groups directly to Saudi processing plants with real-time temperature monitoring.
Supermarkets absorb the bulk of installed capacity; online stores are climbing the fastest as blockchain-enabled traceability mandates force IoT deployment.
End User:
End-user concentration shapes contract structures, with institutional buyers extracting liability protections that fragment supplier rosters and compress spot-market liquidity.
- Restaurants:Quick-service chains in Dubai and Riyadh lock in dedicated chilled poultry volumes through multi-year supply agreements. Consolidated procurement volumes rebalance bargaining power toward large catering groups with quarterly audit requirements.
- Caterers:Central kitchen consolidation among UAE hospitality groups compresses supplier rosters from fragmented local butchers to single-source national distributors. Four-star and five-star procurement directors prioritize liability reduction over unit cost minimization.
- Households:Direct consumption spans fresh counter purchases and premium vacuum-sealed retail formats.
- Food Processors:Further processing into sausages and breaded portions demands consistent specification batches that integrated breeders can guarantee.
Restaurants absorb the bulk of installed capacity; caterers are gaining share fastest as hotel chains mandate fixed-price annual contracting.
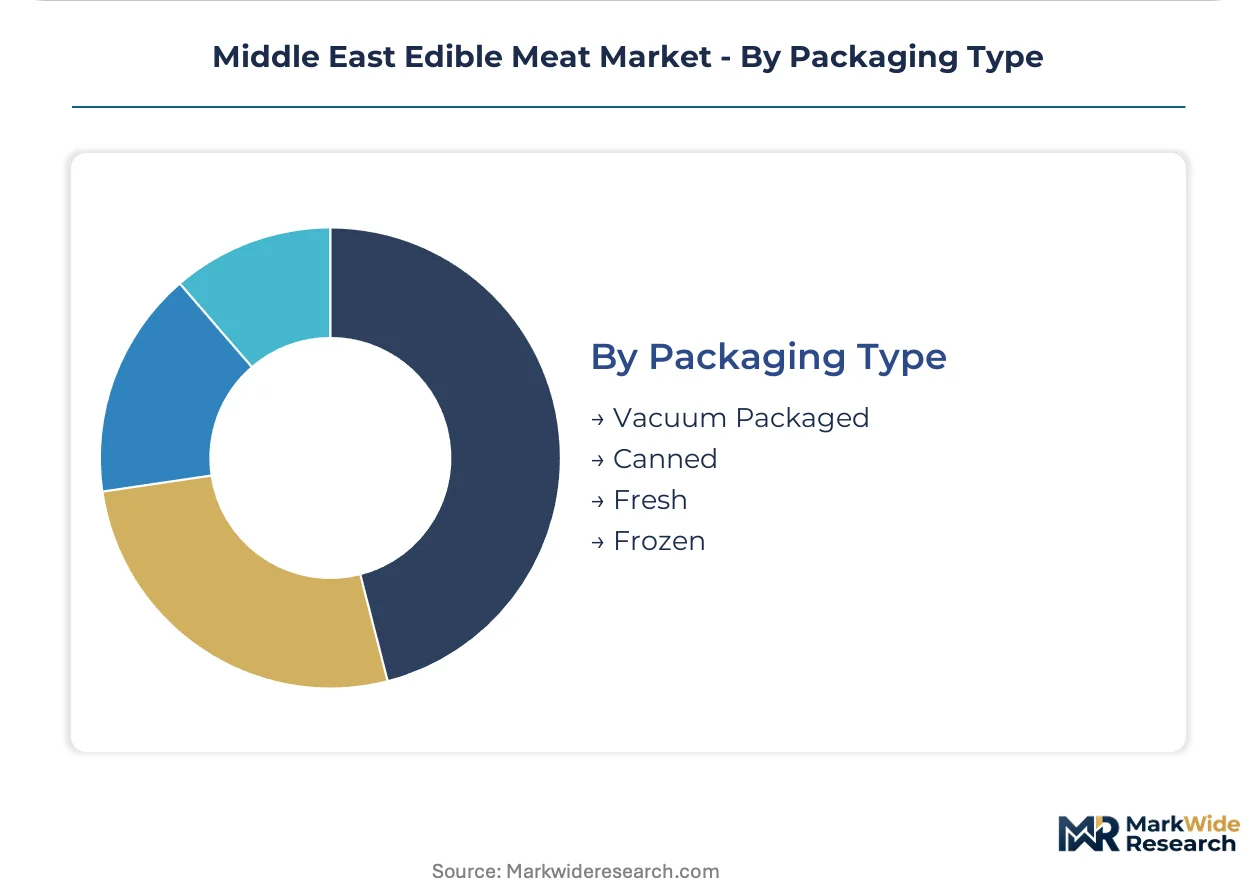
Packaging Type:
Packaging technology selection determines shelf-life extension capabilities and export eligibility, with gas-flushed formats requiring substantial capex that favors incumbent players.
- Frozen:Blast freezing infrastructure dominates wholesale trade volumes through Brazilian and Australian export corridors. Port detention risks from temperature excursions force IoT-enabled container monitoring investments that raise effective entry barriers.
- Vacuum Packaged:Vacuum-skin formats capture premium supermarket margins through extended color stability and reduced drip loss. Jeddah-based retailers prioritize these formats for upscale household channels serving health-conscious consumers.
- Fresh:Chilled distribution above freezing point compresses logistics windows to 72 hours for microbiological safety.
- Canned:Thermal processing extends shelf life for emergency stockpiling and remote distribution.
Frozen absorbs the bulk of installed capacity; vacuum packaged is expanding most quickly as retailers compete for premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement volumes concentrate in Saudi Arabia, where government food security initiatives and large-scale poultry integration projects reshape import dependency patterns across the Gulf. National regulators in Riyadh and Abu Dhabi enforce diverging halal certification standards that fragment supplier compliance costs.
Saudi Arabia
Domestic breeding-to-processing facilities absorb the bulk of government food security funding, compressing feed-to-retail timelines for integrated operators. SFDA halal slaughter standards and blockchain-enabled traceability mandates force cold-chain infrastructure upgrades at Jeddah and Riyadh processing plants. The Riyadh-Jeddah corridor anchors national distribution, with integrated producers capturing economies of scale that commodity importers cannot replicate.
United Arab Emirates
Dubai and Abu Dhabi hospitality chains consolidate procurement around audited national distributors, mandating quarterly microbiological audits and fixed-price annual contracts. MOCCAE residue testing blocks entry for South American suppliers with tetracycline violations, tightening eligible supply pools for hotel buyers. Dubai's central kitchen consolidation compresses supplier rosters from fragmented local butchers to single-source national distributors serving four-star and five-star segments.
Kuwait
Underdeveloped chilled meat distribution networks create first-mover advantages for vacuum-sealed fresh poultry specialists entering the market. The country's national food safety authority enforces import residue limits that shape product eligibility for domestic sale. Port-side trading concentrates Brazilian frozen poultry volumes, exposing buyers to currency fluctuation and shipping disruption risks.
Qatar
Digital tendering systems bypass traditional importer-wholesaler layers, connecting hospitality groups directly to Saudi processing plants with real-time temperature monitoring. National halal certification requirements enforced by the food safety regulator tighten traceability standards across the supply chain. Doha-based hotel chains prioritize liability reduction over unit cost minimization in procurement decisions.
Bahrain
Neighborhood butcher networks remain fragmented, creating consolidation opportunities for vacuum-sealed specialists with shorter shelf-life guarantees. The national food safety authority implements Gulf Standardization Organization harmonization protocols to reduce cross-border compliance costs. Manama retail channels absorb limited chilled poultry volumes, with expansion contingent on cold-chain capex deployment.
Middle East Edible Meat Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue antibiotic-free certification and direct-to-hotel digital procurement platforms. The vendor base clusters around three archetypes: integrated domestic breeders with captive feed-to-retail infrastructure, Brazilian frozen poultry exporters anchoring port-side wholesale trade, and fresh chilled specialists differentiating through vacuum-sealed shelf-life guarantees. Competitive positioning hardens through M&A consolidation among Gulf-based food service buyers and capacity expansion in controlled-atmosphere stunning systems.
Among Saudi-based integrated operators, Almarai Company and Tanmiah Food Company exemplify the vertically structured archetype controlling cold-chain distribution across the Kingdom. BRF S.A. anchors the export-driven tier, representing Brazilian frozen poultry supply into UAE and Kuwait port volumes. These three entities occupy positions that map directly to the tripartite competitive structure: domestic integration, import anchoring, and fresh-format specialization.
| Leading Market Players |
|---|
| Al Ain Farms |
| BRF S.A. |
| Siniora Food Industries Company |
| Tanmiah Food Company |
| The Savola Group |
| Almarai Company |
| Al Islami Foods |
| Americana Group |
| Al-Watania Poultry |
| Others |
Supply & Pricing Matrix
Halal certification grade divergence separates antibiotic-free vacuum-sealed poultry from commodity frozen imports, with premium tiers capturing supermarket shelf space through shorter logistics windows while economy segments endure port detention risks from temperature excursions. This bifurcation manifests in pricing power concentration among integrated Saudi breeders versus margin compression for Brazilian re-exporters facing SFDA blockchain traceability mandates.
Pricing Analysis
Volume-vs-margin split favors frozen wholesale trade through Santos-originated benchmarks, while vacuum-skin formats command premium positioning in Jeddah and Dubai hypermarkets. Three-tier pricing structure across premium antibiotic-free, standard chilled, and economy frozen levels tracks certification investment and cold-chain documentation depth. Pricing pressure stems from feed input volatility transmitting directly into broiler production economics. Quick-service restaurant chains exhibit lowest price sensitivity through multi-year offtake agreements, whereas neighborhood butcher counters in Bahrain and Kuwait face acute spot-market vulnerability.
Supply Chain Analysis
SFDA and MOCCAE halal auditor qualification requirements gate entry for new processing facilities, constraining slaughter supervisor availability and inflating compliance wages. Geographic supply concentration centers on Saudi integrated breeding-to-processing corridors, Brazilian Santos-Paranaguá export terminals, and Australian chilled beef corridors. Raw material dependencies rest on corn and soybean meal feed inputs, gas-stunning tunnel equipment, and IoT-enabled container monitoring systems. Single-source vulnerability runs through Brazilian frozen poultry dominance at UAE and Kuwait ports. Distribution runs through central kitchen consolidation among Dubai hospitality groups bypassing traditional importer-wholesaler layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA blockchain-enabled traceability mandates erect a cost-of-compliance moat that rewards incumbent integrated operators while screening out undercapitalized re-exporters. This regulatory barrier-to-entry structure concentrates procurement power among cold-chain-ready domestic producers.
For Market Incumbents: Deploy controlled-atmosphere stunning capacity additions in Jeddah and Riyadh to maintain simultaneous EU export eligibility and domestic halal compliance. Consolidate supplier rosters around audited national distributors before digital tendering platforms fragment procurement relationships. Channel control through captive cold-chain distribution defends margin position against Brazilian frozen poultry price volatility.
For New Entrants and Emerging Players: Boutique hotel procurement directors in Doha and Manama represent an underserved buyer archetype seeking liability reduction through direct-source relationships with Saudi processing plants. Vacuum-sealed fresh poultry distribution networks in Kuwait and Bahrain offer the most penetrable geography given fragmented neighborhood butcher infrastructure. Antibiotic-free certification investment unlocks premium supermarket placement in Abu Dhabi and Jeddah.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated mid-cap specialists possessing captive feed-to-retail infrastructure and SFDA pre-certified traceability systems given accelerating central kitchen consolidation. Long-term viability over a multi-year window favors operators with backward integration into breeding facilities rather than import-dependent trading positions. The signal to watch is MOCCAE residue limit tightening that would further restrict eligible South American supply pools.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Breeding Facilities | Captive feed-to-retail timelines compress production economics and reduce import dependency exposure. |
| Blockchain-Enabled Traceability Deployment | SFDA mandates require IoT container monitoring to avoid port detention and unlock supermarket channels. |
| Controlled-Atmosphere Stunning Retrofit | Gas-stunning tunnels enable EU export eligibility while maintaining religious compliance for domestic sales. |
| Direct-to-Hotel Digital Procurement Platform | Bypassing importer-wholesaler layers captures Qatari hospitality procurement volumes with real-time temperature data. |
| Antibiotic-Free Certification Investment | EU Green Deal alignment opens premium supermarket positioning in health-conscious Jeddah and Abu Dhabi households. |
Research Methodology
Document review covered customs and trade databases, SFDA regulatory filings, and Gulf Standardization Organization harmonization protocols, complemented by interviews with Saudi processing plant operations directors, UAE hospitality procurement managers, Brazilian export corridor logistics coordinators, and Kuwaiti retail channel partners. Secondary validation drew from port authority throughput statistics, feed commodity price benchmarks, and cold-chain equipment supplier disclosures. Bottom-up facility capacity assessments and top-down consumption estimates were triangulated to anchor volume projections.
Segment-level outputs across product type, distribution channel, end user, and packaging format dimensions were modeled using poultry integration project timelines, quick-service restaurant expansion pipelines, and halal auditor workforce growth assumptions. CAGRs were derived from trajectory fitting against government food security funding allocations and hospitality sector procurement consolidation patterns. Feed input cost volatility and currency fluctuation at Brazilian export terminals served as scenario sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SFDA residue limit enforcement intensity and Gulf Standardization Organization certification harmonization pace. Forecasts reflect assumptions regarding Saudi poultry integration project completion rates and central kitchen consolidation velocity among UAE hospitality groups. A model refresh is warranted upon material change in Brazilian real exchange rate trajectories or MOCCAE antibiotic testing protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Pork Belly Meat Market
Meat Products
Asia-Pacific Low Fat Sausage Market
Meat Products
Canned Chicken Market
Meat Products
Low-Fat Ham Market
Meat Products
India Edible Meat Market
Meat Products
Dehydrated Meat Products Market
Meat Products
Global Edible Meat Market
Meat Products
Europe Meat Products Market
Meat Products
Bacon Market
Meat Products
Mexico Meat Products Market
Meat Products
Germany Meat Products Market
Meat Products
Animal Protein Market
Meat Products
Germany Poultry Meat Market
Meat Products
Meat, Poultry and Seafood Market
Meat Products
Low Fat Sausage Market
Meat Products
3D Printed Meat Market