
 Meat Packaging Market | 2026-2036
Meat Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Packaging Market Outlook
The gap between premium case-ready formats and commodity overwrap is broadening as retailers demand longer shelf life and cleaner label presentation. Amcor plc leverages its global film manufacturing footprint to supply high-barrier laminates for modified atmosphere applications. Sealed Air Corporation sustains technology leadership through vacuum and skin packaging systems that reduce purge and extend color stability. Mondi Group anchors European supply with kraft-paper-based alternatives that target plastic-reduction mandates in retail channels.
Meat packaging encompasses barrier structures, trays, films, and closures engineered to control oxygen transmission, moisture loss, and microbial ingress in fresh and processed protein distribution. Multilayer coextruded films typically achieve oxygen transmission rates below 1 cc/m²/day to preserve myoglobin color and delay lipid oxidation in refrigerated beef and pork. Modified atmosphere packaging and vacuum formats now lead volume as retailers convert from store-wrapped counter service to prepacked case-ready displays. Plastic remains the dominant material substrate, though paper-based and fiber-tray segments are gaining fastest where single-use plastic restrictions tighten. Thermoforming technology dominates tray production for its cost efficiency at scale across beef, poultry, and pork applications.
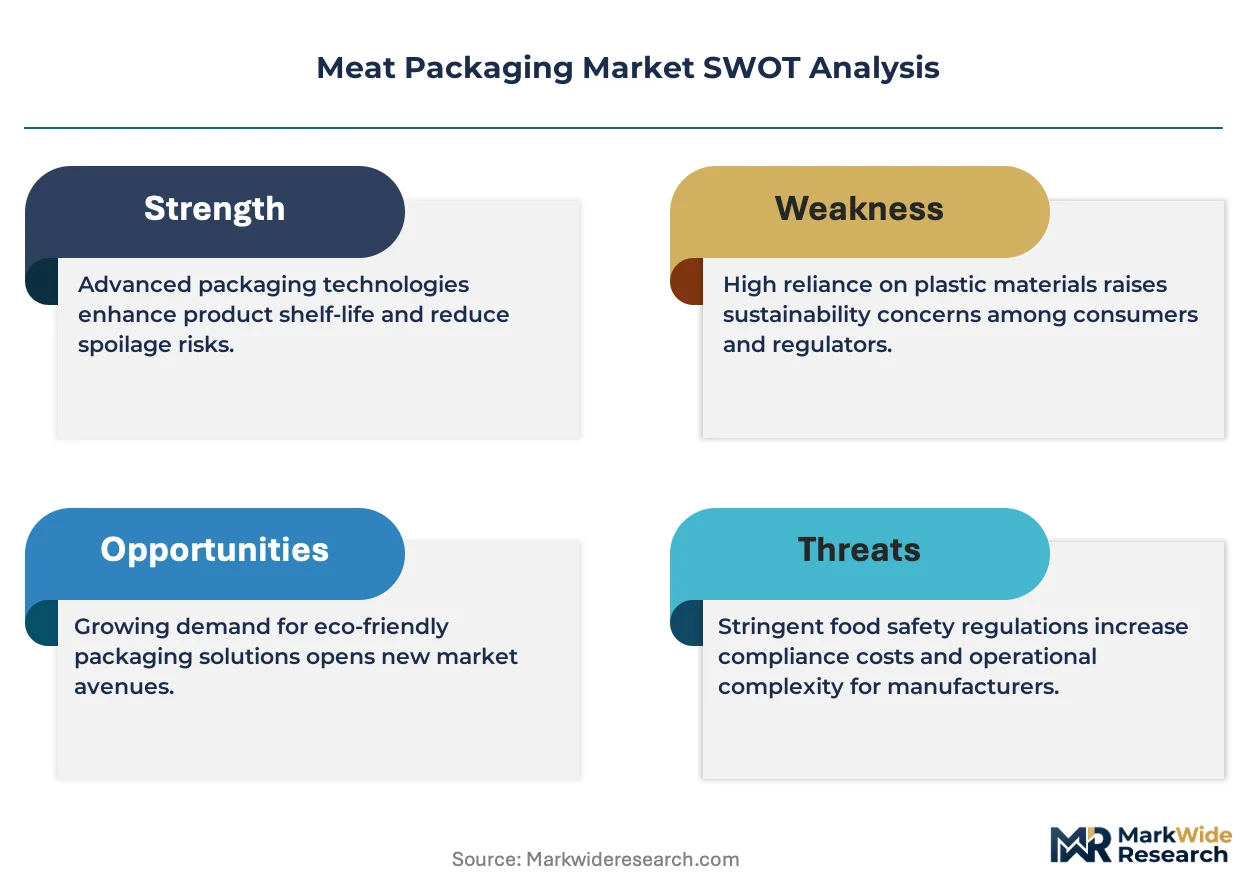
The FDA governs food-contact substance compliance through 21 CFR regulations that dictate migration limits and additive safety for plastic meat packaging in the United States. The EPA oversees per- and polyfluoroalkyl substance (PFAS) phaseouts that are forcing film suppliers to reformulate grease-resistant barriers in paper-based meat wraps. The EU's REACH regulation and PPWR framework collectively restrict certain phthalate plasticizers and mandate minimum recycled content thresholds, reshaping material procurement for exporters serving European retail chains. Stakeholders must monitor evolving state-level extended producer responsibility laws in the United States and incoming EU harmonized labeling requirements that will determine which packaging formats retain market access across major protein export corridors.
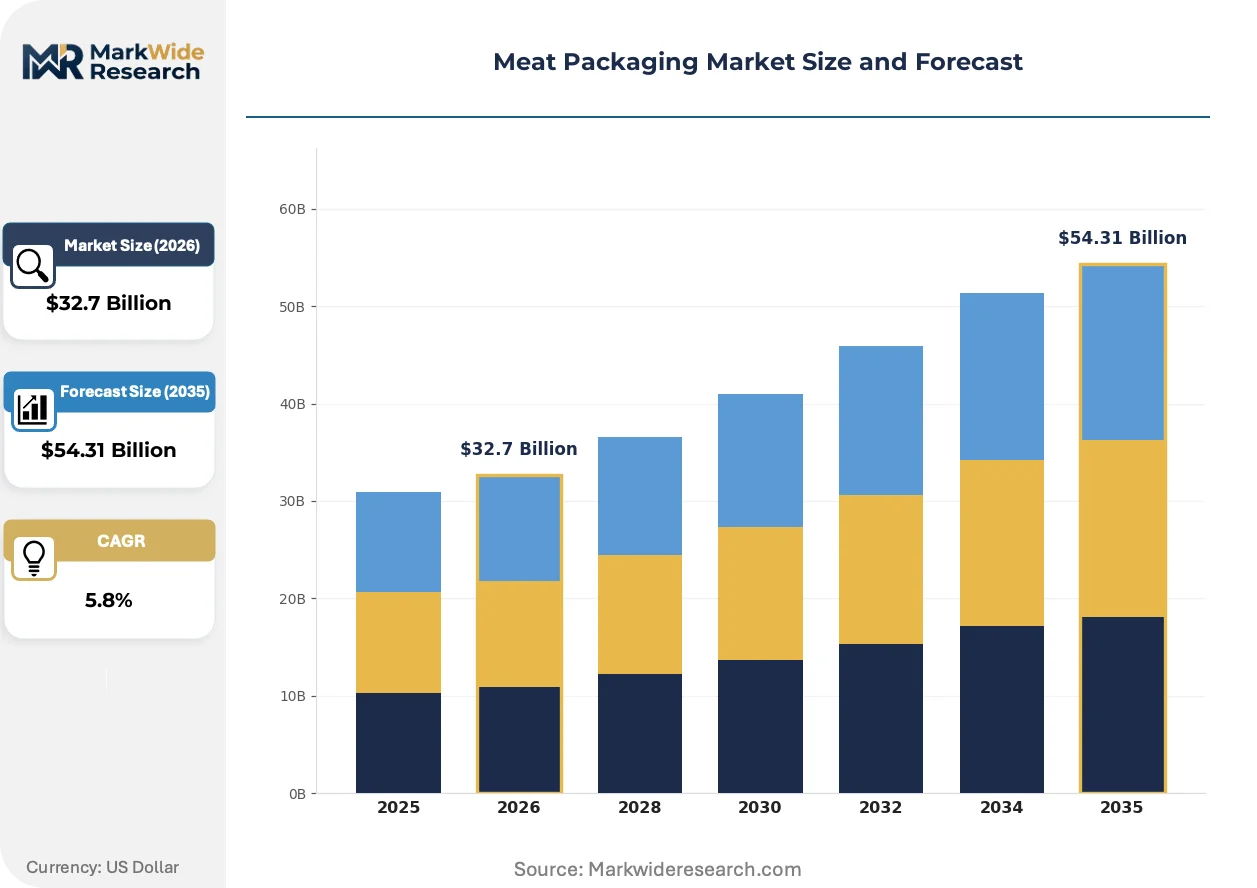
Market Dynamics
Retail conversion from service counters to case-ready displays is compressing the supply base toward high-barrier film specialists capable of delivering sub-1 cc/m²/day oxygen transmission rates at industrial scale.
Growth Catalysts
- EU PPWR recycled-content mandates:Germany's centralized processing infrastructure positions it as the primary adoption corridor for post-consumer recycled tray formats serving export-certified protein channels.
- Modified atmosphere packaging technology:Vacuum and skin formats now dominate fresh beef and pork distribution as retailers eliminate in-store wrapping labor and reduce shrink.
- Food service operator demand:North American restaurant chains are scaling fresh-portion and ready-to-cook formats that require extended color stability and purge reduction.
Market Restraints
- Ethylene and propylene feedstock volatility:Multilayer coextruded film margins compress when olefin input costs spike, forcing reformulation toward thinner gauge structures.
- PFAS barrier phaseout timelines:EPA restrictions on per- and polyfluoroalkyl substances are forcing paper-based wrap suppliers to rebuild grease resistance without proven drop-in alternatives.
- Thermoforming equipment concentration:Tray production capability clusters among a limited set of European and East Asian machinery suppliers, creating capacity bottlenecks during demand surges.
Strategic Opportunities
- Kraft-paper tray segments:Mondi Group's fiber-based alternatives are capturing shelf space in retail channels where single-use plastic restrictions are tightening fastest.
- High-barrier laminate convergence:Combining ethylene vinyl alcohol with bio-based sealants enables compliance with both FDA migration limits and EU plastic-reduction targets.
- Direct-store-delivery channel expansion:Regional protein processors are bypassing centralized distribution to capture margin through temperature-controlled last-mile formats.
Industry Challenges
- Multilayer film recycling infrastructure:Current mechanical separation systems cannot process coextruded meat packaging at commercial scale, complicating extended producer responsibility compliance.
- Migration testing backlog:FDA 21 CFR food-contact substance notifications face 18-24 month review timelines, delaying new barrier additive commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat Packaging Market |
| Market Size in 2026 | $32.7 Billion |
| Market Size in 2035 | $54.31 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: MAP, Vacuum Packaging, Modified Atmosphere Packaging, Skin Packaging Material: Plastic, Foam, Paper, Metal End User: Retail, Food Service, Processing Plants, Exporters Technology: Thermoforming, Injection Molding, Die-Cutting, Printing |
| Companies Covered | Amcor plc, Berry Global Group Inc., Sealed Air Corporation, Mondi Group, Winpak Ltd., Sonoco Products Company, Crown Holdings Inc., Amerplast Ltd., Cascades Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Packaging Market Strategic Shifts
Active and intelligent packaging systems are migrating from premium protein segments toward mainstream retail applications as sensor costs decline and traceability requirements harden across cold chains.
High-barrier ethylene vinyl alcohol laminates are absorbing volume from conventional nylon-based structures in modified atmosphere beef packaging. North American retailers are adopting these films at accelerated pace to extend case-ready shelf life from 21 to 28 days. The technology is absorbing margin from commodity overwrap suppliers unable to meet sub-1 cc/m²/day oxygen transmission specifications.
REACH restrictions on phthalate plasticizers are forcing European film compounders to reformulate flexible meat wraps around bio-based citrate and adipate alternatives. Industrial consequence includes 15-20% raw material cost premiums that processors are passing to retail buyers. German export certification infrastructure is most affected, with suppliers accelerating compliance documentation to maintain supermarket chain access.
Buyer consolidation among protein retail banners is compressing supplier negotiation cycles and unbundling technical service from material supply contracts. Food service distributors are displacing traditional broker networks with direct mill relationships that specify barrier performance rather than brand. This pattern is most visible in the United States, where top-five retail meat buyers now control over half of case-ready packaging specification authority.
Meat Packaging Market Segmentation
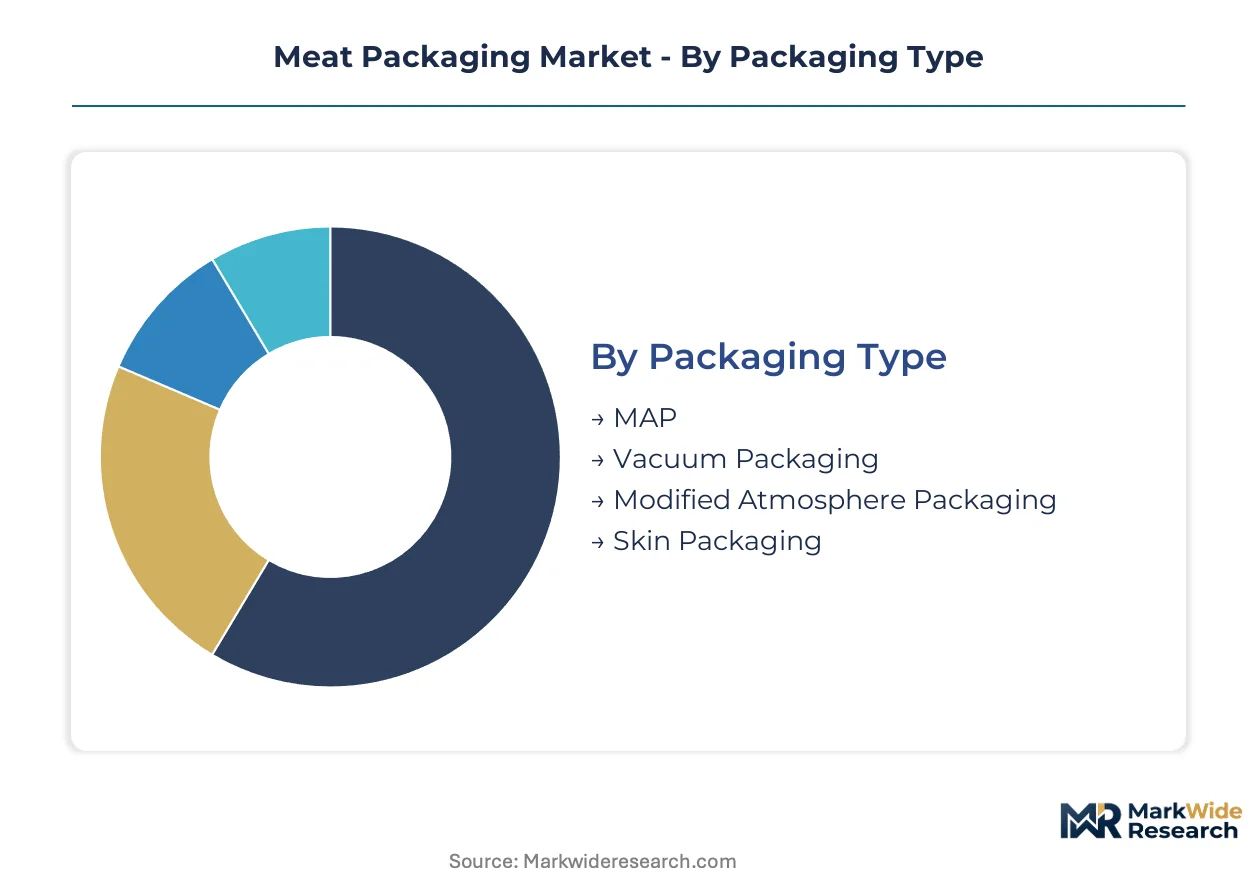
Meat packaging segmentation reveals how oxygen transmission specifications and regulatory compliance requirements fragment procurement across protein supply chains. Each dimension carries distinct margin profiles and technical barriers that reshape supplier relationships.
Packaging Type:
Standalone formats operate independently of retail equipment, while embedded systems require synchronized gas-flushing infrastructure.
- Modified Atmosphere Packaging:Multilayer coextruded films achieve sub-1 cc/m²/day oxygen transmission rates through ethylene vinyl alcohol barriers. German retail chains specify MAP for case-ready beef displays to satisfy export certification requirements.
- Vacuum Packaging:Thermoformed barrier films eliminate headspace oxygen to extend refrigerated shelf life. North American food service distributors specify vacuum formats for fresh-portion programs targeting restaurant chain color stability demands.
- Skin Packaging:Tight-film adherence reduces purge loss in premium protein segments.
Volume placements concentrate in Modified Atmosphere Packaging; the faster expansion belongs to Skin Packaging.
Material:
Cost tiers separate commodity substrates from compliance-grade alternatives facing REACH and PPWR mandates.
- Plastic:Nylon-EVOH-polyethylene laminates dominate fresh protein distribution through industrial thermoforming scale. EU recycled-content thresholds are forcing German processors to source post-consumer feedstocks for tray production.
- Paper:Kraft-paper trays with bio-based sealants absorb shelf space where single-use plastic restrictions tighten fastest in European retail.
- Foam:Expanded polystyrene remains entrenched in commodity poultry shipping.
- Metal:Aluminum barrier layers serve processed meat canning and retort applications.
Plastic retains the dominant placement position; paper formats are climbing the fastest on regulatory tailwinds.
End User:
Customer type determines whether packaging specification authority sits with procurement teams or operations departments.
- Retail:Supermarket banners dictate oxygen transmission specifications and recycled-content thresholds through consolidated buying power. US top-five retail meat buyers now control over half of case-ready packaging decisions.
- Food Service:Restaurant chains and distributors prioritize purge reduction and extended color stability for fresh-portion programs.
- Processing Plants:Centralized meatpacking facilities specify barrier performance for export-certified protein channels.
- Exporters:Cross-border protein shippers face dual compliance burdens from FDA migration limits and EU plastic-reduction targets.
Retail commands the largest placement volume; food service is gaining share fastest as chains scale ready-to-cook formats.
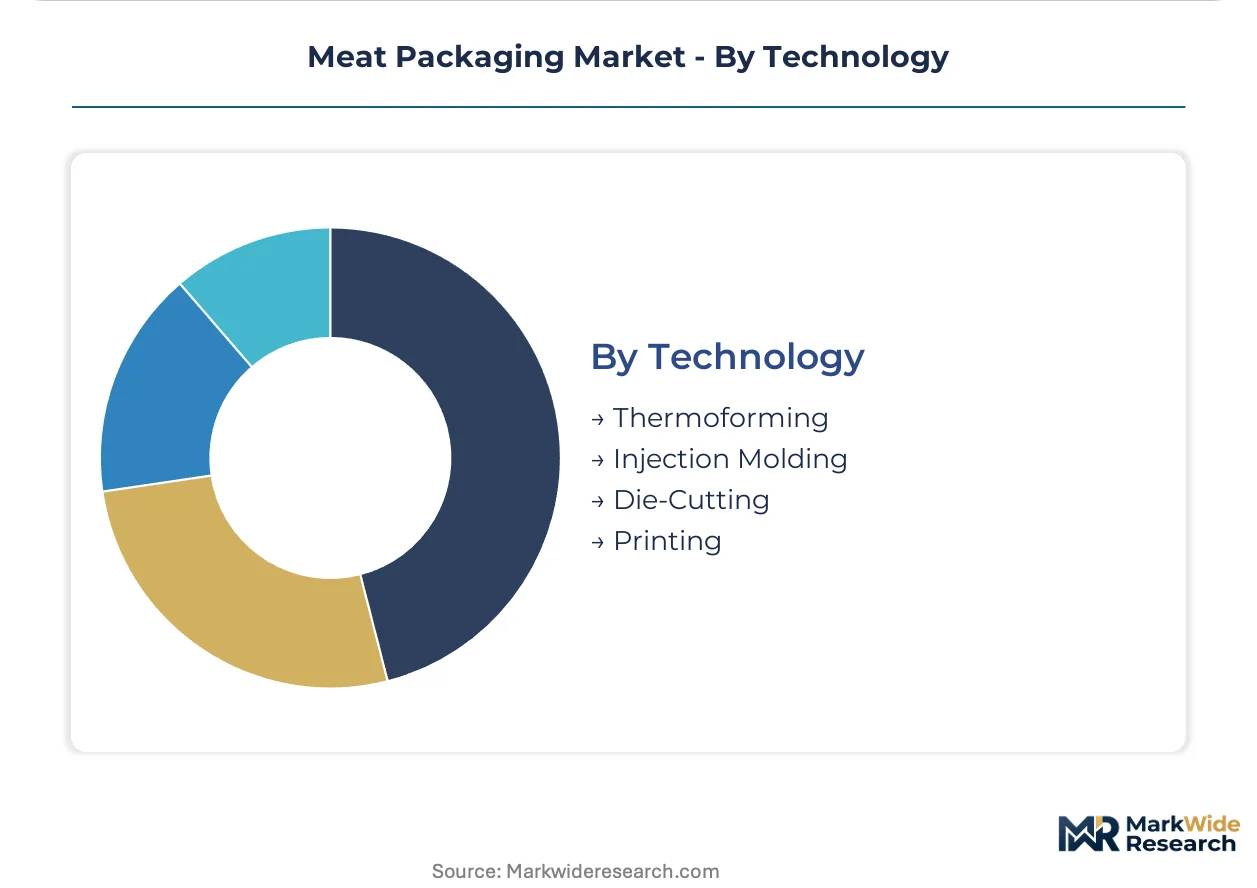
Technology:
Maturity curves separate established thermoforming scale from emerging precision methods.
- Thermoforming:Roll-fed vacuum and pressure forming dominates tray production for beef, pork, and poultry at industrial scale. Equipment concentration among limited European and East Asian machinery suppliers creates capacity constraints during demand surges.
- Injection Molding:Rigid barrier containers serve processed meat segments requiring dimensional precision.
- Die-Cutting:Flat-sheet conversion produces lidding films and flexible wraps.
- Printing:Flexographic and digital systems apply traceability codes and regulatory labels.
Thermoforming holds the volume concentration; injection molding carries the steepest expansion trajectory in premium processed segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rüsselsheim's centralized meat processing corridor drives German demand for case-ready packaging formats that satisfy export certification requirements.
United States
Food service operators in Chicago and Omaha scale fresh-portion programs requiring extended color stability. The EPA's PFAS phaseout forces paper-based wrap suppliers to reformulate grease-resistant barriers. Dallas-Fort Worth distribution hubs concentrate vacuum packaging adoption for regional protein processors.
Germany
Retail chains in Munich and Hamburg specify modified atmosphere packaging for beef displays serving export channels. The EU's PPWR mandates minimum recycled content thresholds for plastic trays. Rüsselsheim's processing infrastructure anchors premium case-ready format adoption across European retail networks.
China
Urban consumers in Shanghai and Beijing drive demand for prepacked fresh protein with visible quality indicators. SAMR enforces GB standards for food-contact materials in plastic packaging. Yangtze River Delta cold chain expansion supports modified atmosphere distribution for imported beef and pork.
Brazil
Beef exporters in São Paulo state adopt high-barrier laminates to meet EU supermarket chain specifications. ANVISA regulates migration limits for plastic food-contact substances in processed meat applications. Campinas industrial corridor concentrates thermoforming capacity for poultry export packaging.
Japan
Convenience retail in Tokyo and Osaka prioritizes skin packaging for premium Wagyu presentation. METI promotes plastic reduction targets that accelerate paper tray trials. Nagoya's machinery suppliers dominate thermoforming equipment exports to Southeast Asian protein processors.
Meat Packaging Market Competitive Environment
Premium-margin players sit above commodity-margin players across barrier performance and regulatory compliance capabilities. The market structure concentrates among film specialists with industrial-scale coextrusion capacity and thermoforming equipment integration. Three archetypes dominate: multinational material science conglomerates with global film manufacturing footprints, European paper-based packaging specialists targeting plastic-reduction mandates, and regional equipment-integrated converters serving food service channels. Competitive moves center on high-barrier laminate portfolio expansion and post-consumer recycled content certification for EU market access.
Within the multinational tier, Amcor plc and Sealed Air Corporation exemplify scale-driven barrier technology leadership. Mondi Group occupies a position representing fiber-based alternative development. These three entities anchor the competitive map across plastic reduction compliance and modified atmosphere performance specifications.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Group Inc. |
| Sealed Air Corporation |
| Mondi Group |
| Winpak Ltd. |
| Sonoco Products Company |
| Crown Holdings Inc. |
| Amerplast Ltd. |
| Cascades Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive film coextrusion capacity anchors both supply security and pricing power for meat packaging specialists serving EU export corridors. German processors with in-house barrier film lines command premium positioning against commodity converters forced into spot resin markets.
Pricing Analysis
Oxygen transmission rate guarantees anchor value-based pricing tiers across modified atmosphere formats. Pricing stratifies across premium sub-1 cc/m²/day barrier laminates, standard nylon-polyethylene structures, and economy-grade commodity overwrap. Cost compression in standard tiers intensifies because ethylene and propylene feedstock volatility squeezes multilayer film margins. Food service distributors exhibit highest price sensitivity; export-certified retail chains accept premiums for compliance documentation.
Supply Chain Analysis
Ethylene vinyl alcohol resin supply rests on Japanese and European specialty chemical producers with limited qualified alternatives. Barrier film production draws from olefin feedstocks, ethylene vinyl alcohol copolymers, and bio-based sealant additives. Single-source vulnerability concentrates in thermoforming equipment where Nagoya and Milan machinery suppliers control global capacity. Distribution runs through centralized meat processing corridors in Germany and regional protein hubs in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU PPWR recycled-content mandates are compressing supplier margins and forcing sub-scale compounders toward exit. Consolidation favors film specialists with certified post-consumer feedstock access and thermoforming equipment integration.
For Market Incumbents: Deepen backward integration into ethylene vinyl alcohol resin compounding to secure barrier performance consistency against feedstock volatility. Expand thermoforming capacity in Rüsselsheim's processing corridor to capture German retail chain consolidation. Prioritize FDA 21 CFR notification pipelines to accelerate new sealant commercialization ahead of migration testing backlogs. For New Entrants and Emerging Players: Launch via direct-store-delivery channel partnerships with regional protein processors bypassing centralized distribution. Target North American food service fresh-portion programs where color stability specifications remain underpenetrated by European incumbents. Lead with bio-based sealant formulations that satisfy both FDA migration limits and EU plastic-reduction targets. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by multinational material science conglomerates seeking barrier technology scale. Five-to-ten year viability favors converters with thermoforming equipment integration and EU PPWR certification infrastructure. Watch EPA PFAS phaseout timelines as inflection indicator for paper-based wrap supplier distress.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Consumer Recycled Content Certification | EU PPWR compliance secures access to German retail export channels. |
| High-Barrier Laminate Portfolio Expansion | Ethylene vinyl alcohol integration extends case-ready shelf life specifications. |
| Thermoforming Equipment Backward Integration | Captive tray production reduces capacity bottlenecks during demand surges. |
| Bio-Based Sealant Formulation Investment | REACH-compliant alternatives capture margin from phthalate-restricted wraps. |
| Direct-Store-Delivery Channel Development | Regional processor partnerships bypass centralized distribution margin capture. |
Study Parameters
Trade publications, customs filings, and regulatory notification databases formed the secondary backbone for this analysis. Primary interviews with meat packaging procurement managers, thermoforming equipment engineers, food service distribution executives, and EU regulatory compliance officers validated secondary findings. Bottom-up volume modeling across packaging type, material substrate, and end-user segments combined with top-down market sizing triangulation.
Historical trendline analysis of barrier film adoption patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include packaging format, material compliance tier, technology platform, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating feedstock cost trajectories, equipment capacity expansion schedules, and mandate implementation timelines.
Feedstock price spikes, EPA PFAS restriction acceleration, and EU harmonized labeling requirement delays are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about regulatory implementation pacing and equipment delivery schedules. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Global Canned Meat Market
Meat Products
United States Red Meat Market
Meat Products
Asia-Pacific Edible Meat Market
Meat Products
United States Animal Protein Market
Meat Products
North America Canned Meat Market
Meat Products
Beef Tallow Market
Meat Products
Saudi Arabia Goat Meat and Cheese Market
Meat Products
North America Processed Poultry Meat Market
Meat Products
India Edible Meat Market
Meat Products
GCC Edible Meat Market
Meat Products
Low-Fat Chorizo Market
Meat Products
Global Beef Market
Meat Products
Germany Meat Products Market
Meat Products
United States Frozen Meat Market
Meat Products
Shark Meat Market
Meat Products
Asia-Pacific Low Fat Sausage Market