
 Organic Meat Market | 2026-2036
Organic Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Meat Market Outlook
The widening price spread between premium pasture-raised organic cuts and commodity conventional meat is repositioning procurement strategies across retail and foodservice channels. Tyson Foods leverages its integrated supply network to secure certified organic feed volumes at scale. Perdue Farms anchors its competitive stance through dedicated organic processing facilities and farmer partnership programs. Applegate differentiates via strict no-antibiotic-ever protocols and transparent farm-level sourcing.
Organic meat denotes livestock raised on certified organic feed without synthetic hormones, antibiotics, or genetically modified organisms, with animals accessing outdoor pasture systems meeting minimum duration standards. The product serves health-conscious consumers and institutional buyers seeking residue-free protein with verifiable chain-of-custody documentation. Beef commands the largest revenue share among product types due to extended finishing cycles and premium positioning, while chicken represents the fastest-expanding category as lower price points attract mass-market trial. Supermarkets dominate distribution channel value, though online retail is capturing growth from subscription-based direct-to-consumer models.
USDA Organic standards, EU Organic Regulation 2018/848, and Codex Alimentarius guidelines collectively define feed composition, livestock living conditions, and labeling requirements that determine market access. These frameworks raise compliance costs for new entrants while rewarding established operators with certified infrastructure. Stakeholders must monitor evolving pasture-access mandates and antibiotic-trace testing protocols that will determine which suppliers retain certification status.
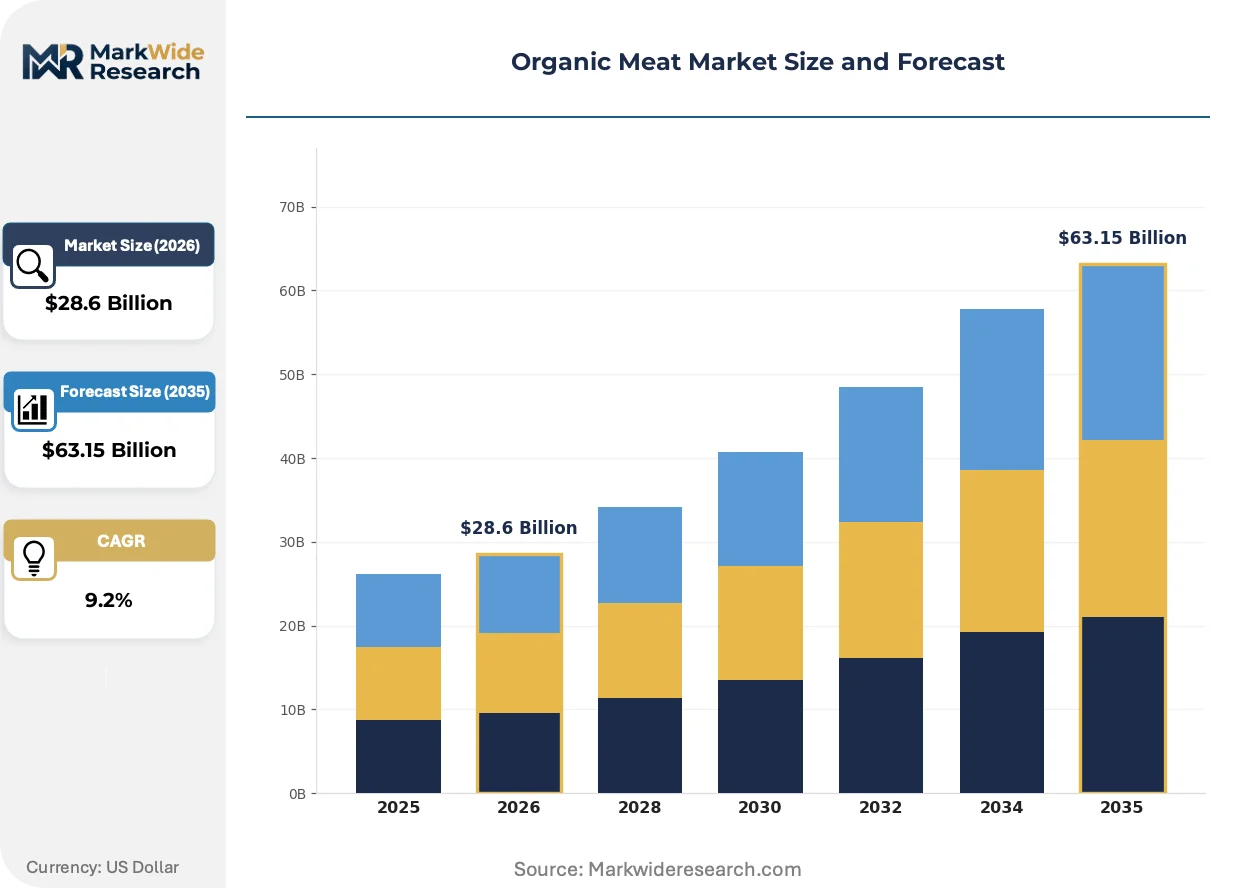
Market Dynamics
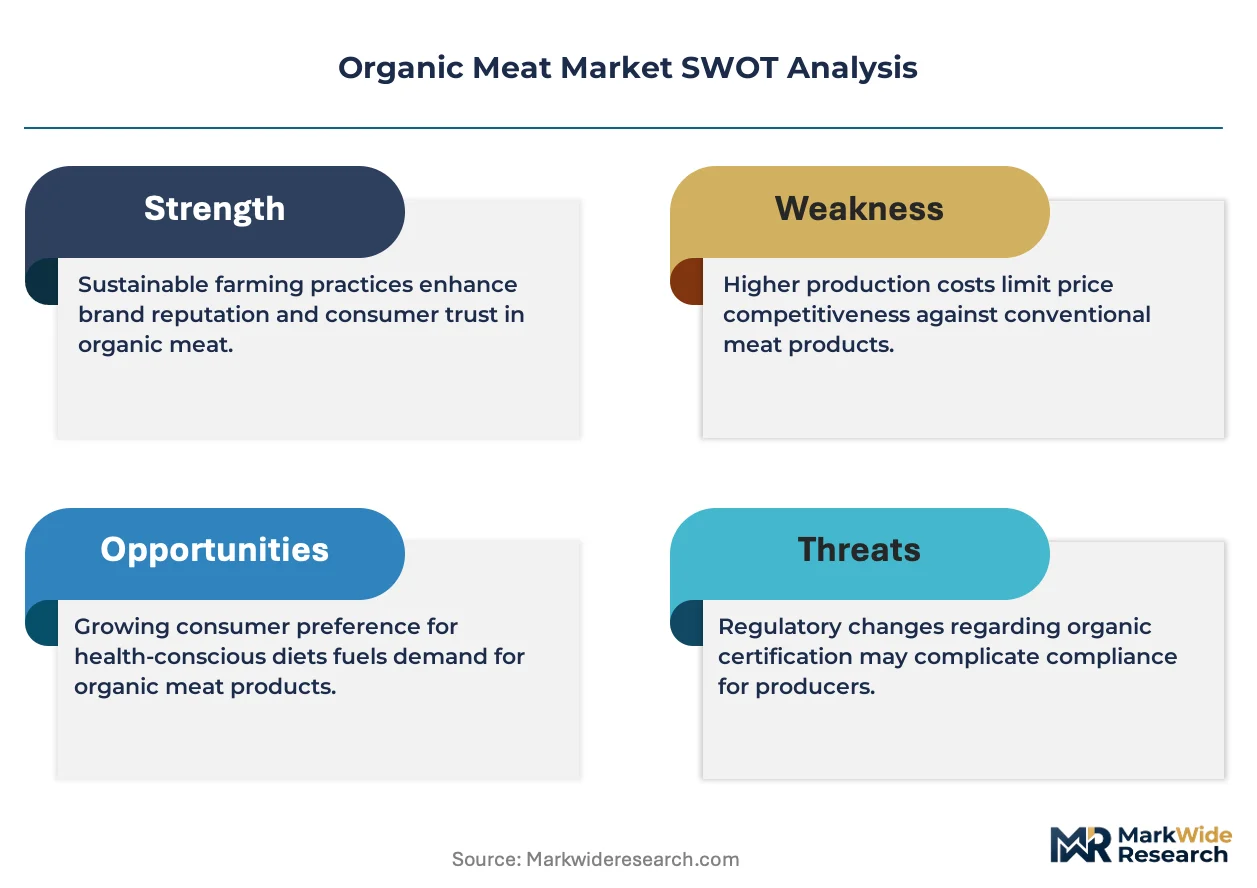
USDA Organic and EU Organic Regulation 2018/848 feed-traceability mandates are compressing supplier margins while rewarding integrated operators with certified infrastructure. This regulatory tightening is the dominant structural force reshaping competitive viability across production regions.
Growth Catalysts
- EU Organic Regulation 2018/848:Tighter feed-source documentation requirements are accelerating consolidation among certified suppliers in Germany and France.
- Pasture-access mandates:Minimum outdoor duration standards are differentiating pasture-raised operations from indoor confinement systems in premium retail channels.
- Foodservice procurement:North American restaurant chains are expanding certified organic cut volumes through direct farmer partnerships.
Market Restraints
- Certified feed cost volatility:Organic grain premiums of 40-60% above conventional inputs compress finishing margins for non-integrated producers.
- Processing concentration:Dedicated organic slaughter and fabrication capacity clusters in the Midwestern United States and Northern Germany, creating regional bottlenecks.
- Substitution pressure:Plant-based protein alternatives and cultivated meat R&D investments divert institutional R&D budgets from organic livestock expansion.
Strategic Opportunities
- Direct-to-consumer subscriptions:Online retail platforms are bypassing supermarket slotting fees through farm-branded monthly box models.
- Regenerative organic certification:USDA Organic plus soil health verification commands additional shelf-space allocation in premium California and Northeast retail.
- Blockchain traceability integration:Immutable feed-to-fork records reduce audit costs while satisfying EU and North American retailer documentation demands.
Industry Challenges
- Veterinary capacity constraints:Certified organic animal health practitioners remain scarce in secondary production regions, extending treatment timelines.
- Conversion period capital intensity:Three-year land and livestock transition to organic certification requires sustained financing without revenue offset.
- Antibiotic residue testing protocols:Enhanced laboratory detection thresholds are disqualifying borderline shipments at EU and US import checkpoints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Meat Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $63.15 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Chicken, Lamb Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Farmers' Markets End User: Households, Restaurants, Food Services, Catering Packaging Type: Vacuum-Sealed, Tray Packaged, Bulk, Canned |
| Companies Covered | Tyson Foods, Pilgrim's Pride Corporation, Applegate, Perdue Farms, JBS, Conagra Brands, Marfrig Global Foods, Cargill Meat Solutions, Primal Pastures, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Meat Market Strategic Shifts
Digital traceability infrastructure and regenerative verification standards are compressing the information gap between farm-level practices and consumer-facing claims. These innovations are redefining how trust is manufactured and priced in premium protein markets.
Blockchain-enabled supply chain documentation is consolidating audit and certification workflows into unified digital platforms. Major North American retailers are mandating participation for shelf-space access by 2026. This consolidation is reducing third-party verification costs while raising barriers for non-compliant suppliers.
EU Organic Regulation 2018/848's full enforcement is tightening cross-border equivalence agreements with third-country exporters. Brazilian and Argentinian suppliers face accelerated compliance timelines for pasture-documentation systems. Beef import flows into Germany and France are rerouting toward domestic EU sourcing as administrative friction mounts.
Subscription-based direct purchasing is displacing traditional supermarket dominance among high-income urban households. Farm cooperatives in Denmark and the Netherlands are launching proprietary digital storefronts to capture margin previously allocated to retail intermediaries. This channel shift is most pronounced in metropolitan France and the Pacific Northwest United States.
Organic Meat Market Segmentation
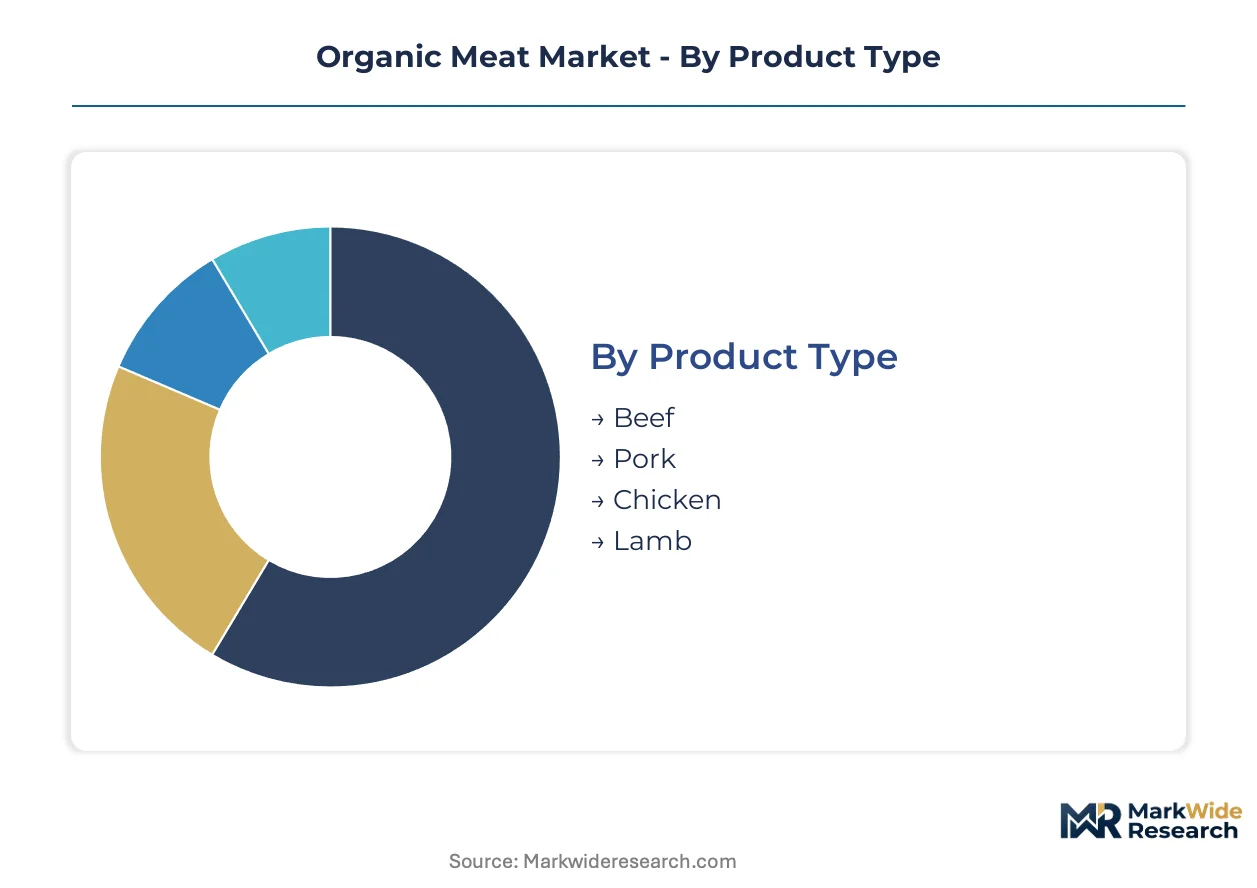
Organic meat segmentation reveals how certification burdens, processing infrastructure, and channel economics concentrate margin capture. Each dimension carries distinct compliance costs and pricing power that reshape supplier viability across production regions.
Product Type:
USDA Organic and EU Organic Regulation 2018/848 impose feed-traceability requirements that vary in stringency across livestock categories, with ruminant systems facing the most complex pasture-documentation mandates.
- Beef:Extended finishing cycles of 18-30 months demand sustained certified feed supply and outdoor pasture access documentation. German and French retail channels allocate premium shelf space to grass-finished organic beef, though feed cost volatility compresses non-integrated producer margins.
- Chicken:Shorter 8-12 week production cycles enable faster inventory turnover and lower trial price points for mass-market consumers. United States supermarket chains are expanding organic chicken SKUs fastest as processing capacity concentrates in the Midwest.
- Pork:Requires certified organic grain and protein meal sourcing with outdoor access mandates for breeding sows.
- Lamb:Seasonal pasture systems align naturally with organic certification but face limited dedicated processing infrastructure.
Beef sits at the top of the volume ranking, with chicken climbing the fastest.
Distribution Channel:
Channel selection determines margin retention and certification audit frequency, with direct routes bypassing retail slotting fees but demanding heavier digital infrastructure investment.
- Supermarkets:Dominant value capture through centralized procurement and private-label organic lines. German chains Edeka and Rewe, plus United States retailers Kroger and Whole Foods Market, are expanding certified organic meat shelf space through dedicated supplier qualification programs.
- Online Retail:Subscription-based direct-to-consumer models are displacing traditional retail among high-income urban households. Farm cooperatives in Denmark and the Netherlands are launching proprietary digital storefronts to capture margin previously allocated to intermediaries.
- Specialty Stores:Focus on butcher-counter traceability and regional sourcing narratives with premium price positioning.
- Farmers' Markets:Lowest barrier to entry for small producers but limited volume scale and seasonal demand concentration.
Supermarkets retain the largest revenue share, while online retail is gaining share fastest through subscription models.
End User:
End-user segmentation tracks procurement sophistication, with institutional buyers demanding batch-level traceability documentation that exceeds retail consumer requirements.
- Restaurants:North American farm-to-table chains and fast-casual concepts are expanding certified organic cut volumes through direct farmer partnerships. Chipotle Mexican Grill and Sweetgreen have established dedicated organic meat supply agreements with integrated processors.
- Households:Health-conscious consumers in metropolitan France and the Pacific Northwest United States are driving subscription adoption for residue-free protein with verifiable chain-of-custody documentation.
- Food Services:Institutional procurement from schools and hospitals requires USDA Organic or equivalent certification for contract eligibility.
- Catering:Event-based demand concentrates in premium urban markets with flexible sourcing timelines.
Households command the highest volume position, with restaurants expanding most quickly through direct supply relationships.
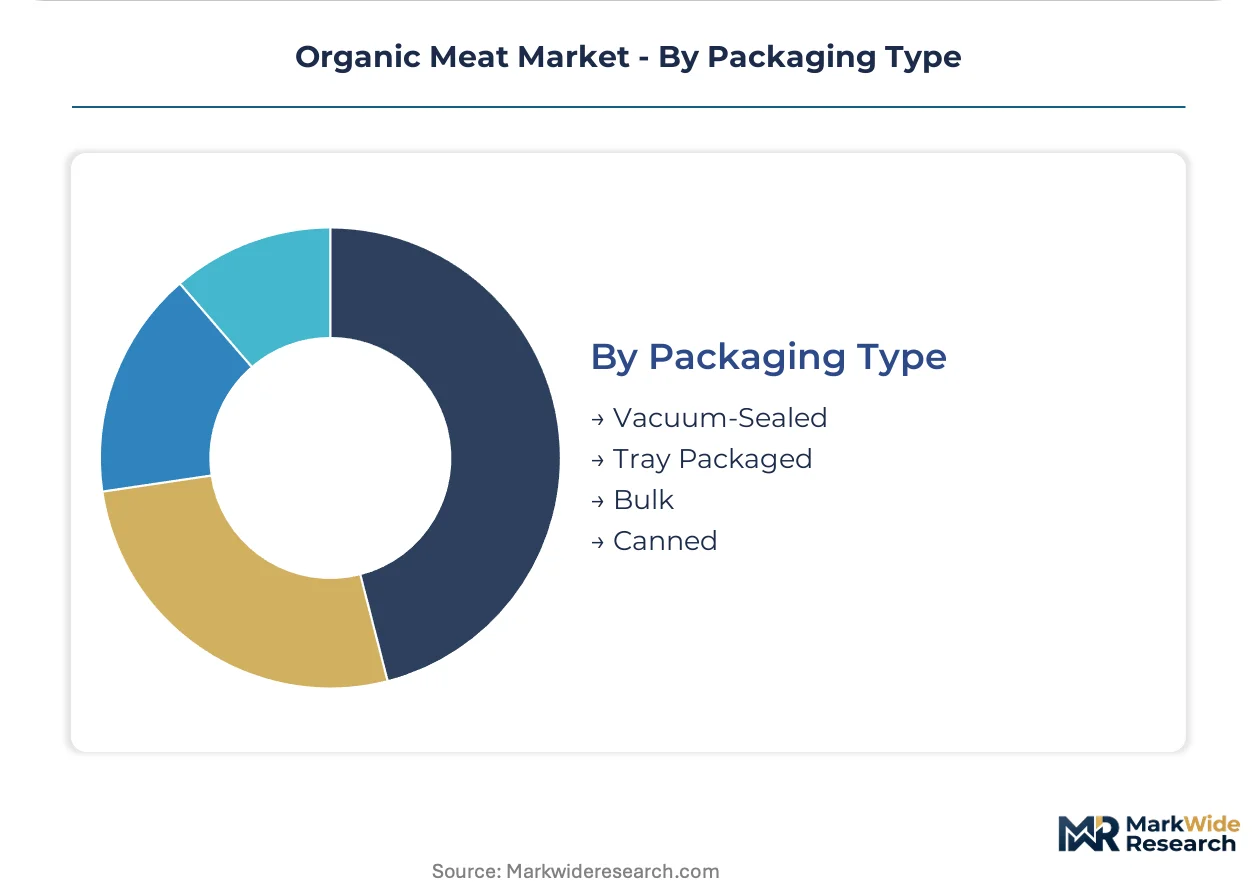
Packaging Type:
Packaging selection interacts with shelf-life requirements and retailer sustainability mandates, with vacuum-sealed formats dominating premium channels due to extended freshness windows.
- Vacuum-Sealed:Modified atmosphere packaging extends retail shelf life to 21-28 days, reducing spoilage rates for premium organic cuts. United States and German supermarkets are mandating vacuum-sealed formats for private-label organic lines to minimize waste.
- Tray Packaged:Standard foam or fiber trays with overwrap film serve price-sensitive retail segments with shorter 5-7 day freshness windows.
- Bulk:Foodservice and restaurant procurement favor primal cuts in master cases to minimize per-unit packaging cost.
- Canned:Niche shelf-stable applications for emergency preparedness and specialty ethnic markets with limited organic certification penetration.
Vacuum-sealed holds the top volume position, with tray packaged formats seeing steepest expansion trajectory in value-oriented retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified organic livestock specialists cluster in Germany, the United States, and France where processing infrastructure and retail distribution networks are most mature. Veterinary talent pools and feed certification expertise concentrate in these markets, anchoring regional competitive advantages.
United States
Midwestern processing hubs in Iowa and Nebraska host dedicated organic slaughter capacity serving national retail chains. USDA Organic standards mandate three-year land conversion and outdoor access documentation that Midwestern cooperatives have operationalized at scale. Tyson Foods and Perdue Farms anchor supply networks through integrated feed procurement and farmer partnership programs.
Germany
Discounter chains Aldi and Lidl drive volume through private-label organic meat lines priced for mass-market penetration. EU Organic Regulation 2018/848 enforcement tightens cross-border equivalence, favoring domestic Bavarian and Lower Saxony producers over third-country imports. Edeka and Rewe expand dedicated organic butcher counters in Berlin and Hamburg metropolitan stores.
France
Metropolitan households in Paris and Lyon sustain subscription-based direct purchasing from farm cooperatives. ANSM and DGCCRF coordinate residue testing protocols that exceed baseline EU requirements for antibiotic trace detection. Brittany and Normandy pasture systems supply grass-finished organic beef to premium Île-de-France retail channels.
Canada
Prairie provinces Alberta and Saskatchewan convert extensive grazing land to certified organic beef production for export and domestic foodservice. Health Canada and PMRA align veterinary biologic regulations with USDA Organic equivalence agreements. Vancouver and Toronto restaurant chains source prairie-raised organic cuts through direct processor partnerships.
Australia
New South Wales and Victoria sheep stations expand organic lamb certification for Middle Eastern and Asian export markets. TGA and DAWE administer parallel organic standards that recognize EU equivalence for beef and lamb shipments. Melbourne and Sydney specialty retailers allocate expanding shelf space to domestic organic red meat alongside conventional product lines.
Organic Meat Market Competitive Environment
Top-tier vendors anchor integrated supply networks, while mid-scale processors compete through certification specialization and regional sourcing narratives. The market structures around three concentration nodes: multinational protein conglomerates with captive organic feed operations, dedicated organic-only processors with farmer partnership programs, and direct-to-consumer farm cooperatives leveraging digital subscription platforms. Dominant competitive moves include backward integration into certified grain production and strategic alliances with retail chains for dedicated shelf-space allocation.
Among the integrated protein majors, Tyson Foods, Perdue Farms, and JBS occupy positions defined by scale advantages in feed procurement and processing capacity. Tyson Foods exemplifies the conglomerate archetype with distributed organic infrastructure across multiple livestock categories. Perdue Farms represents the dedicated-organic specialist model through vertically controlled hatchery-to-retail chicken systems. JBS anchors the multinational footprint with Brazilian-origin operations and North American organic beef fabrication capacity. These three entities collectively illustrate how certification compliance costs filter market structure toward players with capital depth for multi-year conversion timelines and audit infrastructure.
| Leading Market Players |
|---|
| Tyson Foods |
| Pilgrim's Pride Corporation |
| Applegate |
| Perdue Farms |
| JBS |
| Conagra Brands |
| Marfrig Global Foods |
| Cargill Meat Solutions |
| Primal Pastures |
| Others |
Value Chain & Pricing Dynamics
Backward integration into certified organic feed production anchors both supply security and margin defense for Tyson Foods and Perdue Farms. USDA Organic and EU Organic Regulation 2018/848 compliance costs filter market structure toward operators with captive grain sourcing and multi-year land conversion timelines.
Pricing Analysis
Certification-bundled pricing separates USDA Organic and EU Organic tiers from conventional commodity cuts, with pasture-access documentation commanding additional retail premium. Price differentiation rests on feed-traceability grade and brand-verified chain-of-custody, not volume scale alone. Cost compression in non-integrated producer tiers intensifies as organic grain premiums widen against conventional inputs. Mass-market supermarket buyers exhibit highest price sensitivity, while direct-to-consumer subscription households absorb premium positioning with lower elasticity.
Supply Chain Analysis
Veterinary talent scarcity in secondary production regions constrains expansion timelines for certified organic livestock operations across the United States and Germany. Geographic supply concentration clusters in Iowa, Nebraska, Bavaria, and Lower Saxony where dedicated organic slaughter capacity and feed certification expertise co-locate. Raw material dependencies center on certified organic corn, soy protein meal, and pasture acreage verification. Single-source vulnerability runs through Midwestern and Northern German processing hubs. Distribution runs through supermarket centralized procurement and farm-direct subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic meat has entered late-cycle quality competition where residue-free certification and regenerative verification command shelf-space allocation. Demand has shifted toward pasture-raised specifications with blockchain-anchored traceability documentation.
For Market Incumbents: Anticipate substitution pressure from plant-based alternatives and cultivated meat R&D by deepening captive feed production and regenerative organic certification investment. Defend margin position through farmer partnership program expansion in Iowa and Nebraska processing corridors. Blockchain traceability infrastructure serves as the priority lever for retailer qualification.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in beef finishing opens white-space for mid-tier pasture-raised positioning between commodity conventional and certified organic. Target direct-to-consumer subscription channels in metropolitan France and Pacific Northwest United States where traceability premiums absorb higher unit economics. Launch through farm cooperative digital storefronts to bypass supermarket slotting fee barriers.
For Investors and Strategic Acquirers: Roll-up economics work for regional organic processors with certified infrastructure because EU Organic Regulation 2018/848 compliance timelines extend competitive moats beyond five-to-ten year windows. Acquisition focus centers on Bavarian and Lower Saxony operators with established pasture-documentation systems and retailer shelf-space allocation. Watch EU cross-border equivalence enforcement as inflection indicator for import flow rerouting toward domestic EU sourcing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Feed | Tyson Foods secures organic grain volumes at scale through captive Iowa and Nebraska sourcing. |
| Blockchain Traceability Deployment | Immutable feed-to-fork records satisfy EU Organic Regulation 2018/848 documentation mandates for German retail. |
| Regenerative Organic Certification | Soil health verification commands additional shelf-space allocation in California and Northeast premium channels. |
| Direct-to-Consumer Subscription Launch | Farm cooperatives in Denmark and Netherlands capture margin previously allocated to retail intermediaries. |
| Farmer Partnership Program Expansion | Perdue Farms anchors supply security through vertically controlled hatchery-to-retail chicken systems. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with organic livestock producers, USDA-accredited certifiers, supermarket category buyers, restaurant procurement directors, and feed grain suppliers with secondary validation. Sources included USDA Organic certification databases, EU Organic Regulation 2018/848 implementation reports, customs and trade flow records, SEC 10-K filings from integrated protein majors, and Nielsen retail audit data. Bottom-up volume modeling and top-down market sizing triangulated across data streams.
Comparable historical periods anchored the projection framework across the analysis window, with segmentation modeled by livestock category, certification tier, distribution channel, and end-user procurement sophistication. CAGRs derived from trend extrapolation adjusted for regulatory enforcement timelines and processing capacity expansion patterns. Industry-specific inputs included organic grain price spreads, pasture-access mandate compliance rates, and subscription channel adoption curves.
Caveats apply where EU cross-border equivalence enforcement, antibiotic residue testing protocol revisions, or plant-based substitution acceleration could materially shift the outlook. Forecasts reflect assumptions about certification infrastructure retention and feed supply continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Canned Pork Market
Meat Products
Low-Fat Ham Market
Meat Products
Ham Slicers Market
Meat Products
Bacon Slicers Market
Meat Products
Brazil Meat Products Market
Meat Products
United Arab Emirates Edible Meat Market
Meat Products
India Edible Meat Market
Meat Products
North America Processed Poultry Meat Market
Meat Products
Meat Emulsions Market
Meat Products
Beef Fat Powder Market
Meat Products
United States Edible Meat Market
Meat Products
North America Processed Pork Meat Market
Meat Products
Fresh Organic Chicken Market
Meat Products
Canned Beef Market
Meat Products
Global Edible Meat Market
Meat Products
Organic Pork Market