
 Edible Offal Market | 2026-2036
Edible Offal Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Offal Market Analytics
Pet food processors is collapsing the traditional buyer hierarchy that once prioritized sausage manufacturers and household butchers. Tyson Foods leverages its vertically integrated poultry operations to secure consistent liver and heart volumes for premium pet nutrition lines. JBS S.A. anchors South American supply through its integrated beef processing network, while Danish Crown Group differentiates via specialized cold-chain logistics for tripe exports to Asian markets.
Edible offal comprises the internal organs and entrails of slaughtered animals rendered fit for human or animal consumption, with specifications governing microbial load, pH levels, and temperature controls from abattoir to point of sale. The primary commercial purpose spans direct culinary use, processed food manufacturing, and high-protein feed formulations. Liver dominates product type value pools due to its nutritional density and concentration of vitamin A, while pet food application segments outpace cooking and canning in margin expansion. Supermarkets and wholesale channels control volume flows, though online retail is capturing specialty and direct-to-consumer segments.
USDA inspection protocols and FDA hazard analysis requirements govern offal processing standards in the United States, while EFSA and national regulators across Europe enforce category-specific handling rules under the Animal By-Products Regulation. These frameworks elevate compliance costs for smaller processors but create market access barriers that favor scaled operators with dedicated quality systems. Stakeholders must monitor evolving pet food labeling standards and shifting consumer willingness to pay for offal-derived ingredients in premium formulations.
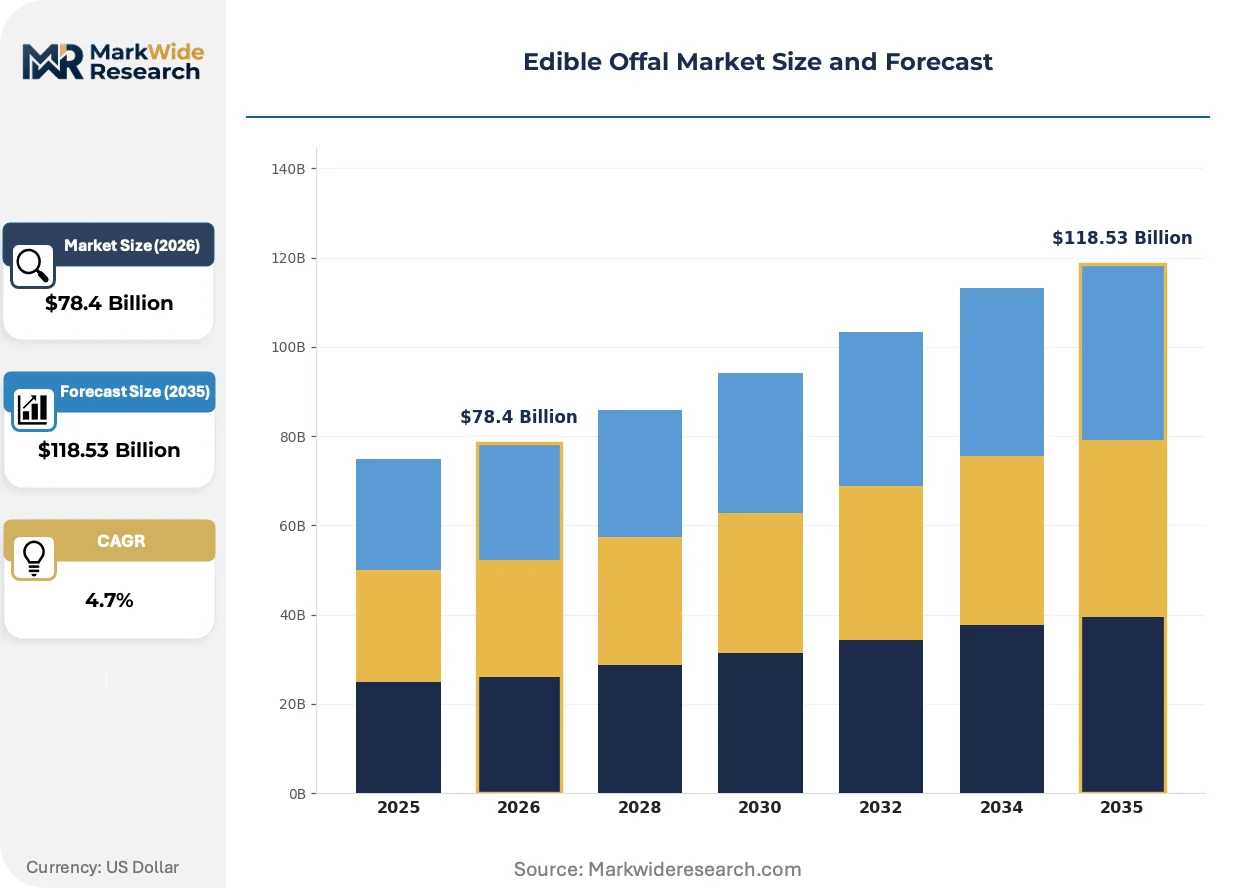
Market Dynamics
The edible offal market is restructuring around the pet food sector's procurement dominance, which is displacing traditional sausage and canned goods manufacturers from priority supply queues and rewiring slaughterhouse offtake agreements toward high-margin animal nutrition specifications.
Growth Catalysts
- Pet Food Formulation Premiumization:Manufacturers are securing dedicated liver and heart supply streams for high-protein kibble and wet food lines, creating stable demand anchors that smooth seasonal volatility in abattoir output.
- EU Animal By-Products Regulation:The updated traceability framework for human-consumption offal is consolidating processing capacity toward certified operators capable of end-to-end documentation.
- Brazilian Integrated Supply Chains:JBS S.A. and Marfrig Global Foods command captive cattle processing networks that guarantee export-grade offal volumes with predictable cold-chain integrity.
Market Restraints
- Input Cost Volatility in Feed Grains:Corn and soybean meal price swings compress margins for rendered offal meal processors who compete with oilseed alternatives in protein feed formulations.
- Supply Concentration Risk in Mercosur:Brazilian and Argentine beef slaughter concentration creates single-point vulnerability for global tripe and kidney export flows.
- Microbial Load Technical Limitations:Intestinal tract offal categories face persistent coliform and salmonella control challenges that restrict their eligibility for premium human-consumption channels.
Strategic Opportunities
- Underpenetrated Southeast Asian Retail:Vietnam and Indonesia lack organized cold-chain infrastructure for fresh offal distribution, creating first-mover openings for blast-frozen export formats.
- Regulatory Tailwind from EU Green Deal:Circular economy mandates valorize animal by-product utilization, potentially expanding eligible offal categories for human food under revised safety protocols.
- Direct-to-Consumer Channel Innovation:Specialty butchers and subscription meat services are bypassing wholesale layers to capture margin on heritage-breed organ meats.
Industry Challenges
- HACCP Certification Timeline Compression:Smaller EU abattoirs face 12-18 month compliance gaps between regulatory updates and operational readiness for Category 3 material handling.
- Capex Intensity in Rendering Technology:Continuous cooker and decanter centrifuge upgrades require seven-figure investments that strain family-owned processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Offal Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $118.53 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liver, Heart, Kidney, Tripe Application: Cooking, Canning, Sausages, Pet Food End User: Households, Restaurants, Food Processors, Exporters Distribution Channel: Online Retail, Supermarkets, Wholesale, Direct Sales |
| Companies Covered | Tyson Foods, JBS S.A., Cargill, NH Foods Ltd., Hormel Foods Corporation, Marfrig Global Foods, Danish Crown Group, Australian Agricultural Company, Vion Food Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Offal Market Evolving Landscape
Enzymatic processing technologies and precision fermentation are converging with tightening veterinary drug residue rules to reshape which offal categories command premium positioning versus relegation to rendering.
High-pressure processing (HPP) is decomposing the traditional heat-pasteurization bottleneck for fresh chilled liver and kidney retail packs. Premium pet food brands in North America are adopting HPP lines at triple-digit annual rates. This non-thermal pathogen reduction is decomposing the historical tradeoff between shelf stability and nutritional integrity that forced offal into frozen or canned formats.
EFSA's updated scientific opinions on transmissible spongiform encephalopathies are tightening specified risk material (SRM) removal protocols for bovine offal across EU member states. Slaughterhouses must now deploy enhanced mechanical separation detection and third-party audit trails for skull, brain, and spinal cord exclusion. The tripe and omasum export sector to East Asian markets is absorbing the bulk of compliance costs through dedicated processing line segregation.
Ingredient buyers are consolidating procurement decisions under centralized nutrition science teams rather than decentralized commodity traders. This concentrates volume commitments with suppliers offering certificate-of-analysis transparency and batch-level mycotoxin documentation. The shift is most pronounced in US and Canadian pet food manufacturing, where procurement officers now specify iron and vitamin A assay thresholds in liver purchase contracts.
Edible Offal Market Segmentation
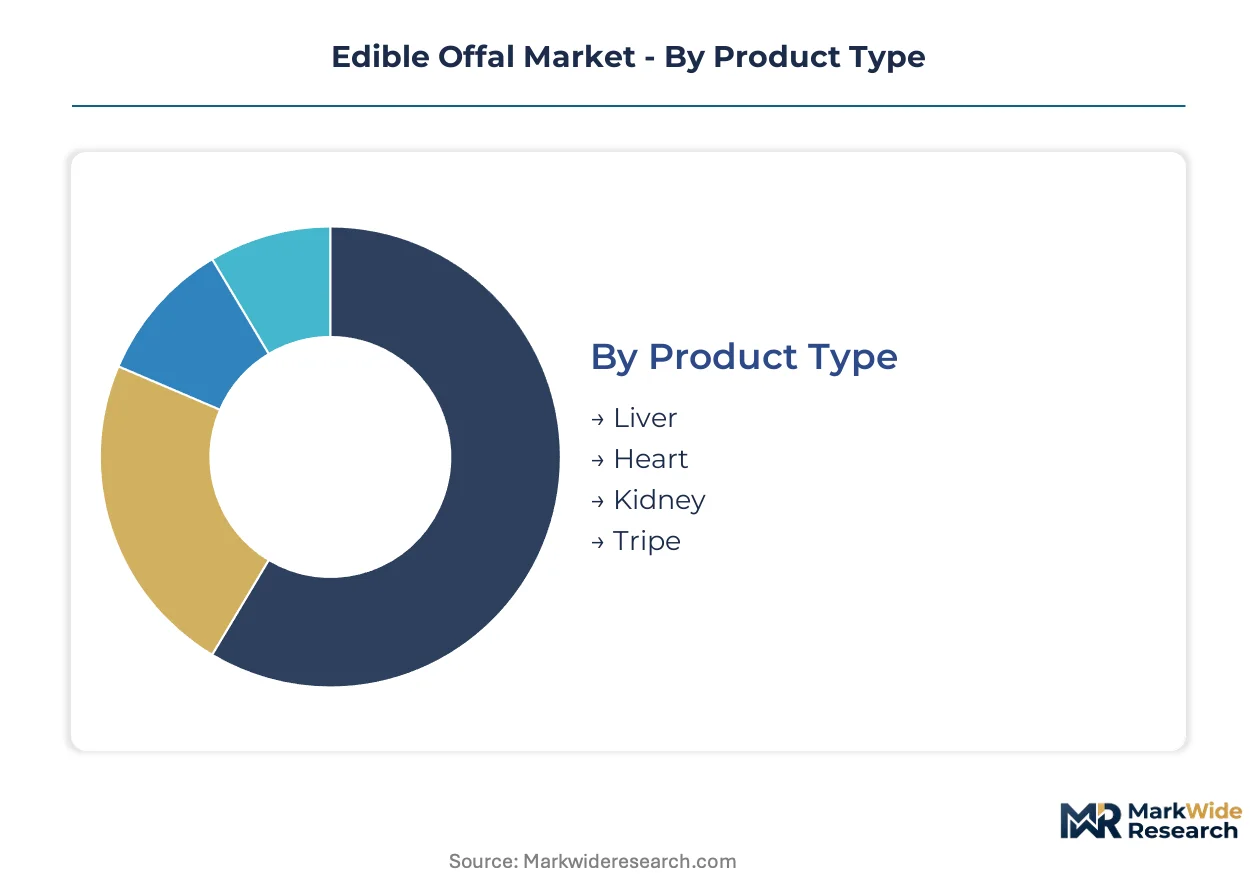
Edible offal segmentation reveals divergent margin structures across product categories and channel tiers. Premium pet food specifications command price multiples over commodity rendering grades, while cold-chain intensity separates profitable export flows from domestic spot markets.
Product Type:
Liver and heart concentrate the highest value per kilogram due to nutritional density and pet food formulation premiums.
- Liver:Rich in vitamin A, iron, and B-complex compounds, liver faces stringent veterinary drug residue thresholds that restrict eligible supply pools. North American pet food manufacturers specify iron assay minimums and batch-level mycotoxin documentation, consolidating procurement with certified processors who maintain end-to-end cold-chain integrity from abattoir to rendering.
- Heart:Lean muscle tissue with high protein density attracts premium positioning in both human-consumption and specialty pet nutrition channels. Brazilian integrated processors leverage captive cattle networks to guarantee heart volumes with predictable pH and temperature controls for export-grade certification.
- Kidney:Functional filtration organ with concentrated mineral content; procurement concentrates in EU-regulated channels requiring enhanced mechanical separation protocols under EFSA specified risk material rules.
- Tripe:Ruminant stomach lining dominates East Asian culinary demand; compliance costs for coliform control and dedicated processing line segregation compress margins for smaller exporters.
The dominant share belongs to liver, while heart is closing the gap fastest on pet food premiumization.
Application:
Volume flows concentrate in traditional processing channels, yet margin expansion clusters in high-specification animal nutrition.
- Cooking:Fresh chilled offal for direct culinary preparation requires HACCP-certified handling and rapid turnover in urban retail environments; microbial load constraints limit shelf life and geographic reach.
- Canning:Heat-stabilized preservation formats face stagnant demand in developed markets as consumers shift toward fresh or frozen alternatives; operational scale determines unit economics.
- Sausages:Ground offal incorporation into emulsified meat products maintains steady industrial offtake, though pet food manufacturers now outbid traditional sausage makers for prime liver and heart supply.
- Pet Food:High-protein kibble and wet food formulations specify organ meat inclusion rates above 15 percent, with procurement officers centralizing purchase decisions under nutrition science teams rather than commodity traders.
Pet food commands the steepest expansion trajectory, while cooking retains volume leadership in emerging markets.
End User:
Customer scale determines specification intensity and contract structure, from spot purchases to multi-year supply agreements.
- Households:Individual consumers purchasing through retail channels drive demand for portion-controlled, pre-cleaned offal packs with extended shelf life; price sensitivity limits premium positioning.
- Restaurants:Foodservice operators in East Asian and Latin American markets source tripe and kidney through wholesale layers, prioritizing consistent supply over traceability documentation.
- Food Processors:Industrial manufacturers of canned goods, sausages, and rendered meals require volume guarantees and certificate-of-analysis transparency for each incoming batch.
- Exporters:Cross-border traders manage cold-chain logistics and regulatory compliance for Mercosur-to-Asia flows, absorbing compliance costs through integrated processing and dedicated line segregation.
Food processors dominate contract volumes, while exporters are gaining share fastest on intercontinental trade expansion.
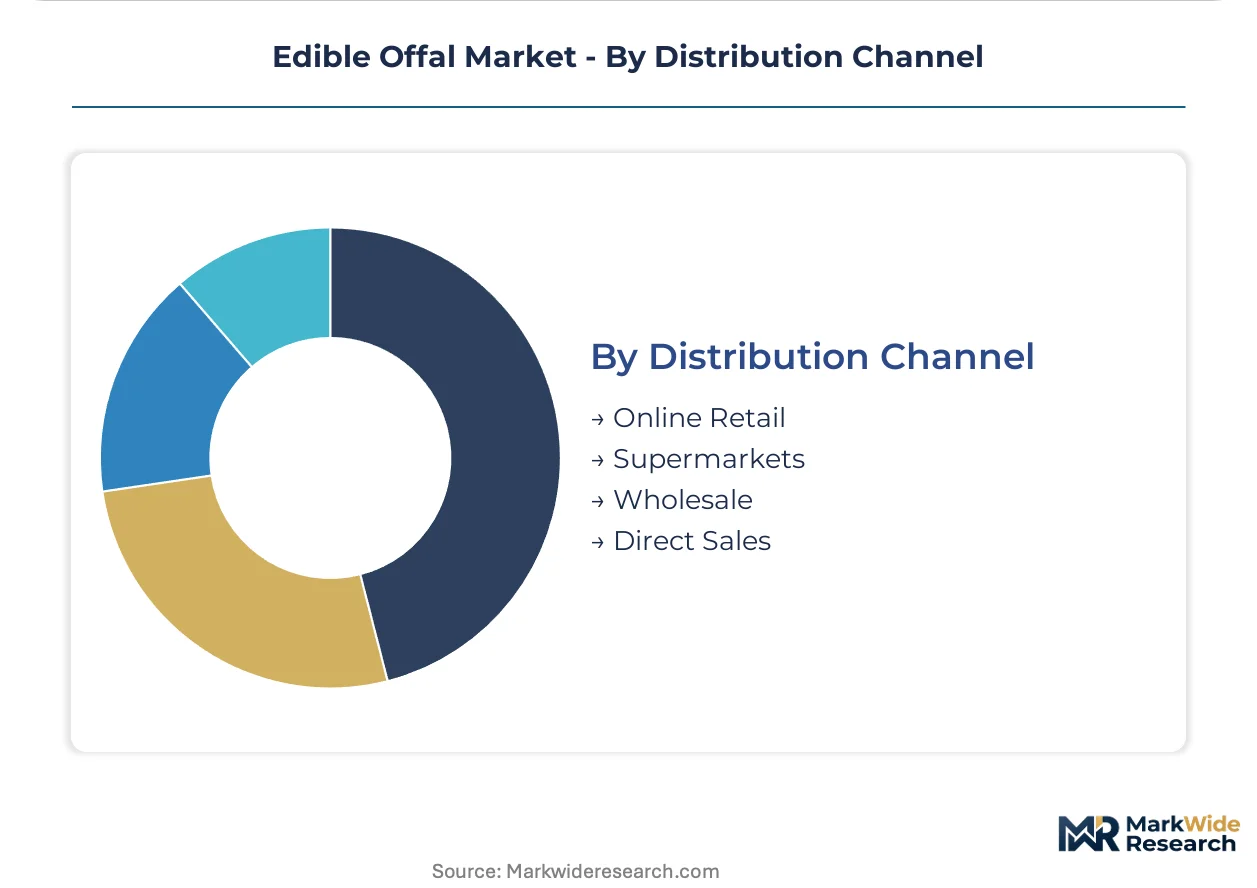
Distribution Channel:
Channel selection governs margin capture, with direct relationships bypassing wholesale markups in premium segments.
- Online Retail:Specialty butchers and subscription meat services deliver heritage-breed organ meats to direct-to-consumer segments, capturing margin through bypassed wholesale layers.
- Supermarkets:Organized retail chains control volume flows in developed markets, leveraging private label programs to standardize specifications and compress supplier margins.
- Wholesale:Traditional intermediaries aggregate fragmented abattoir output for redistribution to food processors and restaurants; concentration risk in Brazilian supply nodes creates single-point vulnerability.
- Direct Sales:Integrated processors like JBS S.A. and Marfrig Global Foods ship export-grade offal directly to international customers, eliminating intermediary costs and ensuring cold-chain custody.
Wholesale maintains volume dominance, while online retail is climbing the fastest on specialty segment premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian and US processors control the majority of export-grade offal volumes, with integrated supply chains from slaughterhouse to cold-chain logistics determining competitive positioning across destination markets.
United States
USDA inspection protocols and FDA hazard analysis requirements govern domestic processing standards, while Tyson Foods leverages vertically integrated poultry operations to secure consistent liver and heart volumes for premium pet nutrition lines. The Midwest cattle processing corridor anchors supply concentration for export-grade tripe and kidney.
Brazil
JBS S.A. and Marfrig Global Foods command captive cattle processing networks that guarantee export-grade offal volumes with predictable cold-chain integrity for Mercosur-to-Asia trade flows. ANVISA enforcement of veterinary drug residue thresholds restricts eligible supply pools for human-consumption channels. São Paulo state hosts the densest concentration of integrated beef processing facilities.
Germany
EFSA specified risk material rules under the EU's updated Animal By-Products Regulation impose enhanced mechanical separation protocols for bovine offal, consolidating processing capacity toward certified operators. The North Rhine-Westphalia slaughterhouse cluster specializes in tripe and omasum preparation for East Asian export markets.
China
Domestic demand for pork offal in culinary applications competes with export-oriented beef tripe processing under tightening GB standards for microbial load control. Yangtze River Delta cold-chain infrastructure supports fresh chilled distribution to urban retail networks. Shanghai and Jiangsu province processors dominate high-volume canning operations.
Australia
Australian Agricultural Company and domestic processors supply halal-certified offal to Middle Eastern and Southeast Asian markets under strict DAWR export health certification requirements. Queensland and New South Wales cattle regions concentrate slaughter capacity with dedicated line segregation for premium organ meat exports.
Edible Offal Market Competitive Landscape
Concentration sits with integrated meatpacking conglomerates that control captive slaughterhouse output and cold-chain logistics. The market structure favors scaled operators with dedicated quality systems capable of end-to-end documentation for EU and US regulatory compliance. Three archetypes dominate: vertically integrated protein majors with global export networks, regional specialists in premium pet nutrition supply, and diversified agricultural conglomerates with rendering operations. Competitive moves center on backward integration into cattle procurement and capacity expansion in HPP-equipped processing lines.
Among the integrated protein majors, JBS S.A. and Tyson Foods exemplify scale-driven positioning through captive supply networks and multi-species processing capabilities. Marfrig Global Foods occupies a comparable tier within South American supply architecture. Danish Crown Group represents the specialist archetype, with differentiated positioning in cold-chain logistics for tripe exports to Asian markets.
| Leading Market Players |
|---|
| Tyson Foods |
| JBS S.A. |
| Cargill |
| NH Foods Ltd. |
| Hormel Foods Corporation |
| Marfrig Global Foods |
| Danish Crown Group |
| Australian Agricultural Company |
| Vion Food Group |
| Others |
Value Network & Pricing Analysis
EFSA's specified risk material protocols gate both supply qualification and price differentiation simultaneously, as processors must absorb enhanced mechanical separation costs to access EU human-consumption channels while pet food manufacturers pay premiums for certificate-of-analysis transparency.
Pricing Analysis
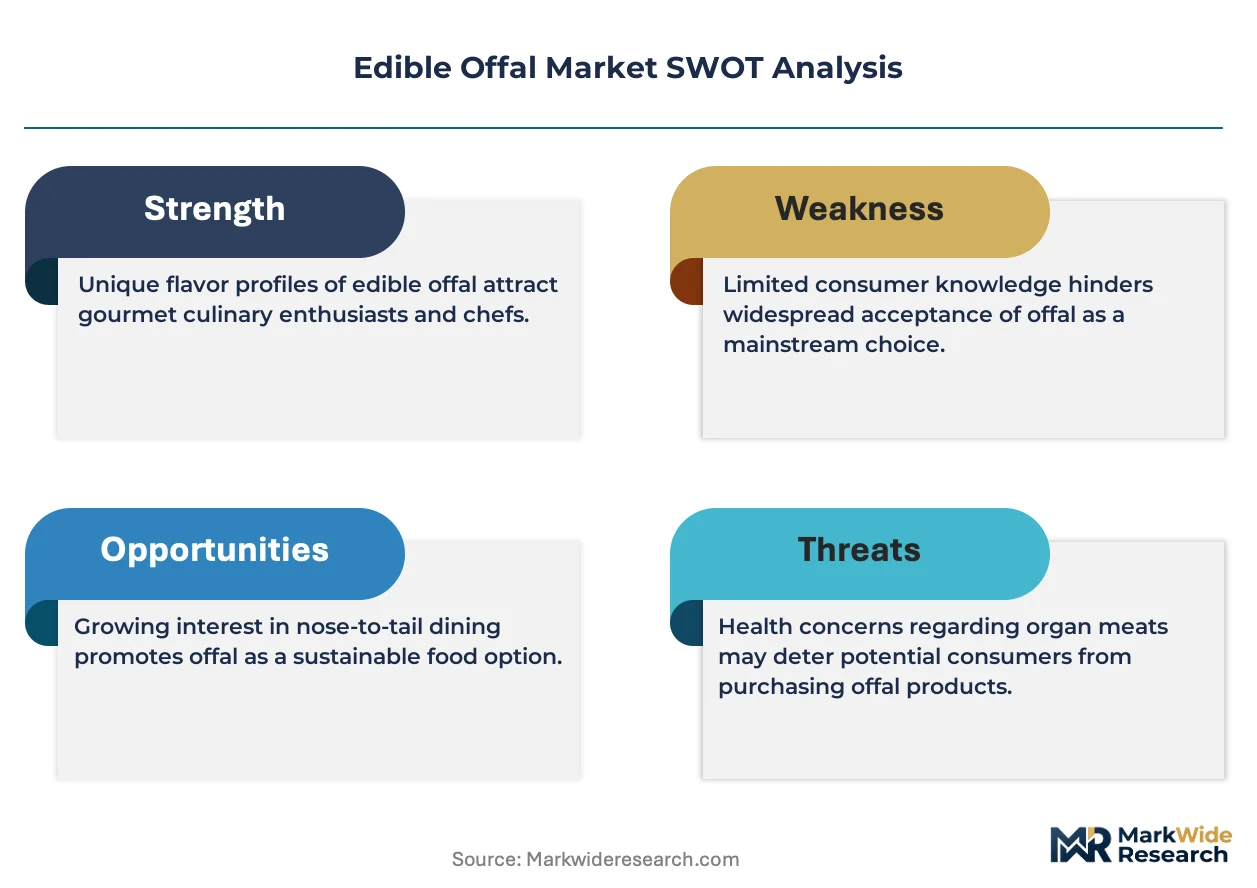
The EU's Animal By-Products Regulation dictates the pricing tier structure across the edible offal market, separating premium human-consumption grades from standard rendering categories based on end-to-end documentation capabilities. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with HACCP-plus-traceability tiers commanding multiples over commodity spot grades. Pricing pressure stems from input cost volatility in feed grains, as corn and soybean meal swings compress margins for rendered offal meal competing with oilseed alternatives. Food processors exhibit the highest price sensitivity due to volume-scale procurement and substitutability with alternative protein sources, while premium pet food manufacturers show least sensitivity given formulation-locked organ meat inclusion rates.
Supply Chain Analysis
Strategic stockpiling of frozen liver and heart inventories dominates procurement behavior among North American pet food manufacturers seeking to smooth seasonal abattoir output fluctuations. Supply concentrates in Brazil, the United States, and Germany, with JBS S.A. and Tyson Foods anchoring captive cattle and poultry networks respectively. Raw material flows draw from cattle slaughter by-products, poultry processing residuals, and imported ruminant stomach linings for East Asian culinary demand. Single-source vulnerability in Mercosur beef slaughter concentration creates structural risk for global tripe and kidney export flows. Distribution runs through integrated processor direct sales for export-grade volumes, while wholesale layers persist for domestic foodservice and retail spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as centralized nutrition science teams consolidate procurement decisions under certificate-of-analysis transparency requirements, creating interoperability premiums for suppliers with batch-level mycotoxin documentation capabilities.
For Market Incumbents: Secure backward integration into cattle procurement networks to guarantee captive liver and heart volumes against emerging regional specialists bidding for premium pet nutrition supply. Expand HPP-equipped processing capacity in Midwest and São Paulo state clusters to capture non-thermal pathogen reduction premiums. Defend against enzymatic processing technology disruptors by locking multi-year supply agreements with centralized pet food procurement officers. For New Entrants and Emerging Players: Differentiate on heritage-breed organ meat provenance for direct-to-consumer subscription channels bypassing wholesale markups. Target Vietnam and Indonesia as underpenetrated Southeast Asian retail markets lacking organized cold-chain infrastructure for fresh offal distribution. Penetrate through blast-frozen export formats with dedicated line segregation for coliform-controlled tripe specifications. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across HPP-equipped processing lines and continuous cooker upgrades, favoring scaled operators over family-owned rendering facilities. Long-term viability over the coming decade rests on regulatory compliance scalability rather than commodity volume positioning. Acquire regional specialists with certified cold-chain logistics capabilities for East Asian export corridors. Watch for EFSA scientific opinion revisions on transmissible spongiform encephalopathies as inflection indicators for eligible offal category expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cattle Procurement | JBS S.A. and Marfrig Global Foods demonstrate how captive supply networks guarantee export-grade offal volumes with predictable cold-chain integrity. |
| HPP Processing Line Expansion | Tyson Foods leverages non-thermal pathogen reduction to decompose the historical tradeoff between shelf stability and nutritional integrity for premium pet nutrition. |
| Direct-to-Consumer Channel Launch | Specialty butchers capture margin through bypassed wholesale layers by delivering heritage-breed organ meats to subscription meat services. |
| EU Green Deal Compliance Positioning | Danish Crown Group differentiates via specialized cold-chain logistics that align with circular economy mandates valorizing animal by-product utilization. |
| Southeast Asian Cold-Chain Infrastructure Buildout | First-mover openings in Vietnam and Indonesia reward blast-frozen export formats with dedicated processing line segregation for coliform control. |
Research Methodology
Initial hypotheses were tested against primary input from pet food procurement officers, abattoir quality managers, rendering facility operators, and East Asian import distributors, then refined through secondary validation. USDA inspection protocols, EFSA scientific opinions, ANVISA enforcement records, and customs trade data provided documentary anchors. Bottom-up volume modeling across product type and application segments triangulated with top-down macroeconomic drivers.
Variance decomposition separated volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product category, application channel, end-user scale tier, and regional regulatory cluster. CAGRs were derived from normalized baseline anchoring and forward trajectory extrapolation. Industry-specific forecast inputs incorporated pet food formulation premiumization rates and EU Animal By-Products Regulation compliance timeline compression.
Material uncertainties — veterinary drug residue threshold revisions, feed grain price volatility, and transmissible spongiform encephalopathy protocol updates — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and cold-chain infrastructure investment continuity. Revision becomes warranted when EFSA specified risk material rules expand eligible offal categories for human consumption beyond current tripe and omasum exemptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Beef Bone Broth Market
Meat Products
United States Edible Meat Market
Meat Products
Meat Paste Market
Meat Products
Mechanically Separated Meat Market
Meat Products
Shark Meat Market
Meat Products
Organic Lamb Market
Meat Products
India Animal Protein Market
Meat Products
Meat Mincers Market
Meat Products
Global Red Meat Market
Meat Products
Blended Meat Market
Meat Products
Global Beef Market
Meat Products
Binders and Scaffolders for Meat and Meat Substitutes Market
Meat Products
Organic Eggs Market
Meat Products
Low-Fat Ham Market
Meat Products
Nitrate-Free Bacon Market
Meat Products
Non-Veg Rte and Rtc Market