
 Automotive Glass Fiber Composites Market | 2026-2036
Automotive Glass Fiber Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Glass Fiber Composites Market Analysis
A capital-intensity divergence between integrated resin producers and specialized fiber manufacturers is redrawing competitive boundaries. Owens Corning leverages captive glass-melting technology to control raw material costs across North America. Jushi Group Co., Ltd. anchors its position through massive furnace scale in China and Southeast Asia. BASF competes by extending its polyamide and polyurethane portfolio into tailored composite matrices for automotive OEMs.
Automotive glass fiber composites combine silica-based glass fibers with thermoset or thermoplastic resin matrices to produce engineered materials with tensile strengths exceeding 300 MPa and density advantages over steel. These composites serve primarily to reduce vehicle mass while maintaining crashworthiness and structural rigidity. Structural components dominate current volume due to load-bearing requirements in chassis and underbody applications, while exterior panels represent the fastest-growing segment as Class-A surface finishing technology matures. Injection molding captures the largest share of manufacturing process value owing to cycle-time efficiency at OEM scale, though compression molding retains margin pools in low-volume electric vehicle platforms.
NHTSA crash-safety standards and EPA Corporate Average Fuel Economy regulations in the United States compel automakers to substitute metals with validated composite architectures. REACH chemical compliance and the EU Green Deal circular-economy framework in Europe restrict certain resin chemistries and mandate end-of-life recyclability pathways. Stakeholders must monitor evolving battery-electric vehicle platform architectures, as skateboard chassis designs fundamentally alter load-path requirements and composite specification priorities.
Market Dynamics
Skateboard battery-electric vehicle architectures are compressing traditional load-path designs and forcing chassis engineers to re-specify glass fiber composite grades for torsional rigidity requirements that differ fundamentally from internal combustion platforms.
Growth Catalysts
- EPA Corporate Average Fuel Economy mandates:United States passenger vehicle fleets must hit progressively tighter grams-per-mile targets, compelling OEMs to substitute steel with validated glass fiber composite body-in-white structures.
- Electric vehicle platform proliferation:Dedicated BEV architectures from Volkswagen, BMW, and emerging Chinese EV specialists specify glass fiber-reinforced polymer for battery enclosure protection and floor pan stiffness.
- Silica supply concentration in China:Massive furnace scale at Jushi Group and regional competitors secures raw material cost advantages that downstream composite processors leverage for export competitiveness.
Market Restraints
- Natural gas price volatility:Glass-melting furnaces consume substantial methane feedstock, and European energy cost spikes since 2022 have compressed margins at regional fiber producers unable to access captive shale gas.
- End-of-life recyclability constraints:REACH chemical compliance and the EU Green Deal circular-economy framework restrict certain thermoset resin chemistries and mandate recyclability pathways that thermoplastic alternatives have yet to fully satisfy.
- Steel industry cost competition:Advanced high-strength steel grades from integrated mills retain cost-per-kilogram advantages in high-volume A-segment vehicles where crash performance requirements remain modest.
Strategic Opportunities
- Class-A surface finishing maturation:Exterior body panels represent underpenetrated white space as in-mold coating and paint-adhesion technologies enable direct replacement of metal hoods and fenders.
- India automotive production scaling:Domestic OEMs and joint ventures expanding capacity under the PLI scheme present first-mover advantages for composite suppliers establishing localized compounding operations.
- Compression molding for low-volume BEVs:Niche electric vehicle platforms with annual volumes below 50,000 units favor this process over injection molding capital intensity, opening margin pools outside mass-market segments.
Industry Challenges
- Composite design engineer scarcity:Automotive OEMs and Tier-1 suppliers face recruitment friction for professionals fluent in anisotropic material modeling and crash simulation for fiber-reinforced polymers.
- NHTSA crash-safety validation timelines:New composite architectures require extended physical testing cycles for frontal and side-impact certification, compressing program launch windows relative to metal baselines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Glass Fiber Composites Market |
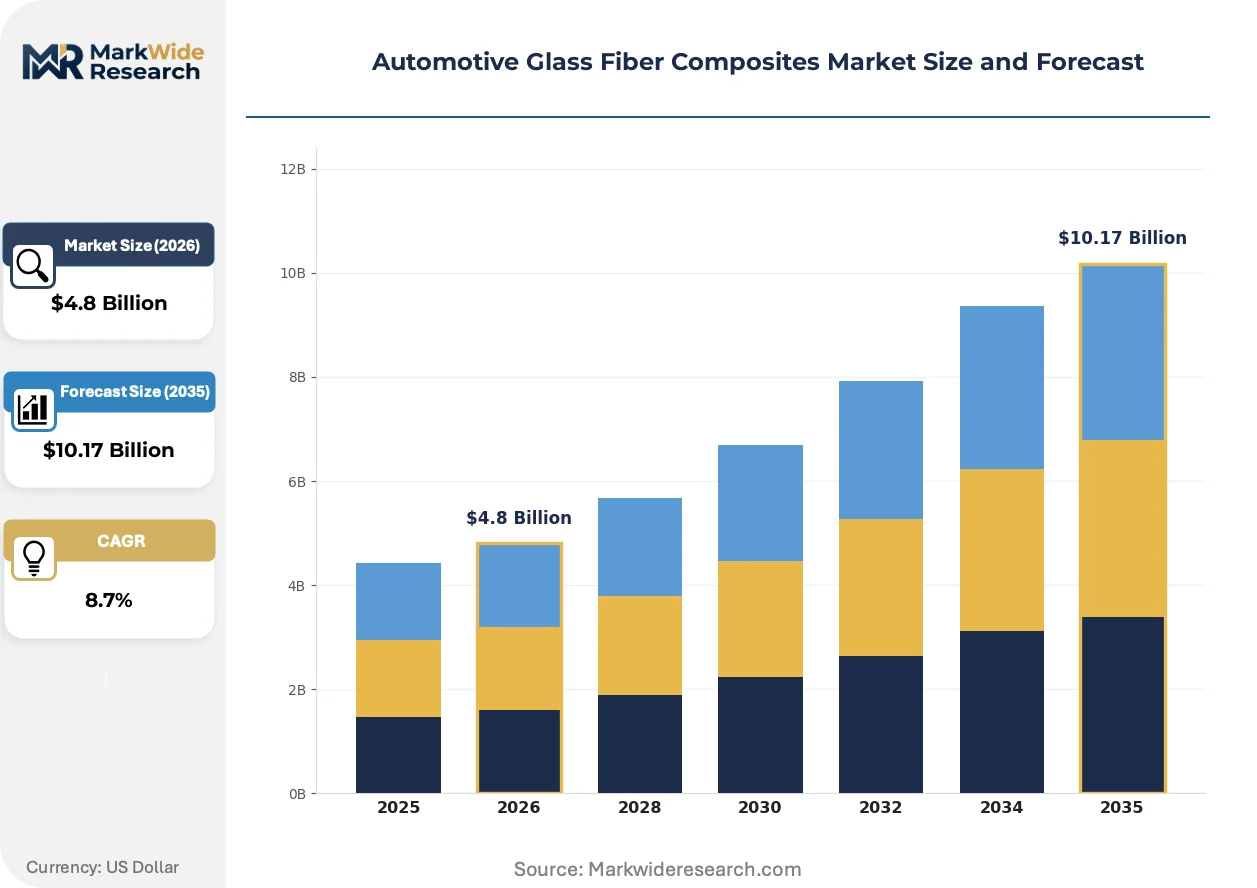
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reinforced Plastics, Structural Components, Interior Panels, Exterior Panels Manufacturing Process: Injection Molding, Compression Molding, Thermoforming, Hand Layup End User: OEMs, Aftermarket Suppliers, Tier-1 Suppliers, Custom Manufacturers Application: Body Panels, Electrical Enclosures, Chassis, Trim Components |
| Companies Covered | BASF, Jushi Group Co., Ltd., Owens Corning, Saint-Gobain, PPG Industries, 3B-the fibreglass company, SABIC, Nippon Electric Glass, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Glass Fiber Composites Market Emerging Trajectories
Material-process convergence is collapsing traditional boundaries between thermoplastic compounding and structural reinforcement, enabling new manufacturing economics for electric vehicle platforms.
Direct long-fiber thermoplastic technology is miniaturizing the fiber length distribution gap between injection-molded short-fiber compounds and compression-molded sheet products. Tier-1 suppliers including Magna and Hanwha Advanced Materials are qualifying DLFT for battery tray and seat pan applications where mid-range mechanical properties suffice. This hybrid approach is miniaturizing the historical trade-off between cycle-time efficiency and structural performance that forced OEMs into binary process selection.
The EU Green Deal circular-economy framework is mandating end-of-life recyclability pathways for automotive materials, with specific targets for fiber-reinforced polymer recovery rates by 2030. ECHA restrictions on certain epoxy hardener chemistries are accelerating resin formulation shifts toward polyamide and polypropylene matrices that support mechanical recycling. European OEMs including BMW and Volvo are responding by specifying thermoplastic composites for non-structural interior and exterior applications where Class-A surfaces are not required.
Automotive procurement organizations are consolidating composite supplier bases and demanding systems-level integration responsibility from fewer Tier-1 partners. Traditional resin distributors and compounders are losing position to full-service module suppliers capable of design, simulation, and assembly. This concentration is most visible in Germany, where Volkswagen Group and Mercedes-Benz have reduced qualified composite suppliers by approximately half since 2020 while expanding technical scope requirements for survivors.
Automotive Glass Fiber Composites Market Segmentation
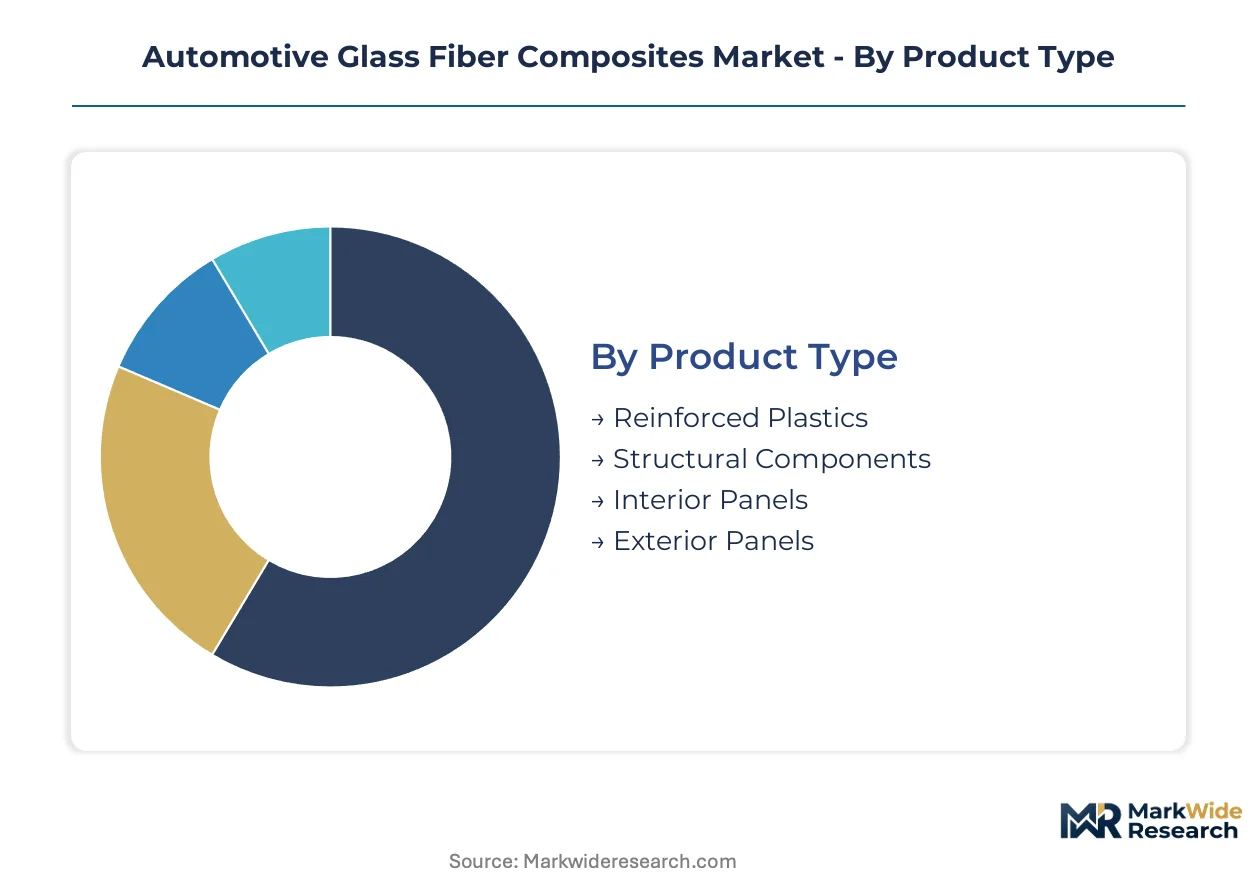
Glass fiber composite specifications diverge sharply across automotive subsystems, with regulatory crash-safety validation and surface-finish requirements dictating material grade selection. Understanding these segment boundaries enables suppliers to align furnace capacity and resin formulation investments with OEM platform roadmaps.
Product Type:
EPA and NHTSA fuel-economy mandates in the United States enforce differentiated mass-reduction targets by vehicle subsystem, creating tiered demand for composite performance characteristics.
- Structural Components:Load-bearing chassis members and underbody reinforcements employ unidirectional or woven glass fiber architectures with thermoset epoxy or vinyl ester matrices. BMW and Volkswagen specify these grades for body-in-white integration in Germany, where OEMs pursue multi-material construction strategies to satisfy EU fleet CO2 regulations.
- Exterior Panels:Class-A surface requirements drive in-mold coating and paint-adhesion technology maturation for hoods, fenders, and liftgates. Demand concentrates at premium German OEMs and emerging Chinese EV specialists seeking visual differentiation for battery-electric platforms.
- Reinforced Plastics:Short-fiber thermoplastic compounds serve non-structural brackets and housings where mechanical properties are secondary to cost and cycle-time efficiency.
- Interior Panels:Door modules, instrument carriers, and seat structures utilize glass-mat thermoplastics with lower fiber loadings, prioritizing acoustic dampening and moldability over structural metrics.
Established volume favors structural components; emerging adoption favors exterior panels.
Manufacturing Process:
Capital intensity and cycle-time economics stratify process selection across production volume tiers, with electric vehicle platform architectures disrupting traditional scale assumptions.
- Injection Molding:Automated high-pressure systems process short-fiber thermoplastic pellets at sub-60-second cycles, dominating mass-market A-segment and B-segment vehicle programs. Volkswagen Group and Mercedes-Benz procurement organizations consolidate supplier bases around this capability for annual volumes exceeding 100,000 units.
- Compression Molding:Sheet molding compound and glass-mat thermoplastic processes accommodate longer fiber lengths and complex geometries at moderate tooling costs. Niche electric vehicle platforms below 50,000 annual units favor this approach for battery enclosures and floor pans.
- Thermoforming:Heated thermoplastic sheets stretch over single-sided molds for large, low-curvature panels with minimal fiber distortion.
- Hand Layup:Manual resin impregnation and consolidation persists in prototype shops and ultra-low-volume specialty vehicle manufacturing.
Scale economics concentrate procurement around injection molding; flexibility requirements sustain compression molding at platform edges.
End User:
Procurement consolidation and systems-integration demands are reshaping tier relationships, with full-service module suppliers displacing traditional resin distributors.
- OEMs:Direct material specification authority resides with BMW, Volkswagen, and Mercedes-Benz engineering organizations in Germany, where composite design capabilities are most developed.
- Tier-1 Suppliers:Magna and Hanwha Advanced Materials assume design, simulation, and assembly responsibility for integrated composite modules.
- Aftermarket Suppliers:Replacement body panels and performance accessories serve collision repair and customization channels with reduced validation burdens.
- Custom Manufacturers:Low-volume specialty and motorsport applications demand tailored fiber architectures outside standard automotive grade specifications.
Technical scope expansion favors Tier-1 suppliers; price pressure concentrates on aftermarket channels.
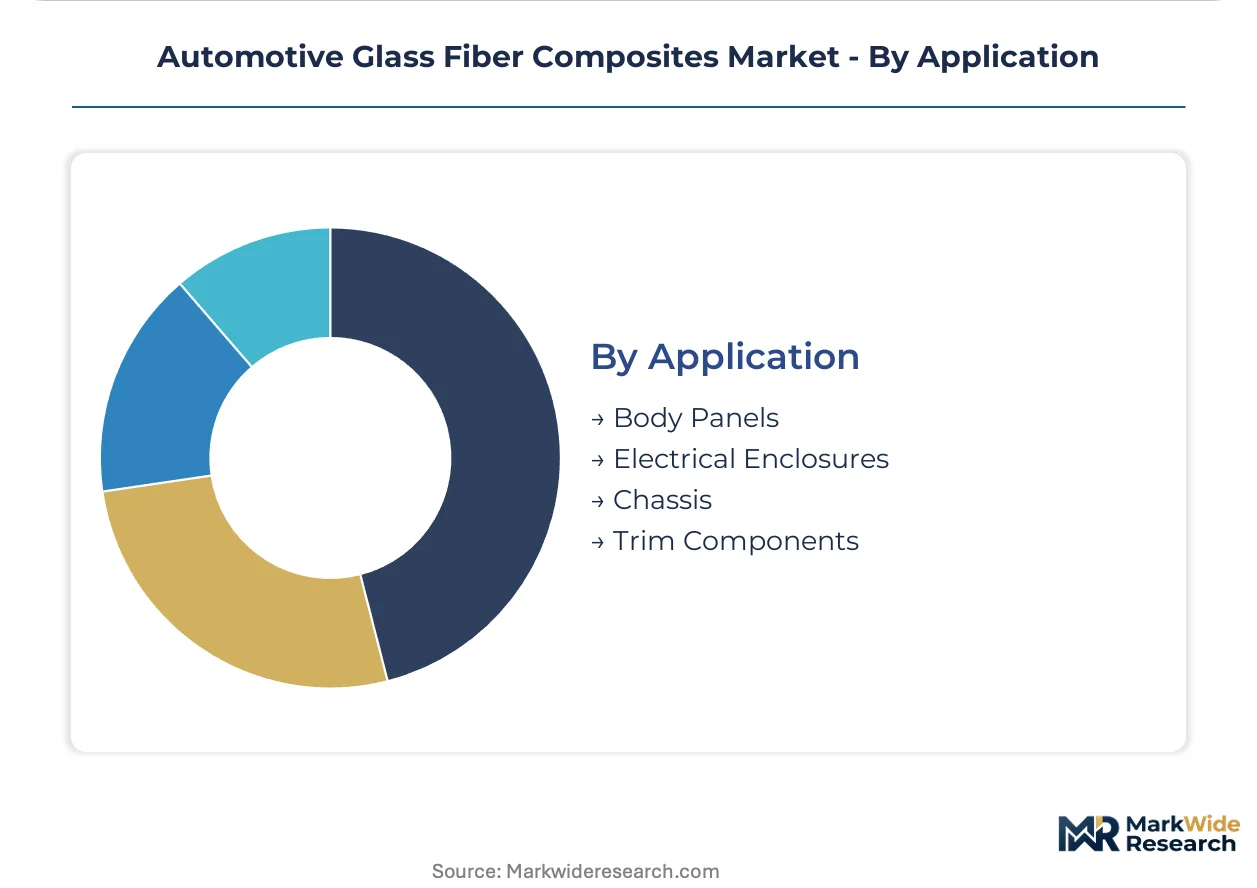
Application:
Load-path reconfiguration in skateboard battery-electric architectures is redistributing composite demand across vehicle structural zones.
- Chassis:Battery tray stiffness and torsional rigidity requirements in dedicated BEV platforms specify glass fiber-reinforced polymers for floor pans and cross-members.
- Body Panels:Hoods, fenders, and liftgates represent underpenetrated white space as surface-finish technologies mature.
- Electrical Enclosures:Battery pack housings and power electronics shields demand flame-retardant resin formulations meeting OEM thermal runaway containment standards.
- Trim Components:Non-structural interior and exterior decorative elements prioritize aesthetic finish and moldability over mechanical performance.
Structural specification favors chassis; surface technology maturation favors body panels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China exhibit the highest price elasticity, driven by massive domestic furnace scale and intense supplier competition, while German OEMs demonstrate lowest elasticity as engineering specifications override cost considerations in premium platform development.
United States
NHTSA crash-safety validation requirements and EPA Corporate Average Fuel Economy mandates compel Detroit automakers to specify validated glass fiber composite architectures for body-in-white structures. The regulatory framework tightens grams-per-mile targets through 2035. Manufacturing clusters concentrate in Michigan and Ohio, where Tier-1 suppliers operate injection molding facilities at OEM-adjacent scale.
Germany
EU Green Deal circular-economy mandates and REACH chemical compliance restrictions accelerate thermoplastic composite adoption for recyclable automotive applications. BMW and Volkswagen engineering organizations specify glass fiber-reinforced polymers for structural body-in-white integration. Industrial activity clusters in Bavaria and Baden-Württemberg, where full-service module suppliers assume expanded design responsibility.
China
Domestic battery-electric vehicle platform proliferation from BYD, NIO, and XPeng generates concentrated demand for glass fiber composites in battery enclosure protection and floor pan applications. MIIT new energy vehicle subsidies and dual carbon goals reinforce lightweight material specification. Production gravity concentrates in Zhejiang and Jiangsu provinces, where Jushi Group operates massive furnace capacity for raw material cost advantage.
Japan
METI carbon neutrality roadmaps and vehicle efficiency standards push Toyota and Honda toward multi-material construction strategies incorporating glass fiber composites. Domestic OEMs prioritize thermoplastic matrices compatible with existing injection molding infrastructure. Technical development concentrates in Aichi and Kanagawa prefectures, where resin compounders collaborate with automakers on anisotropic material modeling.
India
PLI scheme incentives for domestic automotive manufacturing attract composite suppliers establishing localized compounding operations to serve Maruti Suzuki and Hyundai Motor India expansion. BIS material certification requirements create entry barriers for unvalidated imports. Emerging production clusters form in Tamil Nadu and Maharashtra, where joint venture partners scale capacity under government production-linked incentive frameworks.
Automotive Glass Fiber Composites Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Integrated resin producers compete through polyamide and polyurethane formulation expertise, while specialized fiber manufacturers leverage captive glass-melting technology for raw material control. Three archetypes dominate: furnace-scale fiber producers, diversified chemical conglomerates with composite matrix portfolios, and full-service Tier-1 module suppliers. Capacity expansion and strategic partnerships represent the primary competitive moves, as players seek to secure silica supply or secure OEM qualification status.
Among furnace-scale specialists, Jushi Group Co., Ltd. anchors the cost-driven tier through massive production scale in Asia, while Owens Corning occupies a position representing North American vertical integration into raw material supply. BASF exemplifies the diversified chemical archetype, extending polymer formulation capabilities into tailored composite matrices for direct OEM engagement.
| Leading Market Players |
|---|
| BASF |
| Jushi Group Co., Ltd. |
| Owens Corning |
| Saint-Gobain |
| PPG Industries |
| 3B-the fibreglass company |
| SABIC |
| Nippon Electric Glass |
| Solvay |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between glass fiber producers and automotive OEMs lock in silica supply access while providing five-year price visibility that insulates Tier-1 suppliers from European natural gas volatility. These arrangements concentrate procurement leverage at integrated resin compounders serving Volkswagen and BMW platforms in Germany, where EPA and NHTSA validation requirements elevate specification premiums above spot-market alternatives.
Pricing Analysis
After-sales service revenue from composite component replacement and collision repair drives lifetime value capture across the value chain. Three-tier pricing structure across structural-grade, exterior-panel-grade, and reinforced-plastic-grade specifications separates load-bearing chassis applications from non-structural brackets. Cost compression in short-fiber thermoplastic compounds intensifies because Jushi Group furnace scale in China exports feedstock at marginal cost. Tier-1 suppliers exhibit lowest price sensitivity due to OEM qualification lock-in, while aftermarket distributors face acute margin pressure from unvalidated imports.
Supply Chain Analysis
Inventory buffers at European compounders have compressed to three weeks of finished goods as just-in-time delivery contracts with German OEMs eliminated safety stock. Silica feedstock concentrates in China, the United States, and Germany, where Owens Corning and Jushi Group operate captive melting capacity. Finished composite architectures draw from epoxy resin formulations, polyamide matrices, and vinyl ester chemistries. Single-source vulnerability permeates battery enclosure supply chains qualified to specific OEM thermal runaway standards. Distribution runs through full-service module suppliers capable of design-for-manufacturing integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive moat sustained by regulatory entrenchment: NHTSA crash-safety validation timelines create 18-24 month qualification barriers that protect incumbent positions against substitution.
For Market Incumbents: Shield qualified supplier status by accelerating thermoplastic matrix R&D to satisfy EU Green Deal recyclability mandates before REACH restrictions harden. Capacity addition in Zhejiang province secures silica cost advantages against European energy price spikes. Vertical integration into compounding operations defends margin position from resin distributor disintermediation. For New Entrants and Emerging Players: EPA fast-track certification for lightweight body-in-white structures offers entry into US passenger vehicle platforms before Detroit automakers consolidate supplier bases. Compression molding for low-volume BEV architectures below 50,000 units represents the most penetrable white space outside injection-molding scale economics. Partner with emerging Chinese EV specialists seeking localized composite supply to bypass established German procurement networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors furnace-scale specialists with backward integration into raw material supply. Five-to-ten year viability hinges on thermoplastic matrix transition completion before circular-economy mandates render thermoset positions stranded. Acquisition targets should display OEM qualification status across multiple platform architectures. Monitor NHTSA rulemaking on composite crash-testing protocols as inflection indicator for validation cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Melting | Captive glass-melting technology insulates Owens Corning and Jushi Group from European natural gas volatility. |
| Thermoplastic Matrix Formulation Shift | Polyamide and polypropylene investments at BASF align with BMW and Volvo circular-economy specifications. |
| Compression Molding Capacity Expansion | Low-volume BEV platform serviceability opens margin pools outside mass-market injection molding scale. |
| Long-term OEM Qualification Contracts | Volkswagen and Mercedes-Benz procurement consolidation rewards survivors with expanded technical scope. |
| India PLI Scheme Localization | Domestic compounding operations near Tamil Nadu production clusters capture Maruti Suzuki expansion demand. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, Tier-1 supplier procurement directors, glass fiber plant managers, and aftermarket distribution heads anchored the qualitative base for this study. Primary interview insights combined with secondary validation from SEC 10-K filings, ACC industry reports, customs trade data, and vehicle production databases. Bottom-up modeling of content-per-vehicle metrics and top-down triangulation against aggregate automotive production figures ensured cross-verification.
Sensitivity analysis tested forecast outputs against variable natural gas price scenarios and BEV platform adoption rates across the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, composite manufacturing process, and regional production cluster. CAGRs derived from installed base growth and replacement cycle dynamics incorporated EPA fuel-economy mandate compliance trajectories and MIIT new energy vehicle subsidy phase-out patterns.
Decision-makers should treat outputs as directional under assumptions of sustained EPA and NHTSA regulatory stringency; material deviation in mandate timelines or European energy cost normalization would warrant model refresh. Specific risk factors include thermoset resin chemistry restrictions under REACH, skateboard chassis architecture standardization, and steel industry cost competition in A-segment vehicles. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Europe Automotive Bearing Market
Automotive Components
Automotive Retarders Market
Automotive Components
Global Automotive Sun Visor Market
Automotive Components
Automotive Mobile Accessories Market
Automotive Components
Automotive Emblem Market
Automotive Components
Automotive Sensor Cleaning System Market
Automotive Components
Automotive Pedals Market
Automotive Components
Casted Automotive Components Market
Automotive Components
Australia Automotive Pneumatic Actuators Market
Automotive Components
Asia Pacific Automotive Bearing Market
Automotive Components
Global Automotive Coupling Market
Automotive Components
Automotive Stamped Component Market
Automotive Components
Automotive Axle Market
Automotive Components
Automotive Active Suspension System Market
Automotive Components
Automotive Headlight Bulb Market
Automotive Components
Europe Automotive Pneumatic Actuators Market