
 Astaxanthin Market | 2026-2036
Astaxanthin Market Size, Share, and Industry Trends Forecast 2026-2036
Astaxanthin Market Analysis
Pharmaceutical-grade astaxanthin certification is bifurcating the competitive landscape into premium validated supply and commodity-grade alternatives. DSM-Firmenich leverages its integrated biotechnology platform to sustain high-purity fermentation output across European and Asian facilities. AstaReal anchors the Japanese market through proprietary indoor microalgae cultivation systems that dominate quality benchmarks for nutraceutical applications. Cyanotech Corporation specializes in Hawaii-based open-pond production, competing on geographic isolation and natural sunlight optimization.
Astaxanthin is a ketocarotenoid pigment with the molecular formula C40H52O4, synthesized naturally by microalgae such as Haematococcus pluvialis under stress conditions including high salinity or intense light exposure; it functions primarily as a potent antioxidant in commercial applications spanning human nutrition, aquaculture feed fortification, and topical skincare formulations. Microalgae-based astaxanthin commands premium positioning in the product type dimension as clean-label demand shifts procurement toward naturally derived sources, while synthetic variants retain cost-sensitive animal feed applications where regulatory thresholds permit chemical synthesis. The nutraceuticals end user segment leads volume absorption through dietary supplements and functional foods, with softgel and capsule forms capturing disproportionate margin pools due to bioavailability marketing and dosage precision requirements.
EFSA novel food authorization frameworks and FDA GRAS self-affirmation pathways shape market access trajectories for new astaxanthin entrants, with EFSA's stricter toxicological evaluation timelines delaying European product launches relative to US market entry. REACH compliance and EU Green Deal sustainability disclosures are forcing upstream microalgae cultivators to document carbon intensity and water recycling metrics across production batches. Stakeholders must monitor evolving pharmacopeial monograph standards for carotenoid purity thresholds and preemptively secure dual-jurisdiction regulatory dossiers before capacity expansion commitments.
Market Dynamics
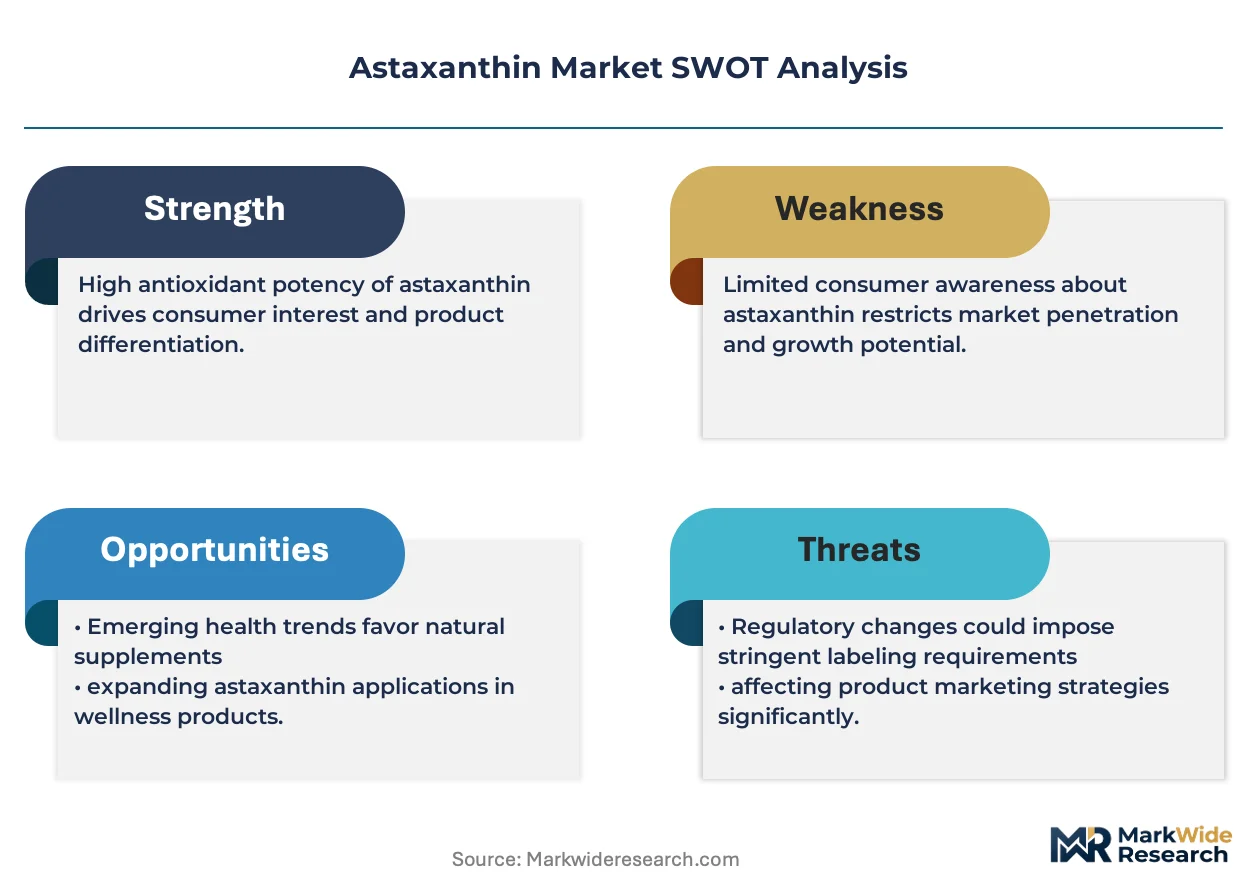
Natural astaxanthin from Haematococcus pluvialis microalgae is displacing synthetic variants as EFSA novel food safety assessments tighten purity thresholds and nutraceutical buyers demand clean-label documentation.
Growth Catalysts
- EFSA Novel Food Framework:Stricter toxicological evaluation timelines for microalgae-sourced antioxidants are accelerating quality differentiation and rewarding validated supply chains with faster European market access.
- Aquaculture Feed Fortification:Salmon and shrimp farming operations in Norway and Chile are expanding astaxanthin inclusion rates to meet consumer-facing pigmentation quality standards in retail seafood.
- Indoor Photobioreactor Cultivation:Closed-system microalgae production technology is reducing contamination risk and enabling year-round output consistency regardless of geographic climate variability.
Market Restraints
- Input Cost Volatility:Carbon dioxide feedstock and specialized LED lighting energy costs fluctuate with regional utility pricing, compressing margins for indoor cultivation operators.
- Supply Concentration Risk:Premium natural astaxanthin production clusters heavily in Japan and Hawaii, creating geographic vulnerability to weather disruptions and logistics bottlenecks.
- Regulatory Friction:REACH compliance and EU Green Deal sustainability disclosure requirements impose documentation burdens on microalgae cultivators that synthetic producers partially circumvent.
Strategic Opportunities
- Underpenetrated China Market:SAMR regulatory pathways for novel food ingredients remain less stringent than EFSA equivalents, offering faster commercialization timelines for validated natural astaxanthin entrants.
- Topical Skincare Convergence:Cosmetic formulators are combining astaxanthin with ceramide complexes and peptide actives, opening premium positioning in dermocoscience channels.
- Direct-to-Consumer Subscription Models:Softgel supplement brands are bypassing traditional pharmacy retail through telehealth-integrated recurring delivery platforms.
Industry Challenges
- Pharmacopeial Certification Timelines:USP and EP monograph compliance for carotenoid purity verification extends 18-24 months, delaying revenue recognition for new production batches.
- Specialized Bioprocess Engineering Talent:Scarcity of professionals with simultaneous expertise in microalgae physiology and GMP fermentation scale-up constrains facility expansion velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Astaxanthin Market |
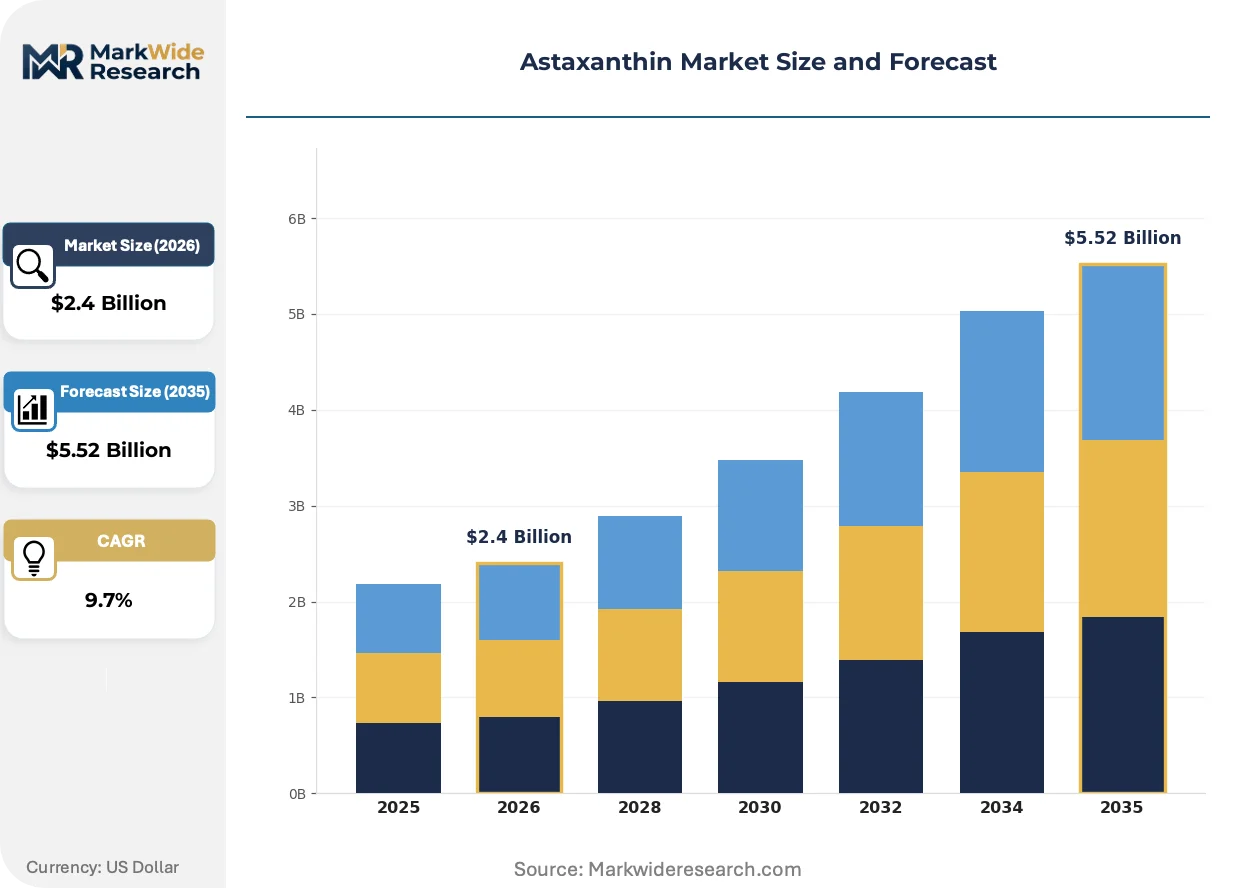
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Microalgae-Based, Chemical Synthesis End User: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals Application: Dietary Supplements, Animal Feed, Beauty Products, Functional Foods Form: Powder, Liquid, Softgel, Capsule |
| Companies Covered | DSM-Firmenich, AstaReal, Algatech Ltd, Algalif, BASF SE, Cyanotech Corporation, Fuji Chemical Industries, Beijing Gingko Group, PIVEG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Astaxanthin Market Emerging Trajectories
Clean-label procurement mandates and biotechnology platform maturation are restructuring competitive advantage around cultivation methodology transparency and carbon intensity documentation.
Photobioreactor-based closed cultivation systems are displacing open-pond production for nutraceutical-grade output. Dietary supplement manufacturers in Germany and Switzerland are prioritizing these sources for premium softgel lines. This technology is displacing commodity-positioned Hawaiian and Indian open-pond supply from high-margin human nutrition contracts.
EFSA's evolving novel food safety assessment protocols now require comprehensive toxicological dossiers including 90-day rodent studies and genotoxicity screening. European astaxanthin entrants face 12-18 month authorization delays versus US FDA GRAS self-affirmation pathways. Nutraceutical brands targeting EU distribution are pre-building regulatory dossiers before capacity commitments to avoid launch timing penalties.
Ingredient provenance documentation has become a primary purchasing criterion for contract manufacturers serving functional food brands. Third-party certified astaxanthin with carbon footprint labeling commands 15-25% procurement premiums over uncertified alternatives in Nordic and Benelux markets. This behavioral shift is most visible in Netherlands-based supplement formulation houses supplying pharmacy retail chains.
Astaxanthin Market Segmentation
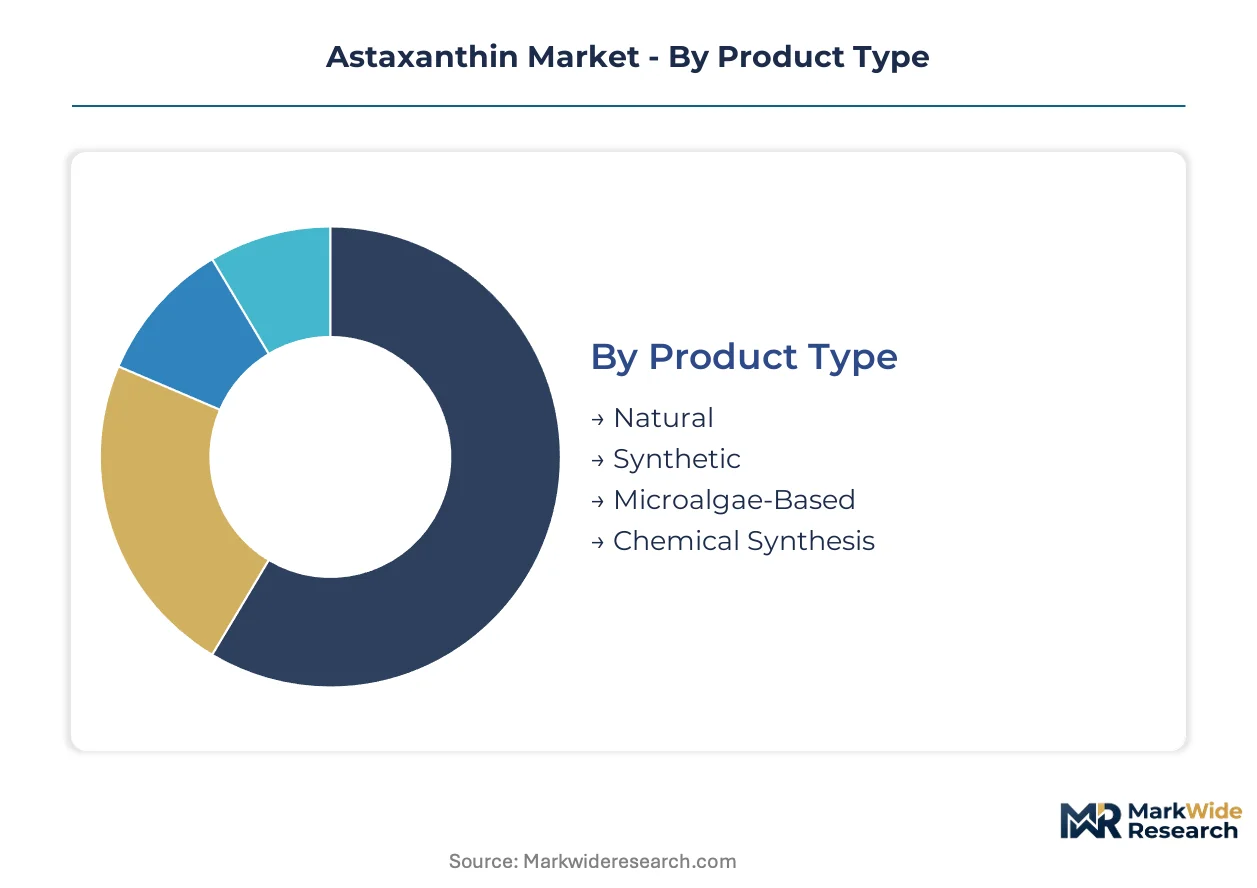
Astaxanthin procurement channels bifurcate sharply between pharmaceutical-grade supply chains demanding pharmacopeial certification and commodity-grade flows serving cost-sensitive aquaculture operations. Segment selection determines regulatory pathway complexity, margin structure, and customer concentration risk for producers.
Product Type:
Natural astaxanthin moves through nutraceutical distributors and pharmacy retail chains, while synthetic variants channel into bulk aquaculture feed compounders.
- Natural:Extracted from crustacean byproducts and other biological sources, this variant carries higher carotenoid complexity and variable purity profiles. Haematococcus pluvialis microalgae cultivation in Japan and Hawaii supplies premium nutraceutical contracts where EFSA novel food authorization validates market access.
- Synthetic:Petrochemical-derived astaxanthin dominates salmon and shrimp feed applications in Norway and Chile where pigmentation standards are enforced but natural sourcing premiums are rejected. Cost structures undercut microalgae alternatives by 60-80% at industrial volumes.
- Microalgae-Based:Haematococcus pluvialis-derived astaxanthin commands clean-label positioning in German and Swiss supplement manufacturing.
- Chemical Synthesis:Laboratory-produced variants serve regulated aquaculture markets with consistent batch-to-batch specifications.
Microalgae-Based dominates installed base. Natural is where expansion concentrates.
End User:
Margin tiers separate pharmaceutical-grade validation requirements from functional food commodity positioning.
- Food & Beverage:Beverage fortification and functional food integration in Japan leverage METI labeling frameworks for antioxidant health claims. EFSA health claim restrictions in Europe limit positioning to basic nutritional declarations.
- Pharmaceuticals:USP and EP monograph compliance for injectable-grade astaxanthin extends 18-24 month certification timelines. PMDA pharmaceutical-grade approvals in Japan enable premium pricing for validated oxidative stress therapeutics.
- Cosmetics:Dermocoscience formulators in France and Switzerland combine astaxanthin with ceramide complexes for premium skincare positioning.
- Nutraceuticals:Softgel and capsule manufacturers absorb the majority of Haematococcus pluvialis supply for direct-to-consumer supplement distribution.
Nutraceuticals captures volume leadership. Pharmaceuticals is climbing the fastest.
Application:
Volume scale versus value concentration determines channel strategy across end-use categories.
- Dietary Supplements:Softgel delivery formats command 15-25% procurement premiums in Nordic pharmacy retail where bioavailability marketing differentiates shelf positioning. German contract manufacturers prioritize photobioreactor-sourced astaxanthin for premium line extensions.
- Animal Feed:Salmon farming operations in Norway mandate astaxanthin inclusion rates for flesh coloration standards that influence retail seafood pricing. Chilean shrimp producers balance synthetic versus natural sourcing based on export market destination requirements.
- Beauty Products:Topical serum formulations in South Korea integrate astaxanthin with peptide actives for anti-aging positioning.
- Functional Foods:Beverage and fortified dairy applications in Japan leverage existing consumer familiarity with microalgae-derived antioxidants.
Animal Feed dominates installed base. Dietary Supplements is where expansion concentrates.
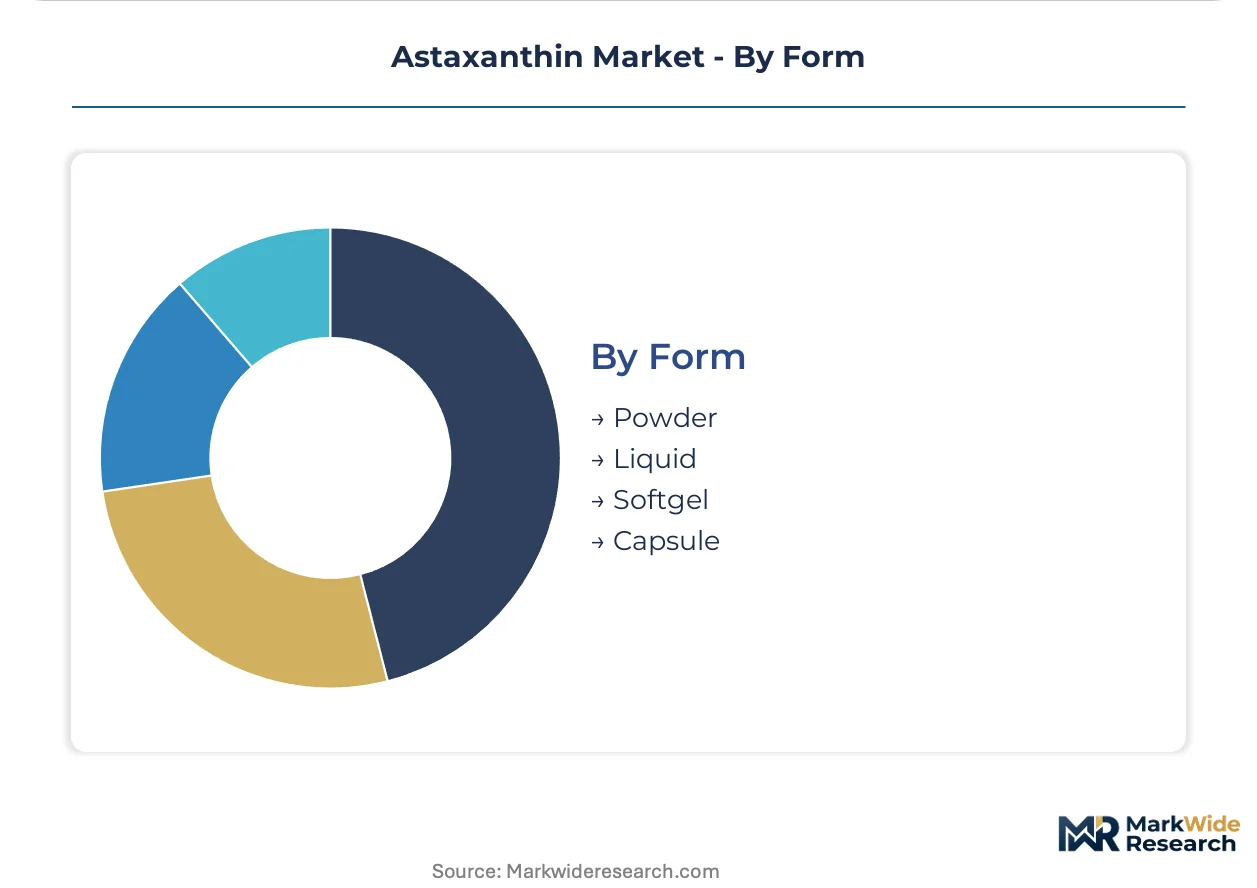
Form:
Delivery format selection drives manufacturing equipment requirements and bioavailability marketing claims.
- Powder:Bulk feed premix applications in aquaculture compounders favor spray-dried microalgae biomass for handling efficiency.
- Liquid:Emulsion formats serve beverage fortification and cosmetic serum applications requiring homogeneous dispersion.
- Softgel:Oil-based encapsulation in Swiss and German manufacturing facilities captures premium supplement positioning through oxidative stability claims.
- Capsule:Hard-shell delivery accommodates powder formulations for vegetarian-positioned product lines in Benelux markets.
Softgel dominates installed base. Liquid is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese buyers absorb premium microalgae-sourced astaxanthin with minimal price elasticity, while Norwegian aquaculture operators demand synthetic variants at 60-80% cost discounts. This demand-elasticity contrast structures regional procurement patterns and margin distribution across supply chains.
Japan
Domestic functional food regulations under METI favor microalgae-sourced antioxidants for health claim labeling. PMDA pharmaceutical-grade approvals enable premium pricing for oxidative stress therapeutics validated through toxicological dossiers. Tokyo and Tsukuba anchor production clusters where AstaReal and Fuji Chemical Industries operate proprietary indoor cultivation systems.
United States
FDA GRAS self-affirmation pathways accelerate nutraceutical product launches versus European authorization timelines. Dietary supplement manufacturers in California and Oregon prioritize softgel formats for direct-to-consumer distribution through telehealth-integrated platforms. Cyanotech Corporation maintains Hawaii-based open-pond production competing on geographic isolation and natural sunlight optimization.
Germany
Contract manufacturers in Bavaria and Baden-Württemberg source photobioreactor-derived astaxanthin for premium pharmacy retail lines. EFSA health claim restrictions limit functional food positioning to basic nutritional declarations, compressing beverage fortification margins. REACH compliance and EU Green Deal sustainability disclosures force upstream cultivators to document carbon intensity metrics across production batches.
China
SAMR regulatory pathways for novel food ingredients remain less stringent than EFSA equivalents, offering faster commercialization timelines for validated natural entrants. Domestic demand concentrates in coastal provinces where functional food familiarity with microalgae antioxidants is established. Beijing Gingko Group represents domestic supply capability serving regional nutraceutical formulation houses.
Norway
Salmon farming operations mandate astaxanthin inclusion rates for flesh coloration standards influencing retail seafood pricing. Synthetic variants dominate feed compounder procurement due to cost structures undercutting microalgae alternatives at industrial volumes. Bergen and Trondheim anchor aquaculture supply chain coordination with Chilean export market intelligence.
Astaxanthin Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with biotechnology-integrated specialists commanding premium nutraceutical contracts while petrochemical-derived suppliers capture volume aquaculture accounts. The competitive structure bifurcates around certification grade rather than scale alone. Three archetypes dominate: indoor photobioreactor cultivators, open-pond microalgae producers, and synthetic chemical manufacturers. Capacity expansion in closed-system cultivation and pharmacopeial certification acceleration represent the dominant competitive moves reshaping supply-side positioning.
Among biotechnology-integrated specialists, DSM-Firmenich leverages fermentation platforms across European and Asian facilities, while AstaReal anchors Japanese market quality benchmarks through proprietary cultivation systems. Cyanotech Corporation exemplifies geographic-isolation positioning in open-pond production. These three represent distinct archetype strategies: integrated biotechnology, regional quality leadership, and climate-advantaged natural sourcing.
| Leading Market Players |
|---|
| DSM-Firmenich |
| AstaReal |
| Algatech Ltd |
| Algalif |
| BASF SE |
| Cyanotech Corporation |
| Fuji Chemical Industries |
| Beijing Gingko Group |
| PIVEG |
| Others |
Supply Flow & Price Mechanics
Natural astaxanthin from Haematococcus pluvialis microalgae displacing synthetic petrochemical variants simultaneously redistributes production geography toward Japan and Hawaii while compressing cost premiums as EFSA novel food authorization validates quality differentiation. This substitution dynamic concentrates pricing power with indoor photobioreactor operators and fragments commodity-grade supply chains.
Pricing Analysis
After-sales regulatory certification revenue drives lifetime value for astaxanthin producers, with pharmacopeial-grade contracts capturing sustained premium streams. Three-tier pricing structure across pharmaceutical, nutraceutical, and feed-grade levels separates USP/EP-validated supply from EFSA novel food tier and uncertified commodity variants. Cost compression in synthetic aquaculture feed grades intensifies because Norwegian and Chilean salmon farmers reject natural sourcing premiums. Aquaculture compounders exhibit highest price sensitivity, while Japanese pharmaceutical buyers absorb validated supply with minimal elasticity.
Supply Chain Analysis
Japan and Hawaii anchor premium microalgae cultivation, with Tsukuba and Kona production clusters supplying validated nutraceutical contracts. Raw material dependencies center on carbon dioxide feedstock, specialized LED lighting systems, and photobioreactor-grade nutrient media. Single-source vulnerability concentrates in geographic weather exposure and logistics bottlenecks for Hawaiian open-pond operations. Distribution runs through nutraceutical distributors and pharmacy retail chains for human-grade supply, while bulk aquaculture feed compounders absorb synthetic volumes through direct long-term offtake arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where EFSA novel food authorization timelines and pharmacopeial certification barriers protect validated incumbent positions against commodity substitution.
For Market Incumbents: Shield market position by accelerating pharmacopeial dossier completion ahead of capacity expansion commitments, countering emerging photobioreactor entrants in Germany and Switzerland. Deepen backward integration into proprietary Haematococcus pluvialis strain development to secure cultivation yield advantages. Prioritize indoor cultivation capacity additions in climatically stable geographies to reduce weather disruption exposure. For New Entrants and Emerging Players: Lead with SAMR regulatory pathway exploitation in China, where novel food ingredient timelines run shorter than EFSA equivalents and coastal province demand familiarity supports faster commercialization. Target underpenetrated topical skincare convergence in South Korean dermocoscience channels, where astaxanthin-peptide combination formulations command premium positioning. Deploy direct-to-consumer subscription models through telehealth-integrated platforms to bypass established pharmacy retail gatekeepers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed indoor photobioreactor specialists possessing EFSA-validated dossiers but constrained by specialized bioprocess engineering talent scarcity. Long-term viability across the analysis window hinges on regulatory authorization durability and cultivation technology IP protection. Watch for pharmacopeial monograph standard revisions as inflection indicators for certification-grade margin compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacopeial Certification Acceleration | USP and EP monograph compliance secures pharmaceutical-grade pricing tiers in Japanese oxidative stress therapeutics. |
| Indoor Photobioreactor Expansion | Closed-system cultivation reduces contamination risk and enables year-round output consistency for German softgel manufacturers. |
| EFSA Novel Food Dossier Pre-Building | Pre-commitment regulatory preparation avoids launch timing penalties in European nutraceutical distribution. |
| Backward Integration into Strain Development | Proprietary Haematococcus pluvialis genetics secures yield advantages against Hawaiian open-pond competitors. |
| Direct-to-Consumer Platform Launch | Telehealth-integrated subscription models bypass pharmacy retail margin extraction in California and Oregon markets. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with microalgae cultivation directors, nutraceutical procurement managers, EFSA regulatory consultants, and pharmacy retail category buyers; and secondary validation through EFSA novel food authorization databases, FDA GRAS notification filings, USP and EP pharmacopeial monograph standards, and customs trade data for astaxanthin feedstock flows. Bottom-up production capacity modeling triangulated against top-down end-use demand segmentation across dietary supplements, aquaculture feed, and pharmaceutical applications.
Across the analysis window, the forecasting framework integrated product type, end user, application, and form dimensions with regional regulatory cluster variations. CAGRs derived from segment-level volume absorption rates and value-per-unit progression by certification tier. Industry-specific inputs included EFSA authorization timeline distributions, salmon farming astaxanthin inclusion rate mandates in Norway, and photobioreactor versus open-pond production cost structures.
The analysis sits within stated boundaries; outcomes outside sustained EFSA regulatory stringency, stable aquaculture pigmentation standards, or continued clean-label procurement preference would require recalibration. Forecasts reflect documented assumptions regarding authorization timeline distributions and cultivation technology maturation curves. Recalibration cycles align with material shifts in pharmacopeial standards, novel food safety assessment protocols, or carbon intensity disclosure requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Fructo-Oligosaccharides (FOS) Market
Food Components and Additives
Germany Food Preservatives Market
Food Components and Additives
Food Grade Calcium Carbonate Market
Food Components and Additives
Polyphenols Market
Food Components and Additives
US Food Hydrocolloids Market
Food Components and Additives
Russia Food Hydrocolloids Market
Food Components and Additives
Bergamot Polyphenol Ingredient Systems Market
Food Components and Additives
Isoflavones Market
Food Components and Additives
Food Hydrocolloids Market
Food Components and Additives
Food Antimicrobial Coating Market
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
Europe Food Stabilizers Market
Food Components and Additives
Europe Food Premix Market
Food Components and Additives
Food Antioxidant Market
Food Components and Additives
Calcium Glycerophosphate Market
Food Components and Additives
Germany Food Hydrocolloids Market