
 Perimeter Intrusion Detection Systems Market | 2026-2036
Perimeter Intrusion Detection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Perimeter Intrusion Detection Systems Market Intelligence
Software-as-a-Service (SaaS) and managed monitoring revenue is narrowing the profitability gap with traditional hardware-centric system sales. This shift favors vendors with strong software and network integration capabilities. Honeywell International Inc. leverages its extensive portfolio in building automation to offer integrated security solutions. Senstar Corporation specializes in a wide array of sensor technologies, from fiber optic to microwave, to address diverse site requirements.
Perimeter Intrusion Detection Systems are integrated solutions designed to detect and alert on unauthorized access across a defined boundary. These systems often utilize sensor fusion, combining data from multiple technologies to achieve a high probability of detection with low nuisance alarm rates. Their primary purpose is to provide early warning for high-security locations like military bases and power plants. Within the technology landscape, video analytics and thermal imaging represent the fastest-growing segments, while radar-based systems are specified for large-scale critical infrastructure protection.
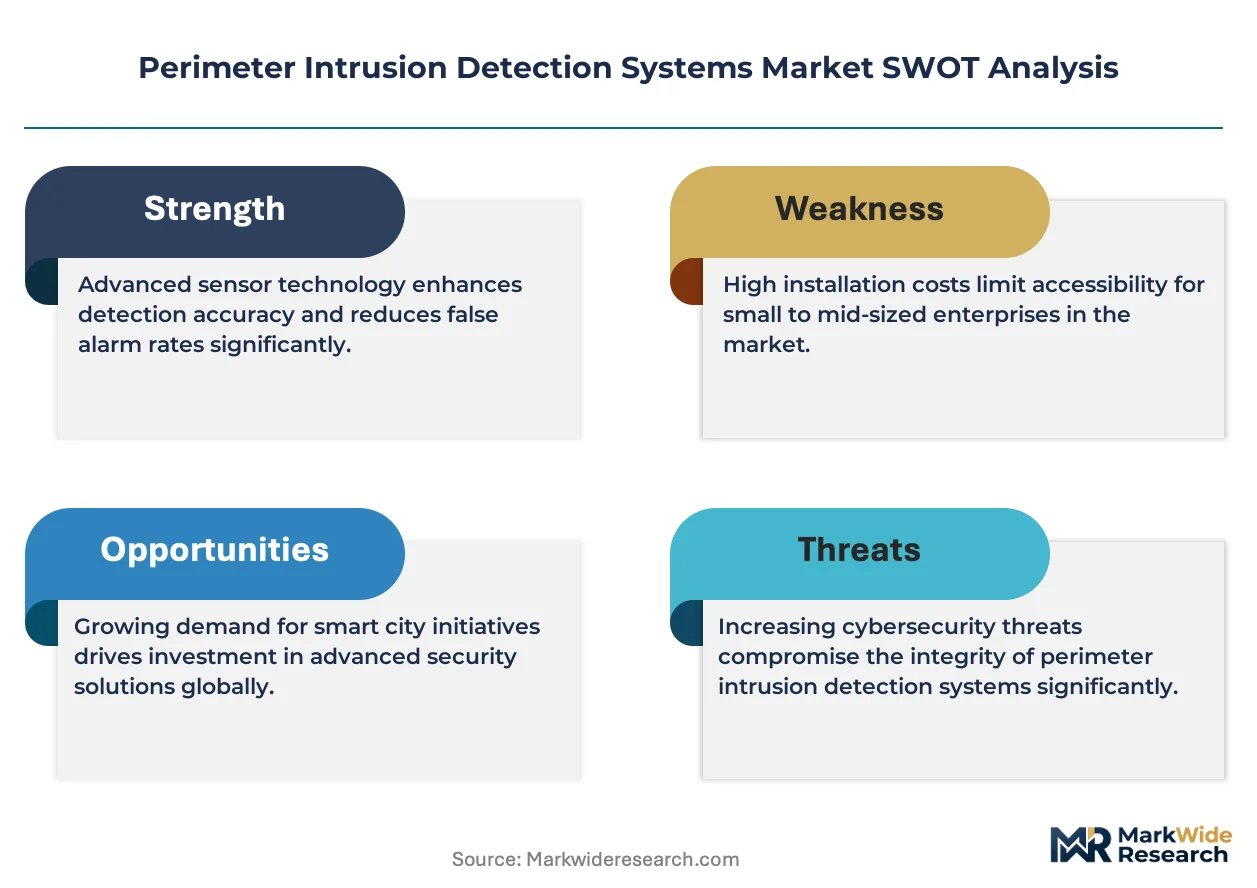
Regulatory frameworks like the US Department of Homeland Security's CFATS program and the EU's Critical Entities Resilience (CER) Directive compel adoption at specific facilities. These standards mandate minimum physical protection levels for operators of essential services, directly influencing system specifications. Consequently, stakeholder decisions will increasingly center on balancing the capital cost of advanced sensor technologies against the operational benefits of reduced false alarm rates.
Market Dynamics
The convergence of physical security hardware with information technology networks is the central force shaping the market. This integration, driven by AI-powered analytics and IoT sensor proliferation, transforms perimeter defense from a static barrier into a dynamic, data-driven intelligence function.
Growth Catalysts
- Regulatory Mandates:The European Union's Critical Entities Resilience (CER) Directive compels operators of essential services to enhance physical security, directly increasing demand for compliant intrusion detection systems at facilities like ports and energy grids.
- Critical Infrastructure Expansion:Construction of new data centers across the United States and transportation hubs in India creates immediate requirements for advanced, large-scale perimeter protection to secure high-value assets and sensitive information.
- Sensor Fusion Adoption:The combination of multiple sensor technologies, such as thermal imaging with radar, improves detection accuracy and significantly reduces false alarms, making investment in these systems more operationally viable for end-users.
Market Restraints
- High Initial Investment:The significant capital expenditure required for advanced systems, particularly large-area surveillance radar and long-range thermal cameras, can be a barrier for organizations with constrained security budgets.
- System Integration Complexity:Integrating modern IP-based PIDS with legacy analog security systems and disparate command-and-control platforms presents significant technical challenges and can lead to implementation delays.
- Environmental Interference:The performance of certain sensor technologies, like microwave and passive infrared, can be degraded by adverse weather conditions, dense vegetation, or wildlife, leading to nuisance alarms that erode operator confidence.
Strategic Opportunities
- SaaS and Managed Services:Shifting from hardware sales to recurring revenue models, such as Video-Surveillance-as-a-Service (VSaaS) and remote monitoring, offers a significant opportunity to capture long-term customer value and lower adoption barriers.
- Counter-Drone Integration:The growing threat of unauthorized drones creates a new market for PIDS solutions that can detect, track, and identify unmanned aerial systems (UAS), integrating this capability with ground-based sensors.
- Emerging Market Infrastructure:Government-led infrastructure projects in developing economies, including Brazil's focus on securing energy and transportation assets, present greenfield deployment opportunities for sophisticated perimeter security solutions.
Industry Challenges
- Cybersecurity of Connected Devices:As PIDS become more networked, they are increasingly vulnerable to cyber-attacks, requiring robust cybersecurity protocols to prevent system compromise or data breaches, a significant operational challenge.
- Specialized Talent Shortage:A lack of technicians and analysts with the necessary skills to design, install, and manage complex, AI-enabled, and networked security systems constrains effective deployment and maintenance.
- Standardization Gaps:The absence of universal interoperability standards for connecting sensors and software from different vendors complicates system design and limits customer choice, often leading to vendor lock-in.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perimeter Intrusion Detection Systems Market |
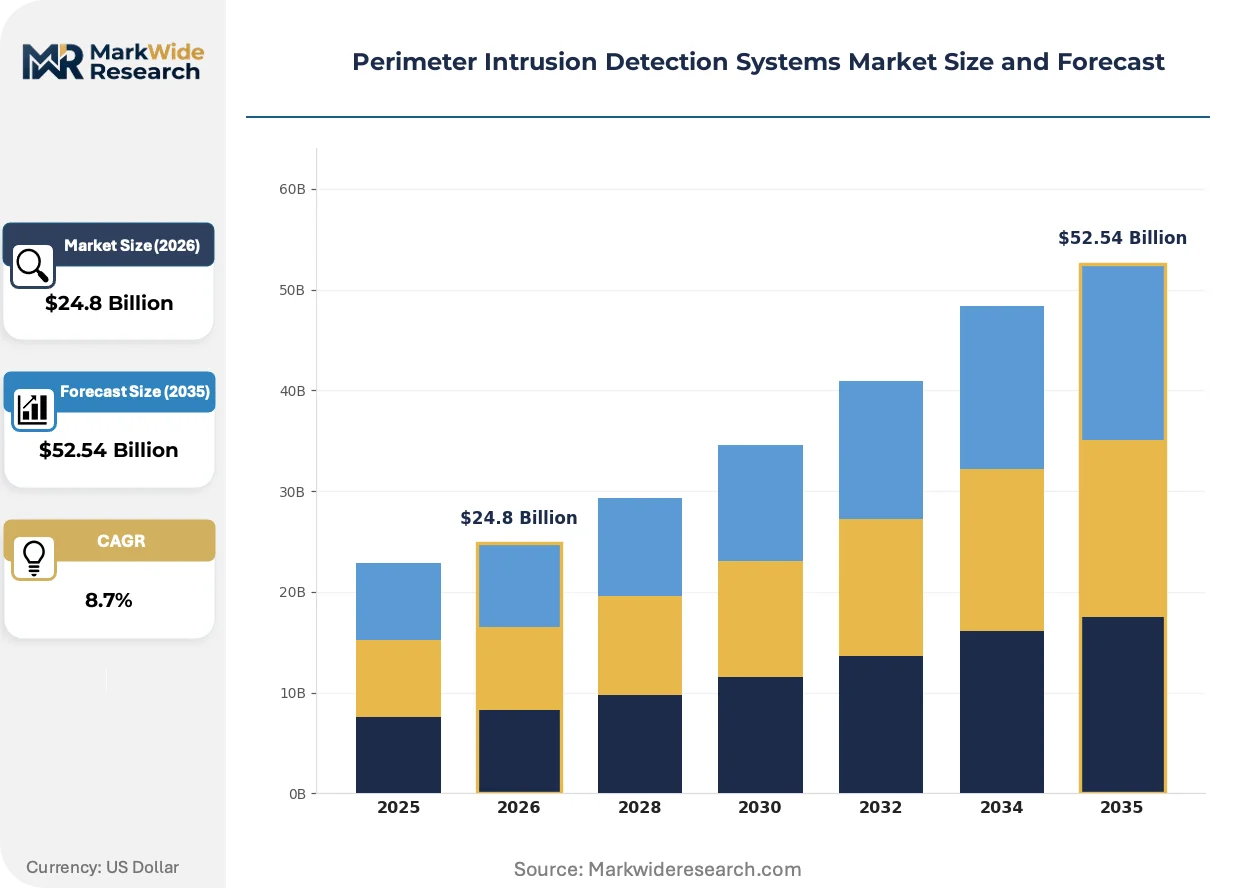
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $52.54 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
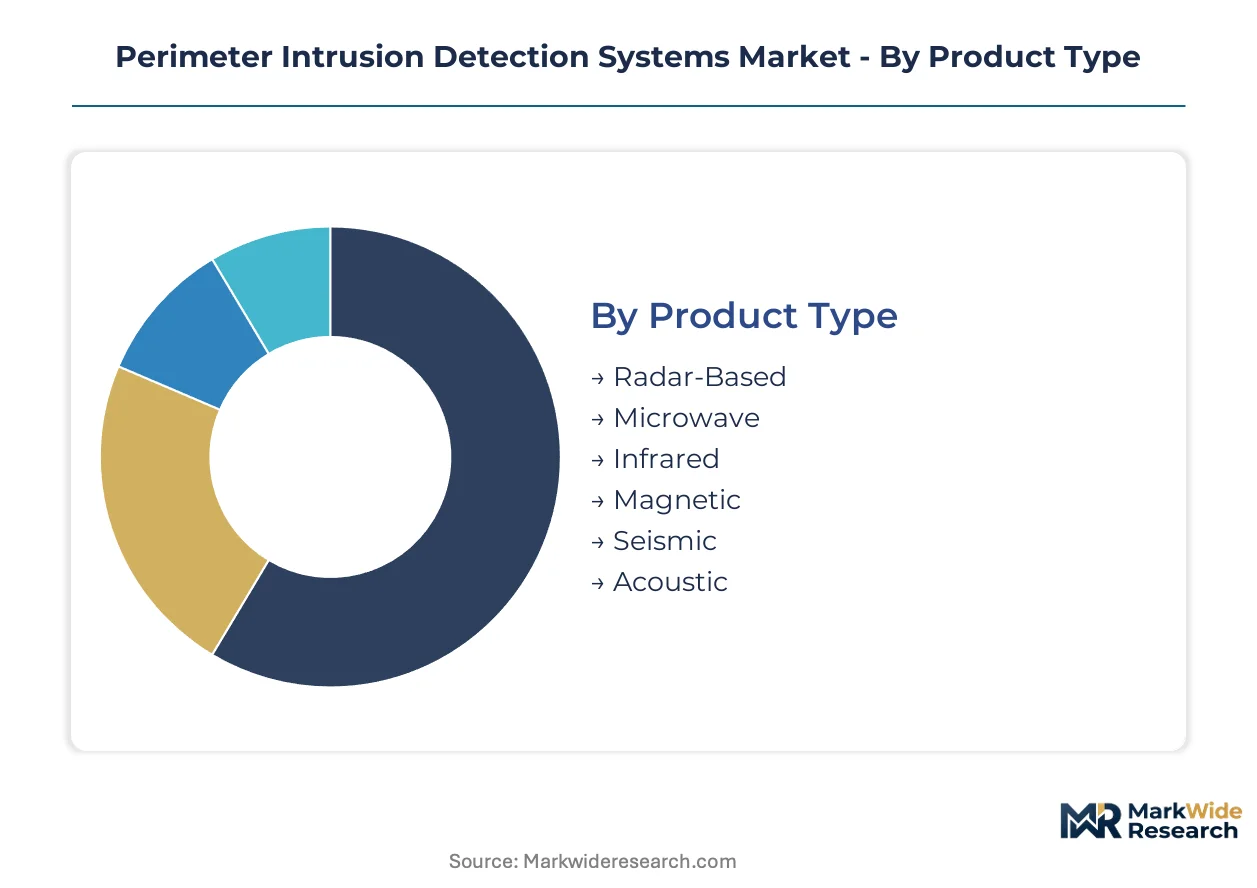
| Segmentation | Product Type: Radar-Based, Microwave, Infrared, Magnetic, Seismic, Acoustic Technology: Fiber Optic, Video Analytics, Thermal Imaging, Laser Sensors, Ultrasonic Detection, Vibration Sensors Application: Critical Infrastructure, Transportation Hubs, Correctional Facilities, Military Bases, Power Plants, Airports End User: Oil & Gas Facilities, Data Centers, Manufacturing Sites, Government Facilities, Utilities, Logistic Centers |
| Companies Covered | Senstar Corporation, Southwest Microwave, Honeywell International Inc., Johnson Controls, Advanced Perimeter Systems Limited, Schneider Electric, RBtec Perimeter Security Systems, Bosch Security Systems, Axis Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perimeter Intrusion Detection Systems Market Strategic Shifts & Innovations
The core evolution in perimeter security is the shift from passive detection to proactive threat assessment. This is enabled by data processing at the network edge and the fusion of sensor inputs, turning distributed hardware into a cohesive, intelligent security fabric.
Artificial intelligence-powered video analytics functions by interpreting video feeds to automatically identify and classify potential threats without human intervention. Critical infrastructure operators, including at airports and power generation facilities, are the primary adopters. This technology is digitizing threat assessment, automating the process of sifting through immense volumes of security data to prioritize genuine alerts for human response.
Implementation of the US Department of Homeland Security's CFATS program sets stringent physical protection standards for chemical facilities. The regulation forces covered sites to deploy, maintain, and test perimeter security systems capable of deterring, detecting, and delaying unauthorized access. High-risk chemical manufacturing and storage sites are most impacted, often needing to replace older systems with modern solutions that meet specific performance criteria.
A significant change in buying behavior is the move away from large, upfront capital outlays toward operational expenditure models. This trend disrupts the business of traditional system integrators by favoring vendors offering subscription-based software and managed monitoring services. The shift is most pronounced in commercial verticals with multiple locations, such as logistics firms and retail chains, that seek predictable costs and centralized management.
Perimeter Intrusion Detection Systems Market Segmentation
Understanding the distinct segments within the Perimeter Intrusion Detection Systems market is crucial for identifying specific demand patterns and technological preferences. This segmentation highlights where investment is currently flowing and where future growth opportunities are concentrated, enabling targeted strategic planning for vendors.
Product Type:
The product type segment illustrates the varying levels of technological maturity and application suitability across perimeter detection solutions.
- Radar-Based:These systems utilize radio waves to detect movement, precisely determining target range, speed, and direction across large areas. Demand concentrates in critical infrastructure protection, particularly at large-scale facilities like power plants, due to their long-range detection capabilities and resilience to environmental factors.
- Microwave:Microwave PIDS create an invisible electromagnetic field between transmitter and receiver, triggering an alarm when an intruder disturbs the field.
- Infrared:Infrared PIDS detect changes in heat signatures, utilizing passive infrared (PIR) or active infrared beams to identify intruders. Demand is significant in securing military bases and correctional facilities, as they offer reliable detection in diverse lighting conditions and are relatively cost-effective.
- Magnetic:Magnetic sensors detect disturbances in the earth's magnetic field caused by metallic objects, often used for fence or gate protection.
- Seismic:Seismic systems detect ground vibrations caused by footsteps or vehicles, providing covert detection for buried applications.
- Acoustic:Acoustic sensors identify sounds associated with intrusion attempts, such as fence climbing or digging, often complementing other sensor types.
Radar-Based systems handle the majority of throughput due to their extensive range; Infrared systems are the fastest mover on share due to their cost-effectiveness and versatility.
Technology:
This technology segment reflects the distinct application scopes and performance characteristics driving adoption in specialized security environments.
- Fiber Optic:Fiber optic sensors detect disturbances along a buried cable or fence line, providing continuous perimeter integrity monitoring for long distances.
- Video Analytics:AI-powered algorithms process video feeds to automatically identify and classify potential threats, distinguishing human activity from environmental factors. Demand concentrates in data centers and transportation hubs in the United States, driven by the need for automated threat assessment and reduced false alarms.
- Thermal Imaging:These cameras detect heat signatures, enabling detection in complete darkness, fog, or smoke, making intruders visible regardless of camouflage. Demand is high in military bases and power generation facilities, where all-weather, 24/7 surveillance is critical for early warning capabilities.
- Laser Sensors:Laser-based systems create an invisible tripwire, providing precise detection for specific zones or access points.
- Ultrasonic Detection:Ultrasonic sensors emit sound waves and detect changes in their reflection patterns, suitable for indoor or confined outdoor spaces.
- Vibration Sensors:These sensors attach to fences or walls, detecting vibrations caused by climbing, cutting, or impact, providing localized intrusion alerts.
Video Analytics technology is currently seeing the highest investment; Thermal Imaging is expanding most quickly in adoption.
Application:
The application segment highlights how regulatory influence and asset value dictate the deployment of perimeter intrusion detection systems across various sectors.
- Critical Infrastructure:This application encompasses essential services like energy, water, and communications, requiring robust multi-layered perimeter security solutions. Demand is compelled by regulatory frameworks like the EU's Critical Entities Resilience (CER) Directive, mandating enhanced physical protection levels for operators.
- Transportation Hubs:Airports, seaports, and railway stations utilize PIDS to secure vast perimeters, manage access, and prevent disruptions to operations.
- Correctional Facilities:These facilities deploy PIDS to prevent escapes and unauthorized entry, maintaining secure environments through continuous surveillance and early detection.
- Military Bases:These highly sensitive sites require advanced PIDS to detect and deter unauthorized access, protecting personnel, classified information, and high-value assets. Demand is consistently strong due to ongoing geopolitical threats and the need for comprehensive security postures.
- Power Plants:Power generation facilities require PIDS for securing critical energy assets against sabotage and unauthorized access, often including radar and thermal systems.
- Airports:Airports use PIDS to protect runways, hangars, and restricted areas from intrusions, complying with strict aviation security regulations.
Critical Infrastructure applications account for the largest share of deployments; Power Plants are witnessing the steepest expansion trajectory.
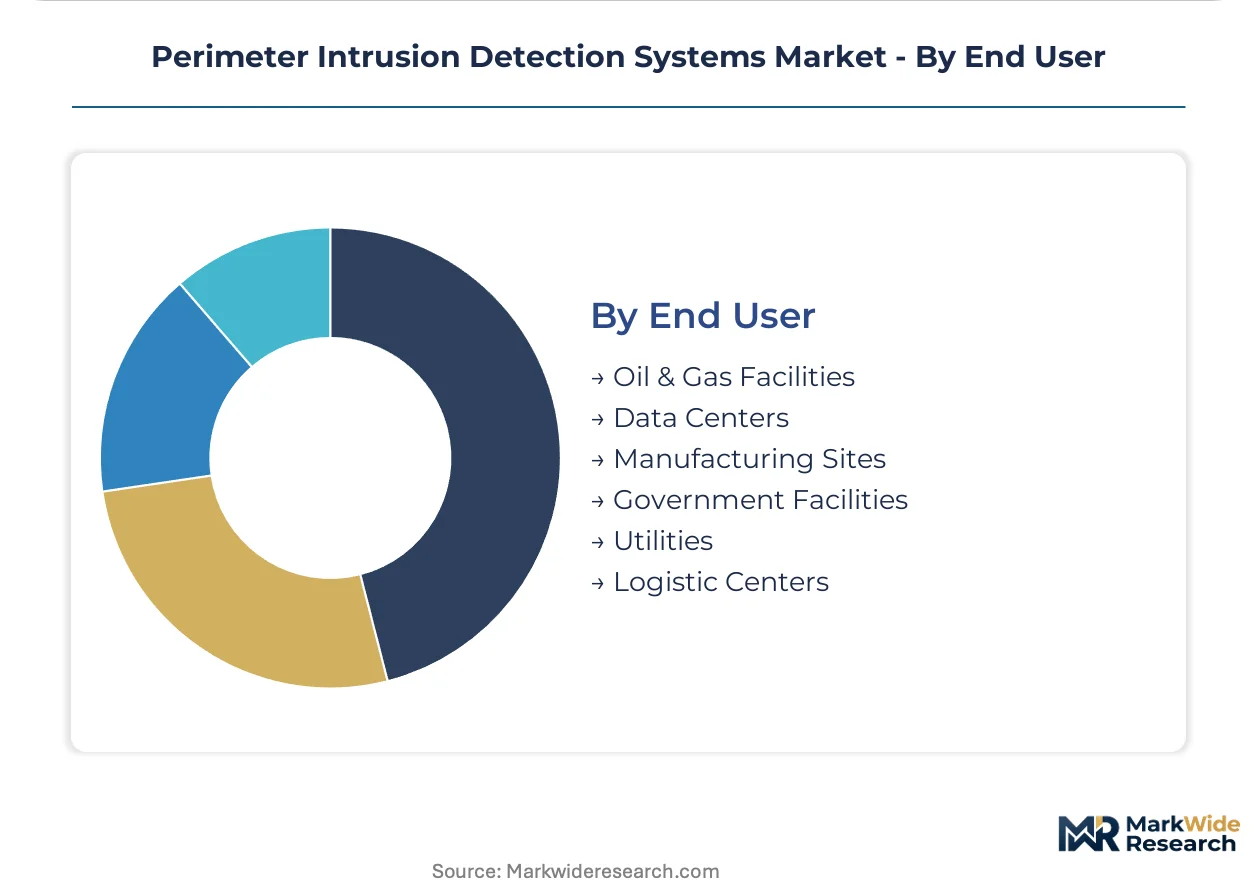
End User:
This end-user segment reflects the diverse asset values and operational requirements that shape the demand for perimeter security solutions.
- Oil & Gas Facilities:These sites require PIDS to secure remote and expansive perimeters, protecting valuable resources and preventing environmental incidents.
- Data Centers:These facilities house sensitive information and IT infrastructure, demanding sophisticated PIDS to prevent physical breaches and protect digital assets. Demand for advanced perimeter protection is significant in new data center construction across the United States.
- Manufacturing Sites:PIDS are deployed in manufacturing facilities to protect valuable equipment, intellectual property, and finished goods from theft or sabotage.
- Government Facilities:This segment includes various administrative, research, and defense installations requiring stringent security measures to protect national interests and confidential operations. Demand is concentrated in securing facilities across India and Brazil, driven by national security mandates.
- Utilities:Utility providers use PIDS to secure substations, water treatment plants, and other distributed assets against vandalism and unauthorized access.
- Logistic Centers:These centers utilize PIDS to protect large warehouses and distribution hubs, safeguarding inventory and ensuring supply chain integrity.
Data Centers represent the largest revenue stream for specialized PIDS; Logistic Centers are gaining share fastest as security priorities evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for perimeter intrusion detection systems varies significantly, with critical infrastructure operators prioritizing advanced, high-cost solutions, while commercial entities often seek more budget-friendly options. This elasticity contrast influences regional investment patterns and technology adoption rates. Regulatory mandates and asset value drive spending in specific geographies.
United States
New data center construction drives significant demand for advanced PIDS, particularly video analytics and thermal imaging. The US Department of Homeland Security's CFATS program mandates stringent physical protection for chemical facilities. Silicon Valley and Northern Virginia concentrate significant PIDS deployments, securing high-value digital assets.
India
Government facilities and transportation hubs in India require robust perimeter security solutions to protect national assets. The Ministry of Home Affairs (MHA) guidelines for critical infrastructure influence system specifications. Delhi-NCR and Mumbai are key centers for PIDS integration within public sector projects.
Brazil
Securing energy and transportation assets remains a priority for government-led infrastructure projects across Brazil. ANVISA regulations for certain facilities necessitate specific security protocols. São Paulo and Rio de Janeiro represent major hubs for PIDS deployment in urban critical infrastructure.
Germany
Critical infrastructure operators in Germany, particularly energy grids and manufacturing sites, demand resilient PIDS solutions. The EU's Critical Entities Resilience (CER) Directive compels enhanced physical security measures. The Rhine-Ruhr region and Bavaria exhibit high PIDS adoption in industrial and automotive sectors.
United Kingdom
Transportation hubs and government facilities in the United Kingdom require sophisticated perimeter defense systems. The Centre for the Protection of National Infrastructure (CPNI) provides guidance for physical security. London and the Southeast region are focal points for PIDS investments in high-security environments.
Perimeter Intrusion Detection Systems Market Key Industry Players
Integrated security solution providers and specialized sensor technology manufacturers split the market for perimeter intrusion detection systems. The competitive landscape shows a blend of established industrial conglomerates and agile technology innovators. Strategic archetypes include comprehensive system integrators offering end-to-end solutions and niche players focusing on advanced sensor development. Geographic expansion and strategic partnerships remain dominant competitive moves.
Within the specialized sensor technology segment, Senstar Corporation exemplifies a focus on diverse detection technologies, ranging from fiber optic to microwave solutions tailored for specific site requirements. Honeywell International Inc., a New York-based corporation, represents the larger industrial conglomerate archetype, leveraging its extensive portfolio in building automation to offer integrated security offerings that span multiple domains. Bosch Security Systems GmbH, a German entity, also sits within this tier, providing comprehensive security and surveillance solutions that address a broad spectrum of enterprise-level needs.
| Leading Market Players |
|---|
| Senstar Corporation |
| Southwest Microwave |
| Honeywell International Inc. |
| Johnson Controls |
| Advanced Perimeter Systems Limited |
| Schneider Electric |
| RBtec Perimeter Security Systems |
| Bosch Security Systems |
| Axis Communications |
| Others |
Cost & Logistics Intelligence
Under-utilization of manufacturing facilities in established European markets drives intense competition among PIDS suppliers. This capacity surplus influences both component procurement strategies and end-product pricing for sophisticated security systems.
Pricing Analysis
After-sales revenue from Software-as-a-Service (SaaS) and managed monitoring services drives significant lifetime value in the PIDS market. The dominant pricing structure increasingly favors subscription-based models over large upfront capital outlays. Price differentiation stems from the customization level required for integrated solutions and the brand premium associated with proven reliability. Critical infrastructure operators prioritize performance and compliance, exhibiting lower price sensitivity compared to commercial verticals seeking predictable operational costs.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities often characterize relationships between PIDS manufacturers and their component suppliers. Geographic supply concentration for microprocessors and specialized optics lies predominantly in China, South Korea, and Germany. Single-source vulnerability for certain advanced sensor components presents a structural risk. Distribution runs through a network of specialized system integrators and direct sales channels to large critical infrastructure end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Perimeter Intrusion Detection Systems market is experiencing a cyclical recovery, primarily driven by renewed global infrastructure spending on new data centers and transportation hubs. This upswing presents strategic opportunities for various market participants.
For Market Incumbents: Entrench existing market positions by deepening AI-powered video analytics integration across their product portfolios. Expanding Software-as-a-Service and managed monitoring services offers a crucial defensive move against agile technology innovators. Strengthen channel control through strategic partnerships with local system integrators to counter rising competition. This approach mitigates margin pressure from commoditized sensor sales. For New Entrants and Emerging Players: Establish a beachhead in the rapidly growing counter-drone integration segment by developing specialized UAS detection and tracking capabilities. Target underpenetrated emerging market infrastructure projects, such as those in Brazil, with cost-effective, scalable solutions. Focus on a go-to-market strategy emphasizing seamless integration with existing security platforms and a lower total cost of ownership. This strategy avoids direct competition with established players in mature segments. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-driven essential services protection play because of continuous mandates for physical security upgrades in critical infrastructure. Acquisition targets should focus on niche software developers specializing in AI-powered video analytics or counter-drone integration technologies. A key signal to watch is the widespread adoption of unified security platforms across diverse critical infrastructure environments. This indicates market consolidation and enhanced operational efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Launch AI-Powered Radar Systems | Enhances detection accuracy and reduces false alarms for critical infrastructure operators. |
| Integrate Unified Security Platforms | Streamlines data from diverse sensors, improving situational awareness for security teams. |
| Form Cybersecurity Partnerships | Addresses the growing vulnerability of networked PIDS to cyber threats for end-users. |
| Acquire Counter-Drone Technology Firm | Expands solution portfolio to detect and mitigate unauthorized unmanned aerial systems. |
| Expand into Emerging Market Infrastructure | Captures greenfield deployment opportunities driven by government projects in Brazil. |
Research Approach
A spread of perspectives from security managers, system integrators, sensor manufacturers, and regulatory compliance officers converged on the working assumptions for this study. Primary interviews with these industry stakeholders were rigorously validated against extensive secondary research. Secondary sources included government security guidelines, industry association reports, patent databases, and relevant company financial filings. This approach ensured a robust bottom-up and top-down triangulation of market data.
Demand-supply balance across the analysis window formed the core of the forecast framework, integrating both qualitative and quantitative insights. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory frameworks. Compound annual growth rates were derived from historical data and projected growth drivers. Key industry-specific forecast inputs included critical infrastructure investment levels and evolving regulatory compliance deadlines.
Stress conditions across geopolitical stability and rapid technological disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding critical infrastructure investment and regulatory enforcement. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Italy Access Control Market
Access Control Systems
Car Security System Market
Access Control Systems
Electronic Cylinder Lock Credentials Market
Access Control Systems
Automatic Gate and Door Opening System Market
Access Control Systems
Latin America Proximity Access Control Market
Access Control Systems
Europe Access Control Hardware Market
Access Control Systems
Germany Access Control Market
Access Control Systems
Turnstiles Access Control Systems Market
Access Control Systems
Europe Pin-Based Access Control Market
Access Control Systems
Role-Based Access Control (RBAC) Market
Access Control Systems
Asia Pacific Access Control Software Market
Access Control Systems
Europe Home Security System Market
Access Control Systems
Europe Proximity Access Control Market
Access Control Systems
Latin America Pin-Based Access Control Market
Access Control Systems
India Access Control Hardware Market
Access Control Systems
Mechanical Locks Market