
 Airport Baggage Screening Systems Market | 2026-2036
Airport Baggage Screening Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Baggage Screening Systems Market Analysis
Leasing and performance-based service contracts are reshaping how airports acquire baggage screening infrastructure, lowering upfront capital barriers for mid-tier facilities. Smiths Detection leverages its integrated service model to sustain long-term revenue streams across European hub airports. Leidos Holdings anchors its position through deep government relationships and classified technology expertise. OSI Systems competes aggressively on manufacturing scale, while Nuctech Company Limited dominates procurement pipelines across Asia-Pacific and African markets with cost-optimized CT platforms.
Airport baggage screening systems comprise integrated detection architectures that combine multi-view X-ray arrays, computed tomography reconstruction engines, and automated explosives trace sensors to inspect hold and carry-on luggage for prohibited items and threat materials. These systems process bags at throughput rates exceeding 1,800 items per hour while maintaining false-alarm thresholds below specified operational limits. CT technology leads capital allocation as airports replace legacy two-dimensional X-ray infrastructure with three-dimensional volumetric scanning that reduces manual bag rechecks. Conveyor systems occupy the largest installed base, though automated machines represent the fastest-growing product category as labor costs rise and checkpoint staffing shortages persist across major aviation markets.
TSA in the United States mandates computed tomography deployment under its checkpoint property screening program, while EASA enforces equivalent performance standards across European Union member states. China's CAAC aligns domestic airport security procurement with GB standards and national dual carbon goals, influencing equipment efficiency requirements. Stakeholders must monitor how regulatory divergence between FAA-certification pathways and EU-type approval processes affects product development timelines and market access strategies.
Market Dynamics
Computed tomography screening equipment is displacing legacy two-dimensional X-ray infrastructure across major aviation hubs, driven by TSA mandates and EASA performance standards that penalize manual bag recheck rates. This technology transition concentrates capital deployment among airports with sufficient passenger volume to justify throughput gains.
Growth Catalysts
- Regulatory Mandates:TSA's checkpoint property screening program and EASA equivalent standards compel airports to replace aging detection systems. These frameworks establish minimum CT deployment timelines.
- Throughput Pressure:Hub airports processing over 1,800 bags per hour require automated explosives trace integration to maintain operational flow during peak scheduling windows.
- Labor Cost Escalation:Checkpoint staffing shortages across United States and European Union markets accelerate automated screening machine procurement to reduce manual inspection headcount.
Market Restraints
- Capital Intensity:CT system installation requires extensive conveyor reconfiguration and civil works, extending payback periods beyond typical airport capital planning cycles.
- Certification Divergence:FAA certification pathways and EU-type approval processes impose redundant testing protocols, lengthening product development timelines for equipment manufacturers.
- Supply Concentration:Detector array and reconstruction engine sourcing concentrates among specialized component suppliers, creating vulnerability to semiconductor fabrication bottlenecks.
Strategic Opportunities
- Mid-Tier Airport Modernization:Leasing and performance-based service contracts lower upfront barriers for secondary hubs in Germany and China seeking CT compliance without balance-sheet strain.
- Integration of AI-Assisted Threat Recognition:Machine learning algorithms layered atop volumetric scanning data reduce false-alarm rates and enable remote screening operations.
- African Hub Development:Greenfield airport construction across Ethiopia, Kenya, and Nigeria presents first-mover advantage for CT-native infrastructure without legacy system write-offs.
Industry Challenges
- Legacy System Interoperability:Retrofitting CT equipment into existing baggage handling architectures requires custom mechanical interfaces and control software adaptation.
- Technical Talent Scarcity:Maintenance of computed tomography reconstruction engines demands specialized training in radiographic physics and automated sensor calibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Baggage Screening Systems Market |
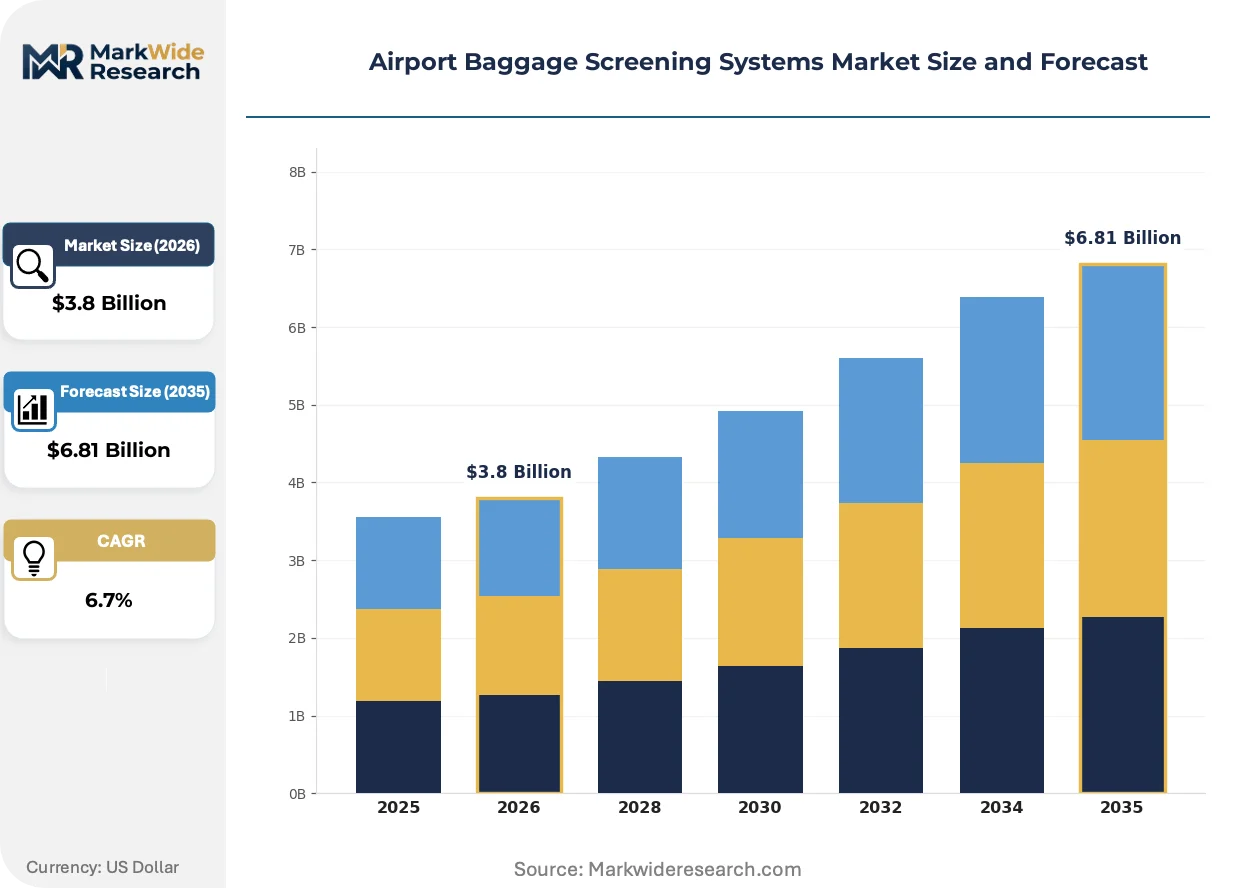
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: X-Ray, CT, Millimeter Wave, Explosives Detection End User: Airports, Airlines, Security Agencies, Customs Authorities Product Type: Conveyor Systems, Standalone Units, Portable Systems, Automated Machines Installation Type: Fixed, Mobile, Integrated Systems, Modular Solutions |
| Companies Covered | Smiths Detection, Leidos Holdings, OSI Systems, Thales Group, L3Harris Technologies, Analogic Corporation, Rapiscan Systems, Nuctech Company Limited, Smiths Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Baggage Screening Systems Market Emerging Trajectories
Volumetric scanning architectures are compressing operational footprints while expanding detection capability, forcing airports to reconsider checkpoint spatial design. Equipment manufacturers now compete on software-defined threat libraries rather than hardware specifications alone.
Dual-energy X-ray arrays paired with computed tomography reconstruction engines is migrating from hold baggage inspection lines into carry-on checkpoint lanes. Major United States hub airports under TSA deployment schedules are adopting these hybrid configurations to reduce passenger queue times. The technology is migrating from centralized screening rooms toward distributed checkpoint integration, enabling parallel processing architectures that compress terminal congestion.
EASA enforcement of equivalent performance standards to TSA CT mandates is harmonizing equipment specifications across European Union member states. This regulatory convergence eliminates manufacturer need for market-specific product variants. Airlines operating transatlantic routes now face unified compliance thresholds, simplifying fleet-wide baggage handling standardization.
Service contract unbundling is fragmenting how mid-tier airports acquire screening infrastructure, separating hardware ownership from maintenance and software update obligations. Third-party facility management firms are capturing procurement influence previously held by direct airport authority capital committees. This shift is most visible across Chinese provincial airports where CAAC efficiency requirements intersect with constrained municipal financing capacity.
Airport Baggage Screening Systems Market Segmentation
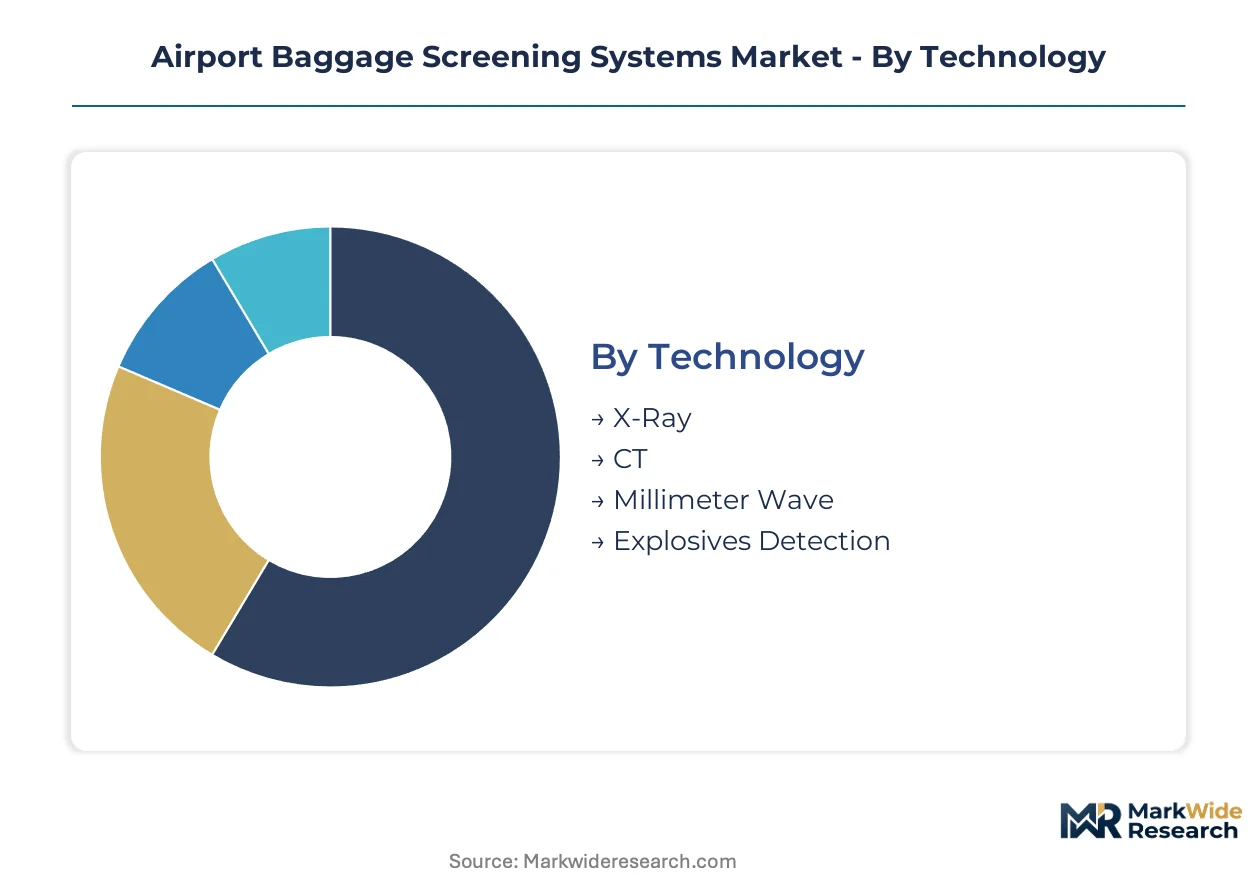
Technology heterogeneity across baggage screening architectures creates distinct procurement patterns. Each segment category reflects divergent capital intensity, regulatory compliance burdens, and operational throughput requirements.
Technology:
Mature two-dimensional imaging platforms coexist with emerging volumetric reconstruction systems across installed bases.
- CT:Three-dimensional volumetric scanning reconstructs bag contents from multiple angular projections, eliminating perspective overlap that obscures threats in planar imaging. Demand concentrates at United States hub airports under TSA checkpoint property screening mandates, where throughput gains above 1,800 bags per hour justify premium capital outlay.
- X-Ray:Dual-energy linear detector arrays discriminate materials by atomic number through differential absorption at high and low keV spectra. Secondary hub modernization in Germany and China sustains replacement demand as airports phase out single-view legacy units ahead of EASA performance standard deadlines.
- Millimeter Wave:Non-ionizing active imaging penetrates clothing and soft materials for personnel screening adjunct applications. Integration into hybrid checkpoint lanes expands at major aviation facilities seeking consolidated threat detection footprints.
- Explosives Detection:Automated trace particle analysis using ion mobility spectrometry or chemiluminescence detects vapor and particulate residue from energetic materials. Deployment concentrates in hold baggage screening lines where regulatory mandates require automated explosive confirmation.
CT retains volume leadership; explosives detection holds the steepest expansion curve.
End User:
Procurement authority fragmentation shapes contracting structures and technology specification authority.
- Airports:Hub operators with annual passenger volumes exceeding 50 million direct capital allocation toward integrated CT-native infrastructure. Chinese provincial airports under CAAC efficiency requirements increasingly favor performance-based service contracts over direct equipment purchase.
- Airlines:Network carriers operating transatlantic routes standardize baggage handling protocols across hub portfolios to simplify crew training and maintenance logistics. Fleet-wide screening consistency reduces operational complexity at outstations.
- Security Agencies:National aviation security directorates specify certification requirements that equipment vendors must satisfy for market access. FAA certification pathways and EU-type approval processes impose distinct testing protocols.
- Customs Authorities:Revenue protection and contraband interdiction missions drive demand for high-resolution imaging with automated narcotics detection algorithms. Integration with existing customs IT infrastructure determines procurement decisions.
Airports dominate capital deployment; security agencies control specification authority.
Product Type:
Physical configuration options span centralized processing architectures to distributed checkpoint integration.
- Conveyor Systems:Continuous belt mechanisms with integrated detection arrays process high-volume baggage streams through centralized screening rooms. Largest installed base reflects decades of hold baggage infrastructure deployment.
- Automated Machines:Self-contained screening units with robotic bag handling reduce manual inspection headcount. Fastest-growing category responds to checkpoint staffing shortages across United States and European Union markets.
- Standalone Units:Discrete screening stations for secondary inspection or small-scale operations. Deployment concentrates at general aviation terminals and remote airport facilities.
- Portable Systems:Battery-powered or rapidly deployable screening equipment for temporary checkpoints or emergency response. Demand fluctuates with major event security requirements and infrastructure construction phases.
Conveyor systems anchor installed capacity; automated machines climb the fastest.
Installation Type:
Structural integration depth determines civil works requirements and operational flexibility tradeoffs.
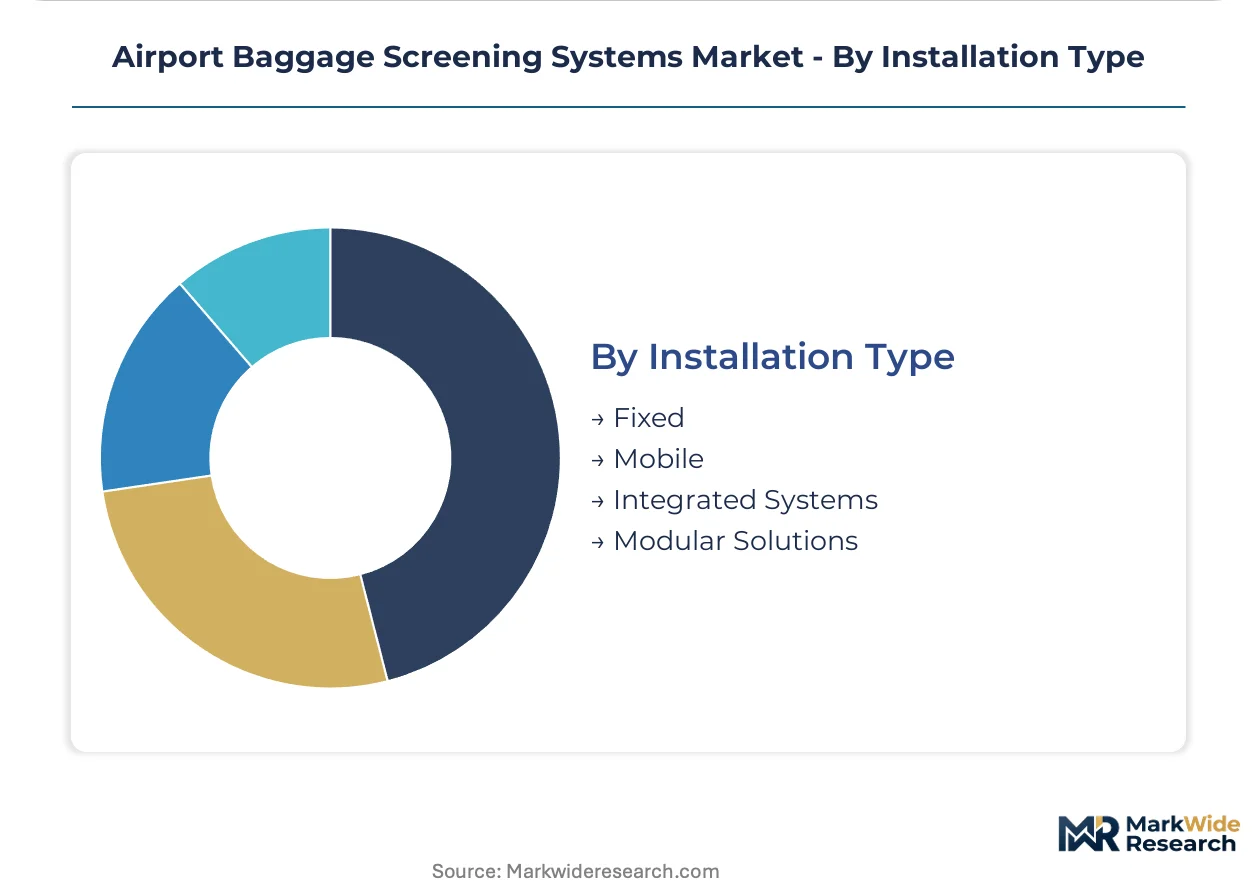
- Fixed:Permanent concrete foundations with embedded conveyor infrastructure support highest-throughput operations. Hub airports processing over 1,800 bags per hour standardize on fixed CT installations.
- Integrated Systems:Screening modules designed for seamless incorporation with existing baggage handling system architectures. Retrofit demand concentrates where legacy two-dimensional X-ray infrastructure requires phased replacement.
- Mobile:Trailer-mounted or skid-based platforms enable rapid repositioning across terminal zones or temporary facilities. African greenfield airport construction in Ethiopia and Kenya favors mobile units during phased infrastructure rollout.
- Modular Solutions:Prefabricated screening cells with standardized mechanical and electrical interfaces. Chinese provincial airports leverage modular procurement to match capacity expansion with passenger traffic growth.
Fixed installations retain revenue concentration; modular solutions gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA checkpoint property screening mandates and EASA performance standards are redirecting capital toward CT-native infrastructure across major aviation hubs. TSA procurement schedules in the United States and CAAC efficiency requirements in China are compressing replacement timelines for legacy two-dimensional X-ray systems.
United States
TSA mandates under the checkpoint property screening program are driving hub airports toward volumetric scanning architectures. FAA certification pathways establish testing protocols that equipment vendors must satisfy for domestic market access. Atlanta Hartsfield-Jackson and Chicago O'Hare are consolidating procurement around integrated CT-conveyor configurations to maintain throughput above 1,800 bags per hour.
China
CAAC aligns domestic airport security procurement with GB standards and national dual carbon goals, influencing equipment efficiency specifications. The country's national aviation regulator enforces performance benchmarks that accelerate replacement of single-view legacy units. Provincial airports in Sichuan-Chongqing and Shandong Peninsula are adopting performance-based service contracts to circumvent municipal financing constraints.
Germany
EASA enforcement of equivalent performance standards to TSA mandates is harmonizing equipment specifications across European Union member states. The German national automotive and aviation regulator KBA influences certification requirements for integrated detection systems. Frankfurt and Munich hubs are deploying automated screening machines to reduce manual inspection headcount amid persistent checkpoint staffing shortages.
United Arab Emirates
Dubai Airports and Abu Dhabi Department of Transport are modernizing hub infrastructure ahead of projected passenger volume recovery. The country's national civil aviation authority specifies high-resolution imaging requirements for contraband interdiction missions. Dubai International Airport is consolidating procurement around modular screening cells to match capacity expansion with traffic growth trajectories.
India
Bureau of Indian Standards certification requirements and DGFT import regulations are shaping equipment sourcing patterns for greenfield airport development. The Airports Authority of India mandates automated explosives trace integration for hold baggage screening lines. Bangalore and Hyderabad international airports are deploying CT-native infrastructure without legacy system write-offs as passenger volumes exceed pre-pandemic thresholds.
Airport Baggage Screening Systems Market Vendor Landscape
Channel-controlling players compete with product-specialist players across divergent procurement pathways. The vendor base organizes around three tiers: integrated service providers sustaining long-term revenue streams through leasing arrangements, government-contracting specialists leveraging classified technology relationships, and manufacturing-scale competitors optimizing cost structures for price-sensitive markets. Strategic moves concentrate on performance-based service contract unbundling and AI-assisted threat recognition integration to differentiate software-defined offerings from hardware-centric portfolios.
Within the integrated service tier, Smiths Detection and Leidos Holdings exemplify divergent approaches to sustaining recurring revenue. Smiths Detection anchors European hub procurement through bundled maintenance and software update obligations, while Leidos Holdings occupies a position within United States federal contracting channels. At the manufacturing-scale end, OSI Systems and Nuctech Company Limited represent cost-optimized fabrication strategies targeting Asia-Pacific and African procurement pipelines.
| Leading Market Players |
|---|
| Smiths Detection |
| Leidos Holdings |
| OSI Systems |
| Thales Group |
| L3Harris Technologies |
| Analogic Corporation |
| Rapiscan Systems |
| Nuctech Company Limited |
| Smiths Group plc |
| Others |
Supply Flow & Price Mechanics
Tariff exposure between the United States and China on semiconductor components determines both pricing tier spreads and supply chain shape in the airport baggage screening systems market. Detector array sourcing from Taiwanese foundries and reconstruction engine fabrication in South Korea create cost differentiation between FAA-certified and non-certified equipment tiers.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FAA-certified CT systems commanding substantial premiums over EASA-equivalent units due to redundant testing protocols. Three-tier pricing structure across premium, standard, and economy levels reflects throughput capability, software bundle depth, and after-sales service obligations. Cost compression in the economy tier is intensifying because Chinese provincial airports favor performance-based contracts over capital purchases. Mid-tier facilities in Germany and secondary Chinese hubs exhibit highest price sensitivity, while United States hub operators under TSA mandates show lowest sensitivity due to federal funding access.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for detector array and reconstruction engine procurement. Manufacturing concentrates in China, South Korea, and Germany, with specialized semiconductor fabrication feeding from Taiwanese foundries. Component sourcing rests on scintillator crystals, photodiode arrays, and high-voltage X-ray tubes. Single-source vulnerability persists in advanced CT reconstruction algorithms held by limited vendors. Distribution runs through direct government contracting channels in the United States and system integrator networks across European Union markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The airport baggage screening systems market sits in early-cycle expansion as regulatory mandates force replacement of legacy X-ray infrastructure with CT-native architectures. TSA checkpoint property screening program deadlines and EASA equivalent standards create synchronized procurement waves across major aviation hubs.
For Market Incumbents: Harden software-defined service offerings against hardware commoditization by embedding AI-assisted threat recognition into recurring revenue streams. Deepen backward integration into detector array manufacturing to reduce exposure to Taiwanese semiconductor bottlenecks. Lock in long-term performance contracts at European hub airports before modular competitors fragment procurement authority.
For New Entrants and Emerging Players: African greenfield airport construction in Ethiopia, Kenya, and Nigeria represents the most penetrable entry point for CT-native infrastructure without legacy system interoperability burdens. Mid-tier Chinese provincial airports under municipal financing constraints offer leasing-model traction. Partner with third-party facility management firms to bypass direct airport authority capital committees.
For Investors and Strategic Acquirers: The market sits at a regulatory-mandate acceleration phase that favors integrated service providers with recurring revenue visibility. Acquisition targets should combine hardware manufacturing scale with software subscription capabilities. Watch TSA deployment schedule adherence at United States hub airports as the inflection indicator for capital allocation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
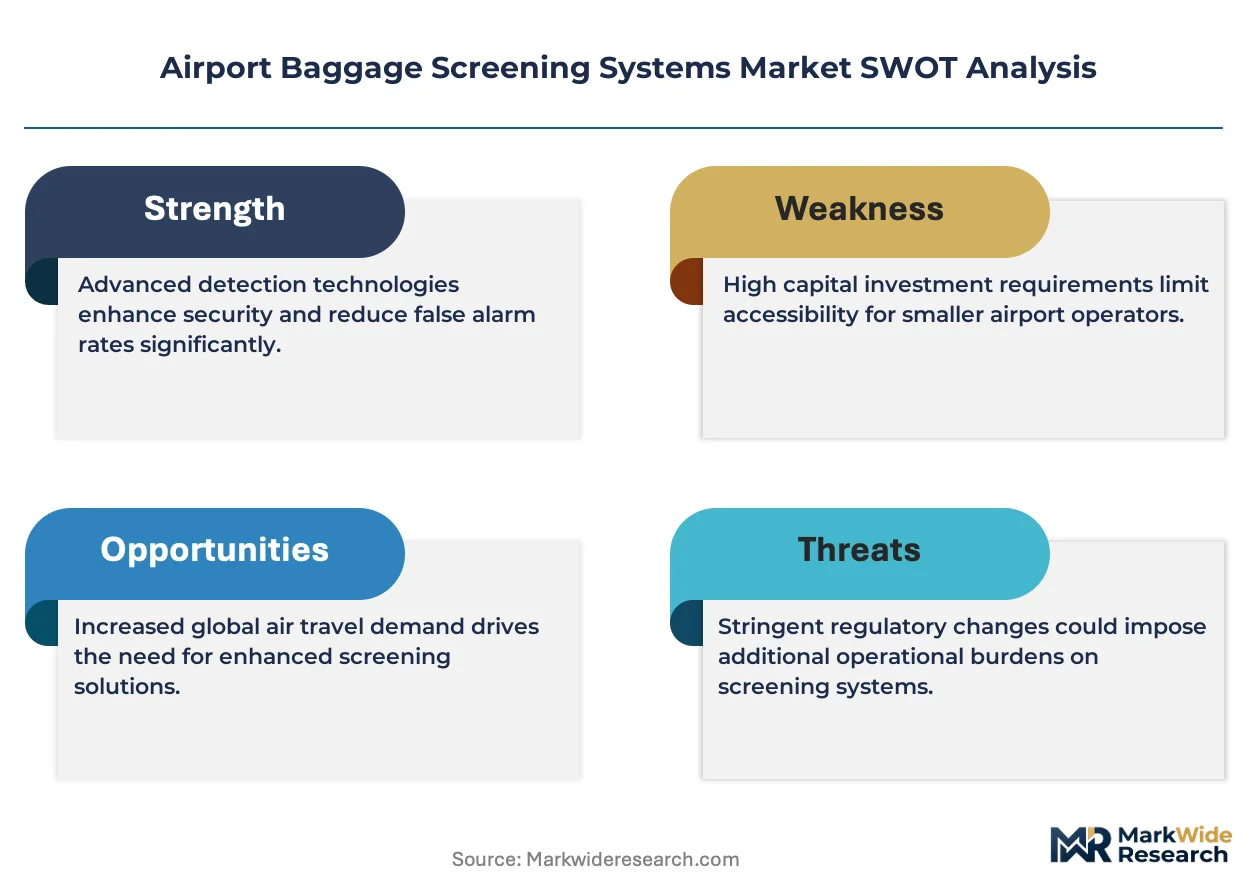
| AI-Assisted Threat Recognition Integration | Machine learning algorithms layered atop CT volumetric data reduce false-alarm rates below TSA operational thresholds. |
| Performance-Based Service Contract Unbundling | Separating hardware ownership from maintenance obligations lowers upfront barriers for Chinese provincial airports. |
| Modular Screening Cell Deployment | Prefabricated cells with standardized interfaces match Dubai International Airport capacity expansion to traffic growth. |
| Backward Integration into Detector Arrays | In-house scintillator crystal production reduces vulnerability to Taiwanese semiconductor fabrication bottlenecks. |
| African Greenfield First-Mover Positioning | CT-native infrastructure deployment in Ethiopia and Kenya avoids legacy system write-off complications. |
Methodological Framework
A standing panel of airport operations directors, TSA procurement officers, EASA certification specialists, and CT equipment maintenance engineers provided ongoing calibration across the study period. Primary interviews combined with secondary validation from FAA certification filings, EASA type-approval databases, CAAC efficiency standard bulletins, and customs trade data on detector array imports. Bottom-up triangulation against airport capital expenditure disclosures and top-down reconciliation with aviation security budget allocations anchored volume estimates.
Scenario bracketing around TSA deployment schedule adherence and EASA enforcement timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology tier, end-user procurement authority, product configuration, installation depth, and regional regulatory cluster. CAGRs derived from installed base replacement curves and greenfield airport construction pipelines, with throughput requirements above 1,800 bags per hour and checkpoint staffing shortage severity serving as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in aviation passenger traffic recovery, municipal bond financing costs, or semiconductor fabrication capacity would shift the trajectory. Forecasts reflect assumptions on regulatory mandate adherence and certification pathway harmonization progress. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Middle East and Africa Cargo Inspection Market
Security and Surveillance
Multi-Layer Security Market
Security and Surveillance
Global Security Assurance Market
Security and Surveillance
Prescriptive Security Market
Security and Surveillance
Stadium Security Market
Security and Surveillance
Narcotics Scanner Market
Security and Surveillance
Cargo and Vehicle Screening Market
Security and Surveillance
Residential Security Market
Security and Surveillance
Radar Security Market
Security and Surveillance
Explosive Detection Technology Market
Security and Surveillance
Intrusion Alarm System Market
Security and Surveillance
Home Security Sensors Market
Security and Surveillance
Underwater Security (Systems and Services) Market
Security and Surveillance
Swimming Pool Alarm Market
Security and Surveillance
Global Security Advisory Services Market
Security and Surveillance
Proactive Security Market