
 Locks Market | 2026-2036
Locks Market Size, Share, and Industry Trends Forecast 2026-2036
Locks Market Insights
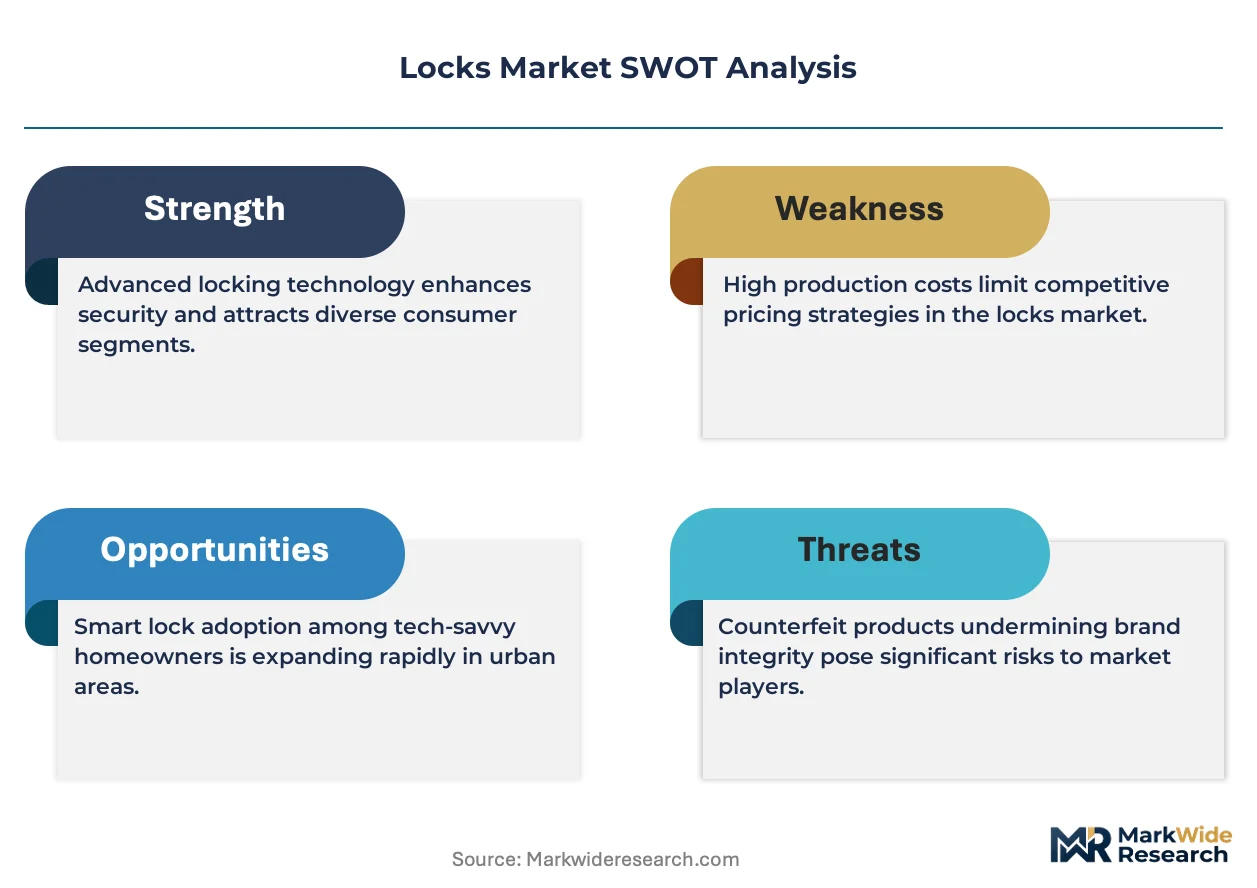
Multi-family residential development is rebalancing demand toward electronic access solutions over traditional mechanical hardware. ASSA ABLOY dominates integrated door opening solutions across Europe and North America through its broad brand portfolio. dormakaba specializes in hospitality and commercial access control, leveraging its SaaS-based platform to sustain recurring revenue streams. Allegion competes aggressively in the educational and healthcare verticals with code-compliant electrified hardware.
Locks are mechanical or electromechanical fastening devices that secure doors, containers, or entry points through bolt engagement with strike plates, typically manufactured from hardened steel or brass alloys with tolerance specifications measured in thousandths of an inch. Their primary purpose is to control physical access, protect assets, and maintain safety perimeters across residential, commercial, and institutional environments. Smart locks represent the fastest-expanding product category, with biometric and wireless technologies capturing margin pools as mechanical deadbolts mature into a replacement-driven commodity segment. Steel remains the dominant material by volume, though zinc alloys gain share in decorative residential hardware where finish quality drives purchasing decisions.
The U.S. Department of Housing and Urban Development influences multifamily specification through accessibility and fire safety mandates, while the EU Cybersecurity Act and ETSI EN 303 645 establish baseline requirements for connected locking devices sold in European markets. China's SAMR enforces GB standards for electronic lock electromagnetic compatibility and durability testing, creating compliance barriers for imported products. Stakeholders must monitor divergence between regional cybersecurity certification regimes and material content regulations as these determine market access velocity and product development prioritization.
Market Dynamics
Multi-family residential developers across the United States are systematically replacing mechanical deadbolts with keyless entry systems that integrate with building management platforms, compressing specification cycles and elevating software compatibility above hardware durability in procurement criteria.
Growth Catalysts
- EU Cybersecurity Act:Mandatory certification for connected locking devices under ETSI EN 303 645 creates compliance-driven replacement cycles among European property managers upgrading legacy electronic access systems.
- Biometric sensor miniaturization:Fingerprint and facial recognition modules achieving sub-$15 unit costs at volume are penetrating mid-market residential segments previously locked out of premium authentication features.
- China's tier-one city concentration:Beijing, Shanghai, and Shenzhen smart home ecosystems from Xiaomi and Huawei generate hardware pull-through as consumers demand seamless interoperability across door hardware and home automation hubs.
Market Restraints
- Semiconductor supply concentration:Microcontroller and Bluetooth SoC dependency on Taiwan and South Korea foundries exposes smart lock manufacturers to allocation volatility and extended lead times.
- Zinc alloy input cost volatility:Decorative residential hardware margins compress when London Metal Exchange zinc prices spike, forcing mid-tier brands toward steel alternatives that sacrifice finish quality.
- Electromagnetic interference limitations:GB standards testing in China rejects products failing radiated emissions thresholds, creating technical barriers for North American and European designs optimized to FCC or CE parameters.
Strategic Opportunities
- India's residential construction acceleration:Metro rail expansion corridors in Bengaluru, Hyderabad, and Pune are spawning gated community developments where electronic access represents first-mover differentiation for premium positioning.
- Short-term rental channel innovation:Airbnb and Vrbo property managers are adopting app-based credential provisioning that eliminates physical key exchange, creating a specialized distribution channel bypassing traditional locksmith and retail networks.
- IRA energy efficiency incentives:Connected locks qualifying as smart home energy management peripherals under U.S. federal tax credits accelerate retrofit adoption among cost-conscious homeowners.
Industry Challenges
- Cybersecurity firmware expertise scarcity:Hardware manufacturers struggle to recruit embedded systems engineers capable of implementing secure boot architectures and over-the-air update protocols resistant to penetration testing.
- Legacy mechanical infrastructure integration:Retrofit smart locks must accommodate non-standard door prep dimensions and mortise configurations prevalent in pre-1990s U.S. housing stock, fragmenting SKU requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Locks Market |
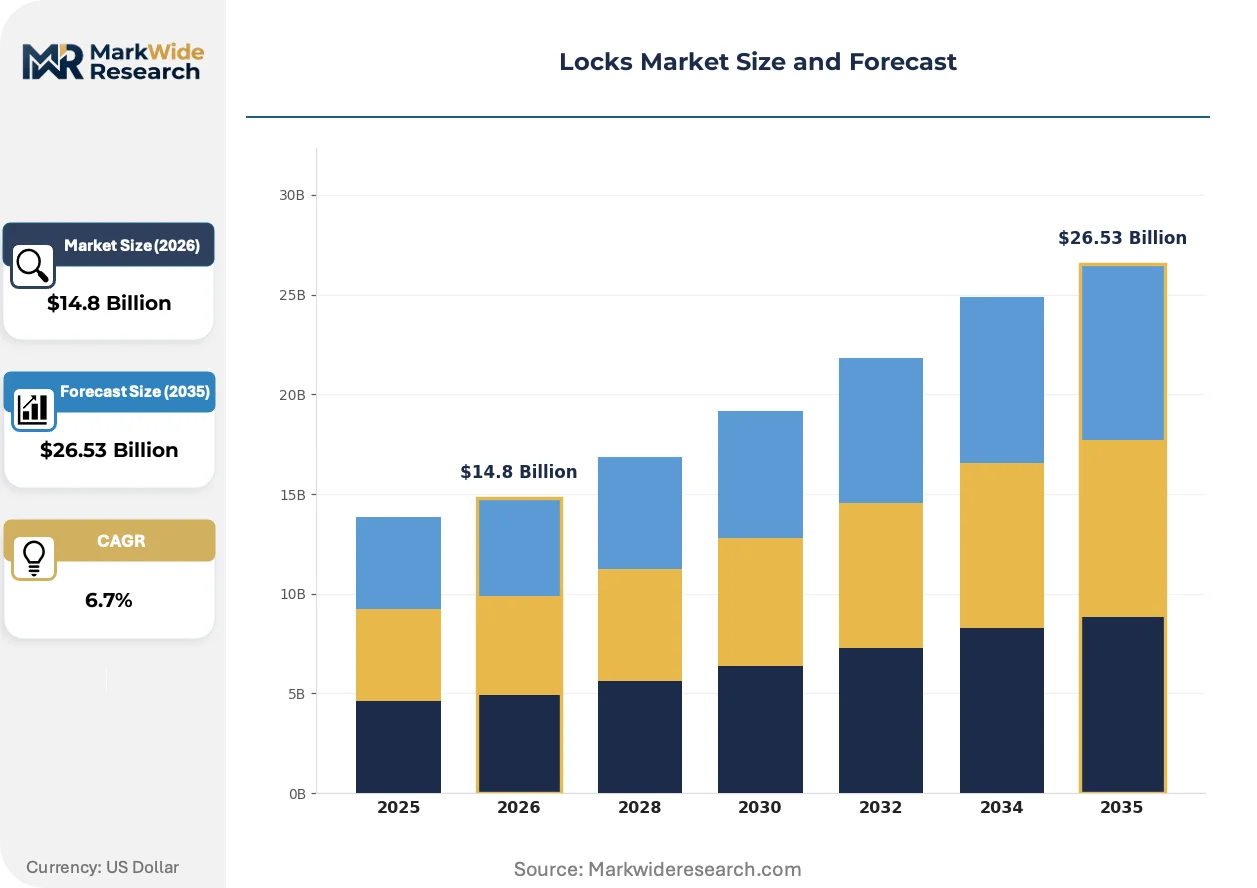
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deadbolts, Padlocks, Knob Locks, Smart Locks Material: Steel, Brass, Aluminum, Zinc End User: Residential, Commercial, Industrial, Institutional Technology: Mechanical, Electronic, Biometric, Wireless |
| Companies Covered | ASSA ABLOY, Allegion, dormakaba, Spectrum Brands, Schlage, Yale, Mul-T-Lock, Medeco, Baldwin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Locks Market Trends and Innovations
Wireless connectivity standards and biometric authentication are converging to redefine access control architecture, shifting competitive advantage from mechanical precision toward software ecosystem integration and data security posture.
Matter protocol implementation is electrifying interoperability across smart home platforms, enabling single-app control of locks alongside lighting, climate, and security systems. Homebuilders in Texas and Florida are specifying Matter-certified hardware as standard to reduce post-sale support burdens. This convergence is compressing market share for proprietary Zigbee and Z-Wave implementations that lock consumers into single-vendor ecosystems.
ETSI EN 303 645 cybersecurity certification is mandating vulnerability disclosure programs and secure update mechanisms for all connected locking devices sold in European Union member states. Hardware manufacturers must maintain dedicated security engineering functions to achieve and retain compliance. French and German property technology integrators now require certified products exclusively, filtering uncertified Asian imports from specification shortlists.
Credential unbundling from physical hardware is disrupting traditional locksmith distribution channels as property managers procure access-as-a-service subscriptions directly from SaaS platforms. Hospitality operators in Spain and Italy are abandoning front-desk key card systems for smartphone-based entry that eliminates plastic waste and front-desk staffing. This behavioral shift concentrates purchasing authority with IT procurement functions rather than facilities management.
Locks Market Segmentation
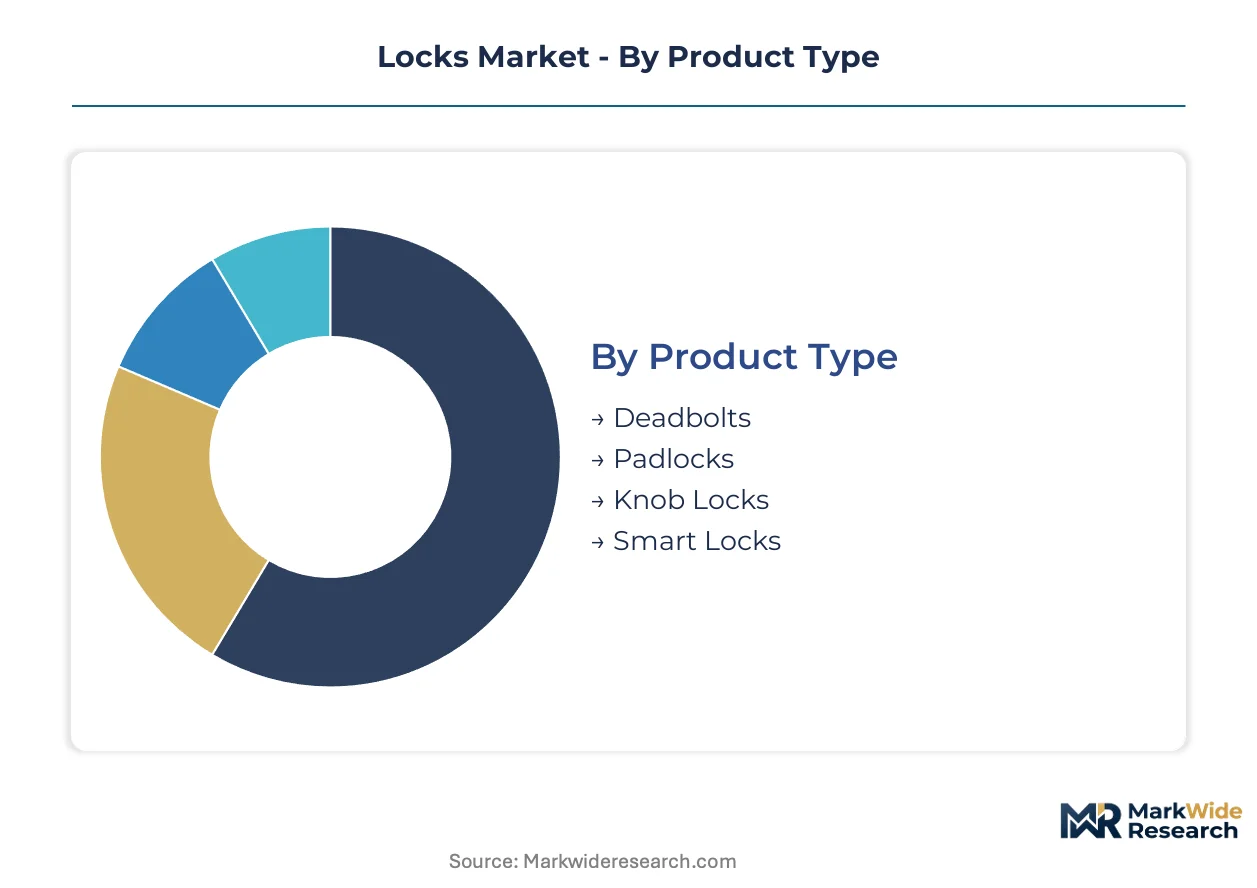
Segmentation in the locks market separates commodity replacement cycles from technology-driven upgrade demand. Product type and technology dimensions capture the divergence between mechanical hardware margins and connected device revenue pools. Material and end-user splits reveal where specification authority concentrates across construction, property management, and institutional procurement functions.
Product Type:
Volume concentrates in mechanical deadbolts and knob locks, while premium growth flows toward smart locks and specialized padlocks for logistics security.
- Deadbolts:Single-cylinder and double-cylinder mechanisms fabricated from hardened steel or brass dominate residential door security specifications. Demand concentrates in U.S. single-family replacement cycles and Indian residential new construction, constrained by price compression from private-label hardware brands.
- Smart Locks:Motorized deadbolts with Wi-Fi, Bluetooth, or Z-Wave connectivity integrate with home automation platforms and property management software. Adoption accelerates in U.S. multi-family developments and Chinese tier-one city smart home ecosystems, driven by keyless credential provisioning and remote access management.
- Padlocks:Portable locking devices for gates, storage units, and industrial equipment.
- Knob Locks:Cylindrical locksets combining latching and locking functions in residential interior doors.
Today's leader: Deadbolts. Tomorrow's challenger: Smart Locks.
Material:
Cost tier stratification separates commodity steel from decorative zinc and corrosion-resistant brass specifications.
- Steel:Hardened carbon and stainless grades provide tensile strength for high-security applications. Specifications dominate commercial and industrial segments where forced-entry resistance ratings determine compliance, though London Metal Exchange price volatility compresses margins for mid-tier manufacturers.
- Zinc:Die-cast zinc alloys enable intricate decorative finishes for residential hardware. Demand clusters in North American home improvement retail where aesthetic differentiation supports premium pricing, constrained by raw material cost spikes that force substitution toward steel alternatives.
- Brass:Copper-zinc alloys with superior corrosion resistance for coastal and institutional environments.
- Aluminum:Lightweight material for low-security applications and auxiliary hardware.
Steel commands current volume. Zinc captures margin where finish quality drives selection.
End User:
Procurement authority fragments across homeowner replacement, builder specification, and institutional compliance mandates.
- Residential:Single-family and multi-family housing drives replacement cycles and new construction specifications. Demand concentrates in U.S. sunbelt metro expansion and Chinese urbanization corridors, with smart lock penetration accelerating among tech-forward property managers.
- Commercial:Office, retail, and hospitality access control systems. Procurement prioritizes code compliance and SaaS integration.
- Industrial:Manufacturing facilities, warehouses, and logistics infrastructure requiring high-cycle durability.
- Institutional:Educational, healthcare, and government facilities with mandated accessibility and fire safety requirements.
Residential segments anchor volume. Commercial verticals expand fastest through electrification mandates.
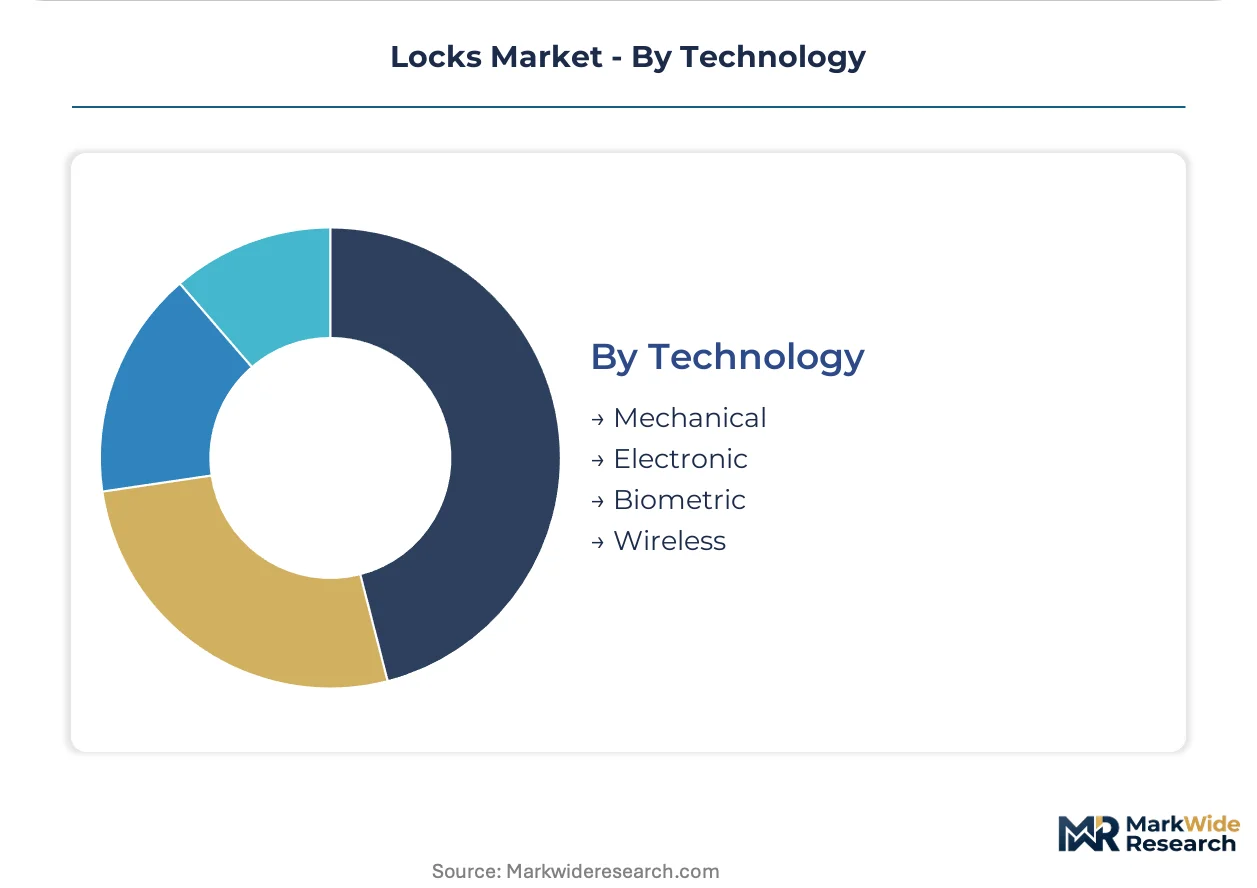
Technology:
Maturity gradients separate established mechanical architectures from emerging biometric and wireless protocols.
- Mechanical:Pin tumbler, wafer, and disc detainer mechanisms with no electrical components. Specifications persist in cost-sensitive residential replacement and developing market new construction, though growth stagnates as electronic alternatives capture specification share.
- Biometric:Fingerprint, facial recognition, and iris scanning modules for authentication without credentials. Sensor miniaturization below $15 unit costs penetrates mid-market residential segments, with Chinese manufacturers driving cost reduction through volume manufacturing.
- Electronic:Keypad, RFID, and magnetic stripe credential systems.
- Wireless:Connectivity protocols enabling remote management and platform integration.
Mechanical foundations persist. Biometric modules gain the steepest expansion trajectory through cost convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing migration toward jurisdictions with streamlined certification pathways is compressing time-to-market for connected locking devices. Compliance cost differentials between the EU Cybersecurity Act regime and alternative markets are redirecting assembly capacity toward Southeast Asian facilities serving re-export demand.
United States
Multi-family residential developers in Texas and Florida are specifying Matter-certified smart locks as standard equipment to reduce post-sale support burdens. The Department of Housing and Urban Development influences specification through accessibility and fire safety mandates. Austin and Miami metro corridors concentrate demand as sunbelt migration accelerates new construction permits.
Germany
Property technology integrators in Frankfurt and Berlin now require ETSI EN 303 645 certified products exclusively, filtering uncertified imports from specification shortlists. The EU Cybersecurity Act mandates vulnerability disclosure programs for all connected locking devices. Industrial clusters in Baden-Württemberg anchor precision manufacturing for high-security mechanical hardware serving institutional buyers.
China
Beijing, Shanghai, and Shenzhen smart home ecosystems from Xiaomi and Huawei generate hardware pull-through as consumers demand seamless interoperability. SAMR enforces GB standards for electronic lock electromagnetic compatibility and durability testing. Guangdong Province manufacturing bases supply cost-optimized biometric modules penetrating mid-market residential segments globally.
India
Metro rail expansion corridors in Bengaluru, Hyderabad, and Pune are spawning gated community developments where electronic access represents premium positioning. BIS certification requirements for imported electronic locks create compliance barriers favoring domestic assembly partnerships. Maharashtra and Karnataka states concentrate demand as IT sector employment drives housing formation.
Japan
Aging population demographics are accelerating demand for keyless entry systems in assisted living facilities and senior housing developments. METI guidelines on IoT device security influence procurement criteria for connected residential hardware. Osaka and Nagoya industrial zones maintain specialized capacity for precision mechanical lock components serving commercial security applications.
Locks Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated solution providers commanding specification authority in commercial verticals while OEM fabricators supply private-label volumes to retail channels. Market structure exhibits tiered concentration: three global groups dominate platform-level integration, mid-tier specialists capture vertical-specific niches, and regional fabricators compete on cost for replacement hardware. Strategic archetypes include ecosystem-integrated platform owners, compliance-forward European specialists, and scale-driven Asian OEMs. Competitive moves center on cybersecurity certification acquisition and SaaS platform partnerships that lock in recurring revenue streams.
Among the named participants, ASSA ABLOY anchors the integrated solutions tier through its broad brand portfolio spanning residential, commercial, and institutional applications. dormakaba occupies a position exemplifying the hospitality and commercial access specialist archetype, with its SaaS-based platform sustaining recurring revenue relationships. Allegion represents the code-compliant electrified hardware segment, competing aggressively in educational and healthcare verticals where specification authority concentrates with facilities compliance officers. These three entities collectively illustrate how competitive positioning diverges between platform breadth, vertical depth, and regulatory-forward product development.
| Leading Market Players |
|---|
| ASSA ABLOY |
| Allegion |
| dormakaba |
| Spectrum Brands |
| Schlage |
| Yale |
| Mul-T-Lock |
| Medeco |
| Baldwin |
| Others |
Pricing and Supply Chain Analysis
Zinc alloy input costs cascade through three pricing tiers as London Metal Exchange volatility forces mid-tier brands toward steel substitution, compressing finish-quality premiums while hardened steel specifications anchor commercial contract pricing. Semiconductor allocation constraints from Taiwan and South Korea foundries amplify smart lock lead-time premiums, concentrating margin capture with vertically integrated OEMs that maintain captive microcontroller supply.
Pricing Analysis
Distributor margin layers separate premium biometric-enabled hardware from economy mechanical replacements, with three-tier pricing structure across premium, standard, and economy levels driven by certification grade and volume scale. Pricing pressure stems from zinc cost spikes that force aesthetic substitution toward lower-margin steel alternatives. Residential home improvement retail channels exhibit highest price sensitivity, while institutional procurement prioritizes forced-entry resistance ratings over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale builder demand for multi-family developments, while locksmith networks and home improvement retail distribute replacement volumes to residential end users. Manufacturing concentrates in Guangdong Province, Baden-Württemberg, and Texas industrial corridors. Raw material dependencies include hardened steel billet, die-cast zinc alloy, and Bluetooth SoC modules. Single-source vulnerability in Taiwan semiconductor foundries exposes smart lock assemblers to allocation volatility. Distribution runs through property technology integrators in commercial verticals and e-commerce platforms in residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The locks market functions as a stable compounder anchored by replacement-driven mechanical hardware demand and technology upgrade cycles in connected access control.
For Market Incumbents: Anticipate margin compression from Chinese biometric module cost convergence by accelerating ETSI EN 303 645 certification investment and securing SaaS platform partnerships that embed recurring revenue. Defend specification authority in multi-family residential developments through Matter protocol integration and builder-direct channel control. For New Entrants and Emerging Players: E-commerce marketplace routes offer lowest-friction entry into North American residential replacement segments, bypassing entrenched locksmith distribution. Target India's gated community developments along Bengaluru and Hyderabad metro corridors with cost-optimized electronic access hardware. Pursue short-term rental channel partnerships with property management software platforms for app-based credential provisioning. For Investors and Strategic Acquirers: Consolidation pressure builds where cybersecurity firmware expertise scarcity fragments mid-tier hardware manufacturers unable to achieve EU certification. Long-term viability favors platform-integrated specialists with SaaS revenue attachment and compliance-forward product portfolios. Monitor ETSI certification adoption rates among European property technology integrators as inflection indicator for specification authority concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | ETSI EN 303 645 compliance filters uncertified competitors from EU specification shortlists. |
| SaaS Platform Partnership | Access-as-a-service subscriptions shift purchasing authority toward IT procurement functions. |
| Biometric Module Integration | Sub-$15 fingerprint sensor costs penetrate mid-market residential segments previously price-excluded. |
| Matter Protocol Implementation | Interoperability certification reduces post-sale support burdens for homebuilder specifications. |
| India Assembly Partnership | BIS certification barriers favor domestic manufacturing partnerships for electronic lock imports. |
Research Methodology
Multiple input streams — primary interviews with hardware manufacturers, property technology integrators, and multi-family developer procurement officers; secondary validation through customs trade data, SEC 10-K filings, and ETSI certification registries; and bottom-up and top-down triangulation — were reconciled to construct segment-level demand estimates. Stakeholder conversations captured specification cycle compression, SaaS procurement authority shifts, and regional certification divergence.
Data-stream reconciliation across product type, material grade, technology architecture, and end-user vertical dimensions produced volume and value outputs over the projection horizon. CAGRs were derived from replacement cycle analysis, new construction permit trajectories, and smart home platform penetration curves. Forecast inputs included semiconductor allocation constraints, zinc price volatility bands, and regional cybersecurity regulatory enforcement timelines.
Semiconductor supply disruption, cybersecurity regulatory enforcement variance, and raw material cost spikes are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumption sets regarding smart lock adoption curves and certification compliance timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Middle East and Africa Pin-Based Access Control Market
Access Control Systems
Automated Barriers and Bollards Market
Access Control Systems
China Access Control Market
Access Control Systems
Indoor Electromagnetic Lock Market
Access Control Systems
Global Industrial Access Control Market
Access Control Systems
Electronic Access Control Systems Market
Access Control Systems
US Restricted Access Barrier System Market
Access Control Systems
France Access Control Market
Access Control Systems
North America Home Security System Market
Access Control Systems
North America Safety Systems Market
Access Control Systems
Home Control and Security Systems Market
Access Control Systems
Bluetooth Smart Lock Market
Access Control Systems
North America Pin-Based Access Control Market
Access Control Systems
Automatic Gate and Door Opening System Market
Access Control Systems
Asia Pacific Access Control Software Market
Access Control Systems
US Access Control Market