
 Europe Air Traffic Management Market | 2026-2036
Europe Air Traffic Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Air Traffic Management Market Analysis
Copper cabling is shifting toward fiber-optic backbone networks in European ATM infrastructure, cutting signal latency for real-time surveillance data. Thales leverages its Gallium Nitride radar component supply chain to sustain competitive positioning in primary surveillance systems. Frequentis AG anchors command-and-control voice communication markets through specialized VCS3020 platforms deployed across Nordic air navigation service providers. Indra competes on integrated tower solutions, while Saab AB dominates remote digital tower deployments with its r-TWR systems across British and Irish airports.
Europe Air Traffic Management encompasses the ground-based and airborne systems that coordinate aircraft separation, routing, and sequencing across national airspaces, operating through radar refresh rates under 5 seconds and VHF voice channels at 25 kHz spacing to ensure continuous communication coverage. Surveillance Technologies lead technology investment as Mode-S and ADS-B OUT mandates expand fleet equipage requirements. Flight Information Services within the service-type dimension represent the fastest-growing category as System Wide Information Management networks replace fragmented aeronautical data distribution. Commercial Aviation commands the largest application share, though UAV Operations is gaining structural importance as EASA regulatory frameworks enable beyond-visual-line-of-sight cargo routes.
EASA's Single European Sky ATM Research program shapes harmonized equipment standards across member states, while the EU Green Deal's ReFuelEU Aviation mandate forces trajectory optimization software upgrades to reduce holding patterns and fuel burn. Eurocontrol's network manager function coordinates cross-border capacity allocation, creating procurement scale for multinational system integrators. Stakeholders must monitor EASA's U-space regulatory package implementation timelines and national air navigation service provider consolidation decisions to align product roadmaps with evolving certification requirements.
Market Dynamics
EU Green Deal mandates are compressing procurement cycles for trajectory optimization software as national air navigation service providers face binding carbon reduction targets for en-route operations.
Growth Catalysts
- EASA U-space regulatory package:Beyond-visual-line-of-sight cargo corridors are unlocking UAV operations as a structural demand vertical across German and French urban air mobility zones.
- Fiber-optic backbone deployment:Copper replacement programs at Frankfurt and Munich airport clusters are cutting surveillance data latency below radar refresh thresholds.
- Trajectory-based operations:Eurocontrol network manager coordination is harmonizing cross-border capacity allocation and creating multinational procurement scale for integrated tower solutions.
Market Restraints
- Gallium Nitride component scarcity:Primary radar supply chains face input concentration risk from limited semiconductor foundry capacity serving defense and aviation dual-use demand.
- Legacy VHF infrastructure lock-in:25 kHz channel spacing standards create technical friction against spectrum reallocation for next-generation datalink services.
- National ANSP fragmentation:Thirty-seven separate procurement authorities across EU member states dilute standardization momentum for Single European Sky interoperability targets.
Strategic Opportunities
- Remote digital tower penetration:British and Irish regional airports present underexploited deployment potential for virtualized air traffic control infrastructure.
- System Wide Information Management integration:Flight information services convergence with meteorological and aeronautical data feeds is opening new service revenue pools.
- ReFuelEU Aviation mandate:Trajectory optimization software upgrades forced by sustainable aviation fuel blending requirements are accelerating replacement cycles for flight management systems.
Industry Challenges
- Mode-S and ADS-B OUT certification backlog:Fleet retrofit timelines are compressing as EASA mandates approach enforcement windows, straining approved design organization capacity.
- Radar refresh rate engineering:Sub-5 second surveillance update requirements demand specialized signal processing expertise that outpaces European technical training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Air Traffic Management Market |
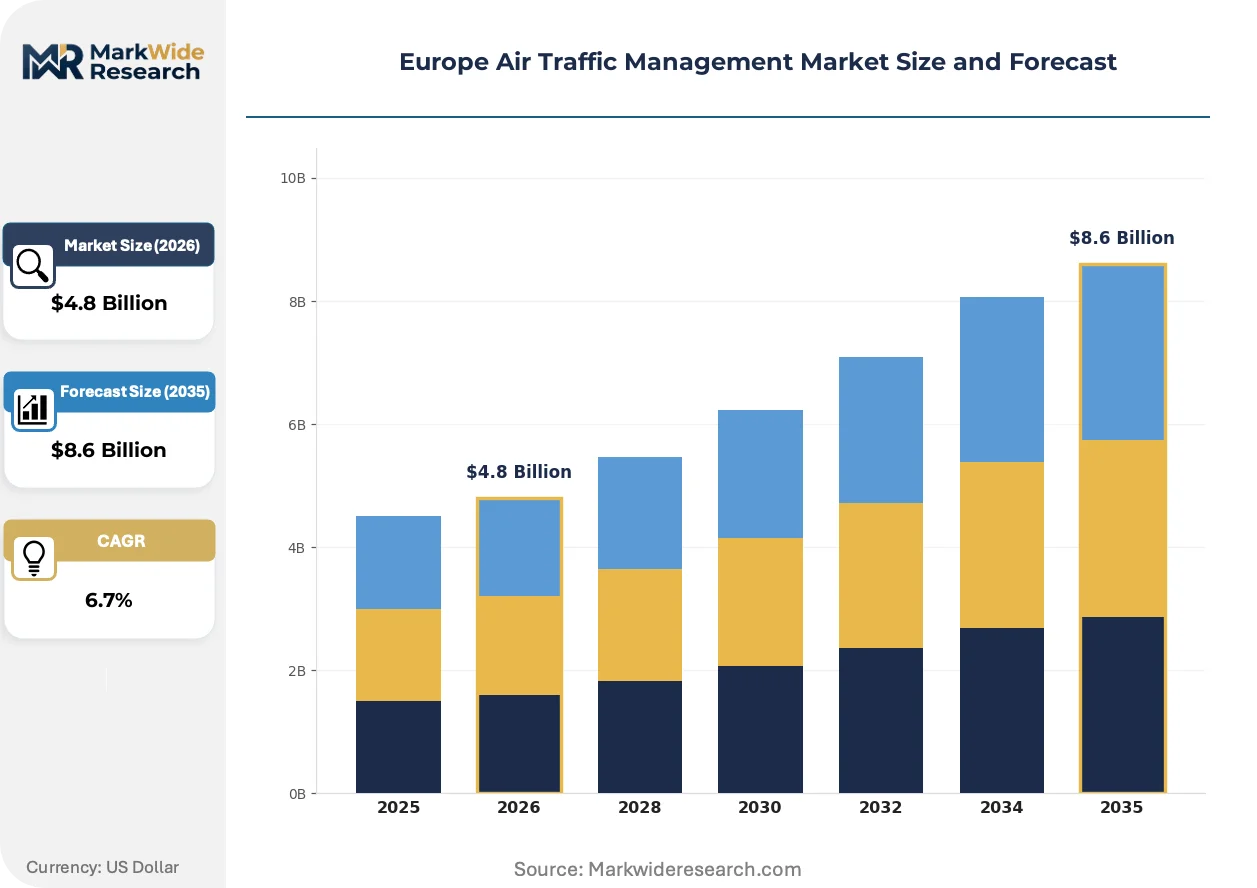
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radar Systems, Communication Network, Navigation Systems, Surveillance Technologies Service Type: Air Traffic Control, Data Management, Flight Information Services, Flight Planning Application: Commercial Aviation, Military Aviation, UAV Operations, Airport Management End User: Airlines, Airport Authorities, Defense Agencies, Air Traffic Service Providers |
| Companies Covered | Honeywell International Inc., RTX Corporation, BAE Systems plc, Saab AB, SITA, Thales, Indra, Frequentis AG, Leonardo S.p.A, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Air Traffic Management Market Emerging Trajectories
Digital tower virtualization and AI-assisted sequencing algorithms are displacing conventional control room architectures across European airport infrastructure investment programs.
Artificial intelligence-based arrival manager systems are converging with machine learning predictive models to optimize runway sequencing. Major hub airports in Germany and the Netherlands are piloting these platforms for peak-hour congestion management. This convergence is compressing the competitive window for legacy rules-based decision support tools.
EU Green Deal ReFuelEU Aviation regulations are mandating holding pattern reduction through continuous descent operations. Airlines operating from Frankfurt, Paris-Charles de Gaulle, and Amsterdam Schiphol must upgrade flight management computers to comply with trajectory optimization requirements. The mandate is forcing accelerated procurement of ground-based precision navigation infrastructure.
Service contracts for surveillance data processing are fragmenting from bundled hardware-software packages toward unbundled software-as-a-service arrangements. Nordic air navigation service providers are leading this disintermediation, separating sensor maintenance from data analytics subscriptions. British airports show the strongest uptake of outcome-based performance contracts linking vendor payments to delay reduction metrics.
Europe Air Traffic Management Market Segmentation
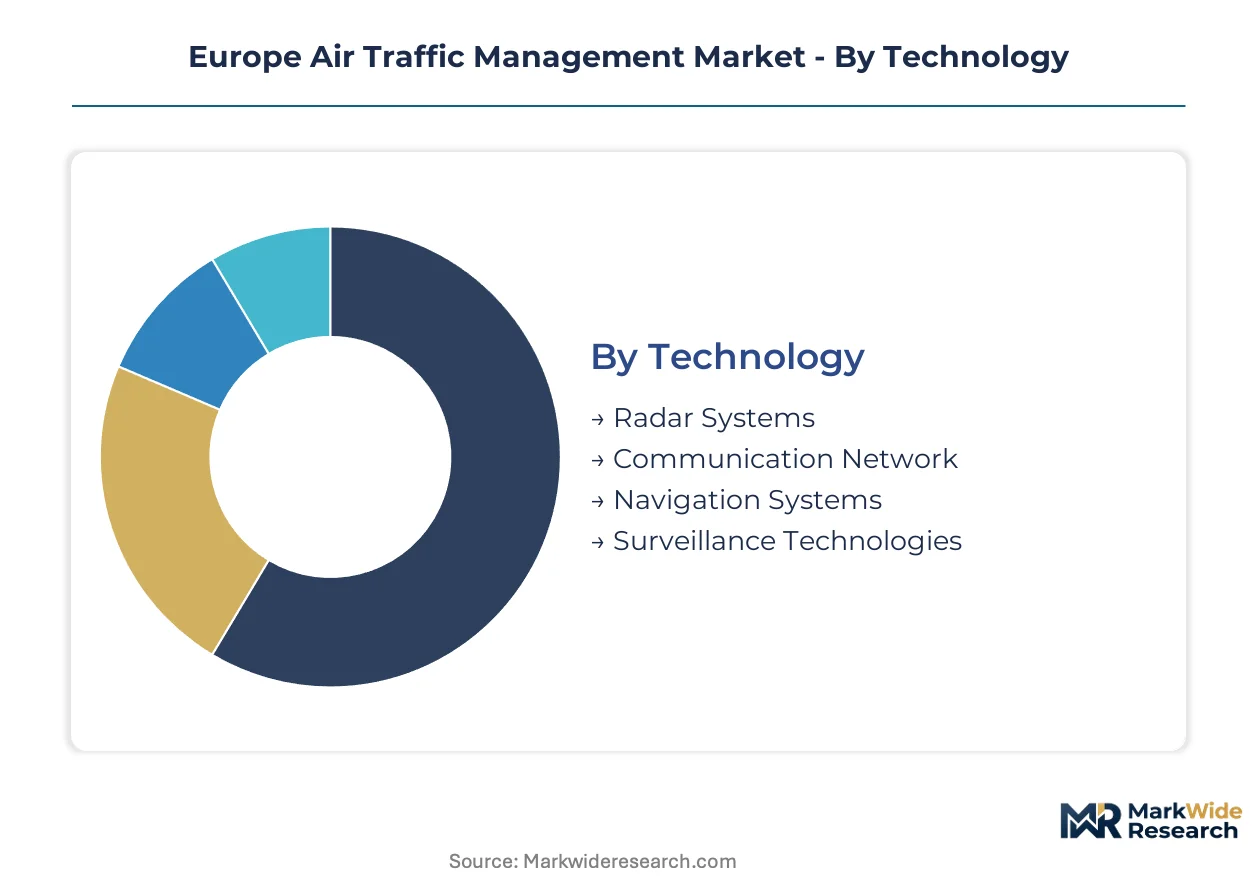
Procurement decisions across European ATM infrastructure hinge on interoperability mandates from EASA and Eurocontrol, forcing buyers to prioritize certified solutions over point innovations. Segmentation reveals how technology investments, service contracts, and end-user requirements fragment across distinct budget authorities with divergent upgrade timelines.
Technology:
Capital allocation intensity varies sharply by refresh cycle length, with surveillance infrastructure commanding multiyear deployment horizons against shorter communication network replacement windows.
- Surveillance Technologies:Mode-S and ADS-B OUT transponder networks form the core infrastructure for cooperative aircraft tracking across German and French airspace. Frankfurt and Munich airport clusters are driving equipage mandates as EASA enforcement windows approach, compressing supplier certification timelines.
- Radar Systems:Primary surveillance radar with Gallium Nitride semiconductor components delivers sub-5 second refresh rates for non-cooperative aircraft detection. Gallium Nitride foundry capacity constraints are creating procurement bottlenecks for national air navigation service providers modernizing en-route coverage.
- Communication Network:VHF voice channels at 25 kHz spacing and fiber-optic backbone infrastructure enable controller-pilot datalink and surveillance data transport.
- Navigation Systems:Ground-based augmentation systems and precision approach path indicators support instrument landing operations.
Volume sits with Surveillance Technologies; growth tilts toward Communication Network as copper-to-fiber replacement programs accelerate.
Service Type:
Contract structures are unbundling from integrated hardware-software bundles toward discrete service subscriptions, with outcome-based pricing gaining traction among Nordic air navigation service providers.
- Flight Information Services:System Wide Information Management networks consolidate meteorological, aeronautical, and surveillance data feeds into unified distribution platforms. Eurocontrol's network manager function is standardizing data exchange protocols across British, Dutch, and German service providers, creating procurement scale.
- Air Traffic Control:Tower and en-route separation services remain the revenue anchor for national air navigation service providers, with digital tower virtualization disrupting conventional staffing models.
- Data Management:Surveillance data processing and analytics subscriptions are separating from sensor maintenance contracts.
- Flight Planning:Trajectory optimization software enables continuous descent operations and holding pattern reduction for ReFuelEU Aviation compliance.
Revenue concentrates in Air Traffic Control; expansion is climbing the fastest in Flight Information Services as SWIM deployment scales.
Application:
Regulatory enablement timelines determine addressable market expansion, with EASA U-space frameworks unlocking new operational categories ahead of military certification harmonization.
- Commercial Aviation:Scheduled passenger and cargo operations dominate installed base value, with hub airports in Germany, France, and the Netherlands driving ground infrastructure modernization budgets.
- UAV Operations:Beyond-visual-line-of-sight cargo corridors in German and French urban air mobility zones are emerging as structural demand verticals under EASA U-space regulatory frameworks.
- Military Aviation:State air forces and NATO coordination requirements sustain specialized communication and surveillance procurement channels.
- Airport Management:Surface movement guidance and apron control systems integrate with tower operations for ground traffic optimization.
Spend sits with Commercial Aviation; expansion tilts toward UAV Operations as regulatory corridors activate.
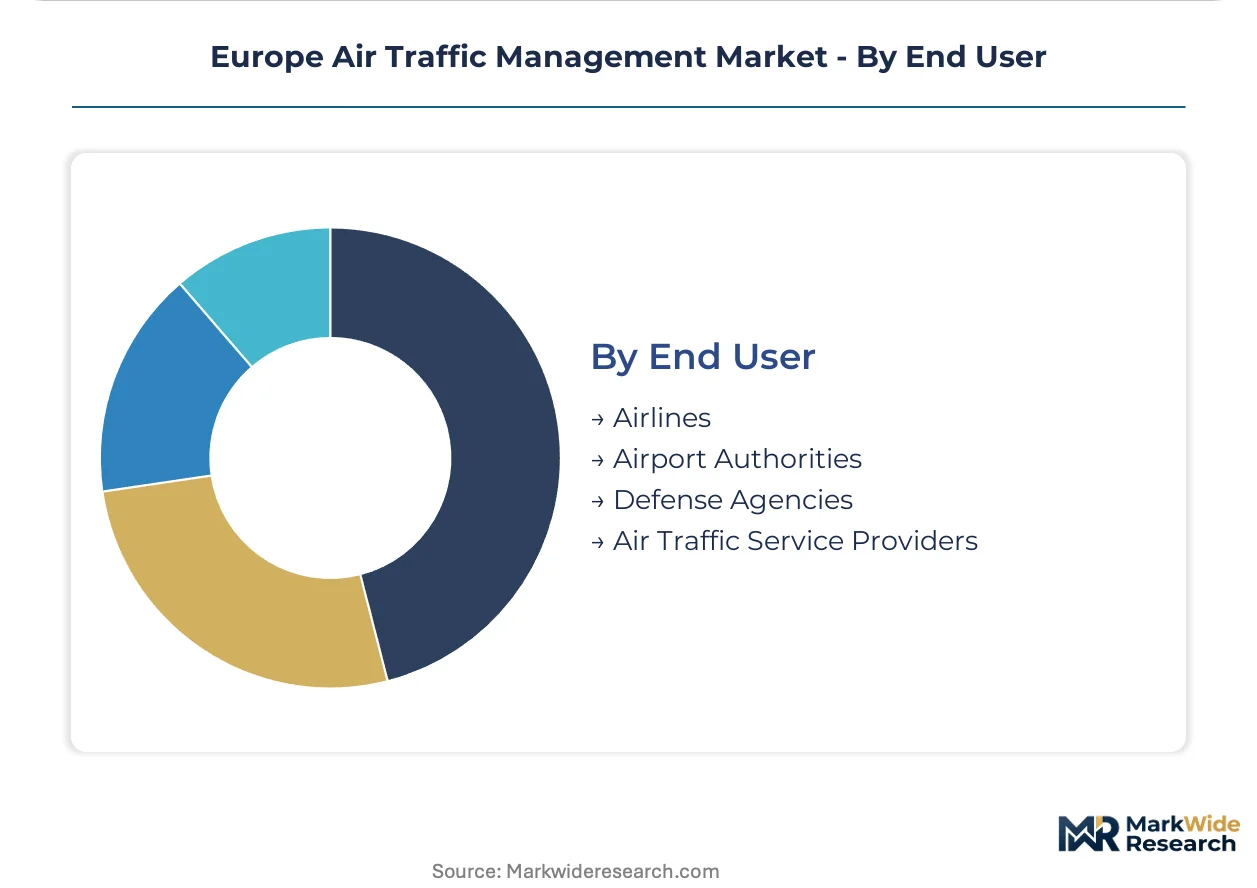
End User:
Budget cycle misalignment creates selling complexity, with airline fleet retrofit programs operating on accelerated timelines against airport authority capital planning horizons.
- Air Traffic Service Providers:National air navigation service providers across thirty-seven EU member state authorities procure ground infrastructure for en-route and terminal airspace management. Eurocontrol coordination is harmonizing cross-border capacity allocation, creating multinational procurement scale for integrated system integrators.
- Airport Authorities:Frankfurt, Munich, Paris-Charles de Gaulle, and Amsterdam Schiphol anchor the largest modernization budgets for tower and surface movement infrastructure.
- Airlines:Fleet operators face Mode-S and ADS-B OUT equipage mandates with EASA enforcement windows approaching.
- Defense Agencies:Military air forces maintain separate procurement channels for secure communication and surveillance capabilities.
Contract value sits with Air Traffic Service Providers; decision velocity tilts toward Airport Authorities as digital tower programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt Airport's status as a Single European Sky performance zone concentrates modernization budgets across the Rhine-Main cluster. German and French urban air mobility corridors are activating beyond-visual-line-of-sight regulatory frameworks ahead of other member states.
Germany
Frankfurt and Munich airport clusters anchor Europe's largest ground infrastructure spending on fiber-optic backbone replacement. EASA Mode-S and ADS-B OUT enforcement windows are compressing fleet retrofit timelines for Lufthansa Group operators. The Bavarian aerospace corridor around Munich is driving digital tower virtualization pilots.
France
Paris-Charles de Gaulle and Orly airport authorities are procuring trajectory optimization software under ReFuelEU Aviation mandates. The EU Green Deal's continuous descent operation requirements are forcing flight management system upgrades. The Île-de-France aviation cluster is integrating AI-assisted arrival sequencing for peak-hour congestion management.
United Kingdom
British regional airports are deploying remote digital tower infrastructure faster than continental counterparts. The CAA's U-space regulatory framework is unlocking beyond-visual-line-of-sight cargo corridors in Scottish and Irish airspace. London Terminal Control's modernization is driving multinational procurement for integrated tower solutions.
Netherlands
Amsterdam Schiphol's network manager coordination role under Eurocontrol creates procurement scale for cross-border capacity allocation systems. Dutch air navigation service providers are piloting unbundled software-as-a-service surveillance contracts. The Randstad aviation cluster is testing machine learning predictive models for runway sequencing optimization.
Spain
Barcelona and Madrid air traffic control centers are upgrading primary surveillance radar amid Gallium Nitride component supply constraints. EASA's Single European Sky ATM Research program is harmonizing equipment standards across Iberian Peninsula corridors. The Mediterranean airspace cluster is prioritizing System Wide Information Management network integration.
Europe Air Traffic Management Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system integrators dominating ground infrastructure while component suppliers capture surveillance technology niches. The vendor base clusters around three archetypes: defense-aerospace conglomerates with dual-use radar capabilities, specialized voice communication platform developers, and digital tower virtualization pure-plays. Consolidation pressure is intensifying through national air navigation service provider procurement centralization, while technology licensing partnerships are proliferating to address EASA certification complexity.
Within the defense-aerospace tier, Thales and BAE Systems exemplify integrated system integrators leveraging dual-use supply chains for primary surveillance radar. Saab AB occupies a distinctive position in remote digital tower deployments across British and Irish markets. Frequentis AG anchors specialized voice communication segments through command-and-control platform development for Nordic air navigation service providers. These three represent contrasting strategic postures: full-stack integration, vertical niche dominance, and regional specialization.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| RTX Corporation |
| BAE Systems plc |
| Saab AB |
| SITA |
| Thales |
| Indra |
| Frequentis AG |
| Leonardo S.p.A |
| Others |
Supply Flow & Price Mechanics
National air navigation service providers concentrate procurement authority across thirty-seven EU member states, anchoring contract-based long-term offtake as the dominant pricing model for ground infrastructure modernization. This buyer concentration creates asymmetric negotiating leverage against specialized radar and digital tower suppliers, compressing margins on standardized equipment while preserving premium capture for EASA-certified integrated systems.
Pricing Analysis
Short lead-time premiums apply to Gallium Nitride radar components and Mode-S transponder modules as EASA enforcement windows compress supplier delivery schedules. Project-based pricing dominates tower infrastructure and fiber-optic backbone deployments, with three-tier pricing structure across premium, standard, and economy levels reflecting certification grade and after-sales service bundling. Cost compression in surveillance hardware intensifies because foundry capacity constraints limit supplier flexibility. Regional airport authorities exhibit highest price sensitivity due to constrained capital planning cycles, while Frankfurt and Munich airport clusters prioritize performance specifications over unit economics.
Supply Chain Analysis
Refurbishment flows for legacy VHF voice communication equipment extend asset lifecycles across Nordic air navigation service providers, creating secondary market liquidity for copper cabling and analog control consoles. Gallium Nitride semiconductor fabrication concentrates in the United States, Taiwan, and South Korea, while precision radar antenna manufacturing draws from Germany, France, and Sweden. Single-source vulnerability permeates defense-aerospace dual-use foundry capacity serving both primary surveillance radar and military electronic warfare demand. Distribution runs through national procurement authorities coordinating with Eurocontrol network manager specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe Air Traffic Management operates as a vertical-integration race where upstream control over Gallium Nitride semiconductor supply and downstream capture of software-as-a-service surveillance contracts determine competitive durability. Players are pursuing backward integration into specialized signal processing components to defend margin position against foundry bottleneck risks.
For Market Incumbents: Hedge against Gallium Nitride component scarcity by securing long-term foundry offtake agreements with Taiwan and South Korean semiconductor fabricators. Deepen software-as-a-service capabilities in surveillance data analytics to offset hardware margin compression from standardized Mode-S and ADS-B OUT equipage mandates. For New Entrants and Emerging Players: Capture remote digital tower deployment opportunities across British and Irish regional airports where virtualization pilots outpace continental adoption. Target unbundled flight information services contracts in Nordic markets where outcome-based performance pricing disrupts legacy bundled procurement structures. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized voice communication platform developers with EASA certification pipelines and established Nordic air navigation service provider relationships over capital-intensive radar hardware manufacturers. Monitor EASA U-space regulatory package implementation timelines as the primary inflection signal for UAV operations market activation.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Tower Virtualization | Saab AB's r-TWR deployments across British and Irish airports demonstrate scalable remote control infrastructure replacement. |
| Fiber-Optic Backbone Deployment | Frankfurt and Munich airport clusters anchor copper replacement programs cutting surveillance data latency below radar refresh thresholds. |
| Trajectory Optimization Software | ReFuelEU Aviation mandates force continuous descent operation upgrades at Paris-Charles de Gaulle and Amsterdam Schiphol. |
| System Wide Information Management Integration | Eurocontrol network manager standardization creates procurement scale for unified meteorological and aeronautical data distribution. |
| Gallium Nitride Supply Security | Thales leverages dual-use defense-aerospace supply chains to sustain competitive positioning in primary surveillance radar. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across air navigation service provider procurement directors, airport authority infrastructure planners, EASA certification engineers, and radar system integration specialists. Eurocontrol network coordination documents, EASA regulatory impact assessments, and national ANSP budget disclosures provided demand-side validation. Bottom-up equipment shipment analysis and top-down infrastructure spending estimates were triangulated against cross-border capacity allocation projections.
Segment-level modeling applied technology refresh cycles, service contract unbundling trajectories, and regulatory enablement timelines across the projection horizon. Surveillance technology, communication network, and navigation system dimensions were modeled with application-specific penetration rates for commercial aviation and UAV operations. CAGRs were derived from compound growth path analysis anchored to EASA mandate enforcement schedules and EU Green Deal implementation milestones. Flight Information Services expansion was calibrated against System Wide Information Management deployment curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EASA U-space regulatory delays and Gallium Nitride foundry capacity allocation shifts between defense and civil aviation demand. Forecasts reflect documented assumptions about national ANSP consolidation timelines and ReFuelEU Aviation trajectory optimization compliance rates. Practitioners should monitor EASA certification backlog resolution and Eurocontrol cross-border procurement centralization decisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Airspace and Procedure Design Market
Aircraft Navigation and Communication
Global Air Traffic Control Equipment Market
Aircraft Navigation and Communication
Air Traffic Management Software Market
Aircraft Navigation and Communication
In Flight Connectivity Market
Aircraft Navigation and Communication
Digital Radiosonde Market
Aircraft Navigation and Communication
5G in Aviation Market
Aircraft Navigation and Communication
Ultra Short Base Line Positioning System Market
Aircraft Navigation and Communication
5G Adoption Analysis in Aviation Market
Aircraft Navigation and Communication
Airborne Radars Market
Aircraft Navigation and Communication
Global Aviation Mapping Software Market
Aircraft Navigation and Communication
Aircraft Communication System Market
Aircraft Navigation and Communication
America Air Traffic Management Market
Aircraft Navigation and Communication
Defense Advanced GPS Receiver (DAGR) Market
Aircraft Navigation and Communication
Asia-Pacific Air Traffic Management Market
Aircraft Navigation and Communication
Global Drone Navigation System Market
Aircraft Navigation and Communication
Airborne High Frequency Radio Market