
 Air Traffic Control Simulator and Training Market | 2026-2036
Air Traffic Control Simulator and Training Market Size, Share, and Industry Trends Forecast 2026-2036
Air Traffic Control Simulator and Training Market Insights
Military buyers is redrawing procurement priorities across the Air Traffic Control Simulator and Training landscape as defense ministries prioritize joint-force interoperability. BAE Systems leverages its long-standing defense relationships to sustain simulator integration programs across European air forces. Thales Group anchors its position through radar-to-simulator technology linkages that dominate French and export military training pipelines.
Air Traffic Control Simulator and Training systems replicate real-world airspace environments using synthetic radar feeds, pseudo-pilot stations, and 360-degree visual dome projections calibrated to ICAO Doc 9625 standards for flight simulation training devices. Their primary purpose is to certify controllers without disrupting live operations or exposing trainees to safety-critical errors. Tower Training Simulator configurations command premium positioning due to their complexity in replicating ground movement and runway incursion scenarios, while Virtual Reality Simulator segments attract R&D investment for cost reduction despite lingering motion fidelity limitations. Desktop Simulator units occupy the volume tier among aviation training schools seeking affordable recurrent training infrastructure.
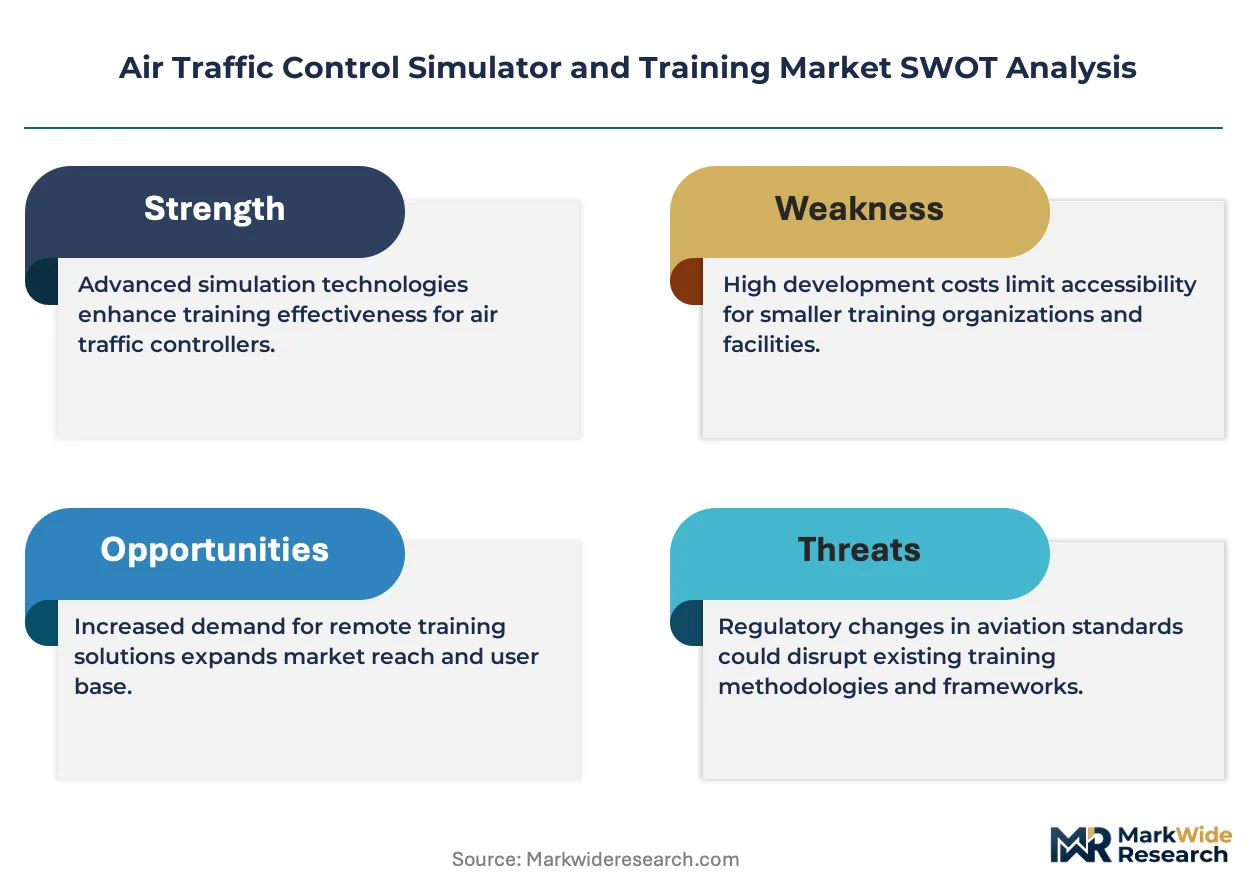
ICAO standards mandate recurrent proficiency checks that directly sustain simulator utilization rates across certified training organizations. The FAA's updated air traffic control training directives in the United States and EASA's regulatory harmonization efforts across EU member states tighten device qualification requirements, raising barriers for non-compliant suppliers. Stakeholders must monitor how next-generation surveillance technologies such as space-based ADS-B reshape scenario libraries and force hardware refresh cycles.
Market Dynamics
Space-based ADS-B surveillance networks are forcing hardware refresh cycles across training infrastructure as legacy radar-replica simulators lose scenario fidelity against modern traffic management protocols.
Growth Catalysts
- ICAO Doc 9625 Recertification Mandates:Proficiency check requirements sustain utilization rates across certified training organizations in Germany, France, and the United Kingdom.
- Military Interoperability Protocols:NATO-aligned defense ministries expand joint-force coordination training, driving simulator procurement for cross-border air defense scenarios.
- Controller Staffing Deficits:Germany's national air navigation service provider faces acute workforce gaps that accelerate simulator deployment for accelerated certification pipelines.
Market Restraints
- Visual Dome Component Concentration:High-fidelity projection systems rely on specialized optics suppliers concentrated in Japan and Germany, creating input cost volatility.
- Regulatory Harmonization Friction:Divergent FAA and EASA device qualification timelines extend certification cycles for multi-jurisdictional suppliers.
- Motion Fidelity Limitations:Virtual reality headsets remain structurally constrained by vestibular mismatch issues that limit tower simulation accuracy.
Strategic Opportunities
- Desktop Simulator Penetration:Aviation training schools in India and Southeast Asia represent underpenetrated volume-tier demand for affordable recurrent training infrastructure.
- AI-Generated Scenario Libraries:Machine learning convergence with synthetic traffic generation enables dynamic airspace complexity without manual scripting.
- EU Green Deal Procurement Incentives:Energy-efficient simulator architectures qualify for public procurement preference margins across member state ANSP tenders.
Industry Challenges
- Legacy Radar Interface Integration:Simulator manufacturers must maintain compatibility with aging ground-based surveillance systems while modernizing synthetic feed architectures.
- Certified Instructor Pipeline Scarcity:Qualified pseudo-pilot operators and simulation facilitators face recruitment bottlenecks that constrain training throughput.
- Hardware Refresh Capital Intensity:Full-dome visual system replacements require substantial capital allocation every seven to ten years.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Traffic Control Simulator and Training Market |
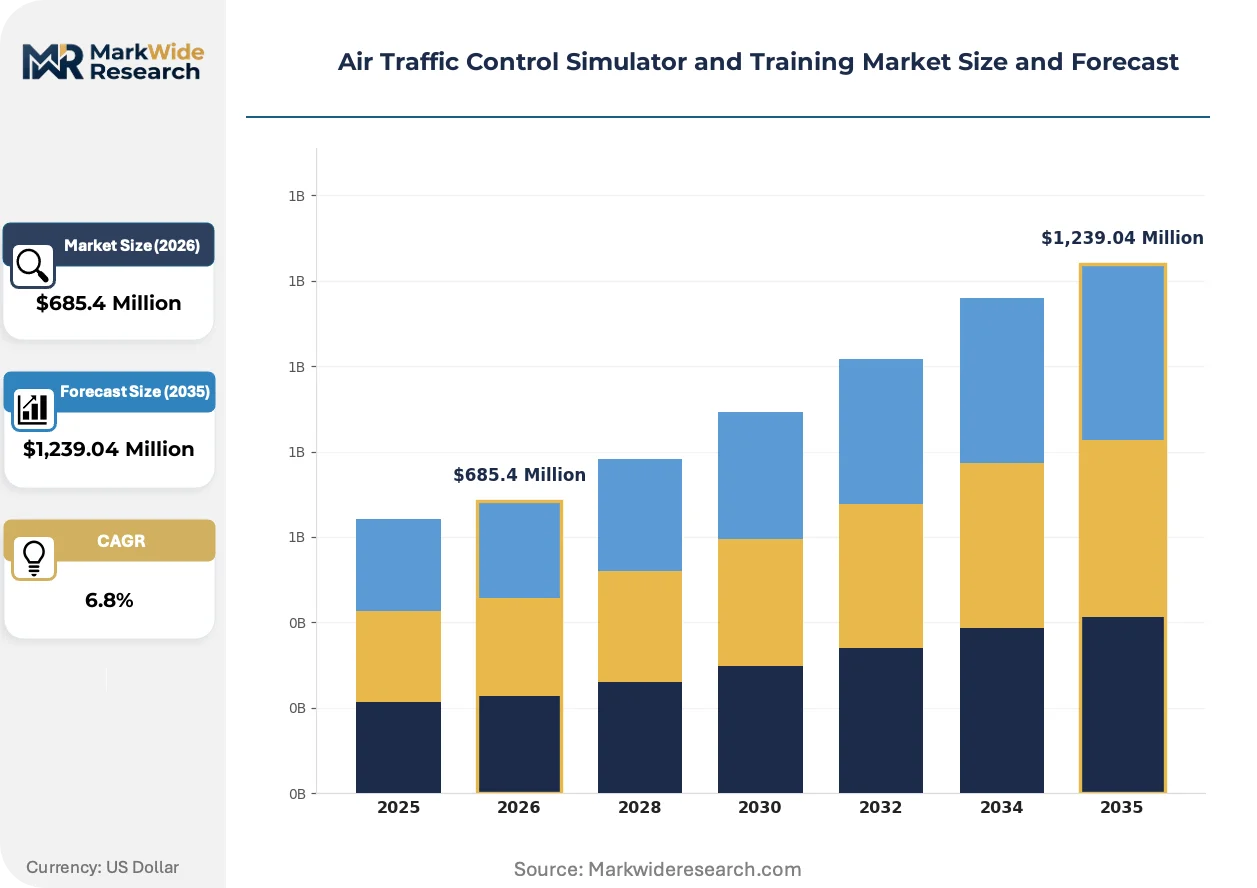
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Flight Simulator, Tower Training Simulator, Desktop Simulator, Virtual Reality Simulator End User: Civil Aviation Authorities, Military, Aviation Training Schools, Airlines Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Training Type: Initial Training, Refresher Training, Certification Training, Scenario-Based Training |
| Companies Covered | Adacel Technologies, BAE Systems, Frequentist, Raytheon Technologies Corporation, Thales Group, Leonardo, Indra, ST Engineering, Saab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Traffic Control Simulator and Training Market Trends and Innovations
Digital twin architectures are compressing the boundary between synthetic and live airspace environments, enabling real-time scenario injection from operational data feeds.
Cloud-native simulator platforms are supplanting on-premise tower and radar training installations. Regional aviation academies in Spain and Italy adopt subscription-based access models to eliminate capital expenditure barriers. This architecture is compressing vendor lock-in durations and accelerating procurement cycle velocity for mid-tier training providers.
EASA's regulatory harmonization framework tightens device qualification requirements across EU member states, raising technical barriers for non-compliant equipment suppliers. Simulator manufacturers must now demonstrate cross-border interoperability certification before tender eligibility. Tower Training Simulator configurations face the steepest compliance burden due to ground movement complexity validation protocols.
Buyer consolidation among national air navigation service providers is concentrating procurement authority into centralized framework agreements. Germany's DFS and France's DSNA now coordinate joint simulator tenders, displacing fragmented regional purchasing. This pattern is most visible across Western European ANSPs seeking volume leverage over specialized tower simulation suppliers.
Air Traffic Control Simulator and Training Market Segmentation
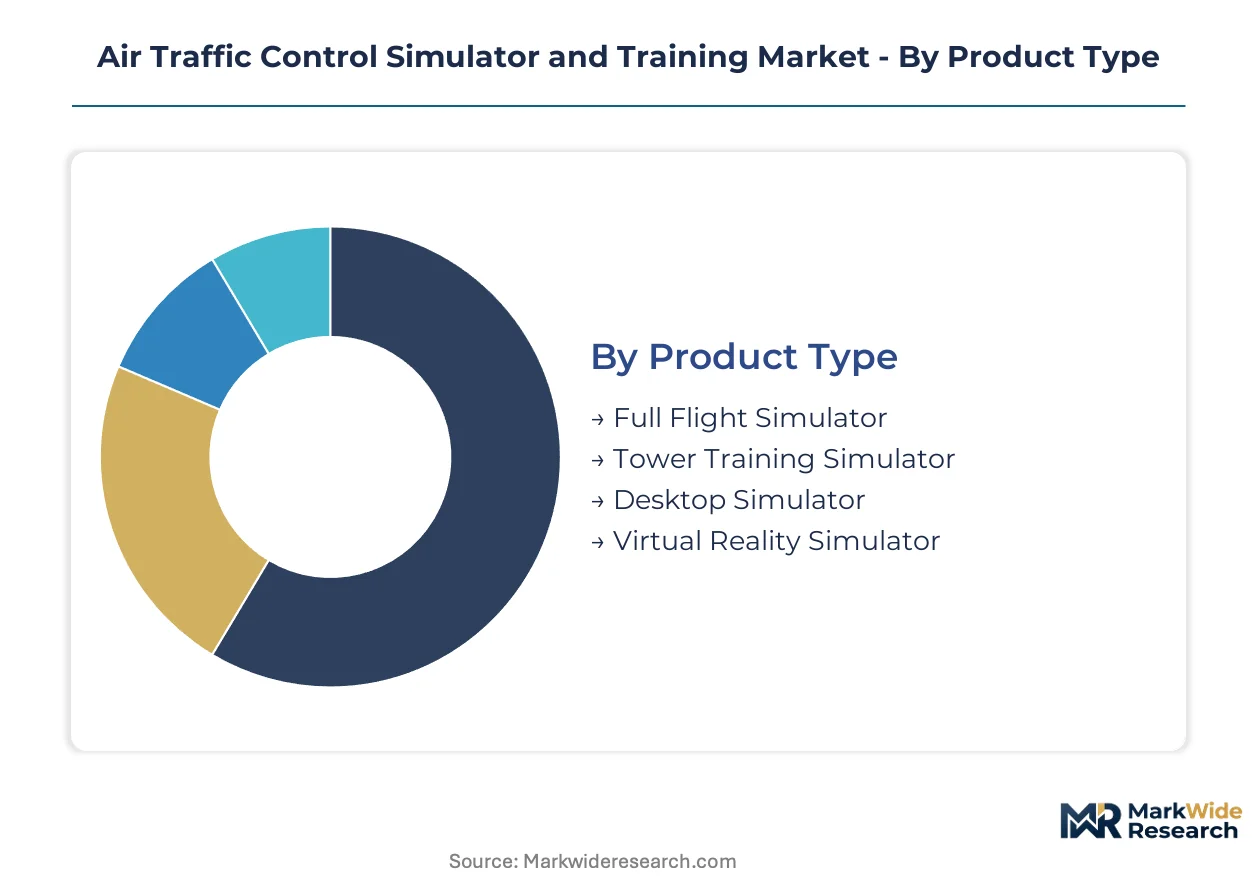
Segmentation in the Air Traffic Control Simulator and Training Market reveals divergent procurement patterns across defense and civilian channels. Each dimension exposes distinct technology requirements, certification burdens, and geographic concentration that shape supplier positioning.
Product Type:
Domestic procurement dominates tower and radar simulators with localized certification requirements, while desktop and VR units flow through export-led distribution to training academies in cost-sensitive markets.
- Tower Training Simulator:These systems replicate ground movement control with 360-degree visual dome projections calibrated to ICAO Doc 9625 standards. German and French air navigation service providers concentrate demand here due to dense European airspace complexity and mandatory runway incursion scenario training.
- Full Flight Simulator:Integrated radar-to-pilot station architectures serve military joint-force coordination protocols across NATO-aligned defense ministries. Procurement runs through centralized framework agreements with extended qualification timelines.
- Desktop Simulator:Volume-tier units target aviation training schools in India and Southeast Asia seeking affordable recurrent training infrastructure without capital-intensive dome installations.
- Virtual Reality Simulator:R&D-heavy segment attracts investment for cost reduction despite vestibular mismatch constraints limiting tower simulation accuracy.
Tower Training Simulator commands the established base. The steepest expansion runs through Desktop Simulator.
End User:
Cost tier stratification separates military and civil aviation authority procurement—premium certified systems versus volume-tier training school deployments.
- Military:Defense ministries prioritize joint-force interoperability with cross-border air defense scenario capabilities. NATO modernization protocols sustain simulator deployment acceleration.
- Civil Aviation Authorities:National air navigation service providers in Germany and France operate under EASA harmonization frameworks with tightened device qualification requirements.
- Aviation Training Schools:Regional academies in Spain and Italy adopt subscription-based cloud access models to eliminate capital expenditure barriers.
- Airlines:In-house controller training programs remain limited due to regulatory delegation to national ANSP certification pipelines.
Civil Aviation Authorities anchor procurement volume. Military programs are gaining share fastest through interoperability mandates.
Deployment:
Application criticality determines architecture choice—live airspace integration favors on-premise security, while recurrent training shifts toward cloud elasticity.
- On-Premise:Tower and radar training installations persist where synthetic feed integration with live operational data requires air-gapped security protocols.
- Cloud-Based:Regional aviation academies adopt subscription models that compress vendor lock-in durations and accelerate procurement velocity for mid-tier providers.
- Hybrid:Split architectures maintain sensitive radar interfaces on-premise while pushing scenario libraries and administrative functions to cloud infrastructure.
- Mobile:Portable units serve remote military deployment scenarios and temporary training facilities with reduced fidelity requirements.
On-Premise retains mission-critical dominance. Cloud-Based deployment is expanding most quickly through European training academy adoption.
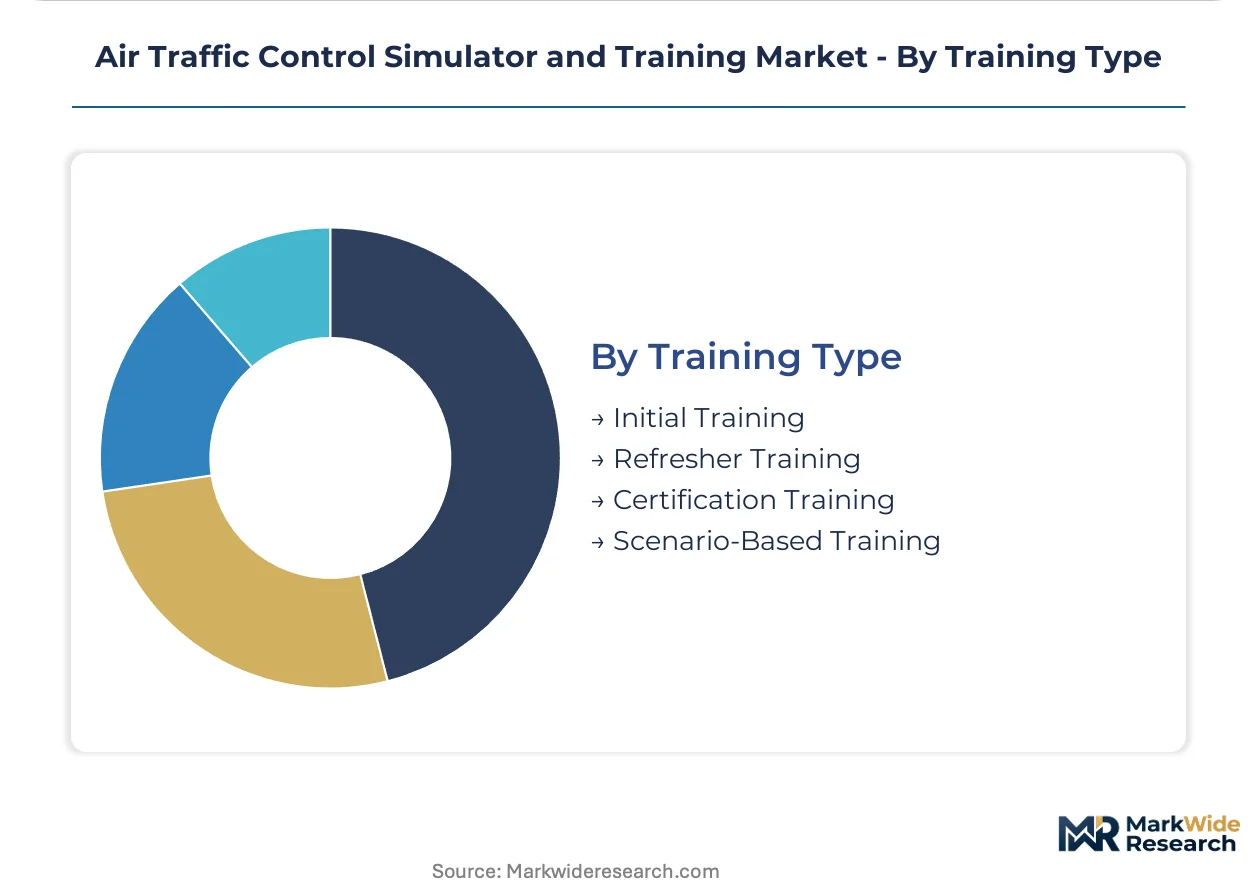
Training Type:
Customer type segmentation separates regulatory-mandated recurrent training from discretionary scenario-based skill development investments.
- Initial Training:Certification pipelines for new controllers require full-dome tower simulators with ground movement complexity validation under EASA protocols.
- Certification Training:ICAO Doc 9625 proficiency checks sustain utilization rates across certified training organizations with mandated recurrent scheduling.
- Refresher Training:Desktop and VR units penetrate this segment for cost-efficient skill maintenance between formal certification cycles.
- Scenario-Based Training:Dynamic airspace complexity generation through machine learning convergence enables adaptive difficulty without manual scripting overhead.
Certification Training generates the recurring revenue base. Scenario-Based Training shows the steepest trajectory through AI-generated library adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German simulator manufacturers export tower training systems to ANSPs across France, Spain, and Italy, establishing a westward trade corridor that supplies EASA-certified infrastructure to NATO-aligned defense ministries and civilian authorities.
Germany
DFS operates Europe's densest airspace and faces acute controller staffing deficits that accelerate simulator deployment. EASA harmonization frameworks mandate ground movement complexity validation for tower certification. Bavaria hosts specialized visual dome optics clusters where calibration laboratories service high-fidelity projection systems for domestic and export contracts.
France
DSNA coordinates joint tenders with German counterparts, consolidating procurement authority into centralized framework agreements. EU Green Deal procurement incentives favor energy-efficient simulator architectures in public tenders. The Île-de-France region anchors radar-to-simulator technology development for military export pipelines.
United Kingdom
NATS pursues cloud-native platform adoption to compress vendor lock-in durations across regional training academies. FAA-EASA regulatory friction extends certification cycles for multi-jurisdictional equipment suppliers. Greater London concentrates simulation facilitator training programs that address certified instructor pipeline scarcity.
United States
FAA updated air traffic control training directives tighten device qualification requirements for domestic suppliers. Military procurement agencies prioritize joint-force interoperability protocols under NATO modernization standards. The Washington DC corridor hosts defense ministry coordination centers that specify cross-border air defense scenario capabilities.
India
Aviation training schools in Maharashtra and Karnataka represent underpenetrated volume-tier demand for affordable desktop simulator units. The country's national aviation regulator aligns recurrent proficiency check mandates with ICAO Doc 9625 standards. Delhi-NCR clusters import refurbished tower systems from European suppliers to bridge infrastructure gaps.
Air Traffic Control Simulator and Training Market Competitive Landscape
Player mix skews toward defense-anchored conglomerates with long-standing military relationships. Market structure concentrates procurement authority through centralized framework agreements among Western European ANSPs. Three archetypes dominate: radar-to-simulator integrators, visual dome specialists, and cloud-native platform developers. Competitive moves center on joint tender coordination and hardware refresh cycle acceleration.
Among defense-anchored conglomerates, BAE Systems and Thales Group exemplify the radar-to-simulator integration archetype, while Raytheon Technologies Corporation occupies a position within the military interoperability tier. Adacel Technologies represents the specialized simulation software segment. These three anchors sit within distinct competitive vectors—European defense relationships, transatlantic military procurement, and dedicated training technology—without overlapping strategic positioning.
| Leading Market Players |
|---|
| Adacel Technologies |
| BAE Systems |
| Frequentist |
| Raytheon Technologies Corporation |
| Thales Group |
| Leonardo |
| Indra |
| ST Engineering |
| Saab |
| Others |
Pricing and Supply Chain Analysis
Twenty-four-month lead times for specialized visual dome optics from Bavarian calibration laboratories concentrate pricing power with German and Japanese projection system suppliers, compressing margin flexibility for tower simulator integrators while amplifying cost pass-through to NATO-aligned defense procurement frameworks.
Pricing Analysis
Current-generation full-dome tower simulators command substantial premiums over prior-generation radar-replica units and next-generation cloud-native platforms. Three-tier pricing structure across premium, standard, and economy levels separates EASA-certified installations from desktop recurrent training units and mobile military deployments. Pricing pressure stems from cloud-based subscription models compressing capital expenditure barriers for European training academies. Aviation training schools in India and Southeast Asia exhibit the highest price sensitivity, while German and French air navigation service providers prioritize certification compliance over unit economics.
Supply Chain Analysis
Germany and Japan anchor high-fidelity visual projection system manufacturing, while Taiwan and South Korea supply specialized display panel components. Synthetic radar feed architectures draw from semiconductor foundries in Taiwan and legacy ground-based surveillance interface specialists in France. Single-source vulnerability concentrates in precision optics suppliers concentrated in Bavaria and Osaka prefectures. Distribution runs through centralized framework agreements coordinated between Western European ANSPs and defense ministry procurement agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Air Traffic Control Simulator and Training Market expansion sits in early-cycle territory as space-based ADS-B surveillance networks force hardware refresh cycles across legacy training infrastructure, creating replacement demand tailwinds independent of new certification pipeline growth.
For Market Incumbents: Consolidate procurement authority through joint tender coordination with neighboring ANSPs, mirroring the DFS-DSNA framework agreement model. Deepen backward integration into visual dome optics manufacturing to reduce exposure to Japanese and German supplier concentration. Prioritize cloud-native platform development to defend against SaaS-based entrants compressing vendor lock-in durations across European training academies.
For New Entrants and Emerging Players: Lead with AI-generated scenario library capabilities targeting the scenario-based training segment where manual scripting overhead constrains incumbent throughput. Target underpenetrated aviation training schools in Maharashtra and Karnataka with desktop simulator units priced for volume-tier recurrent training demand. Establish regulatory foothold through EASA harmonization compliance before pursuing NATO defense ministry certification.
For Investors and Strategic Acquirers: Long-term, this sits as a defense-civilian dual-use infrastructure play because military interoperability mandates and civil aviation authority modernization cycles create synchronized demand pulses across non-correlated budget authorities. Acquisition target archetype: specialized simulation software developers with ICAO Doc 9625 certification pipelines and established pseudo-pilot training networks. Signal to watch: joint tender announcements between previously fragmented ANSPs indicating procurement authority consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Subscription models eliminate capital barriers for Spanish and Italian aviation academies. |
| AI-Generated Scenario Library Development | Machine learning convergence reduces manual scripting overhead for dynamic airspace complexity. |
| Visual Dome Optics Backward Integration | In-house production of projection systems mitigates Japanese and German supplier concentration risk. |
| EASA Cross-Border Interoperability Certification | Joint tender eligibility requires demonstrated certification across multiple EU member states. |
| Space-Based ADS-B Feed Integration | Synthetic scenario libraries must modernize to match operational surveillance protocol fidelity. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with simulation technology directors, ANSP procurement officers, military training commanders, and aviation academy operations heads; and secondary validation against ICAO regulatory filings, EASA device qualification databases, NATO standardization agreements, and defense ministry budget appropriations documents. Bottom-up triangulation across certified training organization deployment counts and top-down reconciliation against ANSP capital expenditure disclosures anchored volume estimates.
Across the analysis window, the forecasting framework modeled product type segmentation, end-user procurement authority concentration, deployment architecture migration patterns, and training type utilization intensity. CAGRs were derived from fitted growth curves calibrated to hardware refresh cycle observations and regulatory recertification mandate schedules. Space-based surveillance technology adoption curves and controller staffing deficit projections served as industry-specific demand drivers.
Forecasts assume regulatory continuity in EASA harmonization frameworks and FAA training directive enforcement; material policy shifts would require re-modeling. Scenario library refresh rates and visual dome replacement cycles represent primary forecast sensitivity variables. Recalibration cycles align with material shifts in surveillance technology standards and ANSP procurement authority consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Military Aerospace Simulation and Training Market
Simulation and Training
Middle East and Africa Ship Bridge Simulators Market
Simulation and Training
Asia-Pacific Ship Bridge Simulators Market
Simulation and Training
Air Traffic Control Simulation and Training Market
Simulation and Training
Global Healthcare Games and Simulation Market
Simulation and Training
Global Military Airborne Simulation and Training Market
Simulation and Training
GNSS Simulators Market
Simulation and Training
Satellite Simulator Market
Simulation and Training
RADAR Simulator Market
Simulation and Training
North America Ship Bridge Simulators Market
Simulation and Training
Police and Military Simulation Training Market
Simulation and Training
North America Simulator Windows and Simulator Skylights Market
Simulation and Training
Trainer Aircraft Market
Simulation and Training
Helicopter Simulator Market
Simulation and Training
Military Simulation and Training Market
Simulation and Training
Global Ship Bridge Simulators Market