
 Digital Radiosonde Market | 2026-2036
Digital Radiosonde Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Radiosonde Market Insights
Chinese sensor manufacturers is repositioning to capture share in the mid-tier radiosonde segment as domestic meteorological bureaus expand sounding station networks. Vaisala leverages its Finland-based R&D campus to sustain technology leadership in GPS-enabled weather balloon systems. GRAW Radiosondes anchors its competitive position through specialized ground station equipment that dominates European national weather services procurement.
A digital radiosonde is a balloon-borne atmospheric sensing instrument that measures pressure, temperature, humidity, and wind velocity via GPS tracking, transmitting data to ground receivers at frequencies near 400 MHz for numerical weather prediction assimilation. Weather balloon systems occupy the largest value pool given their irreplaceable role in synoptic-scale forecasting, while unmanned aerial vehicle platforms represent the fastest-growing product category as drone-based profiling reduces per-observation costs below traditional balloon launches. Sensor modules command premium margins where multi-parameter miniaturization enables hybrid platforms.
FCC spectrum allocation rules in the United States constrain transmitter frequency bands for radiosonde operations, while China's GB standards and MEE atmospheric monitoring directives mandate domestic certification for equipment deployed in national climate networks. EASA coordination with European meteorological agencies harmonizes radiosonde performance specifications across EU member states under WMO guidelines. Stakeholders must weigh regulatory compliance timelines against the pace of RF communication technology refresh cycles.
Market Dynamics
Meteorological agencies are replacing legacy analog radiosondes with GPS-enabled digital units, compressing replacement cycles from decade-long intervals to five-year technology refresh mandates driven by WMO data quality standards.
Growth Catalysts
- China's dual carbon goals:The MEE atmospheric monitoring directives mandate denser upper-air observation networks, accelerating procurement of IoT-connected sensor modules for climate data collection.
- 400 MHz transmitter miniaturization:Advances in RF power efficiency enable lighter balloon payloads, extending flight duration and reducing helium consumption per sounding.
- Numerical weather prediction assimilation:Meteorological bureaus demand higher vertical resolution data, pulling investment toward multi-parameter sensor fusion platforms.
Market Restraints
- Helium supply concentration:Three countries control 75% of global helium extraction, exposing balloon launch operations to input cost volatility and export quota disruptions.
- FCC spectrum allocation friction:United States transmitter licensing constraints limit operational flexibility for research institutions deploying experimental radiosonde configurations.
- Ground station capital intensity:Spaced-based augmentation systems require substantial receiver network investment, creating barriers for smaller national weather services.
Strategic Opportunities
- Drone-based atmospheric profiling:Unmanned aerial vehicle platforms enable on-demand soundings below 3 km altitude, opening service contracts with agricultural and renewable energy sectors.
- India's PLI scheme extension:Domestic manufacturing incentives for precision instruments create localization pathways for sensor module assembly.
- AI-driven forecast validation:Machine learning assimilation of radiosonde data creates demand for higher-frequency launch protocols in severe weather corridors.
Industry Challenges
- RF engineer scarcity:Specialized expertise in 400 MHz antenna design concentrates in defense and telecommunications sectors, constraining radiosonde OEM hiring pipelines.
- GB standards certification timelines:China's mandatory equipment testing for national climate networks extends product approval cycles by 8-14 months.
- Legacy analog ground station integration:Hybrid receiver architectures complicate firmware updates and create interoperability failures during phased digital transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Radiosonde Market |
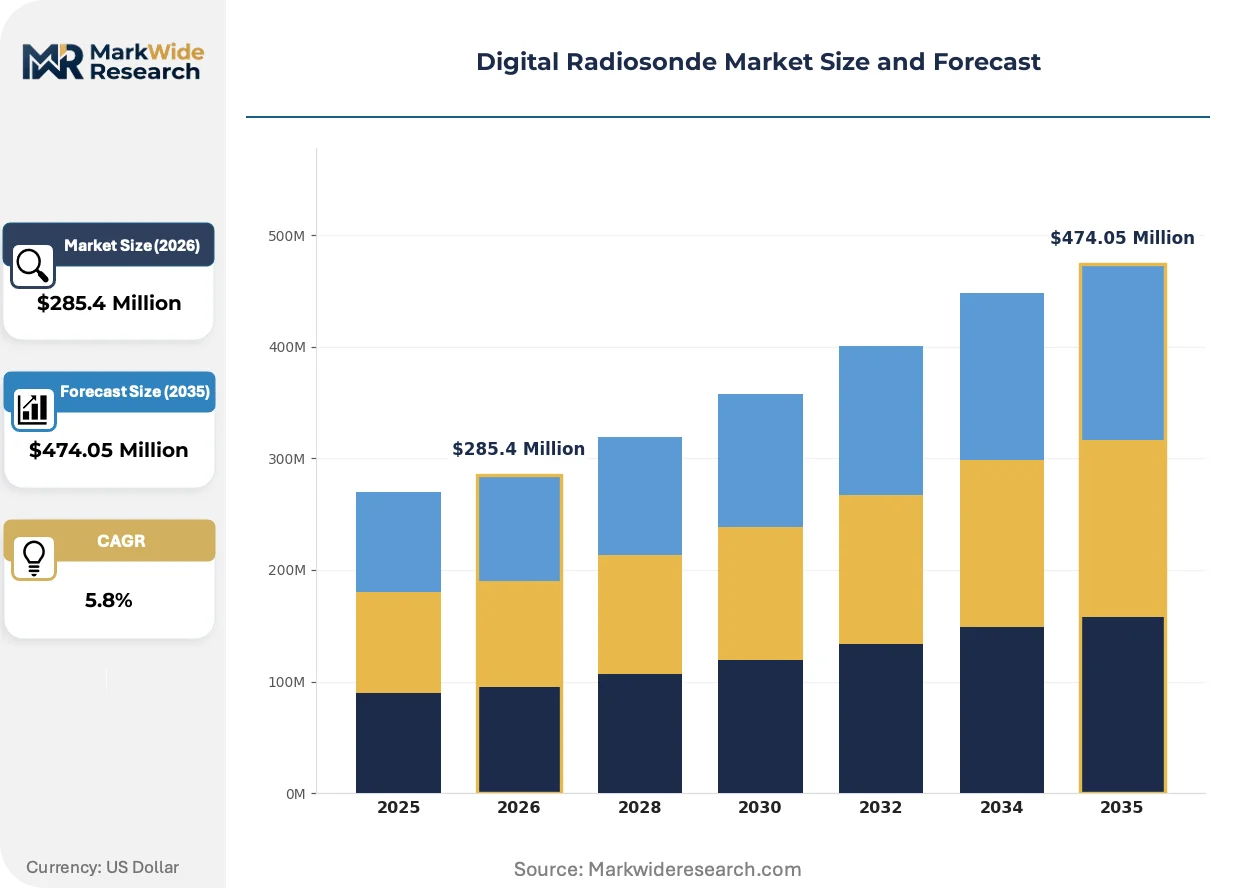
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unmanned Aerial Vehicle, Weather Balloon, Sensor Module, Ground Station End User: Meteorological Agencies, Research Institutions, Aviation Authorities, Educational Institutions Technology: GPS, Bluetooth, RF Communication, IoT Connectivity Application: Weather Forecasting, Climate Research, Atmospheric Studies, Disaster Management |
| Companies Covered | Vaisala, GRAW Radiosondes, InterMet Systems, Meteomodem, Meisei Electric, Lockheed Martin, Meteolabo, Innovative Sensor Technology (IST), Shanghai Changwang, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Radiosonde Market Trends and Innovations
Autonomous launch systems and edge-computing sensor architectures are compressing the interval between observation and forecast assimilation, reshaping how meteorological agencies prioritize capital allocation.
MEMS-based barometric pressure sensors are automating calibration procedures that previously required manual ground-based verification. Japan's meteorological agency has adopted these modules for Pacific typhoon monitoring stations, cutting pre-launch preparation from 45 minutes to under 10 minutes. This compression is automating shift staffing models at remote sounding facilities.
REACH substance restrictions on battery chemistries are forcing lithium-thionyl chloride cell redesigns for European radiosonde deployments. Manufacturers must substitute restricted electrolyte formulations while maintaining cold-temperature performance to -80°C. The F-Gas Regulation's phase-down of sulfur hexafluoride is simultaneously pressuring tracer gas alternatives for wind measurement validation.
Meteorological bureaus are consolidating procurement through framework agreements that bundle radiosonde supply with multi-year ground station maintenance. Australia's Bureau of Meteorology pioneered this model, displacing transactional spot purchasing with performance-guaranteed service contracts. Defense ministries in NATO countries are replicating this structure for battlefield weather support units.
Digital Radiosonde Market Segmentation
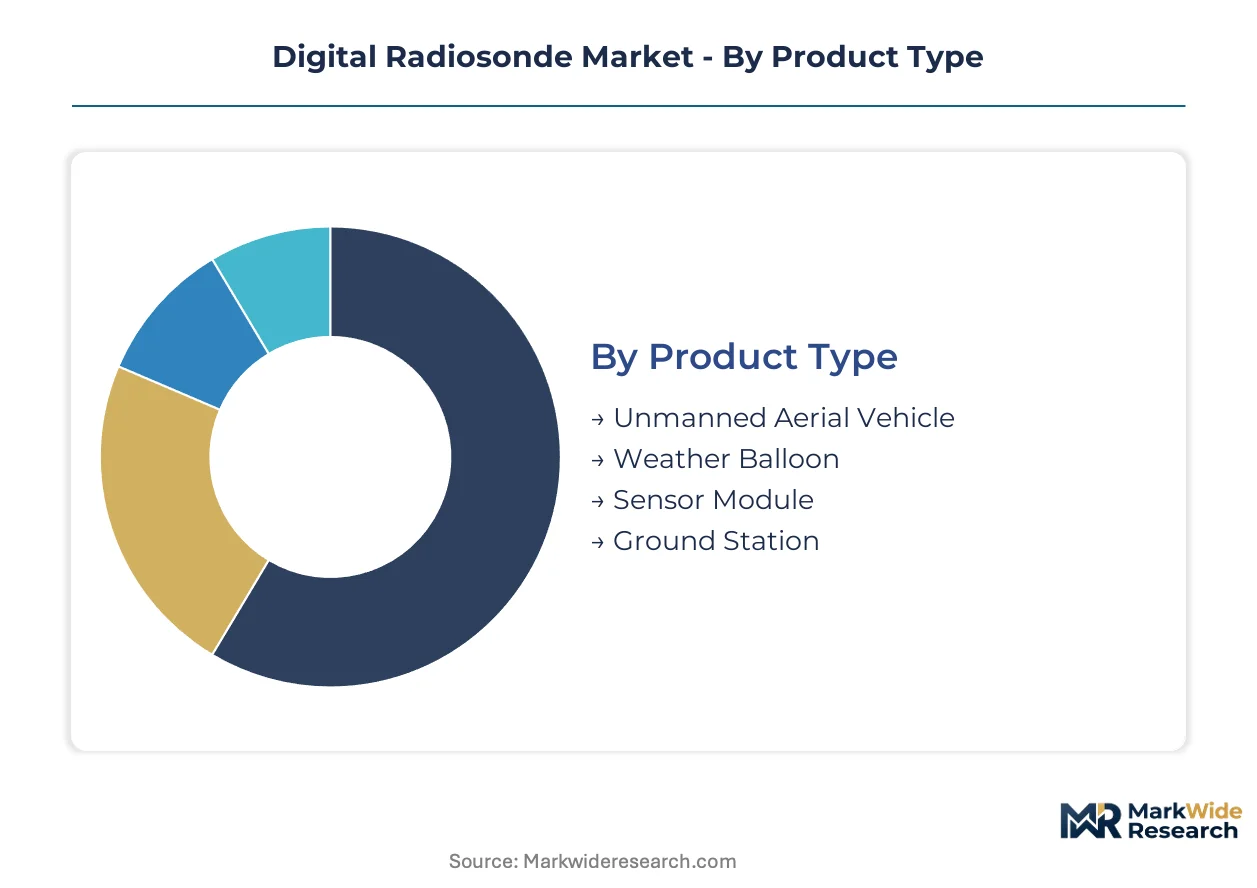
Segmentation in the digital radiosonde market reveals distinct technology-performance-cost tradeoffs across deployment platforms. Procurement patterns diverge sharply between national meteorological networks prioritizing measurement precision and research institutions optimizing for experimental flexibility.
Product Type:
GPS-enabled transmitter miniaturization and payload weight constraints define competitive positioning across balloon-borne and alternative platforms.
- Weather Balloon:Balloon-borne systems carry multi-parameter sensor packages to stratospheric altitudes exceeding 30 km, transmitting pressure-temperature-humidity-wind data via 400 MHz RF links. China's MEE atmospheric monitoring directives are accelerating procurement of IoT-connected modules for climate data collection through denser sounding station networks.
- Sensor Module:Miniaturized multi-parameter sensing units enable hybrid deployment across balloon and drone platforms, commanding premium margins where MEMS-based barometric pressure sensors automate calibration procedures. Japan's meteorological agency has adopted these modules for Pacific typhoon monitoring stations, cutting pre-launch preparation from 45 minutes to under 10 minutes.
- Unmanned Aerial Vehicle:Drone-based profiling reduces per-observation costs below traditional balloon launches for boundary-layer measurements below 3 km altitude.
- Ground Station:Receiver networks for data acquisition and processing require substantial capital investment, creating procurement barriers for smaller national weather services.
Weather balloon systems lead on scale; unmanned aerial vehicle platforms lead on momentum.
End User:
Procurement authority and budget cycles create diverging specification requirements across institutional categories.
- Meteorological Agencies:National weather services operate the densest sounding networks, mandating WMO-compliant data quality standards and five-year technology refresh cycles. Australia's Bureau of Meteorology pioneered framework agreements bundling radiosonde supply with multi-year ground station maintenance, displacing transactional spot purchasing.
- Research Institutions:Experimental deployments prioritize transmitter frequency flexibility for atmospheric chemistry and boundary-layer physics studies. FCC spectrum allocation rules in the United States constrain operational flexibility for research institutions deploying experimental radiosonde configurations.
- Aviation Authorities:Upper-air observation data supports terminal area forecasts and flight path optimization for commercial aviation corridors.
- Educational Institutions:University atmospheric science programs operate lower-cost training deployments with reduced altitude and precision requirements.
Meteorological agencies dominate procurement volume; research institutions drive specification innovation.
Technology:
RF communication architectures and positioning systems determine measurement accuracy and operational range.
- GPS:Satellite-based wind velocity calculation via position differencing has displaced traditional radar tracking, enabling lighter payloads and autonomous launch systems. Vaisala leverages its Finland-based R&D campus to sustain technology leadership in GPS-enabled weather balloon systems.
- RF Communication:400 MHz transmitter designs balance atmospheric penetration with spectrum licensing constraints across regulatory jurisdictions. FCC spectrum allocation friction limits operational flexibility for experimental configurations in the United States.
- IoT Connectivity:Cellular and satellite backhaul integration enables real-time data streaming for severe weather monitoring and AI-driven forecast validation protocols.
- Bluetooth:Short-range wireless supports ground-based sensor configuration and pre-launch diagnostics within 100-meter proximity.
GPS anchors measurement accuracy; IoT connectivity is climbing the fastest for real-time assimilation.
Application:
Data product requirements and launch frequency protocols vary across operational and research objectives.
- Weather Forecasting:Synoptic-scale numerical weather prediction assimilation demands twice-daily soundings at 00Z and 12Z UTC, driving the largest installed base of operational systems. GRAW Radiosondes anchors its competitive position through specialized ground station equipment that dominates European national weather services procurement.
- Climate Research:Long-term trend detection requires instrument stability and inter-calibration across decadal observation records. REACH substance restrictions on battery chemistries are forcing lithium-thionyl chloride cell redesigns for European radiosonde deployments.
- Atmospheric Studies:Process-scale research targets specific phenomena including typhoon intensification and urban heat island dynamics.
- Disaster Management:Rapid deployment protocols for tropical cyclone landfall and wildfire smoke transport require mobile launch capabilities and expedited procurement channels.
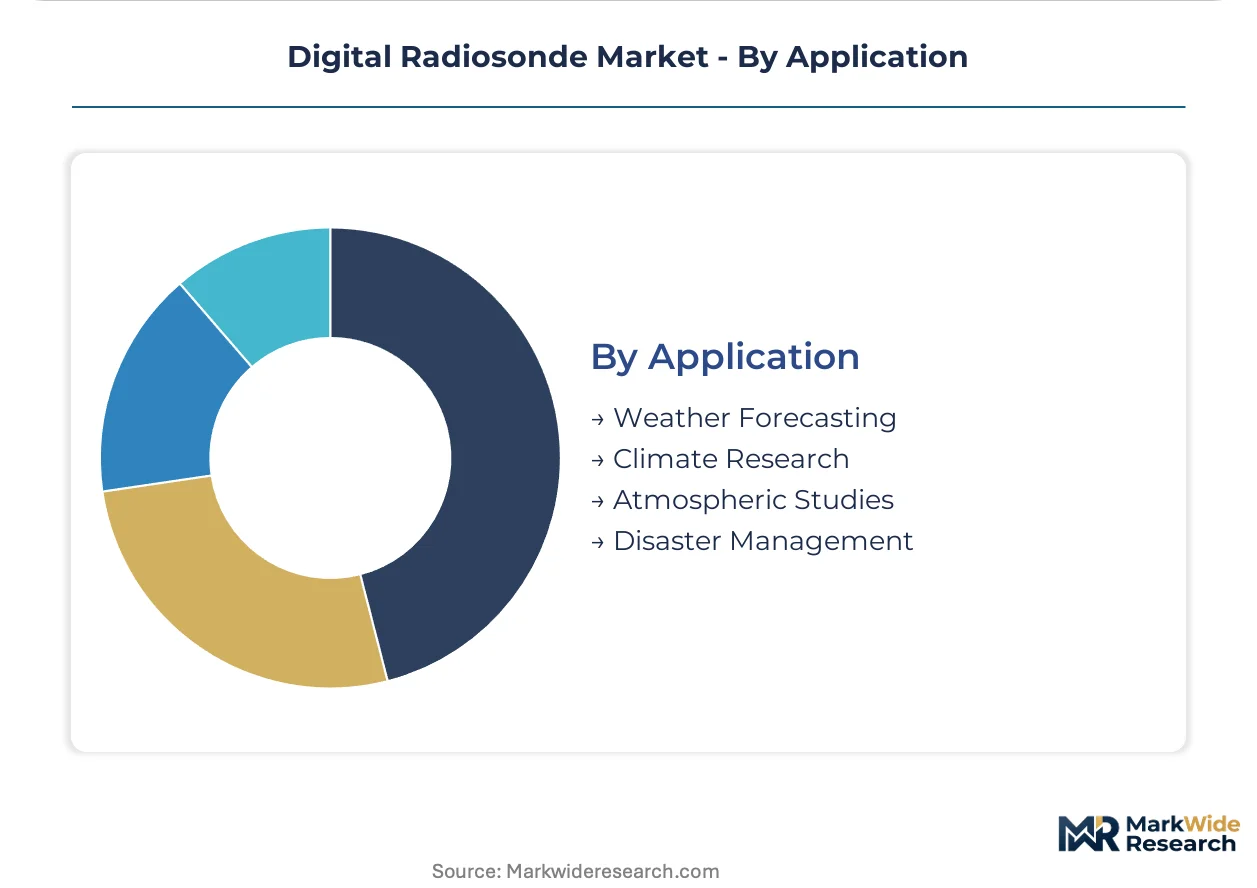
Weather forecasting commands the largest value pool; climate research imposes the most stringent stability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate sensor module assembly to jurisdictions with streamlined certification pathways. Compliance cost differentials between MEE-mandated testing regimes and FCC spectrum licensing frameworks are accelerating facility migration decisions.
China
Domestic meteorological bureaus are densifying upper-air observation networks under dual carbon monitoring mandates. GB standards certification and MEE atmospheric monitoring directives require 8-14 month equipment approval cycles. Manufacturing clusters in Shanghai and the Yangtze River Delta are scaling IoT-connected sensor module output for climate data collection infrastructure.
United States
Research institutions and NOAA facilities drive procurement for GPS-enabled balloon systems with experimental transmitter flexibility. FCC spectrum allocation rules constrain operational bandwidth near 400 MHz for non-commercial deployments. Ground station receiver networks concentrate in Colorado and the Great Plains corridor, supporting severe weather monitoring protocols.
Germany
EASA coordination with national weather services harmonizes radiosonde specifications under WMO guidelines across EU member states. REACH substance restrictions and F-Gas Regulation phase-downs are forcing battery chemistry redesigns and tracer gas substitutions. Industrial activity clusters in Bavaria and Baden-Württemberg host specialized ground station equipment fabrication.
Japan
METI-funded Pacific typhoon monitoring programs are adopting MEMS-based barometric pressure sensors for automated calibration. JIS standards govern equipment interoperability with regional meteorological networks. Manufacturing and R&D activity concentrates in the Kanto region around Tokyo, where pre-launch preparation times have compressed from 45 minutes to under 10 minutes.
Australia
The Bureau of Meteorology pioneered framework agreements bundling radiosonde supply with multi-year ground station maintenance, displacing transactional procurement. TGA-equivalent equipment safety assessments apply to battery and transmitter configurations. Operational infrastructure concentrates in New South Wales and Victoria, supporting synoptic-scale forecasting for aviation and agriculture sectors.
Digital Radiosonde Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue drone-based profiling and AI-driven forecast validation services. The supplier base concentrates around three capability clusters: GPS-enabled transmitter specialists, ground station equipment fabricators, and MEMS sensor miniaturization houses. Competitive positioning hinges on RF power efficiency advances and helium consumption reduction per sounding. Dominant moves include framework agreement bundling with multi-year maintenance contracts and backward integration into sensor module assembly.
Among Finland-based technology developers, Vaisala anchors premium-tier positioning through sustained R&D investment in GPS-enabled weather balloon systems. German specialist GRAW Radiosondes exemplifies the ground station equipment archetype, securing European national weather services procurement through specialized receiver network solutions. Chinese manufacturer Shanghai Changwang represents the mid-tier repositioning strategy, capturing share as domestic meteorological bureaus expand sounding station networks under MEE directives.
| Leading Market Players |
|---|
| Vaisala |
| GRAW Radiosondes |
| InterMet Systems |
| Meteomodem |
| Meisei Electric |
| Lockheed Martin |
| Meteolabo |
| Innovative Sensor Technology (IST) |
| Shanghai Changwang |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between MEE-mandated GB standards equipment and research-grade experimental units manifests in both pricing stratification and supply chain geography. Premium-tier GPS-enabled radiosondes with IoT backhaul command substantial margins through bundled ground station maintenance contracts, while mid-tier sensor modules face cost compression as Chinese manufacturers scale MEMS barometric pressure sensor output for domestic meteorological bureaus.
Pricing Analysis
Direct-to-OEM discounts dominate procurement for national weather services bundling multi-year ground station maintenance with radiosonde supply, displacing distributor markups. Three-tier pricing structure across premium, standard, and economy levels separates WMO-certified GPS-enabled systems from research-grade experimental configurations and educational training deployments. Pricing pressure stems from helium supply concentration in Qatar, Algeria, and the United States exposing balloon launch operations to input cost volatility. Agricultural cooperatives and renewable energy developers represent the most price-sensitive buyer segment, while defense ministries demonstrate lowest sensitivity given mission-critical requirements.
Supply Chain Analysis
Air freight costs for lithium-thionyl chloride battery cells from Japan and specialized 400 MHz RF components from Germany concentrate supply risk in Shanghai and Yangtze River Delta manufacturing clusters. Raw material dependencies span helium extraction from Qatar, MEMS sensor wafers from Taiwan, and precision GPS modules from Finland. Single-source vulnerability in helium supply creates exposure to export quota disruptions from the three countries controlling extraction. Distribution runs through framework agreements with meteorological agencies rather than spot-market transactions, locking in volume commitments and service-level guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between China's extended GB standards certification timelines and Australia's streamlined TGA-equivalent assessments, with 8-14 month approval differentials creating first-mover advantages for manufacturers relocating sensor module assembly.
For Market Incumbents: Lock in framework agreement renewals with European national weather services before REACH substance restrictions force battery chemistry redesigns that disrupt lithium-thionyl chloride cell supply. Deepen backward integration into MEMS barometric pressure sensor fabrication to defend margin position against Chinese mid-tier entrants scaling IoT-connected module output. Prioritize R&D investment in autonomous launch systems that compress pre-launch preparation intervals below 10 minutes, matching Japan's Pacific typhoon monitoring station performance. For New Entrants and Emerging Players: Agricultural cooperatives seeking boundary-layer data below 3 km altitude represent the most penetrable buyer archetype, underserved by balloon-borne systems optimized for stratospheric profiles. Drone-based atmospheric profiling service contracts bypass capital-intensive ground station investment while delivering per-observation cost advantages. Target India's PLI scheme extension for precision instrument manufacturing to establish localized sensor module assembly with domestic certification pathways. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized ground station equipment fabricators possessing EASA-harmonized receiver network solutions across EU member states. Long-term viability hinges on WMO data quality standard refresh cycles compressing replacement intervals from decade-long spans to five-year mandates. Watch for AI-driven forecast validation protocols triggering higher-frequency launch requirements in severe weather corridors as the inflection signal for sensor fusion platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Framework Agreement Bundling | Australia's Bureau of Meteorology pioneered multi-year maintenance contracts that displace spot purchasing across national weather services. |
| MEMS Sensor Miniaturization | Japan's meteorological agency adoption of automated calibration modules cuts pre-launch preparation from 45 minutes to under 10 minutes. |
| Drone-Based Profiling Services | Unmanned aerial vehicle platforms reduce per-observation costs below traditional balloon launches for agricultural and renewable energy sectors. |
| REACH-Compliant Battery Redesign | European manufacturers must substitute restricted lithium-thionyl chloride electrolyte formulations while maintaining cold-temperature performance to -80°C. |
| GB Standards Certification Investment | China's MEE atmospheric monitoring directives mandate 8-14 month equipment approval cycles that advantage domestic manufacturers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with meteorological agency procurement officers, RF communication engineers at transmitter manufacturers, ground station equipment fabricators, and atmospheric research scientists with secondary validation against WMO data quality standard documentation, FCC spectrum allocation filings, MEE atmospheric monitoring directive texts, and EASA coordination frameworks with European national weather services. Bottom-up unit economics for balloon launch operations and sensor module bill-of-materials were triangulated against top-down meteorological bureau budget allocation data across the analysis window.
Historical reference periods anchored volume and value projections through the forecast horizon, with segmentation modeling across product type, end user, technology, and application dimensions plus altitude capability tier as an industry-specific stratifier. CAGRs were derived from logistic diffusion curves fitted to GPS-enabled transmitter adoption rates and helium consumption trajectories per sounding. Forecast inputs incorporated WMO technology refresh cycle mandates, China's dual carbon monitoring infrastructure buildout schedules, and REACH substance restriction implementation timelines.
Underlying measurement precision varies by segment; weather forecasting and climate research applications carry tighter precision than educational training deployments given synoptic-scale assimilation requirements. Forecasts reflect assumptions about helium supply stability, GB standards certification timeline consistency, and RF engineer hiring pipeline depth that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Aircraft Interface Device Market
Aircraft Navigation and Communication
Global Flight Navigation System Market
Aircraft Navigation and Communication
Middle-East and Africa Air Traffic Management Market
Aircraft Navigation and Communication
Defense Advanced GPS Receiver (DAGR) Market
Aircraft Navigation and Communication
Connected Aircraft Market
Aircraft Navigation and Communication
Europe Inertial Systems Market
Aircraft Navigation and Communication
America Air Traffic Management Market
Aircraft Navigation and Communication
Airborne Telemetry Market
Aircraft Navigation and Communication
Ground to Air on-Board Connectivity Market
Aircraft Navigation and Communication
Asia-Pacific VHF Air-Ground Communication Stations Market
Aircraft Navigation and Communication
Electronic Navigational Charts (ENC) Market
Aircraft Navigation and Communication
Global Aviation Mapping Software Market
Aircraft Navigation and Communication
Air-Based Tactical Data Link Market
Aircraft Navigation and Communication
Asia-Pacific Air Traffic Management Market
Aircraft Navigation and Communication
Aircraft Navigation Software Market
Aircraft Navigation and Communication
Europe Air Traffic Management Market