
 5G Adoption Analysis in Aviation Market | 2026-2036
5G Adoption Analysis in Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
5G Adoption Analysis in Aviation Market Insights
Market Context with Strategic Players
Commercial airlines is decoupling from traditional Ku-band satellite systems as passenger expectations for seamless broadband shift procurement priorities. Huawei leverages its massive MIMO patent portfolio to anchor ground station infrastructure bids across Asia-Pacific. Ericsson competes through end-to-end network slicing architectures purpose-built for airport densification. Nokia differentiates with private 5G deployments targeting remote tower operations in Nordic aviation clusters.
Technical Definition and Structural Segments
5G adoption in aviation denotes the integration of fifth-generation cellular networks operating across sub-6 GHz and millimeter wave spectrum bands to enable ultra-reliable low-latency communication for aircraft, ground infrastructure, and air traffic management systems. Massive MIMO antenna arrays with beamforming capabilities allow ground stations to track aircraft at approach speeds exceeding 250 knots while maintaining sub-10 millisecond latency for safety-critical data links. Standalone 5G architectures are capturing the fastest expansion trajectory as aviation regulators certify network-isolated slices for air traffic control independent of public consumer traffic. In-flight connectivity applications currently occupy the largest value pool, though predictive maintenance segments are deepening as airlines deploy continuous sensor telemetry through 5G backhaul to reduce unplanned engine shop visits.
Regulatory Frame and Forward-Looking Close
The FAA's C-band interference assessment protocols, alongside the FCC's aviation spectrum coordination rules and the EU's F-Gas Regulation impacting ground station cooling infrastructure, collectively shape deployment cadence and equipment certification requirements. EASA's cyber-resilience mandates for connected aircraft systems are forcing avionics suppliers to embed 5G modem architectures with hardware-rooted security from initial design phases. Stakeholders must monitor spectrum auction outcomes in Brazil and India, where national regulators are finalizing aviation-specific 5G guard bands that will determine vendor market access and retrofit timing for international fleet operators.
Market Dynamics
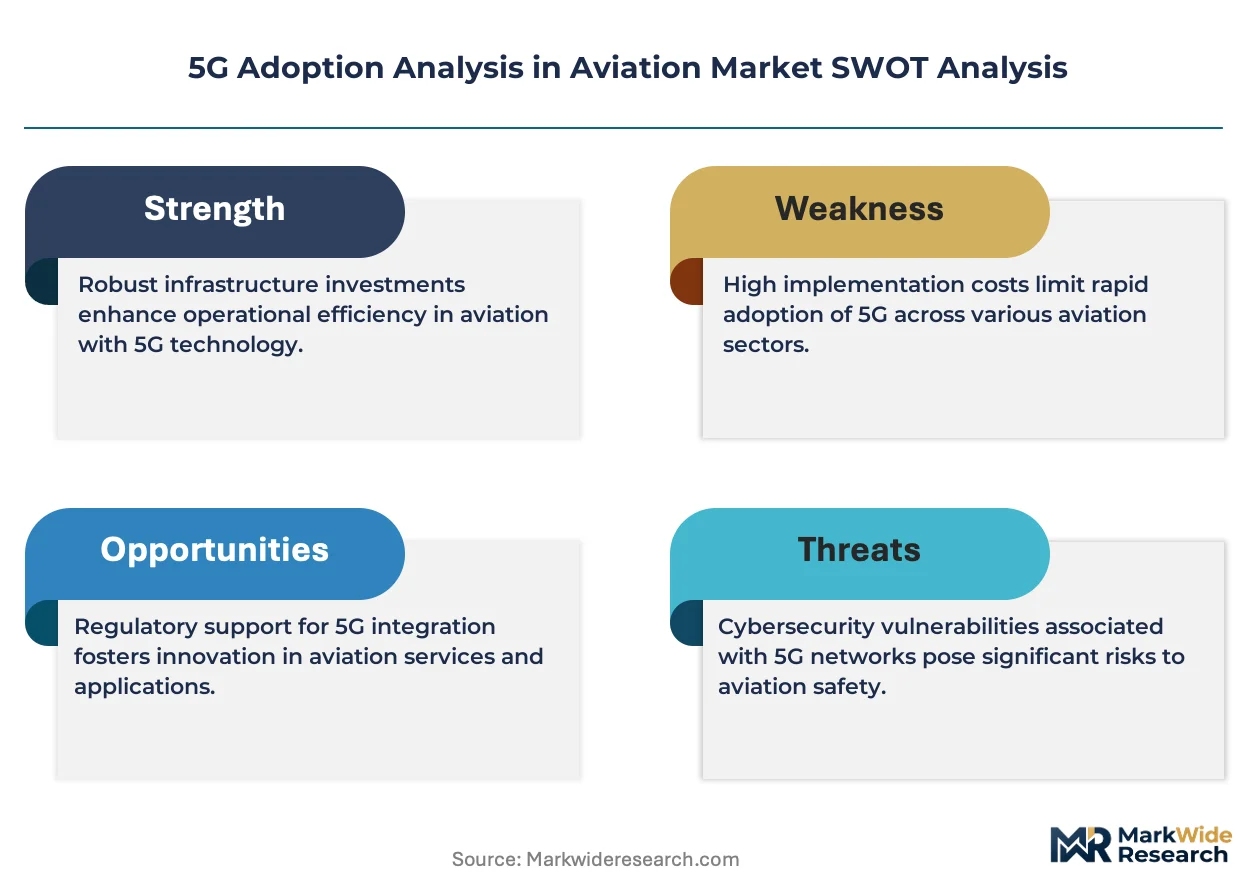
Airlines are abandoning legacy satellite dependency as passenger broadband expectations force a wholesale infrastructure rebuild toward cellular-based connectivity architectures. This structural decoupling from Ku-band systems concentrates capital deployment around ground station densification and aircraft retrofit programs.
Growth Catalysts
- Massive MIMO beamforming:Ground stations now track aircraft at approach speeds exceeding 250 knots while maintaining sub-10 millisecond latency for safety-critical data links. Aviation regulators are certifying these arrays for terminal area operations.
- FAA C-band allocation:Updated spectrum frameworks near airports are unlocking deployment timelines previously blocked by interference concerns. Airlines are accelerating fleet retrofit schedules in response.
- Predictive maintenance telemetry:Continuous sensor backhaul through 5G networks is reducing unplanned engine shop visits. Maintenance operations are capturing operational savings from real-time health monitoring.
Market Restraints
- Aviation-grade hardware costs:Certified 5G modem architectures with hardware-rooted security embed substantial premiums over consumer-grade alternatives. Avionics suppliers are absorbing design-phase cost inflation.
- Ground station cooling infrastructure:The EU's F-Gas Regulation is constraining equipment choices for dense airport deployments. Infrastructure providers are navigating refrigerant compliance complexity.
- Millimeter wave propagation limits:Rain fade and atmospheric absorption degrade signal reliability above 24 GHz during critical approach phases. Network architects are defaulting to sub-6 GHz for safety-critical links.
Strategic Opportunities
- Remote tower operations:Private 5G deployments are enabling centralized air traffic services for multiple small airports from single facilities. Nordic aviation clusters are piloting these architectures.
- Brazil spectrum finalization:National regulators are establishing aviation-specific 5G guard bands that will determine vendor market access. International fleet operators are monitoring auction outcomes for retrofit timing.
- Network slicing convergence:Standalone architectures are isolating air traffic control traffic from public consumer networks. Regulators are certifying these slices for operational independence.
Industry Challenges
- EASA cyber-resilience compliance:Connected aircraft mandates are forcing hardware-rooted security embedding from initial design phases. Avionics development cycles are extending to accommodate certification requirements.
- Legacy system integration:Aircraft with decades-old avionics bus architectures require gateway retrofits to interface with 5G modems. Engineering resources are concentrating on interoperability testing.
- Specialized RF engineering talent:The intersection of aviation safety culture and cellular network deployment expertise remains shallow. Workforce development is lagging deployment demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Adoption Analysis in Aviation Market |
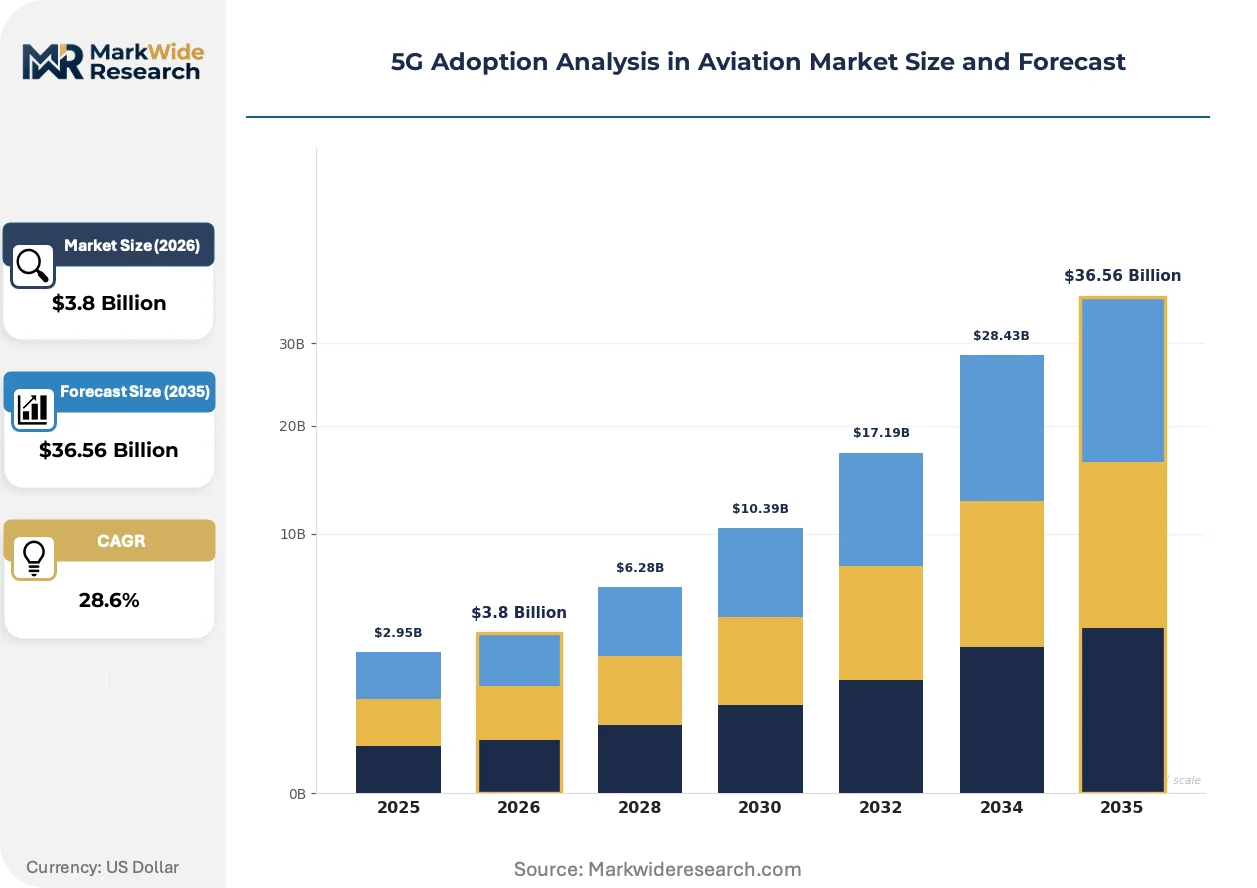
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Standalone 5G, Non-Standalone 5G, Millimeter Wave, Sub-6 GHz, Massive MIMO Application: In-Flight Connectivity, Air Traffic Management, Predictive Maintenance, Airport Operations, Cargo Tracking Deployment: Onboard Aircraft, Ground Stations, Remote Towers, Control Centers, Passenger Terminals End User: Commercial Airlines, General Aviation Operators, Maintenance Providers, Airport Authorities, Government Agencies |
| Companies Covered | Huawei, Ericsson, Nokia, Qualcomm, Vodafone, AT&T, Verizon, Airbus, Thales, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Adoption Analysis in Aviation Market Trends and Innovations
Cellular network architectures are displacing satellite dependency as the default connectivity backbone for commercial aviation, compressing procurement cycles and reshaping vendor competitive dynamics around latency performance rather than coverage footprint.
Massive MIMO antenna arrays with dynamic beamforming capabilities are converging with aircraft tracking requirements to enable ground-to-air links at speeds exceeding 250 knots. Airlines operating high-density routes are prioritizing these systems for terminal area connectivity. The technology is converging with predictive maintenance platforms to enable continuous engine telemetry without satellite latency penalties.
The FAA's updated C-band interference assessment protocols are mandating revised power limits and guard band configurations for ground stations near runway thresholds. Equipment manufacturers are redesigning filter architectures to meet these specifications. In-flight connectivity providers serving US-registered fleets are absorbing certification delays while awaiting final rulemaking.
Airline technology procurement is consolidating around latency-based performance specifications rather than coverage-area metrics. Chief information officers are rewriting connectivity RFPs to prioritize millisecond-grade responsiveness for operational applications. This specification shift is most visible among US major carriers accelerating narrow-body fleet retrofits.
5G Adoption Analysis in Aviation Market Segmentation
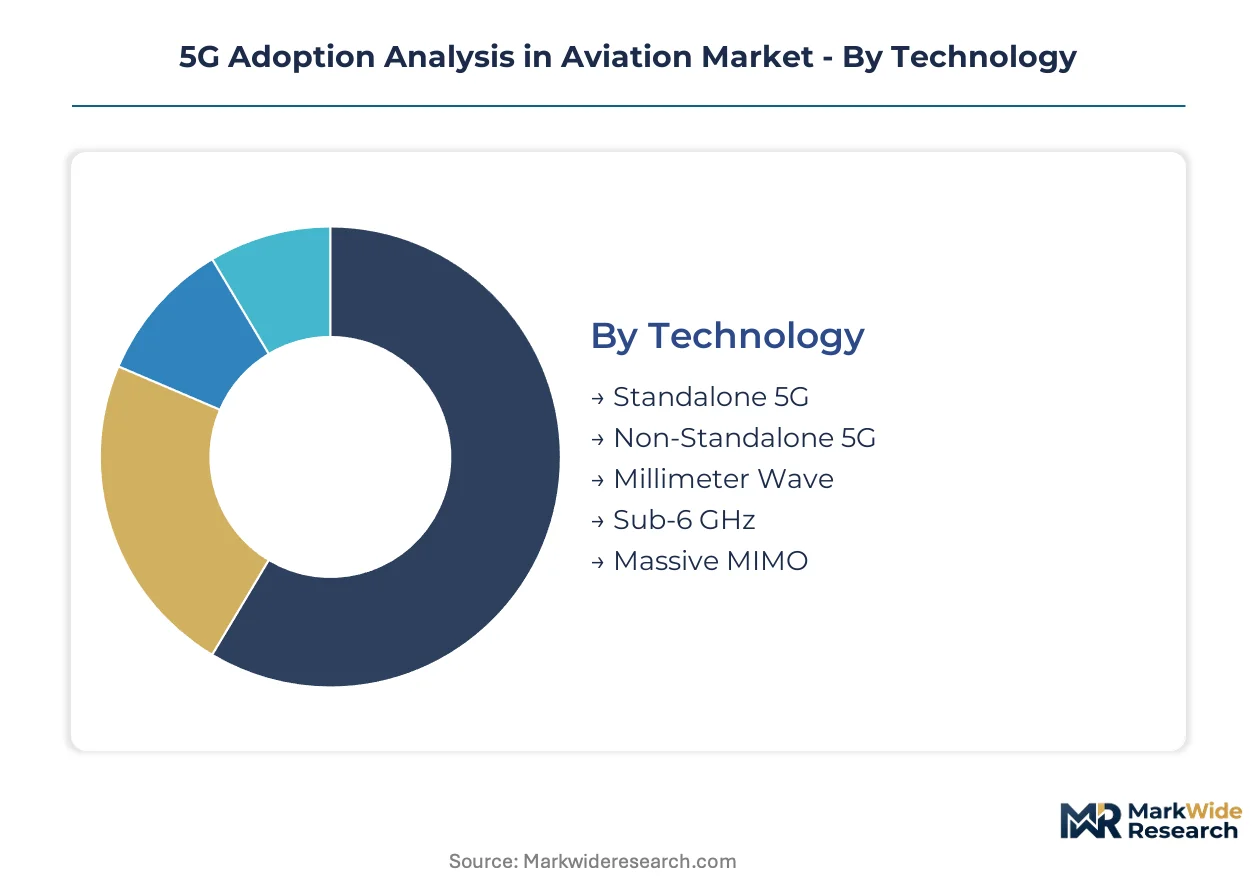
Capital deployment patterns in aviation 5G diverge sharply across technology maturity curves and regulatory certification requirements. Procurement committees weight latency specifications against retrofit complexity when allocating fleet modernization budgets across segment categories.
Technology:
Capital intensity clusters around spectrum licensing and antenna infrastructure, with millimeter wave deployments demanding the densest ground station networks.
- Standalone 5G:Network-isolated architectures operate independently of legacy 4G core infrastructure. EASA certification timelines for air traffic control slices are accelerating airline procurement in Germany and France.
- Massive MIMO:Beamforming arrays with 64+ antenna elements track aircraft through terminal areas. US major carriers prioritize these systems for high-density hub operations where approach speeds exceed 250 knots.
- Non-Standalone 5G:Dual-connectivity modes anchor to existing LTE cores for transitional deployments. Regional operators in India leverage this architecture to defer full core upgrades.
- Millimeter Wave:24-71 GHz spectrum enables multi-gigabit throughput for passenger broadband. Rain fade susceptibility limits deployment to dry-climate airports in the southwestern United States and Gulf states.
- Sub-6 GHz:Mid-band spectrum balances coverage radius with propagation resilience. The FAA's C-band allocation framework is unlocking deployment near runway thresholds previously blocked by interference concerns.
Massive MIMO absorbs the bulk of installed capacity; Standalone 5G is expanding most quickly as regulators certify network slices for operational independence.
Application:
Revenue concentration follows passenger-facing services, though operational applications are deepening retrofit penetration through maintenance cost savings.
- In-Flight Connectivity:Passenger broadband services dominate procurement volumes. US carriers are accelerating narrow-body fleet retrofits as Ku-band contracts expire.
- Predictive Maintenance:Continuous engine telemetry through 5G backhaul reduces unplanned shop visits. Rolls-Royce and GE Aviation are embedding modem architectures in next-generation engine monitoring units.
- Air Traffic Management:Ground-to-air data links replace legacy VHF for trajectory management. Eurocontrol trials in the Netherlands are validating latency performance for separation assurance.
- Airport Operations:Apron vehicle tracking and gate management systems leverage private 5G deployments. Changi Airport's autonomous baggage tractor fleet operates on dedicated network slices.
- Cargo Tracking:Real-time cold chain monitoring for pharmaceutical shipments. Emirates SkyCargo has deployed sensor networks across its Dubai hub freighter fleet.
In-Flight Connectivity commands the largest share of airline technology budgets; Predictive Maintenance is climbing the fastest as engineering departments quantify operational savings.
Deployment:
Physical infrastructure requirements vary from airborne certification complexity to ground-based densification economics.
- Ground Stations:Dense antenna arrays along approach corridors require real estate negotiations with airport authorities. FAA power limit regulations are forcing filter redesigns for installations near runway thresholds.
- Onboard Aircraft:Radome-integrated modem units demand supplemental type certification for each airframe. Boeing and Airbus are pre-certifying 5G architectures on new production lines.
- Remote Towers:Centralized air traffic services for multiple small airports from single facilities. Norway's Avinor operates remote tower centers serving 15 regional airports from Bodo.
- Control Centers:En-route and oceanic airspace management through 5G backhaul. NATS in the United Kingdom is upgrading its Swanwick center with network-sliced connectivity.
- Passenger Terminals:Public network densification for traveler connectivity and operational applications. Incheon International Airport has deployed private 5G for biometric passenger processing.
Ground Stations represent the heaviest capital deployment; Remote Towers are gaining share fastest as Nordic aviation clusters prove centralized service models.
End User:
Procurement authority and budget cycles diverge between fleet operators and infrastructure authorities.
- Commercial Airlines:Fleet-wide retrofit programs driven by passenger experience competition. Delta, United, and American Airlines have announced 5G connectivity mandates for narrow-body fleets.
- Airport Authorities:Ground infrastructure investment through passenger facility charges and operational savings. Heathrow Airport's 5G densification program spans terminals and apron areas.
- Maintenance Providers:Third-party MRO adoption of predictive maintenance platforms. Lufthansa Technik is integrating 5G telemetry into its Engine Health Monitoring service offerings.
- General Aviation Operators:Business jet and helicopter retrofit demand concentrated in long-range aircraft. Gulfstream and Bombardier are offering 5G connectivity as factory options on new deliveries.
- Government Agencies:Military and coast guard aviation applications with hardened security requirements. The US Coast Guard is evaluating 5G for search and rescue coordination networks.
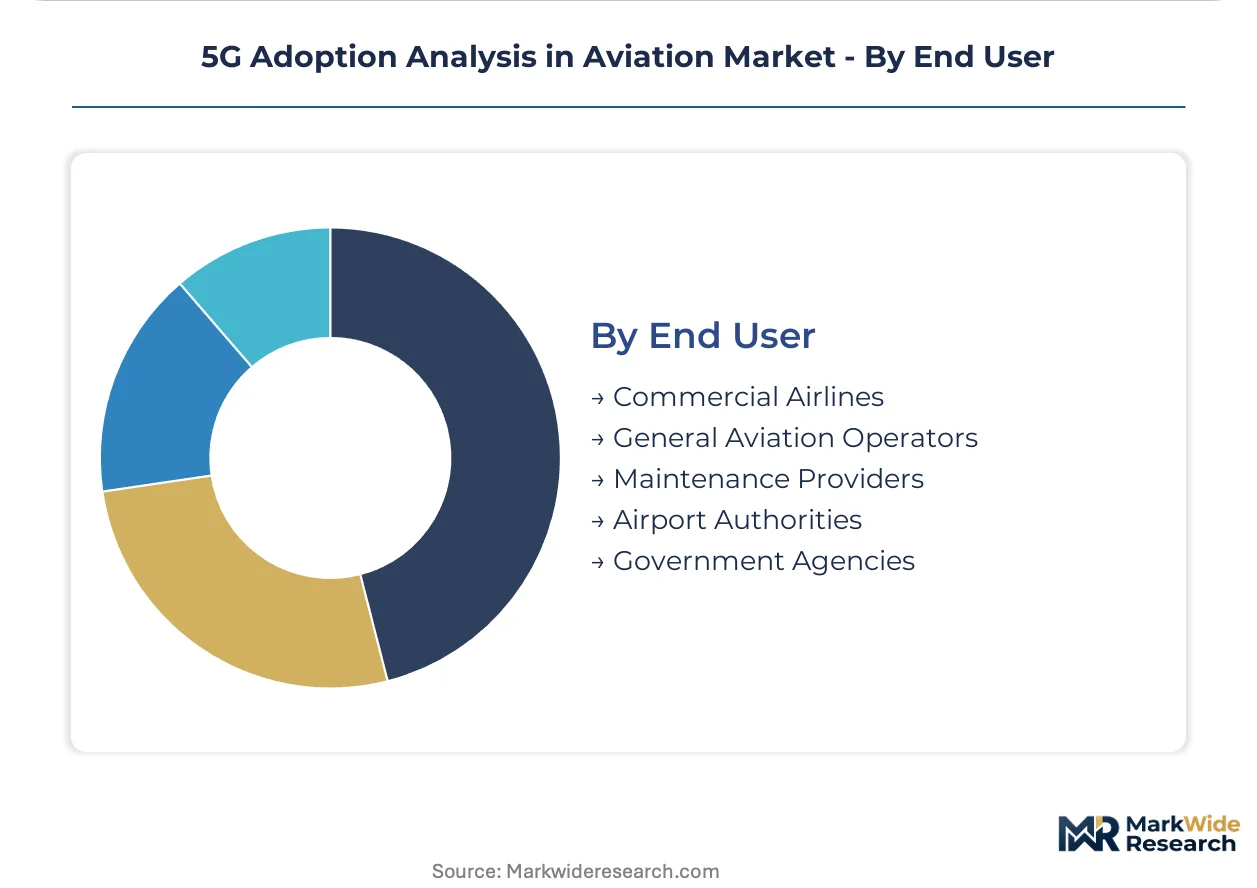
Commercial Airlines direct the largest share of end-user spending; Airport Authorities are expanding most quickly as infrastructure funding mechanisms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aviation 5G deployment clusters around special economic zones offering infrastructure tax incentives, with ground station densification concentrating near hub airports in the United States, Germany, China, Japan, and the United Arab Emirates.
United States
Major carriers including Delta, United, and American Airlines are accelerating narrow-body fleet retrofit programs as Ku-band satellite contracts expire. The FAA's updated C-band interference assessment protocols near runway thresholds are unlocking deployment timelines previously blocked by spectrum concerns. Dallas-Fort Worth International Airport anchors the densest ground station network, with Massive MIMO arrays tracking aircraft at approach speeds exceeding 250 knots.
Germany
Lufthansa Technik is integrating 5G telemetry into Engine Health Monitoring service offerings for predictive maintenance applications. EASA cyber-resilience mandates for connected aircraft systems are forcing avionics suppliers to embed hardware-rooted security from initial design phases. The Munich-Frankfurt aviation corridor hosts the most advanced private 5G deployments for apron vehicle tracking and autonomous baggage operations.
China
Huawei leverages its Massive MIMO patent portfolio to anchor ground station infrastructure bids across Asia-Pacific aviation clusters. MIIT spectrum allocation frameworks are finalizing aviation-specific 5G guard bands that will determine vendor market access for international fleet operators. Beijing Capital International Airport's biometric passenger processing systems operate on dedicated network slices.
Japan
ANA and JAL are prioritizing latency-based performance specifications in connectivity RFPs for operational applications. METI industrial policy is channeling R&D subsidies toward network-sliced architectures for air traffic management independence. The Kansai-Osaka aviation cluster is piloting remote tower operations serving multiple regional airports from centralized facilities.
United Arab Emirates
Emirates SkyCargo has deployed sensor networks across its Dubai hub freighter fleet for real-time cold chain monitoring of pharmaceutical shipments. The country's national telecom regulator is establishing aviation-specific spectrum coordination rules for ground station cooling infrastructure compliance. Dubai International Airport's 5G densification spans terminals, apron areas, and autonomous vehicle corridors.
5G Adoption Analysis in Aviation Market Competitive Landscape
Top-tier vendors anchor infrastructure and equipment supply, while mid-tier specialists and regional system integrators compete on deployment speed and customization. The vendor base stratifies across three tiers: patent-rich equipment manufacturers, network architecture specialists, and aviation-certified integration partners. Two strategic archetypes dominate—telecom infrastructure providers repurposing cellular expertise for aviation applications, and aerospace incumbents embedding connectivity into airframe and avionics platforms. Competitive moves concentrate on spectrum licensing partnerships and airworthiness certification acceleration.
Among infrastructure-focused vendors, Huawei, Ericsson, and Nokia occupy distinct positioning vectors. Huawei exemplifies the patent-anchored equipment archetype with its Massive MIMO portfolio. Ericsson represents the end-to-end network slicing specialist targeting airport densification architectures. Nokia sits within the private 5G deployment tier for remote tower and operational applications.
| Leading Market Players |
|---|
| Huawei |
| Ericsson |
| Nokia |
| Qualcomm |
| Vodafone |
| AT&T |
| Verizon |
| Airbus |
| Thales |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up avionics specialists have consolidated antenna subsystem suppliers across Germany and the United States, tightening component availability and compressing procurement timelines for airlines retrofitting narrow-body fleets. This ownership concentration feeds directly into pricing discipline, as consolidated vendors extract premiums for aviation-grade Massive MIMO arrays with EASA-certified hardware-rooted security.
Pricing Analysis
Short lead-time premiums dominate equipment procurement, with airlines paying substantial markups for certified 5G modem architectures delivering within compressed fleet retrofit windows. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Cost compression in mid-tier hardware is intensifying because avionics suppliers are absorbing design-phase security embedding expenses. Regional operators in India exhibit highest price sensitivity, deferring full core upgrades through Non-Standalone transitional architectures, while US major carriers demonstrate lowest sensitivity as Ku-band contract expirations force accelerated replacement schedules.
Supply Chain Analysis
Freight costs for specialized RF components from Taiwan, South Korea, and Germany have escalated as beamforming chipsets and aviation-grade cooling systems face customs prioritization delays. The supply chain draws from gallium nitride semiconductors, precision-filter substrates, and refrigerant-compliant heat exchangers. Single-source vulnerability concentrates around Massive MIMO baseband processors from limited qualified foundries. Distribution runs through avionics OEM direct channels and certified system integrators serving airline engineering departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EASA cyber-resilience mandates and FAA certification complexity force sub-scale avionics suppliers into distressed exits, concentrating procurement authority among vertically integrated platform providers.
For Market Incumbents: Acquire distressed certification expertise pools in Germany and France to accelerate airworthiness approval timelines for network-sliced architectures. Incumbents should anchor ground station densification partnerships with Dallas-Fort Worth and Beijing Capital airport authorities, while embedding hardware-rooted security capabilities to neutralize emerging entrant threats from telecom-native vendors lacking aviation safety culture integration. For New Entrants and Emerging Players: The FAA's updated C-band interference assessment protocols in the United States open a window for filter-architecture specialists to capture ground station retrofit demand near runway thresholds. New entrants should target Brazil's pending aviation-specific guard band finalization as the most penetrable geography, entering through spectrum coordination consulting services before expanding into equipment supply relationships with international fleet operators. For Investors and Strategic Acquirers: Distressed-cycle entries favor aviation-certified integration specialists with existing EASA approvals in Nordic aviation clusters. Long-term viability hinges on 5G-ATC convergence positioning over the next decade. The signal to watch is Brazil and India spectrum auction timing, which will determine vendor market access and retrofit scheduling for global fleet operators.| Strategic Initiative | Industry Significance |
|---|---|
| Airworthiness Certification Acceleration | EASA pre-approval of 5G modem architectures compresses Delta and United retrofit timelines. |
| Network Slicing Partnership | Ericsson's airport densification architectures isolate air traffic control from consumer traffic. |
| Remote Tower Deployment | Avinor's Bodo center model enables centralized services for 15 Norwegian regional airports. |
| Predictive Maintenance Platform Integration | Rolls-Royce telemetry embedding reduces unplanned engine shop visits through continuous 5G backhaul. |
| Spectrum Coordination Consulting | Specialist advisory on Brazil's aviation guard bands secures vendor positioning before auction finalization. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with airline chief information officers, avionics procurement managers, airport authority technology directors, and EASA certification engineers. FAA C-band interference assessments, EASA cyber-resilience mandates, MIIT spectrum frameworks, and METI industrial policy documents provided regulatory trajectory validation. Bottom-up fleet retrofit schedules triangulated against top-down infrastructure investment flows from ground station densification programs.
Granularity-level modeling operated at technology-architecture, application-function, and deployment-physical-layer dimensions across the analysis window. Standalone versus Non-Standalone adoption curves, Massive MIMO penetration by airport hub density, and predictive maintenance telemetry deployment rates informed segment-level CAGRs. Forecast inputs incorporated airline narrow-body fleet age profiles, satellite contract expiration calendars, and national regulator spectrum auction timelines.
The model assumes a particular technology adoption path; alternative pathways for millimeter wave deployment in wet-climate airports would alter the outlook for passenger broadband throughput assumptions. Forecasts reflect documented regulatory certification timelines and equipment supply constraints. Stakeholders should weight assumptions against their own operating context regarding fleet composition and geographic exposure to spectrum coordination rules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Aircraft Turn Coordinator Market
Aircraft Navigation and Communication
Aircraft Communication System Market
Aircraft Navigation and Communication
In Flight Connectivity Market
Aircraft Navigation and Communication
Defense Advanced GPS Receiver (DAGR) Market
Aircraft Navigation and Communication
Aviation Weather Radar Market
Aircraft Navigation and Communication
Aircraft Navigation System Market
Aircraft Navigation and Communication
Europe Air Traffic Management Market
Aircraft Navigation and Communication
Air Traffic Management Software Market
Aircraft Navigation and Communication
Electronic Navigational Charts (ENC) Market
Aircraft Navigation and Communication
Aircraft Interface Device Market
Aircraft Navigation and Communication
Airspace and Procedure Design Market
Aircraft Navigation and Communication
GPS and GNSS Receivers in Aviation Market
Aircraft Navigation and Communication
Asia-Pacific Air Traffic Management Market
Aircraft Navigation and Communication
Airborne High Frequency Radio Market
Aircraft Navigation and Communication
Airborne Radars Market
Aircraft Navigation and Communication
Ground to Air on-Board Connectivity Market