
 Europe Agriculture Biotech Market | 2026-2036
Europe Agriculture Biotech Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Agriculture Biotech Market Insights
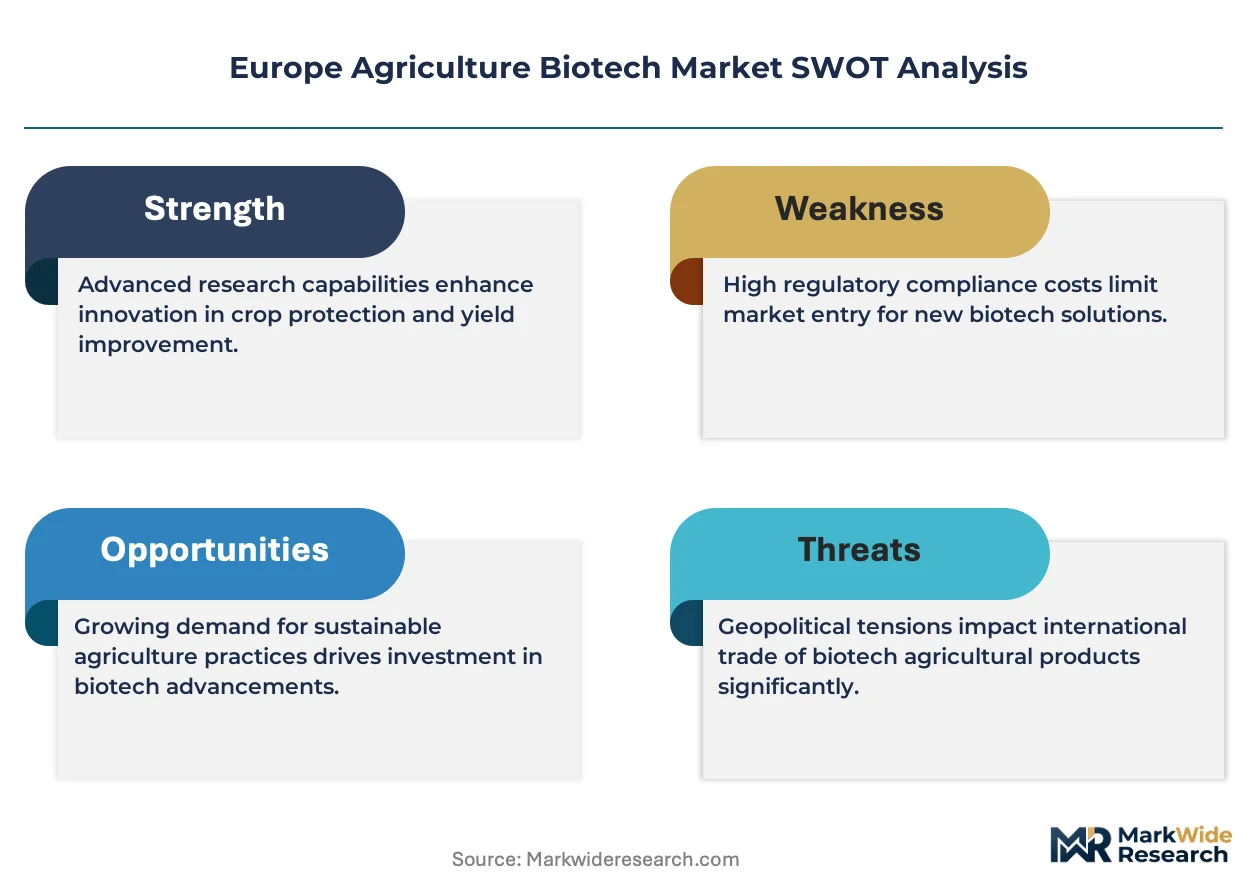
Project finance tied to sustainability-linked lending is rewriting competitive entry conditions in European agricultural biotechnology. Bayer AG leverages its integrated seed-and-trait pipeline to sustain R&D intensity across transgenic and CRISPR platforms. BASF SE anchors its position through microbial formulation expertise and broad crop protection distribution. Koppert Biological Systems specializes in biological pest management, occupying a defensible niche as chemical restrictions tighten under EU policy.
Europe agriculture biotech encompasses living organisms, genetic material, and biological processes applied to crop production, including engineered seeds with pest-resistance traits, microbial inoculants containing specified colony-forming units, and RNA-based crop protection agents designed for targeted gene silencing. Its primary commercial purpose centers on enhancing agricultural productivity while reducing synthetic chemical inputs across the region's cultivated land base. Seeds represent the most mature revenue pool, though biostimulants are attracting capital as growers seek yield improvement without triggering stricter residue regulations. CRISPR technology leads technology-category growth potential, while microbial applications dominate near-term deployment because of established regulatory pathways through EFSA.
EMA guidelines on genetically modified organisms, REACH chemical registration requirements, and the EU Green Deal's pesticide reduction targets collectively shape product development timelines and market access conditions for biological crop inputs. EFSA novel food and feed assessments add another compliance layer for gene-edited traits entering cultivation. Stakeholders must monitor how the EU AI Act intersects with precision agriculture data platforms that increasingly govern biotech application timing and placement decisions.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing chemical pesticide availability and redirecting capital toward biological crop inputs, fundamentally restructuring competitive entry conditions for agricultural biotechnology across the continent.
Growth Catalysts
- REACH chemical registration:Synthetic pesticide approval timelines extend under tightened hazard assessment protocols, creating regulatory space for microbial inoculants and RNA-based agents to capture displaced acreage.
- Precision agriculture platforms:Variable-rate application technology in German large-scale farming operations is integrating biostimulant deployment with sensor-driven placement, improving input efficiency and yield consistency.
- Spanish biostimulant demand:Extensive arable land under intensive cultivation in Andalusia and Castile-La Mancha drives volume uptake of yield-enhancing biologicals as residue thresholds tighten for export crops.
Market Restraints
- EFSA novel food assessments:Gene-edited trait approval pathways require extensive molecular characterization and environmental risk evaluation, extending product development timelines beyond conventional breeding cycles.
- Active ingredient supply concentration:Specialized fermentation capacity for microbial biocontrol agents concentrates in limited European contract manufacturing sites, creating bottleneck risk for formulation scale-up.
- Petrochemical input volatility:Synthetic biology feedstock costs fluctuate with natural gas pricing, compressing margin predictability for fermentation-based biological manufacturing.
Strategic Opportunities
- Polish specialty cropping expansion:Apple and berry production clusters in Mazovia and Greater Poland remain underpenetrated by biological pest management, offering first-mover positioning as EU chemical restrictions phase in.
- EU AI Act intersection:Compliance frameworks for precision agriculture data platforms create partnership opportunities between biotech input providers and farm management software vendors on algorithmic application timing.
- Seed treatment convergence:Coating technology advances enable simultaneous delivery of microbial inoculants and biostimulants at planting, opening bundled product architectures for specialty crop segments in the Netherlands.
Industry Challenges
- Gene editing talent scarcity:CRISPR platform development requires molecular biology expertise concentrated in academic and pharmaceutical sectors, creating recruitment competition for agricultural applications.
- Multi-jurisdiction dossier complexity:Mutual recognition procedures across EU member states for biological plant protection products generate redundant efficacy testing requirements and registration cost inflation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Agriculture Biotech Market |
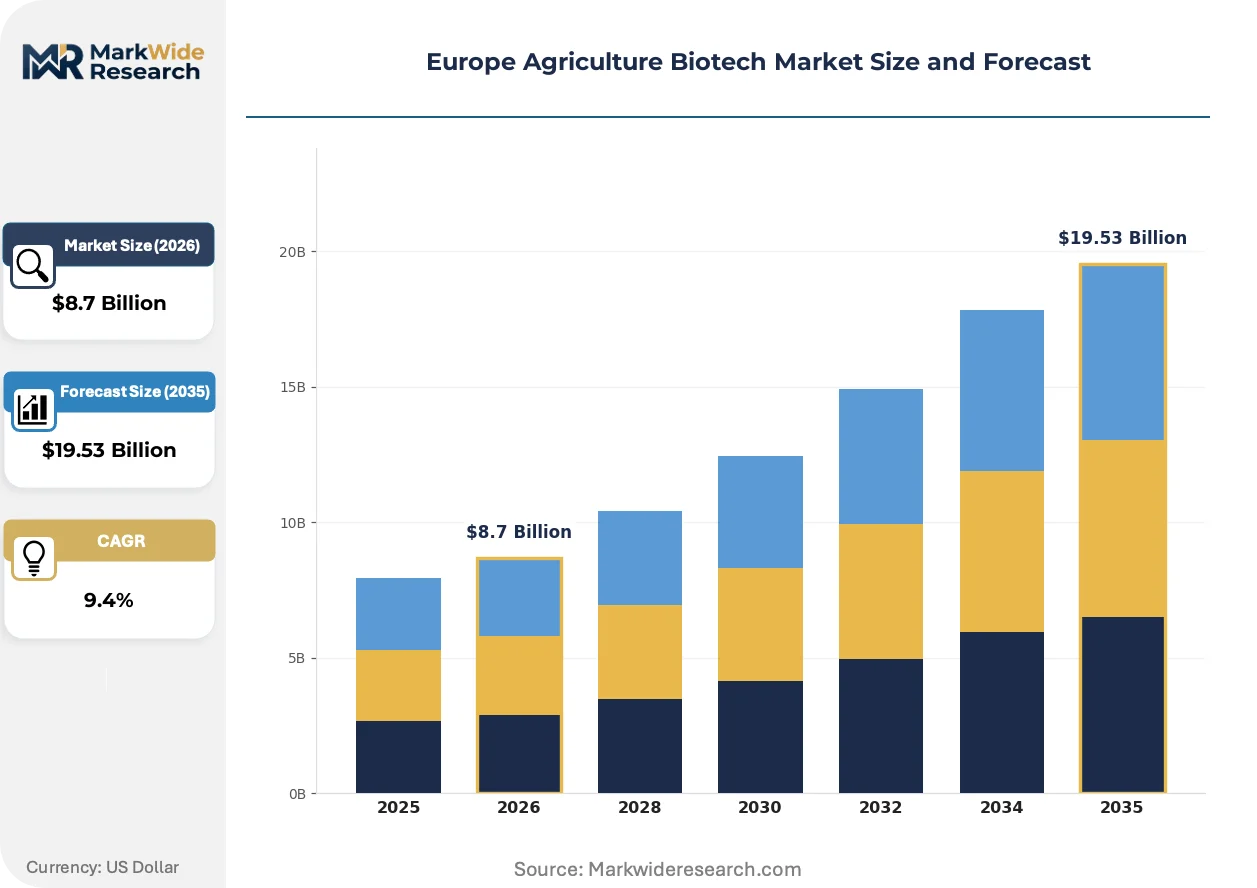
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seeds, Biopesticides, Bioherbicides, Biostimulants Application: Crop Protection, Soil Enhancement, Pest Management, Yield Improvement Technology: Transgenic, CRISPR, RNA Interference, Microbial End User: Agricultural Enterprises, Research Institutions, Farmers, Government Agencies |
| Companies Covered | Syngenta, Bayer AG, BASF SE, KWS SAAT AG, Corteva Agriscience, Koppert Biological Systems, Vilmorin, Yara International, Biobest Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Agriculture Biotech Market Trends and Innovations
Digital infrastructure integration and biological input sophistication are converging to reshape how European growers manage crop productivity within tightening chemical constraints.
RNA interference technology is digitizing crop protection by enabling sequence-specific pest suppression without residual environmental persistence. Large-scale cereal operations in France and Germany are piloting foliar RNAi applications against lepidopteran pests. The technology is digitizing traditional chemical spraying schedules into programmable, trait-matched intervention protocols that compress unnecessary broad-spectrum applications.
EMA guidelines on genetically modified organisms are tightening containment and traceability requirements for field trials of gene-edited crops. Seed developers must now implement molecular detection methods and geographic isolation protocols that extend pre-commercial validation timelines. The regulatory friction most affects CRISPR-edited oilseed and cereal programs targeting the 2035 pesticide reduction milestones.
Service unbundling is fragmenting traditional distributor relationships as grower cooperatives in Spain and Italy establish direct procurement channels with biological input manufacturers. These purchasing collectives are displacing legacy agrochemical dealer networks that historically bundled financing, agronomic advice, and product supply. The channel restructuring is most advanced in fruit and vegetable segments where residue compliance documentation requirements favor transparent supply chain relationships.
Europe Agriculture Biotech Market Segmentation
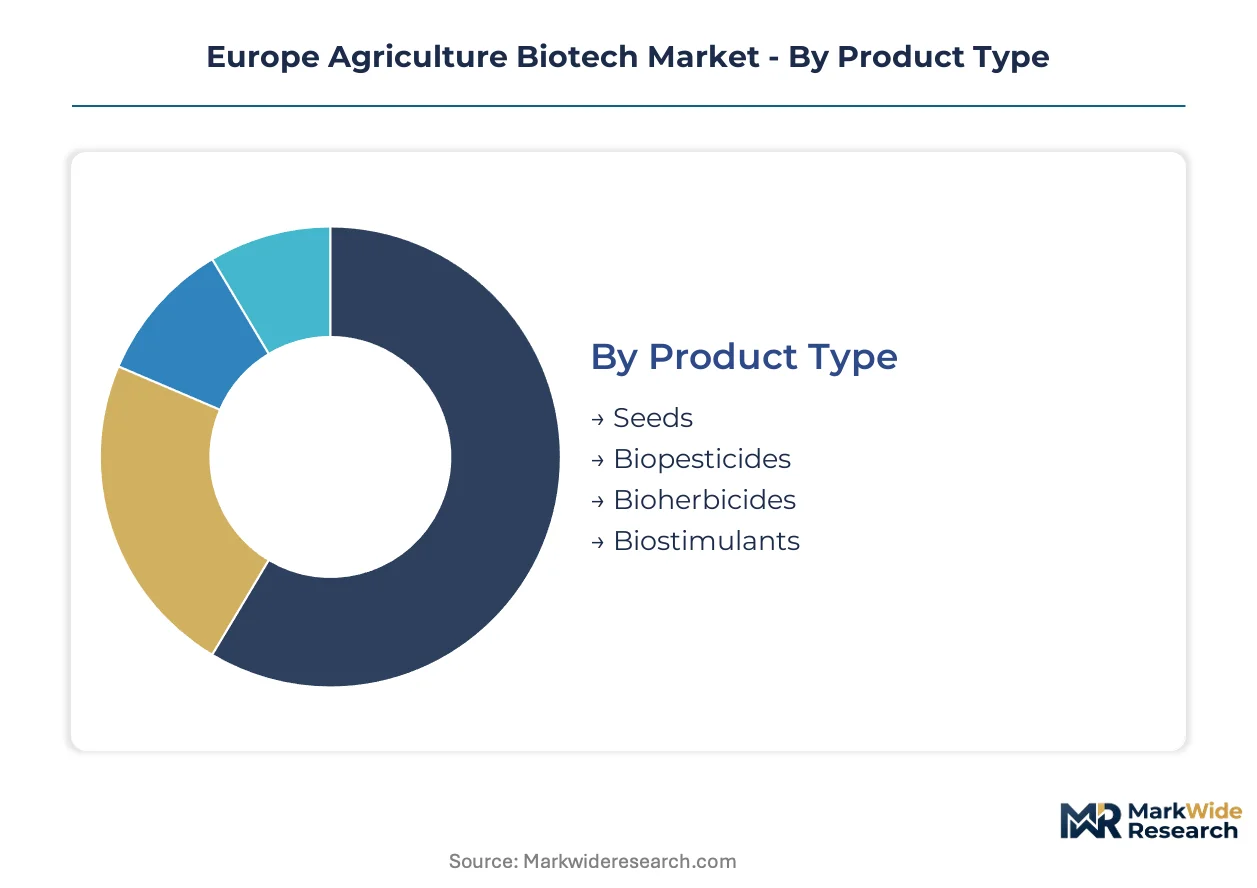
Product architectures in European agricultural biotechnology span radically different development cycles, from decade-long seed trait pipelines to seasonally reformulated microbial cocktails. Understanding these temporal patterns reveals where capital efficiency concentrates and where regulatory friction erodes returns.
Product Type:
Seeds turn over slowest, requiring multi-year breeding cycles and EFSA novel food assessments, while biostimulants refresh annually based on field performance data.
- Seeds:Engineered germplasm incorporating pest-resistance traits, herbicide tolerance, or yield optimization through transgenic or gene-edited platforms. German and Spanish large-scale farming operations anchor demand as precision agriculture programs integrate trait performance with variable-rate planting equipment. EFSA authorization timelines extend commercialization horizons.
- Biostimulants:Microbial and biochemical formulations enhancing nutrient uptake, stress tolerance, or metabolic efficiency without pesticidal claims. French and Dutch specialty cropping enterprises drive uptake as EU Green Deal pesticide restrictions tighten residue thresholds for export-bound produce. Formulation flexibility permits rapid iteration.
- Biopesticides:Living organisms or natural substances suppressing crop pests through predation, parasitism, or biochemical antagonism.
- Bioherbicides:Microbial or botanical agents targeting weed species through host-specific pathogenicity or allelopathic interference.
Seeds dominate installed base. Biostimulants are where expansion concentrates.
Application:
Cost tier separation runs from premium-priced precision placement services to commodity input bundles, with margin structure determining vendor participation intensity.
- Crop Protection:Biological and biotechnological interventions defending cultivated plants against pathogens, pests, and competitive weeds. Spanish intensive vegetable operations in Almería and Murcia concentrate demand as chemical residue limits tighten for Northern European retail contracts. RNA-based agents command premium positioning.
- Yield Improvement:Trait-based or input-based interventions enhancing harvestable output per hectare through photosynthetic efficiency, nutrient assimilation, or stress resilience. French cereal cooperatives in the Paris Basin integrate biostimulant protocols with sensor-driven nitrogen management. Data integration requirements favor technology-forward suppliers.
- Soil Enhancement:Microbial inoculants and amendments improving physical structure, biological activity, or chemical fertility of cultivated substrates.
- Pest Management:Integrated biological control programs combining monitoring, threshold-based intervention, and natural enemy conservation.
Crop Protection captures the largest revenue pool. Yield Improvement is climbing the fastest as carbon accounting pressures intensify.
Technology:
Volume deployment currently favors established platforms with cleared regulatory pathways, while emerging modalities accumulate field validation data.
- Microbial:Bacterial and fungal formulations delivered as seed treatments, soil drenches, or foliar applications, specified by colony-forming units and strain identity. Dutch greenhouse operations and Polish apple orchards drive near-term deployment given existing EFSA guidance and distributor familiarity. Fermentation capacity constraints limit formulation scale-up.
- CRISPR:Site-directed nuclease systems enabling precise genomic modifications without transgenic construct insertion, accelerating trait development timelines. Oilseed and cereal programs target German and French farm cooperative procurement specifications. EMA containment requirements for field trials extend pre-commercial validation.
- Transgenic:Recombinant DNA technology introducing exogenous genetic material conferring novel phenotypic characteristics.
- RNA Interference:Double-stranded RNA molecules triggering sequence-specific gene silencing in target pest organisms.
Microbial platforms command current acreage share. CRISPR represents the steepest expansion trajectory pending regulatory clarity.
End User:
Customer type determines procurement sophistication, with enterprise-scale operations deploying integrated data platforms and smallholders relying on cooperative aggregation.
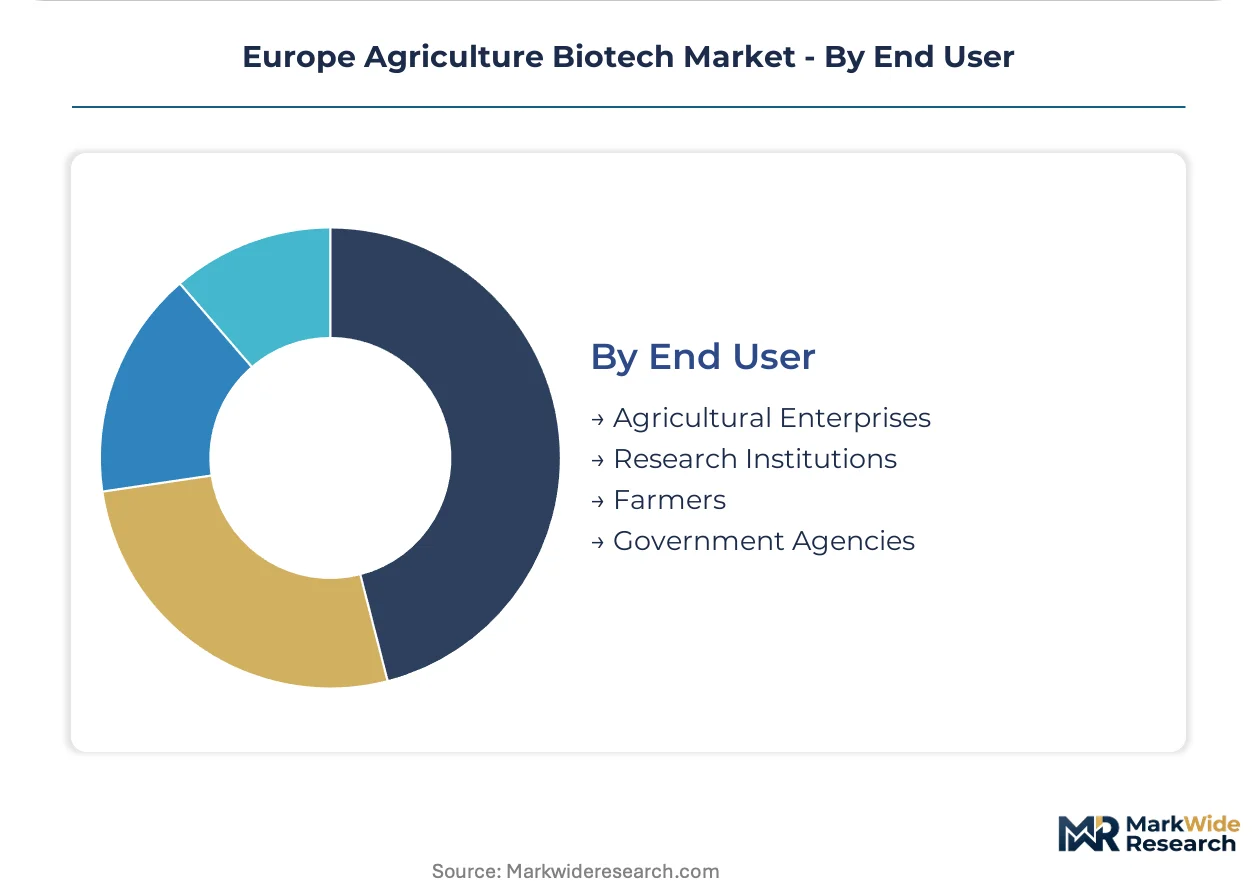
- Agricultural Enterprises:Corporate farming operations and vertically integrated food producers with dedicated agronomy departments and capital budgets for technology adoption. German large-scale arable operations in Lower Saxony and Schleswig-Holstein integrate biostimulant deployment with precision agriculture data infrastructure. Procurement runs through sustainability-linked lending arrangements.
- Farmers:Independent owner-operators and family businesses managing cultivated land directly, ranging from subsistence to commercial scale. Spanish and Italian grower cooperatives in fruit and vegetable segments establish direct manufacturer relationships, displacing legacy distributor networks. Residue documentation requirements favor transparent supply chains.
- Research Institutions:Universities and public agricultural research organizations conducting foundational and applied biotechnology investigation.
- Government Agencies:National and EU-level bodies funding demonstration programs, setting regulatory frameworks, and administering compliance enforcement.
Agricultural Enterprises dominate technology absorption capacity. Farmers are where channel restructuring concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-bound produce from Mediterranean growing regions drives biological input demand, while Northern European precision agriculture programs absorb premium biostimulant formulations. Import dependency for specialized microbial fermentation capacity concentrates supply risk in Benelux contract manufacturing hubs.
Germany
Large-scale arable operations in Lower Saxony and Schleswig-Holstein deploy variable-rate biostimulant application tied to sensor-driven nitrogen management. The EU Green Deal's pesticide reduction targets accelerate procurement through sustainability-linked lending arrangements. Berlin-Brandenburg research clusters advance CRISPR field trial protocols under EMA containment guidelines.
Spain
Intensive vegetable cultivation in Almería and Murcia faces tightening residue limits for Northern European retail contracts. Andalusian greenhouse cooperatives establish direct procurement channels with biological input manufacturers, displacing legacy distributor networks. EFSA novel food assessments govern gene-edited trait entry into Spanish cultivation programs.
France
Cereal cooperatives in the Paris Basin integrate biostimulant protocols with precision agriculture data infrastructure. REACH chemical registration extensions create regulatory space for microbial inoculants in specialty cropping segments. Seed treatment applications expand among Burgundy and Champagne wine grape enterprises seeking reduced chemical footprints.
Netherlands
Greenhouse operations around Westland and Aalsmeer drive near-term microbial platform deployment given established EFSA guidance and distributor familiarity. Seed treatment convergence enables simultaneous delivery of microbial inoculants and biostimulants at planting. Fermentation capacity constraints limit formulation scale-up for export markets.
Poland
Apple and berry production clusters in Mazovia and Greater Poland remain underpenetrated by biological pest management. EU chemical restrictions phase in through 2030, offering first-mover positioning for biocontrol providers. Polish agricultural enterprises lack the capital budgets for precision agriculture integration seen in Western European counterparts.
Europe Agriculture Biotech Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in formulation and strain development. The vendor base spans integrated agrochemical conglomerates, dedicated biological input manufacturers, and regional fermentation service providers. Three archetypes dominate: seed-and-trait pipeline operators, microbial formulation experts, and biological pest management specialists. Competitive moves concentrate on strategic partnerships between biotech input providers and farm management software vendors, plus capacity expansion in specialized fermentation infrastructure.
Among integrated agrochemical conglomerates, Bayer AG and BASF SE exemplify platform breadth spanning transgenic, CRISPR, and microbial modalities. Koppert Biological Systems occupies a defensible position within the biological pest management specialist tier. These three entities represent contrasting strategic postures: conglomerate-scale R&D intensity versus niche regulatory expertise as chemical restrictions tighten under EU policy frameworks.
| Leading Market Players |
|---|
| Syngenta |
| Bayer AG |
| BASF SE |
| KWS SAAT AG |
| Corteva Agriscience |
| Koppert Biological Systems |
| Vilmorin |
| Yara International |
| Biobest Group |
| Others |
Pricing and Supply Chain Analysis
Benelux contract manufacturing hubs concentrate specialized microbial fermentation capacity, tethering margin pools to biostimulant and biopesticide formulators downstream. Dutch and Belgian toll manufacturers command pricing leverage over biological input developers seeking EFSA-compliant production scale.
Pricing Analysis
Agricultural enterprises anchor contract-based long-term offtake arrangements for biostimulant formulations, with pricing stratifying across premium microbial cocktails, standard biochemical blends, and economy-grade bulk inoculants. Certification tier under EU Green Deal sustainability protocols and volume scale drive price differentiation between Dutch greenhouse cooperatives and Polish apple orchard aggregations. Cost compression in economy-tier biopesticides intensifies as REACH chemical registration extensions redirect acreage toward biological alternatives. Polish farmer cooperatives exhibit highest price sensitivity due to capital constraints, while German large-scale arable operations absorb premium positioning for precision-integrated biostimulant protocols.
Supply Chain Analysis
Extended payment terms from Dutch and German distributor networks finance working capital cycles for Benelux fermentation facilities serving biological input manufacturers. Supply draws from Belgium, the Netherlands, and Denmark for microbial strain propagation, while RNA synthesis feedstocks source from Switzerland and specialized biochemical precursors from France. Single-source vulnerability concentrates in contract fermentation capacity for colony-forming unit specifications. Distribution runs through grower cooperative procurement collectives in Spain and Italy, displacing legacy agrochemical dealer networks with direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe agriculture biotech sits at a high-growth inflection as EU Green Deal pesticide reduction targets compress chemical availability and redirect capital toward biological alternatives. CRISPR platform maturation and microbial formulation advances are reshaping competitive entry conditions.
For Market Incumbents: Insulate seed-and-trait pipeline positions through backward integration into microbial fermentation capacity in Benelux manufacturing corridors. Bayer AG and BASF SE must secure captive supply of colony-forming unit production to defend margin structures against toll manufacturer pricing leverage as biostimulant volumes accelerate. For New Entrants and Emerging Players: Pursue Polish specialty cropping clusters in Mazovia and Greater Poland for biological pest management penetration ahead of EU chemical restriction phase-in through 2030. Direct procurement relationships with apple and berry cooperatives offer transparent supply chain positioning absent legacy distributor entrenchment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed microbial formulation specialists holding EFSA regulatory dossier expertise and established distributor relationships. Fermentation capacity scarcity in Benelux contract manufacturing represents the signal to watch for valuation inflection as biological input volumes scale.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Regulatory Dossier Investment | Accelerates market access for microbial biopesticides under EU Green Deal pesticide reduction timelines. |
| Precision Agriculture Data Partnership | Integrates biostimulant application timing with German and French sensor-driven nitrogen management platforms. |
| Fermentation Capacity Expansion | Relieves Benelux manufacturing bottlenecks for colony-forming unit scale-up in biological input production. |
| Seed Treatment Convergence Development | Enables bundled microbial inoculant and biostimulant delivery for Dutch specialty crop segments. |
| CRISPR Field Trial Protocol Advancement | Accelerates oilseed and cereal trait validation under EMA containment guidelines for German cooperatives. |
Research Methodology
Initial hypotheses were tested against primary input from agricultural biotechnology R&D directors, EFSA regulatory affairs specialists, grower cooperative procurement managers, and precision agriculture platform engineers, then refined through secondary validation. EFSA novel food assessment databases, EU Green Deal policy documentation, REACH chemical registration filings, and customs trade data for biological input flows anchored source triangulation. Bottom-up acreage deployment estimates and top-down capital expenditure patterns were reconciled across analytical approaches.
Demand-supply balance modeling tracked biological input adoption against chemical pesticide displacement across the projection horizon. Segmentation dimensions included product architecture, application purpose, technology platform, and end-user procurement sophistication. CAGRs were derived from acreage penetration curves and input intensity assumptions, with EFSA approval timelines and EU AI Act compliance requirements informing adoption rate parameters.
Sensitivities concentrate around EFSA regulatory pathway acceleration, EU Green Deal target revision, and CRISPR field trial authorization delays. Forecasts reflect documented assumptions on policy implementation pace and technology cost trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biotechnology
Stigmasterol-Rich Plant Sterols Market
Agricultural Biotechnology
Ruminant Vaccines Market
Agricultural Biotechnology
Microarray in Agriculture Market
Agricultural Biotechnology
GMO Crops and Seeds Market
Agricultural Biotechnology
Europe Plant Growth Regulators Market
Agricultural Biotechnology
South America Feed Phytogenics Market
Agricultural Biotechnology
Transgenic Seeds Market
Agricultural Biotechnology
Global Poultry Vaccines Market
Agricultural Biotechnology
Plant-Based Vaccines Market
Agricultural Biotechnology
Animal Brucella Antibody ELISA Kits Market
Agricultural Biotechnology
Biorationals Market
Agricultural Biotechnology
Global Plant Hormones Market
Agricultural Biotechnology
Global Animal Biotechnology Market
Agricultural Biotechnology
Agricultural Biotechnology Market
Agricultural Biotechnology
Africa Algae Protein Market
Agricultural Biotechnology
Duckweed Protein Market