
 Stigmasterol-Rich Plant Sterols Market | 2026-2036
Stigmasterol-Rich Plant Sterols Market Size, Share, and Industry Trends Forecast 2026-2036
Stigmasterol-Rich Plant Sterols Market Analytics
Subscription-based technical support for extraction optimization is broadening what ingredient suppliers sell beyond commodity sterol powders. BASF SE leverages its integrated nutrition and health division to sustain global supply chain control from rapeseed and soybean feedstocks. Cargill Incorporated anchors North American production capacity through its oilseed processing infrastructure. DSM Nutritional Products differentiates via pharmaceutical-grade sterol refinement capabilities for high-purity stigmasterol isolation.
Stigmasterol-rich plant sterols comprise a specific phytosterol fraction typically extracted from vegetable oils, containing stigmasterol as the dominant sterol alongside beta-sitosterol and campesterol, with purity grades ranging from 40% to 95% stigmasterol content depending on source material and crystallization method. These sterols serve primarily as precursors for semisynthetic steroid hormone production and as cholesterol-lowering functional ingredients in food and supplement matrices. Powder formulations dominate current volume due to stability in blending operations and extended shelf life, while liquid extracts command premium positioning in pharmaceutical precursor applications where solubility parameters matter. Dietary supplements represent the most mature application segment with established consumer recognition, whereas pharmaceutical products carry the highest margin pools linked to API precursor certification requirements.
FDA botanical drug guidance and EMA quality standards for phytochemical APIs jointly determine sterol purity thresholds and documentation burdens for market access. REACH registration in Europe and EPA renewable fuel standards in the United States create divergent compliance pathways that shape extraction facility location decisions and capital allocation. China's NMPA and GB standards for food-grade sterols add a third regulatory layer for suppliers serving Asian pharmaceutical and nutrition markets. Stakeholders must monitor evolving pharmacopeial monographs for stigmasterol content specifications and decide whether to invest in dedicated pharmaceutical-grade isolation capacity or maintain flexible food-pharma dual-use production lines.
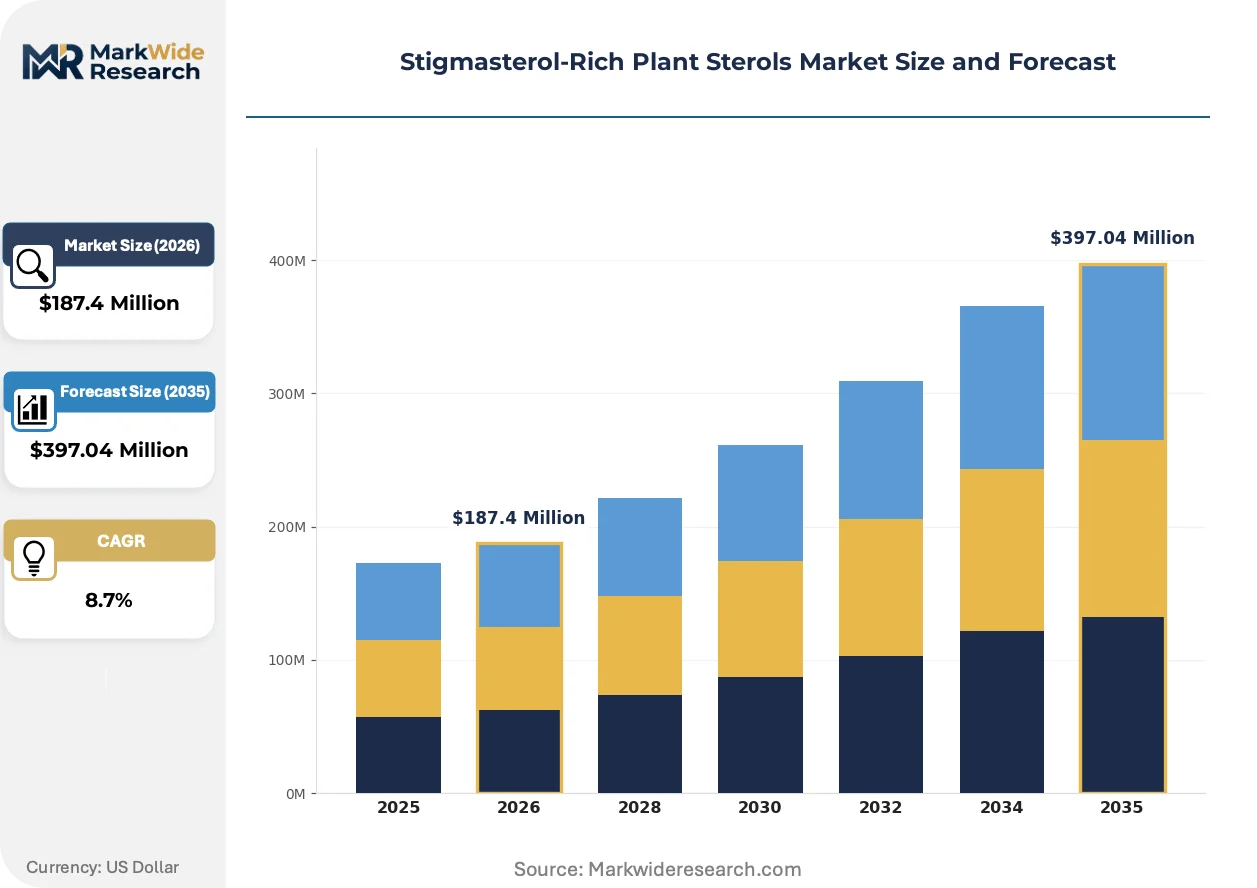
Market Dynamics
Pharmaceutical manufacturers are consolidating long-term stigmasterol supply contracts as corticosteroid precursor demand intensifies, while REACH compliance and FDA botanical drug guidance simultaneously tighten purity benchmarks for API-grade sterol isolation.
Growth Catalysts
- Semisynthetic hormone demand:Corticosteroid and sex hormone precursor synthesis drives pharmaceutical-grade stigmasterol procurement from dedicated extraction facilities.
- REACH registration thresholds:ECHA compliance requirements for phytochemical APIs elevate barriers that favor established European suppliers with documented purity certification.
- India CDMO expansion:Domestic API producers in Hyderabad and Ahmedabad are securing captive plant sterol supply chains to reduce import dependency.
Market Restraints
- Soybean oil price volatility:Feedstock cost swings directly compress margins for solvent-based sterol crystallization operations.
- Chinese supply concentration:Over half of food-grade sterol refining capacity sits in Shandong and Jiangsu provinces, creating geographic single-point vulnerability.
- Synthetic steroid competition:Fully synthetic corticosteroid routes from petrochemical precursors threaten stigmasterol's cost position in commoditized hormone segments.
Strategic Opportunities
- Brazilian Amazon sourcing:Underexploited murumuru and cupuacu butter streams offer novel stigmasterol-rich feedstocks outside established soy-rapeseed duopoly.
- Continuous chromatography adoption:Simulated moving bed technology is automating pharmaceutical-grade sterol separation with higher yield and lower solvent consumption.
- EU Green Deal bioeconomy incentives:Circular processing grants for agricultural waste valorization support new extraction facility development in Poland and Romania.
Industry Challenges
- Pharmacopeial monograph alignment:Reconciling USP, EP, and ChP stigmasterol content specifications delays multi-region product registration timelines.
- Specialized extraction engineering talent:Shortage of process chemists experienced in supercritical CO2 sterol fractionation constrains capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stigmasterol-Rich Plant Sterols Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stigmasterol, Beta-Sitosterol, Campesterol, Other Sterols Application: Dietary Supplements, Functional Foods, Pharmaceutical Products, Animal Feed Form: Powder, Liquid, Granules, Tablets Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Health Food Stores |
| Companies Covered | BASF SE, Archer Daniels Midland, Cargill Incorporated, Raisio Oyj, Arboris LLC, DuPont, DSM Nutritional Products, Bunge Limited, Gustav Parmentier GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stigmasterol-Rich Plant Sterols Market Evolving Landscape
Extraction technology automation and regulatory documentation digitization are compressing batch-to-batch variability while pharmaceutical buyers demand real-time purity verification across supply chains.
Supercritical CO2 extraction systems with inline HPLC monitoring are automating stigmasterol isolation from deodorizer distillates with precision previously requiring multiple crystallization stages. Pharmaceutical CDMOs in Germany and Switzerland are retrofitting existing solvent-based plants with these closed-loop units. The technology is automating quality assurance workflows that previously demanded dedicated analytical laboratories per production site.
EMA's revised quality guidelines for phytochemical starting materials now mandate full supply chain traceability back to oilseed cultivar and harvest location. European API manufacturers must document agricultural sourcing through certified mass balance systems. High-purity stigmasterol isolators serving hormone precursor markets face the steepest documentation burden, with some suppliers exiting pharmaceutical grades to focus on food and supplement applications.
Ingredient buyers are consolidating vendor relationships from transactional spot purchasing toward multi-year toll manufacturing agreements with fixed purity bands. Large supplement formulators in North America now contract directly with extraction facilities rather than distributors, inserting quality audit rights into supply contracts. This concentration is most pronounced among private-label brands seeking differentiated cardiovascular health positioning through certified sterol content claims.
Stigmasterol-Rich Plant Sterols Market Segmentation
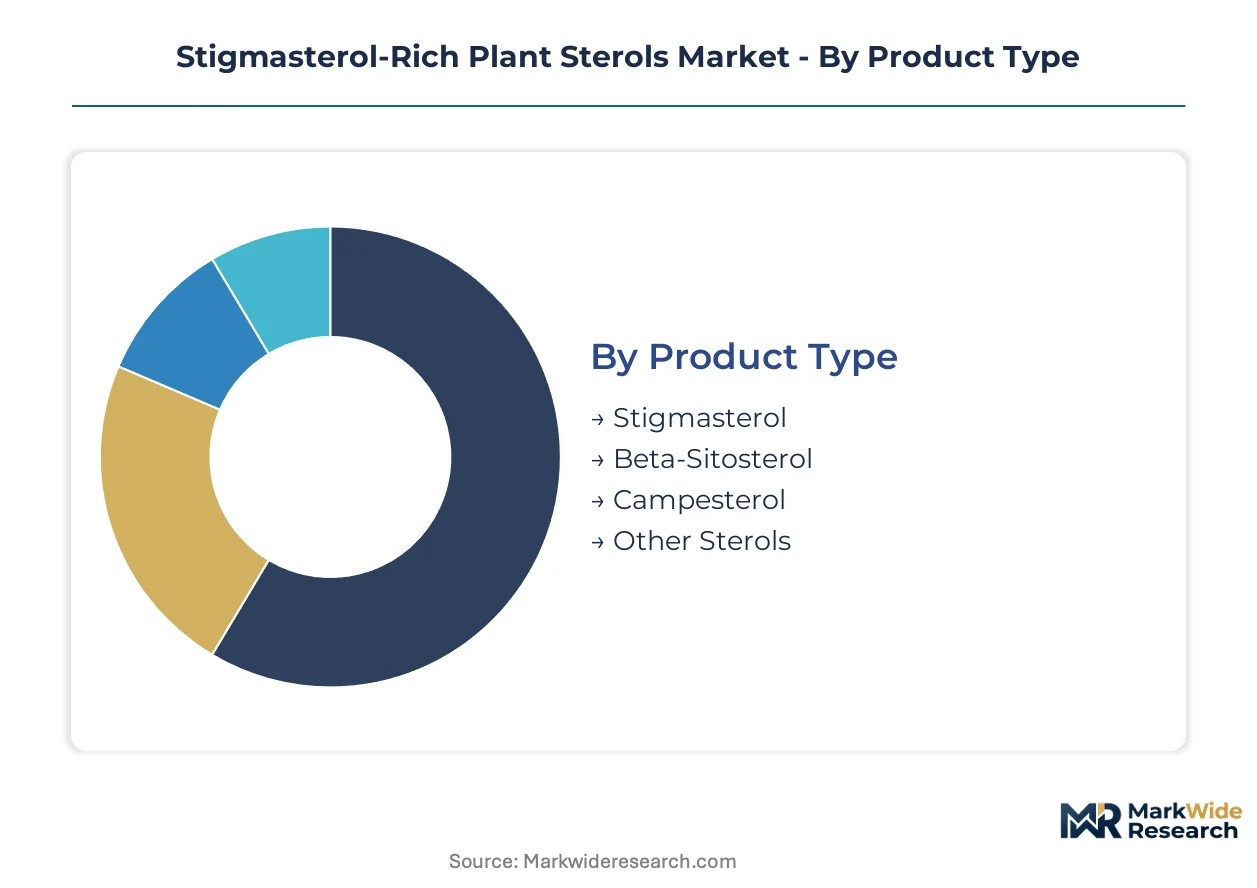
Segmentation in the stigmasterol-rich plant sterols market reveals distinct purity and integration requirements across pharmaceutical precursor, functional food, and supplement applications. Each category carries different certification burdens, margin structures, and supply chain configurations that shape supplier positioning.
Product Type:
Standalone sterol isolates command premium pharmaceutical pricing, while blended sterol fractions serve broader food and feed applications with lower documentation overhead.
- Stigmasterol:High-purity isolates (90%+) serve corticosteroid precursor synthesis for API manufacturers. Demand concentrates in Indian CDMO clusters around Hyderabad and Ahmedabad, driven by domestic hormone production mandates and import substitution policies.
- Beta-Sitosterol:The most abundant plant sterol in nature, typically co-extracted with stigmasterol and separated via fractional crystallization. Volume placements dominate cholesterol-lowering functional foods in North American and European retail channels.
- Campesterol:Minor component in most vegetable oil distillates, often retained in mixed sterol fractions rather than isolated. Applications center on animal feed fortification and lower-specification supplement formulations.
- Other Sterols:Brassicasterol, avenasterol, and trace sterols from specific oilseed sources. Niche demand from research reagent suppliers and specialty cosmetic formulators seeking unique phytosterol profiles.
Volume placements concentrate in Beta-Sitosterol; the faster expansion belongs to high-purity Stigmasterol isolates.
Application:
Application segments stratify sharply by regulatory intensity, with pharmaceutical pathways requiring pharmacopeial-grade documentation absent from food and feed channels.
- Dietary Supplements:Mature consumer segment with established cardiovascular health claims. Softgel and capsule formulations drive powder sterol demand, with North American private-label brands consolidating supplier relationships toward direct extraction facility contracts.
- Pharmaceutical Products:Corticosteroid and sex hormone precursor synthesis represents the highest-margin application. EMA quality guidelines for phytochemical starting materials now mandate full cultivar traceability, favoring suppliers with integrated agricultural documentation systems.
- Functional Foods:Margarine, yogurt, and beverage fortification with cholesterol-lowering claims. EU nutrition and health claims regulation (NHCR) approval requirements limit approved product formats and dosage levels.
- Animal Feed:Poultry and swine ration fortification for growth promotion alternatives to antibiotic feed additives. Price-sensitive segment with tolerance for lower sterol purity and mixed fractions.
Revenue concentration sits in Pharmaceutical Products; Dietary Supplements deliver the steadiest volume base.
Form:
Physical form selection tracks directly to downstream processing requirements, with solubility and blending characteristics determining specification choices.
- Powder:Dominant format for supplement and food blending operations. Spray-dried and micronized grades offer extended shelf stability and uniform dispersion in dry mix applications.
- Liquid:Oil-dissolved sterol concentrates for beverage fortification and pharmaceutical precursor reactions where solubility parameters matter. Commands premium positioning in hormone synthesis workflows.
- Granules:Intermediate physical form improving flow properties for high-speed tablet compression. Preferred by contract manufacturers serving European supplement brands.
- Tablets:Finished dosage form for direct-to-consumer supplement positioning. Requires additional excipient and compression expertise upstream in the supply chain.
Procurement weight rests with Powder; Liquid formats are climbing the fastest on pharmaceutical demand.
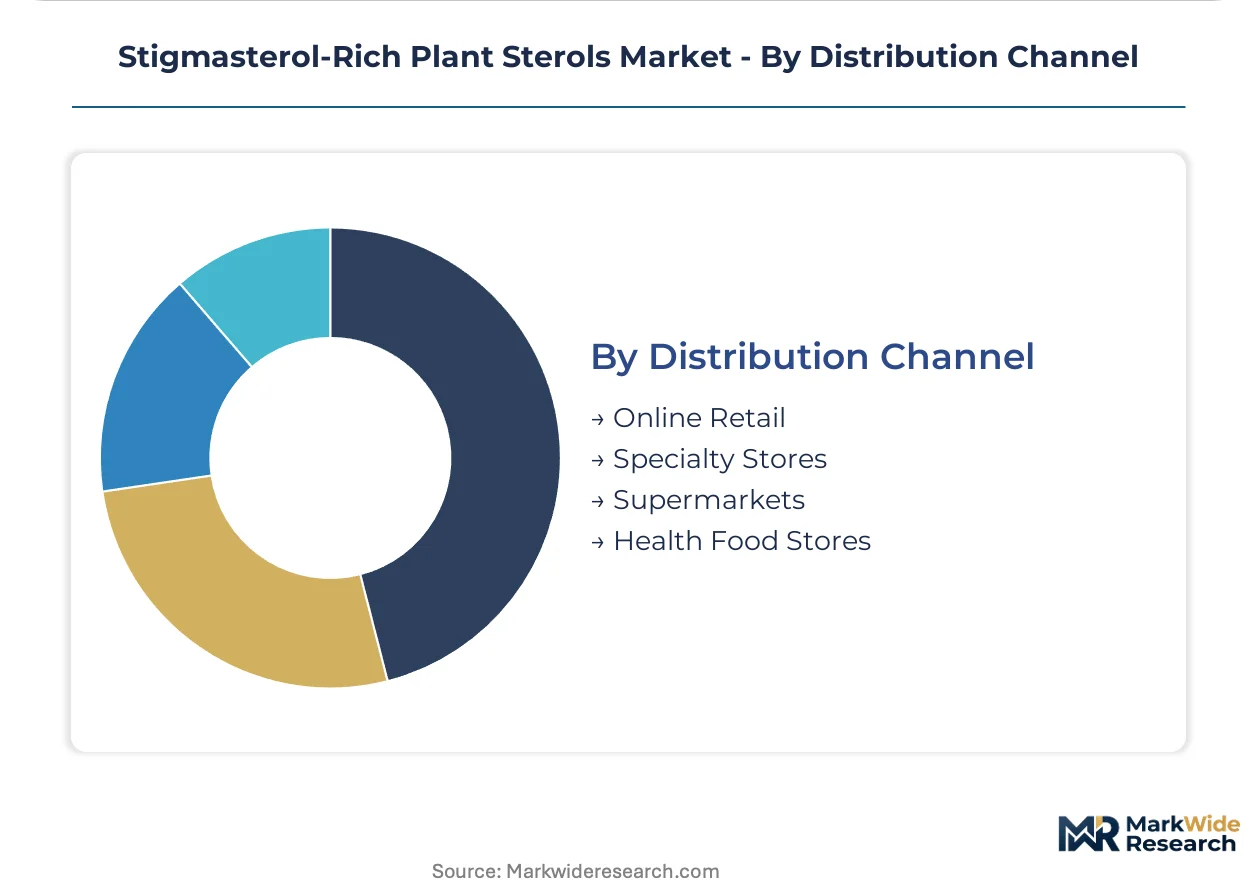
Distribution Channel:
Channel structure reflects end-user scale and quality verification requirements, with large formulators bypassing intermediaries.
- Specialty Stores:Independent health food retailers and professional supplement dispensaries. High service expectations and smaller order quantities favor distributors with technical support capabilities.
- Online Retail:Direct-to-consumer and B2B platform sales accelerating post-pandemic. Amazon and specialized ingredient marketplaces enable smaller supplement brands to access certified sterol suppliers without traditional distributor relationships.
- Supermarkets:Mass-market functional food and supplement placement. Retailer quality audits and traceability documentation requirements mirror pharmaceutical standards in some European chains.
- Health Food Stores:Regional chains and cooperatives with consumer education focus. Staff training on phytosterol benefits drives repurchase rates for cardiovascular positioning products.
Order flow concentrates in Specialty Stores; Online Retail is gaining share fastest among emerging supplement brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad anchors pharmaceutical-grade stigmasterol procurement as Indian CDMOs consolidate captive supply chains for corticosteroid precursor synthesis. The city's API manufacturing corridor now drives contract negotiations with extraction facilities across three continents.
India
Domestic hormone production mandates from CDSCO accelerate long-term supply contracting by Hyderabad and Ahmedabad API producers. The PLI scheme for active pharmaceutical ingredients subsidizes backward integration into plant sterol refining. Gujarat's specialty chemical zone near Vadodara hosts new fractionation capacity serving both pharmaceutical and export markets.
Germany
EMA quality guidelines for phytochemical starting materials force cultivar-traceability documentation upon API manufacturers sourcing stigmasterol. REACH registration thresholds favor established suppliers with mass-balance certification systems. The Rhine-Neckar chemical corridor maintains supercritical CO2 extraction retrofitting for automated sterol isolation.
United States
FDA botanical drug guidance tightens purity benchmarks for sterol-derived active pharmaceutical ingredients entering clinical pipelines. EPA renewable fuel standards divert deodorizer distillate feedstocks toward biodiesel, tightening sterol raw material availability. Iowa and Illinois oilseed processing infrastructure anchors North American mixed sterol fraction output.
China
NMPA pharmaceutical-grade sterol monographs and GB food-grade standards create dual compliance pathways for Shandong and Jiangsu refiners. The country's national pharmaceutical regulator intensifies documentation audits for hormone precursor exports. Jiangsu province concentrates crystallization capacity serving both domestic API makers and international traders.
Brazil
Murumuru and cupuacu butter streams from the Amazon basin offer novel stigmasterol-rich feedstocks outside soy-rapeseed supply chains. ANVISA import substitution policies encourage domestic extraction facility investment for pharmaceutical precursor security. São Paulo state laboratories validate sterol profiles for export certification to European and Asian buyers.
Stigmasterol-Rich Plant Sterols Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the stigmasterol value chain, with integrated oilseed processors holding feedstock cost advantages over toll extraction specialists. The structure tiers between multinational nutrition divisions with captive agricultural sourcing and regional refiners dependent on spot distillate markets. Three archetypes dominate: integrated agribusiness conglomerates controlling crush-to-sterol pipelines; pharmaceutical-grade isolators with pharmacopeial certification capabilities; and commodity traders blending mixed sterol fractions for food and feed channels. Capacity expansion and strategic partnerships represent the dominant competitive moves, as API manufacturers seek supply security through offtake agreements rather than transactional procurement.
Within the integrated agribusiness tier, BASF SE and Cargill Incorporated exemplify upstream control over rapeseed and soybean feedstock flows. DSM Nutritional Products occupies a position among pharmaceutical-grade specialists, with documented sterol refinement capabilities supporting hormone precursor certification requirements. These three anchors demonstrate how scale and regulatory documentation depth separate premium-tier suppliers from commodity-positioned competitors.
| Leading Market Players |
|---|
| BASF SE |
| Archer Daniels Midland |
| Cargill Incorporated |
| Raisio Oyj |
| Arboris LLC |
| DuPont |
| DSM Nutritional Products |
| Bunge Limited |
| Gustav Parmentier GmbH |
| Others |
Value Network & Pricing Analysis
Continuous chromatography adoption is compressing unit economics for pharmaceutical-grade stigmasterol isolation while simultaneously concentrating supply leverage among European and Indian operators with capital to retrofit solvent-based plants. This technology transition widens the cost gap between certified API-grade producers and commodity food-grade refiners, reshaping competitive boundaries across the value chain.
Pricing Analysis
Yield-based pricing anchors pharmaceutical-grade stigmasterol contracts, with API manufacturers paying premiums tied to corticosteroid precursor conversion efficiency rather than raw sterol content alone. Three-tier pricing structure across premium, standard, and economy levels separates pharmacopeial-certified isolates from food-grade fractions and animal feed specifications. Cost compression in standard grades is intensifying because Chinese refiners are expanding crystallization capacity faster than quality differentiation can sustain. Animal feed buyers exhibit highest price sensitivity, while hormone synthesis CDMOs prioritize batch consistency over unit cost.
Supply Chain Analysis
EMA cultivar-traceability mandates and REACH registration thresholds are gating market access, favoring established suppliers with mass-balance documentation systems over spot-market traders. Supply concentrates in China, India, and Germany, with Shandong province hosting the largest food-grade refining base and Hyderabad driving pharmaceutical procurement. Feedstock draws from soybean deodorizer distillates, rapeseed processing streams, and emerging Amazonian butter sources. Single-source vulnerability runs through Chinese crystallization capacity, which handles over half of global food-grade output. Distribution runs through toll manufacturing agreements with fixed purity bands, displacing spot purchasing among large supplement formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
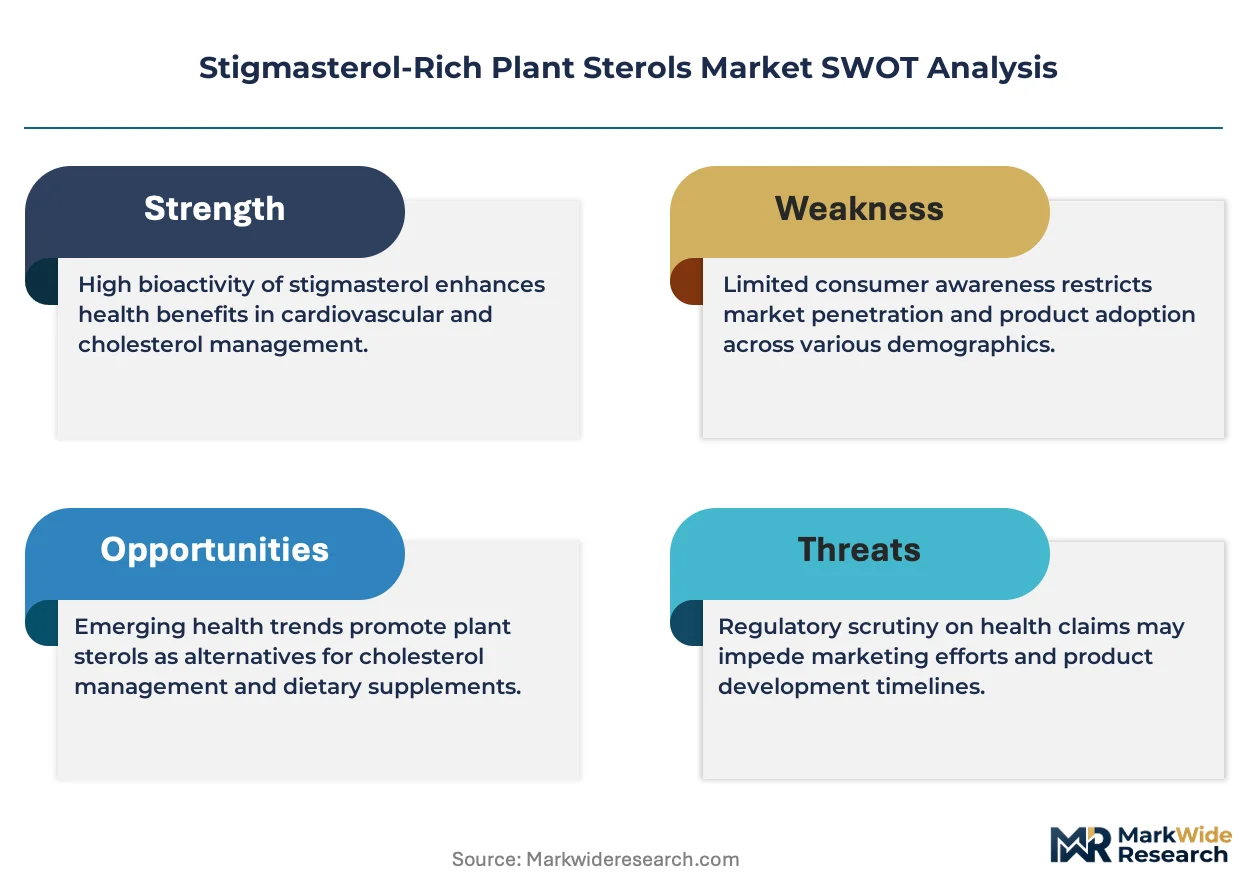
This market reads as a cost-of-compliance story where EMA quality guidelines for phytochemical starting materials erect documentation barriers that protect incumbent positions and strain undercapitalized competitors.
For Market Incumbents: Acquire supercritical CO2 extraction assets in the Rhine-Neckar corridor to automate sterol isolation and reduce batch-to-batch variability. Secure long-term offtake agreements with Hyderabad CDMOs before Indian domestic capacity matures. Synthetic steroid competition from petrochemical routes threatens stigmasterol's cost position in commoditized hormone segments, demanding certification investment as defensive differentiation. For New Entrants and Emerging Players: Continuous chromatography systems with inline HPLC monitoring offer entry pathways outside established solvent-based infrastructure. White-space targets center on Brazilian Amazon feedstocks—murumuru and cupuacu butter streams outside soy-rapeseed supply chains—and EU Green Deal bioeconomy grants supporting circular processing in Poland and Romania. Direct contracting with North American private-label supplement brands bypasses distributor intermediaries. For Investors and Strategic Acquirers: Exit pathways concentrate in pharmaceutical-grade isolators with pharmacopeial certification capabilities and documented cultivar-traceability systems. Long-term viability favors suppliers with backward integration into oilseed processing or captive agricultural sourcing rather than toll refiners dependent on spot distillate markets. Watch for CDSCO domestic hormone production mandates accelerating Indian captive supply chain development as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Hyderabad CDMOs are locking in captive plant sterol streams to reduce import dependency. |
| Backward Integration | Gujarat's specialty chemical zone hosts new fractionation capacity serving pharmaceutical export markets. |
| Green Manufacturing Transition | EU Green Deal bioeconomy incentives support agricultural waste valorization in Poland and Romania. |
| Capacity Expansion | Shandong and Jiangsu refiners are scaling crystallization output for both domestic API makers and international traders. |
| Joint Venture | São Paulo state laboratories validate sterol profiles for ANVISA-compliant export certification to European buyers. |
Research Methodology
Document review covered EMA quality guidelines, FDA botanical drug guidance, CDSCO domestic production mandates, and REACH registration thresholds, complemented by interviews with extraction facility technical directors, pharmaceutical CDMO procurement leads, supplement brand supply chain managers, and oilseed processing plant engineers. Secondary validation drew from customs and trade data on deodorizer distillate flows, pharmacopeial monograph revisions, and SEC filings of integrated agribusiness conglomerates. Bottom-up capacity modeling and top-down demand triangulation from corticosteroid precursor synthesis volumes anchored market sizing.
Segment-level outputs across the projection horizon reflect purity-grade stratification, application-specific certification requirements, and regional regulatory cluster differentiation. The analytical framework modeled stigmasterol isolates versus mixed sterol fractions, pharmaceutical versus food-grade pathways, and powder versus liquid form factors. CAGRs were derived from supply contract tenor analysis and capacity expansion announcements, with feedstock availability constraints and synthetic substitution risk weighted as scenario variables.
Several conditions sit outside the modeled scope, including abrupt shifts in soybean oil price volatility, geopolitical disruption to Chinese crystallization capacity, and breakthrough synthetic corticosteroid routes achieving cost parity. Forecasts reflect assumptions about regulatory documentation burden stability and CDSCO enforcement consistency. A model refresh is warranted upon material change in EMA phytochemical starting material guidelines or EPA renewable fuel standard diversion of deodorizer distillate feedstocks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biotechnology
Plant-Based Vaccines Market
Agricultural Biotechnology
Asia Pacific Feed Phytogenics Market
Agricultural Biotechnology
Asia-Pacific Agriculture Biotech Market
Agricultural Biotechnology
Ruminant Vaccines Market
Agricultural Biotechnology
GMO Crops and Seeds Market
Agricultural Biotechnology
Global Poultry Vaccines Market
Agricultural Biotechnology
Biorationals Market
Agricultural Biotechnology
Agroscience Market
Agricultural Biotechnology
Africa Algae Protein Market
Agricultural Biotechnology
Transgenic Seeds Market
Agricultural Biotechnology
Brazil Veterinary Vaccines Market
Agricultural Biotechnology
Animal Brucella Antibody ELISA Kits Market
Agricultural Biotechnology
Global Animal Biotechnology Market
Agricultural Biotechnology
Europe Plant Growth Regulators Market
Agricultural Biotechnology
Microarray in Agriculture Market
Agricultural Biotechnology
Agricultural Biotechnology Market