
 Global Animal Biotechnology Market | 2026-2036
Global Animal Biotechnology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Animal Biotechnology Market Foresight
Platform licensing revenue is fragmenting as specialized tool providers compete against integrated veterinary health conglomerates. Zoetis Inc. leverages its diagnostics-to-therapeutics portfolio to capture recurring revenue from livestock operations. Thermo Fisher Scientific Inc. anchors the upstream supply chain through controlled distribution of gene editing reagents and sequencing platforms. Boehringer Ingelheim International GmbH differentiates through embedded bioinformatics services that lock in long-term veterinary clinic relationships.
Animal biotechnology encompasses the application of molecular biology, genetic engineering, and cell culture techniques to modify animal genomes, develop veterinary biologics, and enhance reproductive performance, typically operating at nucleotide precision thresholds and requiring pathogen-free production environments. Its primary purpose centers on improving animal health outcomes, accelerating genetic gain in food-producing species, and generating transgenic models for pharmaceutical research. Recombinant vaccines command durable margin pools due to cold-chain complexity and regulatory exclusivity, while gene editing applications attract the fastest investment growth as multiplex CRISPR protocols reduce trait development timelines. Diagnostics kits remain the most mature revenue category, though proteomics-based platforms are displacing legacy immunoassays in large-scale veterinary reference laboratories.
The FDA Center for Veterinary Medicine and the EMA Committee for Medicinal Products for Veterinary Use shape product approval pathways, with both agencies tightening evidentiary standards for gene-edited food animals and establishing traceability mandates that directly affect market access timelines. ISO 17025 accreditation and national reference laboratory designations further constrain which manufacturers can supply regulated jurisdictions. Stakeholders must monitor divergent regulatory frameworks for genome-edited versus transgenic classifications, as these determinations will dictate capital allocation between product development pipelines.
Market Dynamics
CRISPR multiplexing protocols compress trait development timelines from years to months, forcing livestock genetics firms to restructure R&D workflows around nucleotide-precision breeding programs rather than traditional selective breeding.
Growth Catalysts
- Precision breeding mandates:Large-scale dairy operations in the United States deploy genomic selection to accelerate genetic gain in Holstein herds, cutting generational intervals by half.
- EMA regulatory acceleration:The Committee for Medicinal Products for Veterinary Use streamlines evidentiary pathways for gene-edited food animals, reducing market access timelines for developers.
- Cold-chain biologics expansion:Recombinant vaccine platforms command durable margins as pathogen-free production environments become non-negotiable for export certification.
Market Restraints
- Gene editing reagent concentration:Thermo Fisher Scientific controls upstream distribution of CRISPR enzymes and sequencing platforms, creating single-source dependency for mid-tier developers.
- ISO 17025 accreditation barriers:National reference laboratory designations restrict which manufacturers qualify for regulated jurisdictions, freezing out smaller diagnostic kit producers.
- Transgenic classification uncertainty:Divergent FDA and EMA frameworks for genome-edited versus transgenic determinations force parallel compliance investments.
Strategic Opportunities
- Brazilian livestock modernization:Cattle producers in Mato Grosso and São Paulo states expand artificial insemination and embryo transfer adoption, creating demand for embedded bioinformatics services.
- Proteomics platform displacement:Veterinary reference laboratories in Germany and France replace legacy immunoassays with mass spectrometry-based diagnostics, opening reagent supply contracts.
- WTO traceability alignment:Harmonized standards for gene-edited animal product labeling reduce regulatory fragmentation costs for multi-jurisdictional developers.
Industry Challenges
- Bioinformatics talent scarcity:Veterinary clinics lack personnel to interpret genomic data outputs from precision breeding programs, creating service delivery bottlenecks.
- Pathogen-free facility capex:GMP-compliant production environments for recombinant vaccines require capital commitments that strain mid-cap biotechnology firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Animal Biotechnology Market |
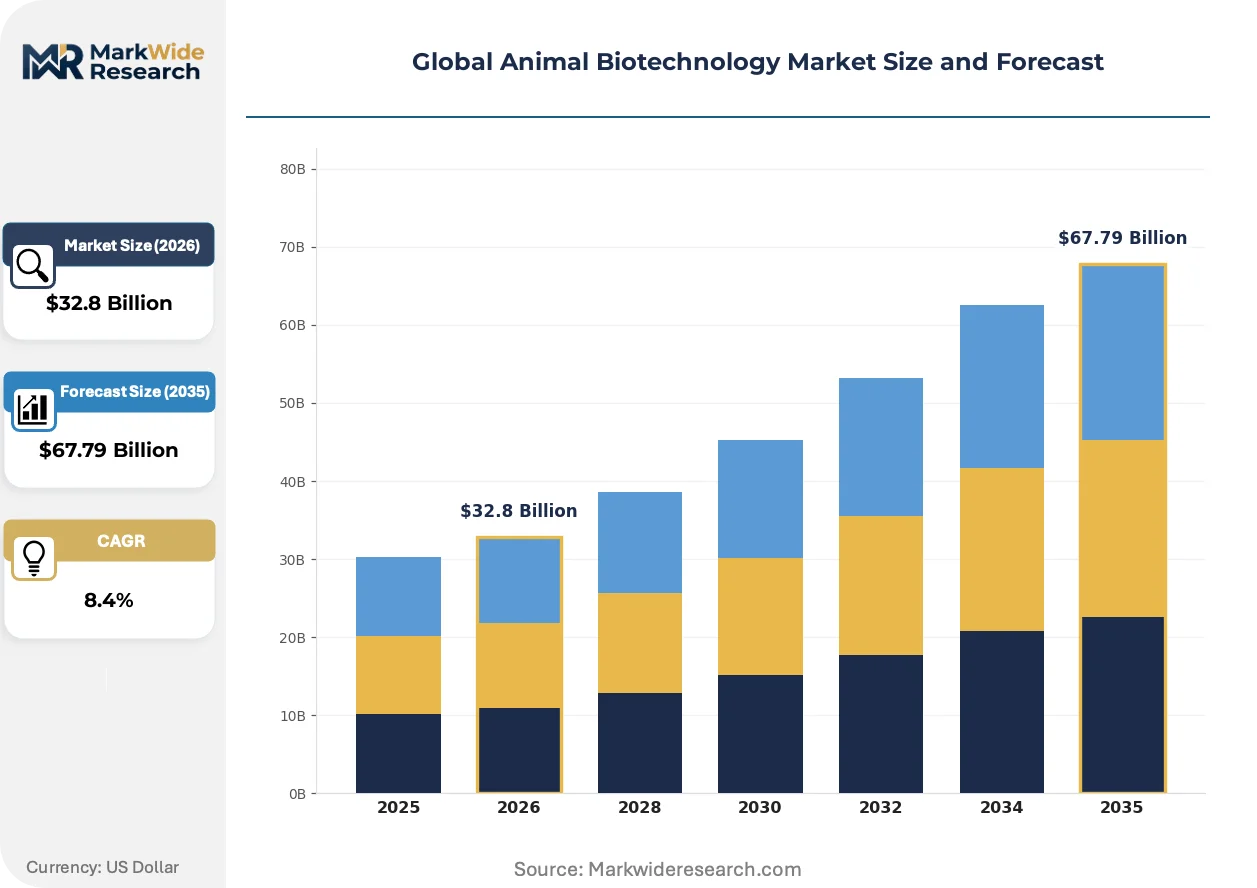
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genetically Modified Organisms, Recombinant Vaccines, Diagnostics Kits, Cell Lines, Bioinformatics Tools Application: Veterinary Diagnosis, Disease Treatment, Genetic Modification, Reproductive Technologies, Feed Improvement End User: Research Institutions, Biopharmaceutical Companies, Veterinary Clinics, Animal Breeders, Food Producers Technology: Gene Editing, Cloning, PCR Techniques, Proteomics, Transcriptomics, Microarrays |
| Companies Covered | Zoetis Inc., Boehringer Ingelheim International GmbH, Merck & Co., Inc., Elanco Animal Health Inc., Virbac S.A., IDEXX Laboratories Inc., Heska Corporation, Thermo Fisher Scientific Inc., Biogénesis Bagó, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Animal Biotechnology Market Shifts & Advancements
Multiplex gene editing platforms and AI-driven phenotypic prediction models are compressing the interval between genomic discovery and commercial trait deployment, restructuring competitive advantage around computational biology capabilities rather than germplasm archives alone.
Single-cell sequencing workflows paired with machine learning trait prediction is digitizing how livestock breeders select for disease resistance and feed efficiency. Large-scale beef operations in Australia and Argentina deploy these platforms to halve the time required to validate genetic markers. The structural consequence is a shift from pedigree-based selection to real-time genomic indexing of replacement heifers.
The EU Green Deal's Farm to Fork strategy tightens sustainability reporting requirements for animal protein supply chains, compelling biotechnology firms to document carbon footprint reductions from precision breeding. German and Dutch regulators now require lifecycle assessments for gene-edited livestock products prior to market authorization. This pressure forces developers to integrate environmental impact metrics into trait selection criteria alongside yield and health outcomes.
Consolidation among dairy cooperatives in Wisconsin and California shifts procurement toward bundled genetics-plus-analytics contracts rather than discrete germplasm sales. Smaller artificial insemination service providers lose share to integrated platforms offering genomic testing, breeding recommendations, and herd management software. This pattern concentrates buying power among fewer livestock operations with capital to invest in end-to-end precision breeding infrastructure.
Global Animal Biotechnology Market Segmentation
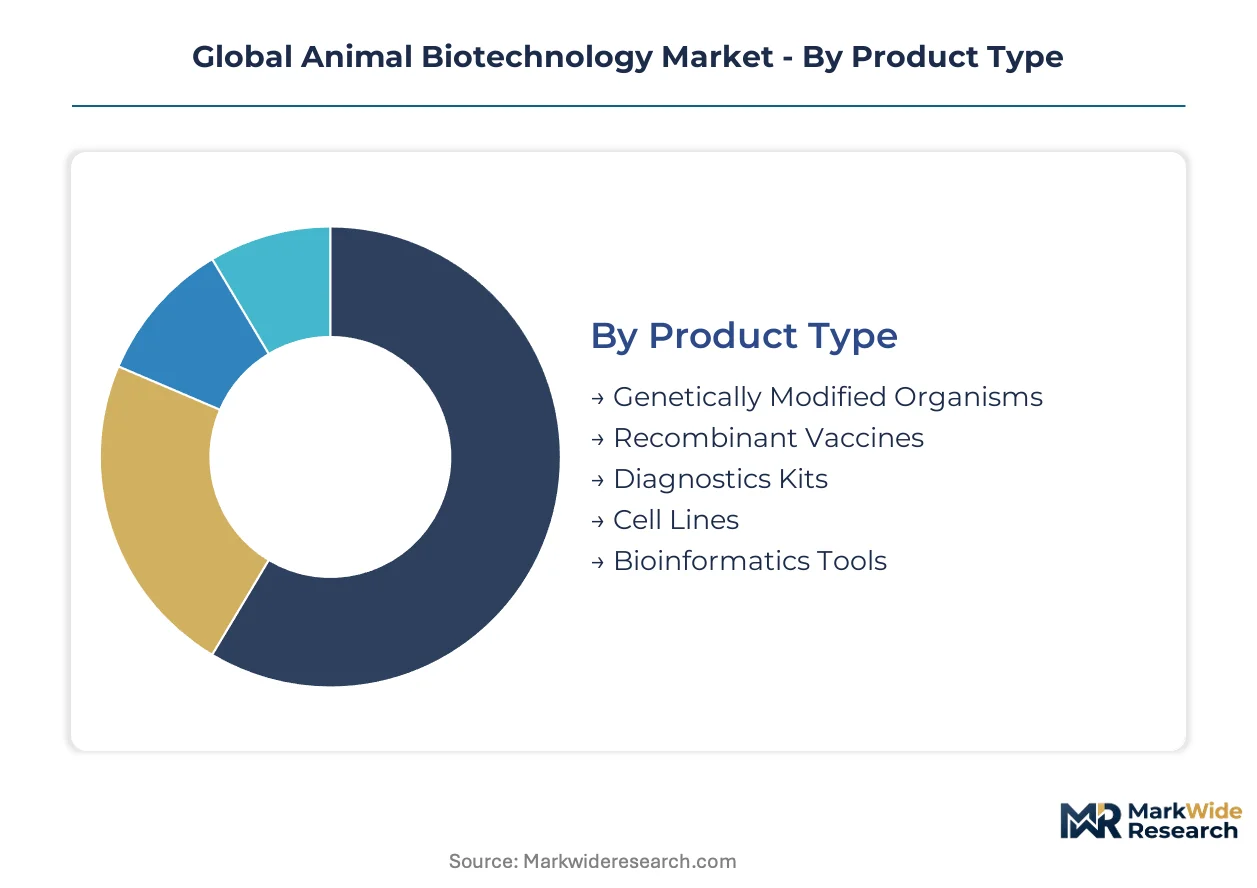
Segmentation in animal biotechnology reveals how value pools concentrate across distinct technical domains and customer workflows. Product type divisions expose margin structures shaped by regulatory complexity, while technology splits illuminate where R&D capital is reallocating fastest.
Product Type:
Cost tier stratification separates premium biologics from commoditized reagents, with pricing power tracking regulatory exclusivity and production complexity.
- Genetically Modified Organisms:Living modified animals or embryos engineered for enhanced traits, requiring multi-generational stability validation. Demand concentrates in large-scale dairy operations across Wisconsin and California, driven by genomic selection mandates that compress generational intervals.
- Recombinant Vaccines:Subunit or vector-based immunogens produced in pathogen-free cell culture systems, commanding durable margins through cold-chain logistics and veterinary prescription requirements. Brazilian cattle producers in Mato Grosso drive procurement volumes as export certification standards tighten.
- Diagnostics Kits:Immunoassay and nucleic acid detection platforms for pathogen identification.
- Cell Lines:Immortalized cultures for vaccine production and monoclonal antibody generation.
- Bioinformatics Tools:Software platforms for genomic data interpretation and breeding decision support.
Recombinant vaccines command the established base. The steepest expansion runs through genetically modified organisms.
Application:
Application scope tracks how biotechnology penetrates distinct operational stages across livestock production and companion animal care.
- Veterinary Diagnosis:Pathogen detection and disease surveillance workflows, spanning PCR-based screening to serological profiling. German and French reference laboratories displace legacy immunoassays with mass spectrometry platforms, opening reagent supply contracts for proteomics vendors.
- Genetic Modification:Genome editing and transgenic development for trait enhancement, operating at nucleotide precision thresholds. FDA and EMA regulatory acceleration for CRISPR-edited food animals compresses market access timelines in the United States and European Union.
- Disease Treatment:Therapeutic biologics and gene therapy interventions for veterinary patients.
- Reproductive Technologies:Artificial insemination, embryo transfer, and in vitro fertilization protocols.
- Feed Improvement:Enzyme additives and microbiome modulation for nutritional efficiency.
Veterinary diagnosis anchors current revenue. Genetic modification is climbing the fastest as multiplex editing protocols mature.
End User:
Customer type segmentation exposes divergent procurement patterns between research-funded institutions and commercially driven livestock operations.
- Research Institutions:Academic and government laboratories conducting foundational genomics and transgenic model development. Funding flows from NIH and USDA competitive grants in the United States, with EU Horizon programs supporting parallel capabilities in the Netherlands and Denmark.
- Biopharmaceutical Companies:Developers of veterinary therapeutics and human pharmaceutical models using transgenic animals. Capital allocation concentrates in Massachusetts and California clusters, driven by FDA Center for Veterinary Medicine approval pathways for novel biologics.
- Veterinary Clinics:Point-of-care diagnostics and treatment service providers.
- Animal Breeders:Commercial germplasm producers and genetic improvement programs.
- Food Producers:Integrated livestock operations with captive breeding and health management functions.
Research institutions represent the stable demand foundation. Biopharmaceutical companies are gaining share fastest through precision breeding platform licensing.
Technology:
Technology splits map competitive advantage from molecular tool maturity, with newer modalities displacing established workflows.
- Gene Editing:CRISPR-Cas systems and base editing platforms enabling targeted genomic modifications without foreign DNA integration. Thermo Fisher Scientific controls upstream enzyme distribution, creating single-source dependency for mid-tier developers in the United States and European Union.
- Proteomics:Mass spectrometry and protein microarray platforms for biomarker discovery and diagnostic validation. Australian and Argentine beef operations deploy single-cell sequencing paired with proteomic phenotyping to halve genetic marker validation timelines.
- Cloning:Somatic cell nuclear transfer for genetic replication of elite animals.
- PCR Techniques:Amplification-based pathogen detection and genetic screening.
- Transcriptomics:RNA sequencing and expression profiling for functional genomics.
- Microarrays:Hybridization-based genotyping for high-throughput screening.
PCR techniques retain the installed base. Gene editing shows the steepest expansion trajectory as regulatory frameworks clarify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Large-scale dairy operations in the United States deploy genomic selection for accelerated genetic gain, while Brazilian cattle producers prioritize reproductive technologies for export certification compliance. European markets emphasize sustainability-linked regulatory frameworks that reshape product authorization pathways.
United States
Holstein herds in Wisconsin and California drive demand for precision breeding platforms that compress generational intervals. The FDA Center for Veterinary Medicine tightens evidentiary standards for gene-edited food animals while streamlining review timelines for CRISPR applications. Greater Boston and California biotech clusters concentrate transgenic model development for pharmaceutical research, attracting venture allocation from NIH and USDA competitive grant programs.
Brazil
Cattle producers in Mato Grosso and São Paulo states expand artificial insemination and embryo transfer adoption to meet tightening export certification standards. ANVISA aligns with international traceability mandates for gene-edited animal products, reducing regulatory fragmentation for multi-jurisdictional developers. The São Paulo industrial corridor anchors embedded bioinformatics service delivery for livestock genetics firms.
Germany
Veterinary reference laboratories in Munich and Berlin displace legacy immunoassays with mass spectrometry-based diagnostics, opening reagent supply contracts for proteomics vendors. The EU Green Deal's Farm to Fork strategy mandates lifecycle assessments for gene-edited livestock products prior to market authorization. Bavaria's research triangle concentrates AI-driven phenotypic prediction model development for feed efficiency traits.
China
Large-scale pork operations in Sichuan-Chongqing and Shandong Peninsula deploy single-cell sequencing paired with machine learning for disease resistance marker validation. The national agricultural regulator establishes traceability frameworks for genome-edited versus transgenic classifications that parallel FDA and EMA determinations. Yangtze River Delta biotech parks attract domestic capital for CRISPR multiplexing protocol commercialization.
Australia
Beef operations in Queensland and New South Wales halve genetic marker validation timelines through real-time genomic indexing of replacement heifers. The TGA coordinates with WTO standards for harmonized gene-edited animal product labeling requirements. Sydney and Melbourne veterinary research hubs concentrate proteomics platform development for pathogen surveillance in export-oriented livestock supply chains.
Global Animal Biotechnology Market Competitive Landscape
Capability concentration sits with specialized tool providers; scale advantage sits with integrated veterinary health conglomerates. The market structures around three tiers: upstream reagent suppliers controlling enzyme distribution, diagnostics-to-therapeutics platforms capturing recurring revenue, and embedded bioinformatics services locking in long-term clinic relationships. Dominant competitive moves include strategic partnerships for regulatory pathway navigation and portfolio diversification into precision breeding analytics.
Within the integrated platform tier, Zoetis Inc. and Boehringer Ingelheim International GmbH exemplify the diagnostics-to-therapeutics model, while Thermo Fisher Scientific Inc. anchors upstream supply chain control over gene editing reagents and sequencing platforms. These three entities represent distinct archetypes: the full-service veterinary health conglomerate, the embedded bioinformatics service provider, and the critical reagent monopolist.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Boehringer Ingelheim International GmbH |
| Merck & Co., Inc. |
| Elanco Animal Health Inc. |
| Virbac S.A. |
| IDEXX Laboratories Inc. |
| Heska Corporation |
| Thermo Fisher Scientific Inc. |
| Biogénesis Bagó |
| Others |
Supply & Pricing Matrix
Single-source dependency on CRISPR enzyme distribution from Thermo Fisher Scientific determines both tiered pricing spreads and supply chain configuration, forcing mid-tier developers into long-term offtake contracts while squeezing margin structures across diagnostics and vaccine production tiers.
Pricing Analysis
Long-term offtake agreements dominate recombinant vaccine procurement, locking in price stability for Brazilian cattle producers facing export certification mandates. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-accredited reference laboratories from point-of-care clinics and research institutions. Cost compression in standard-tier diagnostics is intensifying as proteomics platforms displace legacy immunoassays, with veterinary clinics showing highest price sensitivity and large-scale dairy operations least affected.
Supply Chain Analysis
Extended payment terms from gene editing reagent suppliers strain mid-cap biotechnology firms developing CRISPR applications. Upstream concentration centers on the United States for sequencing platforms, Germany for mass spectrometry diagnostics, and China for single-cell sequencing consumables. Raw material dependencies include pathogen-free cell culture media, synthetic guide RNA, and recombinant protein substrates. Single-source vulnerability in CRISPR-Cas enzyme supply creates regulatory chokepoint risk. Distribution runs through veterinary clinic networks, reference laboratory chains, and direct institutional procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based protein alternatives and precision fermentation threaten substitution pressure on conventional livestock genetics, requiring incumbents to demonstrate measurable productivity gains from biotechnology adoption.
For Market Incumbents: Build regulatory exclusivity moats through accelerated FDA Center for Veterinary Medicine and EMA pathway navigation for gene-edited food animals. Deepen backward integration into pathogen-free production facilities to capture recombinant vaccine margins. Defend against emerging bioinformatics specialists by embedding AI-driven phenotypic prediction into bundled genetics-plus-analytics contracts. For New Entrants and Emerging Players: Underpenetration in Brazilian embedded bioinformatics services offers white-space capture for livestock genetics firms lacking local computational biology infrastructure. Target Australian beef operations deploying real-time genomic indexing, where proteomics platform displacement creates reagent supply openings. Pursue partnership-based go-to-market models with Mato Grosso cattle cooperatives seeking export certification compliance. For Investors and Strategic Acquirers: The market sits at a regulatory-clarification phase that favors vertically integrated veterinary health conglomerates over specialized tool providers. Five-to-ten year viability hinges on portfolio diversification into precision breeding analytics rather than germplasm commoditization. Target acquisition archetypes: diagnostics-to-therapeutics platforms with captive clinic relationships. Watch for FDA-EMA harmonization on genome-edited versus transgenic classifications as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway Navigation | EMA streamlining for CRISPR-edited food animals compresses market access timelines for developers. |
| Embedded Bioinformatics Service Expansion | Boehringer Ingelheim's software platforms lock in long-term veterinary clinic relationships across Germany. |
| Pathogen-Free Manufacturing Scale-Up | GMP-compliant facilities for recombinant vaccines satisfy Brazilian ANVISA export certification requirements. |
| Proteomics Platform Licensing | Mass spectrometry reagent contracts with French reference laboratories displace legacy immunoassay suppliers. |
| Precision Breeding Analytics Integration | Wisconsin dairy cooperatives shift procurement toward bundled genetics-plus-software contracts. |
Research Methodology
Cross-validation between primary interviews with livestock genetics executives, veterinary clinic operators, and regulatory affairs specialists and secondary validation through FDA Center for Veterinary Medicine filings, EMA Committee for Medicinal Products for Veterinary Use submissions, and USDA competitive grant databases anchors the qualitative findings. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators across the analysis window.
Calibration against historical adoption curves for genomic selection and CRISPR multiplexing protocols shapes the analytical framework. Segmentation dimensions span product type, application scope, end-user category, and technology modality. CAGRs derive from fitted growth trajectories incorporating regulatory acceleration timelines and capital allocation patterns into precision breeding infrastructure.
The forecast holds incumbent behavior within observed patterns; aggressive moves by plant-based protein developers or precision fermentation startups would shift outcomes. Macroeconomic volatility in agricultural commodity markets, divergent FDA-EMA regulatory frameworks, or breakthrough advances in base editing efficiency would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biotechnology
Agroscience Market
Agricultural Biotechnology
Asia-Pacific Agriculture Biotech Market
Agricultural Biotechnology
Agricultural Biotechnology Market
Agricultural Biotechnology
Brazil Veterinary Vaccines Market
Agricultural Biotechnology
Microarray in Agriculture Market
Agricultural Biotechnology
Biorationals Market
Agricultural Biotechnology
GMO Crops and Seeds Market
Agricultural Biotechnology
Stigmasterol-Rich Plant Sterols Market
Agricultural Biotechnology
Europe Plant Growth Regulators Market
Agricultural Biotechnology
Duckweed Protein Market
Agricultural Biotechnology
Transgenic Seeds Market
Agricultural Biotechnology
Global Poultry Vaccines Market
Agricultural Biotechnology
Global Plant Hormones Market
Agricultural Biotechnology
Asia Pacific Feed Phytogenics Market
Agricultural Biotechnology
South America Feed Phytogenics Market
Agricultural Biotechnology
Ruminant Vaccines Market