
 Agricultural Biotechnology Market | 2026-2036
Agricultural Biotechnology Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Biotechnology Market Intelligence
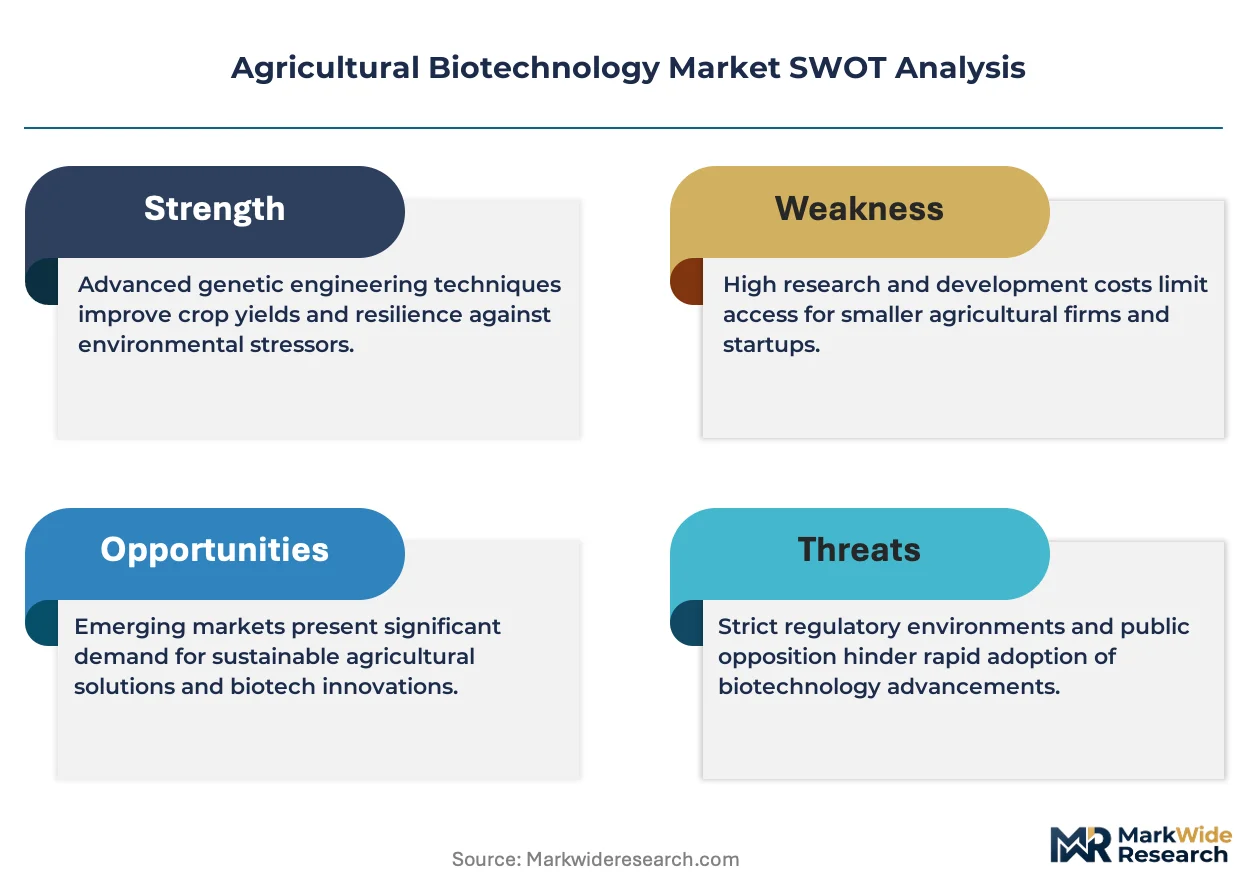
A shortage of molecular breeding specialists is redrawing competitive boundaries across the industry. Bayer AG leverages its integrated seed-chemistry platform to sustain R&D pipelines across multiple crop categories. Corteva Agriscience anchors North American field trials through extensive germplasm libraries. Syngenta Group competes in emerging markets through localized trait development programs.
Agricultural biotechnology encompasses the application of genetic engineering, molecular markers, and tissue culture techniques to modify plant and microbial organisms for enhanced agricultural performance, typically involving DNA insertion, gene silencing, or marker-assisted selection to achieve specific phenotypic outcomes such as herbicide tolerance or drought resistance. Its primary purpose centers on improving crop productivity, reducing chemical inputs, and enabling cultivation under abiotic stress conditions. Genetically modified seeds occupy the dominant value position due to established trait royalties and broad acreage penetration, while biopesticides represent the fastest-expanding product category as residue regulations tighten across import-dependent markets. Gene editing commands concentrated investment from venture-backed startups and incumbent seed companies alike, whereas tissue culture remains a mature, margin-compressed segment serving vegetative propagation for high-value horticulture.
The USDA oversees plant biotechnology deregulation through its Animal and Plant Health Inspection Service, while the EPA evaluates pesticidal proteins in genetically engineered crops under the Federal Insecticide, Fungicide, and Rodenticide Act; the FDA completes the tripartite review framework with voluntary consultation on food safety. These overlapping federal pathways create compliance complexity that favors well-capitalized firms with dedicated regulatory affairs teams. Stakeholders must monitor emerging state-level gene-editing labeling proposals that could fragment market access requirements beyond federal standards.
Market Dynamics
Gene-edited soybeans are accelerating trait development cycles while the EU Green Deal restructures import compliance requirements for seed companies across Brazil and the United States Corn Belt. Molecular breeding specialists remain scarce, forcing incumbents to consolidate R&D pipelines around integrated seed-chemistry platforms.
Growth Catalysts
- EU Green Deal Import Standards:Brazilian seed companies are expanding gene-edited soybean programs to meet residue and sustainability documentation requirements for European grain buyers.
- Precision Breeding in the United States Corn Belt:Large-scale farms are driving investments in marker-assisted selection and high-throughput phenotyping to optimize nitrogen-use efficiency.
- CRISPR-Cas9 Trait Development:Venture-backed startups and incumbent seed firms are deploying multiplexed editing to stack drought tolerance and disease resistance without transgenic regulatory burdens.
Market Restraints
- Phosphorus and Nitrogen Input Volatility:Fertilizer price swings compress margins for trait developers promising nutrient-use efficiency gains that depend on stable input economics.
- Germplasm Library Concentration:North American field trial networks and proprietary seed banks remain controlled by a handful of integrated agrochemical-seed conglomerates.
- EPA Pesticidal Protein Review:Overlapping federal pathways for genetically engineered crops create compliance complexity that disadvantages smaller breeding programs without dedicated regulatory affairs teams.
Strategic Opportunities
- Indian Subsistence Farming Regions:Heat-tolerant rice and millet varieties developed through rapid-cycle marker-assisted selection address abiotic stress in rain-fed cultivation zones.
- Digital Phenotyping Convergence:Satellite imagery and hyperspectral ground sensors are integrating with genomic prediction models to accelerate variety selection for specific microclimates.
- Brazilian State-Level Gene-Editing Frameworks:CTNBio streamlined approval pathways for non-transgenic edited crops, creating regulatory arbitrage opportunities against slower federal systems elsewhere.
Industry Challenges
- Molecular Breeding Talent Scarcity:Quantitative genetics and bioinformatics expertise concentrates in academic institutions and large integrated firms, leaving mid-tier seed companies dependent on contract research organizations.
- Multi-Jurisdictional Trait Registration:Divergent national definitions of genetically modified organisms versus gene-edited products force redundant field trials and dossier preparation for the same event.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Biotechnology Market |
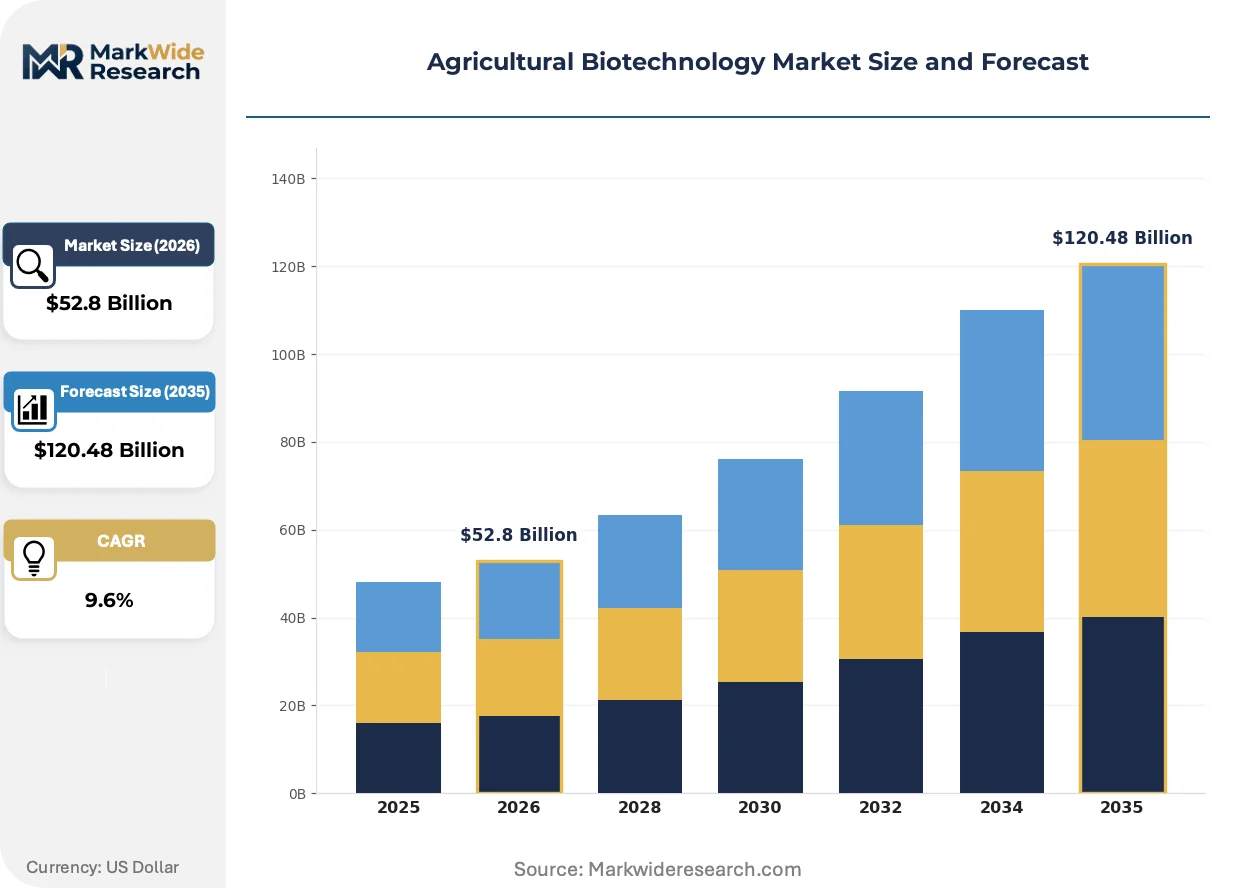
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $120.48 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genetically Modified Seeds, Biofertilizers, Biopesticides, Enzymes, Plant Growth Regulators Application: Crop Protection, Soil Enhancement, Disease Resistance, Pest Control, Yield Improvement End User: Large-Scale Farms, Agribusiness Firms, Research Institutes, Seed Companies, Government Agencies Technology: Gene Editing, RNA Interference, Marker Assisted Selection, Molecular Breeding, Tissue Culture |
| Companies Covered | Bayer AG, Corteva Agriscience, Syngenta Group, BASF SE, KWS SAAT SE & Co. KGaA, Limagrain, Evogene Ltd., Valent BioSciences LLC, Nufarm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Biotechnology Market Strategic Shifts & Innovations
Biotechnology platforms are fragmenting into parallel development tracks as regulatory jurisdictions diverge on edited-versus-transgenic classification. This divergence is compressing time-to-market for some trait categories while extending compliance timelines for others.
CRISPR-Cas12a and base editing systems are bifurcating the precision breeding landscape. Seed companies with established mammalian cell editing expertise are transferring multiplexed guide RNA architectures into plant transformation pipelines. Large-scale row-crop operations in the United States Corn Belt are piloting these tools for herbicide tolerance stacking. The technology is bifurcating trait development into rapid-editing tracks for domestic markets and transgenic-compatible tracks for export-dependent geographies with stricter import protocols.
REACH and EU Green Deal sustainability disclosure requirements are reshaping import documentation for grain traders sourcing from gene-edited supply chains. The European Commission's proposed expansion of novel food regulations to certain editing categories threatens to exclude Brazilian soybean exports from premium European feed markets. Seed companies are responding by segregating edited and conventional seed streams at origin elevators to preserve market optionality.
Farmer procurement of bundled seed-chemistry-trait packages is unbundling as digital platforms enable direct comparison of genetic performance data across breeding programs. Independent agronomists and cooperative purchasing groups in the United States Midwest are displacing traditional dealer networks as the primary influence on variety selection. This channel compression is most visible in Iowa and Illinois, where farm management software integrations allow real-time yield benchmarking against regional variety trials.
Agricultural Biotechnology Market Segmentation
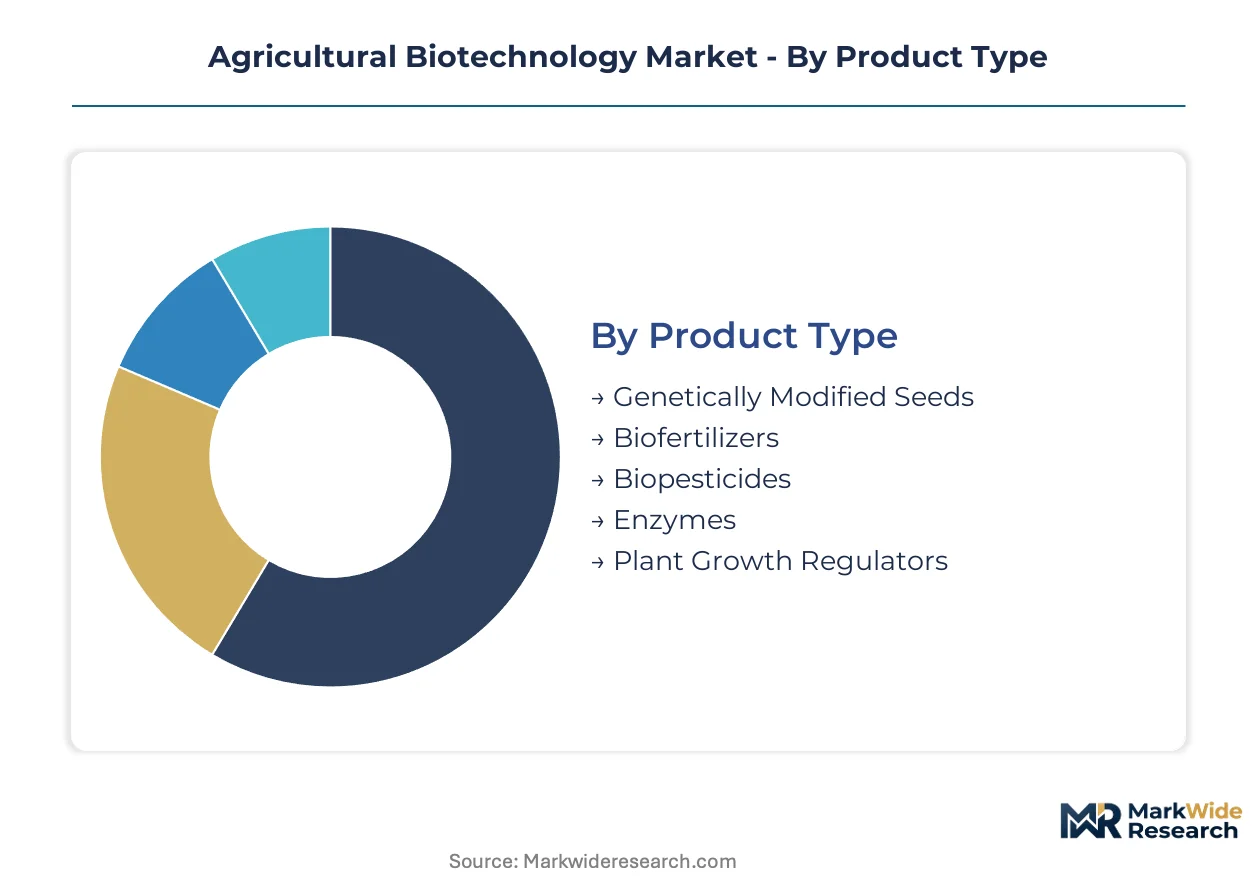
Segmentation in agricultural biotechnology reveals how regulatory jurisdiction and export destination dictate technology adoption patterns. Trait developers must align product portfolios with specific compliance frameworks governing transgenic versus gene-edited classifications.
Product Type:
Domestic consumption in the United States and Brazil centers on stacked-trait seeds, while European import markets drive demand for residue-compliant biopesticides and biofertilizers.
- Genetically Modified Seeds:Stacked herbicide-tolerance and insect-resistance traits dominate acreage in the United States Corn Belt and Brazilian Cerrado. Bayer AG and Corteva Agriscience extract royalty streams through broad patent licensing across North and South American germplasm pools.
- Biofertilizers:Nitrogen-fixing microbial inoculants for soybean and maize root colonization expand fastest in Indian subsistence farming regions where synthetic input costs strain smallholder margins. Regulatory arbitrage between national biofertilizer registration pathways creates market access complexity.
- Biopesticides:Bacillus thuringiensis formulations and botanical extracts target residue thresholds for European grain import contracts.
- Enzymes:Cellulases and amylases process agricultural waste into fermentable substrates for biofuel operations.
- Plant Growth Regulators:Gibberellin and cytokinin applications manage flowering synchronization in high-value horticulture.
Genetically modified seeds command the established base. The steepest expansion runs through biopesticides.
Application:
Cost-tier stratification separates premium trait packages for export-oriented operations from basic protection schemes serving domestic food security programs.
- Crop Protection:Herbicide-tolerance traits and insect-resistant Bt proteins reduce chemical spray passes in large-scale Iowa and Illinois maize operations. EPA pesticidal protein review timelines determine trait launch sequencing.
- Yield Improvement:Drought-tolerance genetics and nitrogen-use efficiency edits concentrate in Brazilian soybean expansion zones facing rainfall variability. CTNBio's streamlined gene-editing approvals accelerate variety release versus transgenic regulatory pathways.
- Soil Enhancement:Microbial inoculants and organic amendment protocols rebuild carbon-depleted Mato Grosso soils.
- Disease Resistance:Fungal and viral resistance traits target Asian soybean rust and maize lethal necrosis.
- Pest Control:RNA interference sprays and mating disruption pheromones complement seed-trait protection.
Crop protection anchors revenue concentration. Yield improvement gains share fastest in climate-stressed production zones.
End User:
Customer-type fragmentation splits procurement between consolidated acreage operators seeking bundled packages and fragmented smallholders accessing traits through cooperative structures.
- Large-Scale Farms:Precision breeding investments concentrate in Nebraska and Kansas operations exceeding 5,000 acres, where digital phenotyping platforms justify per-acre technology fees. Farm management software integrations enable real-time yield benchmarking against regional variety trials.
- Seed Companies:Germplasm library development and trait stacking pipelines absorb R&D capital from integrated agrochemical conglomerates. Molecular breeding specialist scarcity forces mid-tier firms toward contract research organization dependencies.
- Agribusiness Firms:Grain traders and processors demand sustainability documentation aligned with EU Green Deal import standards.
- Research Institutes:Public sector breeding programs advance heat-tolerant rice and millet for Indian rain-fed cultivation.
- Government Agencies:Subsidy programs and biosafety frameworks shape technology diffusion in emerging markets.
Large-scale farms drive premium trait adoption. Seed companies capture margin through intellectual property control.
Technology:
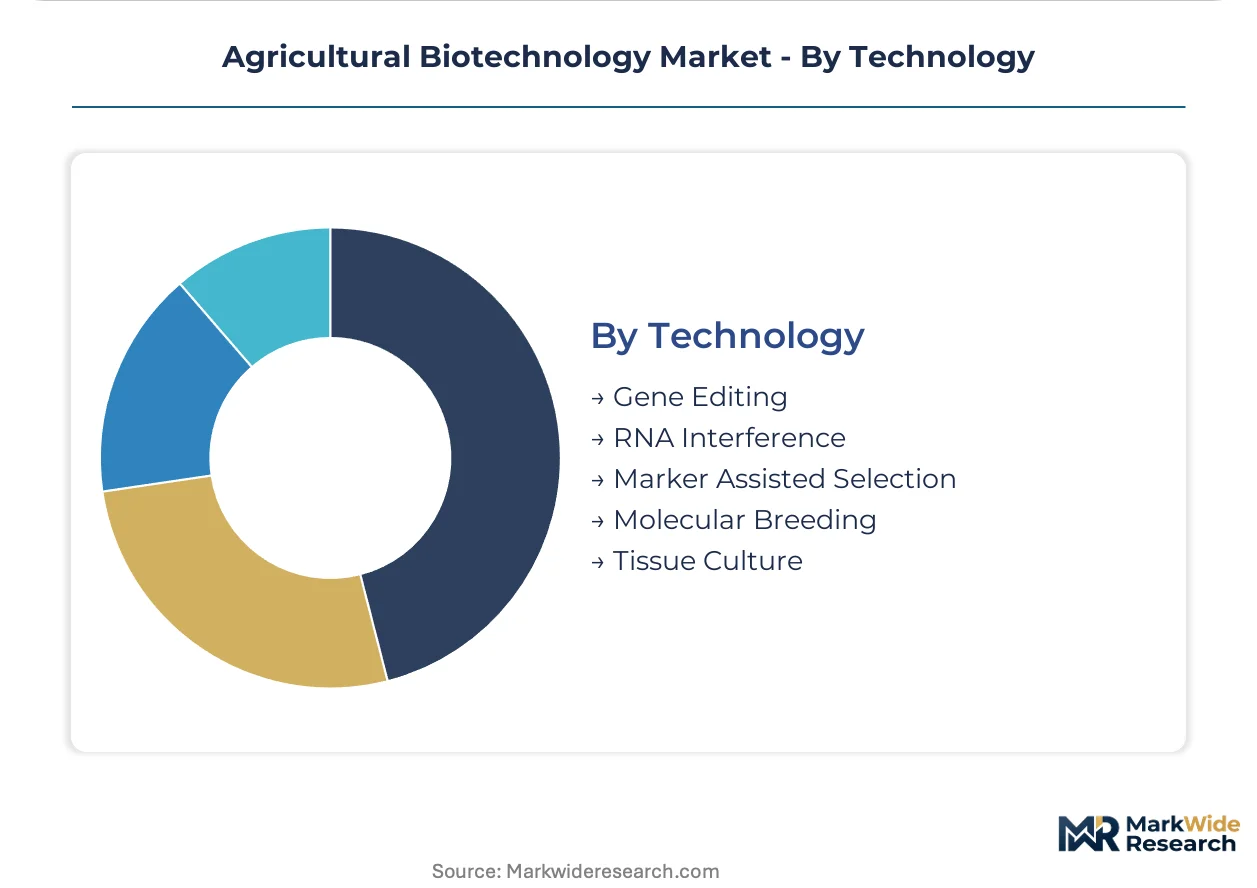
Maturity-stage divergence separates commercialized molecular breeding from venture-backed gene-editing platforms awaiting regulatory clarity.
- Gene Editing:CRISPR-Cas9 and Cas12a systems enable drought-tolerance stacking without transgenic regulatory burdens in Brazilian and United States domestic markets. Multiplexed guide RNA architectures transfer from mammalian cell expertise into plant transformation pipelines.
- Marker Assisted Selection:High-throughput genotyping and genomic prediction models accelerate variety selection for specific United States Corn Belt microclimates. Established infrastructure supports nitrogen-use efficiency breeding programs.
- RNA Interference:Sprayable double-stranded RNA targets specific pest species without broad ecological disruption.
- Molecular Breeding:Quantitative trait locus mapping and genomic selection underpin conventional trait introgression.
- Tissue Culture:Somatic embryogenesis and micropropagation serve vegetative propagation for high-value horticulture with compressed margins.
Marker assisted selection commands the installed base. Gene editing climbs fastest as regulatory jurisdictions diverge on edited-versus-transgenic classification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA deregulation pathways through APHIS anchor North American biotechnology adoption, while Brazil's CTNBio accelerates gene-edited crop approvals and the EU Green Deal reshapes import compliance documentation for grain traders.
United States
Large-scale Corn Belt operations exceeding 5,000 acres drive precision breeding investments in nitrogen-use efficiency traits. EPA pesticidal protein review timelines under FIFRA determine trait launch sequencing for stacked herbicide-tolerance products. Iowa and Illinois field trial networks concentrate germplasm development for maize and soybean varieties.
Brazil
Seed companies expand gene-edited soybean programs to meet EU Green Deal sustainability documentation requirements for European feed markets. CTNBio streamlined approval pathways for non-transgenic edited crops, creating regulatory arbitrage against slower federal systems elsewhere. Mato Grosso and São Paulo state research clusters anchor South American trait development pipelines.
Germany
Specialized molecular breeding equipment and genomic prediction software suppliers serve European research institutes. REACH sustainability disclosure requirements and EFSA novel food regulations constrain transgenic product market access. Bavaria and Baden-Württemberg host precision agriculture technology development centers.
India
Heat-tolerant rice and millet varieties developed through rapid-cycle marker-assisted selection address abiotic stress in rain-fed cultivation zones. FSSAI and the national biosafety regulatory framework govern genetically engineered crop field trials. Telangana and Maharashtra research stations advance public sector breeding programs for subsistence farming regions.
China
National biosafety certificate requirements and import approval pathways for genetically modified crops shape domestic seed company R&D priorities. MEE environmental impact assessments and SAMR food safety regulations complete the oversight framework. Beijing-Tianjin-Hebei and Yangtze River Delta clusters concentrate crop biotechnology research infrastructure.
Agricultural Biotechnology Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with germplasm library concentration and regulatory affairs capabilities determining competitive position. Incumbents leverage seed-chemistry platform integration to sustain R&D pipelines across multiple crop categories. Two strategic archetypes dominate: integrated agrochemical-seed conglomerates controlling proprietary germplasm pools, and venture-backed gene-editing specialists deploying CRISPR architectures. Competitive moves center on molecular breeding talent acquisition and multi-jurisdictional trait registration dossier preparation.
Within the integrated conglomerate tier, Bayer AG, Corteva Agriscience, and Syngenta Group exemplify platform-scale players with established field trial networks and broad patent licensing positions. These Germany-based, US-based, and China-based entities occupy positions defined by germplasm library depth and regulatory affairs infrastructure rather than discrete product categories.
| Leading Market Players |
|---|
| Bayer AG |
| Corteva Agriscience |
| Syngenta Group |
| BASF SE |
| KWS SAAT SE & Co. KGaA |
| Limagrain |
| Evogene Ltd. |
| Valent BioSciences LLC |
| Nufarm |
| Others |
Cost & Logistics Intelligence
Long-term trait-licensing contracts between seed companies and large-scale Corn Belt operators lock in multi-year technology fee commitments while providing visibility into germplasm pipeline access. These agreements concentrate pricing power with integrated agrochemical-seed conglomerates holding proprietary germplasm libraries, while fertilizer price volatility feeds back into farmer willingness to pay for nutrient-use efficiency traits.
Pricing Analysis
Price spreads between Brazilian gene-edited soybean premiums and United States Corn Belt stacked-trait baselines reflect divergent regulatory compliance costs and export market access tiers. Royalty-based pricing structures dominate genetically modified seeds, with differentiation driven by trait stacking complexity and EPA pesticidal protein registration status. Cost compression in basic trait packages intensifies as digital platforms enable direct price comparison across breeding programs. Cooperative purchasing groups in Iowa and Illinois exhibit highest price sensitivity, while export-oriented operations in Mato Grosso prioritize residue-compliant premiums over unit economics.
Supply Chain Analysis
Just-in-time seed inventory management prevails among large-scale United States operators, while Brazilian traders maintain strategic stockpiles to navigate EU Green Deal documentation windows. Germplasm development concentrates in the United States, Brazil, and Germany, with proprietary seed banks anchoring R&D pipelines. Supply chains draw from CRISPR reagent suppliers, high-throughput genotyping service providers, and specialized phenotyping equipment manufacturers. Single-source vulnerability runs through concentrated molecular breeding specialist pools. Distribution runs through dealer networks undergoing channel compression from farm management software platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as seed-chemistry-biotechnology convergence creates winner-take-most dynamics around integrated germplasm-data-chemistry stacks. Interoperability between genomic prediction models and satellite-based phenotyping platforms is redrawing ecosystem boundaries.
For Market Incumbents: Shield germplasm library value through accelerated CRISPR trait stacking in Brazilian and United States domestic markets, where CTNBio and USDA deregulation pathways offer regulatory arbitrage. Prioritize backward integration into high-throughput genotyping infrastructure to reduce contract research organization dependencies. Channel control investments should target farm management software integrations displacing traditional dealer networks in Iowa and Illinois.
For New Entrants and Emerging Players: Anchor in Indian subsistence farming regions, where heat-tolerant rice and millet varieties developed through rapid-cycle marker-assisted selection address unmet abiotic stress needs. Target public sector breeding program partnerships as the most penetrable channel, given molecular breeding talent scarcity at mid-tier seed companies. Pursue regulatory dossier preparation services as a go-to-market angle, exploiting multi-jurisdictional trait registration complexity.
For Investors and Strategic Acquirers: Gene-editing specialists with mammalian-to-plant technology transfer capabilities represent the most defensible acquisition archetype, given multiplexed guide RNA architecture advantages. Long-term viability hinges on regulatory jurisdiction divergence persisting across the analysis window. Watch CTNBio approval velocity versus EPA FIFRA review timeline compression as the inflection signal for platform-scale consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Trait Stacking Pipeline Expansion | Accelerates drought-tolerance and disease-resistance combinations without transgenic regulatory burdens under CTNBio pathways. |
| Digital Phenotyping Platform Integration | Links satellite imagery and hyperspectral sensors with genomic prediction models for microclimate-specific variety selection. |
| Germplasm Library Acquisition | Consolidates proprietary seed banks and field trial networks currently fragmented across mid-tier breeding programs. |
| Regulatory Affairs Infrastructure Buildout | Navigates overlapping USDA-EPA-FDA pathways and emerging state-level gene-editing labeling proposals. |
| Farm Management Software Partnership | Captures channel compression in Iowa and Illinois as cooperative purchasing groups displace traditional dealer networks. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with seed company R&D directors, regulatory affairs leads at integrated agrochemical conglomerates, farm management software platform engineers, and cooperative purchasing group agronomists in the United States Corn Belt. Secondary validation drew from USDA APHIS deregulation filings, EPA FIFRA registration databases, CTNBio approval records, and SEC 10-K disclosures from listed agrochemical-seed companies. Bottom-up acreage and trait penetration estimates were triangulated against top-down market value reconstructions.
Across the projection horizon, the analytical framework modeled segmentation dimensions including technology type, crop application, farm scale tier, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to trait adoption histories and adjusted for policy inflection scenarios. Industry-specific forecast inputs incorporated CTNBio approval velocity indices and EU Green Deal sustainability disclosure implementation timelines.
Material uncertainties — regulatory reclassification of gene-edited products, phosphorus and nitrogen input price volatility, and molecular breeding specialist supply constraints — sit outside the modeled envelope. Forecasts reflect assumptions about jurisdictional divergence on edited-versus-transgenic classification persisting throughout the analysis window. Revision becomes warranted when EPA FIFRA review timelines or EU novel food regulation expansions cross threshold disruption levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biotechnology
Global Animal Biotechnology Market
Agricultural Biotechnology
Global Poultry Vaccines Market
Agricultural Biotechnology
Plant-Based Vaccines Market
Agricultural Biotechnology
Africa Algae Protein Market
Agricultural Biotechnology
Biorationals Market
Agricultural Biotechnology
Agroscience Market
Agricultural Biotechnology
Brazil Veterinary Vaccines Market
Agricultural Biotechnology
Europe Plant Growth Regulators Market
Agricultural Biotechnology
South America Feed Phytogenics Market
Agricultural Biotechnology
Transgenic Seeds Market
Agricultural Biotechnology
Europe Agriculture Biotech Market
Agricultural Biotechnology
GMO Crops and Seeds Market
Agricultural Biotechnology
Asia-Pacific Agriculture Biotech Market
Agricultural Biotechnology
Duckweed Protein Market
Agricultural Biotechnology
Asia Pacific Feed Phytogenics Market
Agricultural Biotechnology
Ruminant Vaccines Market