
 Europe Plant Growth Regulators Market | 2026-2036
Europe Plant Growth Regulators Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Plant Growth Regulators Market Foresight
Synthetic auxin chemistry is decoupling from petroleum-derived feedstocks as European manufacturers pivot to fermentation-based precursors. BASF SE leverages its Ludwigshafen integrated complex to secure backward integration into biotechnological cytokinin intermediates. Bayer Crop Science anchors its position through high-R&D intensity in ethylene-release formulations tailored to Mediterranean horticulture. Syngenta Group differentiates via proprietary granular delivery systems that reduce drift losses in field crop applications.
Plant growth regulators comprise organic compounds that modulate physiological processes in cultivated plants, including cell elongation, division, and differentiation, typically applied at concentrations below one part per million to trigger hormonal responses without phytotoxicity. Their primary commercial purpose centers on optimizing agricultural productivity through controlled flowering acceleration, fruit thinning, and stress tolerance enhancement across intensive farming systems. Cytokinins command the dominant product position due to established efficacy in tissue culture propagation and post-harvest shelf-life extension, while gibberellins represent the fastest-expanding category driven by seedless grape and citrus cultivation expansion across southern Europe. Liquid formulations retain the largest share of form-based demand, though tablet configurations are gaining traction among precision viticulture operators seeking metered dosing accuracy.
The European Commission's Farm to Fork strategy and ECHA's REACH framework jointly constrain synthetic agrochemical portfolios while creating preferential pathways for microbial-derived regulator registrations. EFSA residue reassessments are tightening maximum residue limits for conventional auxin products, redirecting formulation investment toward bio-stimulant-integrated alternatives. France's ANSES and Germany's BfR coordinate divergent national hazard classifications that complicate pan-European product authorization strategies. Stakeholders must monitor the evolving interface between EU Green Deal carbon accounting rules and plant growth regulator manufacturing process certifications to anticipate compliance cost trajectories.
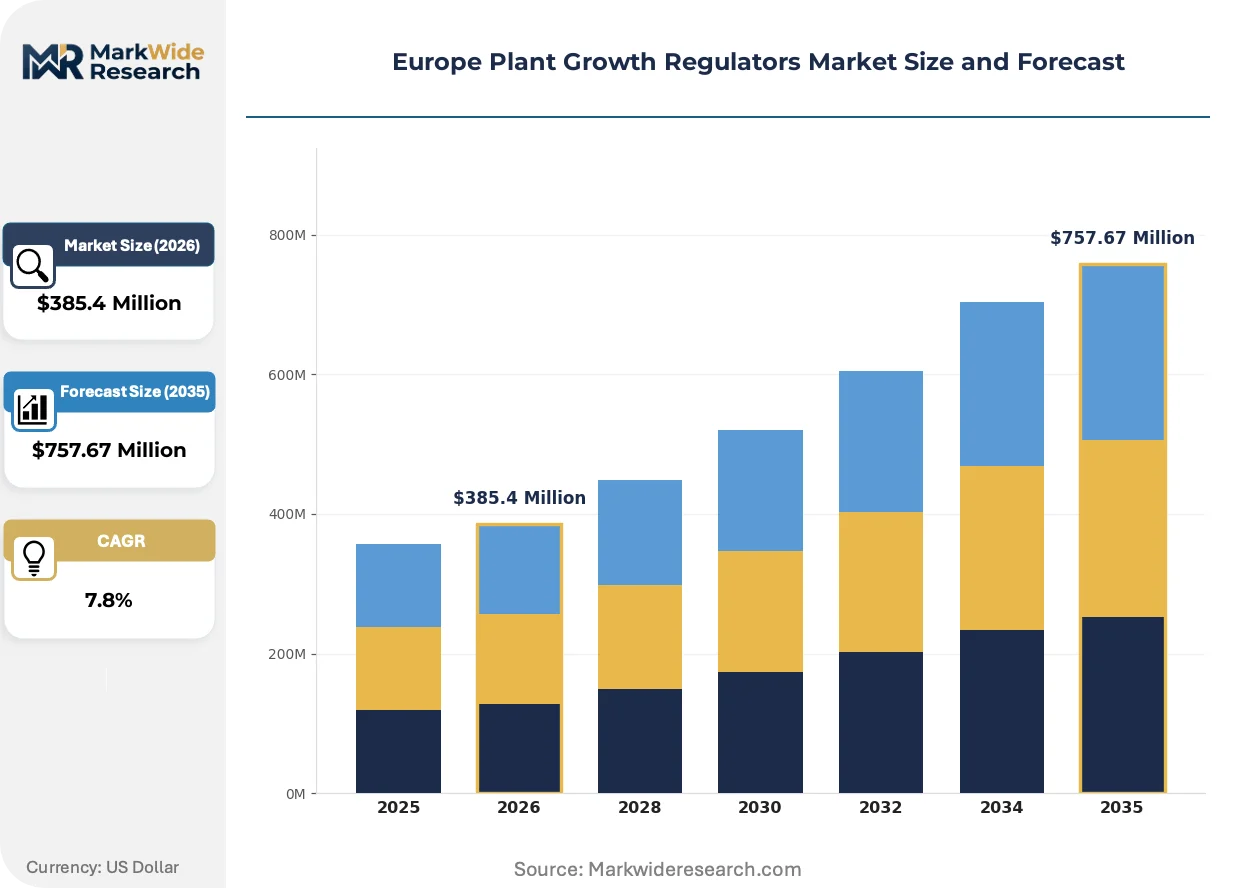
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing synthetic chemistry margins while accelerating bio-based formulation approvals, forcing manufacturers to reconfigure production footprints around fermentation-derived precursors and integrated carbon accounting.
Growth Catalysts
- Precision viticulture adoption:French and Italian orchard operators deploy metered gibberellin dosing systems to optimize fruit set uniformity under water-stress conditions.
- REACH bio-based registration pathways:ECHA's streamlined microbial-derived substance approvals reduce time-to-market for cytokinin alternatives sourced from fermentation processes.
- Post-harvest shelf-life extension:Spanish citrus packers integrate cytokinin treatments to reduce cold-chain spoilage losses in export logistics to northern European markets.
Market Restraints
- Petroleum feedstock volatility:Synthetic auxin production remains exposed to naphtha and benzene price swings that compress formulation margins.
- EFSA residue reassessments:Tightening maximum residue limits for conventional 2,4-D products force reformulation investments without guaranteed authorization timelines.
- Biological substitute encroachment:Protein-based biostimulants from agricultural waste streams capture share in soil-applied growth promotion segments.
Strategic Opportunities
- Table grape seedless expansion:Portuguese and Greek producers increase gibberellin uptake to meet supermarket specifications for uniform berry sizing.
- Granular delivery system deployment:Precision agriculture contractors in Germany's Rhineland adopt drift-reducing tablet configurations for field crop applications.
- CSRD carbon disclosure alignment:Manufacturers embedding process emissions data into product certifications gain preferential access to sustainability-linked procurement pools.
Industry Challenges
- Cross-border authorization fragmentation:Divergent hazard classifications between France's ANSES and Germany's BfR complicate pan-European product registration strategies.
- Fermentation scale-up capital requirements:Biotechnological cytokinin production demands dedicated bioreactor infrastructure with long depreciation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Plant Growth Regulators Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $757.67 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Auxins, Cytokinins, Gibberellins, Ethylene Application: Field Crops, Horticulture, Turf, Ornamentals Form: Liquid, Granular, Powder, Tablet Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | BASF SE, Bayer Crop Science, Corteva Agriscience, Syngenta Group, FMC Corporation, Nufarm, Sumitomo Chemical Co., Ltd., UPL, Tata Chemicals Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Plant Growth Regulators Market Shifts & Advancements
Bio-fermentation processes are displacing petrochemical synthesis routes across European manufacturing bases, while regulatory carbon accounting rules reshape competitive positioning around verified supply chain emissions data.
Microbial-derived cytokinin production is expanding into commercial-scale manufacturing as BASF SE and specialized biotech suppliers deploy continuous fermentation systems at Ludwigshafen and comparable integrated sites. Spanish and Italian tissue culture propagation facilities adopt these bio-based intermediates for ornamental and fruit tree cloning operations. This shift is expanding into premium formulation tiers where carbon footprint certifications command price premiums over conventional synthetic alternatives.
EFSA's systematic reassessment of auxin residue limits under the EU Green Deal's chemical sustainability criteria is forcing reformulation investments toward bio-stimulant-integrated alternatives. The Farm to Fork strategy's 50% pesticide reduction target redirects R&D expenditure from synthetic chemistry toward microbial metabolite screening. Southern European horticulture sectors face the steepest compliance transitions as their established 2,4-D and naphthaleneacetic acid applications require rapid substitution.
Specialty crop producers in France's Champagne and Bordeaux regions now specify metered-dose tablet formulations rather than bulk liquid procurement, compressing distributor margins while rewarding precision application technology providers. German precision viticulture contractors consolidate purchasing through direct manufacturer relationships, bypassing traditional agrochemical distribution layers. This channel restructuring is most visible in high-value permanent crop segments where application timing accuracy directly correlates with harvest quality premiums.
Europe Plant Growth Regulators Market Segmentation
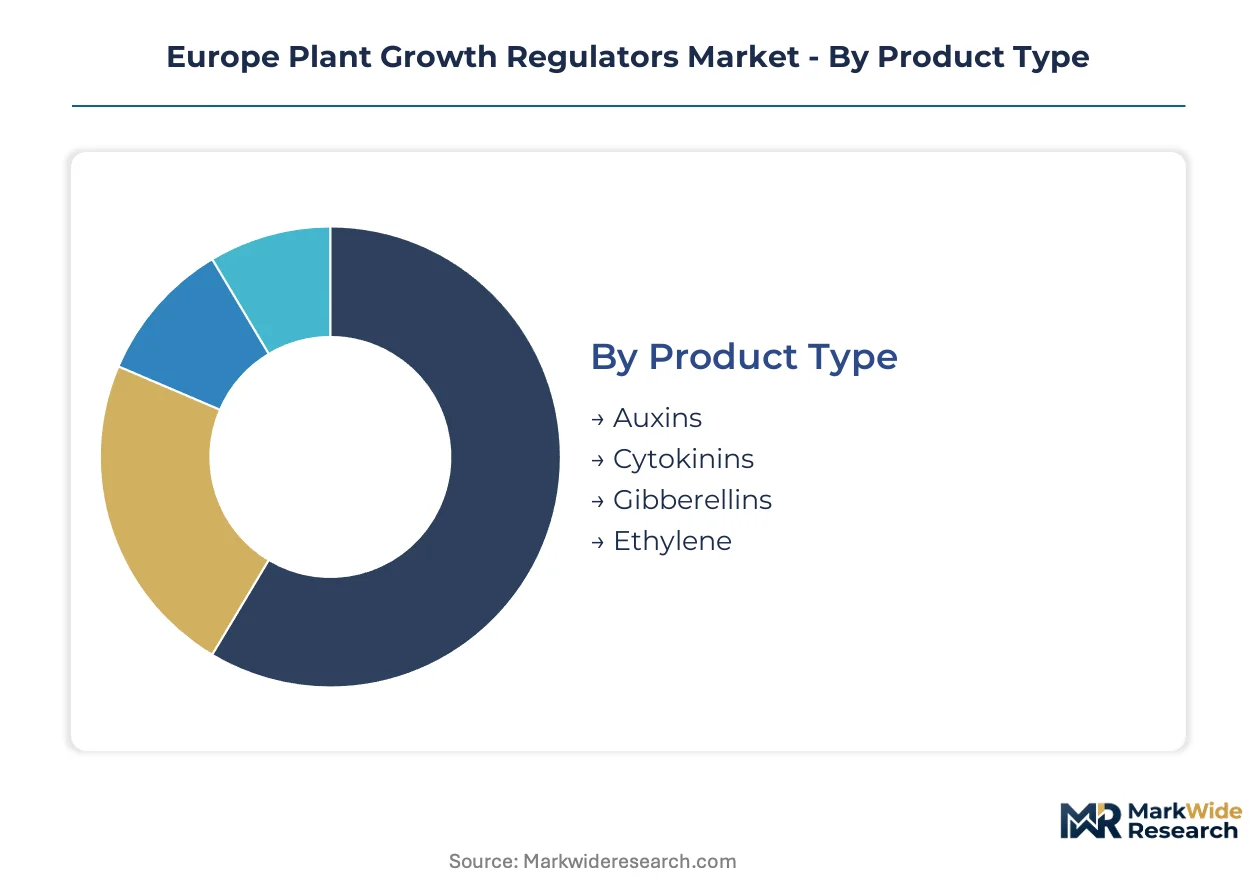
Segmentation in the Europe Plant Growth Regulators Market reveals distinct technology-application pairings where formulation chemistry, crop specificity, and channel economics create divergent margin profiles. Understanding these splits enables targeted portfolio reconfiguration as regulatory pressure intensifies across member states.
Product Type:
Volume concentration sits with mature hormonal classes, while premium pricing accrues to fermentation-derived alternatives with verified carbon credentials.
- Cytokinins:These adenine-derived compounds stimulate cell division and delay senescence in harvested produce. French and Spanish citrus packers dominate procurement for post-harvest shelf-life extension, driven by cold-chain logistics demands for export markets. ECHA's streamlined bio-based registration pathways accelerate fermentation-sourced cytokinin uptake.
- Gibberellins:Diterpenoid acids promote stem elongation and seedless fruit development. Italian and Portuguese table grape producers deploy precision dosing systems to meet supermarket berry-sizing specifications, with water-stress adaptation adding resilience value. This segment is climbing the fastest as seedless varietal expansion accelerates across Mediterranean horticulture.
- Auxins:Indole-based compounds regulate apical dominance and root initiation. German and Dutch ornamental propagators maintain steady demand for tissue culture applications.
- Ethylene:Gaseous and liquid-release formulations control ripening synchronization. Italian tomato processors and French apple storage operators prioritize controlled-release configurations.
Today's leader: Cytokinins. Tomorrow's challenger: Gibberellins.
Application:
Margin structure inverts between commodity field systems and high-value permanent crops where application timing precision commands technology premiums.
- Horticulture:Intensive fruit and vegetable operations in France's Loire Valley and Italy's Po Valley generate concentrated demand for metered growth regulation. Champagne and Bordeaux vineyard operators specify tablet formulations for flowering synchronization, with quality-linked harvest premiums justifying input cost escalation.
- Ornamentals:Dutch floriculture and German nursery stock producers drive cytokinin consumption for tissue culture propagation and cutting establishment. Labor cost pressures in Netherlands' greenhouse clusters accelerate automation-compatible formulation adoption.
- Field Crops:Large-scale cereal and oilseed operations across Germany's eastern plains and Poland's agricultural belt apply auxin-based regulators for lodging resistance. Price-sensitive procurement favors generic liquid formulations distributed through cooperative purchasing structures.
- Turf:Golf course maintenance and sports pitch management in UK and Ireland sustain steady gibberellin uptake for growth suppression and color enhancement. Seasonal application windows concentrate demand in spring and autumn maintenance cycles.
Horticulture commands current margin pools. Ornamentals are expanding most quickly through propagation facility modernization.
Form:
Application precision requirements reshape formulation preferences as drift regulations tighten and labor availability constrains field operations.
- Liquid:Concentrated emulsifiable concentrates and soluble granules retain broad compatibility with existing spray infrastructure. French cereal cooperatives and Spanish citrus associations maintain bulk procurement patterns for high-volume seasonal applications.
- Tablet:Metered-dose configurations enable exact ppm delivery in precision viticulture. German Rhineland contractors adopt drift-reducing tablets for field crop spot treatments, bypassing traditional distributor layers through direct manufacturer relationships.
- Granular:Slow-release matrices suit soil-incorporated applications in orchard establishment. Italian olive and almond replanting programs generate specialized demand.
- Powder:Technical-grade materials supply downstream formulation and research applications. Benelux distribution hubs consolidate blending operations for pan-European supply.
Liquid formulations anchor present volume. Tablets are gaining share fastest through precision agriculture contractor consolidation.
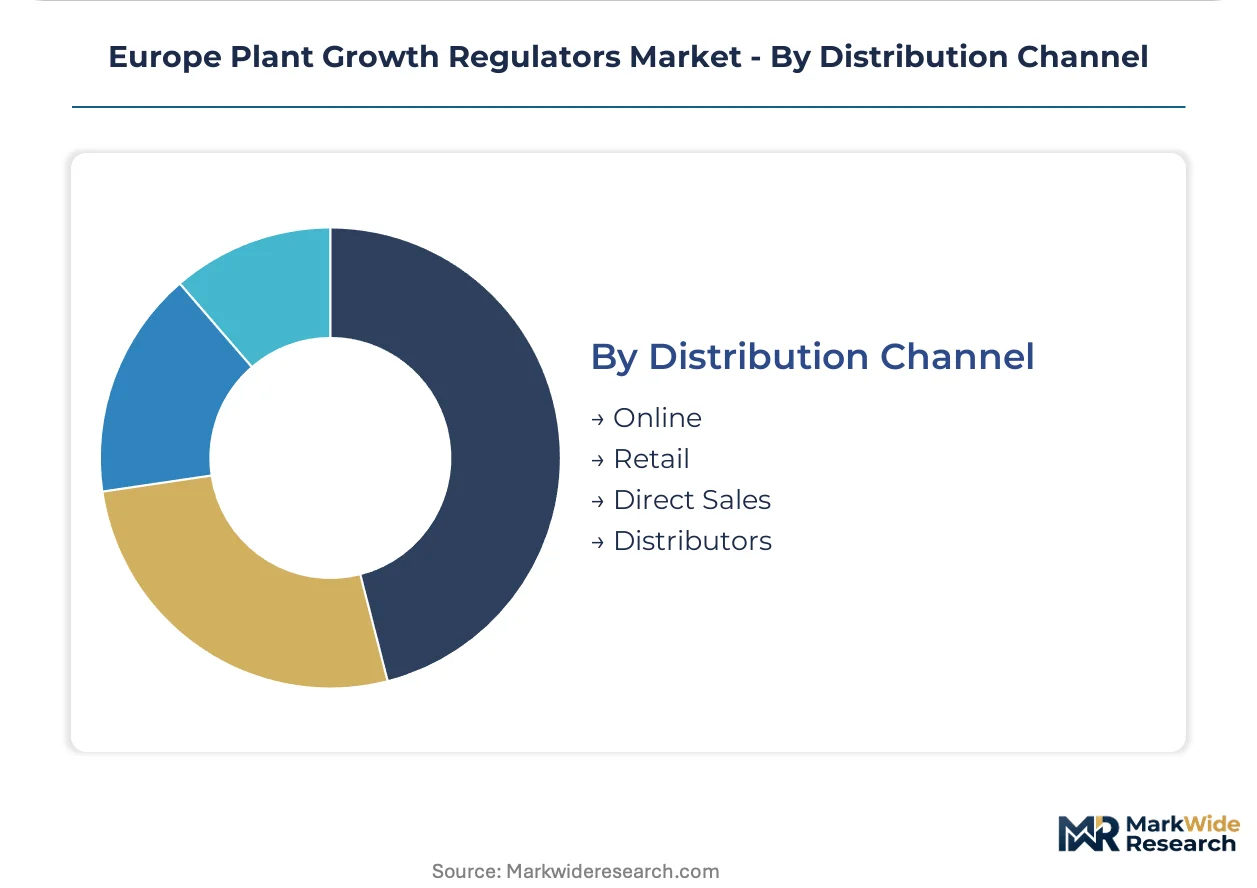
Distribution Channel:
Channel economics fragment as high-value crop producers disintermediate traditional agrochemical distributors while commodity growers reinforce cooperative purchasing leverage.
- Distributors:Regional agrochemical wholesalers maintain inventory depth and technical advisory capacity across fragmented farm structures. Eastern European markets and smaller-scale French producers rely on distributor credit terms and localized application guidance.
- Direct Sales:Manufacturers cultivate relationships with large-scale vineyard operators and greenhouse conglomerates. Champagne houses and Dutch floriculture cooperatives negotiate volume commitments with formulation-specific technical support.
- Retail:Agricultural supply stores and garden centers serve hobbyist and smallholder segments. German and Austrian consumer horticulture channels sustain modest growth regulator SKUs.
- Online:Digital procurement platforms emerge for standardized formulations with clear application protocols. Younger farm operators in Scandinavia and UK pilot e-commerce channels for repeat purchases.
Distributors defend current volume leadership. Direct sales are expanding most quickly through permanent crop consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's intensive viticulture belt concentrates European demand for precision growth regulation, with Champagne and Bordeaux vineyard operators driving metered-dose formulation uptake under tightening environmental protocols.
France
Champagne houses and Loire Valley orchard operators deploy gibberellin tablet systems for flowering synchronization. ANSES hazard classifications diverge from neighboring jurisdictions, complicating cross-border product registrations. The Bordeaux wine cluster anchors premium-tier procurement through direct manufacturer relationships that bypass traditional distribution layers.
Germany
Rhineland precision agriculture contractors adopt drift-reducing granular configurations for field crop spot treatments. BfR coordinates hazard assessments with French counterparts while maintaining distinct national classification protocols. Bavarian nursery stock producers sustain steady cytokinin demand for tissue culture propagation of ornamental varieties.
Italy
Po Valley fruit growers and Sicilian citrus operators expand auxin applications for fruit set uniformity under water-stress conditions. EFSA residue reassessments force rapid substitution of established 2,4-D chemistries. The Emilia-Romagna horticulture cluster integrates fermentation-derived cytokinins into post-harvest shelf-life protocols for export logistics.
Spain
Valencian citrus packers and Andalusian table grape producers drive gibberellin uptake for seedless varietal expansion. The EU Green Deal's Farm to Fork strategy accelerates bio-based formulation approvals through ECHA streamlined pathways. Catalonian tissue culture facilities adopt microbial-derived intermediates for ornamental cloning operations.
Netherlands
Dutch floriculture cooperatives in the Randstad cluster automate cytokinin dosing for greenhouse propagation at scale. Labor cost pressures accelerate compatibility demands for robotic application systems. Wageningen-area research institutions pilot carbon-accounted supply chain certifications that command procurement premiums.
Europe Plant Growth Regulators Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents reconfigure around fermentation-derived precursors and integrated carbon accounting. The vendor base concentrates among integrated agrochemical conglomerates with backward control over biotechnological intermediates, alongside specialized biotech suppliers deploying continuous manufacturing systems. Three archetypes define competitive positioning: integrated chemical-biotech hybrids, precision formulation specialists, and regional distribution-focused operators. Capacity expansion in microbial cytokinin production and M&A targeting carbon-accounted supply chains represent the dominant competitive moves reshaping market structure.
Within the integrated chemical-biotech tier, BASF SE and Bayer Crop Science exemplify archetypes of manufacturing footprint reconfiguration around Ludwigshafen-scale fermentation complexes. Syngenta Group occupies a position among formulation innovators, anchoring competitive differentiation through proprietary delivery system architectures. These three entities collectively represent the scale-driven end of European plant growth regulator supply, with each embedding process emissions data into product certifications to secure preferential access to sustainability-linked procurement pools.
| Leading Market Players |
|---|
| BASF SE |
| Bayer Crop Science |
| Corteva Agriscience |
| Syngenta Group |
| FMC Corporation |
| Nufarm |
| Sumitomo Chemical Co., Ltd. |
| UPL |
| Tata Chemicals Ltd. |
| Others |
Supply & Pricing Matrix
Champagne and Bordeaux vineyard operators specifying metered-dose tablet formulations are compressing distributor margins and forcing manufacturers to reconfigure production footprints around precision-capable fermentation infrastructure, elevating pricing power for carbon-certified bio-based intermediates.
Pricing Analysis
Petroleum-derived naphtha and benzene feedstock volatility passes through to synthetic auxin formulations, widening spreads between conventional and fermentation-sourced alternatives. Three-tier pricing structure across carbon-certified premium, REACH-compliant standard, and generic economy levels separates procurement pools. Cost compression in commodity liquid formulations is intensifying as Spanish citrus cooperatives consolidate purchasing volume. Field crop operators across Germany's eastern plains exhibit highest price sensitivity, while French viticulture houses accept premium positioning for flowering synchronization accuracy.
Supply Chain Analysis
Cytokinin intermediate supply rests on German integrated chemical complexes, Dutch fermentation specialty producers, and Spanish tissue culture propagation facilities. Key inputs comprise adenine-derived precursors, diterpenoid acid feedstocks, and microbial fermentation substrates. Single-source vulnerability concentrates in Ludwigshafen-scale bioreactor infrastructure. Distribution runs through regional agrochemical wholesalers in Eastern Europe, direct manufacturer relationships with Dutch greenhouse conglomerates, and cooperative purchasing structures for German cereal operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's Farm to Fork strategy compounds market value through mandated synthetic pesticide reduction targets, accelerating bio-based formulation substitution across Mediterranean horticulture.
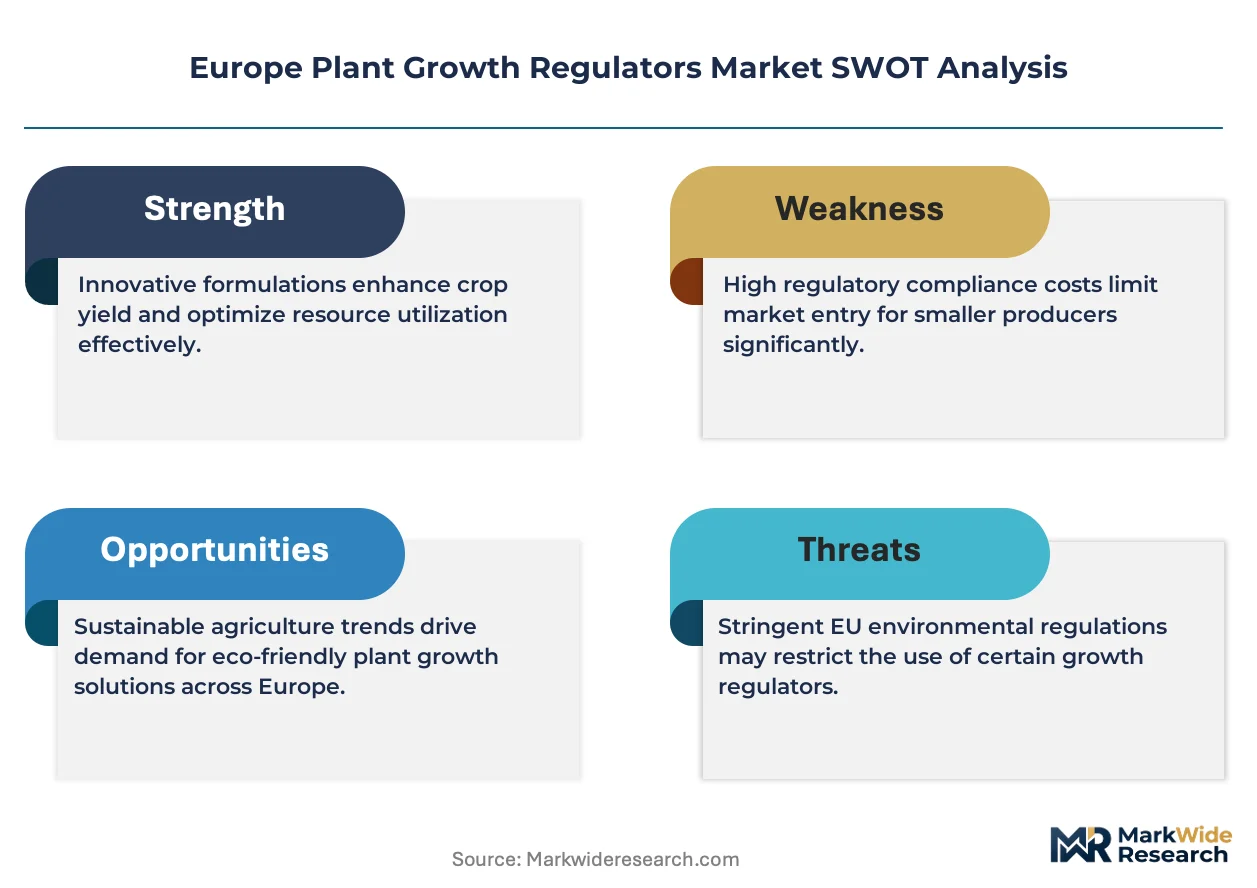
For Market Incumbents: Hedge synthetic chemistry exposure by accelerating backward integration into fermentation-based cytokinin production at Ludwigshafen-scale sites. Secure captive supply of adenine-derived precursors before bioreactor capacity tightens. EFSA residue reassessments threaten conventional 2,4-D authorization timelines, demanding rapid reformulation investment into bio-stimulant-integrated alternatives. For New Entrants and Emerging Players: Launch via direct sales relationships with precision viticulture contractors in Germany's Rhineland, bypassing entrenched distributor layers. Target Portuguese and Greek table grape producers expanding gibberellin uptake for seedless varietal specifications. White-space opportunity concentrates in carbon-accounted supply chain certifications that command procurement premiums from Dutch floriculture cooperatives. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized biotech suppliers deploying continuous fermentation systems for microbial-derived regulator production. Long-term viability over a multi-year horizon hinges on CSRD-aligned carbon disclosure capabilities. Acquisition targets should demonstrate ECHA streamlined registration pathway expertise. Watch EFSA systematic reassessment pace as inflection indicator for synthetic chemistry obsolescence velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Infrastructure | BASF SE's Ludwigshafen complex secures captive cytokinin intermediate supply against feedstock volatility. |
| Carbon Certification Program | Manufacturers embedding CSRD-aligned emissions data gain preferential access to Dutch sustainability-linked procurement pools. |
| Precision Formulation Development | Metered-dose tablet configurations capture margin from Champagne houses seeking flowering synchronization accuracy. |
| Direct Channel Establishment | Manufacturer relationships with Bordeaux wine clusters bypass distributor margin compression. |
| REACH Bio-Based Registration Investment | Streamlined ECHA pathways for microbial-derived substances reduce time-to-market for fermentation alternatives. |
Research Methodology
Bottom-up horticulture demand modeling reconciled against top-down fermentation capacity tracking forms the analytical core. Primary interviews with formulation R&D directors, French vineyard operations managers, Dutch floriculture procurement leads, and ECHA regulatory affairs specialists combined with secondary validation from customs trade data, Cefic sector reports, SEC 10-K filings, and EU Green Deal implementation documents. Triangulation against bioreactor installation records and REACH registration databases anchors supply-side calibration.
Historical trendline analysis of auxin, cytokinin, and gibberellin consumption patterns across the projection horizon informs growth trajectory assumptions. Segmentation modeling spans product type, application intensity, formulation configuration, and distribution channel structure. CAGRs derive from regression analysis against vineyard hectare expansion, greenhouse propagation facility investment cycles, and EFSA reassessment schedule impacts. Forecast inputs incorporate Farm to Fork pesticide reduction compliance timelines and carbon accounting rule adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EFSA residue limit tightening or petroleum feedstock price spikes. Projections reflect assumptions regarding ECHA registration pathway efficiency and bioreactor scale-up capital availability. A small set of named triggers warrants ongoing watch: EU Green Deal implementation velocity, ANSES-BfR hazard classification convergence, and fermentation-derived intermediate cost parity achievement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biotechnology
Duckweed Protein Market
Agricultural Biotechnology
GMO Crops and Seeds Market
Agricultural Biotechnology
Stigmasterol-Rich Plant Sterols Market
Agricultural Biotechnology
Transgenic Seeds Market
Agricultural Biotechnology
Europe Agriculture Biotech Market
Agricultural Biotechnology
Global Animal Biotechnology Market
Agricultural Biotechnology
Plant-Based Vaccines Market
Agricultural Biotechnology
South America Feed Phytogenics Market
Agricultural Biotechnology
Biorationals Market
Agricultural Biotechnology
Brazil Veterinary Vaccines Market
Agricultural Biotechnology
Animal Brucella Antibody ELISA Kits Market
Agricultural Biotechnology
Microarray in Agriculture Market
Agricultural Biotechnology
Asia Pacific Feed Phytogenics Market
Agricultural Biotechnology
Africa Algae Protein Market
Agricultural Biotechnology
Agroscience Market
Agricultural Biotechnology
Agricultural Biotechnology Market