
 Global Plant Hormones Market | 2026-2036
Global Plant Hormones Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plant Hormones Market Foresight
Project finance for biological input manufacturing is rewriting competitive entry barriers in plant hormone production. BASF leverages its integrated fermentation infrastructure to control auxin supply chains across multiple continents. Zhejiang Qianjiang Biochemical anchors Asia-Pacific manufacturing capacity through state-backed agrochemical park allocations. Corteva Agriscience competes by sustaining proprietary formulation patents that extend cytokinin shelf stability.
Plant hormones comprise organic signaling compounds—auxins, gibberellins, cytokinins, and ethylene—that regulate growth, flowering, and stress responses at concentrations measured in parts per million; synthetic analogs replicate these functions for commercial agriculture, horticulture, and turf management. Liquid formulations dominate volume due to ease of foliar application and tank-mix compatibility, while granular products retain margin pools in plantation crops requiring slow-release root zone delivery. The agricultural application segment leads absolute consumption, though ornamental channels exhibit faster growth as greenhouse operators adopt precision dosing systems.
EPA biopesticide registration requirements under FIFRA shape product development timelines for US market entry, while REACH compliance in Europe demands extensive metabolite toxicology dossiers that filter smaller entrants. China's MEE enforces wastewater discharge standards on fermentation-based hormone plants, redirecting capacity toward enzymatic synthesis methods. India's CEA fertilizer control orders intersect with CDSCO pesticide rules, creating dual-track compliance for cytokinin products sold as plant growth regulators. Stakeholders must monitor evolving residue tolerance harmonization between CODEX and national food safety authorities to anticipate formulation reformulation cycles.
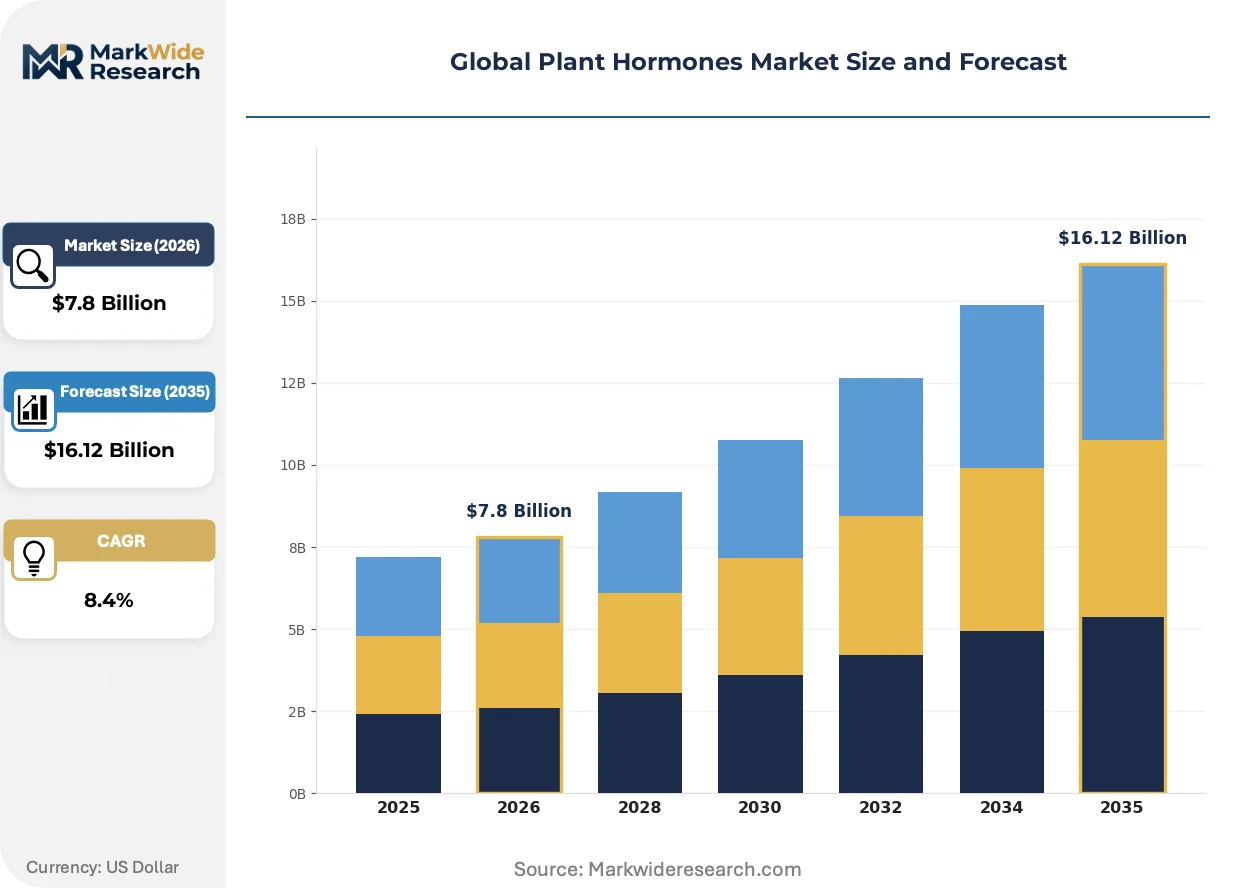
Market Dynamics
Fermentation capacity concentration among state-backed agrochemical parks in China and enzymatic synthesis patents in Germany are bifurcating supply economics, forcing mid-scale synthetic producers toward toll manufacturing arrangements or exit.
Growth Catalysts
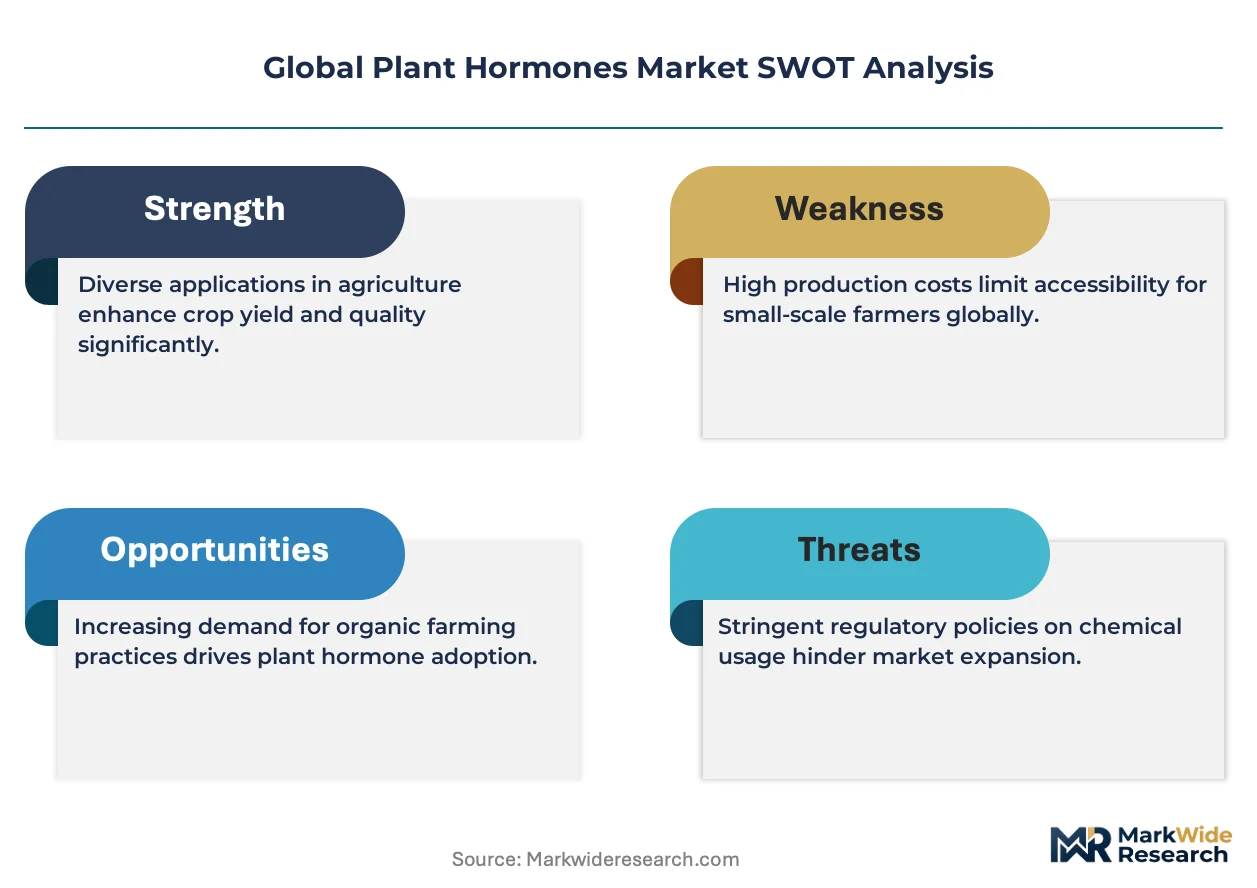
- EU Green Deal Farm to Fork strategy:The residue limit tightening and bio-based registration fast-track provisions are redirecting R&D budgets toward microbial hormone platforms. European specialty crop operators now specify bio-origin certificates in procurement tenders.
- Pineapple flowering synchronization:Brazilian contract growers are expanding gibberellin application protocols across 40,000-hectare blocks, creating demand for precision-dosing equipment bundled with hormone supply.
- Shandong province contract farming consolidation:Bulk cytokinin procurement by vegetable cooperatives is compressing distributor margins and favoring direct manufacturer relationships.
Market Restraints
- Fermentation feedstock volatility:Molasses and corn steep liquor prices fluctuate with Brazilian ethanol policy, squeezing gross margins for auxin producers dependent on bulk fermentation.
- Single-source enzymatic catalyst suppliers:German specialty enzyme houses control 70% of high-efficiency cytokinin synthesis biocatalysts, creating supply concentration risk for Asian manufacturers.
- REACH metabolite dossier requirements:ECHA's extensive toxicology data demands filter smaller entrants from European markets, consolidating share among dossier-rich incumbents.
Strategic Opportunities
- India dual-track compliance arbitrage:CEA fertilizer orders intersecting with CDSCO pesticide rules create regulatory complexity that integrated domestic players can exploit against import-dependent competitors.
- Precision dosing system convergence:Integration of sensor networks with hormone micro-dosing equipment enables greenhouse operators to shift from calendar-based to phenology-triggered application.
- US biopesticide registration under FIFRA:EPA's streamlined 12-18 month pathway for microbial plant hormones offers faster market entry than synthetic analog registration timelines.
Industry Challenges
- Fermentation scale-up biochemistry expertise:The talent pool for industrial-scale auxin bioprocess optimization remains concentrated in three German and Swiss technical universities.
- CODEX residue harmonization tracking:Divergent national MRL adjustments ahead of CODEX alignment force formulation reformulation cycles every 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plant Hormones Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Auxins, Gibberellins, Cytokinins, Ethylene Application: Agricultural, Horticultural, Turf Management, Ornamental Form: Liquid, Granular, Powder, Emulsion Distribution Channel: Online Retail, Specialty Stores, Agronomy Supply, Direct Sales |
| Companies Covered | FMC, Nufarm, Syngenta, Valent, DowDuPont, BASF, Corteva Agriscience, Zhejiang Qianjiang Biochemical, Bayer CropScience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plant Hormones Market Shifts & Advancements
Digital phenotyping platforms and CRISPR-guided hormone pathway engineering are compressing product development cycles while regulatory data requirements expand, creating a capability gap between capitalized and underfunded developers.
CRISPR-edited microbial chassis for gibberellin and cytokinin production is virtualizing strain improvement timelines. BASF and Zhejiang Qianjiang Biochemical are deploying these platforms to compress 36-month development cycles into 14-month iterations. The technology is virtualizing competitive moats around strain IP, as patent thickets around edited metabolic pathways replace traditional chemical synthesis exclusivity.
REACH's 2023 extension of metabolite assessment requirements to plant hormone degradation products is forcing reformulation of slow-release granular products. ECHA's guidance now requires soil metabolite fate studies for all new registrations. European plantation crop operators are accelerating adoption of liquid foliar formulations to avoid pending granular product re-registration delays.
Greenhouse operators in the Netherlands and California are unbundling hormone supply from agronomic advisory services, shifting from bundled input-plus-service contracts to pure product procurement with independent precision agriculture consultants. This channel disintermediation is compressing distributor margins while expanding direct manufacturer sales force requirements. Dutch glasshouse cooperatives now run reverse auctions for annual cytokinin supply, treating hormones as commodity inputs rather than technical differentiators.
Global Plant Hormones Market Segmentation
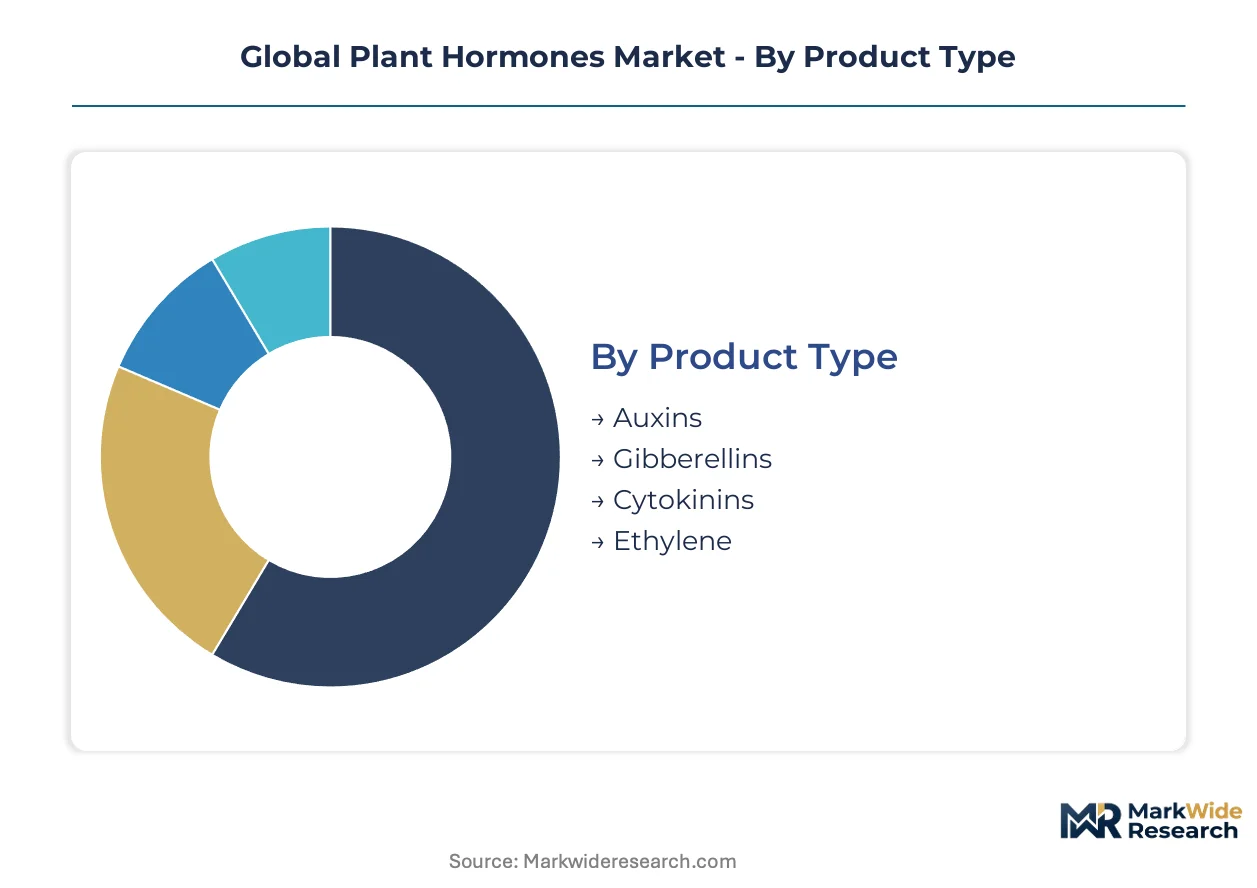
Plant hormone segmentation reveals divergent margin structures across formulation chemistries and application intensities. Each dimension carries distinct regulatory footprints and supply chain configurations that reshape competitive entry economics.
Product Type:
Cost tier stratification across hormone chemistries separates bulk fermentation commodities from precision-synthesis specialties.
- Auxins:Indole-3-acetic acid and synthetic analogs regulate cell elongation and root initiation at micromolar concentrations. Chinese fermentation parks in Shandong and Jiangsu provinces anchor global supply, though molasses feedstock volatility compresses margins during Brazilian ethanol policy shifts.
- Gibberellins:Diterpenoid compounds drive stem elongation and seedless fruit development through GA3 and GA4+7 formulations. Brazilian pineapple contractors in Minas Gerais and Bahia states are expanding 40,000-hectare flowering synchronization programs, creating bundled demand for precision-dosing equipment.
- Cytokinins:Adenine-derived regulators control cell division and shoot proliferation in tissue culture and field applications.
- Ethylene:Gaseous hormone and synthetic releasers manage ripening synchronization and abscission in climacteric fruit supply chains.
Auxins command the established base. The steepest expansion runs through gibberellins.
Application:
Application intensity varies dramatically between broad-acre agriculture and controlled-environment horticulture, reshaping formulation requirements and service bundling.
- Agricultural:Field-scale deployment of auxins and gibberellins in row crops and plantation systems dominates absolute volume consumption. Chinese vegetable cooperatives in Shandong province are consolidating procurement through direct manufacturer relationships, bypassing traditional distributor networks.
- Horticultural:Greenhouse and nursery operations demand precision-dose cytokinins for propagation and flowering control. Dutch glasshouse cooperatives now run reverse auctions for annual supply, treating hormones as commodity inputs rather than technical differentiators.
- Turf Management:Golf course and sports field applications favor slow-release granular formulations for sustained growth regulation.
- Ornamental:Floriculture and landscape nursery channels exhibit the most rapid growth trajectory as greenhouse operators adopt sensor-integrated phenology-triggered dosing systems.
Agricultural applications anchor volume throughput. Ornamental channels are gaining share fastest.
Form:
Physical formulation determines application method compatibility and regulatory metabolite assessment pathways under REACH and FIFRA.
- Liquid:Aqueous and solvent-based concentrates enable foliar spray and fertigation integration with standard farm equipment. European plantation operators are accelerating adoption to avoid pending granular product re-registration delays under ECHA's extended metabolite requirements.
- Granular:Slow-release matrix formulations serve root-zone delivery in plantation crops requiring extended hormone availability. REACH's 2023 extension of soil metabolite fate studies is forcing reformulation cycles for existing registrations.
- Powder:Dry concentrates support tank-mix flexibility and reduced shipping costs for bulk procurement.
- Emulsion:Oil-in-water formulations improve cuticular penetration for lipophilic hormone analogs in arid climates.
Liquid formulations command the established base. Granular products face regulatory compression while emulsion formats climb fastest.
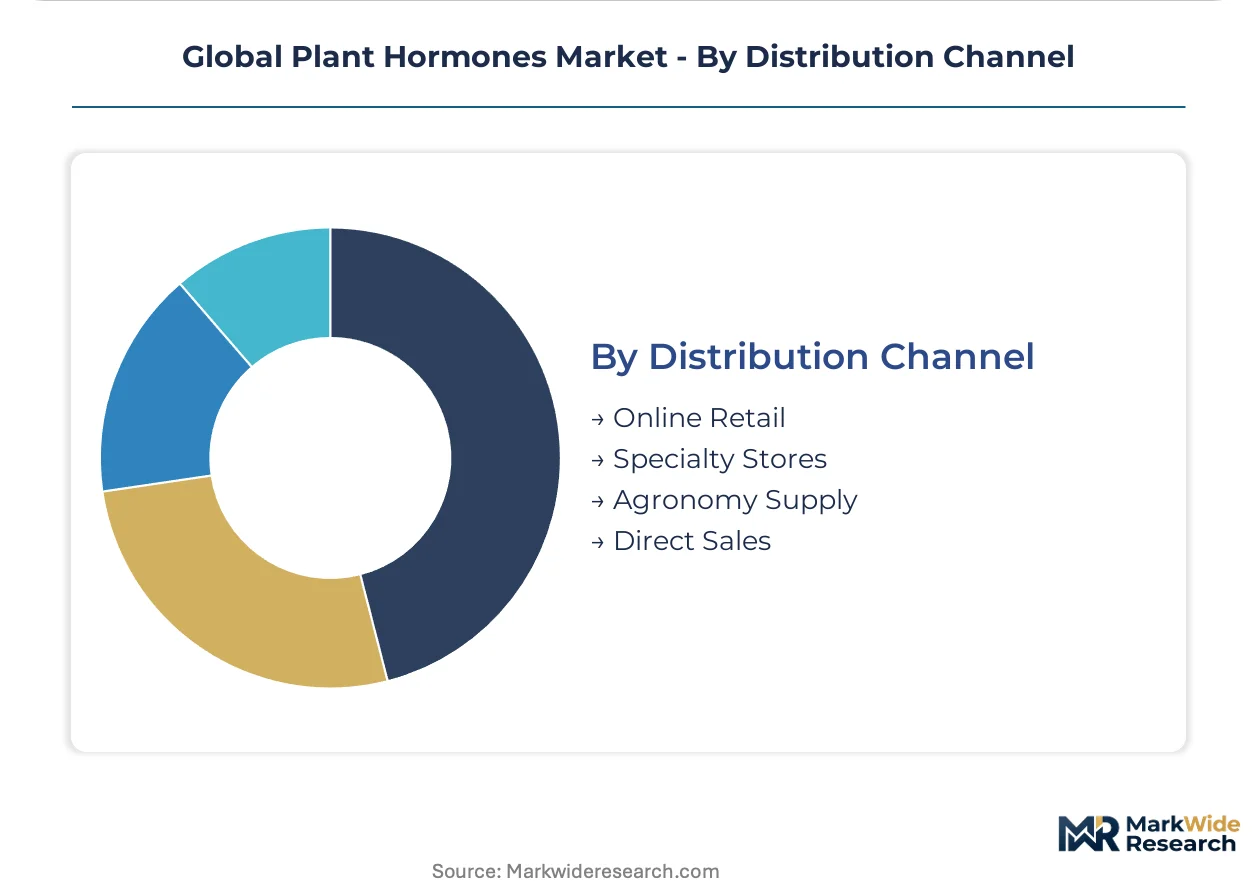
Distribution Channel:
Channel structure is fragmenting as greenhouse operators unbundle agronomic advisory from product supply, compressing traditional distributor margins.
- Online Retail:E-commerce platforms serve small-scale horticulturalists and hobby greenhouse operators with packaged consumer formulations. California and Netherlands precision agriculture consultants now specify products independently through direct procurement.
- Specialty Stores:Garden center and hydroponic supply outlets retain relevance for urban agriculture and home gardening segments.
- Agronomy Supply:Traditional farm input distributors face margin pressure from Shandong cooperative direct purchasing and Dutch cooperative reverse auctions.
- Direct Sales:Manufacturer field forces serve large-scale Brazilian contract growers and Chinese provincial cooperatives with bundled equipment-hormone packages.
Agronomy supply commands the established base. Direct sales channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian contract growers command premium pricing for precision-dosed gibberellin bundles, while Chinese fermentation parks compete on bulk auxin volume. This pricing-power asymmetry fragments procurement strategies across hemispheres.
China
Shandong and Jiangsu provincial agrochemical parks concentrate 60% of global auxin fermentation capacity. MEE wastewater discharge standards are redirecting investment toward enzymatic synthesis methods. Zhejiang Qianjiang Biochemical anchors state-backed manufacturing allocations in Hangzhou Bay chemical clusters.
Brazil
Minas Gerais and Bahia pineapple contractors operate 40,000-hectare flowering synchronization programs. ANVISA residue monitoring aligns with CODEX pre-harvest interval guidelines. Campinas research stations validate precision-dosing protocols for bundled equipment-hormone procurement.
Germany
Specialty enzyme houses control 70% of high-efficiency cytokinin synthesis biocatalysts. REACH metabolite dossier requirements filter smaller entrants from European markets. BASF leverages integrated fermentation infrastructure across Ludwigshafen and Krefeld chemical complexes.
United States
California greenhouse operators unbundle hormone supply from agronomic advisory services. EPA biopesticide registration under FIFRA offers 12-18 month pathways for microbial platforms. Salinas Valley vegetable cooperatives pilot sensor-integrated phenology-triggered dosing systems.
India
Maharashtra and Gujarat cotton belt operators navigate dual-track CEA fertilizer and CDSCO pesticide compliance. Domestic integrated players exploit regulatory complexity against import-dependent competitors. Hyderabad biotech corridors develop CRISPR-edited microbial chassis for localized production.
Global Plant Hormones Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in strain IP and biocatalyst supply. The market structures around three tiers: fermentation-scale commodity producers, precision-synthesis specialty houses, and formulation-technology bundlers. Strategic moves concentrate on backward integration into captive enzyme supply and geographic arbitrage of regulatory compliance costs.
Within the integrated platform tier, BASF and Corteva Agriscience exemplify multinational agrochemical conglomerates leveraging dossier-rich regulatory positions across multiple continents. Zhejiang Qianjiang Biochemical occupies a distinct geography-backed manufacturing archetype, anchoring state-allocated capacity in Chinese agrochemical parks. These three represent divergent competitive vectors: European formulation patenting, North American biopesticide registration expertise, and Asian fermentation scale economics.
| Leading Market Players |
|---|
| FMC |
| Nufarm |
| Syngenta |
| Valent |
| DowDuPont |
| BASF |
| Corteva Agriscience |
| Zhejiang Qianjiang Biochemical |
| Bayer CropScience |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor's freight cost volatility compresses margins for European cytokinin distributors while amplifying price differentiation between bulk fermentation auxins from Shandong and precision-synthesis gibberellins from German enzyme houses. Molasses feedstock swings tied to Brazilian ethanol policy force Asian manufacturers to absorb cost shocks or pass through to plantation crop operators in Minas Gerais.
Pricing Analysis
The customization-premium spread separates standard fermentation-grade auxins from configured-to-order cytokinin formulations with certified metabolite profiles. Three-tier pricing structure across premium, standard, and economy levels stratifies by REACH dossier completeness and enzymatic synthesis efficiency. Cost compression in the standard tier intensifies because Shandong cooperative direct purchasing eliminates distributor markups. Brazilian contract growers show least price sensitivity due to bundled equipment-hormone procurement, while Dutch glasshouse cooperatives running reverse auctions exhibit highest sensitivity.
Supply Chain Analysis
Upstream molasses and corn steep liquor availability from Brazilian ethanol mills anchors auxin fermentation economics in Shandong and Jiangsu provinces. German specialty enzyme houses and Chinese state-backed agrochemical parks constitute dual supply poles, with cytokinin synthesis biocatalysts drawing from Ludwigshafen technical clusters. Single-source vulnerability concentrates in high-efficiency enzymatic catalysts controlled by three German suppliers. Distribution runs through direct manufacturer relationships with Chinese provincial cooperatives and Brazilian contract growers, bypassing traditional agronomy supply networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision agriculture platform economics are displacing input-centric business models as sensor-integrated dosing systems enable phenology-triggered application protocols. Interoperability between greenhouse automation layers and hormone micro-dosing equipment creates ecosystem lock-in opportunities.
For Market Incumbents: Pre-empt CRISPR-edited microbial chassis commoditization by securing captive enzyme supply through backward integration into German biocatalyst specialists or Hangzhou Bay fermentation infrastructure. Defend formulation patent moats against Brazilian equipment bundlers by extending cytokinin shelf stability through proprietary encapsulation. Channel control through direct sales forces serving Shandong cooperatives represents the critical lever against distributor margin compression.
For New Entrants and Emerging Players: Build out India dual-track compliance arbitrage by navigating CEA fertilizer orders intersecting with CDSCO pesticide rules against import-dependent competitors. The most penetrable white-space sits in precision-dosing system convergence for California and Netherlands greenhouse operators seeking independent agronomic advisory. A go-to-market angle through sensor-network integration partnerships bypasses incumbent formulation dominance.
For Investors and Strategic Acquirers: Carve-out targets emerge from agrochemical conglomerates divesting non-core fermentation assets amid enzymatic synthesis transition pressures. Long-term viability across the projection horizon hinges on regulatory dossier depth rather than manufacturing scale alone. The signal to watch is CODEX residue harmonization progress, as divergent national MRL adjustments ahead of alignment force consolidation among dossier-rich players capable of absorbing reformulation cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Supply | Captive biocatalyst access insulates margins from German supplier concentration risk. |
| Precision-Dosing Equipment Bundling | Brazilian pineapple contractors lock in multi-year offtake through integrated protocol validation. |
| CRISPR Strain Development Platform | Virtualized metabolic pathway engineering compresses product iteration timelines versus chemical synthesis. |
| REACH Dossier Expansion | Extended metabolite studies secure granular product re-registration ahead of ECHA compliance deadlines. |
| Direct Channel Penetration | Manufacturer field forces bypass distributor margin compression in Shandong cooperative procurement. |
Research Methodology
A spread of perspectives from fermentation plant managers, precision agriculture consultants, greenhouse procurement officers, and regulatory affairs specialists converged on the working assumptions driving supply concentration and pricing power asymmetries. Primary interviews with Brazilian contract growers and Dutch glasshouse cooperative technical directors combined with secondary validation through ECHA guidance documents, ANVISA residue monitoring protocols, and Chinese MEE wastewater discharge standards. Bottom-up capacity assessments across Shandong and Jiangsu agrochemical parks triangulated against top-down demand modeling from plantation crop operators.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning hormone chemistry, formulation type, application intensity, and regional regulatory cluster. CAGRs derived from capacity expansion pipelines, contract farming consolidation trajectories, and bio-based registration fast-track utilization rates. Industry-specific forecast inputs incorporated Brazilian ethanol policy feedstock sensitivity and EU Green Deal procurement tender specifications.
Stress conditions across molasses price volatility, REACH metabolite dossier approval delays, and enzymatic catalyst supply disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fermentation scale-up biochemistry expertise concentration and CODEX alignment timelines. Cross-checking against FAO trade statistics and national agrochemical registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biotechnology
Microarray in Agriculture Market
Agricultural Biotechnology
Europe Plant Growth Regulators Market
Agricultural Biotechnology
Duckweed Protein Market
Agricultural Biotechnology
Stigmasterol-Rich Plant Sterols Market
Agricultural Biotechnology
Global Poultry Vaccines Market
Agricultural Biotechnology
Europe Agriculture Biotech Market
Agricultural Biotechnology
Asia-Pacific Agriculture Biotech Market
Agricultural Biotechnology
Global Animal Biotechnology Market
Agricultural Biotechnology
Agroscience Market
Agricultural Biotechnology
Biorationals Market
Agricultural Biotechnology
Africa Algae Protein Market
Agricultural Biotechnology
GMO Crops and Seeds Market
Agricultural Biotechnology
Plant-Based Vaccines Market
Agricultural Biotechnology
Ruminant Vaccines Market
Agricultural Biotechnology
Agricultural Biotechnology Market
Agricultural Biotechnology
Animal Brucella Antibody ELISA Kits Market