
 Biorationals Market | 2026-2036
Biorationals Market Size, Share, and Industry Trends Forecast 2026-2036
Biorationals Market Intelligence
The distributor-to-grower channel is narrowing as large agricultural cooperatives consolidate procurement and demand direct technical support. Bayer AG leverages its seeds-and-traits infrastructure to bundle biorational offerings with conventional crop protection. Koppert Biological Systems sustains its position through specialized technical service teams embedded in regional markets. Valent BioSciences LLC dominates the pheromone and insect growth regulator segments with dedicated fermentation capacity.
Biorationals comprise biologically derived substances including plant extracts, microbial organisms, and naturally occurring biochemicals that disrupt pest physiology or behavior through non-toxic modes of action, typically requiring EPA FIFRA registration under reduced-risk or biochemical criteria. These inputs serve commercial agriculture's need for resistance management, residue compliance, and pollinator safety in integrated pest management programs. Microbial products now capture the largest revenue share among product types, while botanical insecticides represent the fastest-expanding category as extraction technologies improve yield and standardization. Agricultural crops absorb the majority of application volumes, though post-harvest treatment shows the steepest growth trajectory driven by export phytosanitary requirements.
The EPA's reduced-risk designation and the EU's Farm to Fork Strategy under the European Green Deal are reshaping registration pathways and maximum residue limits for biological inputs across both markets. India's Central Insecticides Board and Brazil's national health surveillance agency, ANVISA, are tightening equivalency standards for imported biological active ingredients, raising compliance costs for multinational suppliers. Stakeholders must monitor how divergent national data requirements for microbial strain characterization and metabolite profiling affect product development timelines and geographic launch sequencing.
Market Dynamics
Consolidation among agricultural cooperatives is compressing the distributor-to-grower channel, forcing biorational suppliers to embed technical service teams directly at the farm level and restructure incentive programs around resistance management outcomes rather than volume rebates.
Growth Catalysts
- EPA reduced-risk designation:The EPA's streamlined registration pathway for biological active ingredients accelerates time-to-market for novel microbial strains and botanical extracts, compressing development cycles by eliminating redundant toxicology studies required for conventional chemistries.
- Brazilian resistance mandates:ANVISA protocols in Brazil's soybean belt now require rotation with non-synthetic modes of action, creating compulsory demand pull for microbial insecticides and pheromone disruptors in the world's largest export soybean region.
- California IPM expansion:Specialty crop growers in California's Central Valley are embedding biorationals into integrated pest management programs to meet export residue limits for berries, tree nuts, and vegetables destined for EU and Japanese markets.
Market Restraints
- Strain characterization costs:India's Central Insecticides Board and ANVISA in Brazil are tightening equivalency standards for imported microbial active ingredients, forcing suppliers to conduct redundant metabolite profiling studies that inflate registration costs by 40-60% for multi-country launches.
- Fermentation capacity concentration:Dedicated fermentation infrastructure for pheromone and insect growth regulator production concentrates in Western Europe and North America, creating supply bottlenecks and extended lead times for Asian and Latin American formulators.
- Shelf stability limitations:Live microbial formulations face temperature sensitivity constraints that restrict distribution radius and exclude them from markets with inadequate cold chain infrastructure in Sub-Saharan Africa and Central Asia.
Strategic Opportunities
- Post-harvest phytosanitary gap:Export certification requirements for fruit and vegetable shipments are expanding biorational fumigation and coating applications, with citrus and mango exporters in Mexico and Southeast Asia driving fastest-category expansion.
- Seed treatment integration:Biological seed coatings containing entomopathogenic fungi and nematodes are converging with precision planting equipment, enabling early-season pest suppression that reduces later foliar spray requirements.
- EU Farm to Fork tailwinds:The European Green Deal's 50% pesticide reduction target is redirecting national extension service budgets toward biorational demonstration plots and grower training programs across France, Germany, and the Netherlands.
Industry Challenges
- Field efficacy variability:Microbial product performance fluctuates with humidity, UV exposure, and soil microbiome composition, requiring agronomists to recalibrate application timing and tank-mix protocols for each microclimate and crop stage.
- Technical service bandwidth:Grower cooperatives consolidating procurement now demand dedicated on-farm support for biorational integration, stretching supplier personnel across larger territories and compressing response times during critical pest pressure windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biorationals Market |
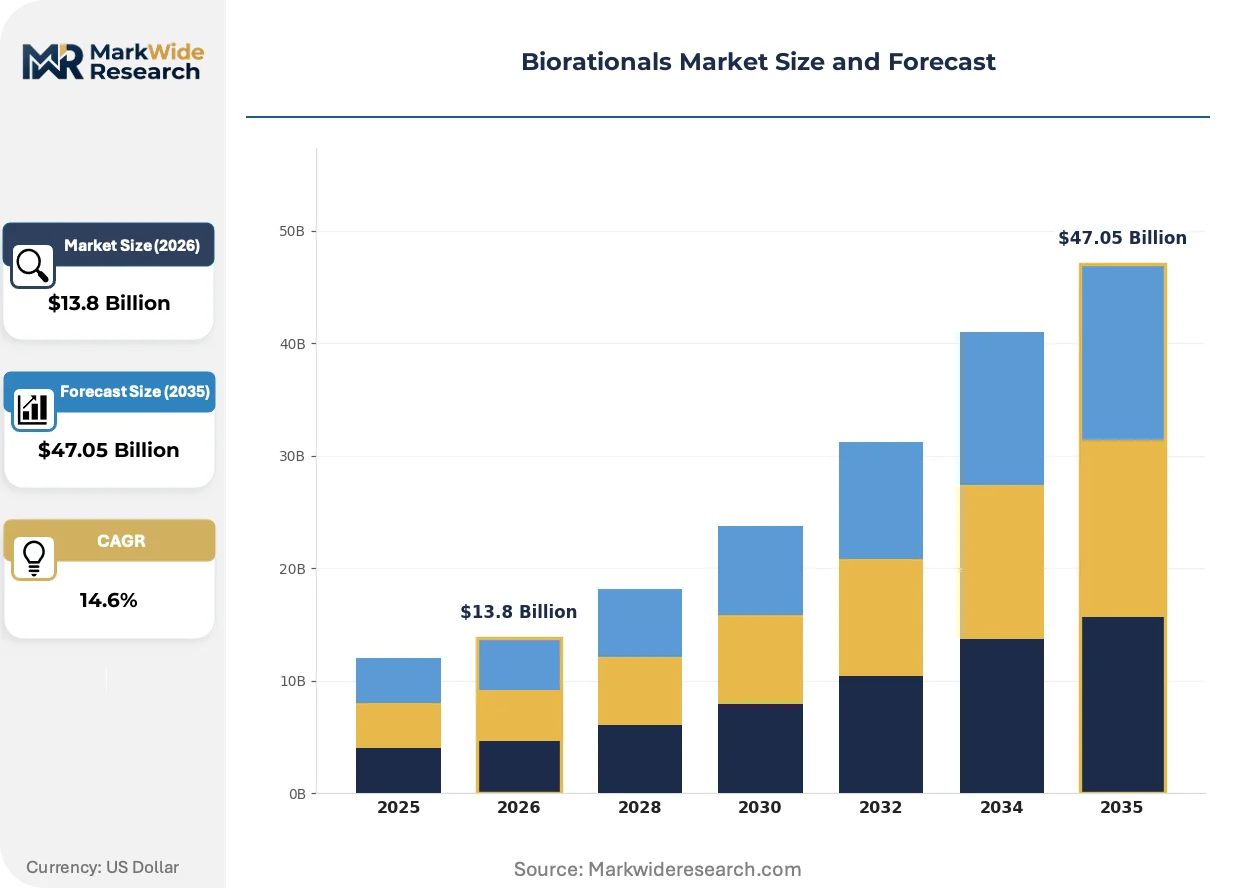
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $47.05 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Botanical Insecticides, Microbial Products, Biochemical Pesticides, Plant Growth Regulators Application: Agricultural Crops, Horticultural Crops, Turf and Ornamental, Post-Harvest Treatment End User: Farmers, Organic Producers, Agricultural Cooperatives, Landscape Professionals Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Koppert Biological Systems, Marrone Bio Innovations, Bayer AG, Gowan Company, Isagro, BASF SE, Valent BioSciences LLC, Summit Chemical, Inc., Syngenta Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biorationals Market Strategic Shifts & Innovations
Digital agronomy platforms are virtualizing field-level decision support, compressing the gap between biological product development and precise application timing while reshaping how technical knowledge transfers from supplier to grower.
RNA interference technology is virtualizing conventional insecticide modes of action by enabling species-specific silencing of essential pest genes without off-target effects. Row crop operators in the US Corn Belt and Brazilian Cerrado are piloting foliar sprays and seed treatments containing double-stranded RNA molecules against rootworm and stink bug populations. This precision mechanism is virtualizing the competitive boundary between biological and synthetic chemistry by delivering comparable mortality rates with zero residue concerns.
The EU's Farm to Fork Strategy under the European Green Deal is mandating 50% synthetic pesticide reduction by 2030, forcing national regulators to rewrite maximum residue limits and accelerate biological product review timelines. German and French authorities are expanding parallel-track evaluation procedures that allow provisional authorization while confirmatory field data accumulates. Horticultural exporters in Spain and Italy are responding by retrofitting packing facilities with biological post-harvest treatment systems to maintain EU market access.
Large agricultural cooperatives are consolidating procurement decisions and demanding direct technical partnerships that bypass traditional distribution tiers. Midwestern US grain cooperatives and Brazilian soybean consortiums now negotiate enterprise-level biorational supply agreements with embedded agronomist support. This channel compression is most visible in Iowa and Mato Grosso, where cooperative technical staff now outnumber independent crop consultant recommendations in grower decision-making.
Biorationals Market Segmentation
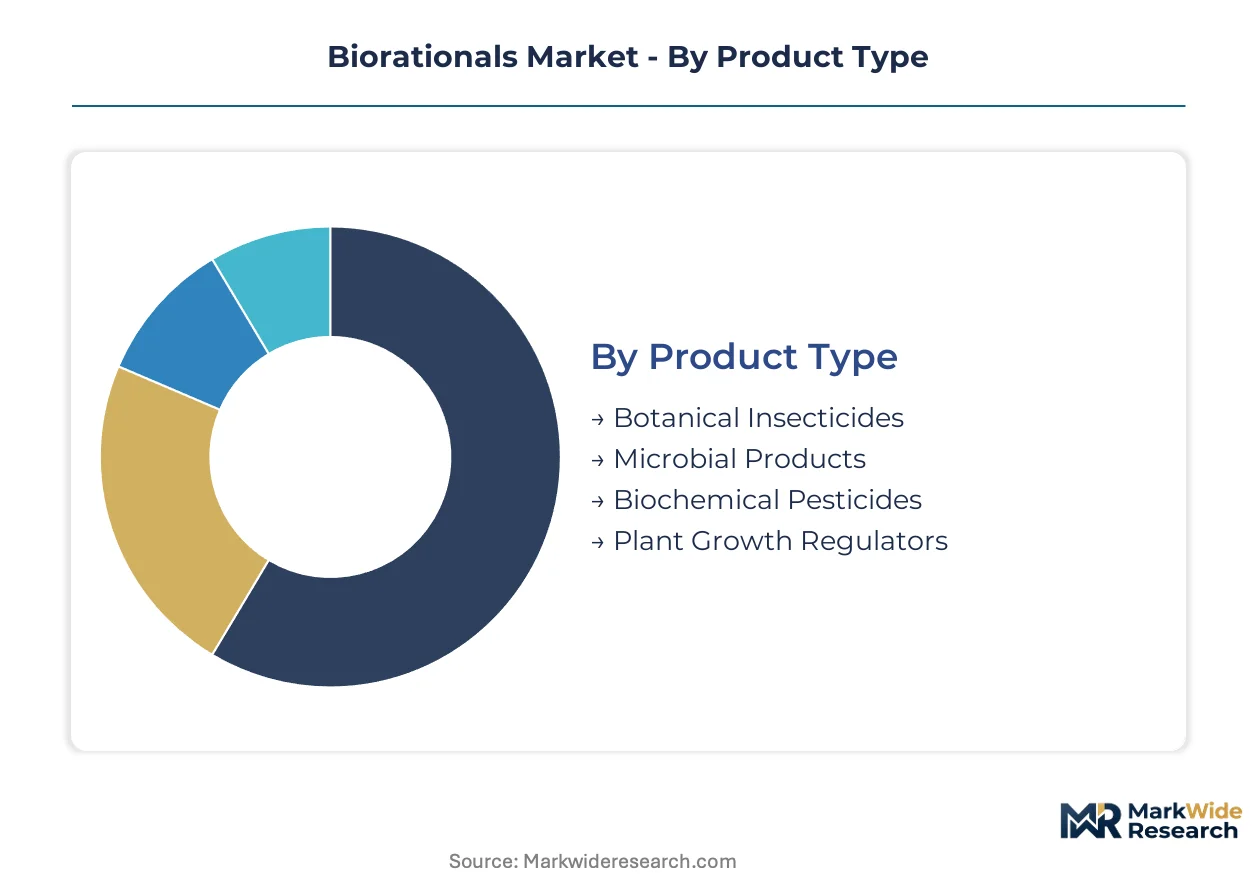
Biorationals serve distinct use-case spectrums ranging from intensive row-crop operations to precision horticulture and export phytosanitary compliance. Segmentation reveals how formulation chemistry, application timing, and procurement channel each dictate supplier strategy and margin structure across commercial agriculture.
Product Type:
Formulation chemistry spans living organisms, extracted botanicals, and synthetic mimics of natural compounds, each demanding different manufacturing infrastructure and regulatory pathways.
- Botanical Insecticides:Purified plant extracts including pyrethrins, azadirachtin, and essential oils disrupt pest neural function or feeding behavior through multiple non-toxic modes of action. California Central Valley berry growers and Southeast Asian mango exporters are driving formulation demand as residue compliance tightens for EU and Japanese market access.
- Microbial Products:Living formulations of bacteria, fungi, and viruses infect target pests through species-specific pathogenesis, requiring fermentation capacity and cold chain integrity. Brazil's soybean belt now mandates microbial rotation under ANVISA resistance protocols, concentrating procurement through agricultural cooperatives in Mato Grosso and Rio Grande do Sul.
- Biochemical Pesticides:Naturally occurring substances including pheromones, insect growth regulators, and plant defense elicitors modify pest behavior or physiology without direct toxicity. EPA reduced-risk designation accelerates registration for semiochemical disruptors targeting codling moth and pink bollworm.
- Plant Growth Regulators:Biologically derived compounds manipulating hormone pathways to control fruit set, ripening uniformity, or vegetative growth. Specialty citrus and table grape producers in Spain and Italy deploy these for export sizing standards.
The dominant share belongs to Microbial Products, while Botanical Insecticides is closing the gap fastest.
Application:
Application timing determines formulation requirements, from in-season foliar protection through post-harvest phytosanitary certification.
- Agricultural Crops:Row-crop deployment of microbial insecticides and botanical extracts for resistance management in corn, soybean, and cotton systems. Iowa and Illinois grain cooperatives negotiate enterprise supply agreements with embedded technical service.
- Horticultural Crops:Precision applications in protected cultivation and open-field vegetables where residue limits and pollinator safety constrain synthetic chemistry. Dutch greenhouse operators and Almeria plasticulture clusters drive pheromone mating disruption adoption.
- Turf and Ornamental:Golf course superintendents and municipal park managers deploy entomopathogenic nematodes and botanical fungicides for aesthetic pest suppression with minimal environmental persistence.
- Post-Harvest Treatment:Biological fumigation and coating applications for export phytosanitary compliance in citrus, mango, and avocado shipments. Mexican packing facilities and Thai cold storage operators are retrofitting biological treatment lines.
Agricultural Crops commands the volume base, though Post-Harvest Treatment shows the steepest expansion trajectory.
End User:
Customer sophistication varies from individual growers requiring technical guidance to consolidated cooperatives demanding direct supplier partnerships.
- Farmers:Individual commercial operators integrating biorationals into IPM rotations based on independent crop consultant recommendations or extension demonstration plots.
- Organic Producers:Certified operations for whom biorationals represent permitted inputs under USDA National Organic Program and EU organic regulations, with zero synthetic tolerance.
- Agricultural Cooperatives:Consolidated procurement entities in Brazil and the US Midwest now bypass distributors for direct technical partnerships with microbial suppliers.
- Landscape Professionals:Municipal and commercial grounds managers seeking pollinator-safe alternatives to neonicotinoid and pyrethroid perimeter treatments.
Agricultural Cooperatives are capturing procurement share fastest, though Farmers remain the numerically dominant category.
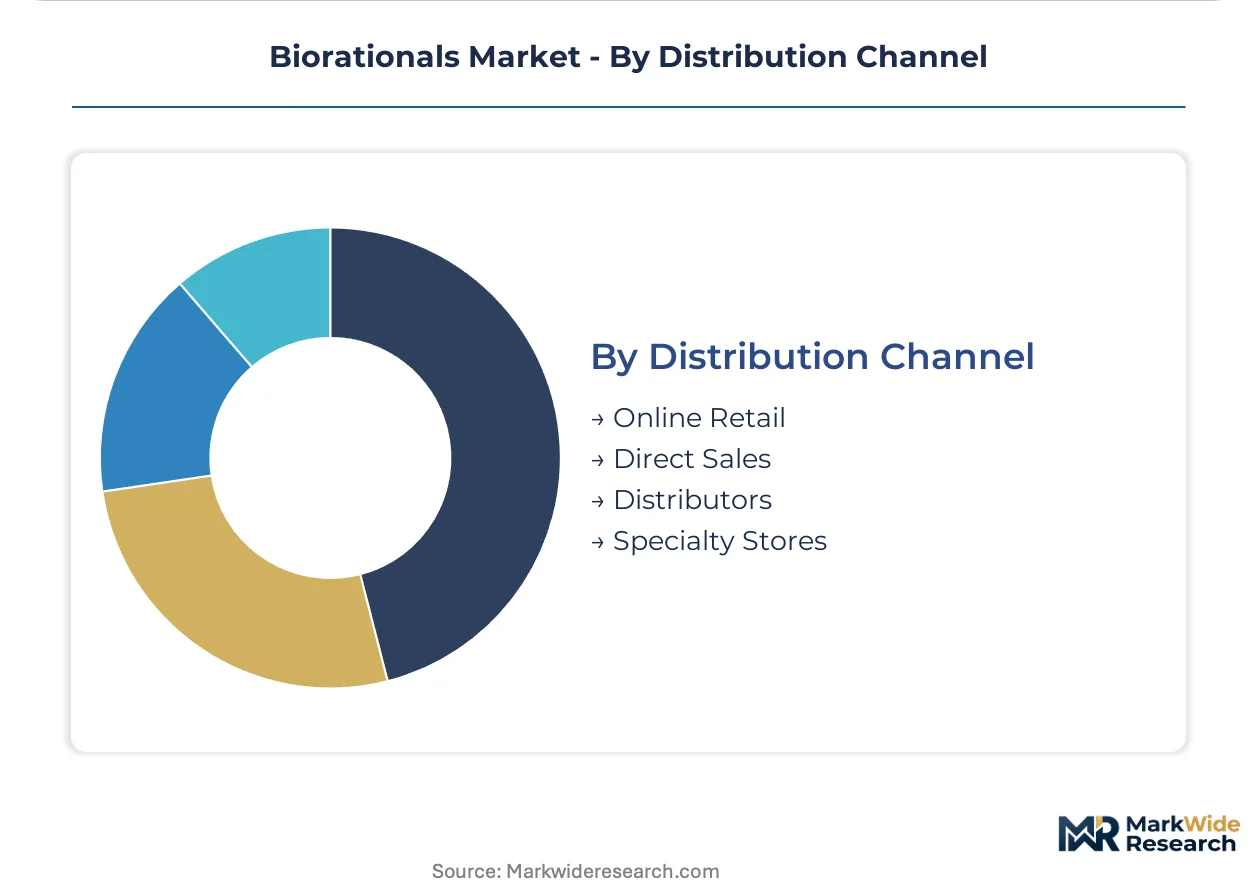
Distribution Channel:
Channel structure is compressing as technical knowledge requirements and consolidation reshape how biological products reach end users.
- Online Retail:E-commerce platforms serving small-scale organic producers and hobby farmers with standardized botanical formulations and microbial inoculants.
- Direct Sales:Supplier technical teams embedded with large cooperatives and integrated growers, replacing traditional distributor relationships in Iowa and Mato Grosso.
- Distributors:Regional agricultural supply houses maintaining inventory and credit relationships with independent growers, though their share is narrowing.
- Specialty Stores:Localized retailers serving horticultural and turf segments with application equipment and tailored advice.
Direct Sales is gaining share fastest against a shrinking Distributor base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Western European fermentation hubs while Brazilian soybean cooperatives extract volume discounts through consolidated procurement. California specialty crop premiums offset higher compliance costs for residue-sensitive exports. Regulatory divergence between EPA reduced-risk pathways and EU Farm to Fork mandates fragments product launch sequencing across Atlantic markets.
United States
California Central Valley berry and tree nut growers drive biorational adoption to meet Japanese and EU maximum residue limits. EPA's reduced-risk designation compresses registration timelines for microbial insecticides and pheromone disruptors. Iowa and Illinois grain cooperatives negotiate enterprise supply agreements with embedded technical service teams replacing traditional distributors.
Brazil
ANVISA resistance management protocols mandate rotation with non-synthetic modes of action across Mato Grosso and Rio Grande do Sul soybean belts. Agricultural cooperatives consolidate procurement decisions and demand direct supplier partnerships bypassing regional distributors. Fermentation capacity constraints extend lead times for imported microbial formulations during critical planting windows.
Germany
EU Farm to Fork Strategy redirects national extension budgets toward biorational demonstration plots and grower training programs. ECHA and EFSA accelerate parallel-track evaluation procedures allowing provisional biological product authorization. Bavarian and Lower Saxony horticultural clusters retrofit greenhouse systems with pheromone mating disruption for residue compliance.
India
Central Insecticides Board tightening equivalency standards for imported microbial active ingredients inflates registration costs for multinational suppliers. Punjab and Haryana wheat-rice systems pilot entomopathogenic fungi integration against resistant stem borer populations. Domestic fermentation capacity expansion targets import substitution for botanical extract formulations.
Netherlands
Almeria plasticulture and Dutch greenhouse clusters lead pheromone mating disruption adoption for pollinator-safe intensive horticulture. National regulators align with EU Green Deal pesticide reduction targets through accelerated biological product review timelines. Wageningen research corridor anchors public-private partnerships for RNA interference technology development in row crop applications.
Biorationals Market Key Industry Players
Integrated agrochemical conglomerates and specialized biological suppliers split the market along technical service intensity and manufacturing scale vectors. Consolidation among agricultural cooperatives compresses distribution tiers, forcing suppliers to embed field-level support teams directly with grower decision-makers. Three archetypes dominate: multinational seeds-and-traits platforms bundling biological offerings, dedicated fermentation specialists with captive strain libraries, and regional technical service providers. Competitive moves center on backward integration into fermentation capacity and strategic partnerships with precision agriculture equipment manufacturers.
Within the specialized biological tier, Koppert Biological Systems and Valent BioSciences LLC exemplify technical service-intensive positioning through embedded regional agronomist networks. Bayer AG represents the integrated platform archetype, leveraging seeds-and-traits infrastructure to bundle biorational offerings with conventional crop protection portfolios. Marrone Bio Innovations occupies a position between pure-play specialization and platform scale, reflecting the mid-market consolidation pressure from above and below.
| Leading Market Players |
|---|
| Koppert Biological Systems |
| Marrone Bio Innovations |
| Bayer AG |
| Gowan Company |
| Isagro |
| BASF SE |
| Valent BioSciences LLC |
| Summit Chemical, Inc. |
| Syngenta Group |
| Others |
Cost & Logistics Intelligence
Rotterdam-Antwerp corridor freight costs for temperature-sensitive microbial formulations compress margin structures for Asian formulators while amplifying price premiums for Western European fermentation hubs serving Brazilian soybean cooperatives and California specialty crop exporters.
Pricing Analysis
The customization-premium spread between configured-to-order strain formulations and standard microbial products spans three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on cold chain certification grade and embedded technical service intensity, with cooperatives in Mato Grosso extracting volume discounts that compress margins for imported formulations. Pricing pressure stems from redundant metabolite profiling requirements for ANVISA and India's Central Insecticides Board equivalency standards. Individual farmers in Sub-Saharan Africa exhibit highest price sensitivity due to limited credit access, while Dutch greenhouse operators accept premium positioning for pollinator-safe pheromone systems.
Supply Chain Analysis
Export-control regimes for dual-use fermentation technology restrict strain transfer protocols between Western European production hubs and emerging Asian manufacturing sites. Supply concentrates in the Netherlands, Germany, and the United States for dedicated pheromone and insect growth regulator capacity, while India and China expand domestic fermentation infrastructure for botanical extract processing. Raw material dependencies include molasses feedstocks, specialized bioreactor vessels, and cryogenic preservation media. Single-source vulnerability concentrates in cold chain logistics providers serving live microbial formulations. Distribution runs through direct technical partnerships with agricultural cooperatives, displacing traditional regional distributors in Iowa and Rio Grande do Sul.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation strain libraries and embedded agronomist networks constitute the scarce capabilities that separate viable competitors from commodity formulators in this market.
For Market Incumbents: Harden technical service bandwidth through captive agronomist teams embedded directly with Mato Grosso and Iowa grain cooperatives, replacing distributor-dependent support models. Defend margin position by securing backward integration into cold chain logistics providers serving live microbial formulations, insulating against third-party capacity constraints during critical planting windows. For New Entrants and Emerging Players: Pursue post-harvest phytosanitary applications in Mexican citrus and Thai mango packing facilities, where export certification requirements outpace incumbent biological treatment capacity. Target seed treatment integration partnerships with precision planting equipment manufacturers in the US Corn Belt, leveraging early-season pest suppression protocols that reduce foliar spray requirements for grower customers. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated agrochemical conglomerates seeking to divest non-core biological assets amid portfolio rationalization pressures. Long-term viability rests on fermentation capacity scale and strain IP depth rather than formulation chemistry alone. Watch for ANVISA resistance protocol expansions beyond soybeans into cotton and corn as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captive production of pheromones and insect growth regulators reduces lead times for Brazilian cooperatives. |
| Direct Technical Partnership | Embedded agronomist teams with Iowa and Mato Grosso cooperatives displace traditional distribution tiers. |
| Cold Chain Infrastructure Investment | Temperature-controlled logistics networks unlock live microbial distribution in Sub-Saharan African markets. |
| RNA Interference Pipeline Development | Wageningen research partnerships accelerate species-specific pest gene silencing for row crop applications. |
| Post-Harvest Treatment Line Retrofit | Mexican and Southeast Asian packing facilities adopt biological fumigation for EU phytosanitary compliance. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fermentation plant managers, agricultural cooperative procurement leads, EPA regulatory affairs specialists, and botanical extraction R&D directors. Secondary validation drew from EPA reduced-risk registration databases, ANVISA resistance protocol filings, EU Farm to Fork Strategy implementation documents, and customs trade data for microbial active ingredient flows. Bottom-up volume estimates from individual crop applications were triangulated against top-down market sizing from supplier revenue disclosures.
Calibration against historical registration timelines and adoption curves anchored projections across the analysis window. Segmentation dimensions modeled include product type chemistry, application timing, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating EPA review acceleration effects, EU pesticide reduction mandates, and cooperative procurement consolidation trajectories. Strain characterization cost inflation and cold chain infrastructure penetration served as industry-specific forecast inputs.
Sensitivities concentrate around ANVISA equivalency standard tightening, EU maximum residue limit revisions, and cooperative procurement consolidation pace. Forecasts reflect documented assumptions regarding regulatory review timelines and grower training program funding levels. Material shifts in RNA interference regulatory classification or major cold chain infrastructure investments in Sub-Saharan Africa would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biotechnology
Global Animal Biotechnology Market
Agricultural Biotechnology
Animal Brucella Antibody ELISA Kits Market
Agricultural Biotechnology
Europe Plant Growth Regulators Market
Agricultural Biotechnology
Transgenic Seeds Market
Agricultural Biotechnology
Duckweed Protein Market
Agricultural Biotechnology
Africa Algae Protein Market
Agricultural Biotechnology
Global Plant Hormones Market
Agricultural Biotechnology
Agroscience Market
Agricultural Biotechnology
Europe Agriculture Biotech Market
Agricultural Biotechnology
GMO Crops and Seeds Market
Agricultural Biotechnology
Global Poultry Vaccines Market
Agricultural Biotechnology
Plant-Based Vaccines Market
Agricultural Biotechnology
Ruminant Vaccines Market
Agricultural Biotechnology
Asia Pacific Feed Phytogenics Market
Agricultural Biotechnology
Asia-Pacific Agriculture Biotech Market
Agricultural Biotechnology
South America Feed Phytogenics Market