
 Ruminant Vaccines Market | 2026-2036
Ruminant Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Ruminant Vaccines Market Analytics
EU MDR for veterinary medicinal products is restructuring the cost-of-entry calculus for new ruminant vaccine entrants, forcing smaller manufacturers to absorb substantial compliance costs before market authorization. Zoetis leverages its vertically integrated manufacturing network to sustain competitive positioning across multiple delivery modes. Boehringer Ingelheim anchors its European operations with specialized R&D facilities focused on foot-and-mouth disease formulations. Merck & Co., Inc. differentiates through its dominance in bovine respiratory disease combination vaccines across North American cattle operations.
Ruminant vaccines comprise immunological preparations administered to cattle, sheep, goats, and other multi-stomached livestock to induce active immunity against bacterial and viral pathogens, typically formulated as live attenuated, inactivated, or subunit preparations stabilized in aqueous or oil-adjuvant suspensions for intramuscular, subcutaneous, or oral delivery. Their primary commercial purpose centers on reducing morbidity and mortality in food-producing herds while satisfying food-chain safety requirements for residue-free animal products. The live attenuated delivery mode segment occupies the largest current volume share due to its established efficacy in foot-and-mouth disease control programs, though mRNA platforms represent the fastest-growing technology category as developers pursue rapid strain-adaptable formulations. Intramuscular administration leads in product type penetration among commercial dairy operations, while oral delivery gains traction in extensive grazing systems where animal handling infrastructure remains limited.
EMA's centralized marketing authorization procedure governs veterinary vaccine approval across European member states, while USDA-APHIS regulates interstate movement and importation of biological products in the United States, and India's CDSCO oversees manufacturing licensing through its state-level committees. These frameworks collectively elevate product quality thresholds, extend development timelines, and concentrate market access among manufacturers with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving mRNA platform guidance from major regulators, as classification uncertainties around novel delivery technologies could reshape competitive positioning and investment priorities for pipeline assets.
Market Dynamics
The EU MDR for veterinary medicinal products is restructuring approval pathways for ruminant vaccine developers, forcing manufacturers to absorb substantial compliance costs before market authorization while favoring entities with dedicated regulatory affairs capabilities.
Growth Catalysts
- Brazilian dairy expansion:Large-scale cooperative herds in Minas Gerais and São Paulo states are institutionalizing preventive vaccination protocols, creating sustained demand for foot-and-mouth disease and bovine respiratory disease formulations.
- EU Green Deal Farm to Fork Strategy:This regulatory framework mandates reduced antibiotic use in livestock production, elevating preventive immunization as the primary pathogen management tool across member state cattle operations.
- mRNA platform maturation:Rapid strain-adaptable formulation capabilities are accelerating development timelines for emerging pathogen variants, attracting investment from developers seeking competitive differentiation in outbreak response scenarios.
Market Restraints
- Adjuvant input cost volatility:Oil-based adjuvant suspensions depend on petroleum derivative pricing, exposing formulation costs to energy market fluctuations that compress margin structures for inactivated vaccine producers.
- Cold chain infrastructure gaps:Extensive grazing systems across Argentina's Pampas region lack reliable refrigerated distribution networks, limiting live attenuated product penetration in high-volume beef production zones.
- EMA centralized procedure complexity:Marketing authorization timelines for novel delivery technologies extend development cycles, concentrating market access among manufacturers with established European regulatory expertise.
Strategic Opportunities
- India's northern dairy belt:Cooperative-led cattle health programs in Punjab, Haryana, and Uttar Pradesh are scaling rapidly, creating underpenetrated demand for affordable multivalent formulations targeting smallholder operations.
- Oral delivery channel innovation:Bait-based and water-soluble formulations are penetrating extensive grazing systems where animal handling infrastructure remains limited, opening new access points in Australia's rangeland beef sector.
- USDA-APHIS streamlined import pathways:Revised interstate movement regulations for approved biological products are reducing time-to-market for foreign manufacturers targeting North American cattle feedlot operations.
Industry Challenges
- mRNA manufacturing skill scarcity:Lipid nanoparticle formulation and cold-chain stabilization expertise remains concentrated among human pharmaceutical specialists, constraining talent pipelines for veterinary platform adaptation.
- Combination vaccine certification timelines:Multivalent formulation approvals require separate efficacy demonstrations for each antigen component, extending regulatory submission preparation and delaying commercial launch schedules.
- Legacy intramuscular infrastructure lock-in:Dairy operations with substantial capital investment in chute-based handling systems face switching costs when evaluating novel needle-free delivery technologies.
Report Scope
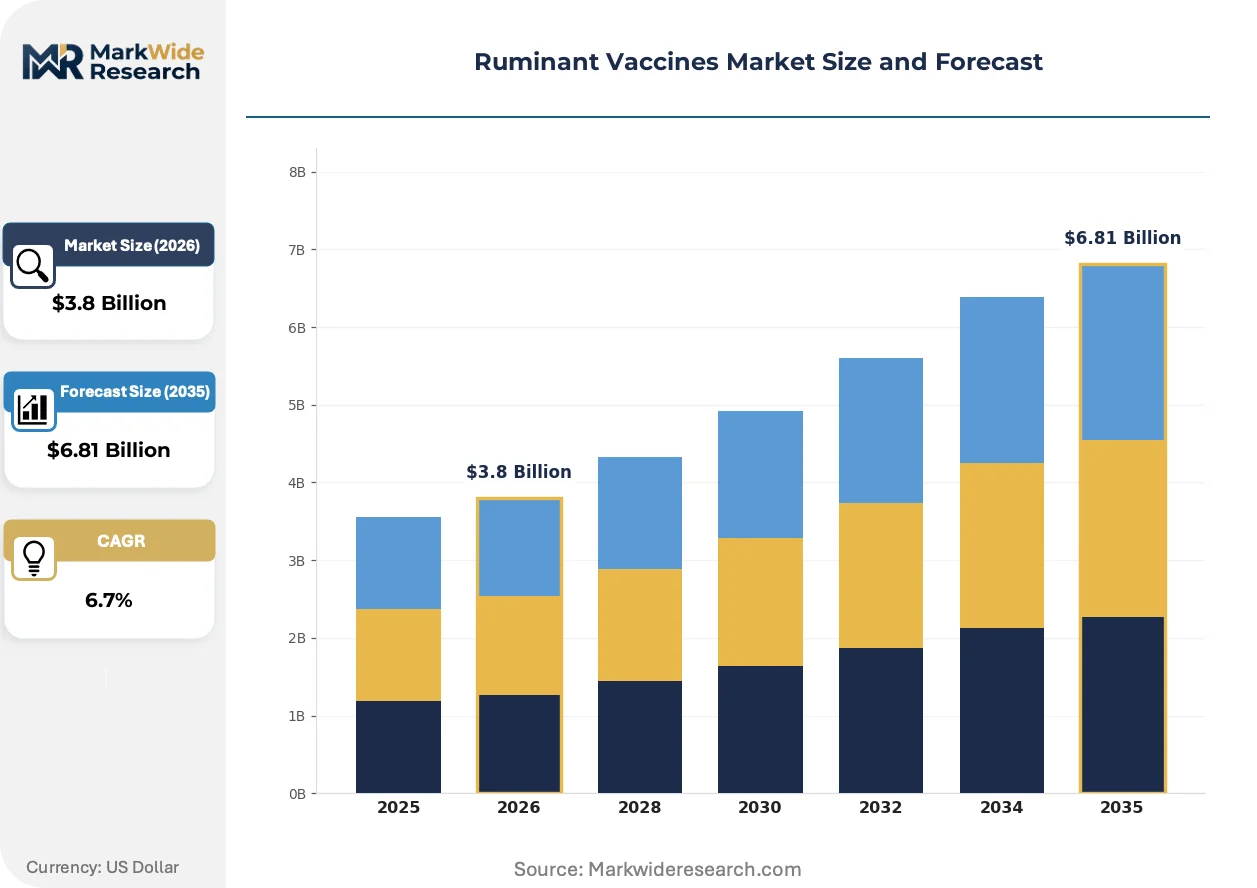
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ruminant Vaccines Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intramuscular, Subcutaneous, Oral, Dermal Delivery Mode: Live Attenuated, Inactivated, Subunit, mRNA Indication: Brucellosis, Foot and Mouth Disease, Pasteurellosis, Bovine Respiratory Disease End User: Farmers, Veterinary Clinics, Agricultural Cooperatives, Research Institutions |
| Companies Covered | Zoetis, Boehringer Ingelheim, Merck & Co., Inc., Elanco Animal Health, Ceva Santé Animale, Virbac, Vaxxinova International BV, Bimeda, CZ Vaccines S.A.U., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ruminant Vaccines Market Evolving Landscape
mRNA platform development is actively compressing traditional vaccine development cycles while enabling real-time strain adaptation capabilities that static live attenuated formulations cannot match.
Subunit recombinant formulations stabilized in novel lipid matrices are expanding into commercial dairy operations across the United States and Germany, where herd managers prioritize residue-free certification for export-market milk production. These platforms reduce withdrawal periods compared to oil-adjuvanted alternatives, enabling tighter compliance with EU Green Deal residue thresholds. The structural consequence is expanding into premium-priced product tiers previously dominated by established inactivated brands.
REACH regulatory extensions for veterinary pharmaceutical manufacturing are mandating enhanced environmental risk assessments for adjuvant disposal and manufacturing effluent, elevating compliance costs for European production facilities. Cattle vaccine manufacturers with German and Dutch manufacturing footprints are responding by retrofitting wastewater treatment systems and reformulating toward biodegradable suspension media. Small and mid-scale developers without captive chemistry expertise face accelerated consolidation pressure.
Dairy cooperative procurement collectives in India are consolidating purchasing decisions at state federation levels, displacing fragmented individual farm transactions that previously characterized vaccine distribution. These centralized buying committees now negotiate directly with manufacturers for annual supply contracts, compressing distributor margins and favoring suppliers with volume-scaled pricing flexibility. The procurement concentration is most visible in Gujarat and Rajasthan, where Amul-aligned cooperatives coordinate immunization schedules across member herds exceeding two million head.
Ruminant Vaccines Market Segmentation
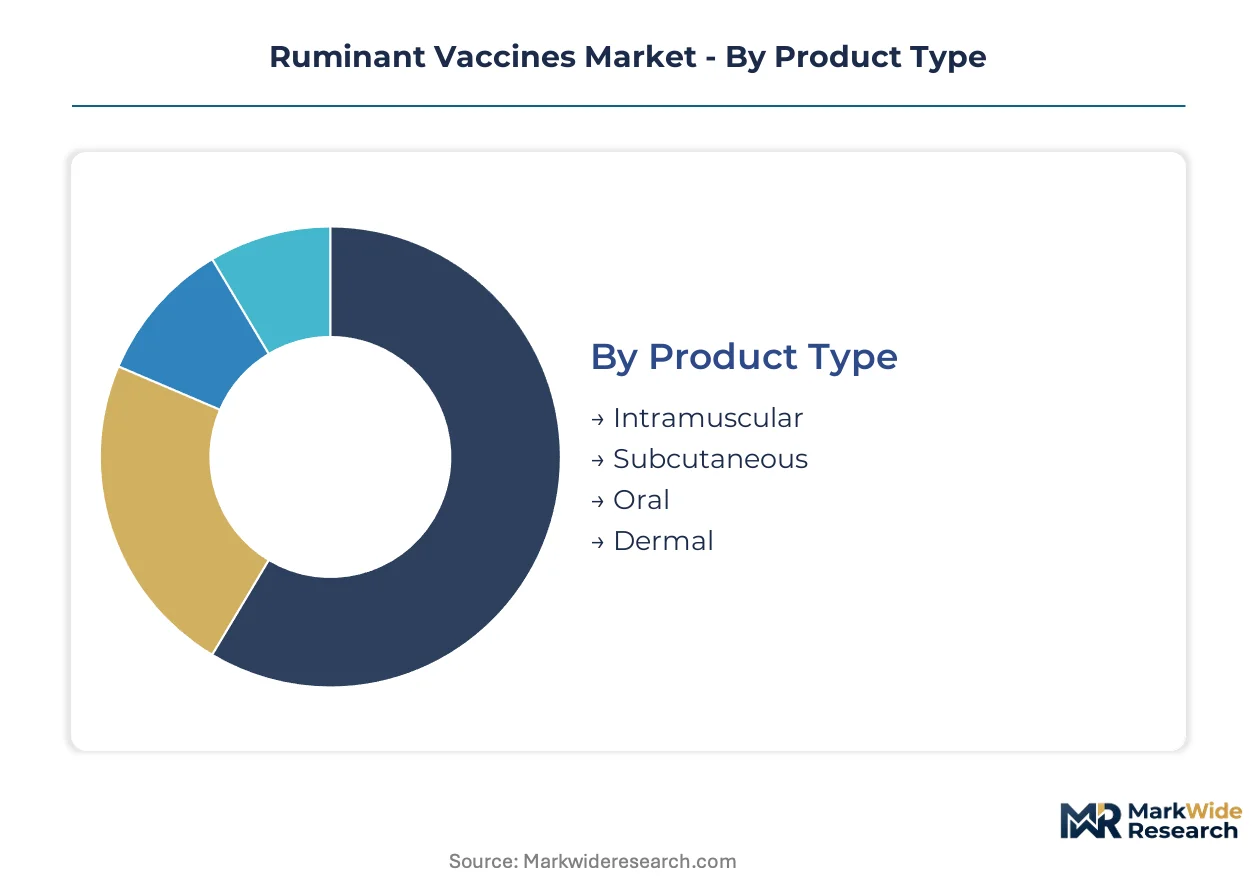
Ruminant vaccine segmentation reveals distinct technical and commercial boundaries that manufacturers navigate through specialized formulation strategies. Each dimension—administration route, immunological platform, disease target, and procurement channel—carries unique regulatory hurdles and margin structures that reshape competitive positioning.
Product Type:
Integration depth varies sharply across administration routes, with intramuscular and subcutaneous delivery dominating embedded veterinary service workflows while oral and dermal formats enable standalone deployment in remote grazing systems.
- Intramuscular:Deep-tissue injection into the neck or hindquarter muscle groups using oil-adjuvanted suspensions that prolong antigen release. Demand concentrates in Brazil's Minas Gerais dairy belt, where cooperative veterinarians administer scheduled multivalent protocols through chute-based handling systems.
- Subcutaneous:Needle placement beneath the skin surface permits smaller-gauge delivery and reduced tissue reaction compared to intramuscular alternatives. European cattle operations in Germany and the Netherlands favor this route for subunit recombinant formulations targeting residue-sensitive export markets.
- Oral:Bait-based and water-soluble preparations bypass handling infrastructure entirely. Argentina's Pampas beef producers deploy these in extensive rangeland systems where mustering costs exceed vaccine expenditure.
- Dermal:Needle-free jet injection or skin-patch delivery targets superficial lymphatic activation. Australian rangeland operators pilot these technologies to reduce needle-stick injuries in low-labor environments.
Volume placements concentrate in Intramuscular; the faster expansion belongs to Oral.
Delivery Mode:
Cost tier stratification separates mature platform technologies from emerging premium formats, with inactivated and live attenuated vaccines occupying economy-standard tiers while mRNA platforms command premium positioning through accelerated development timelines.
- Live Attenuated:Weakened pathogen strains replicate briefly to stimulate cellular and humoral immunity without causing disease. Foot-and-mouth disease control programs across India's Punjab and Haryana dairy belt rely heavily on these established formulations.
- Inactivated:Chemically killed pathogens suspended in oil or aluminum adjuvants provide stable, non-reverting safety profiles. These dominate commercial dairy operations seeking regulatory simplicity across multiple export jurisdictions.
- Subunit:Purified protein antigens eliminate whole-pathogen safety concerns entirely. German and Dutch manufacturers emphasize these for EU Green Deal compliance, as reduced adjuvant loads shorten milk withdrawal periods.
- mRNA:Lipid nanoparticle-encapsulated genetic instructions enable rapid strain adaptation without cell-culture manufacturing. Developers target this platform for emerging variant response, though veterinary cold-chain requirements and formulation expertise constraints limit current penetration.
Live Attenuated retains dominant volume share; mRNA platforms are climbing the fastest as developers pursue outbreak-responsive positioning.
Indication:
Application criticality shapes procurement urgency, with notifiable diseases commanding mandatory government programs while production-limiting conditions drive discretionary commercial purchasing.
- Brucellosis:Zoonotic bacterial infection triggering reproductive failure and human health risks. National eradication programs in Brazil and Argentina mandate vaccination, creating stable demand through government tender channels.
- Foot and Mouth Disease:Highly contagious viral infection devastating trade access for affected herds. India's cooperative-led cattle health programs scale rapidly around this indication, with Punjab state federations coordinating immunization across millions of head.
- Pasteurellosis:Respiratory and septicemic bacterial complex emerging during transport stress. North American feedlot operators prioritize these formulations in arrival processing protocols.
- Bovine Respiratory Disease:Multifactorial syndrome combining viral and bacterial pathogens. Combination vaccines targeting this complex dominate premium product tiers in intensive dairy and beef finishing systems.
Foot and Mouth Disease captures the largest program volumes; Bovine Respiratory Disease combination vaccines show the steepest expansion trajectory in premium commercial segments.
End User:
Customer type determines purchasing sophistication, with institutional buyers leveraging technical evaluation capabilities that individual farmers lack.
- Farmers:Individual livestock owners making direct procurement decisions based on veterinary recommendation and price sensitivity. India's smallholder dairy producers in Uttar Pradesh exemplify this segment, often purchasing single-dose sachets through local distributors.
- Veterinary Clinics:Service providers bundling vaccination into health programs with technical advisory components. Brazilian clinics in São Paulo state coordinate preventive protocols for medium-scale independent herds.
- Agricultural Cooperatives:Centralized purchasing bodies negotiating volume contracts and standardizing immunization schedules. Gujarat's Amul-aligned federations represent this segment's procurement concentration, displacing fragmented individual transactions.
- Research Institutions:Academic and governmental entities evaluating novel platforms and field efficacy. These users drive early adoption curves for mRNA and subunit technologies before commercial scaling.
Agricultural Cooperatives are gaining share fastest through procurement consolidation; Farmers retain residual volume in fragmented smallholder systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minas Gerais state's dairy special economic zones in Brazil concentrate preventive vaccination infrastructure, attracting formulation manufacturers seeking proximity to cooperative-led herd health programs.
Brazil
São Paulo and Minas Gerais dairy cooperatives institutionalize foot-and-mouth disease protocols for millions of head. ANVISA's veterinary pharmaceutical regulations govern import licensing and manufacturing standards. Campinas anchors formulation packaging operations serving southeastern cooperative networks.
India
Punjab, Haryana, and Uttar Pradesh dairy federations scale cattle health programs rapidly. CDSCO state committees oversee manufacturing licensing through decentralized approval pathways. Anand's Amul-aligned cooperatives coordinate immunization across member herds exceeding two million head.
United States
North American feedlot operators prioritize bovine respiratory disease combination vaccines in arrival processing protocols. USDA-APHIS regulates interstate movement and importation of biological products. Kansas and Texas Panhandle feedlot corridors concentrate demand for multivalent respiratory formulations.
Germany
Dutch and German dairy operations favor subunit recombinant formulations for residue-sensitive export milk production. EMA's centralized marketing authorization procedure governs approval across member states. Lower Saxony's concentrated dairy belt drives demand for reduced-withdrawal-period vaccines.
Argentina
Pampas beef producers deploy oral delivery formats in extensive rangeland systems lacking handling infrastructure. The country's national pharmaceutical regulator mandates efficacy demonstrations for multivalent approvals. Buenos Aires province anchors distribution networks reaching remote grazing zones.
Ruminant Vaccines Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressure favors entities with captive regulatory affairs capabilities and multi-plant manufacturing footprints. Three archetypes dominate: vertically integrated pharmaceutical conglomerates, regional specialists with deep distribution networks, and platform-technology developers pursuing mRNA differentiation. Competitive moves concentrate on portfolio diversification into rapid-response platforms and strategic partnerships bridging cold-chain infrastructure gaps.
Among US-based pharmaceutical conglomerates, Zoetis and Merck & Co., Inc. occupy positions reflecting scale-driven manufacturing networks and established veterinary service relationships. Boehringer Ingelheim represents European-anchored specialization in foot-and-mouth disease formulations. These three exemplify how regulatory expertise concentration and captive production infrastructure create defensive positioning against compliance cost escalation.
| Leading Market Players |
|---|
| Zoetis |
| Boehringer Ingelheim |
| Merck & Co., Inc. |
| Elanco Animal Health |
| Ceva Santé Animale |
| Virbac |
| Vaxxinova International BV |
| Bimeda |
| CZ Vaccines S.A.U. |
| Others |
Value Network & Pricing Analysis
mRNA platform maturation is simultaneously compressing development cost structures and concentrating manufacturing expertise among human pharmaceutical specialists, creating dual pressure on traditional live attenuated producers to either acquire lipid nanoparticle capabilities or accept margin erosion in commodity vaccine tiers.
Pricing Analysis
Lead-time-driven pricing stratification separates outbreak-responsive mRNA developers commanding premium positioning from spot-market inactivated vaccine suppliers competing on inventory availability. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—EMA centralized authorization commands highest tiers, while state-level CDSCO licensing enables economy positioning. Pricing pressure stems from petroleum derivative volatility affecting oil-adjuvant formulations, compressing margins for inactivated producers. Smallholder farmers in India's Uttar Pradesh exhibit highest price sensitivity, while German dairy cooperatives prioritize residue-free certification over unit cost.
Supply Chain Analysis
Adjuvant input supply rests on German and Dutch specialty chemical producers for oil-based suspensions, while lipid nanoparticle manufacturing draws from US and Swiss human pharmaceutical infrastructure. Key dependencies include petroleum derivatives for adjuvant formulations, cell-culture media for live attenuated production, and cold-chain equipment for mRNA stabilization. Single-source vulnerability concentrates in lipid nanoparticle expertise, where veterinary adaptation talent remains scarce. Distribution runs through cooperative procurement federations in Brazil's Minas Gerais and India's Gujarat, displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU MDR for veterinary medicinal products constructs a substantial compliance moat, elevating cost-of-entry for new manufacturers while rewarding entities with captive regulatory affairs capabilities and multi-plant manufacturing footprints.
For Market Incumbents: Anchor defensive positioning through backward integration into adjuvant chemistry and lipid nanoparticle formulation capabilities, countering mRNA platform disruption from human pharmaceutical crossovers. Prioritize certification investment in EMA centralized procedures to exploit compliance cost escalation forcing smaller competitors toward exit or acquisition.
For New Entrants and Emerging Players: Smallholder dairy cooperatives in India's northern belt represent the most penetrable buyer archetype, underserved by multivalent formulations priced for commercial operations. Pursue oral delivery innovation for Argentina's Pampas beef sector, where handling infrastructure gaps exclude intramuscular competitors. Go-to-market execution should leverage state federation direct contracting, bypassing distributor margin compression.
For Investors and Strategic Acquirers: Re-rating potential sits with platform-technology developers possessing mRNA strain-adaptation capabilities, given EMA regulatory clarity on novel delivery classifications as the catalyst. Long-term viability favors entities bridging human pharmaceutical expertise into veterinary cold-chain applications. Watch for CDSCO manufacturing licensing acceleration in Indian states as the inflection signal for cooperative procurement scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| mRNA Platform Adaptation | Lipid nanoparticle expertise from human pharma enables rapid veterinary strain response against foot-and-mouth disease variants. |
| Oral Delivery Formulation Development | Bait-based vaccines penetrate Argentina's Pampas rangelands where mustering costs exclude handling-intensive alternatives. |
| EMA Centralized Authorization Investment | Regulatory affairs capabilities exploit MDR compliance costs forcing consolidation among smaller European manufacturers. |
| Cooperative Procurement Direct Contracting | Amul-aligned federations in Gujarat displace distributor margins through centralized annual supply negotiations. |
| Cold Chain Infrastructure Partnership | Bridging gaps in Brazil's remote dairy zones sustains live attenuated product viability against subunit alternatives. |
Research Methodology
Multi-period observation of vaccination protocol adoption rates, cooperative procurement consolidation, and regulatory submission timelines anchored the trend analysis, supplemented by interviews with veterinary service directors, cooperative federation procurement managers, regulatory affairs leads at formulation manufacturers, and state-level CDSCO licensing officers. Secondary validation drew from EMA centralized procedure databases, USDA-APHIS biological product import records, ANVISA veterinary pharmaceutical filings, and cooperative annual reports. Bottom-up demand modeling across administration routes, delivery modes, and disease indications triangulated against top-down manufacturer capacity assessments.
Segment-weighting approaches allocated volume and value projections across intramuscular, subcutaneous, oral, and dermal administration routes, further disaggregated by live attenuated, inactivated, subunit, and mRNA delivery modes. CAGRs derived from logistic curve fitting to adoption pattern data, adjusted for regulatory approval timeline probabilities and cold-chain infrastructure rollout schedules. Forecast inputs incorporated EU Green Deal antibiotic reduction mandates, Brazilian dairy cooperative expansion trajectories, and Indian state federation immunization program scaling.
Revisions become necessary when EMA issues definitive mRNA platform guidance, when petroleum derivative volatility exceeds historical bands affecting adjuvant costs, or when Indian state-level procurement centralization accelerates beyond modeled adoption curves. Forecasts reflect documented assumptions about regulatory timeline stability, cooperative governance continuity, and technology transfer feasibility from human to veterinary applications. A small set of named triggers—EMA mRNA classification clarity, CDSCO licensing velocity, and lipid nanoparticle manufacturing cost curves—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biotechnology
Plant-Based Vaccines Market
Agricultural Biotechnology
Transgenic Seeds Market
Agricultural Biotechnology
Europe Plant Growth Regulators Market
Agricultural Biotechnology
Africa Algae Protein Market
Agricultural Biotechnology
Brazil Veterinary Vaccines Market
Agricultural Biotechnology
Microarray in Agriculture Market
Agricultural Biotechnology
Agroscience Market
Agricultural Biotechnology
Biorationals Market
Agricultural Biotechnology
Stigmasterol-Rich Plant Sterols Market
Agricultural Biotechnology
Global Animal Biotechnology Market
Agricultural Biotechnology
South America Feed Phytogenics Market
Agricultural Biotechnology
Duckweed Protein Market
Agricultural Biotechnology
Global Plant Hormones Market
Agricultural Biotechnology
GMO Crops and Seeds Market
Agricultural Biotechnology
Global Poultry Vaccines Market
Agricultural Biotechnology
Europe Agriculture Biotech Market