
 GMO Crops and Seeds Market | 2026-2036
GMO Crops and Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
GMO Crops and Seeds Market Foresight
Direct-to-farm distribution is narrowing as seed companies consolidate channel control across major agricultural belts. Bayer AG leverages its integrated trait-platform pipeline to sustain farmer loyalty programs in North American corn and soybean regions. Corteva Agriscience anchors its position through deep germplasm libraries and localized breeding stations. Syngenta AG competes on digital agronomy bundling, pairing seed sales with predictive analytics subscriptions.
Genetically modified organisms in crops and seeds are organisms whose DNA has been altered through recombinant nucleic acid techniques to express desired traits such as Bacillus thuringiensis protein production for lepidopteran resistance or CP4 EPSPS enzyme expression for glyphosate tolerance, primarily engineered to reduce input costs and stabilize yields across variable growing conditions. Herbicide-tolerant product types dominate planted acreage in soybean and corn rotations, though nutritionally enhanced variants command premium positioning in identity-preserved supply chains. Seed traits lead trait category revenue due to stacked-gene complexity, while quality traits occupy emerging margin pools in high-oil soybean and low-lignin alfalfa segments.
The USDA's Animal and Plant Health Inspection Service governs interstate movement and field release permits, while the EPA regulates plant-incorporated protectants under FIFRA, and FDA evaluates food safety through voluntary consultation, collectively creating a multi-agency compliance architecture that shapes product development timelines and market entry costs. Brazil's ANVISA and CTNBio enforce parallel biosafety frameworks that determine trait approval velocity in the second-largest adoption geography. Stakeholders must monitor regulatory divergence between stacked-trait approval pathways, as asynchronous authorizations disrupt seed trade flows and inventory planning across hemispheres.
Market Dynamics
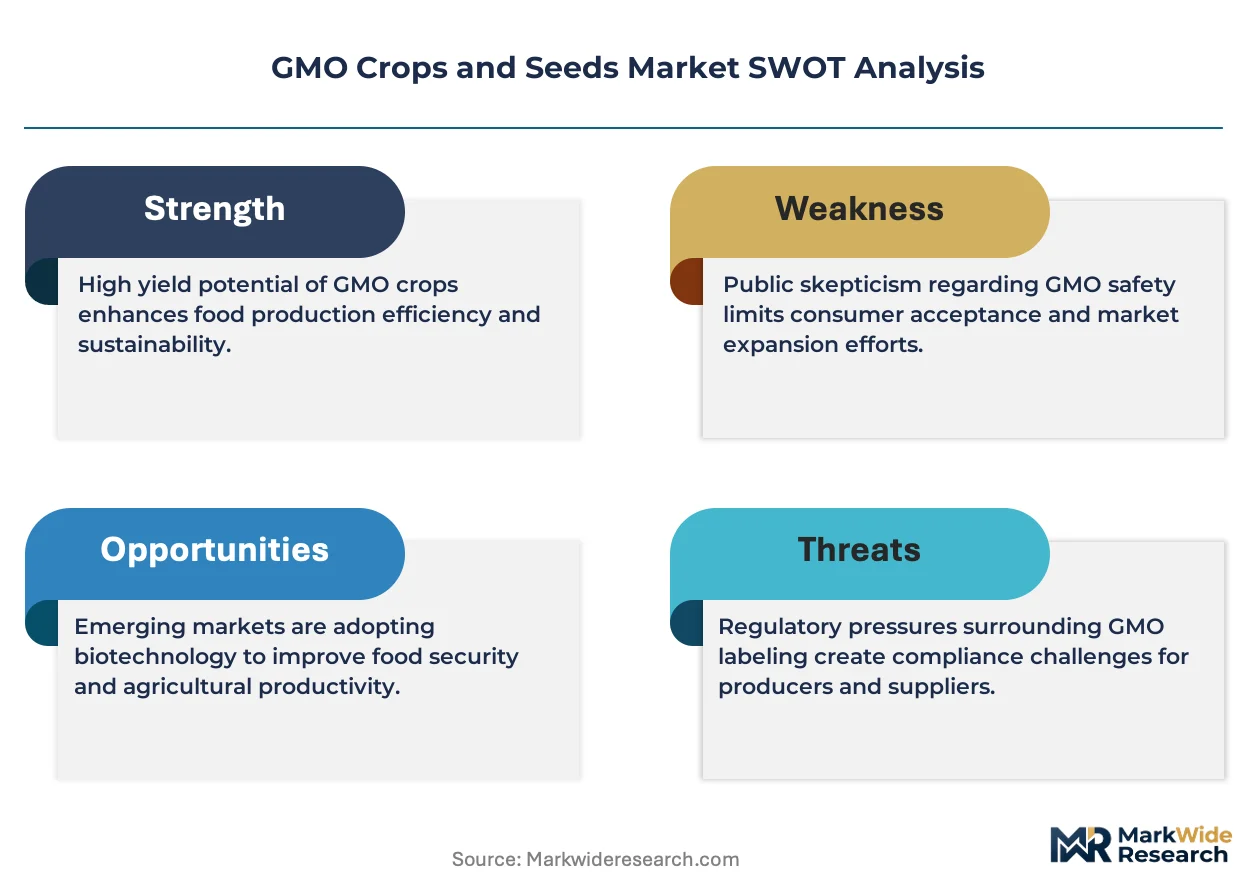
Stacked-trait gene editing is compressing product development cycles while regulatory asynchrony between the USDA, EPA, and FDA fragments approval timelines for novel plant-incorporated protectants.
Growth Catalysts
- Herbicide-tolerance stacking:Brazilian soybean growers under ANVISA's revised protocols are accelerating adoption of multi-trait varieties that reduce spray passes and labor inputs.
- Climate volatility:Drought-tolerant maize germplasm is gaining traction in rainfed production zones where yield stability now outweighs seed cost premiums.
- CTNBio expedited review:Brazil's streamlined biosafety assessments for known trait mechanisms are shortening market entry lags for second-generation events.
Market Restraints
- Trait royalty stacking:Licensing fees from multiple technology providers inflate per-acre seed costs beyond break-even thresholds for smaller operators.
- Asynchronous authorizations:EU regulatory delays on import approvals disrupt commodity trade flows and force inventory segregation in port logistics.
- Gene flow containment:Pollen-mediated trait migration into organic and conventional seed lots triggers liability exposure and identity-preserved supply chain premiums.
Strategic Opportunities
- Nutritionally enhanced soybeans:High-oleic acid variants for food oil applications command identity-preserved premiums in North American crush facilities.
- Digital agronomy bundling:Subscription-based predictive analytics paired with seed purchases are locking in multi-year grower commitments.
- Low-lignin alfalfa:Reduced fiber content variants improve dairy feed digestibility and open premium forage segments in livestock-dense regions.
Industry Challenges
- Regulatory science capacity:Shortages of molecular biologists and ecotoxicologists are extending dossier preparation timelines for novel trait submissions.
- Seed purification infrastructure:Cross-contamination risks in conditioning plants demand capital-intensive facility segregation and testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GMO Crops and Seeds Market |
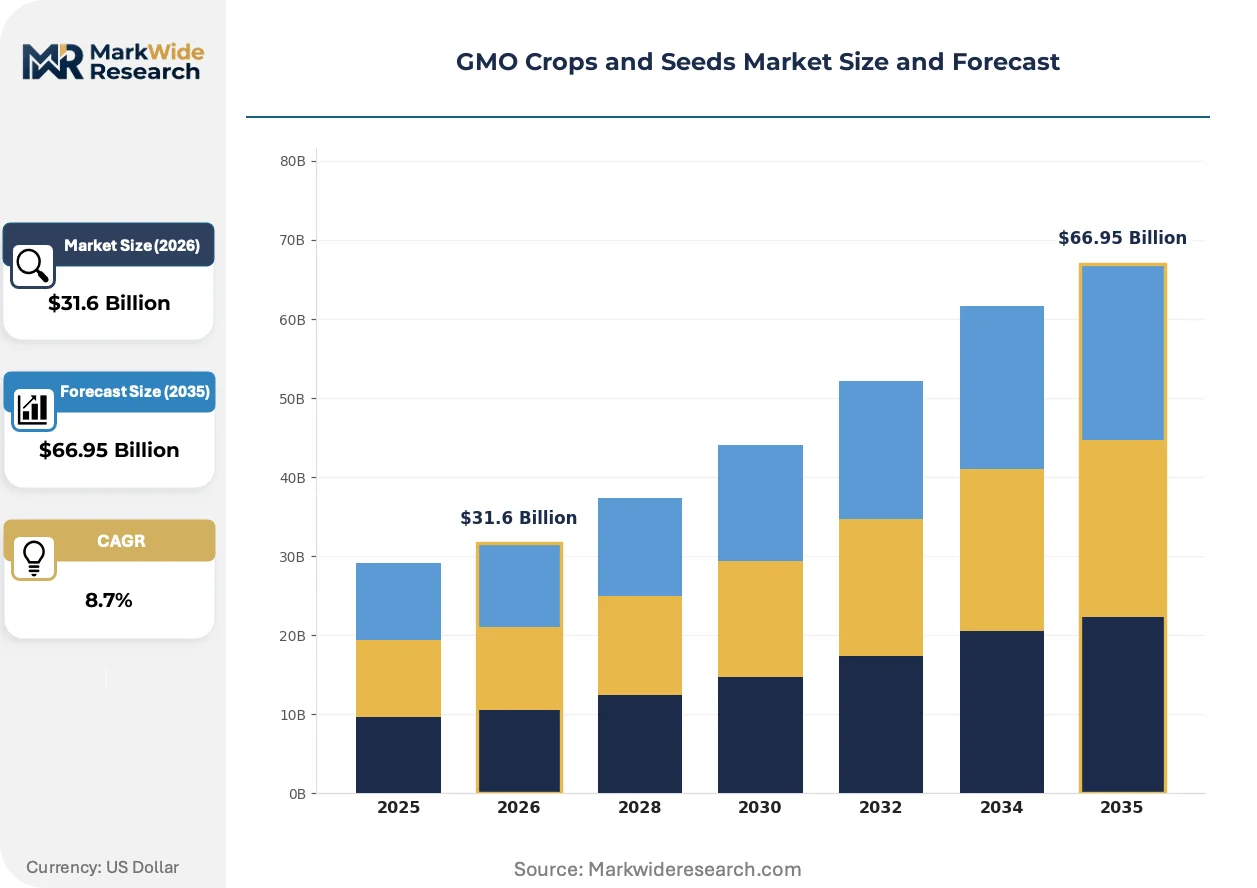
| Market Size in 2026 | $31.6 Billion |
| Market Size in 2035 | $66.95 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicide-Tolerant, Insect-Resistant, Drought-Resistant, Nutritionally Enhanced Trait: Seed Trait, Agronomic Trait, Quality Trait, Functional Trait End Use: Agricultural Production, Feed, Food Processing, Biofuel Production Distribution Channel: Direct Sales, Retail, Online, Third-Party Distributors |
| Companies Covered | Syngenta AG, KWS SAAT SE, Bayer AG, Sakata Seed Corporation, J.R. Simplot Co, Corteva Agriscience, Groupe Limagrain Holding SA, Beijing DaBeiNong Biotechnology Co Ltd, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GMO Crops and Seeds Market Shifts & Advancements
Gene editing platforms are supplanting transgenic insertion methods, compressing development timelines and expanding accessible trait categories beyond what agrobacterium-mediated transformation permitted.
CRISPR-Cas9 precise nucleotide editing is rendering obsolete the random insertion limitations of first-generation recombinant DNA techniques. Major row-crop breeding programs are integrating these platforms into soybean and corn pipelines. The technology is rendering obsolete lengthy backcrossing cycles and enabling direct modification of elite germplasm without yield drag.
EPA's revised plant-incorporated protectant exemption framework is narrowing registration requirements for certain gene-edited traits. This regulatory recalibration accelerates field release timelines for pest-resistant variants. Corn rootworm-resistant events are the primary beneficiaries, with developers redirecting regulatory budgets toward trait efficacy trials rather than mammalian toxicology studies.
Direct-to-farm seed procurement is consolidating around loyalty programs that bundle genetics with agronomic advisory services. Traditional distributor networks are ceding share to company-controlled channel structures in the US Corn Belt and Brazilian Cerrado. This channel compression is most pronounced in soybean markets where grower data integration drives repeat purchase behavior.
GMO Crops and Seeds Market Segmentation
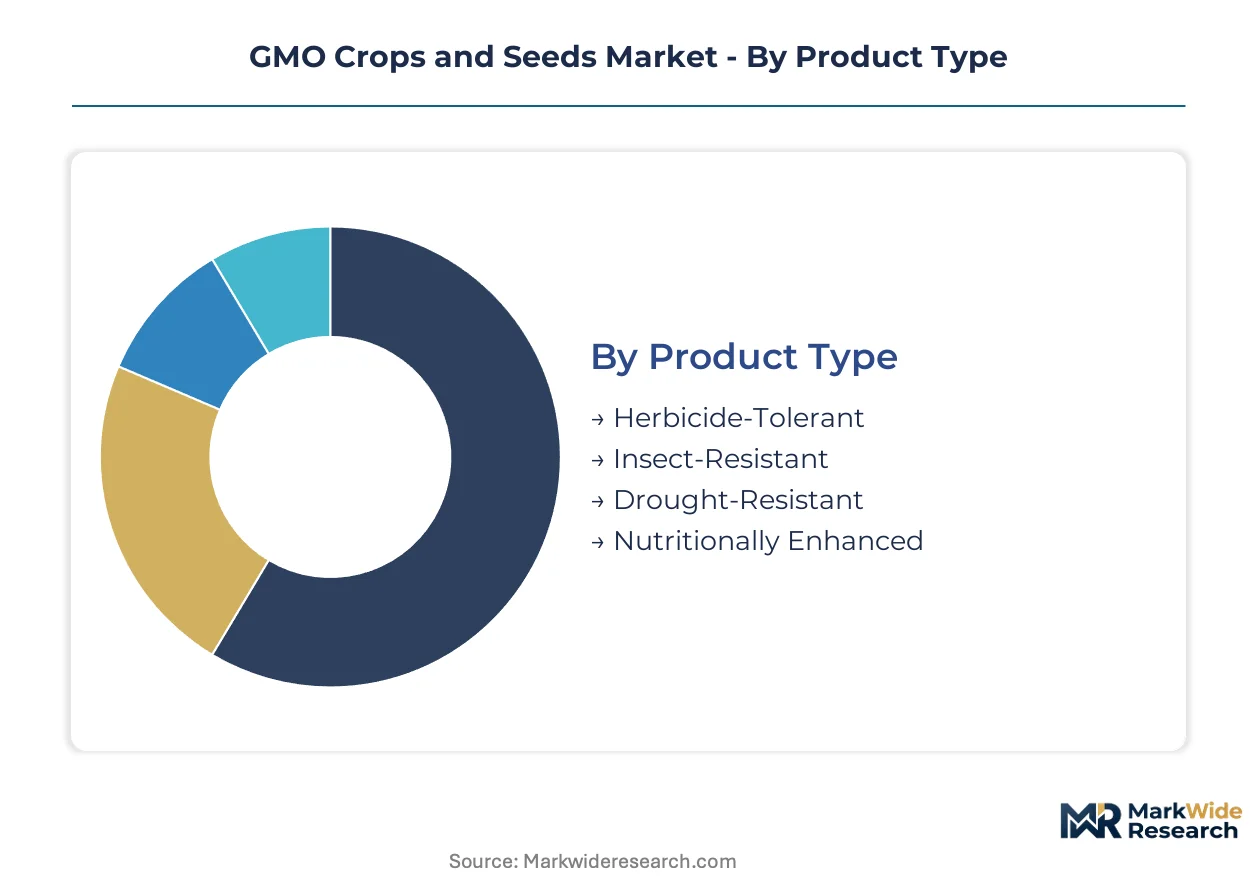
Segmentation in the GMO crops and seeds market reveals distinct commercial rhythms across product generations and trait categories. Breeders align portfolio refresh cycles with regulatory authorization timelines and farmer replacement rates for germplasm.
Product Type:
Herbicide-tolerant varieties turn over fastest as stacked-gene versions displace single-trait predecessors, while nutritionally enhanced lines move slowest due to identity-preserved infrastructure requirements.
- Herbicide-Tolerant:CP4 EPSPS and 2,4-D-resistant enzyme systems dominate soybean and corn rotations. Brazilian Cerrado operators under ANVISA's revised protocols are accelerating multi-trait adoption to reduce spray passes and labor inputs.
- Insect-Resistant:Bacillus thuringiensis protein expression targets lepidopteran and coleopteran pests in maize and cotton. Demand concentrates in North American corn rootworm pressure zones where refuge requirements shape planting patterns.
- Drought-Resistant:CspB and other stress-tolerance genes stabilize yields in rainfed production zones. US Great Plains dryland operations prioritize these traits where yield stability outweighs seed cost premiums.
- Nutritionally Enhanced:High-oleic soybean and low-lignin alfalfa variants require segregated handling infrastructure. Premium positioning in identity-preserved supply chains slows volume scaling relative to agronomic traits.
Herbicide-tolerant varieties anchor the volume base while nutritionally enhanced lines gain share at the steepest rate.
Trait:
Cost tier stratification separates commodity-priced agronomic traits from premium-positioned quality and functional categories with specialized downstream applications.
- Seed Trait:Stacked-gene complexity in germplasm drives the highest royalty stacking and per-unit pricing. Brazilian and US breeding programs concentrate R&D here due to repeat purchase lock-in.
- Agronomic Trait:Yield stability and stress tolerance genes deliver measurable field performance. Rainfed maize zones in Argentina and South Africa show concentrated demand where climate volatility pressures farm economics.
- Quality Trait:Oil composition and protein content modifications command crush facility premiums. North American high-oleic soybean contracts specify fatty acid profiles for food oil applications.
- Functional Trait:Industrial enzyme production and pharmaceutical protein expression occupy emerging margin pools. Regulatory complexity limits current deployment to contained production systems.
Seed traits dominate revenue concentration while functional traits expand most quickly into adjacent industrial applications.
End Use:
Application-driven demand splits between high-volume commodity channels and specialized segments with certification requirements and price premiums.
- Agricultural Production:Direct on-farm planting of GM seed for grain and fiber output represents the foundational demand pool. Large-scale mechanized operations in Brazil and the US Midwest drive trait adoption velocity.
- Feed:Corn and soybean meal specifications for livestock and aquaculture nutrition. Poultry-dense regions in Thailand and Vietnam import GM feed grains under asynchronous authorization constraints.
- Food Processing:Identity-preserved high-oleic and low-saturated-fat variants for packaged food manufacturers. North American crush facilities maintain segregated handling for premium oil extraction.
- Biofuel Production:Enzyme-enhanced corn varieties optimize ethanol fermentation efficiency. US Renewable Fuel Standard compliance drives consistent demand for yield-dense germplasm.
Agricultural production anchors the volume base while food processing climbs the fastest on premium oil and protein specifications.
Distribution Channel:
Customer type and geography dictate channel selection, with direct sales consolidating in concentrated farming belts and retail persisting in fragmented landholding regions.
- Direct Sales:Seed companies bypass distributors to control grower data and loyalty program enrollment. US Corn Belt and Brazilian Cerrado operations favor this channel for bundled agronomic advisory.
- Retail:Independent dealers and cooperatives serve smaller operators with credit terms and localized service. Fragmented landholding regions in India and Eastern Europe maintain retail dependence.
- Online:Digital procurement platforms emerge for standard trait packages with transparent pricing. Younger farm operators in Australia and Canada experiment with direct-to-farm e-commerce.
- Third-Party Distributors:Regional seed houses with conditioning and treatment capabilities intermediate in markets with infrastructure gaps. Sub-Saharan African markets rely on this channel for last-mile delivery.
Direct sales anchors the volume base while online channels gain share at the steepest rate among digitally integrated farm operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Brazilian Cerrado operations where ANVISA's expedited CTNBio reviews compress trait approval cycles, while EU import authorization delays force North American exporters into costly inventory segregation protocols at Rotterdam and Hamburg port terminals.
United States
USDA-APHIS field release permits and EPA FIFRA plant-incorporated protectant registrations govern the largest commercial GM crop acreage globally. The Iowa-Illinois corn-soybean belt drives stacked-trait germplasm turnover through company-controlled direct-to-farm channels. Bayer AG and Corteva Agriscience anchor loyalty programs that bundle predictive analytics with seed purchases across the Midwest.
Brazil
CTNBio's streamlined biosafety assessments for known trait mechanisms shorten market entry lags for second-generation herbicide-tolerant soybean events. ANVISA's revised protocols enable multi-trait variety launches that reduce spray passes in Mato Grosso's mechanized operations. Seed distributors expand portfolios across the Cerrado where large-scale farming accelerates adoption velocity.
Argentina
The country's national biosafety commission CONABIA evaluates stacked-trait events for corn and soybean commercialization in the Pampas grain belt. Drought-tolerant maize germplasm gains traction in rainfed western provinces where yield stability outweighs seed cost premiums. Buenos Aires province anchors crush facility demand for high-oleic soybean identity-preserved contracts.
China
MOA seed variety approval and MEE biosafety certificates regulate domestic GM crop cultivation limited currently to cotton and papaya. The Yangtze River Delta and North China Plain concentrate research station activity for drought-resistant maize germplasm development. Beijing DaBeiNong Biotechnology anchors domestic breeding programs targeting eventual soybean and corn commercialization.
Canada
Health Canada novel food assessments and CFIA environmental release permits govern canola trait commercialization on the Prairies. Alberta and Saskatchewan seed growers prioritize herbicide-tolerant canola varieties for export crush markets. Identity-preserved handling infrastructure at Vancouver port terminals serves premium oil specification contracts for Asian food processors.
GMO Crops and Seeds Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in trait licensing and germplasm refinement. The market structure concentrates around three global conglomerates with integrated trait-to-seed pipelines, while regional breeders and gene editing boutiques occupy specialized niches. Two strategic archetypes dominate: full-stack integrators controlling genetics, chemistry, and digital agronomy; and modular specialists licensing discrete traits to third-party seed houses. Competitive moves center on M&A-driven germplasm library expansion and direct-to-farm channel compression that displaces independent distributors.
Among German-based conglomerates, Bayer AG and BASF SE exemplify the integrated platform archetype through captive trait pipelines and loyalty program infrastructure. Corteva Agriscience, spun from DowDuPont, occupies a position bridging germplasm depth with digital bundling strategies. Syngenta AG, under ChemChina ownership, represents the state-linked platform model with emphasis on emerging market penetration. Beijing DaBeiNong Biotechnology anchors the domestic Chinese specialist tier focused on regulatory preparation for eventual commercial trait releases.
| Leading Market Players |
|---|
| Syngenta AG |
| KWS SAAT SE |
| Bayer AG |
| Sakata Seed Corporation |
| J.R. Simplot Co |
| Corteva Agriscience |
| Groupe Limagrain Holding SA |
| Beijing DaBeiNong Biotechnology Co Ltd |
| BASF SE |
| Others |
Supply & Pricing Matrix
Mato Grosso's seed conditioning clusters anchor South American supply capacity, where CTNBio-authorized trait volumes concentrate before dispersal to Brazilian Cerrado operators and Argentine Pampas growers. This geographic concentration grants conditioning facilities significant leverage over per-unit seed premiums, particularly for stacked-gene varieties requiring specialized purification protocols.
Pricing Analysis
The customization-premium spread separates identity-preserved high-oleic soybean contracts from commodity herbicide-tolerant base pricing. Three-tier pricing structure across premium, standard, and economy levels reflects trait complexity, with stacked-gene germplasm commanding royalty premiums and single-trait varieties competing on volume discounts. Cost compression in standard-tier soybean seed is intensifying because Brazilian distributors consolidate purchasing power under ANVISA's revised protocols. Smaller operators in fragmented landholding regions exhibit highest price sensitivity, while large-scale mechanized farms in the US Corn Belt prioritize trait performance over per-acre cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for soybean germplasm exporters. Production concentrates in the United States, Brazil, and Argentina, where breeding stations and conditioning plants draw from captive germplasm libraries, proprietary trait licenses, and regional fertilizer inputs. Single-source vulnerability around CRISPR-Cas9 platform patents threatens second-generation development timelines. Distribution runs through company-controlled direct-to-farm channels in concentrated farming belts, with third-party distributors persisting in infrastructure-limited markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene editing platforms are compressing product development cycles by half relative to transgenic methods, creating a regulatory inflection as EPA narrows plant-incorporated protectant registration requirements.
For Market Incumbents: Pre-empt trait royalty stacking pressure by consolidating licensing agreements with gene editing boutiques before second-generation events reach CTNBio review. Deepen backward integration into seed conditioning infrastructure across Mato Grosso and Iowa to capture identity-preserved premiums. Defend against digital agronomy disruptors by embedding predictive analytics subscriptions into multi-year grower contracts. For New Entrants and Emerging Players: Pursue drought-tolerant maize germplasm development for rainfed zones in Argentina's western provinces, where yield stability premiums outweigh established player loyalty. Target nutritionally enhanced soybeans for North American crush facilities seeking high-oleic oil specifications. Deploy subscription-based agronomic advisory as the primary go-to-market angle to bypass distributor channel control. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform integrators bundling seed sales with digital agronomy subscriptions. Long-term viability centers on germplasm library depth and regulatory dossier preparation capacity. Acquire gene editing boutiques with EPA-exempt trait pipelines. Monitor CTNBio authorization velocity as the inflection signal for Brazilian market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Editing Platform Integration | CRISPR-Cas9 adoption compresses development timelines and expands accessible trait categories beyond transgenic limits. |
| Direct-to-Farm Channel Expansion | Bayer AG and Corteva Agriscience bypass distributors to control grower data and lock in repeat purchases. |
| Regulatory Dossier Preparation | EPA's revised plant-incorporated protectant framework narrows registration requirements for certain gene-edited traits. |
| Digital Agronomy Bundling | Syngenta AG pairs seed sales with predictive analytics subscriptions to secure multi-year grower commitments. |
| Identity-Preserved Infrastructure Investment | Segregated handling capabilities at crush facilities enable premium positioning for high-oleic soybean contracts. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of USDA-APHIS field release permits, EPA FIFRA registrations, CTNBio authorization records, and seed company SEC disclosures. Primary interviews engaged trait development scientists, regulatory affairs directors at major seed houses, Brazilian distributor procurement managers, and US Corn Belt farm operators. Secondary validation drew from ANVISA biosafety protocol revisions, FDA voluntary consultation filings, and commodity trade flow data. Bottom-up acreage estimates and top-down revenue triangulation anchor the analytical framework.
Forecast inputs include trait adoption velocity across herbicide-tolerant, insect-resistant, and nutritionally enhanced product categories, segmented by crop type, trait complexity, distribution channel, and regional regulatory cluster. Modeled dimensions span seed traits versus quality traits, direct sales versus retail channel penetration, and Brazilian Cerrado versus US Midwest adoption patterns. CAGRs derive from acreage expansion rates and per-unit pricing trajectories across the projection horizon. Industry-specific inputs incorporate CTNBio review cycle durations and EPA exemption pathway eligibility.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, fertilizer input costs, or currency volatility in Brazil and Argentina would shift the trajectory. Forecasts reflect assumptions around regulatory authorization synchronization and gene editing platform adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biotechnology
Transgenic Seeds Market
Agricultural Biotechnology
Microarray in Agriculture Market
Agricultural Biotechnology
Asia-Pacific Agriculture Biotech Market
Agricultural Biotechnology
Global Plant Hormones Market
Agricultural Biotechnology
Brazil Veterinary Vaccines Market
Agricultural Biotechnology
Stigmasterol-Rich Plant Sterols Market
Agricultural Biotechnology
Biorationals Market
Agricultural Biotechnology
Asia Pacific Feed Phytogenics Market
Agricultural Biotechnology
Europe Agriculture Biotech Market
Agricultural Biotechnology
Animal Brucella Antibody ELISA Kits Market
Agricultural Biotechnology
South America Feed Phytogenics Market
Agricultural Biotechnology
Agroscience Market
Agricultural Biotechnology
Global Animal Biotechnology Market
Agricultural Biotechnology
Africa Algae Protein Market
Agricultural Biotechnology
Ruminant Vaccines Market
Agricultural Biotechnology
Agricultural Biotechnology Market