
 Global Poultry Vaccines Market | 2026-2036
Global Poultry Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Poultry Vaccines Market Foresight
Multi-source procurement among integrated poultry producers is broadening as disease pressure diversifies across geographies. Zoetis leverages its recombinant platform portfolio to sustain technology leadership in vector-based solutions. Boehringer Ingelheim International GmbH anchors European supply through high-volume manufacturing infrastructure. Merck & Co., Inc. differentiates via deep R&D investment in next-generation delivery systems.
Poultry vaccines are biological preparations containing attenuated, inactivated, or recombinant antigenic material designed to induce active immunity against avian pathogens such as Newcastle disease virus, infectious bronchitis virus, and avian influenza; formulations typically require cold-chain maintenance at two to eight degrees Celsius and deliver protection through humoral and cell-mediated immune responses in broiler, layer, and breeder populations. Live attenuated products dominate volume sales due to cost efficiency and rapid onset of immunity in high-turnover broiler operations. Recombinant vaccines represent the fastest-growing product category as producers seek marker-assisted differentiation between field and vaccine strains. Application demand skews heavily toward broilers, where short production cycles amplify the economic impact of outbreak-related mortality and condemnations.
USDA and FDA oversight in the United States, EMA and EFSA frameworks in Europe, and China's MEE dual carbon compliance requirements collectively shape product registration pathways, manufacturing standards, and cross-border trade access for poultry vaccine suppliers. India's CDSCO and BIS certification mandates further complicate market entry for foreign manufacturers seeking participation in government-backed poultry health programs. Stakeholders must monitor evolving regulatory convergence around antigen traceability and cold-chain documentation as import authorities tighten biosecurity protocols.
Market Dynamics
The recombinant vector platform transition is compressing development timelines while fragmenting procurement patterns across integrated poultry operations. Brazil, Southeast Asia, and the United States drive divergent demand specifications that suppliers must reconcile through modular manufacturing architectures.
Growth Catalysts
- Biosecurity mandates in Southeast Asia:Commercial broiler operations face intensifying regulatory requirements for pathogen traceability. This accelerates adoption of marker-assisted vaccines that enable serological differentiation.
- Vertical consolidation in Brazil:Integrated producers are centralizing vaccine procurement decisions to manage pathogen pressure in dense production zones. This concentrates volume purchasing power among fewer decision-makers.
- Recombinant platform maturation:Vector-based delivery systems now support multivalent antigen expression. This reduces administration frequency and labor costs in high-turnover broiler operations.
Market Restraints
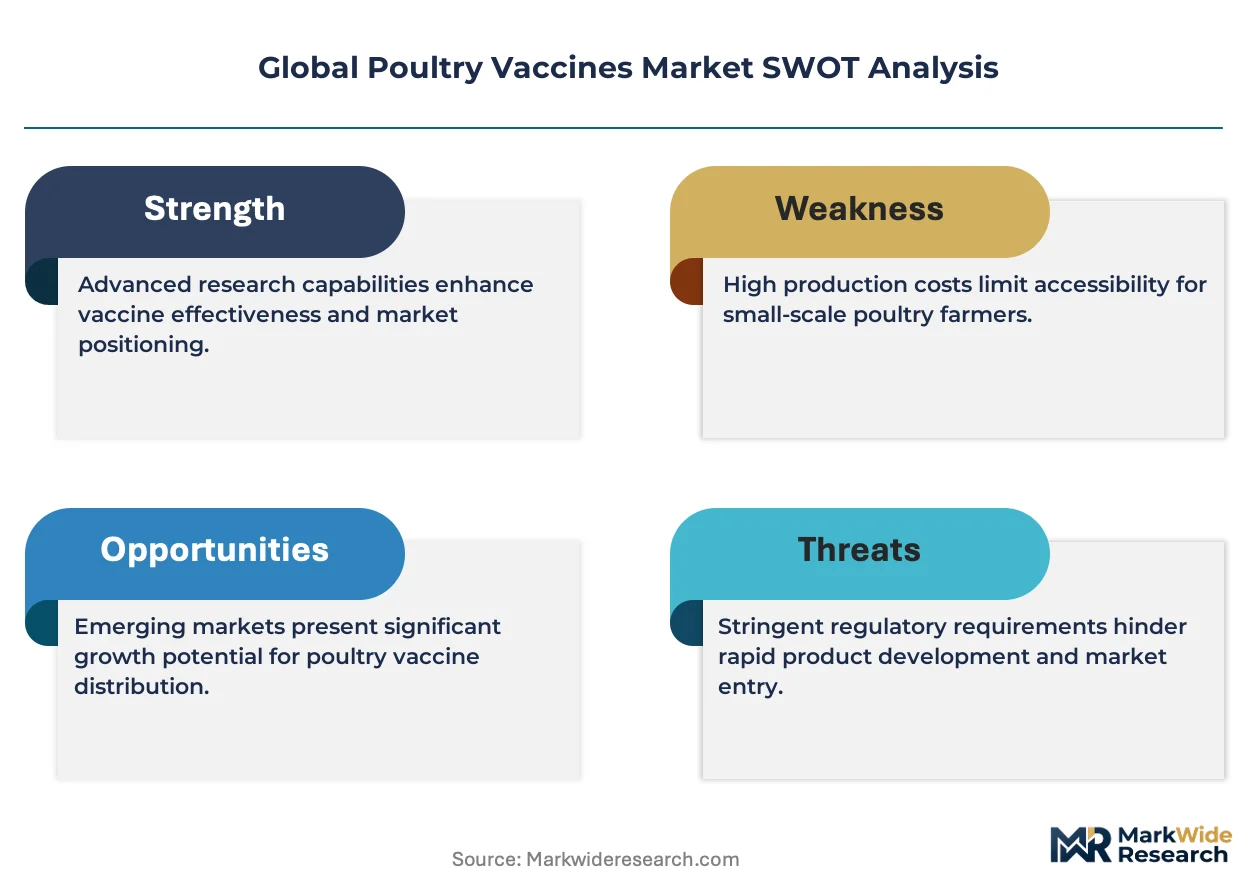
- Cold-chain infrastructure gaps:Two-to-eight-degree Celsius maintenance requirements exclude rural poultry operations in tropical climates. Distribution losses concentrate in last-mile segments lacking refrigerated logistics.
- Regulatory fragmentation:USDA, EMA, and China's MEE maintain divergent antigen traceability standards. Registration timelines extend as manufacturers replicate documentation across jurisdictions.
- Live attenuated cost anchoring:Established low-cost alternatives constrain pricing power for recombinant entrants. Broiler operations with thin margins resist premium formulations despite superior safety profiles.
Strategic Opportunities
- India's government-backed health programs:CDSCO and BIS certification pathways, once navigated, unlock participation in subsidized vaccination campaigns targeting smallholder integration.
- Thermostable formulation development:Elimination of cold-chain dependence would expand addressable market to off-grid poultry operations. This convergence of materials science and delivery technology represents unclaimed white space.
- Digital health integration:Vaccination records linked to blockchain traceability systems align with EU Green Deal and CSRD supply-chain disclosure requirements. Early movers capture premium positioning in European export supply chains.
Industry Challenges
- Specialized formulation expertise scarcity:Recombinant vector optimization requires rare combinations of virology and immunology training. Recruitment competition intensifies between animal health and human pharmaceutical sectors.
- Legacy system integration friction:Existing inventory management platforms at integrated producers lack API compatibility with new digital vaccination tracking tools. Retrofit costs delay technology adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Poultry Vaccines Market |
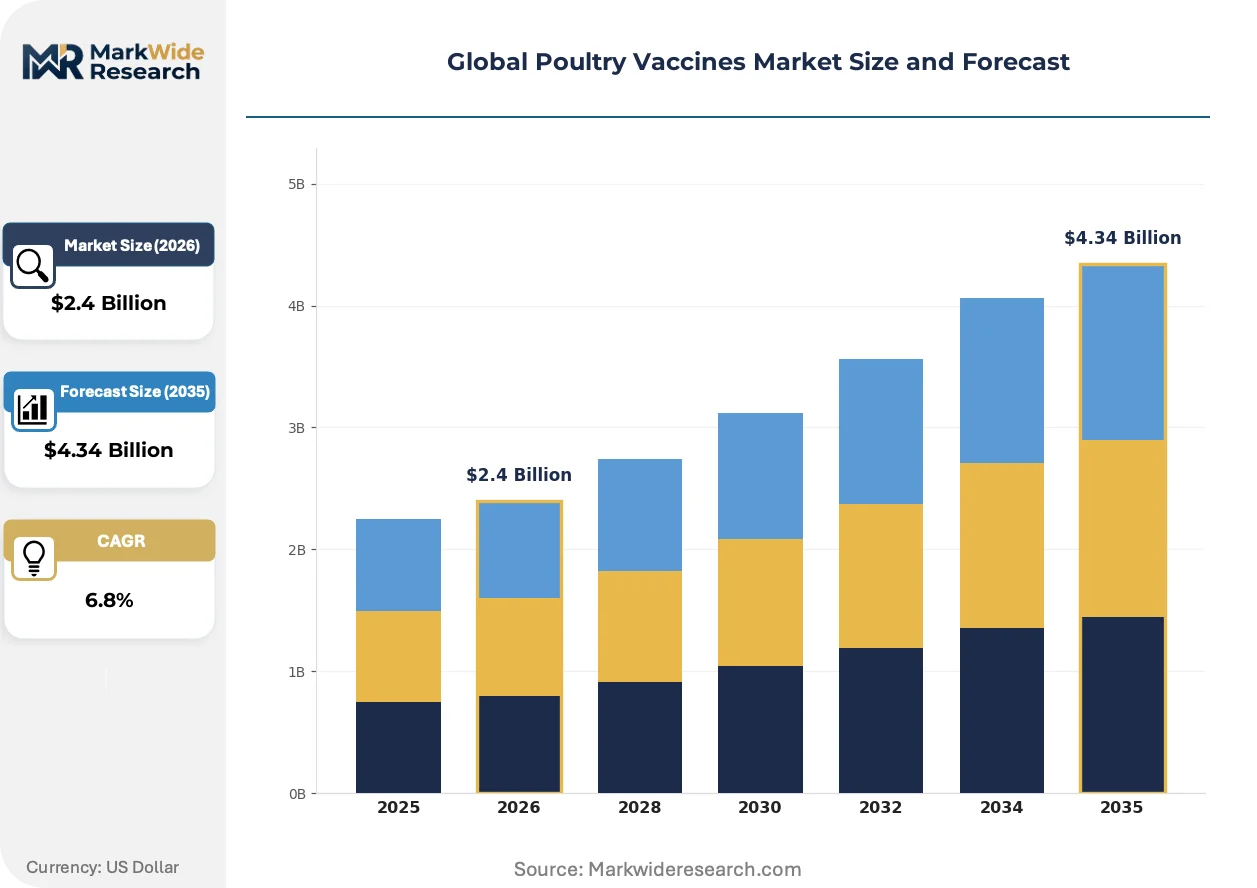
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Attenuated, Inactivated, Subunit, Recombinant, DNA, Toxoid Application: Broilers, Layers, Breeders, Quails, Turkeys, Ducks End User: Commercial Farms, Backyard Farms, Veterinary Clinics, Research Institutes Distribution Channel: Direct Sales, Wholesalers, Retail Pharmacies, Online Platforms, Veterinary Distributors |
| Companies Covered | Boehringer Ingelheim International GmbH, Zoetis, Merck & Co., Inc., Elanco, Ceva Sante Animale, Phibro Animal Health Corporation, Hester Biosciences Limited, Dechra Pharmaceuticals PLC, Vaxxinova International BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Poultry Vaccines Market Shifts & Advancements
Platform convergence between molecular biology and data analytics is redefining how poultry vaccines are designed, monitored, and valued. Three interconnected developments are compressing innovation cycles and reshaping competitive boundaries.
Recombinant vector platforms are absorbing development investment previously allocated to conventional attenuation methods. These systems enable rapid antigen swapping against emerging Newcastle disease variants. Large integrated producers in Brazil and Thailand are adopting them at accelerating pace. The technology is absorbing regulatory scrutiny that formerly targeted live virus handling protocols, compressing biosafety infrastructure requirements.
EU Green Deal and CSRD supply-chain disclosure mandates are forcing antigen provenance documentation. European importers now require batch-level traceability from hatchery to processing facility. This regulatory shift favors manufacturers with integrated quality management systems. Layer operations supplying European retail chains are most affected, driving consolidation toward suppliers with established EU veterinary certificates.
Outcome-based purchasing agreements are displacing traditional unit-price contracting in North American broiler operations. Buyers now tie payment to flock performance metrics including mortality rates and feed conversion ratios. This restructuring transfers disease risk from producers to vaccine suppliers. The model is most visible in vertically integrated operations across the southeastern United States, where scale permits statistical validation of efficacy claims.
Global Poultry Vaccines Market Segmentation
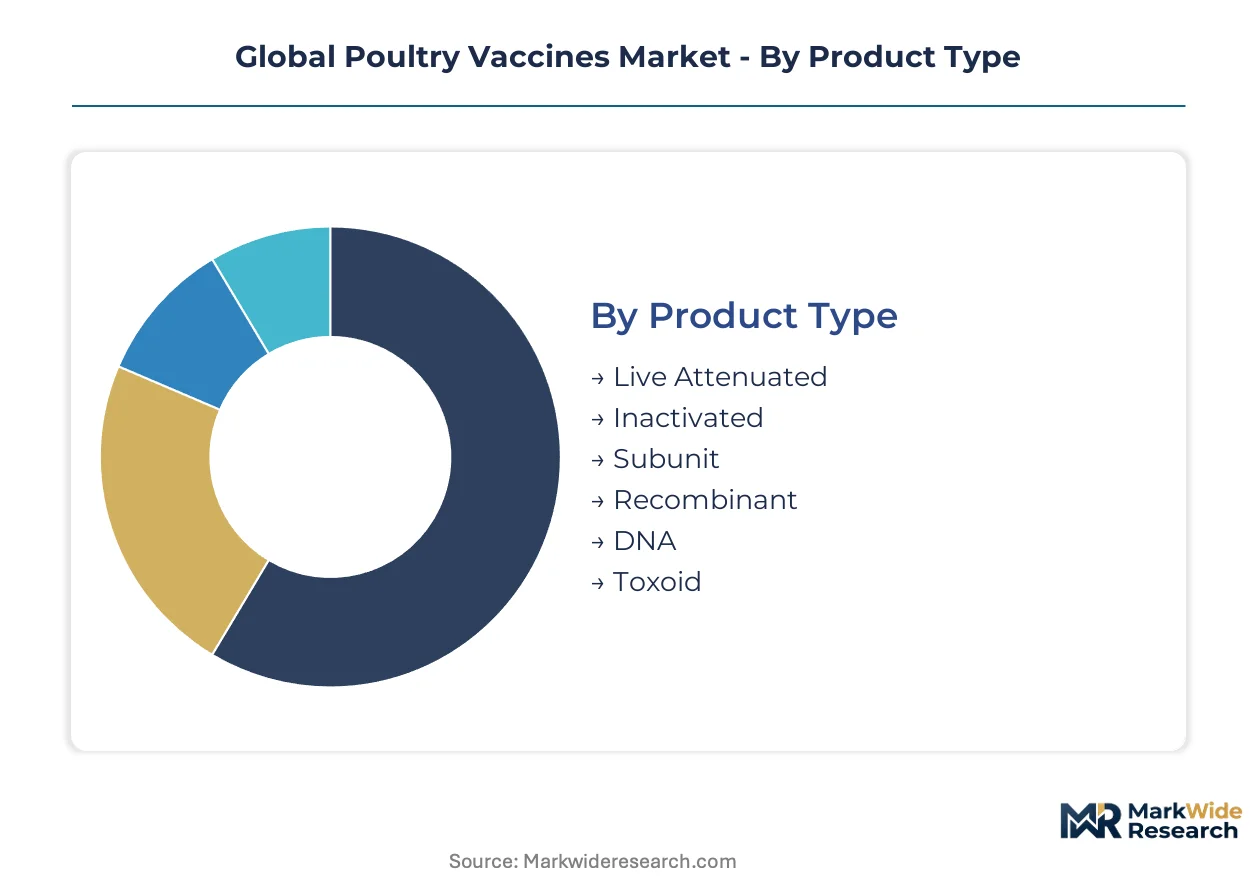
Poultry vaccine procurement patterns fragment sharply across production scales and biosecurity requirements. Understanding these divisions reveals where recombinant platforms displace legacy formulations and which channels capture margin in cold-chain-dependent distribution.
Product Type:
Standalone live attenuated products dominate high-volume, low-margin operations where rapid immunity onset outweighs biosafety infrastructure costs. Recombinant and DNA platforms embed into integrated systems requiring marker-assisted serological differentiation.
- Live Attenuated:Formulations contain weakened pathogenic strains that replicate minimally in host tissue to stimulate robust cell-mediated immunity. Demand concentrates in Brazilian commercial broiler houses where thin margins prioritize cost-per-dose over biosafety infrastructure; established supply chains and veterinary familiarity sustain entrenched positioning despite handling complexity.
- Recombinant:Vector-based delivery systems express target antigens without replication-competent pathogen presence, enabling DIVA-compliant serological monitoring. Southeast Asian integrated producers are adopting these platforms fastest as regulatory mandates for field-vaccine strain differentiation harden; reduced biosafety containment requirements offset higher per-unit costs.
- Inactivated:Killed whole-pathogen preparations requiring adjuvant enhancement and multi-dose protocols.
- Subunit:Purified protein or polysaccharide antigens selected for conserved epitopes.
- DNA:Plasmid-encoded antigen expression systems with extended onset intervals but simplified cold-chain tolerance.
- Toxoid:Inactivated exotoxin preparations targeting clostridial diseases in breeder management protocols.
Volume placements concentrate in Live Attenuated; the faster expansion belongs to Recombinant.
Application:
Short production cycles in meat-focused segments prioritize rapid onset and cost minimization. Layer and breeder operations accept extended protocols to safeguard longer productive lifespans and vertical disease transmission risks.
- Broilers:Meat-focused birds harvested within 35-42 days require vaccines inducing protection before maternal antibody decay. Brazilian and Thai integrated operations drive specification standards; recombinant vector adoption accelerates here as outcome-based contracting links payment to feed conversion and mortality performance.
- Layers:Extended 60-80 week production cycles demand sustained immunity against respiratory and reproductive pathogens. European layer operations supplying retail chains face EU Green Deal traceability mandates; batch-level antigen provenance documentation favors suppliers with integrated quality management systems.
- Breeders:Parent stock operations require comprehensive protection against vertically transmitted pathogens to safeguard commercial offspring.
- Quails:Specialized game bird production with localized veterinary protocol variation.
- Turkeys:Seasonal production cycles with distinct pathogen pressure profiles requiring species-specific formulation adaptation.
- Ducks:Aquaculture-integrated operations in Southeast Asia with emerging influenza vaccination requirements.
Broilers absorb the highest absolute dose volumes; Layers command premium positioning through certification-linked procurement.
End User:
Scale determines whether procurement centralizes through integrated supply chains or fragments across independent veterinary relationships. Cold-chain capability and diagnostic infrastructure separate addressable segments.
- Commercial Farms:Large-scale operations with automated vaccination equipment and on-site cold storage. Vertically integrated Brazilian and US southeastern producers centralize procurement decisions; volume purchasing power concentrates among fewer decision-makers managing pathogen pressure in dense production zones.
- Veterinary Clinics:Professional service intermediaries with diagnostic capability and prescriptive authority. These channels dominate in regions with fragmented farm ownership where technical consultation justifies margin capture.
- Backyard Farms:Smallholder operations with limited cold-chain access and informal supply relationships.
- Research Institutes:Institutional purchasers supporting field trial validation and regulatory submission requirements.
Procurement value concentrates in Commercial Farms; service intensity peaks in Veterinary Clinics.
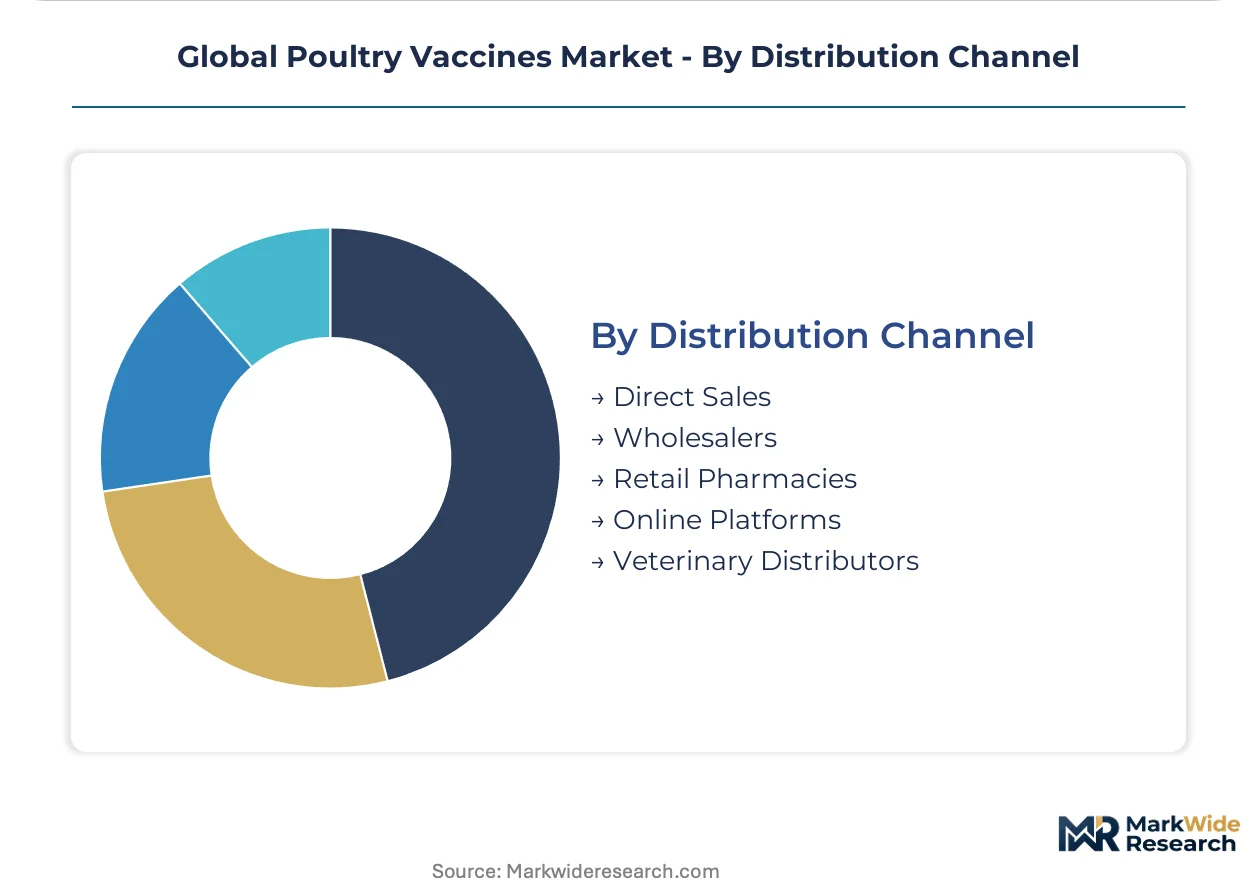
Distribution Channel:
Direct relationships dominate where volume and technical support requirements justify dedicated account management. Intermediary channels persist where geographic fragmentation or regulatory complexity demands local presence.
- Direct Sales:Manufacturer-to-producer relationships with embedded technical service and flock performance monitoring. Large integrated operations in Brazil and the United States favor this channel; outcome-based purchasing agreements require direct data integration between supplier and buyer systems.
- Veterinary Distributors:Specialized intermediaries with cold-chain logistics and field technical capacity. These networks capture margin in regions with dispersed commercial farm geography where manufacturer direct coverage is uneconomical.
- Wholesalers:Generalist distributors with limited technical value-add.
- Retail Pharmacies:Point-of-sale access for smallholder and backyard operations.
- Online Platforms:Emerging direct-to-farm channels with documentation limitations for regulated biologics.
Direct Sales commands the highest value per transaction; Veterinary Distributors retain essential reach in fragmented geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Brazil, the United States, and China, where integrated poultry operations drive specification standards for recombinant vector platforms and cold-chain distribution infrastructure.
Brazil
Vertical consolidation among integrated producers concentrates procurement decisions in São Paulo and Paraná states. ANVISA registration pathways govern import authorization for foreign-manufactured biologics. Dense production zones around Londrina and Chapecó amplify pathogen pressure, accelerating adoption of marker-assisted vaccines for serological differentiation.
United States
USDA and FDA oversight shapes manufacturing standards for domestic suppliers and import authorization protocols. Outcome-based purchasing agreements in the southeastern broiler belt tie vaccine payments to flock performance metrics. Georgia and Arkansas operations lead recombinant platform adoption as large integrators centralize supply chain control.
China
MEE dual carbon compliance requirements intersect with agricultural biosecurity mandates to reshape manufacturing facility standards. Yangtze River Delta and Shandong Peninsula clusters house domestic vaccine production capacity serving vertically integrated poultry groups. Local producers dominate government-backed vaccination campaigns targeting smallholder integration.
India
CDSCO and BIS certification mandates complicate market entry for foreign manufacturers seeking participation in subsidized poultry health programs. Gujarat and Maharashtra commercial farms drive demand for cost-optimized live attenuated formulations. Haryana's breeder operations represent emerging adoption pockets for recombinant platforms requiring cold-chain infrastructure investment.
Germany
EMA frameworks and EU Green Deal supply-chain disclosure requirements impose batch-level antigen provenance documentation on layer operations supplying retail chains. Lower Saxony's dense poultry production geography favors veterinary distributor networks with embedded cold-chain logistics. Bavarian integrated producers anchor regional specification standards for multivalent vector-based delivery systems.
Global Poultry Vaccines Market Competitive Landscape
Portfolio diversification dominates the current landscape as suppliers reconcile divergent regional specifications through modular manufacturing architectures. The vendor base clusters around three strategic archetypes: diversified animal health conglomerates with recombinant platform portfolios, regional specialists with established regulatory pathways in single geographies, and contract manufacturing organizations serving private-label vaccine programs. Technology licensing agreements and capacity expansion in high-growth markets represent the dominant competitive moves as firms position for outcome-based contracting adoption.
Among diversified animal health conglomerates, Boehringer Ingelheim International GmbH, Zoetis, and Merck & Co., Inc. occupy positions exemplifying the scale-driven archetype. Boehringer Ingelheim International GmbH represents European-anchored manufacturing infrastructure serving high-volume contract requirements. Zoetis exemplifies recombinant vector platform leadership through technology portfolio breadth. Merck & Co., Inc. anchors the R&D-intensive tier with next-generation delivery system investments. These three entities sit within the premium-tier supplier category where direct sales relationships and integrated quality management systems determine competitive positioning.
| Leading Market Players |
|---|
| Boehringer Ingelheim International GmbH |
| Zoetis |
| Merck & Co., Inc. |
| Elanco |
| Ceva Sante Animale |
| Phibro Animal Health Corporation |
| Hester Biosciences Limited |
| Dechra Pharmaceuticals PLC |
| Vaxxinova International BV |
| Others |
Supply & Pricing Matrix
Outcome-based purchasing agreements in the southeastern United States and Brazil are compressing supplier margins and forcing manufacturers toward direct sales relationships with embedded technical service. This procurement shift concentrates volume purchasing power among fewer integrated producers, eroding price premiums for intermediated distribution while rewarding suppliers with flock performance data integration capabilities.
Pricing Analysis
Volume placements concentrate in live attenuated formulations where thin margins in Brazilian broiler operations anchor per-dose pricing floors; premium-mid-economy pricing differentiation separates recombinant vector platforms with DIVA compliance from commodity live products. Price differentiation hinges on biosafety infrastructure avoidance and serological traceability certification. Pricing pressure stems from cold-chain distribution losses in tropical last-mile segments. Backyard farms and smallholder operations exhibit highest price sensitivity; European layer operations supplying retail chains show lowest sensitivity due to EU Green Deal compliance premiums.
Supply Chain Analysis
Direct-to-producer channels handle hyperscale demand from Brazilian and US southeastern integrated operations, while veterinary distributor networks retain essential reach in geographically fragmented European and Indian markets. Manufacturing concentration centers on Germany, the United States, and China for recombinant platform production; Brazil and India host regional fill-finish capacity for live attenuated formulations. Active ingredient supply draws from specialized bioreactor equipment and SPF egg production facilities. Single-source vulnerability concentrates in vector strain licensing agreements. Distribution runs through cold-chain-dependent logistics with two-to-eight-degree Celsius maintenance requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recombinant platform maturation is consolidating procurement decisions among fewer integrated producers with technical validation capabilities, forcing regional specialists without vector expertise toward contract manufacturing or exit.
For Market Incumbents: Lock in exclusive supply relationships with Brazil's vertically integrated producers through outcome-based contracting tied to feed conversion metrics. Prioritize thermostable formulation R&D to capture off-grid smallholder demand currently excluded by cold-chain requirements. Defend against emerging contract manufacturing organizations by embedding flock performance monitoring software into direct sales relationships. For New Entrants and Emerging Players: Launch via India's subsidized poultry health programs after navigating CDSCO and BIS certification pathways. Target thermostable vaccine development as the most penetrable white space, where materials science convergence with delivery technology remains unclaimed. Pursue white-label manufacturing partnerships with domestic Indian producers lacking recombinant vector capabilities. For Investors and Strategic Acquirers: The window for entry favors contract manufacturing organizations with established regulatory pathways in high-growth markets. Long-term viability rests on capturing share from regional specialists unable to fund recombinant platform transitions. Watch for ANVISA registration acceleration in Brazil as the inflection signal for foreign manufacturer market access liberalization.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Platform Licensing Agreement | Vector strain access from Boehringer Ingelheim or Zoetis compresses development timelines for regional entrants. |
| Thermostable Formulation Development | Elimination of cold-chain dependence expands addressable market to Southeast Asian smallholder operations. |
| Direct Sales Channel Expansion | Embedded technical service captures outcome-based contracts with Brazilian integrated producers. |
| CDSCO Certification Pathway Investment | Unlocks participation in India's government-backed vaccination campaigns targeting smallholder integration. |
| Blockchain Traceability Integration | Batch-level antigen provenance documentation aligns with EU Green Deal supply-chain disclosure mandates. |
Research Methodology
Independent corroboration across regulatory filing databases, customs trade records, and veterinary procurement registries underwrites the qualitative findings. Primary interviews with poultry vaccine development executives, regulatory affairs leads at animal health conglomerates, integrated producer procurement directors, and veterinary distributor operations heads combined with secondary validation from USDA APHIS import authorization records, ANVISA registration filings, EMA veterinary product databases, and CDSCO approval trackers. Bottom-up segment sizing and top-down market reconciliation triangulate volume and value estimates.
Rate-of-change decomposition across the analysis window isolates volume growth from price-mix effects in broiler, layer, and breeder application segments. The analytical framework models product type transitions, regional regulatory cluster adoption curves, and end-user scale distributions. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporate recombinant platform penetration assumptions and cold-chain infrastructure development trajectories.
The model assumes a particular technology adoption path; alternative pathways for thermostable formulation breakthroughs would alter the outlook. Forecasts reflect assumptions regarding regulatory convergence timelines and integrated producer consolidation rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biotechnology
South America Feed Phytogenics Market
Agricultural Biotechnology
GMO Crops and Seeds Market
Agricultural Biotechnology
Europe Plant Growth Regulators Market
Agricultural Biotechnology
Global Animal Biotechnology Market
Agricultural Biotechnology
Animal Brucella Antibody ELISA Kits Market
Agricultural Biotechnology
Stigmasterol-Rich Plant Sterols Market
Agricultural Biotechnology
Plant-Based Vaccines Market
Agricultural Biotechnology
Microarray in Agriculture Market
Agricultural Biotechnology
Biorationals Market
Agricultural Biotechnology
Ruminant Vaccines Market
Agricultural Biotechnology
Europe Agriculture Biotech Market
Agricultural Biotechnology
Agricultural Biotechnology Market
Agricultural Biotechnology
Transgenic Seeds Market
Agricultural Biotechnology
Asia Pacific Feed Phytogenics Market
Agricultural Biotechnology
Africa Algae Protein Market
Agricultural Biotechnology
Duckweed Protein Market