
 Duckweed Protein Market | 2026-2036
Duckweed Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Duckweed Protein Market Foresight
Direct procurement between duckweed cultivators and nutraceutical formulators is tilting away from traditional ingredient distributors. Plantible Foods leverages its proprietary lemna cultivation platform to anchor supply security for large-scale buyers. Hinoman, Ltd. competes through controlled-environment agriculture systems that sustain year-round protein yields regardless of climate variability.
Duckweed protein comprises dried and processed biomass from lemna, spirodela, and wolffia species, typically yielding 35-45% crude protein with a complete amino acid profile including lysine and methionine; the material serves as a functional ingredient in food fortification, feed formulation, and nutritional supplements. Powder formats dominate current commercial volumes due to superior shelf stability and blending compatibility with existing manufacturing lines. Human consumption applications represent the fastest-expanding margin pool as clean-label positioning commands premium pricing over commodity feed grades.
The FDA GRAS notification framework and EU Novel Food Regulation govern market entry pathways for duckweed-derived ingredients, with EFSA safety assessments increasingly referenced by national regulators in Germany and France. The USDA BioPreferred program and evolving EPA biofuel coproduct standards indirectly shape cultivation economics by valorizing residual biomass streams. Stakeholders must monitor how protein digestibility-corrected amino acid scoring methodologies evolve, as these metrics will determine competitive positioning against established pea and soy isolates.
Market Dynamics
Direct supply agreements between Dutch biorefinery clusters and North American food formulators are compressing traditional ingredient distribution tiers, restructuring how duckweed protein reaches commercial buyers.
Growth Catalysts
- EU Novel Food Regulation:Accelerated safety assessment pathways are compressing approval timelines for lemna-derived ingredients entering human food applications.
- Controlled-environment agriculture:Closed-system photobioreactor deployments sustain year-round protein yields regardless of outdoor climate variability.
- Netherlands:Dense agrotech infrastructure enables integrated cultivation-processing-logistics chains that lower unit economics for export volumes.
Market Restraints
- Input cost volatility:Nutrient media and artificial lighting energy costs fluctuate with natural gas pricing, squeezing margins for indoor cultivation operators.
- Supply concentration risk:Commercial-scale biomass output clusters in the Netherlands and selected US states, creating geographic vulnerability to localized disruptions.
- Regulatory friction:FDA GRAS notification timelines vary unpredictably, delaying market entry for new cultivator-processor entrants.
Strategic Opportunities
- Germany:Underdeveloped domestic cultivation capacity creates import demand for EU-compliant duckweed protein isolates.
- Precision fermentation convergence:Hybrid processing combining biomass extraction with microbial protein enhancement opens novel ingredient categories.
- USDA BioPreferred program:Federal procurement preferences for bio-based materials create institutional purchasing pull for certified duckweed derivatives.
Industry Challenges
- Phycobiology expertise scarcity:Limited talent pools for lemna strain optimization and aquaculture engineering constrain R&D throughput.
- Digestibility certification timelines:PDCAAS and DIAAS validation studies require 12-18 month laboratory cycles before nutritional claims approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Duckweed Protein Market |
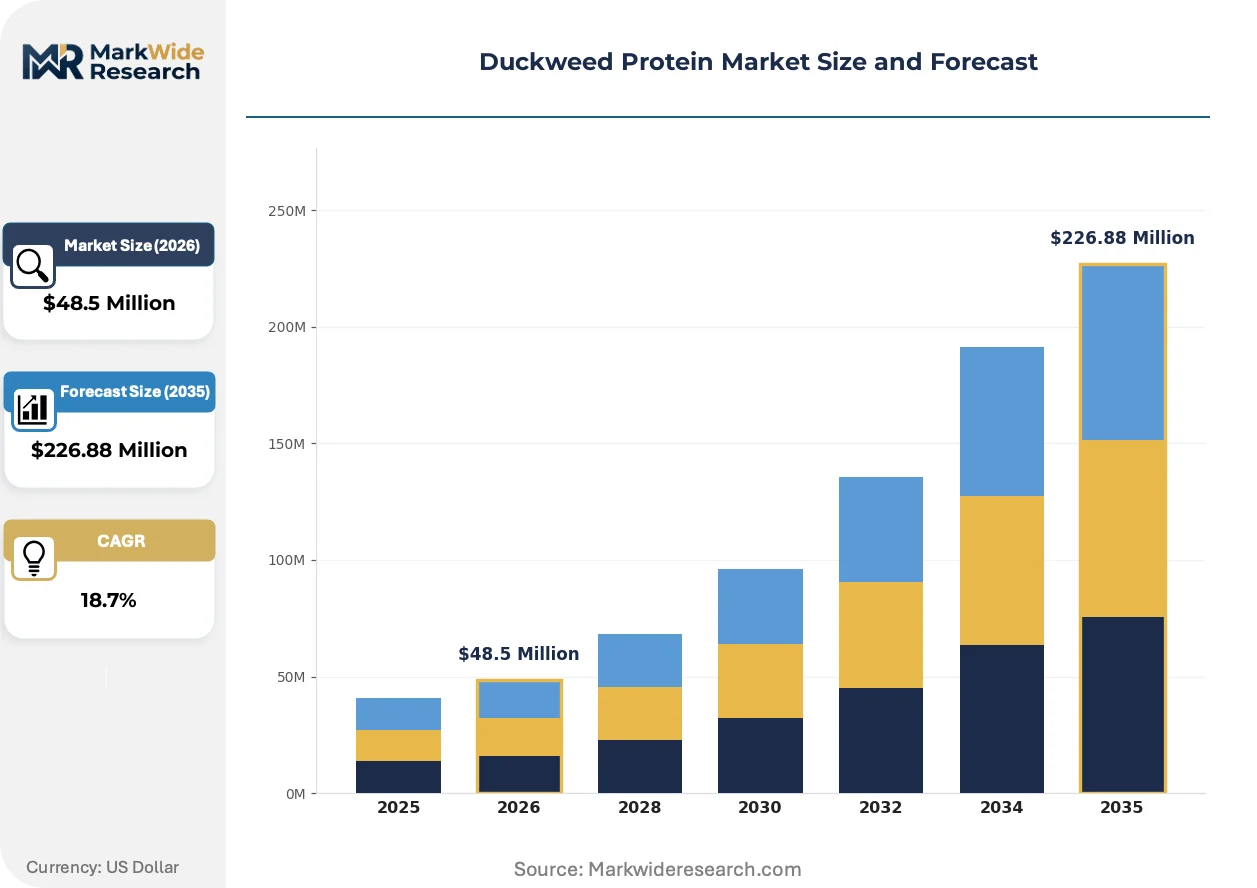
| Market Size in 2026 | $48.5 Million |
| Market Size in 2035 | $226.88 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Flour, Extract, Granules End User: Food Industry, Feed Industry, Nutraceuticals, Cosmetics Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales Application: Sustainable Agriculture, Aquaculture, Human Consumption, Animal Feed |
| Companies Covered | Barentz Bio Healthife, Lempro Inc., Plantible Foods, GreenOnyx Ltd., Nutraceutical International Corporation, Hinoman, Ltd., Seta Organics, Algama, Parabel USA Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Duckweed Protein Market Shifts & Advancements
Processing technology convergence and regulatory pathway maturation are compressing the gap between pilot-scale biomass output and commercial ingredient integration.
Photobioreactor engineering is hybridizing with membrane filtration systems to enable continuous-flow protein extraction that preserves functional properties. Food formulators in the plant-based meat sector are adopting these hybrid lines to secure non-soy, non-pea protein supplies. The technology is hybridizing traditional batch processing economics with continuous manufacturing throughput, compressing capital recovery periods for facility operators.
EFSA safety assessment methodologies are harmonizing across Germany, France, and the Netherlands, reducing redundant national filings for Novel Food authorizations. This regulatory convergence accelerates cross-border ingredient trade within the EU single market. Dutch cultivators are responding by scaling biorefinery capacity to serve pan-European buyers under unified compliance frameworks.
Ingredient procurement is consolidating around multi-year offtake contracts with embedded volume commitments and quality specifications. Traditional spot-market purchasing through commodity distributors is retreating as food manufacturers prioritize supply security. This pattern is most visible in North American plant-based meat operations, where formulators bypass distributors to contract directly with cultivation platforms.
Duckweed Protein Market Segmentation
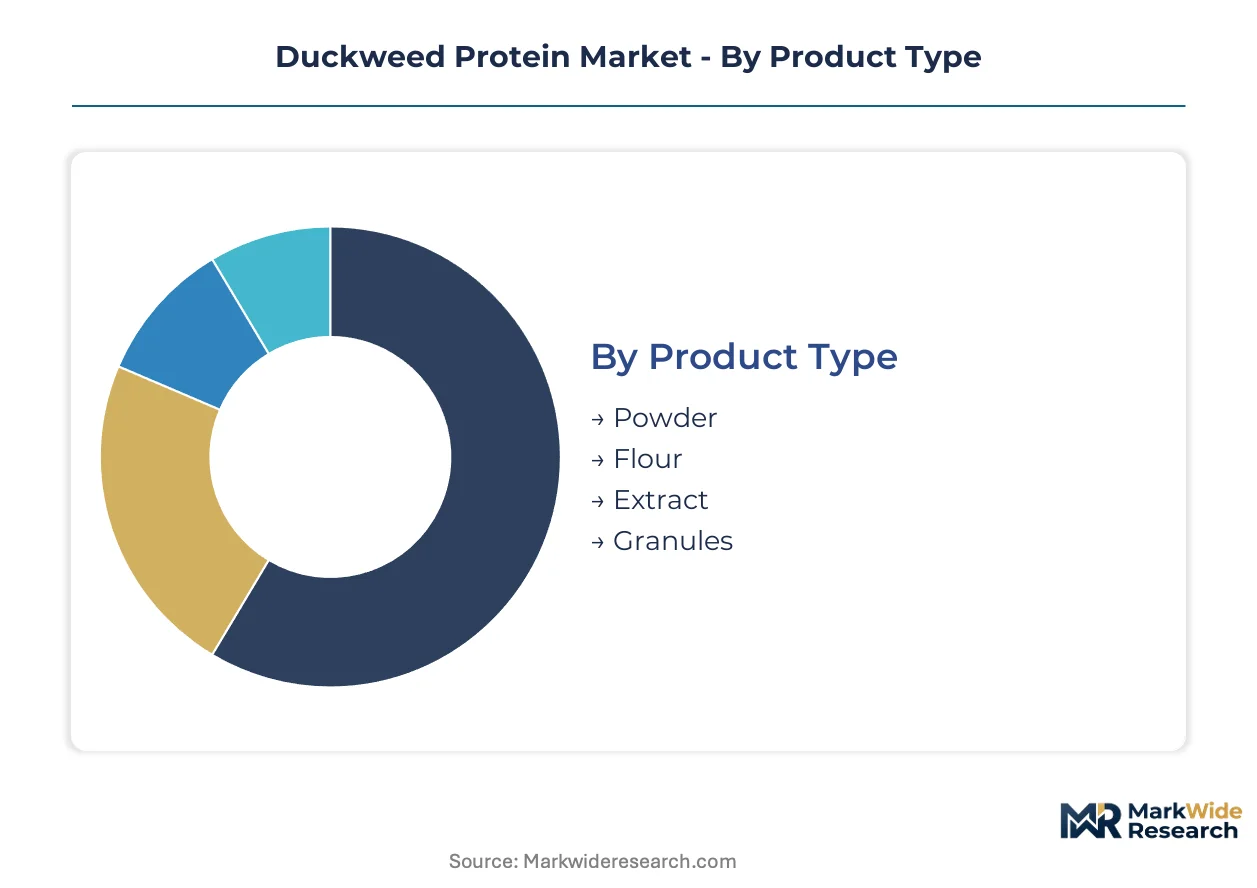
Segmentation in duckweed protein reveals how processing intensity and regulatory pathways split value capture across the value chain. Product format determines shelf stability and formulation compatibility, while end-use application governs margin structure and certification requirements.
Product Type:
Powder formats turn inventory fastest due to standardized specifications and bulk purchasing patterns, whereas extracts require longer validation cycles with nutraceutical formulators.
- Powder:Spray-dried or freeze-dried particulate with 35-45% protein concentration and 12-18 month shelf stability. Dutch biorefinery clusters supply North American plant-based meat manufacturers seeking soy-free binding agents under FDA GRAS notifications.
- Flour:Coarsely milled whole biomass retaining fiber and lipid fractions for bakery fortification. German millers integrate lemna flour into clean-label bread formulations, though EFSA Novel Food dossiers delay commercial rollout.
- Extract:Protein isolates achieve 60-70% purity through aqueous or enzymatic fractionation. Extended PDCAAS certification timelines constrain near-term volume scaling.
- Granules:Agglomerated particles for feed pelleting compatibility. Aquafeed compounders in Vietnam and Bangladesh source granules for tilapia and pangasius diets.
Powder dominates installed base. Extract is where expansion concentrates.
End User:
Cost tier stratification separates commodity feed buyers from premium-positioned nutraceutical and cosmetic formulators willing to absorb higher per-kilogram pricing.
- Food Industry:Plant-based meat analogues, dairy alternatives, and sports nutrition products. Netherlands-based formulators leverage lemna protein for EU-compliant clean-label positioning against pea and soy isolates.
- Feed Industry:Poultry, swine, and aquaculture compound feeds. Vietnamese integrators trial duckweed meal as fishmeal partial replacement in shrimp diets.
- Nutraceuticals:Protein supplements, meal replacements, and clinical nutrition. EFSA health claim substantiation requirements extend product development cycles.
- Cosmetics:Bioactive peptides for skincare formulations. Korean and French cosmetic houses evaluate lemna-derived antioxidants for anti-aging product lines.
Feed Industry commands current volume. Nutraceuticals is climbing the fastest.
Distribution Channel:
Supply concentration tilts procurement patterns toward direct relationships, compressing traditional wholesale tiers for large-scale industrial buyers.
- Online Retail:Direct-to-consumer protein supplements and specialty ingredients. Amazon and specialized platforms serve hobbyist aquaculturists and small-scale food entrepreneurs.
- Supermarkets:Mass-market placement remains limited pending broader consumer recognition and retail slotting fee negotiations.
- Health Stores:Natural products retailers stock duckweed-based supplements in California, Oregon, and Colorado markets with established plant-forward consumer bases.
- Direct Sales:Multi-year offtake contracts between cultivators and food manufacturers bypass commodity distributors. Plant-based meat formulators in California and Illinois anchor procurement through direct supply agreements.
Direct Sales anchors industrial procurement. Online Retail is gaining share fastest among emerging applications.
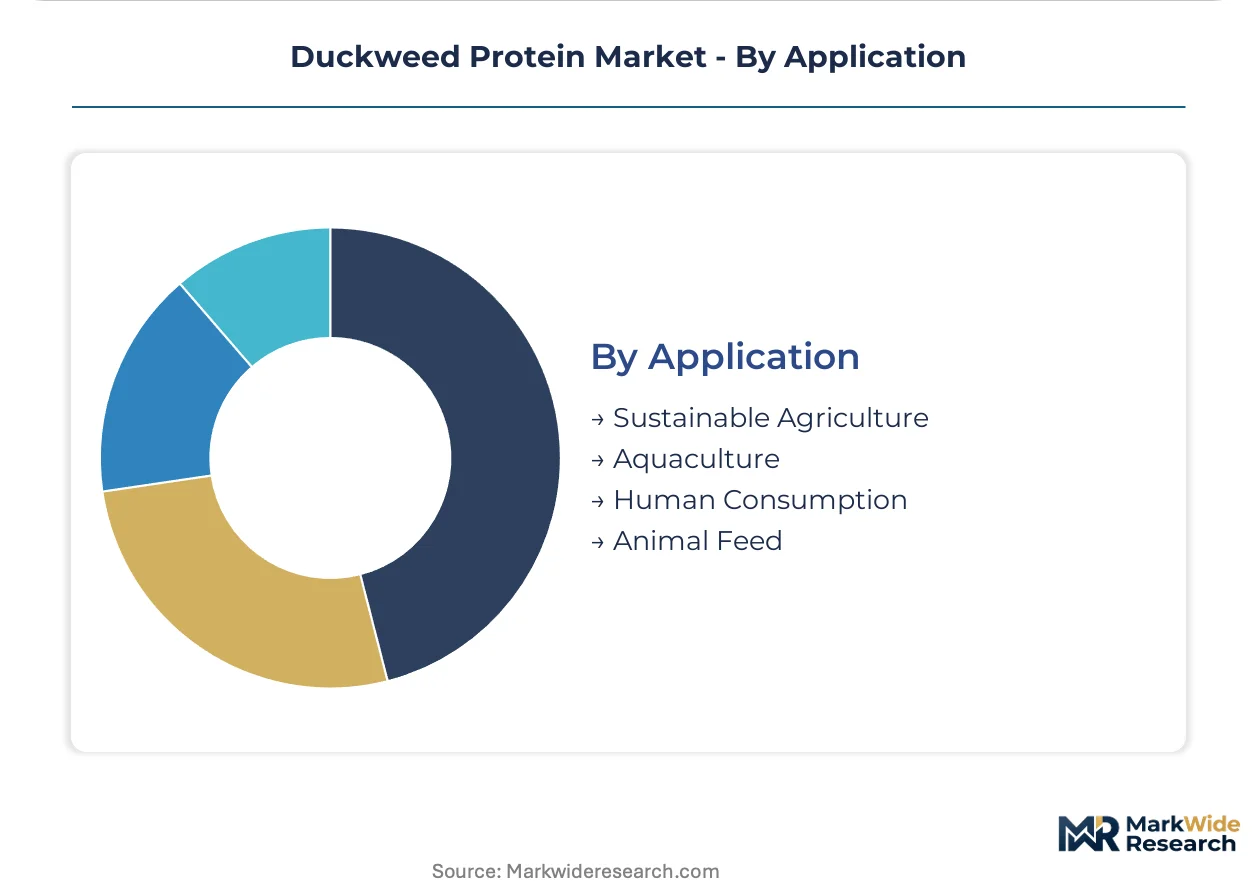
Application:
Volume maturity separates established feed uses from emerging human consumption platforms requiring novel food safety dossiers.
- Sustainable Agriculture:Biofertilizer and soil amendment applications utilizing residual biomass after protein extraction. USDA BioPreferred certification creates federal procurement pull for certified derivatives.
- Aquaculture:Freshwater species diets incorporating whole or processed lemna biomass. Vietnamese and Indonesian shrimp farms represent concentrated demand nodes.
- Human Consumption:Food fortification, meat analogues, and nutritional beverages. EFSA Novel Food harmonization across Germany, France, and the Netherlands accelerates cross-border ingredient trade.
- Animal Feed:Conventional livestock rations for poultry and swine. Lower protein digestibility scores versus soybean meal constrain premium pricing power.
Animal Feed dominates installed base. Human Consumption is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands commands 18-20% price premiums over Vietnamese feed-grade material, reflecting regulatory certification value and biorefinery density. German buyers absorb mid-tier pricing for EFSA-compliant isolates. United States formulators source through direct contracts that bypass distributor markups entirely.
Netherlands
Food-grade protein demand from plant-based meat formulators drives Dutch cultivation scaling. EFSA Novel Food harmonization with Germany and France accelerates cross-border approvals. The Randstad biorefinery cluster integrates photobioreactor cultivation with membrane filtration processing for North American export volumes.
Germany
Clean-label bakery fortification and sports nutrition applications absorb premium-priced lemna flour and isolates. BfR (Federal Institute for Risk Assessment) consults EFSA safety assessments for national Novel Food implementation. North Rhine-Westphalia milling operations trial lemna integration pending full EFSA authorization.
United States
California and Illinois plant-based meat manufacturers anchor procurement through multi-year offtake agreements. FDA GRAS notification pathways govern human food ingredient entry, with notification timelines varying by submission quality. Pacific Northwest controlled-environment agriculture deployments sustain year-round biomass output for nutraceutical extractors.
Vietnam
Aquaculture feed compounders source granulated duckweed meal for tilapia and pangasius diets at commodity price points. The Ministry of Agriculture and Rural Development oversees feed safety standards without Novel Food-equivalent human food pathways. Mekong Delta open-pond cultivation clusters supply regional aquafeed integrators at scale.
France
Cosmetic bioactive peptide applications from lemna-derived antioxidants attract Korean and domestic skincare formulators. ANSM (National Agency for Food, Environmental and Occupational Health Safety) coordinates with EFSA on Novel Food dossier reviews. Provence-Alpes-Côte d'Azur biotech incubators evaluate lemna strain optimization for high-value extract production.
Duckweed Protein Market Competitive Landscape
Biorefinery-scale cultivators and controlled-environment specialists split the market between export-oriented volume production and climate-resilient supply security. The vendor base concentrates around Dutch agrotech infrastructure and North American direct-sales platforms. Three archetypes dominate: integrated cultivation-processor platforms, technology-licensing specialists, and regional feed-grade suppliers. Competitive moves center on multi-year offtake contract anchoring and backward integration into proprietary strain development.
Within the integrated platform tier, Plantible Foods and Hinoman, Ltd. exemplify divergent scale strategies. Plantible Foods anchors supply security through proprietary lemna cultivation systems for large-scale North American buyers. Hinoman, Ltd. occupies a position emphasizing controlled-environment agriculture for year-round yield consistency. Parabel USA Inc. represents the regional feed-grade supply archetype serving aquaculture markets.
| Leading Market Players |
|---|
| Barentz Bio Healthife |
| Lempro Inc. |
| Plantible Foods |
| GreenOnyx Ltd. |
| Nutraceutical International Corporation |
| Hinoman, Ltd. |
| Seta Organics |
| Algama |
| Parabel USA Inc. |
| Others |
Supply & Pricing Matrix
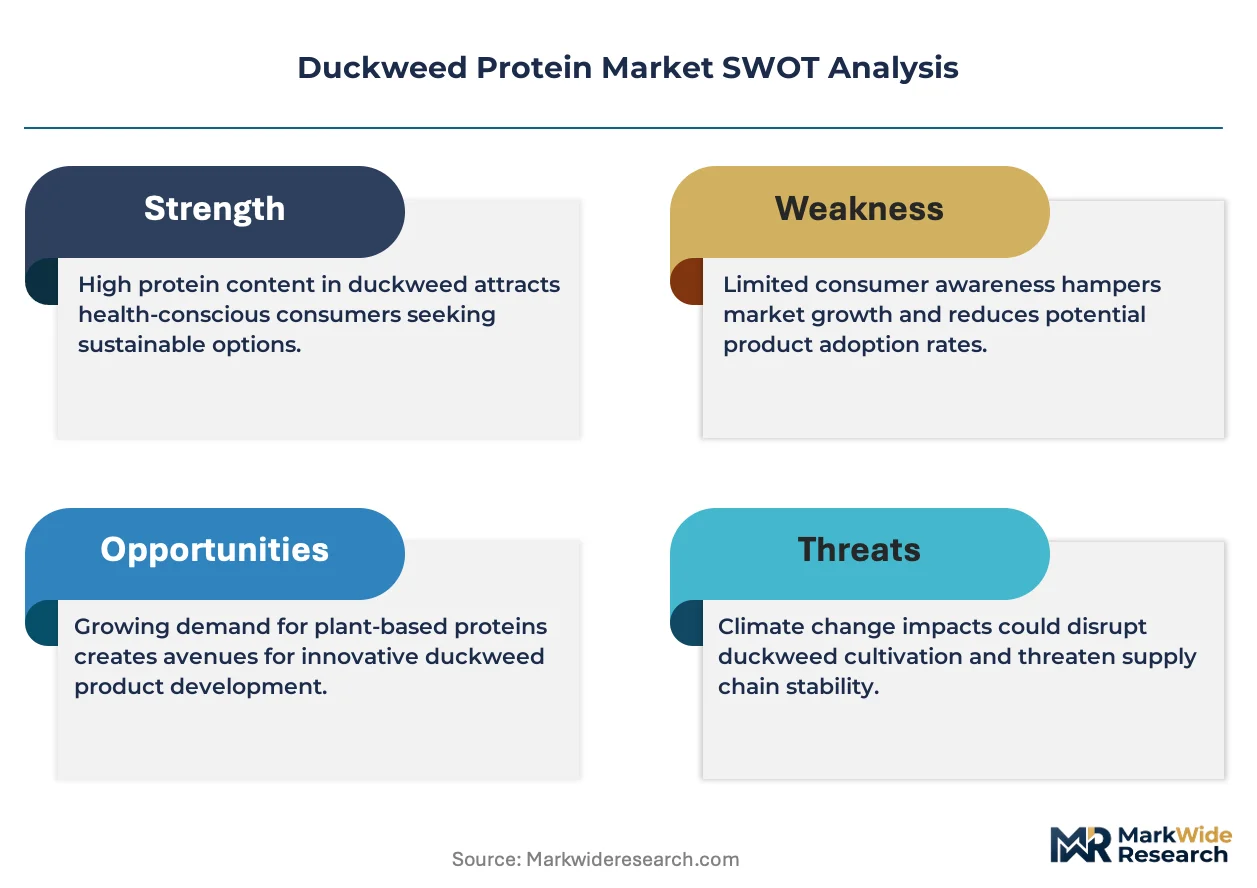
Regulatory chokepoint exposure at EFSA Novel Food approval gates determines both the premium spread between EU-certified and feed-grade material and the geographic clustering of cultivation assets around Dutch biorefinery infrastructure. Buyers absorbing these certification premiums secure supply priority, while price-sensitive feed compounders concentrate procurement in Vietnam and Bangladesh where regulatory pathways remain undeveloped.
Pricing Analysis
Configured-to-order pricing for EFSA-compliant isolates commands substantial premiums over standard feed-grade powder, with certification tier and volume scale as the primary differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade extracts from food-grade isolates and commodity feed meal. Cost compression in the standard tier is intensifying because Vietnamese open-pond operators are expanding biomass output without comparable quality certification investments. Feed industry buyers exhibit highest price sensitivity, while nutraceutical formulators absorbing premium positioning show least elasticity.
Supply Chain Analysis
Upstream feedstock cultivation draws from proprietary lemna strain stocks, synthetic nutrient media, and controlled-environment photobioreactor infrastructure concentrated in the Netherlands, United States, and Vietnam. Raw material dependencies center on nitrogen-phosphorus nutrient formulations, artificial lighting energy inputs, and membrane filtration consumables. Single-source vulnerability runs through Dutch biorefinery clusters where 18-20% of food-grade export capacity concentrates. Distribution runs through multi-year offtake contracts that displace traditional ingredient distributor tiers for North American plant-based meat manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. EFSA Novel Food approval timelines create switching costs that lock in early movers and fragment competitive access across national boundaries.
For Market Incumbents: Build certification moats by accelerating EFSA dossier submissions for secondary lemna strains before harmonized assessments tighten. Defensive consolidation should prioritize backward integration into proprietary photobioreactor engineering to neutralize controlled-environment agriculture specialists. Capacity addition in Germany's North Rhine-Westphalia region captures import demand from domestic milling operations awaiting full authorization.
For New Entrants and Emerging Players: Pursue white-space capture in German bakery fortification and French cosmetic peptide applications where EFSA Novel Food harmonization has compressed cross-border entry friction. The most penetrable segment sits in aquaculture feed where Vietnamese and Indonesian shrimp farms absorb commodity-grade material without human-food regulatory burdens. A go-to-market angle anchored in USDA BioPreferred certification unlocks federal procurement channels for residual biomass derivatives.
For Investors and Strategic Acquirers: EFSA Novel Food harmonization across Germany, France, and the Netherlands reshapes the acquisition landscape by consolidating regulatory compliance value in pan-European cultivation platforms. Long-term viability over the next decade hinges on digestibility certification completion and precision fermentation convergence capabilities. Acquisition target archetypes center on integrated cultivation-processor platforms with captive strain libraries. The signal to watch is PDCAAS validation study completion rates as an inflection indicator for human-food margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Expansion | Accelerates pan-European market access for lemna-derived isolates beyond Dutch biorefinery clusters. |
| Controlled-Environment Agriculture Scale-Up | Pacific Northwest deployments sustain year-round biomass yields independent of climate variability. |
| Precision Fermentation Convergence | Hybrid processing with microbial protein enhancement opens novel ingredient purity categories. |
| Direct Sales Contract Anchoring | Multi-year offtake agreements with California plant-based meat manufacturers displace distributor markups. |
| USDA BioPreferred Certification | Federal procurement preferences create institutional purchasing pull for certified residual biomass streams. |
Research Methodology
Desk research of EFSA Novel Food authorization databases, FDA GRAS notification filings, and Dutch customs export records preceded structured interviews with biorefinery operations managers, plant-based meat formulation scientists, aquafeed procurement directors, and nutraceutical regulatory affairs specialists. Secondary validation drew from USDA BioPreferred program certifications, EPA biofuel coproduct standards documentation, and SEC filings of publicly traded ingredient distributors. Bottom-up volume estimates from cultivation facility outputs were triangulated against top-down demand projections from end-use sector consumption patterns.
Assumptions held fixed across the modeling period include EFSA regulatory harmonization trajectory and natural gas pricing sensitivity for artificial lighting energy inputs. Variables modeled across segmentation dimensions encompassed product format tier, end-use application margin structure, and geographic regulatory cluster. CAGRs were derived from logistic adoption curves fitted to historical Novel Food approval timelines and projected capacity buildout schedules. Industry-specific forecast inputs incorporated PDCAAS certification completion rates and photobioreactor deployment capital expenditure cycles.
Sensitivities concentrate around EFSA safety assessment timeline extensions, nutrient media cost volatility, and digestibility scoring methodology revisions that could alter competitive positioning against pea and soy isolates. Cross-checking against USDA National Agricultural Statistics Service cultivation area surveys and EU import tariff schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biotechnology
South America Feed Phytogenics Market
Agricultural Biotechnology
Global Plant Hormones Market
Agricultural Biotechnology
Microarray in Agriculture Market
Agricultural Biotechnology
Global Poultry Vaccines Market
Agricultural Biotechnology
Stigmasterol-Rich Plant Sterols Market
Agricultural Biotechnology
Global Animal Biotechnology Market
Agricultural Biotechnology
Asia Pacific Feed Phytogenics Market
Agricultural Biotechnology
Transgenic Seeds Market
Agricultural Biotechnology
Africa Algae Protein Market
Agricultural Biotechnology
Plant-Based Vaccines Market
Agricultural Biotechnology
GMO Crops and Seeds Market
Agricultural Biotechnology
Agroscience Market
Agricultural Biotechnology
Biorationals Market
Agricultural Biotechnology
Europe Agriculture Biotech Market
Agricultural Biotechnology
Animal Brucella Antibody ELISA Kits Market
Agricultural Biotechnology
Brazil Veterinary Vaccines Market