
 Microarray in Agriculture Market | 2026-2036
Microarray in Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Microarray in Agriculture Market Insights
China is reconfiguring its agricultural biotechnology infrastructure with expanded microarray manufacturing capacity for domestic crop improvement programs. Illumina Inc. leverages its sequencing-to-array workflow integration to anchor supply relationships with major seed producers. Thermo Fisher Scientific Inc. sustains broad portfolio coverage across fluorescence detection and laser scanning platforms. Agilent Technologies Inc. specializes in high-density DNA microarray formats for complex trait mapping in cereals.
Agricultural microarrays are solid-substrate analytical devices bearing ordered arrays of nucleic acid probes, typically printed at densities exceeding 10,000 features per square centimeter, designed to simultaneously measure gene expression or genotype thousands of loci in plant and livestock samples. DNA microarrays dominate current revenue contribution due to established protocols for single nucleotide polymorphism discovery in major crops, while protein microarrays represent a faster-growing segment as researchers pursue direct phenotypic protein profiling for stress response validation. Fluorescence detection technology leads instrument attachment rates because of its compatibility with existing laboratory workflows, though surface plasmon resonance configurations are gaining traction where label-free kinetic analysis is required.
The USDA regulates agricultural biotechnology products under coordinated frameworks with FDA and EPA oversight, creating compliance pathways that shape microarray validation requirements for commercial seed release. China's NMPA and Ministry of Agriculture and Rural Affairs enforce biosafety certification for genetically modified crops, directly influencing microarray-based molecular characterization standards in that market. ISO 17025 accreditation requirements for testing laboratories further constrain instrument selection and data reporting protocols. Stakeholders must monitor evolving equivalence agreements between national biosafety regimes to anticipate where cross-border seed trade will demand harmonized molecular verification methods.
Market Dynamics
Genomic selection protocols are compressing breeding cycles from multiple seasons to single-generation decisions, forcing seed producers to embed molecular verification into every stage of commercial variety development rather than treating it as a terminal quality checkpoint.
Growth Catalysts
- EU Green Deal agricultural targets:The European Commission's Farm to Fork strategy mandates 25% organic farming coverage and 50% pesticide reduction, accelerating marker-assisted breeding programs that rely on high-throughput genotyping infrastructure.
- CRISPR-edited crop commercialization:Regulatory clarity on gene-edited varieties in multiple jurisdictions is expanding the addressable sample volume for molecular characterization platforms.
- Livestock genomic selection:Dairy and beef operations in North America are deploying dense SNP panels for predictive breeding value calculations, creating parallel demand streams beyond row crops.
Market Restraints
- Fluorophore supply concentration:Specialty dye chemistries for fluorescence detection remain concentrated among German and Japanese chemical suppliers, exposing instrument manufacturers to input cost volatility and allocation constraints.
- Sequencing cost compression:Next-generation sequencing workflows are achieving per-sample economics below array-based genotyping in certain throughput bands, creating substitution pressure at the research-use end of the market.
- USDA-APHIS permitting timelines:Coordinated framework review periods for biotechnology-derived traits extend molecular validation requirements across multiple regulatory submissions, stretching working capital cycles for seed developers.
Strategic Opportunities
- India's PLI scheme for biotechnology:Production-linked incentive structures for precision breeding infrastructure are attracting microarray platform assembly capacity to serve South Asian crop improvement programs.
- Protein microarray convergence:Integration of antibody-based protein profiling with metabolite detection arrays is opening direct phenotypic validation workflows for abiotic stress response in cereals.
- Digital marketplace distribution:Cloud-connected instrument platforms with consumption-based reagent provisioning are displacing traditional capital-sale models in mid-tier agricultural research stations.
Industry Challenges
- Bioinformatics talent scarcity:Agricultural research institutions face acute shortages of computational biologists capable of interpreting high-density array outputs for quantitative trait locus mapping.
- ISO 17025 accreditation timelines:Testing laboratories serving commercial seed release require 12-18 month validation cycles for molecular methods, compressing the effective commercial window for new platform introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microarray in Agriculture Market |
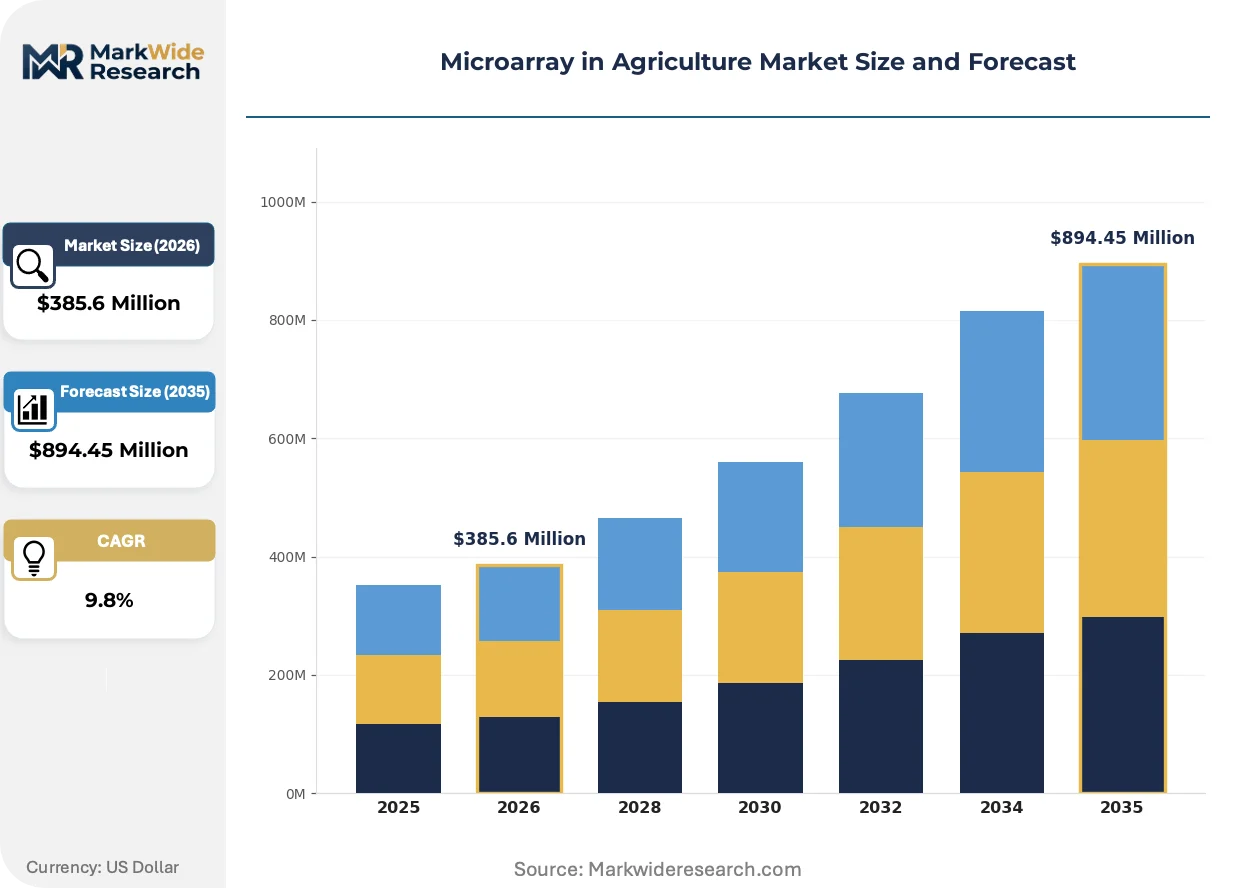
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $894.45 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Microarrays, RNA Microarrays, Protein Microarrays, Tissue Arrays Application: Genetic Mapping, Plant Breeding, Disease Resistance, Crop Quality Assessment End User: Agricultural Research Institutes, Seed Companies, Biotech Firms, Universities Technology: Non-Contact Printing, Fluorescence Detection, Surface Plasmon Resonance, Laser Scanning |
| Companies Covered | Illumina Inc., Thermo Fisher Scientific Inc., Agilent Technologies Inc., F. Hoffmann-La Roche AG, PerkinElmer Inc., Bio-Rad Laboratories Inc., Arrayit Corporation, Molecular Devices LLC, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microarray in Agriculture Market Trends and Innovations
Workflow integration between sample preparation, hybridization, and data interpretation is eliminating discrete process boundaries that previously segmented the agricultural genomics value chain.
Surface plasmon resonance microarrays are rendering obsolete fluorescence-dependent kinetic analysis in certain regulatory compliance workflows. Seed companies in jurisdictions with stringent biosafety documentation requirements are adopting label-free detection for real-time binding validation. The shift is compressing the timeline between molecular characterization and regulatory submission by eliminating secondary confirmatory assays.
China's NMPA has issued revised biosafety certification protocols for genetically modified crops that mandate specific molecular characterization density standards. The regulation is forcing international seed exporters to deploy identical microarray platforms in Chinese regulatory submissions as used in their home-country validation workflows. Agricultural biotechnology firms are responding by standardizing on high-density formats across all geographic operations.
Consolidated procurement of genotyping services by multinational seed producers is displacing distributed instrument ownership among regional breeding stations. Large-scale breeding programs in the United States and Brazil are contracting directly with platform operators for seasonal sample volume commitments rather than maintaining captive laboratory infrastructure. The model shift is most visible in maize and soybean breeding pipelines where annual sample volumes exceed 100,000 units.
Microarray in Agriculture Market Segmentation
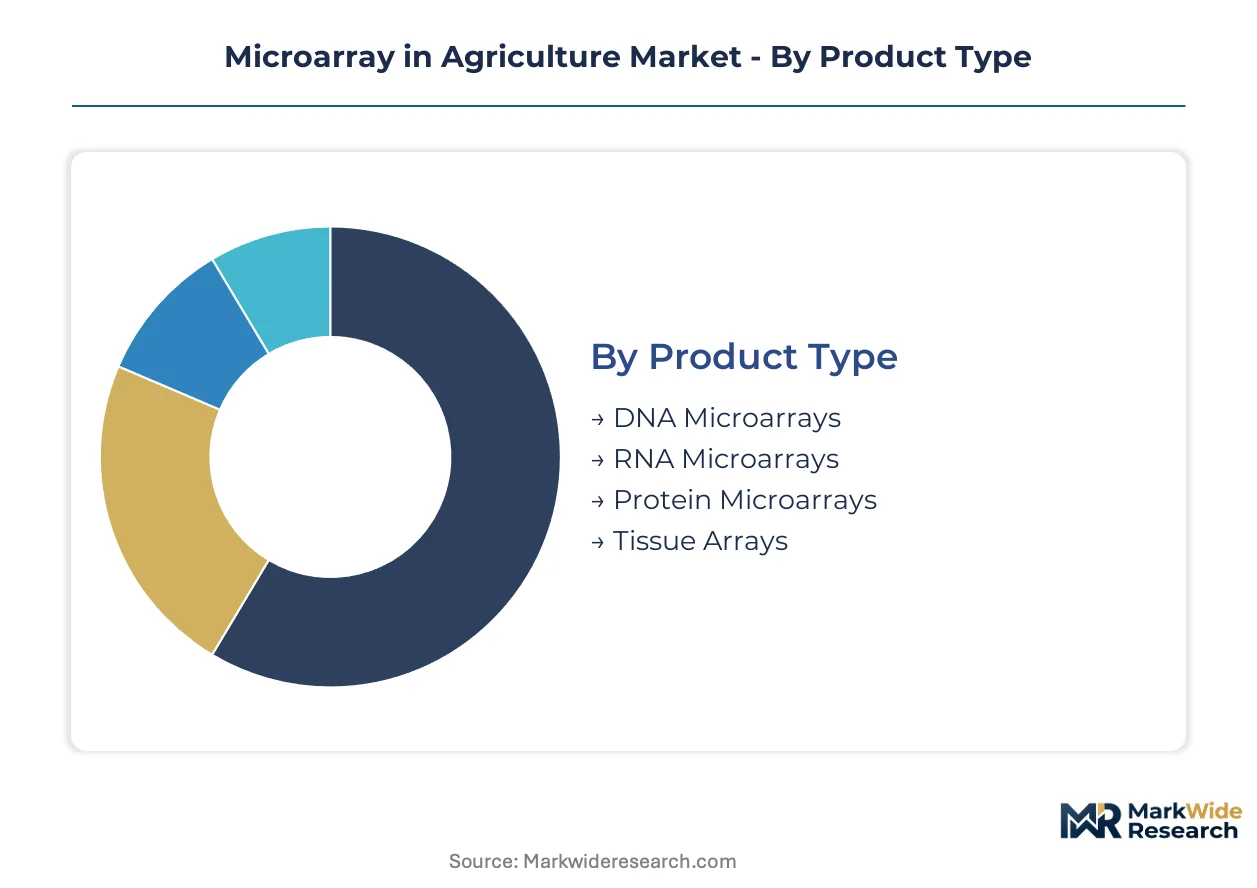
Microarray segmentation in agriculture reflects divergent technical requirements across molecular characterization workflows. Breeding programs select platforms based on throughput economics, regulatory documentation needs, and integration with existing laboratory infrastructure.
Product Type:
Use-case spectrum spans from single-nucleotide polymorphism discovery in staple crops to direct protein-level phenotyping for abiotic stress validation.
- DNA Microarrays:Solid-substrate platforms bearing ordered nucleic acid probe arrays at densities exceeding 10,000 features per square centimeter, optimized for high-throughput genotyping. Seed companies in the United States deploy these for marker-assisted selection in maize and soybean breeding pipelines, driven by compressed breeding cycles demanding single-generation molecular decisions.
- Protein Microarrays:Antibody-based analytical substrates enabling simultaneous measurement of thousands of protein targets in plant tissue extracts. Agricultural research institutes in Germany are adopting these for direct phenotypic validation of drought response in cereals, accelerating regulatory submission timelines by eliminating secondary confirmatory assays.
- RNA Microarrays:Transcriptome profiling platforms measuring gene expression dynamics across developmental stages or environmental conditions.
- Tissue Arrays:Paraffin-embedded specimen collections enabling spatial gene expression analysis in plant pathology research.
Established volume favors DNA Microarrays; emerging adoption favors Protein Microarrays.
Application:
Cost tier differentiation separates high-volume screening applications from specialized regulatory documentation workflows.
- Plant Breeding:Genomic selection protocols integrating dense marker panels with predictive breeding value calculations. Multinational seed producers in Brazil are contracting directly with platform operators for seasonal sample volumes exceeding 100,000 units, displacing distributed instrument ownership among regional stations.
- Disease Resistance:Pathogen-specific molecular characterization for commercial variety release. China's NMPA biosafety certification mandates specific molecular density standards, forcing exporters to deploy identical platforms in Chinese submissions as in home-country validations.
- Genetic Mapping:Quantitative trait locus identification for complex agronomic characteristics.
- Crop Quality Assessment:Metabolite and protein profiling for nutritional and processing trait verification.
Commercial breeding drives Plant Breeding volumes; regulatory complexity elevates Disease Resistance platform specifications.
End User:
Customer type concentration reflects procurement consolidation toward centralized genotyping service contracts.
- Seed Companies:Commercial breeding operations requiring ISO 17025-accredited molecular validation for regulatory submission. Large-scale programs maintain direct platform operator relationships rather than captive laboratory infrastructure, compressing working capital cycles.
- Agricultural Research Institutes:Public-sector crop improvement programs with biosafety documentation obligations. India's PLI scheme for biotechnology infrastructure is attracting microarray platform assembly capacity to serve South Asian research networks.
- Biotech Firms:Gene-edited crop developers navigating coordinated framework review timelines.
- Universities:Academic research units pursuing fundamental trait discovery with lower throughput requirements.
Procurement consolidation favors Seed Companies; capability building favors Agricultural Research Institutes.
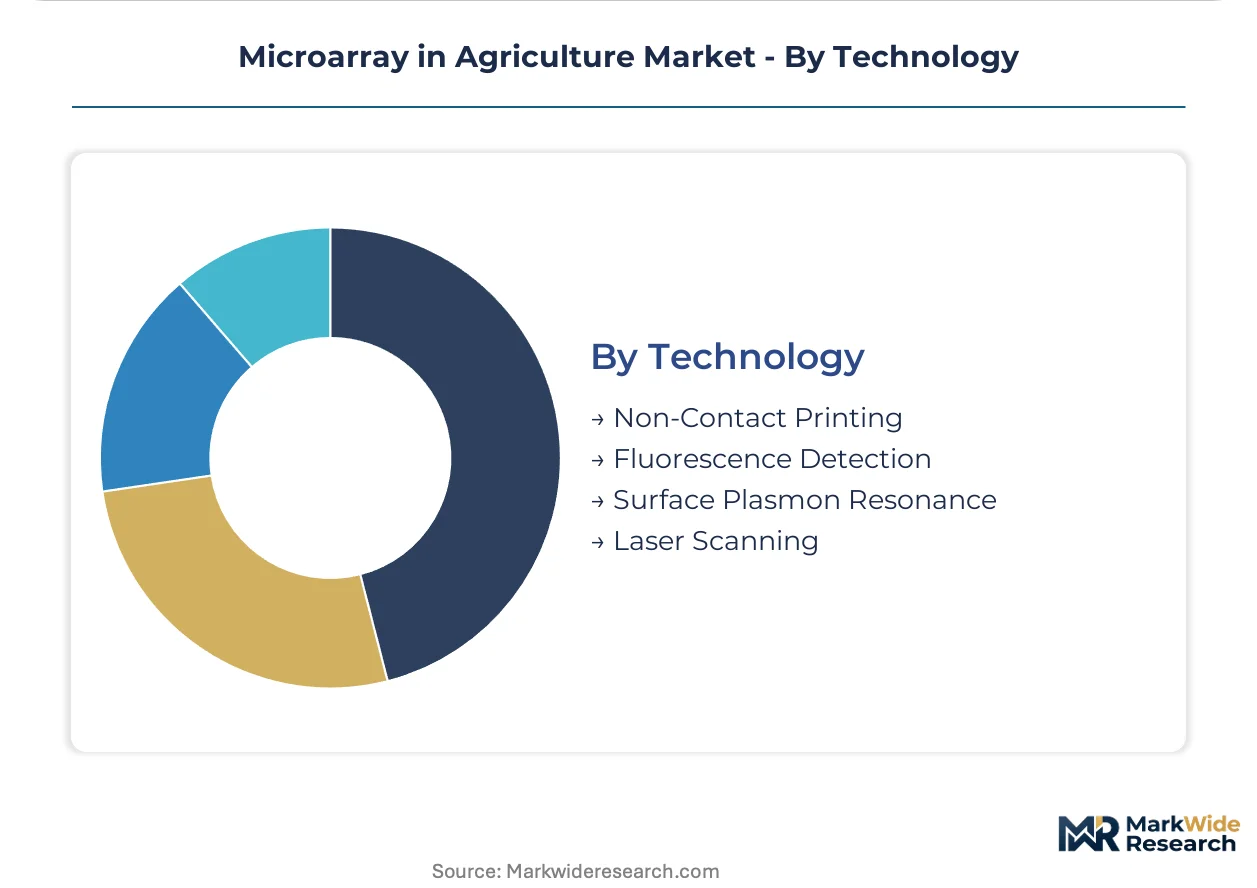
Technology:
Margin structure separates established fluorescence workflows from premium label-free configurations.
- Fluorescence Detection:Mature analytical platforms utilizing specialty dye chemistries for signal generation. Attachment rates remain highest due to compatibility with existing laboratory workflows, though fluorophore supply concentration among German and Japanese chemical suppliers exposes manufacturers to input cost volatility.
- Surface Plasmon Resonance:Label-free kinetic analysis configurations enabling real-time binding validation without secondary assays. Seed companies in jurisdictions with stringent biosafety requirements are adopting these for regulatory submission compression.
- Laser Scanning:High-resolution imaging platforms for dense feature array readout.
- Non-Contact Printing:Piezoelectric or inkjet probe deposition enabling rapid array customization.
Workflow compatibility sustains Fluorescence Detection dominance; regulatory efficiency drives Surface Plasmon Resonance expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Microarray manufacturing capacity clusters in the United States, China, and Germany, with seed company procurement consolidating toward direct platform operator relationships rather than distributed instrument ownership. The EU Green Deal and China's revised biosafety protocols are accelerating technology deployment across distinct regulatory environments.
United States
USDA-APHIS coordinated framework review timelines extend molecular validation requirements across multiple regulatory submissions for biotechnology-derived traits. The Farm to Fork strategy alignment pressures seed companies to embed marker-assisted selection into compressed breeding cycles. Multinational breeding programs in Iowa and Illinois contract directly with platform operators for seasonal sample volumes exceeding 100,000 units.
China
NMPA revised biosafety certification protocols mandate specific molecular characterization density standards for genetically modified crop submissions. The Ministry of Agriculture and Rural Affairs enforces these standards through domestic crop improvement programs. Manufacturing capacity expansion in Yangtze River Delta clusters serves both domestic demand and regional seed export verification requirements.
Germany
Specialty fluorophore chemistries for fluorescence detection concentrate among German chemical suppliers, exposing instrument manufacturers to input cost volatility. EFSA regulatory documentation requirements drive adoption of label-free surface plasmon resonance configurations for real-time binding validation. Agricultural research institutes in Bavaria deploy protein microarrays for direct phenotypic validation of drought response in cereals.
Brazil
Large-scale maize and soybean breeding programs contract directly with platform operators for seasonal genotyping commitments rather than maintaining captive laboratory infrastructure. ANVISA biosafety documentation requirements for commercial variety release shape platform selection criteria. São Paulo-based breeding stations consolidate procurement toward centralized service contracts with throughput economics below distributed ownership models.
India
PLI scheme production-linked incentive structures for precision breeding infrastructure attract microarray platform assembly capacity to serve South Asian crop improvement programs. CDSCO and the Ministry of Agriculture enforce molecular characterization standards for genetically modified crop approvals. Agricultural research networks in Maharashtra and Karnataka build ISO 17025-accredited validation capacity for commercial seed release.
Microarray in Agriculture Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in probe chemistries and detection modules. The vendor base separates into consolidated instrument manufacturers with sequencing-to-array workflow integration and fragmented reagent suppliers facing fluorophore allocation constraints. Two strategic archetypes dominate: vertically integrated life science conglomerates spanning fluorescence detection and laser scanning platforms, and specialized high-density format developers for complex trait mapping. Competitive moves concentrate on strategic partnerships for workflow integration and capacity expansion in emerging regulatory jurisdictions.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. and Merck KGaA exemplify the integrated platform archetype with broad portfolio coverage across detection technologies. Agilent Technologies Inc. occupies a specialized position in high-density DNA microarray formats. Illumina Inc. anchors the sequencing-to-array workflow integration segment, representing the convergence point between next-generation sequencing and array-based genotyping infrastructure.
| Leading Market Players |
|---|
| Illumina Inc. |
| Thermo Fisher Scientific Inc. |
| Agilent Technologies Inc. |
| F. Hoffmann-La Roche AG |
| PerkinElmer Inc. |
| Bio-Rad Laboratories Inc. |
| Arrayit Corporation |
| Molecular Devices LLC |
| Merck KGaA |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta manufacturing clusters anchor global microarray substrate production, translating concentrated fluorophore supply into asymmetric pricing power for German and Japanese chemical suppliers serving instrument manufacturers.
Pricing Analysis
ISO 17025 accreditation dictates the pricing tier structure across agricultural microarray platforms. Three-tier pricing structure across premium, standard, and economy levels separates regulatory-grade systems with full validation documentation from research-use configurations. Price differentiation centers on certification completeness and after-sales service bundling. Cost compression in economy-tier fluorescence detection is intensifying because specialty dye allocation constraints from concentrated chemical suppliers. Seed companies exhibit highest price sensitivity, while biotech firms navigating USDA-APHIS timelines absorb premium pricing for accelerated validation workflows.
Supply Chain Analysis
Specialty fluorophore chemistries draw from German and Japanese chemical suppliers, while substrate manufacturing concentrates in China and the United States. Probe synthesis relies on phosphoramidite chemistries, glass slide substrates, and precision printing equipment. Single-source vulnerability in fluorophore supply exposes instrument manufacturers to allocation constraints during peak agricultural breeding seasons. Distribution runs through direct platform operator contracts with multinational seed producers, displacing traditional capital-sale channels among regional breeding stations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as procurement consolidation among multinational seed producers creates service gaps at mid-tier agricultural research stations requiring ISO 17025-accredited validation without captive infrastructure investment.
For Market Incumbents: Insulate fluorescence detection platform margins through backward integration into probe chemistries or captive supply arrangements with Yangtze River Delta substrate manufacturers. Threat from next-generation sequencing cost compression below array-based genotyping in mid-throughput bands demands workflow integration investments that embed microarrays into multi-modal molecular characterization pipelines. For New Entrants and Emerging Players: Establish a beachhead in protein microarray configurations for direct phenotypic validation of abiotic stress response in cereals, where regulatory submission compression creates premium pricing tolerance. India's PLI scheme for biotechnology infrastructure offers lowest competitive density for platform assembly capacity serving South Asian crop improvement programs. Go-to-market angle: cloud-connected consumption-based reagent provisioning displaces capital-sale friction at mid-tier research stations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized high-density format developers with regulatory submission density standards locked into Chinese NMPA protocols. Long-term viability hinges on convergence between sequencing-to-array workflows and label-free detection configurations. Acquisition target archetype: surface plasmon resonance platform specialists with biosafety documentation workflows validated in multiple jurisdictions. Signal to watch: equivalence agreements between national biosafety regimes that harmonize molecular verification methods for cross-border seed trade.| Strategic Initiative | Industry Significance |
|---|---|
| Workflow Integration Investment | Sequencing-to-array convergence anchors supply relationships with major seed producers like Illumina. |
| Regulatory Certification Expansion | ISO 17025 accreditation opens commercial seed release validation contracts with multinational breeding programs. |
| Geographic Capacity Expansion | PLI scheme positioning in India captures South Asian crop improvement program procurement consolidation. |
| Label-Free Detection Development | Surface plasmon resonance configurations compress USDA-APHIS submission timelines for gene-edited varieties. |
| Cloud Platform Deployment | Consumption-based reagent provisioning displaces capital-sale models at mid-tier agricultural research stations. |
Research Methodology
Cross-validation between primary interviews with seed company molecular breeding directors, platform operator service managers, and regulatory affairs specialists anchors the qualitative findings against secondary validation from USDA-APHIS coordinated framework guidance documents, EFSA regulatory opinions, and China NMPA biosafety certification protocols. Bottom-up triangulation across instrument shipment data and top-down reconciliation against seed industry R&D expenditure patterns ensures dimensional consistency.
Calibration against historical adoption curves for genomic selection protocols and regulatory submission volume trends shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application workflow, end-user procurement consolidation stage, and detection technology configuration. CAGRs derive from slope analysis of technology substitution patterns and regulatory-driven platform standardization mandates. Industry-specific forecast inputs incorporate EU Green Deal organic farming coverage targets and CRISPR-edited crop commercialization clarity timelines.
Stress conditions across fluorophore supply allocation constraints, sequencing cost compression trajectories, and biosafety equivalence agreement negotiation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against seed industry capital expenditure disclosures and agricultural biotechnology patent filing trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biotechnology
South America Feed Phytogenics Market
Agricultural Biotechnology
Agricultural Biotechnology Market
Agricultural Biotechnology
Stigmasterol-Rich Plant Sterols Market
Agricultural Biotechnology
Duckweed Protein Market
Agricultural Biotechnology
Brazil Veterinary Vaccines Market
Agricultural Biotechnology
Ruminant Vaccines Market
Agricultural Biotechnology
Africa Algae Protein Market
Agricultural Biotechnology
Europe Plant Growth Regulators Market
Agricultural Biotechnology
Global Animal Biotechnology Market
Agricultural Biotechnology
Global Poultry Vaccines Market
Agricultural Biotechnology
Global Plant Hormones Market
Agricultural Biotechnology
Transgenic Seeds Market
Agricultural Biotechnology
Asia Pacific Feed Phytogenics Market
Agricultural Biotechnology
Europe Agriculture Biotech Market
Agricultural Biotechnology
Asia-Pacific Agriculture Biotech Market
Agricultural Biotechnology
Plant-Based Vaccines Market