
 South America Feed Phytogenics Market | 2026-2036
South America Feed Phytogenics Market Size, Share, and Industry Trends Forecast 2026-2036
South America Feed Phytogenics Market Analytics
The South America feed phytogenics market is repositioning around a widening split between premium essential oil formulations and commodity herbal powders. DSM-Firmenich leverages its integrated biotechnology platforms to dominate high-purity oleoresin production for Brazilian integrators. Cargill anchors its position through direct distribution networks across Argentina's Pampas feedlot region.
Feed phytogenics comprise bioactive plant-derived compounds including essential oils, oleoresins, and standardized herbal extracts used to modulate gut microbiota, enhance nutrient digestibility, and replace antibiotic growth promoters in livestock diets. Essential oils command the highest margin pool due to concentration requirements and encapsulation complexity, while poultry applications outpace ruminant segments as Brazilian broiler integrators accelerate antibiotic-free commitments. Liquid formulations lead volume share for automated feed mill integration, though powder variants gain traction among smaller Argentine swine operations lacking liquid handling infrastructure.
Brazil's MAPA enforces residue monitoring protocols that directly elevate demand for documented phytogenic alternatives, while ANVISA governs feed additive safety assessments that shape product registration timelines. Argentina's SENASA implements parallel import controls on unregistered botanical premixes, creating compliance barriers for non-local suppliers. Stakeholders must monitor evolving equivalency determinations between national regulators as cross-border formulation standardization remains unresolved.
Market Dynamics
The South America feed phytogenics market pivots on Brazil's MAPA residue enforcement, which is systematically displacing ionophore growth promoters across southern poultry integrators and forcing rapid reformulation of antibiotic-free feed programs.
Growth Catalysts
- MAPA residue protocols:Brazil's tightening veterinary drug monitoring creates documented demand for phytogenic alternatives with traceable supply chains.
- Poultry belt concentration:Integrators in Paraná and Santa Catarina accelerate phytogenic inclusion to meet export market antibiotic-free specifications.
- Encapsulation advances:Microencapsulation technologies protect essential oil bioactives through pelleting heat, improving feed mill integration rates.
Market Restraints
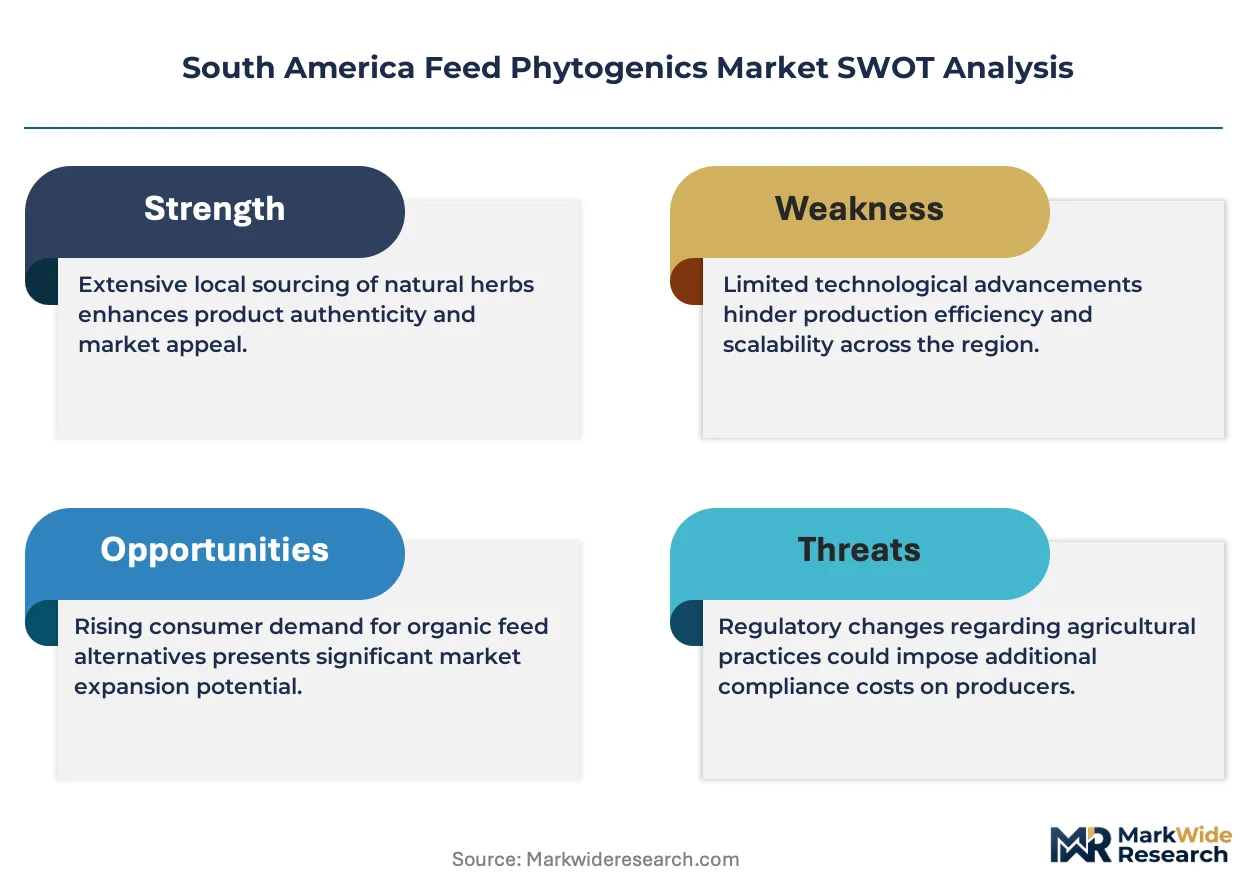
- Raw material volatility:Oregano and thyme oil prices swing with Mediterranean harvest cycles, compressing margin predictability for formulators.
- Registration bottlenecks:ANVISA's botanical safety assessments extend product approval timelines by 18-24 months versus synthetic alternatives.
- Technical standardization gaps:Inconsistent thymol and carvacrol concentration assays across Argentine and Brazilian laboratories create quality arbitration disputes.
Strategic Opportunities
- Argentine Pampas feedlots:Cattle finishing operations remain underpenetrated for phytogenic methane mitigation and liver abscess control.
- ANVISA equivalency pathways:Emerging mutual recognition frameworks with Chile and Uruguay could streamline cross-border formulation registrations.
- Precision delivery systems:Site-specific release coatings for rumen bypass are converging with essential oil matrices to unlock ruminant value pools.
Industry Challenges
- Phytochemistry expertise scarcity:Formulation chemists with combined plant secondary metabolite and animal nutrition training remain concentrated in São Paulo and Buenos Aires research clusters.
- Integration complexity:Retrofitting Argentine swine operations with liquid phytogenic dosing equipment conflicts with existing powder-based premix infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Feed Phytogenics Market |
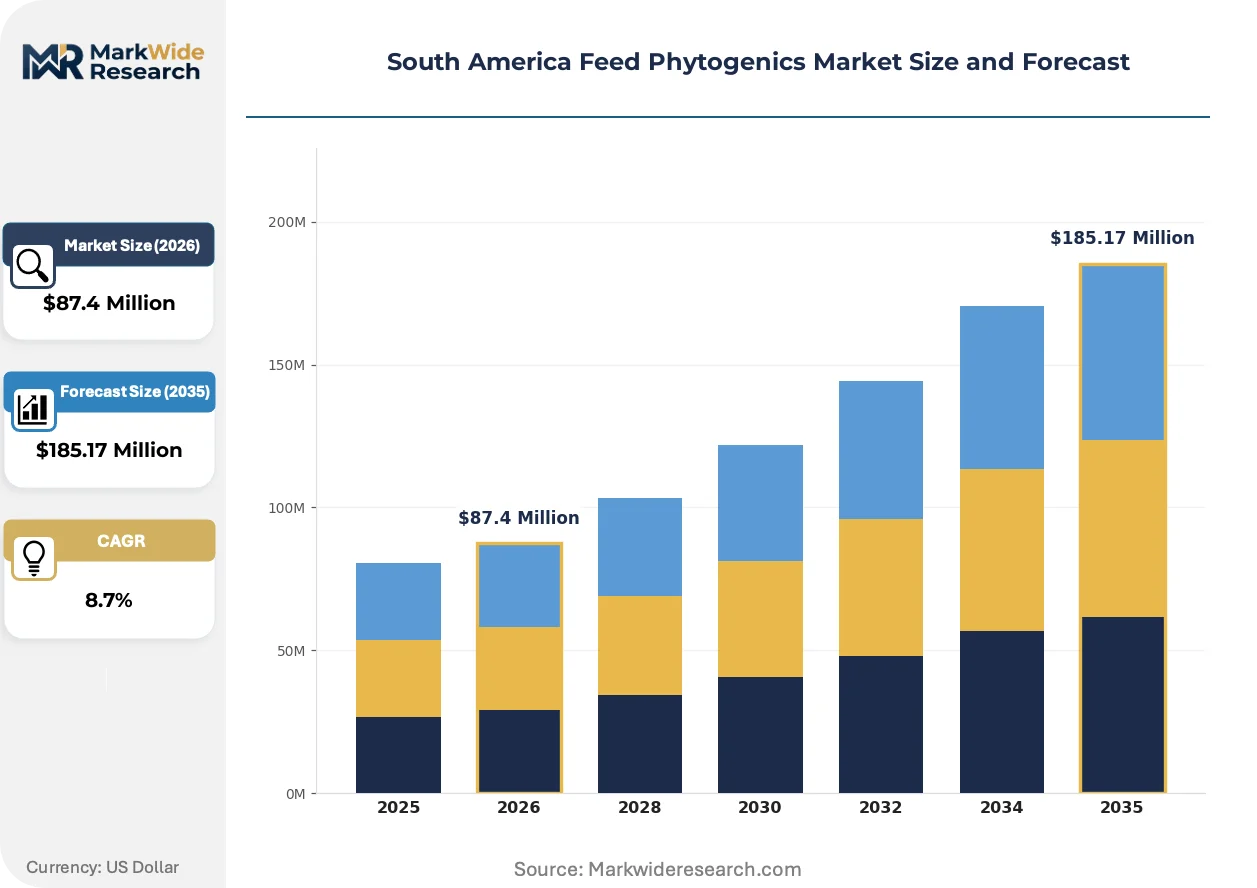
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $185.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Oleoresins, Extracts, Herbal Powders Application: Poultry, Ruminants, Swine, Aquaculture Form: Liquid, Powder, Granule, Tablet Distribution Channel: Online, Offline, Direct Sales, Distributors |
| Companies Covered | DSM-Firmenich, Cargill, Phytobiotics Futterzusatzstoffe GmbH, Adisseo, Kemin Industries, Delacon Biotechnik, EW Nutrition, Evonik Industries, Biomin Holding, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Feed Phytogenics Market Evolving Landscape
Encapsulation and precision delivery systems are compressing the performance gap between phytogenics and legacy antibiotic growth promoters, while regulatory enforcement hardens formulation documentation requirements across the continent.
Microencapsulation of essential oil matrices is automating the protection of heat-sensitive bioactives during feed pelleting at temperatures exceeding 85°C. Brazilian broiler integrators in the southern belt are adopting these systems at scale to maintain thymol and cinnamaldehyde potency through processing. This technology is automating quality consistency that previously required batch-specific dosage adjustments, reducing formulation waste and enabling single-species feed mill lines to handle multiple phytogenic inclusion rates without cross-contamination protocols.
ANVISA's 2023 botanical feed additive guidance established equivalence testing requirements that parallel EFSA's qualified presumption of safety framework. The regulation mandates full toxicological dossiers for novel plant extracts, elevating documentation costs for regional suppliers. Poultry premix manufacturers in São Paulo state are most affected, with several reformulating around GRAS-status essential oils to compress registration timelines and avoid novel substance safety studies.
Direct procurement contracts between Argentine feedlots and phytogenic suppliers are displacing traditional distributor intermediaries in the Pampas region. Large cattle finishing operations in Buenos Aires province now negotiate oleoresin supply agreements with quality-assured documentation for export beef traceability. This pattern is most visible across the Humid Pampas, where EU-bound beef exports require verifiable antibiotic-free feeding protocols and integrators seek supply chain transparency that distributors cannot provide.
South America Feed Phytogenics Market Segmentation
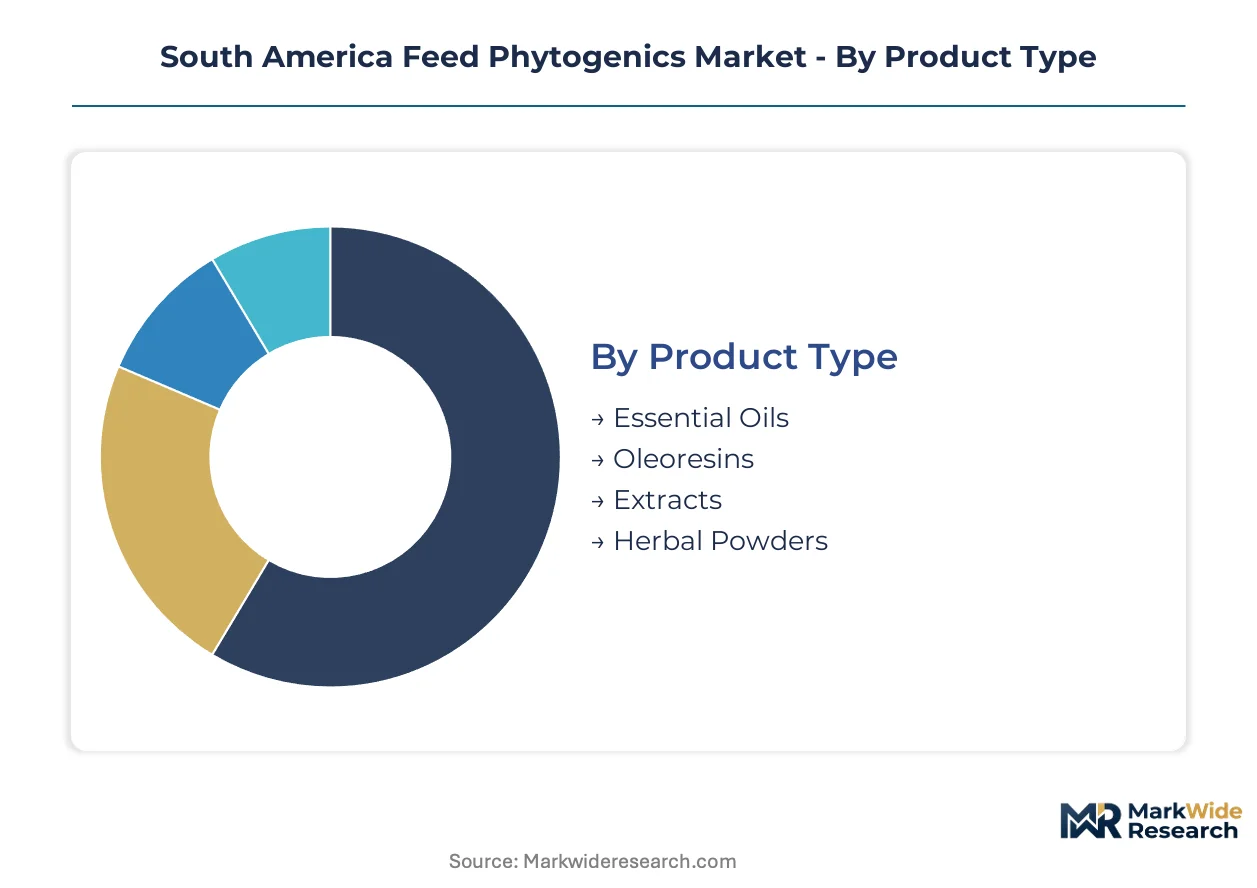
Segmentation in the South America feed phytogenics market maps directly to regulatory burden tiers, with ANVISA registration pathways varying sharply between standardized essential oils and novel botanical extracts. Understanding these divisions enables suppliers to allocate compliance resources efficiently across product portfolios.
Product Type:
Essential oils and oleoresins carry lighter ANVISA documentation loads due to established GRAS frameworks, while novel herbal extracts trigger full toxicological dossier requirements that extend approval timelines substantially.
- Essential Oils:Concentrated volatile compounds from oregano, thyme, and cinnamon requiring microencapsulation for heat stability. Brazilian poultry integrators in Paraná specify thymol-rich formulations to meet MAPA residue protocols for antibiotic-free export programs. ANVISA recognizes these as qualified presumption of safety substances, compressing registration to 8-12 months versus novel extracts.
- Oleoresins:Solvent-extracted resinous concentrates combining volatile and non-volatile bioactives. DSM-Firmenich dominates high-purity production for Brazilian integrators seeking standardized carvacrol content with batch-traceable documentation. These command premium positioning due to concentration consistency and lower inclusion rates in finished feed.
- Extracts:Standardized botanical preparations requiring full safety assessments under ANVISA's 2023 guidance. Regional suppliers face 18-24 month approval timelines.
- Herbal Powders:Ground dried plant material with variable active compound levels. Argentine swine operations favor these for cost-sensitive applications lacking liquid handling infrastructure.
Essential oils sit at the top of the volume ranking, with oleoresins climbing the fastest as Brazilian integrators prioritize concentration standardization.
Application:
Poultry applications concentrate regulatory attention due to MAPA's residue monitoring intensity in Brazil's southern belt, while ruminant segments face lighter enforcement but steeper technical barriers for rumen-protected delivery.
- Poultry:Broiler and layer operations driving phytogenic inclusion to satisfy EU and Japanese import specifications. Santa Catarina integrators deploy liquid essential oil systems at scale across automated feed mills. Heat-stable encapsulation formats dominate as pelleting temperatures exceed 85°C.
- Ruminants:Cattle finishing operations in Argentina's Humid Pampas represent underpenetrated demand for methane mitigation and liver abscess control. Direct procurement contracts between Buenos Aires feedlots and suppliers are displacing traditional distributors for export-traceable beef protocols.
- Swine:Argentine operations in Córdoba and Santa Fe provinces favor powder formulations compatible with existing premix infrastructure. SENASA import controls on unregistered botanicals create compliance barriers for non-local suppliers.
- Aquaculture:Emerging segment concentrated in southern Chile and Brazilian coastal regions. ANVISA has not established species-specific guidance, leaving registration pathways uncertain.
Poultry commands the dominant revenue share, with ruminants expanding most quickly as Argentine feedlots adopt phytogenic protocols for EU-bound beef exports.
Form:
Liquid formulations align with high-volume Brazilian feed mill automation, while powder variants serve smaller Argentine operations where capital retrofit costs block liquid system adoption.
- Liquid:Standard for large-scale Brazilian poultry integrators with automated dosing infrastructure. Microencapsulated essential oil suspensions protect bioactives through pelleting heat.
- Powder:Dominant in Argentine swine and smaller ruminant operations lacking liquid handling equipment. Herbal powders and spray-dried extracts comprise the bulk of volume.
- Granule:Intermediate format gaining traction for rumen bypass applications requiring site-specific release coatings.
- Tablet:Niche format for on-farm top-dressing in smallholder dairy operations, particularly in Uruguay and Paraguay.
Liquid leads volume share, with granule formats gaining share fastest as precision delivery technologies mature for ruminant applications.
Distribution Channel:
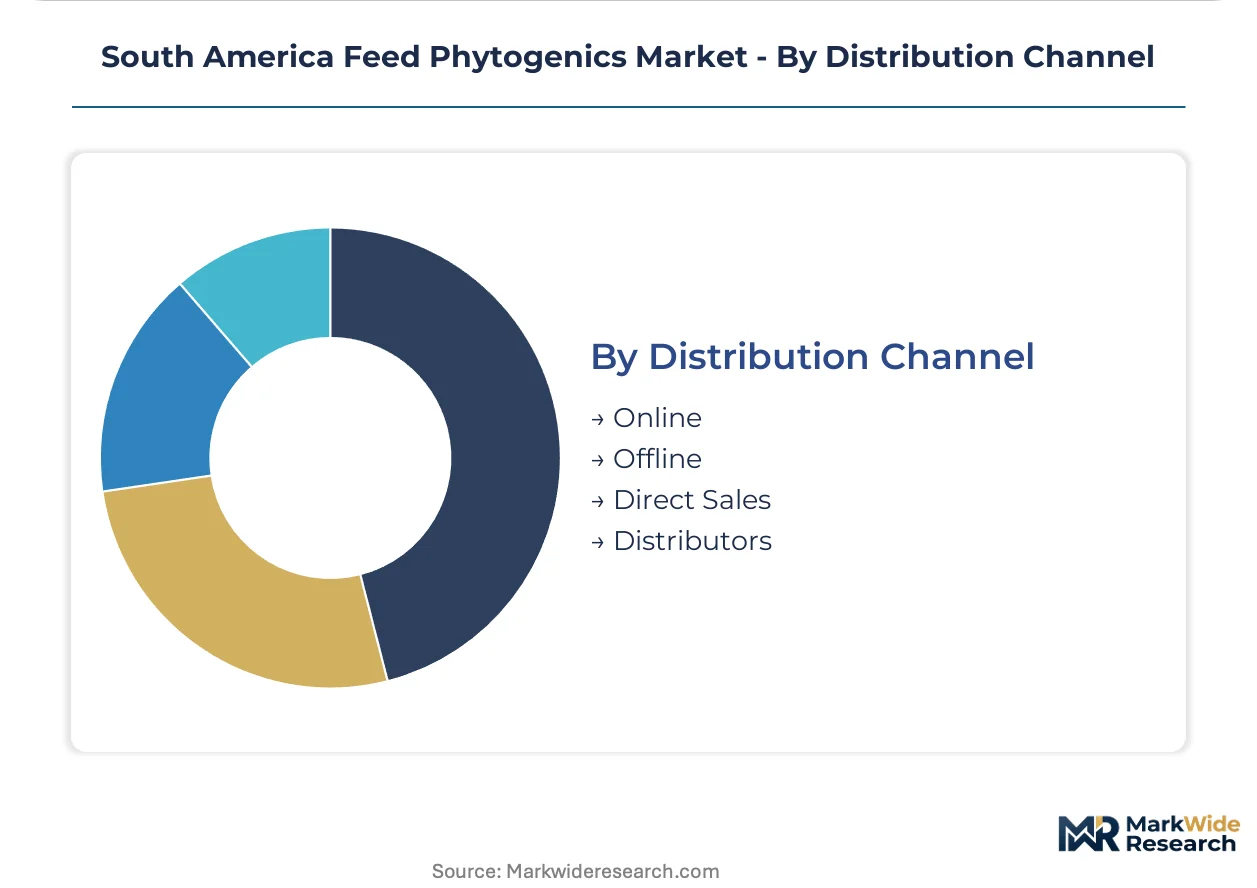
Channel selection reflects customer scale and documentation requirements, with large Argentine feedlots bypassing intermediaries to secure supply chain transparency for export traceability.
- Direct Sales:Large cattle finishing operations in Buenos Aires province negotiate oleoresin supply agreements with quality-assured documentation. This pattern is displacing traditional distributors across the Humid Pampas.
- Distributors:Remain critical for mid-sized Brazilian poultry operations and smaller Argentine swine farms requiring technical support and inventory management.
- Offline:Feed mill partnerships and veterinary supply networks dominate transaction volume, particularly in Brazil's southern poultry belt.
- Online:Emerging channel for standardized essential oil formulations among smaller operators seeking price transparency, though regulatory documentation requirements limit adoption.
Direct sales sit at the top of the value ranking, with this channel climbing the fastest as large integrators prioritize supply chain transparency over distributor convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil concentrates the highest phytogenic demand volume, while Argentina's Pampas feedlots are accelerating adoption for export-traceable beef protocols. Chile and Uruguay maintain smaller but technically advanced markets shaped by salmon aquaculture and dairy export standards. Paraguay represents emerging demand from integrated poultry operations serving Brazilian supply chains.
Brazil
Paraná and Santa Catarina poultry integrators deploy liquid essential oil systems at scale across automated feed mills. MAPA enforces residue monitoring protocols that systematically displace ionophore growth promoters. São Paulo state hosts the dominant concentration of formulation chemists and ANVISA-registered premix manufacturers.
Argentina
Buenos Aires province cattle finishing operations negotiate direct oleoresin procurement contracts for EU-bound beef traceability. SENASA implements parallel import controls on unregistered botanical premixes, creating compliance barriers for non-local suppliers. Córdoba and Santa Fe swine operations favor powder formulations compatible with existing premix infrastructure.
Chile
Southern coastal aquaculture clusters represent emerging phytogenic demand for species-specific gut health modulation. The national pharmaceutical regulator has not established aquaculture-specific guidance, leaving registration pathways uncertain. Salmon producers in Los Lagos region experiment with essential oil matrices for antibiotic-free farming protocols.
Uruguay
Smallholder dairy operations in the central region drive niche tablet-format demand for on-farm top-dressing applications. Export-oriented beef producers adopt phytogenic protocols to maintain access to premium EU and US markets. Montevideo serves as the technical services hub for cross-border formulation support into southern Brazil.
Paraguay
Integrated poultry operations in the Eastern Region expand capacity to serve Brazilian supply chain integration. SENAVE regulates feed additive imports with documentation requirements that favor established Brazilian suppliers. Ciudad del Este clusters distribute phytogenic premixes across the tri-border zone with Brazil and Argentina.
South America Feed Phytogenics Market Competitive Landscape
Top-tier vendors anchor integrated biotechnology platforms, while mid-tier specialists compete on regional registration expertise and distributor relationships. The market structure consolidates around essential oil standardization capabilities and ANVISA dossier preparation speed. Three archetypes dominate: multinational nutrition conglomerates with captive oleoresin production, European phytogenic specialists with established GRAS portfolios, and regional premix formulators with local regulatory navigation expertise. Competitive intensity concentrates on M&A activity targeting encapsulation technology assets and strategic partnerships between European suppliers and Brazilian distribution networks.
Within the multinational tier, DSM-Firmenich and Cargill exemplify divergent approaches to South American market development. DSM-Firmenich occupies a position emphasizing high-purity oleoresin production and integrated biotechnology platforms. Cargill anchors its presence through direct distribution network control across Argentina's Pampas feedlot region. Among European specialists, Phytobiotics Futterzusatzstoffe GmbH represents the archetype of GRAS-status portfolio concentration and compressed ANVISA registration timelines.
| Leading Market Players |
|---|
| DSM-Firmenich |
| Cargill |
| Phytobiotics Futterzusatzstoffe GmbH |
| Adisseo |
| Kemin Industries |
| Delacon Biotechnik |
| EW Nutrition |
| Evonik Industries |
| Biomin Holding |
| Others |
Value Network & Pricing Analysis
Large Brazilian poultry integrators in Paraná and Santa Catarina anchor pricing power through volume-based oleoresin procurement contracts tied to MAPA compliance documentation. This buyer concentration forces suppliers into performance-guaranteed pricing models where batch-traceable carvacrol standardization commands substantial premiums over commodity herbal powders.
Pricing Analysis
Essential oil suppliers bundle microencapsulation services with active compound guarantees, while unbundled herbal powders trade on spot markets with variable thymol content. Three-tier pricing structure across premium, standard, and economy levels separates GRAS-status oleoresins with ANVISA fast-track registration from novel extracts requiring full toxicological dossiers. Cost compression in economy-tier herbal powders is intensifying because Argentine swine operations lack liquid handling infrastructure and prioritize cost over concentration consistency. Mid-sized Brazilian poultry operations show highest price sensitivity due to capital constraints for automated dosing systems, while large integrators absorb premium pricing for supply chain transparency.
Supply Chain Analysis
Direct-to-feedlot channels handle large Argentine cattle finishing demand in Buenos Aires province, displacing traditional distributor intermediaries for EU-bound beef traceability. Mediterranean harvest cycles for oregano and thyme feed raw material volatility into Brazilian formulation plants, while solvent extraction capacity concentrates in São Paulo state research clusters. Supply chain risk centers on single-source vulnerability for high-purity oleoresin production where DSM-Firmenich dominates integrated biotechnology platforms. Distribution runs through veterinary supply networks and feed mill partnerships across Brazil's southern poultry belt, with SENASA import controls creating compliance barriers for non-local suppliers entering Argentine markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Brazil's MAPA residue enforcement systematically displaces ionophore growth promoters and creates structural demand for documented phytogenic alternatives.
For Market Incumbents: Extend encapsulation technology leadership through precision delivery system investments targeting rumen bypass applications in underpenetrated Argentine feedlots. Backward integration into Mediterranean herb cultivation hedges raw material volatility from harvest cycle swings. Prioritize ANVISA equivalency pathway navigation with Chile and Uruguay to compress cross-border registration timelines before regional mutual recognition frameworks mature. For New Entrants and Emerging Players: Argentine distributor partnerships offer the fastest channel access for GRAS-status essential oil formulations targeting mid-sized swine operations in Córdoba and Santa Fe provinces. White-space concentration sits in ruminant methane mitigation where direct procurement contracts between Buenos Aires feedlots and suppliers are displacing traditional intermediaries. Site-specific release coating technologies for rumen bypass unlock premium positioning in cattle finishing operations seeking liver abscess control alternatives. For Investors and Strategic Acquirers: Animal nutrition conglomerates with captive oleoresin production are the most active acquirers in this space, consolidating encapsulation technology assets to defend margin position against European phytogenic specialists. Long-term viability hinges on regulatory navigation speed rather than manufacturing scale alone. Acquisition targets should demonstrate ANVISA dossier preparation capabilities and established GRAS portfolios compressing approval timelines. The signal to watch is ANVISA's implementation of mutual recognition frameworks with neighboring regulators, which would revalue regional premix formulators with cross-border registration expertise.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Acquisition | Brazilian integrators demand heat-stable essential oil matrices protecting bioactives through pelleting temperatures exceeding 85°C. |
| Direct Procurement Contract Expansion | Buenos Aires feedlots negotiate oleoresin supply agreements with quality-assured documentation for EU-bound beef traceability. |
| ANVISA Equivalency Pathway Investment | Mutual recognition frameworks with Chile and Uruguay would streamline cross-border formulation registrations for regional suppliers. |
| Precision Delivery System Development | Site-specific release coatings for rumen bypass converge with essential oil matrices to unlock Argentine ruminant value pools. |
| Mediterranean Cultivation Integration | Backward integration into oregano and thyme sourcing hedges margin predictability against harvest cycle price swings. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Brazilian premix formulation chemists, Argentine feedlot procurement managers, ANVISA regulatory affairs specialists, and southern Chile aquaculture nutrition directors with secondary validation. Trade data from Brazilian MAPA residue monitoring disclosures, Argentine SENASA import control records, ANVISA botanical feed additive guidance documents, and EU import specification databases anchored supply-side estimates. Bottom-up volume builds from individual feed mill deployments and top-down cross-checks against national livestock production statistics ensured triangulation integrity.
Historical reference periods spanning pre-MAPA enforcement baselines through current antibiotic-free program acceleration anchored the projection horizon across the analysis window. Segmentation dimensions modeled include product type concentration tiers, application-specific regulatory burden intensity, formulation heat stability requirements, and distribution channel transparency levels. CAGRs derived from compound growth trajectory fitting to documented phytogenic inclusion rate shifts in Brazilian broiler integrator disclosures. Industry-specific forecast inputs incorporated MAPA inspection frequency trends and EU-Japanese import specification evolution for antibiotic-free meat certification.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ANVISA registration timeline variability, Mediterranean herb harvest volatility, and Argentine feedlot adoption speed for phytogenic methane mitigation protocols. Outputs reflect documented assumption sets around regulatory enforcement continuity and cross-border equivalency framework implementation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biotechnology
Africa Algae Protein Market
Agricultural Biotechnology
Europe Plant Growth Regulators Market
Agricultural Biotechnology
Global Animal Biotechnology Market
Agricultural Biotechnology
Biorationals Market
Agricultural Biotechnology
Plant-Based Vaccines Market
Agricultural Biotechnology
Transgenic Seeds Market
Agricultural Biotechnology
Stigmasterol-Rich Plant Sterols Market
Agricultural Biotechnology
Ruminant Vaccines Market
Agricultural Biotechnology
Europe Agriculture Biotech Market
Agricultural Biotechnology
Agroscience Market
Agricultural Biotechnology
Microarray in Agriculture Market
Agricultural Biotechnology
Animal Brucella Antibody ELISA Kits Market
Agricultural Biotechnology
Asia Pacific Feed Phytogenics Market
Agricultural Biotechnology
GMO Crops and Seeds Market
Agricultural Biotechnology
Asia-Pacific Agriculture Biotech Market
Agricultural Biotechnology
Global Plant Hormones Market