
 Turkey Agricultural Tractor Market | 2026-2036
Turkey Agricultural Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Agricultural Tractor Market Analytics
Single-source supply dependency on imported powertrain components is shifting toward dual-source and localized procurement strategies across Turkish tractor manufacturing. Türk Traktör ve Ziraat Makineleri A.Ş. leverages captive engine production through its long-standing joint venture structure to insulate margin pressure. Tümosan Motor ve Traktör Sanayi A.Ş. anchors its position through vertically integrated diesel engine manufacturing at its Konya facility. Erkunt Traktör Sanayii A.Ş. specializes in cast-iron component foundry work that supplies multiple domestic OEMs.
An agricultural tractor is a self-propelled vehicle engineered to deliver traction and power for agricultural implements, typically featuring diesel engines rated between 15 and 600 horsepower, mechanical or hydrostatic transmissions, and three-point hitch systems standardized to ISO 730 specifications. Its primary commercial purpose centers on soil preparation, planting, cultivation, and harvesting operations across arable land and specialized crop systems. Utility tractors and compact tractors together command the volume core of the Turkish market, with four-wheel drive tractors capturing expanding share as farm consolidation progresses in the Aegean and Marmara basins. GPS-enabled tractors represent the fastest-growing technology category, though electric tractors remain nascent given charging infrastructure gaps in rural Anatolia.
Türkiye's Ministry of Agriculture and Forestry coordinates equipment subsidy schemes with BIS-equivalent machinery certification requirements, while the country's national standards body enforces TSE (Turkish Standards Institution) compliance for safety and emissions. These frameworks shape demand by restricting import eligibility to certified units and directing public support toward domestically manufactured equipment. Stakeholders must monitor how pending EU alignment discussions on Stage V emissions standards will reshape engine architecture investments across Turkish production lines.
Market Dynamics
The Turkish agricultural tractor market is undergoing a structural transformation driven by the Ministry of Agriculture and Forestry's subsidy realignment toward domestically manufactured equipment with TSE certification, compressing import-dependent supply chains and accelerating localization investments across Anatolian production clusters.
Growth Catalysts
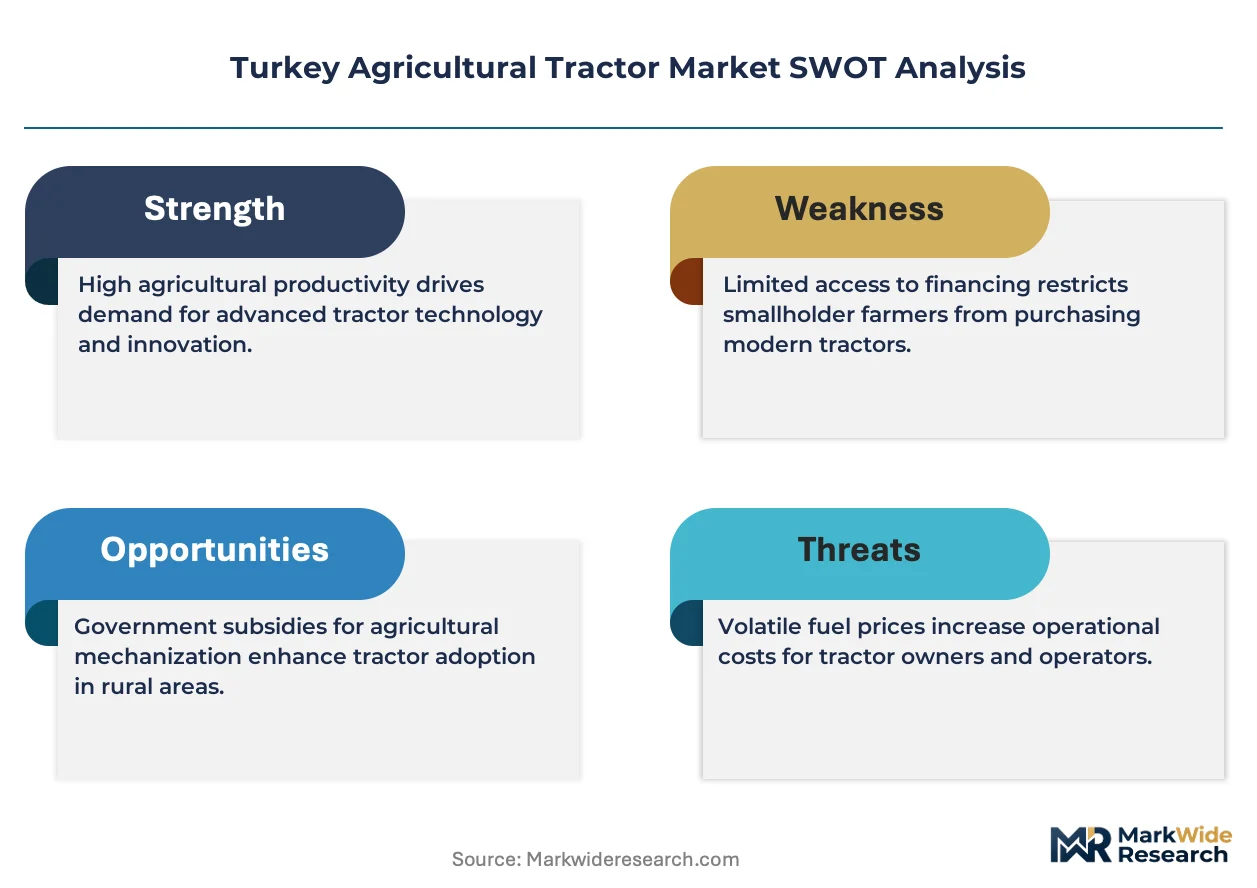
- Equipment Subsidy Programs:The Ministry of Agriculture and Forestry directs public support toward domestically manufactured tractors, lowering effective procurement costs for smallholder cooperatives in Central Anatolia.
- Large-Scale Mechanization:Crop farming consolidation across the Konya Plain creates sustained demand for higher-horsepower four-wheel-drive tractors with advanced hitch systems.
- GPS Technology Diffusion:Precision agriculture adoption among commercial grain producers in the Aegean basin is automating field operations and reducing input waste.
Market Restraints
- Powertrain Import Dependency:Single-source reliance on foreign-sourced engine components exposes Turkish OEMs to currency volatility and extended lead times.
- Charging Infrastructure Gaps:Rural Anatolia's sparse electrical grid coverage constrains electric tractor commercialization despite pilot programs.
- Stage V Alignment Uncertainty:Pending EU emissions standard discussions create investment paralysis around engine architecture decisions.
Strategic Opportunities
- Foundry Capacity Expansion:Erkunt's cast-iron component specialization positions domestic suppliers to capture outsourced production from European tractor manufacturers.
- Cooperative Financing Models:Agricultural credit cooperatives in Southeastern Anatolia are developing lease-to-own structures for smallholders excluded from traditional bank lending.
- Telematics Integration:Convergence of GPS guidance with remote diagnostic platforms enables predictive maintenance services for fleet operators in the Marmara region.
Industry Challenges
- Skilled Technician Scarcity:Hydrostatic transmission and electronic control system repair expertise concentrates in Konya and İstanbul, leaving rural service networks understaffed.
- Certification Timeline Compression:TSE safety and emissions testing bottlenecks delay product launches by 8-14 months, eroding first-mover advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Agricultural Tractor Market |
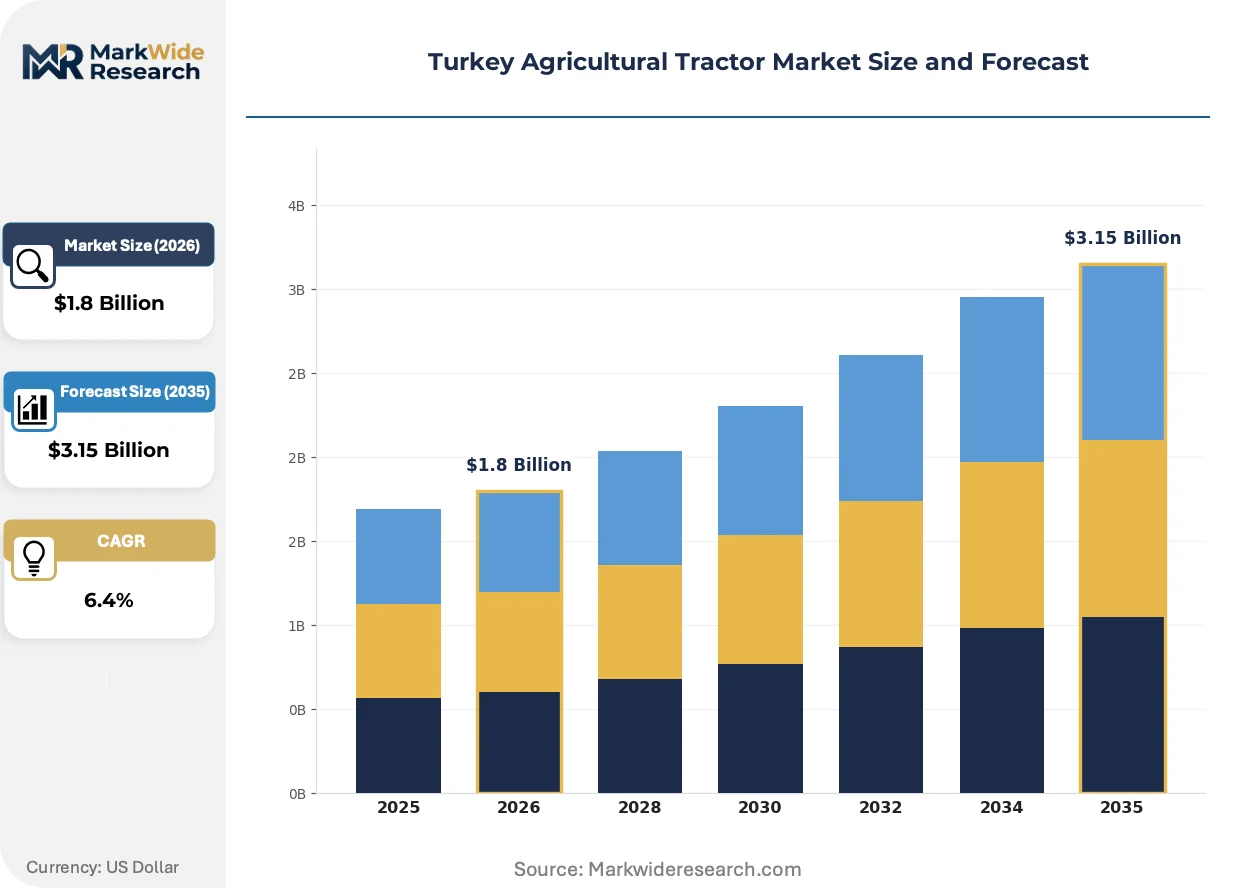
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Tractors, Utility Tractors, Row Crop Tractors, Four-Wheel Drive Tractors Application: Crop Farming, Livestock Farming, Orchard Management, Greenhouse Operations End User: Farmers, Agricultural Cooperatives, Agribusiness Firms, Contractors Technology: GPS-Enabled Tractors, Autonomous Tractors, Fuel-Efficient Tractors, Electric Tractors |
| Companies Covered | Türk Traktör ve Ziraat Makineleri A.Ş., Tümosan Motor ve Traktör Sanayi A.Ş., Erkunt Traktör Sanayii A.Ş., Hattat Traktör Sanayi ve Ticaret A.Ş., Uzel Makina Sanayi A.Ş., AGCO Corporation, CNH Industrial N.V., Deere & Company, Kubota Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Agricultural Tractor Market Evolving Landscape
GPS-enabled precision agriculture is rapidly penetrating Turkish farming operations, while regulatory pressure on emissions and domestic content requirements reshape competitive positioning. Three developments merit particular attention.
Autosteering and variable-rate application technology is automating seeding and fertilizing workflows across the Konya Plain's wheat and barley operations. Large commercial farms with contiguous land holdings are adopting these systems faster than fragmented smallholdings. The technology is automating operator labor requirements and compressing seasonal windows for critical field tasks.
Türkiye's national standards body is enforcing TSE compliance alongside Ministry of Agriculture and Forestry subsidy eligibility rules. This dual framework restricts import participation to certified units and channels public procurement toward domestic manufacturing. Four-wheel-drive tractors above 75 horsepower face the most stringent documentation requirements, pushing OEMs toward captive engine production.
Smallholder cooperatives in Central Anatolia are consolidating equipment purchasing through centralized procurement committees. Traditional dealer networks face disintermediation as cooperatives negotiate direct manufacturer relationships for volume discounts. This behavioral shift is most pronounced among grain-producing collectives with formalized management structures in Konya and Ankara provinces.
Turkey Agricultural Tractor Market Segmentation
Turkish tractor procurement patterns diverge sharply across operational scales and crop systems. Subsidy eligibility tied to TSE certification creates divergent compliance burdens that reshape segment attractiveness for domestic versus import-dependent suppliers.
Product Type:
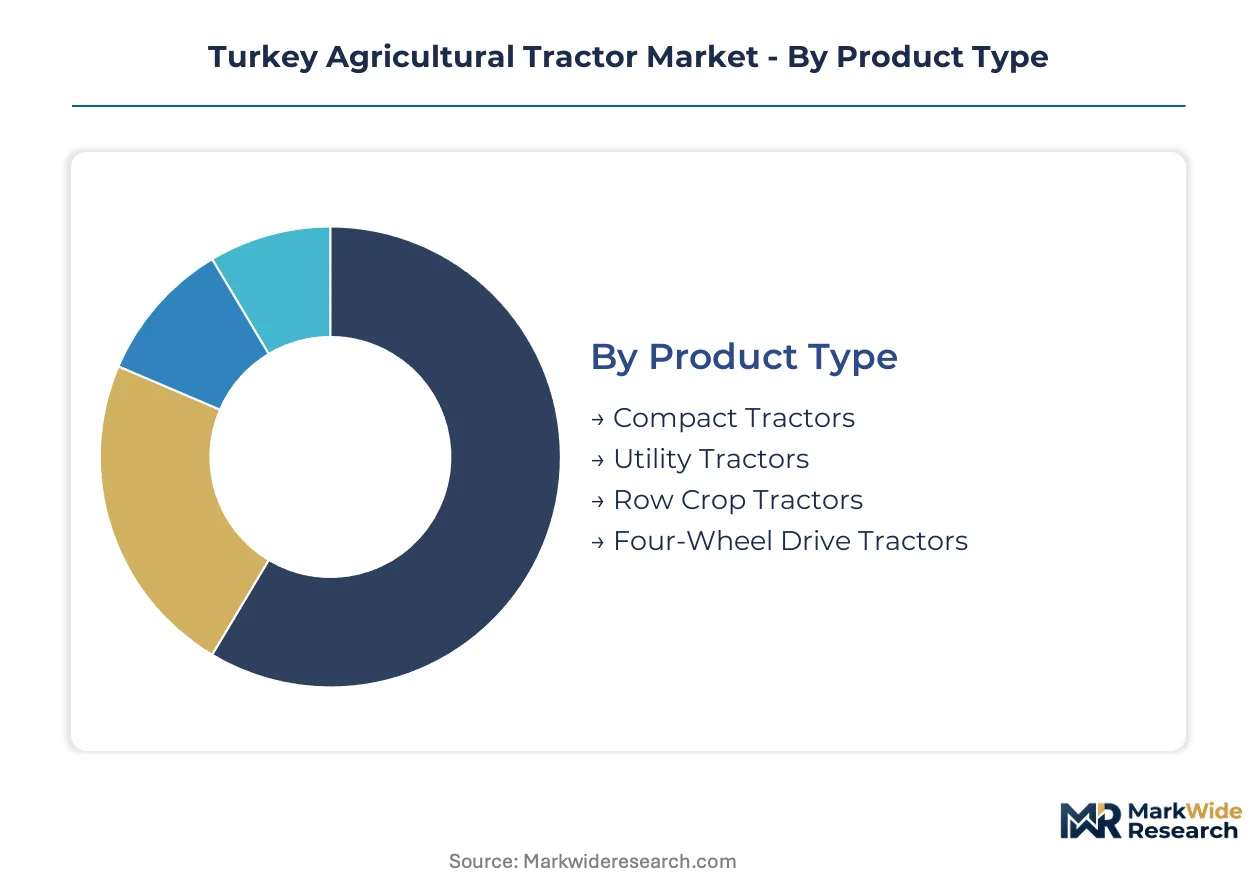
Utility tractors and four-wheel-drive models above 75 horsepower face the most stringent TSE documentation requirements, while compact tractors navigate lighter certification pathways.
- Compact Tractors:Diesel engines rated 15-50 horsepower power these maneuverable units for smallholder vegetable plots and greenhouse accessways. Demand clusters among Aegean olive groves and Black Sea tea gardens where narrow terraces exclude larger machinery. TSE certification timelines compress margin for import-dependent distributors.
- Utility Tractors:Mid-range horsepower platforms dominate equipment pools across Central Anatolia grain cooperatives. Three-point hitch compatibility with domestic implements drives procurement decisions in Konya and Ankara provinces. These units capture the highest subsidy allocation under Ministry of Agriculture and Forestry programs.
- Row Crop Tractors:Specialized narrow-frame configurations serve cotton and sugar beet operations in Çukurova.
- Four-Wheel Drive Tractors:High-horsepower articulated designs penetrate consolidated wheat farms across the Konya Plain.
Utility tractors sit at the top of the volume ranking, with four-wheel drive tractors climbing the fastest.
Application:
Operational intensity and seasonal window pressure differentiate margin structures across farming systems, with crop farming commanding the steepest mechanization investment.
- Crop Farming:Wheat, barley, and corn operations across the Konya Plain and Southeastern Anatolia drive the bulk of tractor replacement cycles. GPS-enabled seeding and fertilizing workflows automate labor requirements on contiguous commercial holdings. Consolidation trends in the Aegean basin accelerate four-wheel-drive adoption.
- Orchard Management:Narrow-gauge compact tractors navigate pistachio and hazelnut groves in Gaziantep and Giresun provinces. Specialized low-clearance designs accommodate canopy spraying and inter-row cultivation. TSE safety certification for rollover protection structures adds procurement lead time.
- Livestock Farming:Loader-equipped utility tractors handle feed distribution and manure management in dairy operations.
- Greenhouse Operations:Ultra-compact electric prototypes serve covered vegetable production in Antalya and Mersin.
Crop farming anchors procurement volume, though orchard management gains share fastest as permanent crop acreage expands.
End User:
Financing access and subsidy navigation capability separate buyer segments, with cooperatives leveraging collective bargaining power unavailable to individual farmers.
- Agricultural Cooperatives:Centralized procurement committees in Konya and Ankara provinces negotiate direct manufacturer relationships, disintermediating traditional dealer networks. Volume discounts and coordinated maintenance contracts reduce lifecycle costs. Formal management structures enable subsidy application expertise that individual farmers lack.
- Farmers:Fragmented smallholders across Eastern Anatolia depend on dealer credit and secondhand equipment markets. Currency volatility exposes this segment to import price shocks. Lease-to-own structures from agricultural credit cooperatives expand access.
- Agribusiness Firms:Corporate grain operations in the Marmara region deploy GPS-enabled fleets with telematics integration.
- Contractors:Seasonal service providers rent high-horsepower units for planting and harvest windows.
Farmers retain the largest installed base, while agricultural cooperatives expand procurement fastest through consolidated purchasing.
Technology:
Precision agriculture diffusion rates vary sharply by grid connectivity and technician availability, creating geographic technology gradients across Anatolia.
- GPS-Enabled Tractors:Autosteering and variable-rate application systems automate field operations on commercial grain farms. The technology compresses seasonal windows for critical planting and fertilizing tasks. Service expertise concentrates in Konya and İstanbul, leaving rural networks understaffed.
- Electric Tractors:Battery-powered prototypes remain nascent given sparse electrical grid coverage in rural Anatolia. Pilot programs in Antalya greenhouse clusters test viability where short duty cycles and return-to-base charging suffice. Stage V alignment uncertainty delays manufacturer architecture commitments.
- Fuel-Efficient Tractors:Common-rail diesel and CVT transmissions reduce operating costs for high-hour users.
- Autonomous Tractors:Fully unmanned systems remain experimental, constrained by liability frameworks and field variability.
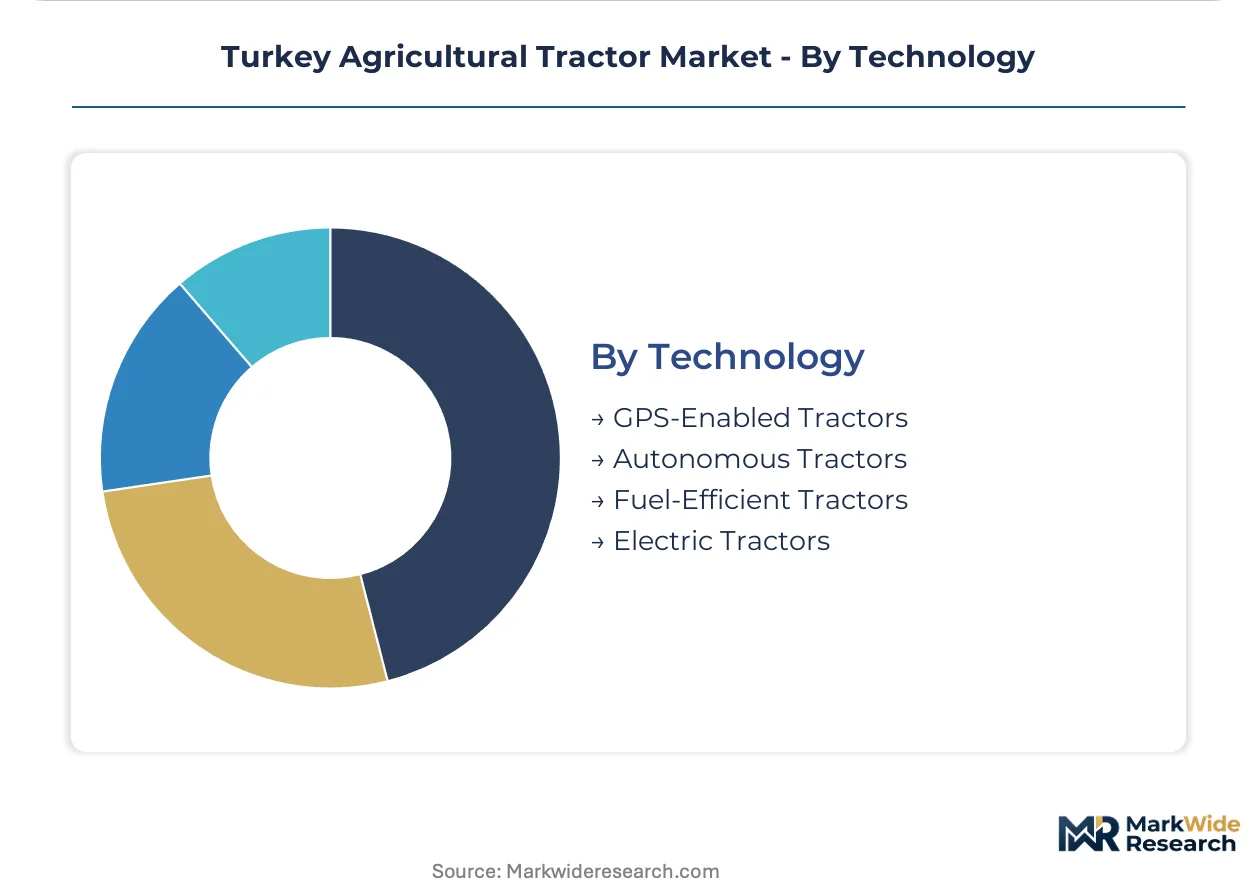
Fuel-efficient tractors dominate current procurement, with GPS-enabled platforms expanding most quickly among commercial grain producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Konya anchors Turkish tractor demand through its dominance of large-scale grain operations on the Central Anatolian Plateau. Subsidy programs from Türkiye's Ministry of Agriculture and Forestry channel procurement toward domestically manufactured equipment with TSE certification. Regional specialization clusters around cast-iron foundries, engine assembly plants, and precision agriculture service hubs.
Central Anatolia
Wheat and barley mechanization across the Konya Plain drives replacement cycles for four-wheel-drive tractors above 75 horsepower. The Ministry of Agriculture and Forestry directs subsidy eligibility toward TSE-certified domestic units, compressing import participation. Konya's vertically integrated manufacturing cluster hosts captive engine production and foundry operations serving multiple OEMs.
Marmara Region
Corporate grain operations deploy GPS-enabled fleets with telematics integration for predictive maintenance scheduling. TSE emissions testing requirements shape procurement timelines for equipment upgrades across commercial holdings. İstanbul concentrates service expertise for hydrostatic transmission and electronic control system repairs.
Aegean Basin
Olive grove consolidation accelerates compact tractor demand for narrow terrace accessways in İzmir and Aydın provinces. Subsidy navigation through agricultural cooperatives disintermediates traditional dealer networks for volume procurement. Farm consolidation trends push four-wheel-drive adoption among expanding commercial operations.
Southeastern Anatolia
Cotton and sugar beet operations in Çukurova require specialized row-crop configurations with narrow-frame designs. Agricultural credit cooperatives develop lease-to-own structures for smallholders excluded from conventional bank lending. Gaziantep's pistachio groves sustain demand for low-clearance orchard tractors with rollover protection structures.
Black Sea Region
Tea garden terraces in Rize and Trabzon provinces limit machinery size to ultra-compact diesel units under 50 horsepower. TSE safety certification for rollover protection adds procurement lead time for specialized equipment. Hazalnut operations in Giresun drive seasonal contractor demand for narrow-gauge cultivation tractors.
Turkey Agricultural Tractor Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision agriculture technology and electric powertrain development. Turkish manufacturing clusters around three domestic OEMs with captive engine or foundry capabilities, while multinational subsidiaries compete through import-dependent distribution. The competitive terrain separates vertically integrated domestic specialists from technology-forward international brands and regional foundry suppliers. Capacity expansion in cast-iron components and strategic partnerships for GPS platform licensing dominate competitive maneuvering.
Among Turkish-based manufacturers, Türk Traktör ve Ziraat Makineleri A.Ş. and Tümosan Motor ve Traktör Sanayi A.Ş. occupy positions reflecting long-standing joint venture structures and vertically integrated diesel engine production respectively. Erkunt Traktör Sanayii A.Ş. exemplifies the foundry-specialist archetype through its cast-iron component supply relationships with multiple domestic OEMs. These three anchors represent distinct strategic postures: captive powertrain insulation, upstream manufacturing control, and component supply diversification.
| Leading Market Players |
|---|
| Türk Traktör ve Ziraat Makineleri A.Ş. |
| Tümosan Motor ve Traktör Sanayi A.Ş. |
| Erkunt Traktör Sanayii A.Ş. |
| Hattat Traktör Sanayi ve Ticaret A.Ş. |
| Uzel Makina Sanayi A.Ş. |
| AGCO Corporation |
| CNH Industrial N.V. |
| Deere & Company |
| Kubota Corporation |
| Others |
Value Network & Pricing Analysis
Cast-iron foundry output from Konya feeds into three distinct pricing tiers downstream, with raw material volatility compressing margins at the economy tier while premium GPS-enabled platforms absorb cost pass-through through bundled service contracts.
Pricing Analysis
Input-cost pass-through from captive engine production insulates Türk Traktör and Tümosan from currency-driven margin erosion that squeezes import-dependent distributors. Three-tier pricing structure across premium, standard, and economy levels separates GPS-enabled fleet packages from bare-utility units and secondhand refurbished equipment. Pricing pressure stems from Ministry of Agriculture and Forestry subsidy realignment favoring TSE-certified domestic manufacture. Agricultural cooperatives in Central Anatolia exhibit lowest price sensitivity through volume procurement committees, while fragmented Eastern Anatolian smallholders face acute exposure to import price shocks.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale cooperative demand in Konya and Ankara provinces, while dealer networks serve fragmented individual farmers. Geographic supply concentration centers on Türkiye for cast-iron components and final assembly, with Germany and Italy as secondary sources for precision hydraulics and electronic control modules. Raw material dependencies rest on domestic scrap steel recycling, imported high-grade alloy additives, and rubber-track compounds from Southeast Asian suppliers. Single-source vulnerability in powertrain electronics creates exposure to extended lead times. Distribution runs through agricultural cooperative procurement committees that disintermediate traditional dealer markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Türkiye's agricultural tractor market functions as a regulatory compounder where Ministry of Agriculture and Forestry subsidy schemes tied to TSE certification create accelerating preference for domestic manufacture.
For Market Incumbents: Hedge against Stage V emissions alignment uncertainty by diversifying engine architecture investments across multiple technology pathways. Deepen backward integration into electronic control module assembly to reduce single-source dependency on German and Italian suppliers. Expand foundry capacity to capture outsourced component demand from European OEMs facing cost pressure. For New Entrants and Emerging Players: GPS-enabled telematics platforms offer a technology-first wedge into the Marmara region's corporate grain operations where predictive maintenance contracts command premium pricing. Target Southeastern Anatolia's lease-to-own financing gap for smallholders excluded from conventional bank lending. Pursue direct cooperative relationships bypassing established dealer networks. For Investors and Strategic Acquirers: Roll-up economics work for foundry-specialist component suppliers because Erkunt's cast-iron model demonstrates scalable supply relationships across multiple domestic OEMs. Five-to-ten year viability hinges on EU emissions convergence trajectory. Monitor Stage V implementation timeline as primary inflection signal for engine architecture investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Engine Production Expansion | Tümosan's Konya facility insulates margin from currency volatility and import lead times. |
| GPS Telematics Platform Licensing | Predictive maintenance contracts lock in recurring revenue from Marmara fleet operators. |
| Foundry Capacity Buildout | Erkunt's cast-iron specialization captures outsourced European OEM component demand. |
| Cooperative Direct Procurement | Centralized purchasing committees in Konya disintermediate dealer network markups. |
| Stage V Emissions Pre-Compliance | Early architecture investment positions domestic OEMs ahead of EU alignment deadlines. |
Research Methodology
Coverage spans Central Anatolia, Marmara, Aegean, Southeastern Anatolia, and Black Sea regions, with primary inputs from each. The research combines structured interviews with agricultural cooperative procurement managers, tractor OEM product planning directors, Ministry of Agriculture and Forestry subsidy administrators, and TSE certification engineers with secondary validation from customs trade records, TSE regulatory filings, and agricultural machinery registration databases. Bottom-up equipment shipment data triangulates against top-down subsidy allocation records.
Rate-of-change decomposition separates volume growth from mix-shift effects across horsepower tiers, technology categories, and end-user segments. The analytical framework models product type, application intensity, cooperative versus individual farmer procurement patterns, and regional subsidy penetration rates across the projection horizon. CAGRs derive from segmented growth trajectory analysis incorporating equipment replacement cycle timing and GPS technology diffusion curves.
The model holds under continued Ministry of Agriculture and Forestry subsidy continuity and stable currency conditions; deviation in EU Stage V implementation timing or lira volatility would shift equipment import competitiveness and domestic production planning horizons. Forecasts reflect documented assumptions about cooperative consolidation rates and precision agriculture adoption thresholds. Periodic stress-testing of base assumptions against regulatory milestone announcements and exchange rate movements is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Orchard Type Tractors Market
Agricultural Machinery
Europe Agricultural Machinery Market
Agricultural Machinery
Agricultural Food Grade Rubber Conveyor Belt Market
Agricultural Machinery
China Agricultural Tractors Market
Agricultural Machinery
Vietnam Agricultural Tractor Market
Agricultural Machinery
Canada Robotic Fruit Picker Market
Agricultural Machinery
Autonomous Electric Tractor Market
Agricultural Machinery
Farm Tractor Market
Agricultural Machinery
Two-Wheeler Tractors Market
Agricultural Machinery
Rotary Tiller Market
Agricultural Machinery
Hydrogen Powered Tractor Market
Agricultural Machinery
Utility Tractor Market
Agricultural Machinery
Agricultural Tractor Market
Agricultural Machinery
France Agricultural Machinery Market
Agricultural Machinery
Argentina Agricultural Machinery Market
Agricultural Machinery
Canada Agricultural Machinery Market