
 Autonomous Electric Tractor Market | 2026-2036
Autonomous Electric Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Electric Tractor Market Insights
The autonomous electric tractor category is restructuring around a sharp split between premium fully autonomous platforms and semi-autonomous electric utility models serving price-sensitive buyers. John Deere leverages its precision agriculture ecosystem to dominate the high-tier segment with integrated autonomy stacks. Monarch Tractor anchors the mid-market with compact electric designs purpose-built for specialty crop operations. Kubota Corporation competes through its established dealer network across North American row-crop territories.
An autonomous electric tractor integrates battery-electric propulsion with self-driving capabilities via sensor fusion, GPS-RTK guidance, and onboard machine learning processors executing path planning without human intervention; these systems typically operate at 40-75 kWh battery capacity and serve to eliminate diesel fuel consumption while addressing chronic farm labor scarcity. Fully autonomous platforms command the steepest R&D investment but capture the highest margin pools as early adopters prioritize unmanned overnight operations. Semi-autonomous electric utility tractors sustain broader volume traction among farming cooperatives balancing capital constraints with electrification goals. Sensor technology and computer vision subsystems represent the fastest-expanding cost centers as manufacturers race to improve obstacle detection in variable field conditions.
The US EPA and California Air Resources Board shape product development through escalating off-road emissions rules that effectively mandate zero-exhaust powertrains in key agricultural states, while the FAA monitors low-altitude drone coordination protocols that increasingly intersect with autonomous ground fleet management. The EU Green Deal and F-Gas Regulation pressure exporters to certify battery thermal systems for European climate zones. Stakeholders must weigh battery supply chain commitments against the pace of rural charging infrastructure deployment before scaling manufacturing capacity.
Market Dynamics
The US EPA's escalating Tier 4 Final and proposed Tier 5 emissions standards for off-road diesel equipment are forcing agricultural equipment manufacturers to accelerate battery-electric platform development, compressing traditional product cycle timelines by half.
Growth Catalysts
- Farm Labor Scarcity:Chronic shortages of seasonal agricultural workers across California's Central Valley and the US Corn Belt are pushing large-scale producers toward unmanned overnight tractor operations.
- IRA Clean Energy Credits:The Inflation Reduction Act's commercial clean vehicle tax credits offset up to forty percent of electric tractor acquisition costs for qualifying farming cooperatives.
- Precision Agriculture Integration:GPS-RTK guidance systems and sensor fusion technologies now enable centimeter-accurate autonomous field navigation without human intervention.
Market Restraints
- Battery Supply Concentration:Lithium-ion cell production concentrates in Chinese and South Korean manufacturing facilities, exposing OEMs to raw material price volatility and export restriction risks.
- Rural Charging Infrastructure Gap:Level 3 DC fast charging remains unavailable across seventy percent of US agricultural counties, limiting electric tractor operational range.
- Technical Limitation in Variable Terrain:Current computer vision systems struggle with obstacle detection in muddy conditions and dense crop canopies, requiring human oversight.
Strategic Opportunities
- Specialty Crop Penetration:Vineyards and orchards in California's Napa Valley and Washington's Yakima Valley present untapped demand for compact autonomous electric utility tractors.
- Swappable Battery Architectures:Standardized battery pack interfaces enable field-side hot-swapping, eliminating downtime during critical planting and harvest windows.
- Carbon Credit Monetization:USDA Climate-Smart Commodities grants allow producers to document diesel displacement and sell verified carbon offsets through voluntary markets.
Industry Challenges
- Autonomy Software Certification:The FAA and state departments of agriculture lack harmonized safety standards for unmanned agricultural vehicles, creating regulatory uncertainty for fleet deployments.
- Legacy Equipment Integration:Proprietary CAN bus protocols from incumbent diesel tractor manufacturers block seamless data exchange with third-party autonomous electric platforms.
- Technician Skill Gap:Rural equipment service centers lack trained personnel for high-voltage battery system diagnostics and machine learning sensor calibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Electric Tractor Market |
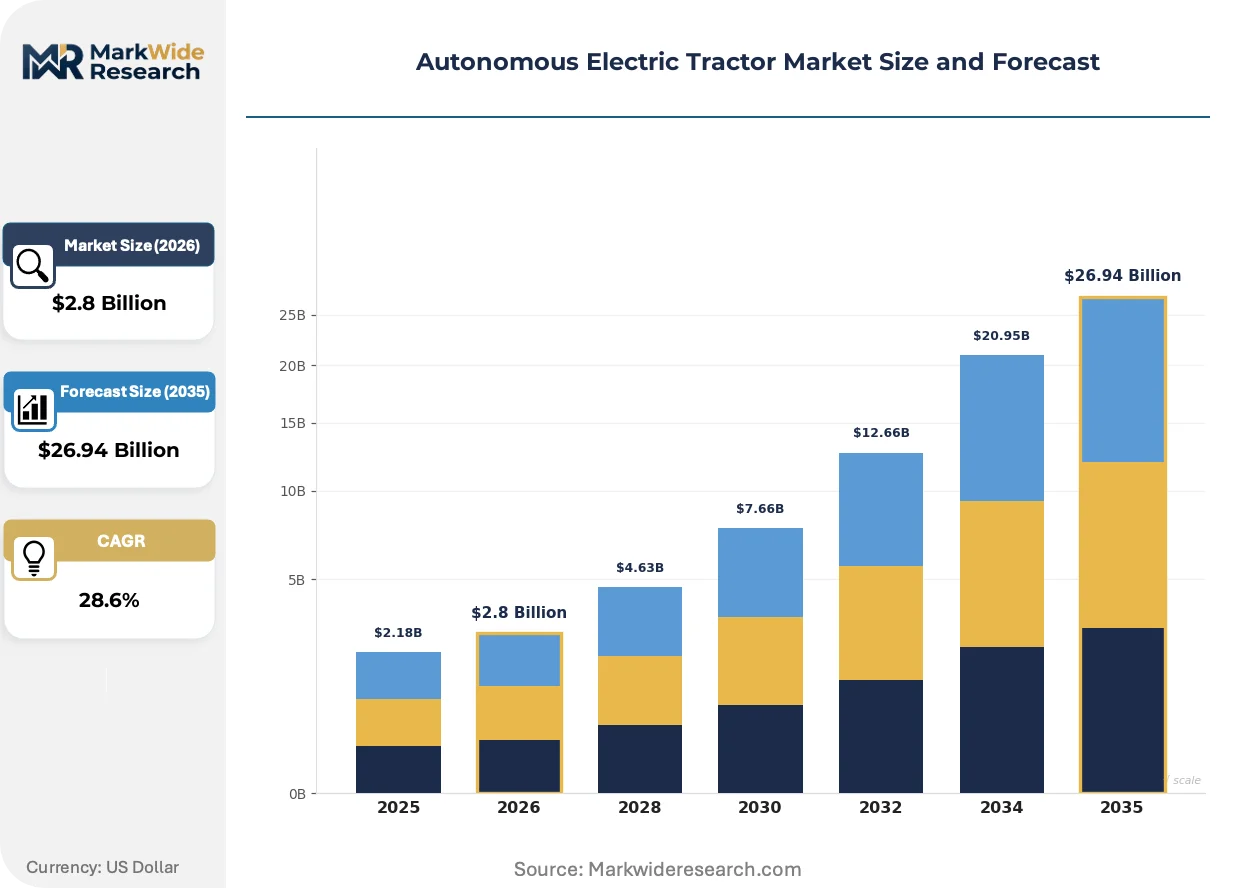
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $26.94 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
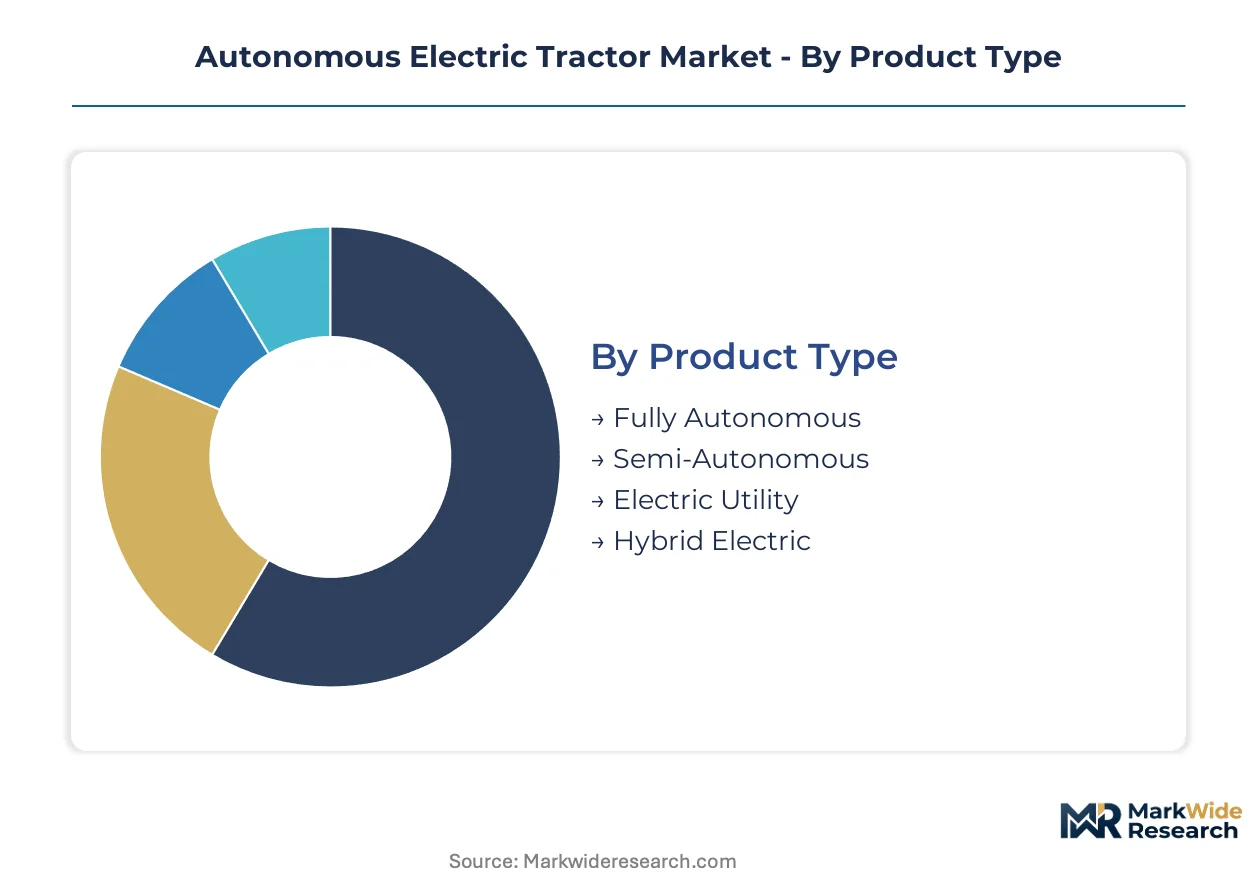
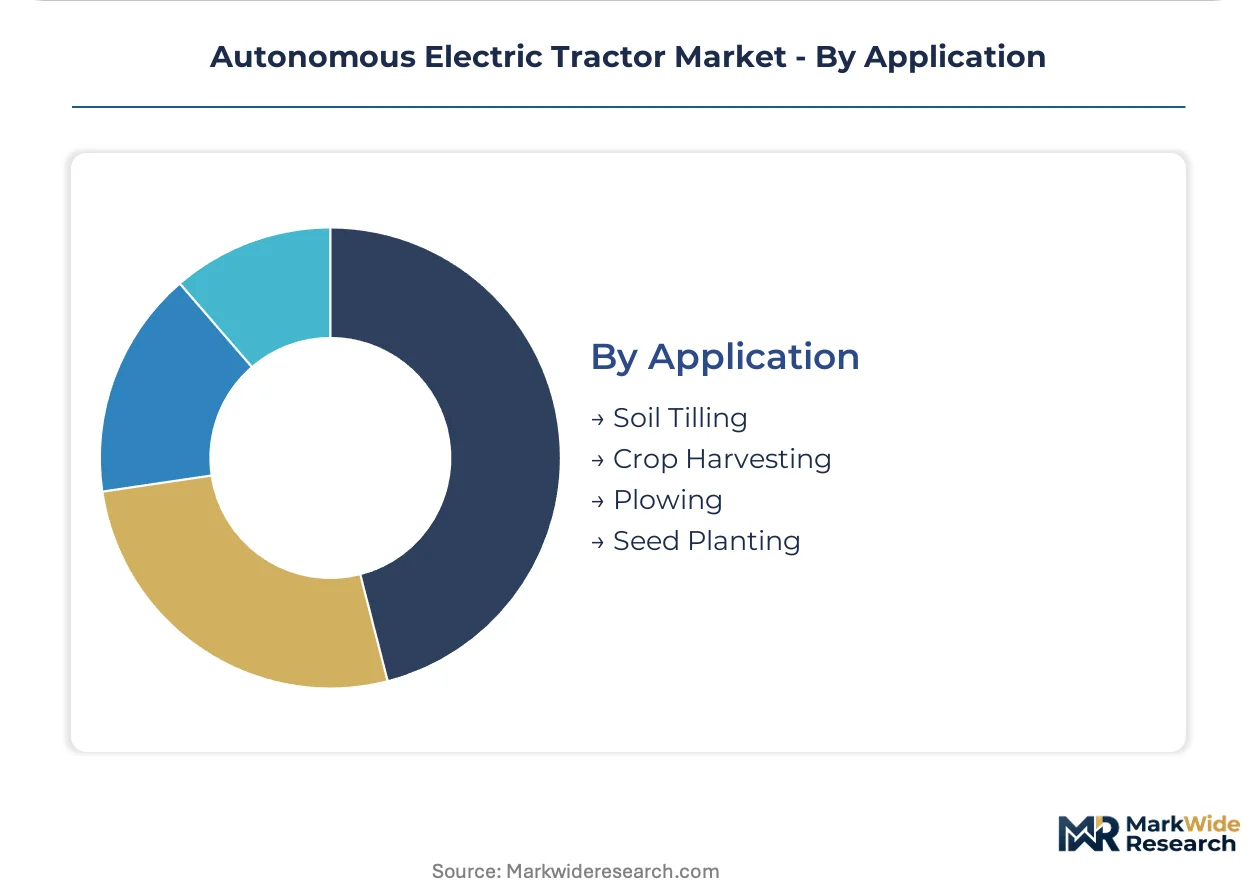
| Segmentation | Product Type: Fully Autonomous, Semi-Autonomous, Electric Utility, Hybrid Electric End User: Agricultural Producers, Farming Cooperatives, Agricultural Contractors, Research Institutions Technology: Machine Learning, Sensor Technology, Computer Vision, IoT Connectivity Application: Soil Tilling, Crop Harvesting, Plowing, Seed Planting |
| Companies Covered | John Deere, Monarch Tractor, Kubota Corporation, CNH Industrial, AGCO Corporation, Mahindra & Mahindra, Yanmar Co., Ltd., Escorts Kubota Limited, Autonomous Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Electric Tractor Market Trends and Innovations
Autonomous electric tractor architecture is fragmenting into specialized configurations as manufacturers abandon universal platforms in favor of crop-specific designs optimized for distinct operational envelopes and duty cycles.
Swappable battery pack systems are modularizing tractor powertrain architecture. Specialty crop operators in California and Washington are adopting standardized interfaces that enable field-side battery exchange within four minutes. This modularity is compressing total cost of ownership calculations by eliminating range anxiety and enabling continuous seasonal operation without overnight charging delays.
The US EPA's proposed Tier 5 off-road emissions standards will effectively prohibit new diesel tractor sales in regulated states by the early 2030s. Equipment manufacturers are reallocating engineering resources from compliance-focused exhaust aftertreatment to battery thermal management and electric drivetrain optimization. California's Central Valley air districts are responding with accelerated grant programs for zero-emission agricultural equipment.
Cooperative purchasing agreements are consolidating buyer power among mid-scale farming operations. Groups of fifty to two hundred member farms are negotiating fleet pricing directly with manufacturers, bypassing traditional dealer networks. This channel compression is most visible across the US Corn Belt, where Iowa and Illinois-based cooperatives now represent the fastest-growing customer segment for semi-autonomous electric utility tractors.
Autonomous Electric Tractor Market Segmentation
Autonomous electric tractor procurement patterns diverge sharply between large-scale operators seeking unmanned overnight capability and mid-tier buyers prioritizing electrification within capital constraints. Segment boundaries are blurring as swappable battery architectures and precision agriculture integration reshape total cost calculations across all buyer categories.
Product Type:
Propulsion architecture and autonomy level define the core technology axis, with battery capacity and sensor fusion density determining operational envelope and price positioning.
- Fully Autonomous:These platforms integrate 40-75 kWh battery systems with GPS-RTK guidance and onboard machine learning processors executing path planning without human intervention. Demand concentrates among California Central Valley specialty crop producers facing EPA Tier 4 Final compliance deadlines and acute seasonal labor shortages.
- Semi-Autonomous:Human-supervised electric tractors retain operator cabs while automating repetitive field tasks through sensor-assisted steering and implement control. US Corn Belt farming cooperatives dominate procurement, leveraging IRA clean vehicle tax credits to offset acquisition costs while maintaining operational flexibility.
- Electric Utility:Compact battery-electric designs without full autonomy stacks serve vineyard and orchard operations in Washington's Yakima Valley where maneuverability in tight row spacing outweighs unmanned capability requirements.
- Hybrid Electric:Range-extended architectures combining battery-electric propulsion with small onboard generators address rural charging infrastructure gaps across Midwest agricultural counties lacking Level 3 DC fast charging availability.
Fully Autonomous leads on scale; Semi-Autonomous leads on momentum.
End User:
Buyer organizational structure dictates fleet sizing, financing mechanisms, and autonomy risk tolerance across the procurement landscape.
- Agricultural Producers:Large-scale integrated operations with thousand-plus acre holdings in Iowa and Illinois deploy fully autonomous platforms for continuous overnight tillage and planting windows. These buyers negotiate direct manufacturer relationships, bypassing traditional dealer networks through cooperative purchasing agreements.
- Farming Cooperatives:Member-owned entities representing fifty to two hundred farms consolidate negotiating power for semi-autonomous electric utility fleets. USDA Climate-Smart Commodities grants enable these groups to document diesel displacement and monetize verified carbon offsets through voluntary markets.
- Agricultural Contractors:Seasonal service providers serving multiple farm clients prioritize swappable battery architectures to eliminate charging downtime during critical planting and harvest periods across dispersed job sites.
- Research Institutions:University agricultural extension programs and USDA field stations acquire platforms for computer vision algorithm development and autonomous system safety validation in controlled test environments.
Agricultural Producers dominate current revenue; Farming Cooperatives are climbing the fastest.
Technology:
Sensor and compute subsystem selection determines field performance in variable terrain and weather conditions.
- Machine Learning:Onboard neural networks process real-time sensor feeds to adapt path planning for obstacle detection in muddy conditions and dense crop canopies where rule-based systems fail.
- Sensor Technology:LiDAR, radar, and ultrasonic arrays provide redundant environmental mapping for safety-critical autonomous operations in GPS-denied environments such as tree canopies or steep topography.
- Computer Vision:Camera-based systems enable crop health monitoring and weed identification concurrent with primary field operations, generating data layers for precision agriculture platforms.
- IoT Connectivity:Cellular and mesh networking protocols enable fleet management, over-the-air software updates, and remote diagnostic access for rural equipment service centers lacking high-voltage battery system expertise.
Sensor Technology anchors current deployments; Machine Learning is gaining share fastest.
Application:
Operational duty cycle and seasonal timing windows drive tractor specification requirements and battery capacity sizing.
- Soil Tilling:High-drawbar applications in heavy clay soils of the US Corn Belt demand sustained power output and thermal management systems capable of continuous operation during compressed spring preparation windows.
- Crop Harvesting:Time-critical grain and specialty crop collection operations prioritize swappable battery architectures to maintain throughput during weather-limited harvest periods.
- Plowing:Deep tillage operations in California's Central Valley face escalating air district grant program requirements for zero-emission equipment compliance.
- Seed Planting:Precision planting applications leverage GPS-RTK guidance for centimeter-accurate row spacing, with autonomous platforms enabling 24-hour operation during optimal soil moisture conditions.
Soil Tilling represents the largest installed base; Crop Harvesting shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision engineering clusters accelerate autonomous electric tractor development faster than Brazil's agribusiness belt, where electrification infrastructure lags commodity export priorities. Regulatory divergence between EU Green Deal mandates and Mercosur trade frameworks shapes divergent investment timelines across major agricultural economies.
United States
California's Central Valley specialty crop producers and Iowa's corn-soy operations drive divergent demand profiles for compact versus row-crop autonomous platforms. The EPA's Tier 4 Final and proposed Tier 5 off-road emissions standards compel zero-exhaust powertrain adoption by the early 2030s. Chicago-based equipment finance consortia structure cooperative purchasing agreements for Corn Belt farming cooperatives seeking IRA clean vehicle tax credit optimization.
Germany
Baden-Württemberg's automotive supplier networks repurpose electric drivetrain expertise for agricultural machinery applications. The EU Green Deal and F-Gas Regulation mandate battery thermal system certification for European climate zone compliance. Bavarian precision agriculture technology clusters near Munich integrate sensor fusion systems with legacy equipment protocols.
China
Shandong Province's agricultural machinery manufacturing bases scale battery-electric platform production for domestic wheat and rice cultivation regions. MIIT dual carbon goals and GB standards for off-road electric vehicles accelerate OEM electrification roadmaps. Yangtze River Delta battery cell suppliers negotiate long-term lithium supply contracts with tractor manufacturers.
Brazil
Mato Grosso soybean mega-farms evaluate autonomous electric tractors against diesel cost advantages in remote cerrado regions lacking grid connectivity. ANVISA and the national agricultural regulator coordinate safety standards for unmanned vehicle certification. São Paulo state research stations test computer vision systems for tropical crop canopy navigation.
India
Punjab and Haryana smallholder cooperatives pilot compact electric utility tractors under PLI scheme subsidies for domestic manufacturing. BIS standards for agricultural electrification equipment and state-level farm mechanization programs compress payback periods. Karnataka precision agriculture startups near Bangalore develop low-cost sensor packages for semi-autonomous retrofit kits.
Autonomous Electric Tractor Market Competitive Landscape
Top-tier vendors anchor the fully autonomous premium segment, while mid-market specialists and regional fabricators occupy distinct price-performance tiers. The competitive structure consolidates around integrated precision agriculture ecosystems, compact specialty crop platforms, and scale-driven row-crop equipment. Three archetypes dominate: legacy agricultural machinery conglomerates with dealer network advantages, electric-first challengers with software-native architectures, and Asian conglomerates leveraging diversified manufacturing scale. Strategic moves concentrate on swappable battery standardization alliances and precision agriculture data platform integration.
Within the legacy machinery tier, John Deere exemplifies ecosystem-integrated autonomy stacks, while Kubota Corporation occupies a position bridging established dealer networks with electrification transitions. Monarch Tractor represents the electric-native challenger archetype, anchoring mid-market penetration through purpose-built compact designs. These three companies illustrate the competitive divergence between software-defined platforms and hardware-optimized incrementalism.
| Leading Market Players |
|---|
| John Deere |
| Monarch Tractor |
| Kubota Corporation |
| CNH Industrial |
| AGCO Corporation |
| Mahindra & Mahindra |
| Yanmar Co., Ltd. |
| Escorts Kubota Limited |
| Autonomous Solutions |
| Others |
Pricing and Supply Chain Analysis
Fully autonomous platform premiums diverge sharply from semi-autonomous electric utility pricing, with that bifurcation manifesting in both acquisition cost structures and lithium-ion cell procurement strategies across California Central Valley specialty crop producers and US Corn Belt farming cooperatives.
Pricing Analysis
Capacity additions in Chinese and South Korean battery cell manufacturing are reshaping price floors for electric drivetrain components. Three-tier pricing structure across premium fully autonomous, standard semi-autonomous, and economy electric utility levels reflects sensor fusion density and battery capacity differentials. Cost compression in the mid-market tier is intensifying because IRA clean vehicle tax credits compress net acquisition costs for qualifying farming cooperatives. Agricultural Producers demonstrate lowest price sensitivity given unmanned overnight operational requirements, while Farming Cooperatives exhibit highest sensitivity as they balance electrification goals against capital constraints.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from thousand-plus acre integrated operations, while established dealer networks serve mid-market semi-autonomous electric utility procurement. Geographic supply concentration centers on China, South Korea, and Japan for lithium-ion cell production. Raw material dependencies draw from lithium carbonate, cobalt sulfate, and rare earth permanent magnets for electric drivetrain motors. Single-source vulnerability in Chinese cathode active material production exposes OEMs to export restriction risks. Distribution runs through cooperative purchasing agreements consolidating fifty to two hundred member farms across Iowa and Illinois.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This autonomous electric tractor market represents a late-cycle quality story as buyer procurement shifts decisively toward fully autonomous platforms with integrated precision agriculture ecosystems and unmanned overnight capability.
For Market Incumbents: Anticipate software-native challengers eroding mid-market share through purpose-built compact designs by accelerating dealer network electrification certification and securing long-term lithium supply contracts with Yangtze River Delta suppliers. Vertical integration into sensor fusion subsystem development defends margin position against electric-first entrants. For New Entrants and Emerging Players: Dealer network partnerships in rural equipment service centers unlock fastest penetration pathways for swappable battery architectures targeting agricultural contractors with dispersed seasonal job sites. Washington's Yakima Valley specialty crop operations present the most penetrable white-space segment given maneuverability requirements in tight orchard row spacing. USDA Climate-Smart Commodities grant alignment accelerates cooperative purchasing agreement access. For Investors and Strategic Acquirers: Consolidation pressure builds where precision agriculture data platform integration creates switching costs exceeding standalone hardware value. Five-to-ten year viability favors electric-native challengers with software-defined architectures over legacy manufacturers managing diesel-electric transition portfolios. Monitor EPA Tier 5 off-road emissions standard finalization timing as inflection indicator for zero-exhaust powertrain adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Swappable Battery Standardization Alliance | Field-side hot-swapping eliminates downtime during critical planting windows for agricultural contractors. |
| Precision Agriculture Platform Integration | GPS-RTK guidance and sensor fusion create data layer monetization opportunities for California Central Valley producers. |
| Dealer Network Electrification Certification | Rural service centers gain high-voltage battery diagnostics capability addressing technician skill gaps. |
| Cooperative Purchasing Agreement Expansion | Consolidated buyer power compresses acquisition costs for fifty to two hundred member farming cooperatives. |
| Carbon Credit Monetization Program | USDA Climate-Smart Commodities grants enable diesel displacement documentation for voluntary offset markets. |
Research Methodology
Direct dialogue with agricultural equipment procurement directors, precision agriculture technology leads, rural equipment service center managers, and cooperative purchasing agreement negotiators grounded qualitative findings. Secondary validation drew from EPA Tier 4 Final regulatory filings, USDA Climate-Smart Commodities program documentation, IRA clean vehicle tax credit guidance, and agricultural machinery trade association production data. Bottom-up unit economics modeling triangulated against top-down market sizing across the analysis window.
Segment-level value outputs reflect a structured approach modeling propulsion architecture, autonomy level, battery capacity tier, end-user organizational structure, and regional regulatory cluster dimensions. CAGRs derived from historical adoption pattern extrapolation adjusted for EPA emissions timeline acceleration and rural charging infrastructure deployment trajectories. Forecast inputs incorporated lithium-ion cell price curves and precision agriculture software attach rate assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA Tier 5 standard finalization timing and Chinese export restriction implementation. Projections reflect documented assumptions regarding battery thermal system certification pathways and cooperative purchasing agreement penetration rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Global Agricultural Sprayer Market
Agricultural Machinery
United States Agricultural Machinery Market
Agricultural Machinery
Agricultural Unit Heaters Market
Agricultural Machinery
Mini Tractors Market
Agricultural Machinery
Agriculture Sprayers Market
Agricultural Machinery
South America Agricultural Machinery Market
Agricultural Machinery
Europe Agricultural Machinery Market
Agricultural Machinery
Milking Robots Market
Agricultural Machinery
Asia-Pacific Agricultural Tractors Market
Agricultural Machinery
India Tractor Market
Agricultural Machinery
US Lawn Mowers Market
Agricultural Machinery
Hydrogen Powered Tractor Market
Agricultural Machinery
Brazil Tractors Market
Agricultural Machinery
Farm Tractor Market
Agricultural Machinery
North America Agricultural Tractors Market
Agricultural Machinery
Turkey Agricultural Tractor Market