
 Asia-Pacific Agricultural Tractors Market | 2026-2036
Asia-Pacific Agricultural Tractors Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Agricultural Tractors Market Outlook
Market Context with Strategic Players
The capability gap between high-capital and low-capital manufacturers is rotating competitive advantage toward vertically integrated producers. Kubota Corporation leverages its engine-manufacturing depth to control cost structures across compact and mid-size ranges. Mahindra and Mahindra Ltd. anchors its position through dominant distribution networks in India and extended service reach into Bangladesh and Sri Lanka. Deere and Company competes on precision agriculture integration, though its premium positioning limits penetration among Asia-Pacific's price-sensitive smallholder base.
Technical Definition and Structural Segments
Asia-Pacific agricultural tractors are self-propelled vehicles engineered to deliver drawbar and power-take-off torque for soil preparation, planting, and harvesting operations, typically featuring diesel powertrains rated from 15 to 300+ horsepower with hydrostatic or powershift transmissions. Their primary commercial purpose is to replace animal and human labor in tillage and transport, thereby expanding cultivable acreage per worker. The 4-Wheel Drive segment leads in revenue contribution where paddy-field traction demands dominate, while Electric fuel-type tractors represent the fastest-growing structural category as China's MIIT pushes battery-swap standards and subsidy eligibility. Compact-size units sustain the largest volume base across Japan's terraced highlands and Vietnam's Mekong Delta smallholdings, though margin pools concentrate in specialized vineyard and orchard configurations.
Regulatory Frame and Forward-Looking Close
China's MIIT and MEE enforce Stage IV emission standards and dual carbon goals that compel domestic manufacturers to retool engine architectures or accelerate electrification roadmaps. India's BIS and CEA coordinate testing protocols and rural electrification standards that shape tractor-eligible subsidy disbursements under centrally sponsored schemes. Japan's METI maintains JIS certification requirements that constrain import access and preserve domestic manufacturer competitiveness. Stakeholders must monitor how subsidy qualification criteria evolve across Beijing, New Delhi, and Tokyo, as these will determine which powertrain technologies achieve scale economics before the next replacement cycle peaks.
Market Dynamics
China's dual carbon goals and India's PLI scheme for farm machinery are redirecting manufacturer investment toward electrification and precision agriculture, compressing replacement cycles across the Indo-Gangetic Plains where rice-wheat cropping intensity peaks.
Growth Catalysts
- India's PLI scheme for farm machinery:Production-linked incentives accelerate domestic assembly capacity and reduce import dependency for critical powertrain components.
- Smallholder cooperatives across Southeast Asia:Mechanization is deepening as collective purchasing pools overcome individual capital constraints for compact tractor acquisition.
- Battery-swap standards from China's MIIT:Subsidy eligibility tied to standardized charging infrastructure is unlocking electric tractor adoption in paddy-field applications.
Market Restraints
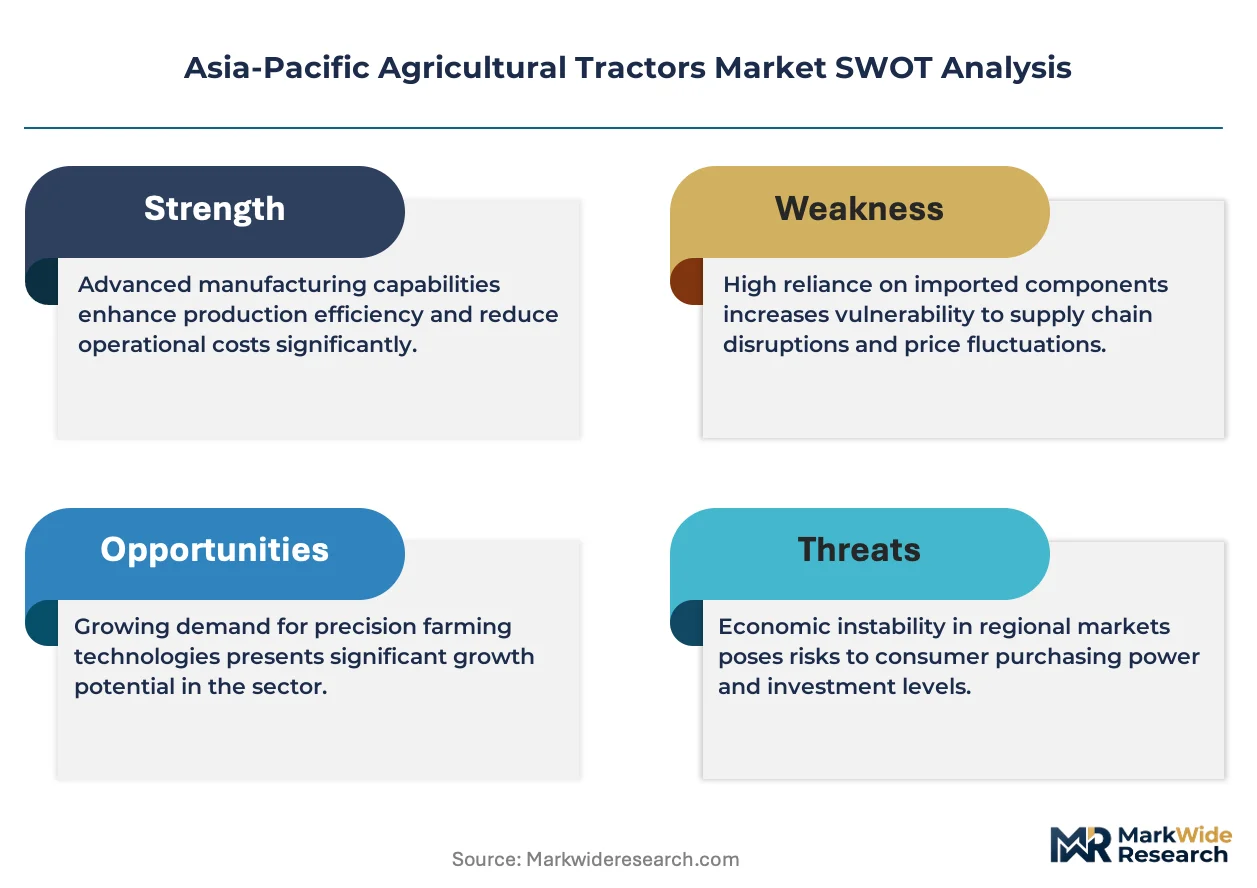
- Steel and semiconductor input cost volatility:Price swings in cast iron housings and ECU chipsets compress margin pools for mid-size manufacturers lacking captive foundry capacity.
- Stage IV emission compliance friction:China's MEE enforcement timelines force simultaneous engine retooling and electrification R&D, straining engineering bandwidth.
- Animal draft persistence in marginal terrain:Water buffalo and manual tillage retain cost advantage in terraced highlands of Laos and Myanmar, limiting addressable market expansion.
Strategic Opportunities
- Vietnam's Mekong Delta smallholdings:Compact-size unit penetration remains below replacement-cycle saturation, creating whitespace for orchard-configuration specialists.
- Autosteer-to-telemetry convergence:Integration of RTK guidance with cloud-based fleet management enables outcome-based service contracts for cooperative buyers.
- Japan's METI rural electrification standards:Grid-hardening subsidies in Hokkaido and Tohoku expand battery-electric tractor operational radius beyond current range anxiety thresholds.
Industry Challenges
- Precision agriculture technician scarcity:Shortage of certified diagnostic specialists for CAN-bus telemetry and hydraulic troubleshooting extends downtime in remote service territories.
- Legacy mechanical-to-electronic control migration:Retrofit complexity with existing power-take-off implements creates integration friction for first-time precision-ag buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Agricultural Tractors Market |
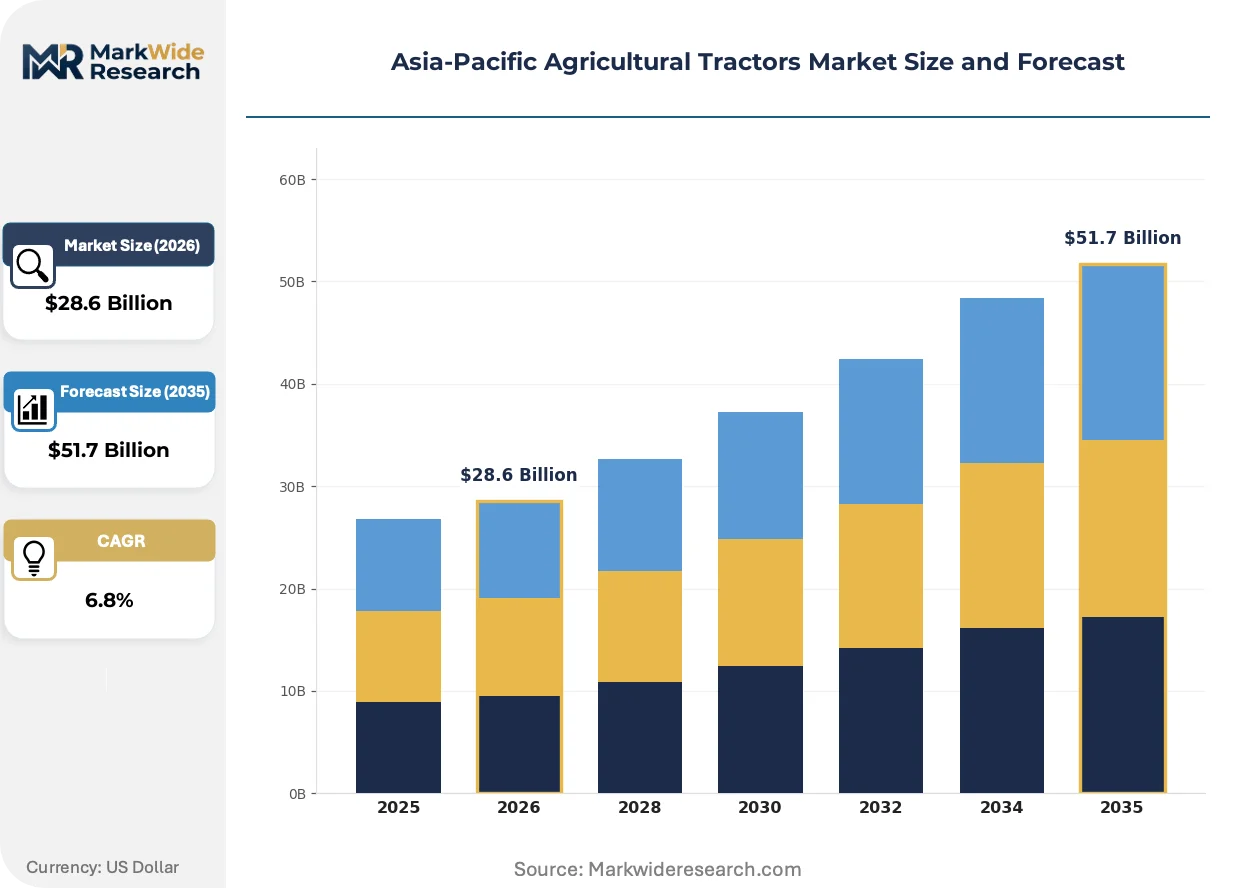
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2-Wheel Drive, 4-Wheel Drive, Utility, Specialized End Use: Crop Farming, Livestock, Forestry, Horticulture Fuel Type: Diesel, Gasoline, Electric, Biofuel Size: Compact, Medium, Large, Extra Large |
| Companies Covered | CNH Industrial N.V., AGCO Corporation, Kubota Corporation, Lovol Heavy Industry Co., Ltd., Iseki & Co., Ltd., Mahindra and Mahindra Ltd., Yanmar Co., Ltd., Daedong Corporation, Deere and Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Agricultural Tractors Market Strategic Shifts
Powertrain electrification, precision-agriculture integration, and cooperative purchasing consolidation are actively reshaping competitive positioning across the Asia-Pacific agricultural tractors landscape.
Modular battery-pack architectures are decomposing traditional diesel-engine value chains in China's Yangtze River Delta manufacturing clusters. Domestic OEMs adopting swappable cell configurations bypass import-dependent engine supply constraints. This technology shift is compressing time-to-market for electric variants while fragmenting incumbent supplier relationships.
India's BIS and CEA coordination on rural electrification standards is tightening subsidy disbursement criteria for tractor-eligible equipment. Manufacturers must now certify grid-compatibility and charging-protocol compliance before centrally sponsored scheme participation. The 25-40 horsepower segment faces the steepest compliance timeline compression as state-level procurement shifts toward electrified demonstration fleets.
Cooperative bulk procurement is consolidating buyer power across Bangladesh's rice-wheat belt and Indonesia's Java corridor. Aggregated tender processes displace individual dealer relationships, forcing distributors to unbundle financing and after-sales service into separately negotiable contracts. This channel restructuring is most visible in Tamil Nadu's farmer producer organizations, where collective bargaining now dictates warranty-term standardization.
Asia-Pacific Agricultural Tractors Market Segmentation
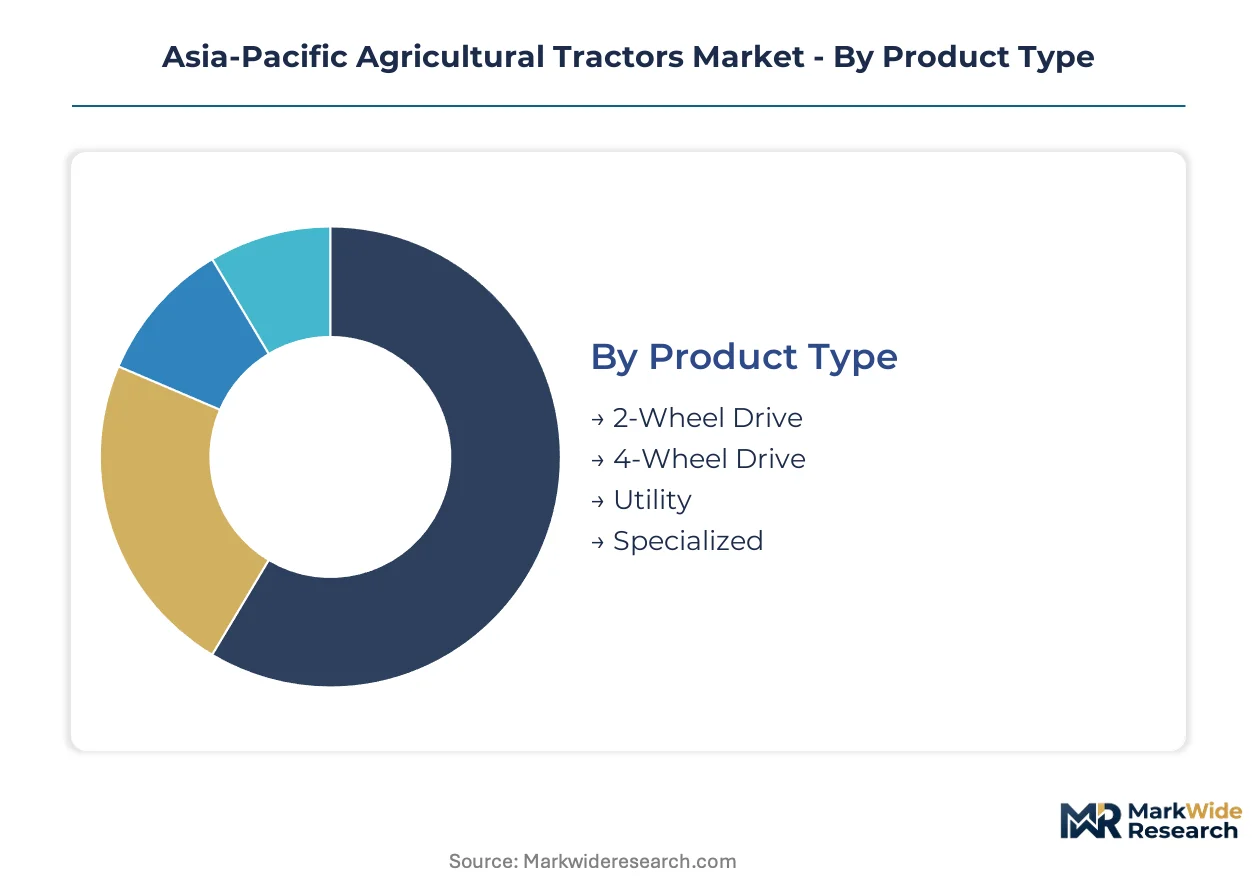
Segmentation reveals how powertrain electrification and cooperative purchasing reshape equipment procurement across the Asia-Pacific agricultural tractors market. Distinct performance requirements by terrain and crop type fragment manufacturer positioning across drivetrain configurations and horsepower tiers.
Product Type:
Substitution pressure from two-wheel tractors and power tillers threatens the compact utility segment most acutely in Southeast Asian smallholdings where capital constraints dominate.
- 2-Wheel Drive:Lightweight chassis configurations dominate Vietnam's Mekong Delta and Bangladesh's rice-wheat belt where saturated paddy soils demand minimal soil compaction. Animal draft substitution accelerates as cooperatives pool acquisition capital for mechanized tillage.
- 4-Wheel Drive:Differential-lock axles and hydrostatic transmissions deliver traction in India's Indo-Gangetic Plains where rice-wheat double-cropping intensifies field moisture retention. Replacement cycles compress as cropping intensity peaks in Punjab and Haryana.
- Utility:Multi-purpose three-point hitch compatibility serves mixed-crop smallholders in Indonesia's Java corridor requiring transport and tillage flexibility.
- Specialized:Narrow-track vineyard configurations and orchard cabs target Japan's terraced highlands and China's Shandong Peninsula fruit belts.
4-Wheel Drive anchors the volume base while Specialized gains share at the steepest rate as precision horticulture expands.
End Use:
Cost tier differentiation separates commodity grain operations from high-value specialty cropping in equipment specification and service bundling.
- Crop Farming:Drawbar and PTO torque ratings align with rice-wheat rotation intensity across India's northern plains. China's Yangtze River Delta manufacturers optimize engine maps for flooded-field torque curves.
- Livestock:Front-loader compatibility and manure-handling PTO implements dominate Australia's Queensland beef operations and New Zealand's dairy belt. Australia's NMI maintains biosecurity washdown standards for cross-farm equipment movement.
- Forestry:Reinforced frames and winch packages serve Indonesia's Kalimantan logging concessions and Malaysia's Sabah timber plantations.
- Horticulture:Ultra-low ground pressure tires and precision seeding attachments target Japan's greenhouse clusters and South Korea's protected vegetable farms.
Crop Farming commands the largest equipment fleet while Horticulture shows the steepest expansion trajectory as protected cultivation intensifies.
Fuel Type:
Application context determines powertrain selection, with grid access and duty cycle predictability driving electrification feasibility.
- Diesel:Compression-ignition architectures retain dominance in remote service territories lacking charging infrastructure across Myanmar's central dry zone and Laos' northern highlands.
- Gasoline:Spark-ignition units serve hobby farms and municipal maintenance fleets in Australia's peri-urban fringe where duty cycles remain intermittent.
- Electric:Battery-swap compatibility under China's MIIT standards unlocks paddy-field adoption in Jiangsu and Zhejiang provinces where grid-hardening subsidies expand operational radius.
- Biofuel:Biodiesel-flexible injection systems align with Indonesia's palm oil mill effluent-to-energy programs and Thailand's cassava ethanol supply chains.
Diesel retains the installed base dominance while Electric climbs the fastest as subsidy eligibility tightens around charging-protocol compliance.
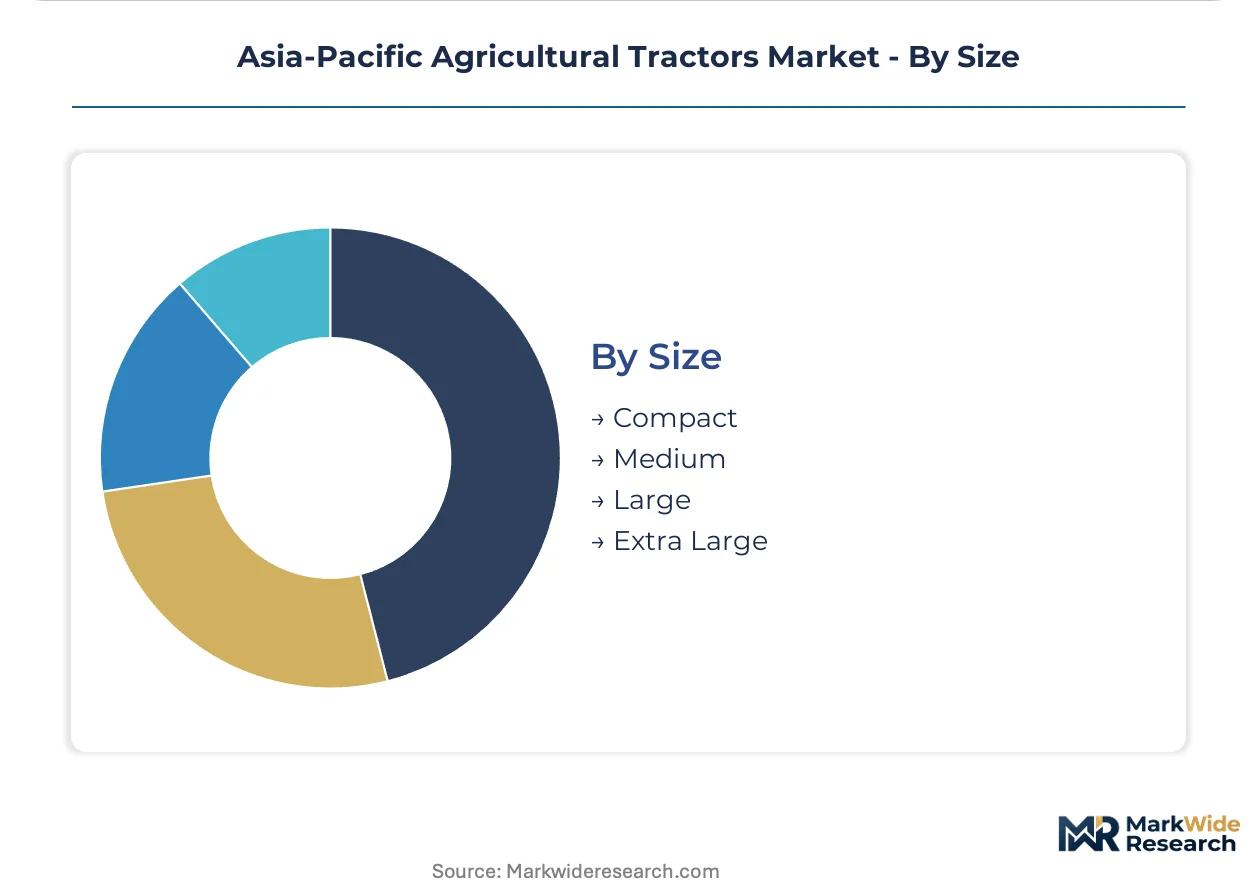
Size:
Customer type fragmentation separates estate-scale buyers from cooperative purchasing pools in specification complexity and financing structure.
- Compact:Sub-40 horsepower hydrostatic transmissions dominate Japan's terraced highlands and Vietnam's Mekong Delta where field dimensions constrain turning radius.
- Medium:40-100 horsepower ranges serve India's farmer producer organizations in Tamil Nadu and Karnataka where collective bargaining now dictates warranty-term standardization.
- Large:100-175 horsepower powershift units target Australia's wheat-sheep belt and China's Northeast Plain state farms where continuous operation economics justify capital intensity.
- Extra Large:175+ horsepower articulated chassis serve corporate sugar estates in Thailand's Central Plains and palm oil plantations in Malaysia's Johor corridor.
Compact size sustains the broadest unit volume while Extra Large captures expanding share as plantation consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for powertrain components shapes procurement patterns across Asia-Pacific, with domestic assembly capacity expansion redirecting trade flows in India and China while Southeast Asian markets remain net importers of finished units.
China
Battery-swap infrastructure deployment accelerates electric tractor adoption in Jiangsu and Zhejiang provinces where paddy-field applications dominate. MIIT Stage IV emission standards and dual carbon goals compel domestic OEMs to retool engine architectures or accelerate electrification roadmaps. Yangtze River Delta manufacturing clusters adopt modular battery-pack architectures that fragment traditional diesel-engine supplier relationships.
India
Rice-wheat double-cropping intensity in Punjab and Haryana compresses replacement cycles for 4-wheel drive units with differential-lock axles. BIS and CEA coordination on rural electrification standards tightens subsidy disbursement criteria under centrally sponsored schemes. Tamil Nadu's farmer producer organizations now dictate warranty-term standardization through collective bargaining in the 40-100 horsepower segment.
Japan
Terraced highland cultivation in Hokkaido and Tohoku sustains compact-size unit demand where field dimensions constrain turning radius. METI grid-hardening subsidies expand battery-electric tractor operational radius beyond current range anxiety thresholds. Domestic manufacturers leverage JIS certification requirements to constrain import access and preserve competitiveness in orchard and vineyard configurations.
Vietnam
Mekong Delta smallholdings drive 2-wheel drive penetration where saturated paddy soils demand minimal soil compaction. Animal draft substitution accelerates as cooperatives pool acquisition capital for mechanized tillage. Compact-size unit penetration remains below replacement-cycle saturation, creating whitespace for orchard-configuration specialists in the southern rice belt.
Indonesia
Java corridor cooperative bulk procurement consolidates buyer power through aggregated tender processes that displace individual dealer relationships. Palm oil mill effluent-to-energy programs align with biodiesel-flexible injection system adoption in Kalimantan logging concessions. State farms in Sumatra's estate belt drive extra-large unit demand as plantation consolidation accelerates.
Asia-Pacific Agricultural Tractors Market Competitive Environment
Concentration sits with vertically integrated engine manufacturers and dominant distribution network operators. The capability gap between high-capital and low-capital producers rotates competitive advantage toward captive foundry capacity and precision agriculture integration specialists. Three archetypes define positioning: engine-integrated cost leaders, precision-agriculture technology integrators, and cooperative-focused distribution specialists. Engineering bandwidth competition and channel restructuring constitute the dominant competitive moves.
Within the engine-integrated tier, Kubota Corporation and Yanmar Co., Ltd. exemplify cost-structure control through in-house powertrain manufacturing depth. Mahindra and Mahindra Ltd. anchors cooperative-focused distribution reach across South Asian markets. Deere and Company occupies a position on the precision-agriculture vector, though premium positioning limits penetration among price-sensitive smallholder bases. These three represent the strategic archetypes reshaping competitive dynamics.
| Leading Market Players |
|---|
| CNH Industrial N.V. |
| AGCO Corporation |
| Kubota Corporation |
| Lovol Heavy Industry Co., Ltd. |
| Iseki & Co., Ltd. |
| Mahindra and Mahindra Ltd. |
| Yanmar Co., Ltd. |
| Daedong Corporation |
| Deere and Company |
| Others |
Value Chain & Pricing Dynamics
Captive foundry capacity in China's Yangtze River Delta manufacturing clusters compresses cost floors for domestic OEMs while straining margin pools for import-dependent assemblers across Southeast Asia. Scale economics in engine block casting and hydrostatic transmission machining rotate pricing power toward vertically integrated producers with in-house powertrain depth.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Asia-Pacific agricultural tractors market. Price differentiation rests on certification grade under China's MIIT Stage IV standards and after-sales service bundling through cooperative procurement channels. Pricing pressure stems from steel and semiconductor input cost volatility, particularly for ECU chipsets and cast iron housings. Smallholder cooperatives in Vietnam and Bangladesh exhibit the highest price sensitivity, while Australia's estate-scale wheat-sheep belt buyers prioritize precision-agriculture integration over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites component flow security for diesel engine blocks sourced from Japan and precision hydraulic pumps manufactured in South Korea. Raw material dependencies center on high-grade steel from China's Baowu Group facilities, aluminum castings from India's Hindalco operations, and rare earth magnets for electric powertrains concentrated in China's Jiangxi province. Single-source vulnerability concentrates in semiconductor ECU chipsets where Taiwan's foundry capacity feeds tier-1 suppliers. Distribution runs through cooperative bulk procurement aggregators in India's Tamil Nadu and Indonesia's Java corridor, displacing traditional dealer networks with tender-based contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific agricultural tractors market represents an early-cycle electrification expansion story, with battery-swap infrastructure deployment in China's paddy-field regions accelerating adoption beyond current replacement-cycle baselines.
For Market Incumbents: Shield margin pools by deepening backward integration into hydrostatic transmission manufacturing and securing captive foundry capacity for cast iron engine housings. Counter emerging electric-only entrants from China's Yangtze River Delta by accelerating JIS certification investment for orchard-configuration specialists in Japan's terraced highlands. Priority lever: channel control through unbundled financing and warranty-term standardization in cooperative procurement territories. For New Entrants and Emerging Players: BIS fast-track certification for grid-compatible electric tractors unlocks subsidy eligibility under India's centrally sponsored schemes before state-level procurement shifts harden. Target Vietnam's Mekong Delta compact-size whitespace where orchard-configuration penetration remains below replacement-cycle saturation. Go-to-market angle: battery-swap subscription models that bypass upfront capital constraints for smallholder cooperatives. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-agriculture integration specialists with CAN-bus telemetry and RTK guidance capabilities. Long-term viability across the analysis window hinges on electrification roadmap credibility and MIIT subsidy qualification. Acquisition target archetype: cooperative-focused distribution networks in South Asia with aggregated tender relationships. Signal to watch: CEA rural electrification standard tightening that compresses diesel-eligible subsidy windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powertrain Manufacturing | Captive engine and transmission production insulates margin pools from steel and semiconductor volatility. |
| Battery-Swap Infrastructure Partnership | MIIT-standardized charging protocols unlock subsidy eligibility for electric tractor adoption in Jiangsu paddy fields. |
| Cooperative Procurement Channel Capture | Aggregated tender relationships in Tamil Nadu farmer producer organizations displace traditional dealer networks. |
| Precision-Agriculture Telemetry Integration | RTK guidance with cloud-based fleet management enables outcome-based service contracts for cooperative buyers. |
| JIS Certification Investment for Orchard Configurations | METI standards compliance preserves domestic market access against import competition in Japan's terraced highlands. |
Study Parameters
A spread of perspectives from tractor OEM platform engineers, cooperative procurement managers in India's farmer producer organizations, aftermarket service heads across Southeast Asia, and BIS certification specialists converged on the working assumptions. Primary fieldwork combined with secondary validation from MIIT emission standard filings, India's PLI scheme disbursement records, customs data on powertrain component trade flows, and SEC disclosures from listed agricultural equipment manufacturers. Bottom-up unit shipment modeling and top-down value aggregation triangulated across the analysis window.
Segmentation dimensions modeled include drivetrain configuration, horsepower tier, fuel type, and cooperative versus individual buyer archetype throughout the forecast period. CAGRs derived from replacement-cycle intensity in rice-wheat double-cropping regions, electrification subsidy eligibility trajectories, and cooperative purchasing consolidation rates. Industry-specific inputs incorporated paddy-field torque curve requirements and grid-hardening subsidy deployment timelines.
Underlying assumptions cover MIIT Stage IV enforcement timelines and CEA rural electrification standard coordination, with deviation risk concentrated in semiconductor supply continuity and steel price volatility. Practitioners should keep alternative scenarios live as battery-swap infrastructure deployment rates and cooperative procurement regulatory frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Agricultural Harvester Market
Agricultural Machinery
France Agricultural Machinery Market
Agricultural Machinery
Mexico Agricultural Machinery Market
Agricultural Machinery
North America Plowing and Cultivating Machinery Market
Agricultural Machinery
Vietnam Agricultural Machinery Market
Agricultural Machinery
Agriculture Drones Market
Agricultural Machinery
Agricultural Electric Tractor Market
Agricultural Machinery
Milking Robots Market
Agricultural Machinery
North America Agricultural Machinery Market
Agricultural Machinery
Vietnam Combine Harvester Market
Agricultural Machinery
China Agricultural Machinery Market
Agricultural Machinery
Brazil Agricultural Machinery Market
Agricultural Machinery
India Agricultural Machinery Market
Agricultural Machinery
Latin America Agricultural Machinery Market
Agricultural Machinery
US Lawn Mowers Market
Agricultural Machinery
Spain Agricultural Machinery Market