
 Wound Healing Market | 2026-2036
Wound Healing Market Size, Share, and Industry Trends Forecast 2026-2036
Wound Healing Market Outlook
Aftermarket service revenue for wound care device maintenance is narrowing as manufacturers shift toward disposable advanced dressing platforms. Smith+Nephew leverages its orthopedic heritage to dominate hydrocolloid and antimicrobial segments across European hospital networks. Mölnlycke Health Care AB anchors its position through vertical integration into surgical tape and film production, controlling raw material quality. ConvaTec Group PLC specializes in ostomy and wound convergence, competing on clinician training programs rather than price alone.
Wound healing encompasses the physiological restoration of skin integrity through hemostasis, inflammation, proliferation, and remodeling phases, with advanced dressings incorporating alginate, silver-ion, or collagen matrices to maintain moist environments and modulate metalloproteinase activity. Chronic wound applications command the deepest margin pools as diabetic foot ulcers and venous leg ulcers require months of sustained intervention with biologic adjuncts. Electroceutical technology represents the fastest-expanding segment, displacing passive dressings in surgical recovery protocols with bioelectric stimulation devices that accelerate re-epithelialization. Hospitals remain the dominant end-user channel, though homecare is gaining share as reimbursement frameworks expand remote monitoring eligibility.
FDA 510(k) premarket notification requirements govern advanced wound dressing approvals in the United States, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence standards for biologic-containing products seeking CE marking. Japan's PMDA enforces QMS ministerial ordinances that delay market entry but reward compliant manufacturers with premium pricing corridors. Stakeholders must monitor evolving antimicrobial resistance surveillance data from WHO and national health agencies to anticipate regulatory restrictions on silver-based formulations.
Market Dynamics
Electroceutical stimulation technology is compressing the traditional dressing replacement cycle, forcing manufacturers to abandon passive moisture-management platforms in favor of active bioelectric systems that command recurring revenue through disposable electrode arrays.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA's abbreviated premarket pathway for substantially equivalent advanced dressings accelerates commercialization timelines for silver-ion and collagen-matrix products, reducing regulatory capital requirements for mid-tier developers.
- Homecare Reimbursement Expansion:Medicare's remote patient monitoring codes now cover wound imaging and bioimpedance spectroscopy, shifting site-of-care economics toward residential settings and extending treatment duration per patient.
- Alginate-Hydrogel Hybridization:Material science advances in ionic crosslinking enable dual-function dressings that simultaneously manage exudate and deliver antimicrobial ions, replacing sequential product layering in hospital protocols.
Market Restraints
- Silver Price Volatility:Fluctuations in London Bullion Market Association silver pricing directly compress margins on antimicrobial dressing lines, with no viable substitution for ionic release kinetics in chronic wound applications.
- EU MDR Clinical Evidence Burden:The Medical Device Regulation's requirement for prospective clinical data on biologic-containing products extends CE marking timelines by 18-24 months and excludes legacy collagen dressings from automatic grandfathering.
- Autologous Skin Graft Competition:Harvest Technologies' point-of-care keratinocyte expansion systems are capturing deep diabetic foot ulcer cases previously committed to long-term advanced dressing regimens.
Strategic Opportunities
- German Outpatient Wound Centers:The country's 1,200 specialized ambulatory clinics operate with diagnosis-related group carve-outs that favor high-material-cost advanced dressings over conservative therapy, creating premium pricing corridors for bioactive platforms.
- Japan's Super-Aged Corridor:METI's regional healthcare consolidation in Shizuoka and Fukuoka prefectures bundles wound care into integrated community care systems, opening sole-supplier contracts for platform vendors with training infrastructure.
- Silicone-Edge Convergence:Peristomal skin protection chemistry from ostomy care is migrating into sacral pressure injury prevention, enabling cross-category portfolio leverage and unified sales call points in long-term care facilities.
Industry Challenges
- Bioelectric Stimulation Training Deficits:Clinician competency in electrode placement and impedance monitoring lags device availability, requiring manufacturers to absorb front-loaded education costs before achieving utilization targets.
- Legacy EHR Integration Friction:Wound measurement apps and connected dressing sensors require HL7 FHIR interoperability investments that strain mid-cap development budgets and delay hospital system procurement approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wound Healing Market |
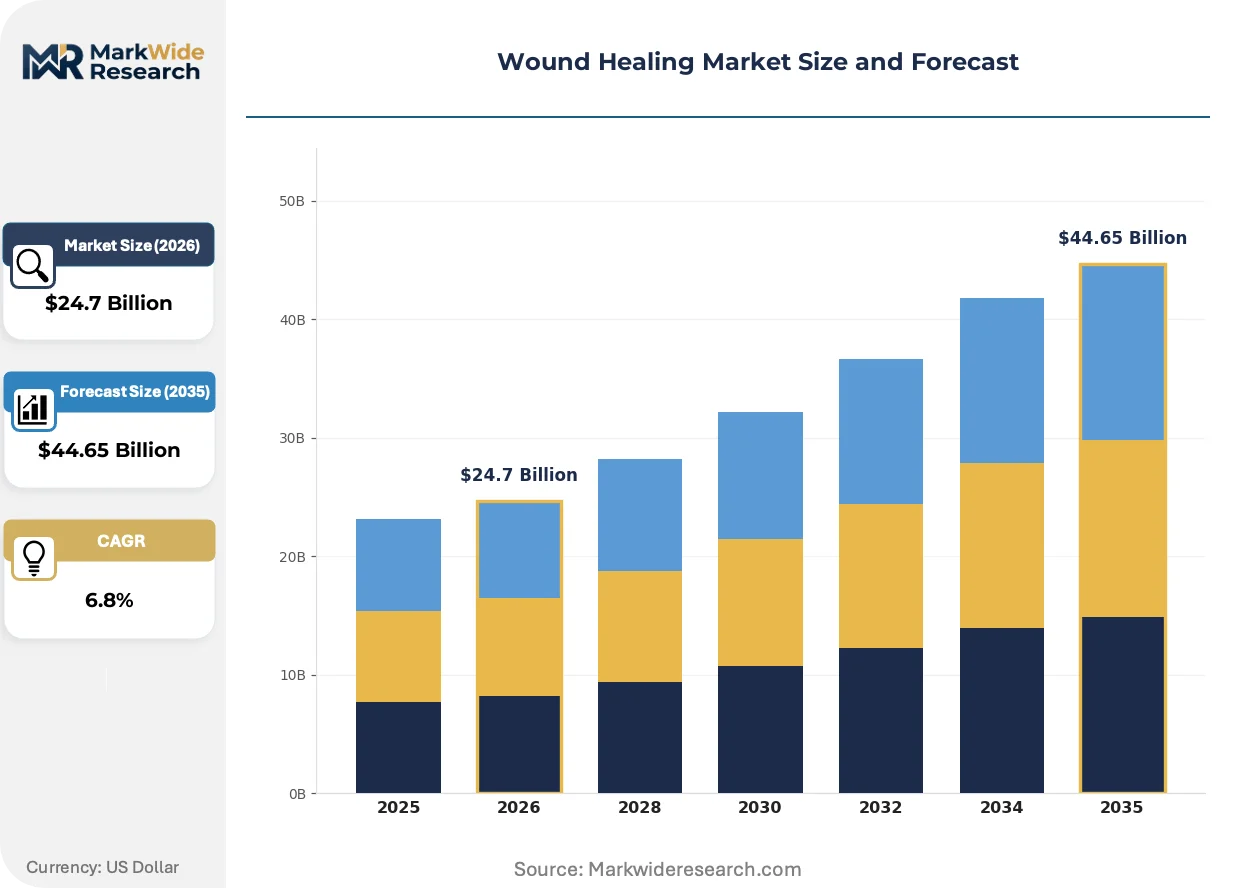
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $44.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Gels, Films, Foams Application: Chronic Wounds, Surgical Wounds, Traumatic Wounds, Burns End User: Hospitals, Homecare, Specialty Clinics, Rehabilitation Centers Technology: Biologics, Antimicrobial, Hydrocolloid, Electroceutical |
| Companies Covered | Solventum, Johnson & Johnson Services, Inc., Smith+Nephew, Mölnlycke Health Care AB, 3M, ConvaTec Group PLC, Cardinal Health, Baxter International, Coloplast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wound Healing Market Strategic Shifts
Active healing modalities are overtaking passive moisture management as the default clinical standard, with reimbursement codes and professional society guidelines simultaneously pivoting toward technologies that demonstrably accelerate re-epithelialization timelines.
Bioelectric stimulation is migrating from post-surgical incision care into chronic wound protocols. Hospital wound centers in the United States are adopting disposable microcurrent-generating dressings for venous leg ulcers, displacing multilayer compression as the sole reimbursed intervention. This migration is compressing the addressable market for hydrocolloid and foam dressings in tertiary care settings.
The EU MDR's 2024 guidance on animal-derived collagen sourcing is forcing manufacturers to document supply chain traceability through slaughterhouse-to-sterilization batch records. German and French notified bodies are rejecting technical files lacking TSE/BSE risk assessments for bovine and porcine matrices. Dressing producers are responding by accelerating recombinant human collagen fermentation programs to eliminate zoonotic regulatory exposure.
Long-term care procurement is consolidating through group purchasing organizations that unbundle dressing selection from individual facility preference. Ontario's 600+ nursing homes now purchase through centralized health authority tenders that specify performance-based outcome metrics rather than brand loyalty. This consolidation is visible across Canadian provinces and is compressing manufacturer margins while rewarding vendors with robust clinical evidence packages.
Wound Healing Market Segmentation
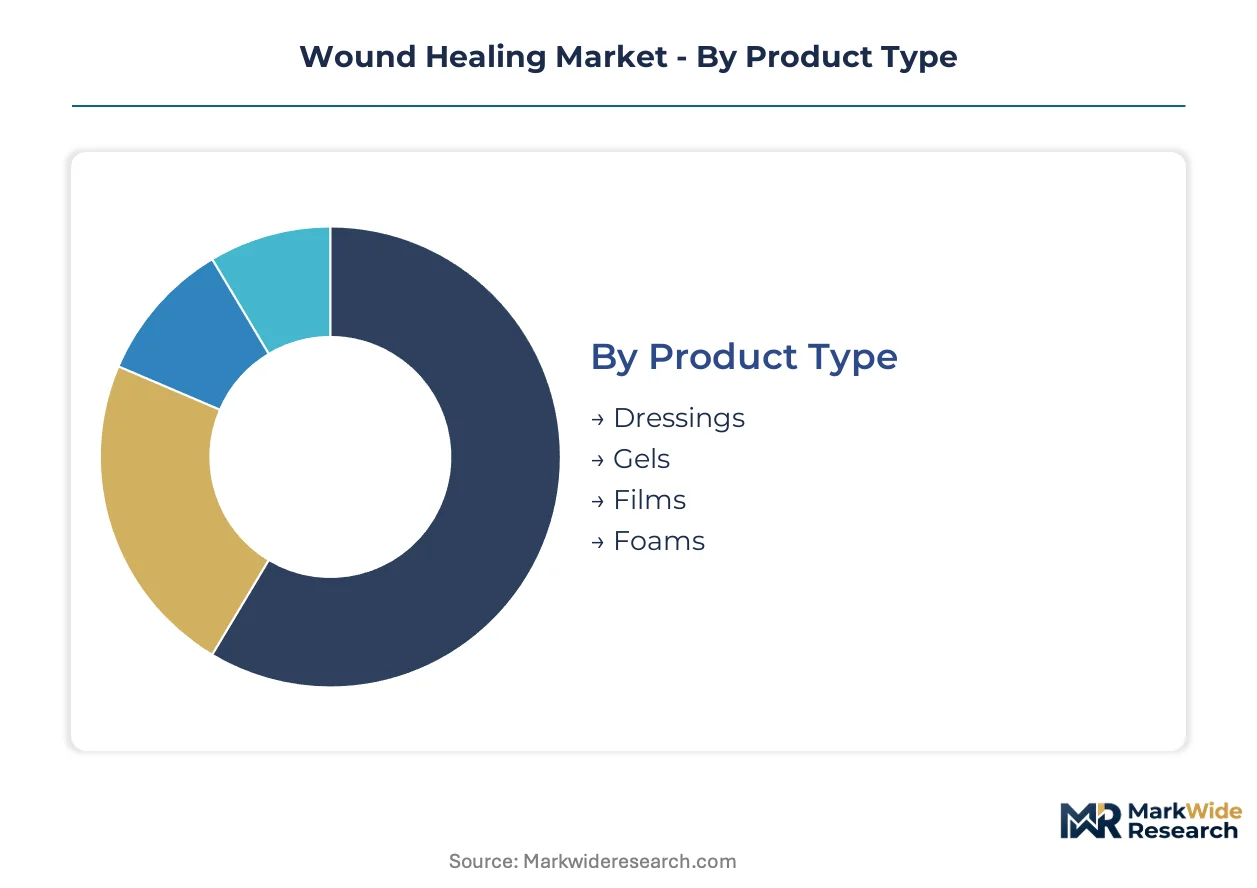
Wound healing product selection hinges on exudate management requirements, infection risk profiles, and reimbursement eligibility across care settings. Segmentation reveals how technology maturity and clinical evidence depth determine pricing power and procurement access.
Product Type:
The use-case spectrum spans moist wound healing maintenance to active biologic delivery, with material composition dictating wear time and clinician labor intensity.
- Dressings:Alginate, hydrocolloid, and foam matrices dominate hospital formularies through established moisture-retention protocols and predictable wear-time economics. Demand concentrates in United States long-term care facilities where Medicare reimbursement favors advanced dressing platforms over gauze-based alternatives.
- Gels:Amorphous hydrogels and sheet formulations enable conformal coverage of irregular wound beds while maintaining autolytic debridement. German outpatient wound centers drive adoption through diagnosis-related group carve-outs that reward high-material-cost interventions.
- Films:Semi-permeable polyurethane barriers protect partial-thickness wounds with minimal exudate, serving post-operative incision care.
- Foams:Open-cell polyurethane structures absorb moderate-to-heavy exudate in pressure injury protocols.
Established volume favors dressings; emerging adoption favors gels.
Application:
Cost tier separation distinguishes acute intervention from chronic management, with reimbursement duration and clinical outcome metrics driving portfolio prioritization.
- Chronic Wounds:Diabetic foot ulcers and venous leg ulcers require sustained multi-month intervention with biologic adjuncts and compression systems. Japan's super-aged prefectures of Shizuoka and Fukuoka anchor demand through integrated community care bundles.
- Surgical Wounds:Post-operative incision care commands premium pricing for antimicrobial and negative-pressure platforms. United States ambulatory surgery centers represent the steepest expansion trajectory as site-of-care migration accelerates.
- Traumatic Wounds:Emergency department protocols favor rapid-application hemostatic dressings with military-derived technology transfer.
- Burns:Specialized burn centers require silver-impregnated and biosynthetic temporary skin substitutes.
Margin concentration sits with chronic applications; volume velocity favors surgical segments.
End User:
Customer type determines training infrastructure requirements and purchasing authority concentration, with procurement consolidation reshaping vendor access.
- Hospitals:Tertiary wound centers maintain the deepest formulary access to biologic and electroceutical platforms through value-analysis committee governance. Ontario's 600-plus nursing homes now purchase through centralized health authority tenders specifying outcome metrics.
- Homecare:Remote patient monitoring eligibility under Medicare codes is shifting site-of-care economics toward residential settings with extended treatment duration.
- Specialty Clinics:Germany's 1,200 ambulatory wound centers operate with procedure carve-outs favoring advanced materials.
- Rehabilitation Centers:Post-acute facilities prioritize cost-per-healed-wound metrics over acquisition price.
Procurement scale favors hospitals; reimbursement expansion favors homecare.
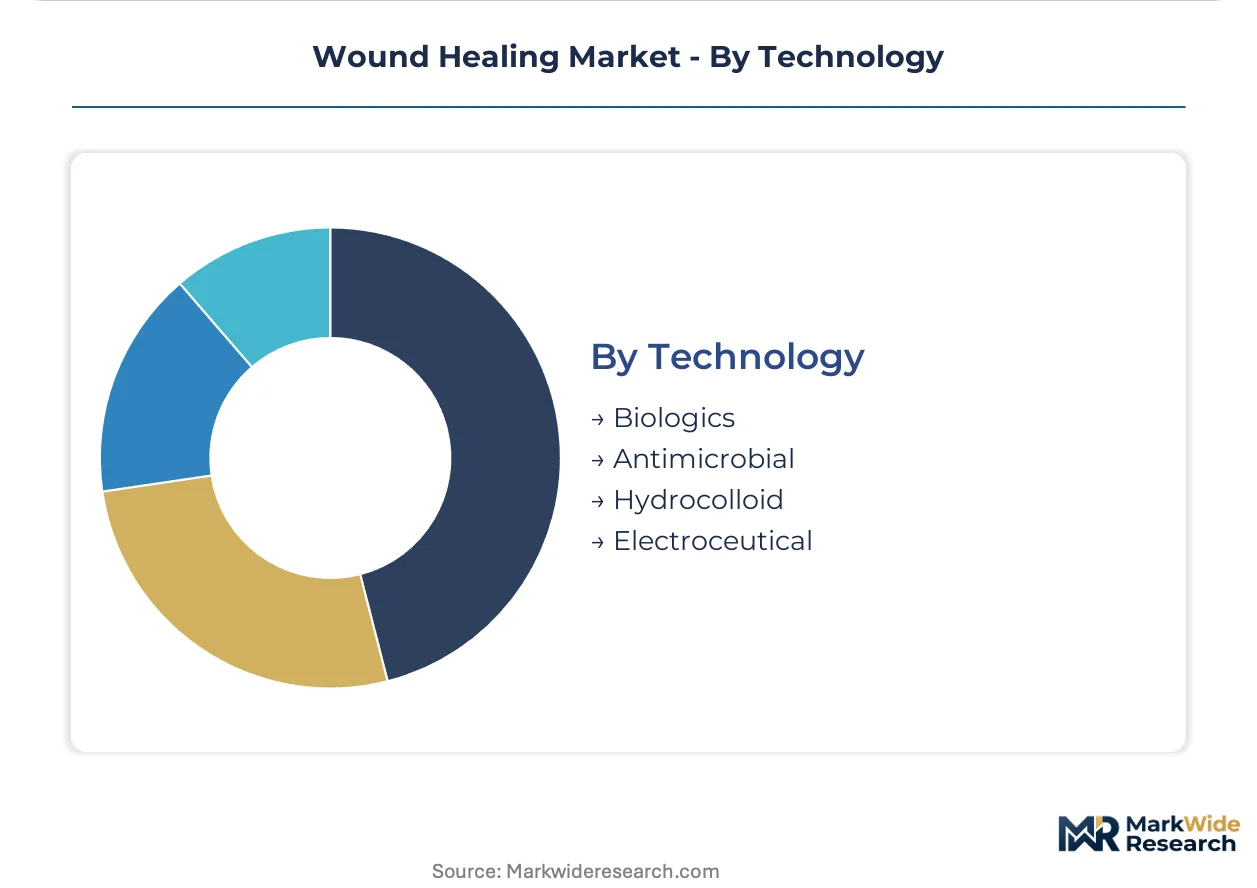
Technology:
Supply concentration in active modalities is displacing passive platforms, with regulatory evidence thresholds determining competitive moat depth.
- Biologics:Collagen matrices, growth factor formulations, and cell-based products command the deepest margin pools through FDA 510(k) and EU MDR clinical evidence requirements. French and German notified bodies enforce TSE/BSE traceability mandates that exclude non-compliant suppliers.
- Electroceutical:Bioelectric stimulation devices with disposable electrode arrays are compressing traditional dressing replacement cycles. United States hospital wound centers adopt microcurrent-generating dressings for venous leg ulcer protocols.
- Antimicrobial:Silver-ion and iodine-releasing platforms face pricing pressure from London Bullion Market Association silver volatility.
- Hydrocolloid:Mature moisture-management technology competes primarily on manufacturing scale and distribution reach.
Evidence burden favors biologics; adoption velocity favors electroceutical platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German outpatient clinics favor high-material-cost advanced dressings through diagnosis-related group carve-outs, while United States long-term care facilities prioritize Medicare-reimbursable platforms over gauze alternatives. Japanese integrated community care systems bundle wound management into regional healthcare consolidation, creating distinct procurement economics.
United States
Medicare's remote patient monitoring codes now cover wound imaging and bioimpedance spectroscopy, shifting site-of-care economics toward residential settings. FDA 510(k) premarket notification requirements govern advanced wound dressing approvals, streamlining commercialization for silver-ion and collagen-matrix products. Hospital wound centers in the Northeast and Midwest maintain the deepest formulary access to biologic and electroceutical platforms through value-analysis committee governance.
Germany
The country's 1,200 specialized ambulatory wound centers operate with procedure carve-outs favoring high-material-cost advanced dressings over conservative therapy. EU Medical Device Regulation imposes stricter clinical evidence standards for biologic-containing products seeking CE marking, extending timelines by 18-24 months. The North Rhine-Westphalia and Bavaria regions concentrate demand through integrated outpatient networks that specify performance-based outcome metrics.
Japan
Shizuoka and Fukuoka prefectures anchor demand through METI's regional healthcare consolidation, bundling wound care into integrated community care systems. PMDA enforces QMS ministerial ordinances that delay market entry but reward compliant manufacturers with premium pricing corridors. The super-aged demographic structure in these prefectures creates sole-supplier contract opportunities for platform vendors with training infrastructure.
United Kingdom
Specialist wound clinics in England drive adoption of alginate-hydrogel hybrid dressings through National Health Service procurement frameworks. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR standards for biologic-containing products, requiring TSE/BSE risk assessments for animal-derived collagen. London and the Southeast concentrate private-pay demand for electroceutical stimulation devices in post-surgical recovery protocols.
France
French notified bodies enforce TSE/BSE traceability mandates for bovine and porcine matrices, excluding non-compliant suppliers from CE marking. The Auvergne-Rhône-Alpes and Île-de-France regions host specialized burn centers requiring silver-impregnated and biosynthetic temporary skin substitutes. Regional health agencies specify antimicrobial resistance surveillance compliance for silver-based formulations in hospital formularies.
Wound Healing Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. The wound healing market structures around diversified medical technology conglomerates with orthopedic and surgical heritage, specialized wound care pure-plays with vertical control over raw materials, and emerging electroceutical technology developers. Strategic archetypes include: integrated platform vendors competing on clinician training infrastructure, material science specialists leveraging captive supply chains, and active modality disruptors displacing passive dressings. Dominant competitive moves encompass M&A activity targeting biologic dressing portfolios and strategic partnerships for EHR interoperability integration.
Within the integrated platform tier, Smith+Nephew and Mölnlycke Health Care AB exemplify divergent strategic positions. Smith+Nephew leverages its orthopedic heritage to anchor hospital network relationships across European markets. Mölnlycke Health Care AB occupies a position defined by backward integration into surgical tape and film production, controlling raw material quality through captive supply. ConvaTec Group PLC represents the convergence specialist archetype, competing on clinician training programs rather than price alone in ostomy-wound crossover applications.
| Leading Market Players |
|---|
| Solventum |
| Johnson & Johnson Services, Inc. |
| Smith+Nephew |
| Mölnlycke Health Care AB |
| 3M |
| ConvaTec Group PLC |
| Cardinal Health |
| Baxter International |
| Coloplast |
| Others |
Value Chain & Pricing Dynamics
Silver price volatility on the London Bullion Market Association directly compresses margins on antimicrobial dressing lines while simultaneously forcing manufacturers to reconfigure sourcing strategies toward ionic-release alternatives. This commodity exposure creates pricing tier spreads that separate silver-impregnated premium platforms from standard hydrocolloid alternatives, with supply chain shape bending toward dual-source mineral procurement and synthetic antimicrobial substitution programs.
Pricing Analysis
Long-term offtake agreements dominate procurement between hospital group purchasing organizations and dressing manufacturers, though spot purchasing persists for emergency stock replenishment. Price differentiation rests on FDA 510(k) clearance tier and clinical evidence depth, with biologic-containing platforms commanding substantial premiums over passive moisture-management alternatives. Cost compression in standard foam and hydrocolloid segments is intensifying because of Ontario-style centralized health authority tenders that unbundle brand preference from facility-level decision rights. Long-term care facilities exhibit the highest price sensitivity due to fixed reimbursement ceilings, while German outpatient wound centers demonstrate the lowest sensitivity through diagnosis-related group carve-outs that reward high-material-cost interventions.
Supply Chain Analysis
Contract manufacturing concentration for advanced wound dressings sits with specialized medical textile producers in Germany, the United States, and Japan, with few CMs holding validated sterile barrier packaging capabilities for biologic-containing products. Raw material dependencies span alginate harvest from Atlantic seaweed beds, recombinant collagen fermentation facilities, and silver-ion masterbatch compounding. Single-source vulnerability concentrates in porcine-derived collagen supply chains facing EU MDR TSE/BSE traceability mandates that exclude non-compliant slaughterhouse networks. Distribution runs through hospital system value-analysis committees in tertiary markets and group purchasing organization aggregators in long-term care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electroceutical stimulation competency gaps separate platform vendors from commodity dressing suppliers, with clinician training infrastructure emerging as the scarcest capability asset for market access. The transition from passive to active healing modalities rewards manufacturers who can absorb front-loaded education costs before achieving utilization targets.
For Market Incumbents: Insulate formulary position by accelerating backward integration into recombinant collagen fermentation to eliminate zoonotic regulatory exposure from EU MDR TSE/BSE mandates. Prioritize capacity addition in Shizuoka and Fukuoka prefectures to capture Japan's super-aged corridor sole-supplier contracts before METI's regional healthcare consolidation finalizes vendor selection. Electroceutical technology entrants threaten hospital wound center relationships previously anchored on hydrocolloid and foam platform familiarity. For New Entrants and Emerging Players: Build out bioelectric stimulation training infrastructure as the primary white-space entry mechanism, targeting United States ambulatory surgery centers where site-of-care migration accelerates and incumbent relationships remain unsettled. Germany's 1,200 outpatient wound centers offer the most penetrable geography through procedure carve-outs that favor novel technology adoption. Lead with disposable electrode array economics that demonstrate cost-per-healed-wound superiority over multilayer compression protocols. For Investors and Strategic Acquirers: The market sits at a modality-transition phase that favors electroceutical technology developers with FDA 510(k) clearances and hospital system pilot data. Long-term viability across the analysis window hinges on reimbursement code expansion for remote patient monitoring and bioimpedance spectroscopy coverage. Acquisition target archetype: mid-cap specialists with proprietary ionic crosslinking patents for alginate-hydrogel hybrid platforms. Monitor Medicare remote patient monitoring code revisions as the critical inflection signal for homecare economics shift.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Electroceutical Platform | Accelerates commercialization timelines for bioelectric stimulation devices competing against passive dressings. |
| CE Marking Pathway Under EU MDR | Unlocks German outpatient wound center access through biologic-containing product clinical evidence requirements. |
| Hospital System Partnership for Training Infrastructure | Addresses clinician competency deficits in electrode placement that lag device availability. |
| Software Companion Development for EHR Integration | Resolves HL7 FHIR interoperability friction that delays procurement approvals from value-analysis committees. |
| Reimbursement Strategy for Remote Patient Monitoring | Captures Medicare code expansion for wound imaging and bioimpedance spectroscopy in residential settings. |
Study Parameters
A standing panel of wound care clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, EU MDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement records. This study combined primary interviews with industry stakeholders and secondary source triangulation through bottom-up product-level modeling and top-down market sizing reconciliation.
Scenario-bracketing framed demand projections across the modeling period, with segmentation dimensions spanning product type, application severity tier, end-user channel, and technology modality. CAGRs were derived from fitted growth curves against historical adoption patterns and reimbursement elasticity estimates. Industry-specific forecast inputs incorporated silver price volatility assumptions and EU MDR clinical evidence timeline impacts on biologic-containing product commercialization.
Practitioners should monitor antimicrobial resistance surveillance data from WHO and national health agencies, silver price movements on the London Bullion Market Association, and Medicare remote patient monitoring code revisions for early signals of forecast deviation. Quarterly review of FDA 510(k) clearance velocity, EU notified body technical file rejection rates, and Japanese PMDA QMS ministerial ordinance enforcement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Irrigation Devices Market
Wound Care
Asia Pacific Wound Care Biologics Market
Wound Care
Venous Leg Ulcer (VLU) Treatment Market
Wound Care
Vascular Ulcer Treatment Market
Wound Care
Advanced Wound Care Market
Wound Care
Europe Advanced Wound Care Market
Wound Care
Foam Dressing Market
Wound Care
Pressure Bandages Market
Wound Care
Non-Invasive Surgical Wound Closure Market
Wound Care
Advanced Wound Care and Dressings Market
Wound Care
Wound Cleanser Products Market
Wound Care
North America Wound Care Management Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
Asia Pacific Wound Care Market
Wound Care
Moist Wound Dressings Market
Wound Care
Burn Care Centers Market