
 Germany Respiratory Devices Market | 2026-2036
Germany Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Respiratory Devices Market Foresight
The EU Green Deal's push for circular medical equipment procurement is repositioning how hospitals evaluate device lifecycles and refurbishment options. Drägerwerk AG leverages its Lübeck manufacturing base to sustain domestic ventilator production with vertically integrated component sourcing. Koninklijke Philips NV anchors its European respiratory portfolio through specialized sleep therapy platforms distributed via German home care networks. Fisher & Paykel Healthcare Limited competes on humidification technology leadership integrated into acute and chronic ventilation systems.
Germany respiratory devices comprise mechanical, pneumatic, and electronic systems engineered to assist, monitor, or replace spontaneous breathing across pressure ranges typically spanning 5–40 cm H₂O, with flow delivery precision measured in liters per minute. These systems serve acute critical care, chronic disease management, and diagnostic sleep medicine applications in clinical and domestic settings. Ventilators and CPAP devices command the dominant installed base across German hospital intensive care units, while oxygen concentrators represent the fastest-expanding category as home care providers build decentralized respiratory therapy infrastructure. Inhalers and nebulizers retain mature volume positions within pharmacy and retail channels, though margin pools increasingly shift toward connected-dose monitoring technologies.
Germany's Federal Institute for Drugs and Medical Devices (BfArM) enforces MDR transition timelines that compress certification windows for legacy respiratory products, while the German Social Code (SGB V) shapes reimbursement velocity for home oxygen and sleep therapy prescriptions. KBA-equivalent transport safety protocols govern portable oxygen concentrator mobility approvals, and DIN standards specify electrical safety and electromagnetic compatibility for devices deployed in residential care environments. Stakeholders must monitor how BfArM's post-market surveillance intensification alters warranty and service obligations across distributed device fleets.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing certification timelines for Class IIa and above respiratory equipment, forcing manufacturers to accelerate conformity assessments while home care providers simultaneously expand portable oxygen concentrator networks across Bavaria and North Rhine-Westphalia.
Growth Catalysts
- Ambulatory diagnostic pathways:Urban hospital networks in Berlin and Hamburg are shortening patient time-to-treatment for sleep apnea, expanding CPAP device demand through streamlined referral protocols.
- EU Green Deal procurement mandates:Circular medical equipment requirements are repositioning hospital evaluation criteria toward device lifecycles and refurbishment options.
- Decentralized respiratory therapy infrastructure:Home care providers are building distributed oxygen concentrator fleets to serve chronic disease patients outside acute settings.
Market Restraints
- MDR conformity assessment bottlenecks:BfArM's compressed certification windows for legacy respiratory products are creating regulatory friction and extending time-to-market for updated devices.
- Semiconductor input volatility:Flow sensors and pressure transistors face supply concentration risk from East Asian foundries, disrupting ventilator production schedules.
- Technical limitation in portable power:Battery energy density constraints restrict continuous oxygen delivery duration for ambulatory concentrator users.
Strategic Opportunities
- Connected-dose monitoring technologies:Inhaler and nebulizer manufacturers can capture margin pools shifting from hardware to data-enabled adherence platforms.
- Rural home care penetration:Mecklenburg-Vorpommern and Saxony-Anhalt present underpenetrated geographies for sleep therapy device distribution networks.
- Humidification-ventilation convergence:Integration of heated humidification with acute ventilation systems creates technology differentiation in intensive care procurement.
Industry Challenges
- BfArM post-market surveillance intensification:Warranty and service obligations across distributed device fleets are expanding compliance costs for manufacturers.
- KBA-equivalent transport safety certification:Portable oxygen concentrator mobility approvals require specialized testing protocols that extend product development timelines.
- DIN electromagnetic compatibility standardization:Residential care deployment specifications are forcing redesign cycles for devices originally engineered for clinical environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Respiratory Devices Market |
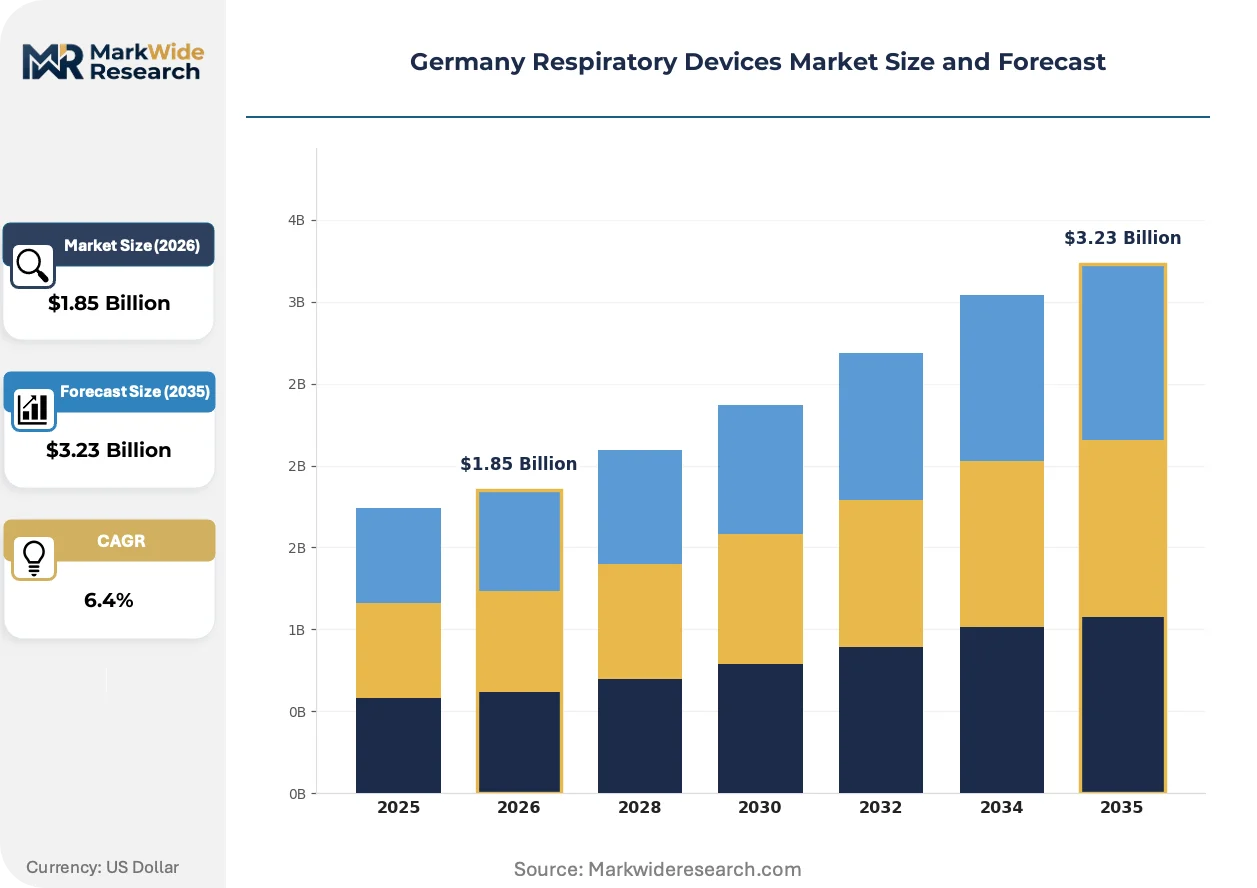
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, Oxygen Concentrators, CPAP Devices, Ventilators Therapy Area: Chronic Obstructive Pulmonary Disease, Asthma, Sleep Apnea, Cystic Fibrosis, Pulmonary Fibrosis End User: Hospitals, Clinics, Home Care Providers, Rehabilitation Centers, Specialty Clinics Distribution Channel: Pharmacies, Online Retailers, Medical Supply Stores, Direct Sales, Healthcare Facilities |
| Companies Covered | Drägerwerk AG, Geratherm Respiratory GmbH, DeVilbiss Healthcare GmbH, Fisher & Paykel Healthcare Limited, Koninklijke Philips NV, Medtronic, GlaxoSmithKline PLC, Invacare Corporation, General Electric Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Respiratory Devices Market Shifts & Advancements
Connected respiratory platforms are reshaping competitive positioning across German clinical and home care channels, with data-enabled adherence monitoring and remote patient management emerging as core differentiators.
Closed-loop oxygen delivery systems are integrating pulse oximetry feedback with automated flow adjustment to maintain target saturation ranges without manual intervention. Intensive care units in university hospitals across Munich and Cologne are piloting these platforms to reduce nursing workload and improve weaning outcomes. The technology is integrating algorithmic control into mechanical ventilation, compressing the gap between critical care and step-down unit capabilities.
BfArM's MDR transition enforcement is tightening technical documentation requirements for legacy respiratory products still holding pre-2021 certificates. Manufacturers must resubmit clinical evidence packages or withdraw devices from the German market, with sleep therapy platforms facing the steepest re-certification burdens due to software-as-medical-device classifications. Small and mid-sized device firms are responding by consolidating regulatory affairs functions and outsourcing notified body interactions.
Hospital procurement committees are unbundling device acquisition from service contracts, separating capital expenditure decisions from multi-year maintenance agreements. This pattern is displacing traditional bundled pricing models in North Rhine-Westphalia's hospital networks, where purchasing cooperatives now negotiate equipment and service lines independently. The shift is most visible among municipal hospital systems seeking operational flexibility amid budget consolidation pressures.
Germany Respiratory Devices Market Segmentation
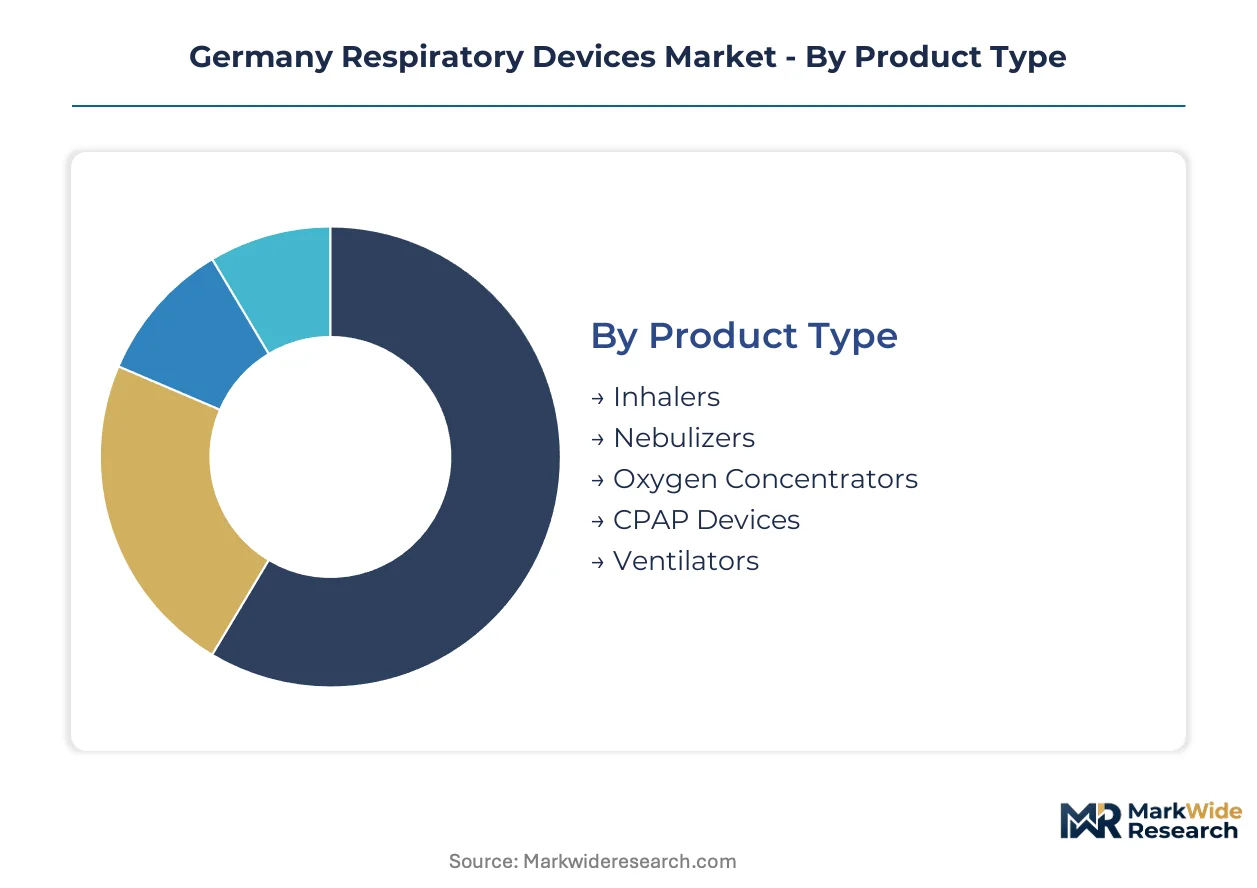
German respiratory device procurement patterns diverge sharply across clinical versus domestic settings, with reimbursement pathways under SGB V and MDR compliance tiers creating distinct margin architectures. Manufacturers must align product portfolios to these segment-specific regulatory and pricing pressures.
Product Type:
Supply concentration clusters around acute care platforms with the highest certification barriers, while decentralized home care demand pulls component sourcing toward portable, low-power architectures.
- Ventilators:Electromechanical systems delivering pressure-controlled or volume-controlled breath support across 5–40 cm H₂O ranges with integrated alarm management. Demand concentrates in university hospital ICUs across Berlin and Munich as BfArM intensifies post-market surveillance obligations for Class IIb devices.
- CPAP Devices:Continuous positive airway pressure platforms maintaining patent upper airways via 4–20 cm H₂O pressure delivery with heated humidification integration. Bavarian home care networks are expanding device fleets as ambulatory sleep diagnostics compress time-to-treatment pathways.
- Oxygen Concentrators:Pressure swing adsorption systems generating 90–96% oxygen purity at 1–10 L/min flow rates. North Rhine-Westphalia providers are building distributed fleets for chronic disease management outside acute settings.
- Inhalers:Metered-dose and dry-powder delivery systems for bronchodilator and corticosteroid administration. Pharmacy channels retain volume leadership though margin pools shift toward connected-dose monitoring platforms.
- Nebulizers:Compressor and mesh-based aerosol generation devices for medication delivery to lower airways. Pediatric and geriatric applications in rehabilitation centers sustain replacement demand cycles.
Ventilators and CPAP devices absorb the bulk of installed capacity; oxygen concentrators are expanding most quickly across decentralized care networks.
Therapy Area:
Reimbursement velocity under Germany's statutory health insurance system varies dramatically by diagnostic category, shaping manufacturer investment in clinical evidence packages.
- Sleep Apnea:Obstructive and central sleep-disordered breathing requiring positive airway pressure or adaptive servo-ventilation intervention. Urban hospital networks in Hamburg and Cologne are streamlining diagnostic-to-treatment protocols, expanding device demand through shortened referral pathways.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation managed through long-term oxygen therapy and non-invasive ventilation. Home care infrastructure investments in Saxony and Baden-Württemberg are pulling concentrator and ventilator demand toward domestic settings.
- Asthma:Reversible airway obstruction addressed through inhaled corticosteroid and bronchodilator therapy. Pharmacy and retail channels dominate volume distribution though adherence monitoring technologies are capturing emerging margin pools.
- Cystic Fibrosis:Genetic mucociliary clearance disorder requiring nebulized mucolytics and airway clearance devices. Specialized centers in Heidelberg and Berlin concentrate prescriber influence and high-acuity device procurement.
- Pulmonary Fibrosis:Interstitial lung disease with progressive hypoxemia managed through supplemental oxygen and eventual ventilatory support. Palliative care integration in municipal hospital networks shapes late-stage device deployment patterns.
Sleep Apnea and COPD together anchor reimbursement volume; Sleep Apnea is climbing the fastest as ambulatory diagnostic penetration deepens.
End User:
Procurement authority fragmentation across German healthcare tiers creates distinct contracting dynamics, from centralized hospital purchasing cooperatives to fragmented home care provider networks.
- Hospitals:Acute care facilities with centralized biomedical engineering and intensive care capabilities. North Rhine-Westphalia purchasing cooperatives are unbundling device acquisition from service contracts, separating capital expenditure from multi-year maintenance agreements.
- Home Care Providers:Decentralized respiratory therapy services managing chronic patient populations in residential settings. Bavarian and Baden-Württemberg networks are building portable oxygen concentrator fleets to serve patients outside institutional environments.
- Clinics:Outpatient facilities providing diagnostic and therapeutic respiratory services without overnight admission. Pulmonary function testing and sleep study centers in urban clusters drive diagnostic device demand.
- Rehabilitation Centers:Post-acute facilities delivering weaning and respiratory muscle training programs. Weaning protocols in cardiorespiratory rehabilitation units sustain ventilator and secretion management device demand.
- Specialty Clinics:Focused practices in sleep medicine, pulmonology, or allergy/immunology with concentrated prescriber influence. Berlin and Munich sleep centers anchor CPAP device prescription volume through direct distribution relationships.
Hospitals retain the dominant procurement value; Home Care Providers are gaining share fastest as SGB V reimbursement shifts toward ambulatory care.
Distribution Channel:
Channel configuration reflects the tension between regulatory oversight requirements and patient convenience expectations, with MDR traceability obligations favoring established healthcare supply chains over direct-to-consumer models.
- Healthcare Facilities:Direct procurement by hospitals, clinics, and integrated delivery networks through tender and framework agreements. Municipal hospital systems in North Rhine-Westphalia are consolidating purchasing authority to extract volume discounts.
- Pharmacies:Community and hospital pharmacy networks with prescription fulfillment and patient counseling obligations. Inhaler and nebulizer volume concentrates here though connected-device margins are shifting toward platform providers.
- Medical Supply Stores:Specialized durable medical equipment retailers with home care service capabilities. Oxygen concentrator and CPAP device distribution in rural Mecklenburg-Vorpommern depends on this channel for patient training and support.
- Online Retailers:E-commerce platforms with expanding presence in consumables and accessories. Regulatory constraints on prescription device sales limit penetration in core therapeutic categories.
- Direct Sales:Manufacturer-to-provider relationships bypassing intermediaries for high-value capital equipment. Ventilator and ICU platform procurement increasingly employs this channel for service integration.
Healthcare Facilities and Pharmacies together dominate transaction volume; Direct Sales is expanding most quickly as manufacturers seek service contract attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's respiratory device production concentrates in northern industrial clusters while consumption spreads across decentralized home care networks in southern and western states. This geographic split shapes logistics infrastructure and regulatory enforcement patterns.
Bavaria
Munich anchors diagnostic device demand as university hospitals pilot closed-loop oxygen delivery systems. BfArM's MDR transition timelines compress certification windows for sleep therapy platforms distributed through Bavarian home care networks. Nuremberg-based medical supply stores build patient training capacity for portable oxygen concentrator fleets.
North Rhine-Westphalia
Cologne and Düsseldorf hospital purchasing cooperatives unbundle device acquisition from service contracts, separating capital expenditure from maintenance agreements. DIN electromagnetic compatibility standards govern residential deployment specifications for devices originally engineered for clinical environments. The Ruhr industrial corridor sustains component sourcing for ventilator manufacturing.
Baden-Württemberg
Stuttgart medical technology clusters integrate heated humidification with acute ventilation systems for intensive care differentiation. KBA-equivalent transport safety protocols extend product development timelines for portable oxygen concentrator mobility approvals. Freiburg rehabilitation centers drive weaning protocol device demand through cardiorespiratory programs.
Berlin-Brandenburg
Berlin sleep centers anchor CPAP prescription volume through direct distribution relationships with specialty clinics. The EU Green Deal's circular procurement mandates reposition hospital evaluation criteria toward device lifecycles and refurbishment options. Brandenburg home care providers expand into rural peripheries as SGB V reimbursement shifts toward ambulatory settings.
Hamburg
Hamburg's streamlined diagnostic-to-treatment protocols expand CPAP device demand through shortened referral pathways in urban hospital networks. BfArM post-market surveillance intensification alters warranty obligations across distributed device fleets in the metropolitan region. The port city's logistics infrastructure supports medical device import distribution to northern European markets.
Germany Respiratory Devices Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with established notified body relationships and specialized respiratory pure-plays with technology differentiation. Market positions stratify across three tiers: integrated critical care platform providers, sleep therapy specialists with home care channel depth, and component-focused humidification technology developers. Consolidation pressure intensifies as MDR compliance costs favor scaled regulatory affairs functions over fragmented operations.
Among Germany-based manufacturers, Drägerwerk AG and Geratherm Respiratory GmbH exemplify the vertically integrated domestic production archetype, with Lübeck manufacturing sustaining captive component sourcing for ventilator platforms. Koninklijke Philips NV and Fisher & Paykel Healthcare Limited represent the multinational specialist tier, anchoring European respiratory portfolios through sleep therapy distribution networks and humidification-ventilation convergence technologies respectively.
| Leading Market Players |
|---|
| Drägerwerk AG |
| Geratherm Respiratory GmbH |
| DeVilbiss Healthcare GmbH |
| Fisher & Paykel Healthcare Limited |
| Koninklijke Philips NV |
| Medtronic |
| GlaxoSmithKline PLC |
| Invacare Corporation |
| General Electric Company |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between Class IIb ventilators and unclassified consumables splits pricing power along MDR compliance lines, with notified body scarcity inflating premium-tier acquisition costs while commodity inhaler margins compress under pharmacy reimbursement ceilings. This divergence channels supply chain investment toward vertically integrated production clusters that can absorb regulatory overhead, leaving fragmented component vendors exposed to price-down pressure from consolidated hospital purchasing cooperatives.
Pricing Analysis
Margin tightening in home care oxygen concentrators reflects SGB V reimbursement velocity caps, while acute care ventilator pricing holds firmer under bundled service contract structures. Three-tier pricing structure across premium, standard, and economy levels separates university hospital ICU platforms from municipal hospital step-down units and home care portable devices. Price differentiation hinges on MDR certification tier and after-sales service integration, with Baden-Württemberg hospital systems exhibiting lowest price sensitivity due to capital budget autonomy and Saxony home care providers most sensitive due to thin per-patient margins.
Supply Chain Analysis
Refurbishment flows for legacy ventilator fleets are accelerating under EU Green Deal circular procurement mandates, with Drägerwerk AG's Lübeck facility capturing remanufactured device margins that bypass raw material exposure. Component sourcing draws from Germany for precision pneumatics, Taiwan for flow sensors, and China for battery cells, creating tariff vulnerability at the semiconductor interface. Single-source concentration in East Asian foundries for pressure transistors threatens ventilator production schedules, while distribution runs through healthcare facilities and direct sales channels that prioritize service contract attachment over transactional hardware margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's respiratory device sector is transitioning from pneumatic-mechanical platforms to algorithmic closed-loop systems, with pulse-oximetry-integrated oxygen delivery displacing manual flow adjustment in university hospital pilots.
For Market Incumbents: Acquire regulatory affairs capabilities to compress MDR conformity assessment timelines for legacy device recertification. Consolidate notified body relationships and backward-integrate into flow sensor production to offset East Asian supply concentration risk. Defend against software-as-medical-device entrants by embedding algorithmic control into hardware platforms before pure-play AI diagnostics capture ICU procurement committees.
For New Entrants and Emerging Players: Begin with connected-dose monitoring platforms for inhaler adherence, where pharmacy channel fragmentation creates white-space for data-enabled service layers. Target rural Mecklenburg-Vorpommern home care networks for portable oxygen concentrator distribution, exploiting underpenetrated geography with direct-to-provider sales models that bypass established medical supply store relationships.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap respiratory pure-plays with MDR transition completion and sleep therapy platform installed base. Long-term viability favors firms bridging acute-to-home care device convergence with software companion development. Monitor BfArM post-market surveillance enforcement intensity as inflection signal for warranty cost escalation and service obligation expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Conformity Assessment Acceleration | Compressed certification windows favor scaled regulatory affairs functions over fragmented competitors. |
| Closed-Loop Oxygen Delivery Development | Munich and Cologne university hospital pilots validate algorithmic control integration. |
| Hospital System Partnership Expansion | North Rhine-Westphalia purchasing cooperatives unbundle device and service contracting. |
| Software Companion Platform Launch | Connected-dose monitoring captures adherence data margins beyond hardware commoditization. |
| Reimbursement Strategy Investment | SGB V pathway optimization accelerates home oxygen and sleep therapy prescription velocity. |
Research Methodology
Document review covered BfArM device registrations, DIN electromagnetic compatibility standards, and SGB V reimbursement schedules, complemented by interviews with hospital biomedical engineers, home care provider network managers, GPO contracts specialists, and notified body technical assessors. Secondary validation drew from EU MDR implementation guidance, hospital procurement database extracts, and medical device trade flow records. Bottom-up installed base modeling and top-down expenditure allocation triangulated segment-level demand estimates.
Cross-referencing historical adoption curves against clinical panel input shaped the projection framework across the analysis window. Segmentation dimensions modeled include product type, therapy area, end user procurement tier, and distribution channel regulatory intensity. CAGRs derived from elasticity-adjusted demand curves incorporating MDR transition friction coefficients and SGB V reimbursement velocity parameters, with oxygen concentrator fleet expansion and sleep apnea diagnostic penetration as primary volume drivers.
Underlying measurement precision varies by segment; ventilator and CPAP device estimates carry tighter precision due to centralized procurement visibility than inhaler retail audit approximations. Forecasts reflect assumptions about MDR enforcement continuity and semiconductor supply normalization. Practitioners should monitor BfArM post-market surveillance bulletin frequency and KBA transport safety protocol amendments for early signals of compliance cost inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
BFS Syringes Market
Medical Devices
Chest Drainage System Market
Medical Devices
Compression Therapy Devices Market
Medical Devices
United Kingdom Drug Delivery Devices Market
Medical Devices
Transcatheter Aortic Valve Implantation (TAVI) Market
Medical Devices
Arthroscopy Devices Market
Medical Devices
Nasal Implant Market
Medical Devices
Medical Device and Accessories Market
Medical Devices
Global Foot Orthotic Insoles Market
Medical Devices
Portable Ultrasound Devices Market
Medical Devices
Lancing Devices and Lancets Market
Medical Devices
Electrical Stimulation Devices (Esds) Market
Medical Devices
Cardiopulmonary Bypass System Market
Medical Devices
Anesthesia Laryngeal Masks Market
Medical Devices
Ingestible Thermometers Market
Medical Devices
India Drug Delivery Devices Market