
 Blood Clotting Accelerant Market | 2026-2036
Blood Clotting Accelerant Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Clotting Accelerant Market Outlook
Trauma care is rebalancing the end-use vertical mix as battlefield medicine protocols and civilian mass-casualty preparedness expand procurement of rapid-acting hemostatics. Baxter International Inc leverages its hospital distribution network to sustain channel control across North American trauma centers. Pfizer Inc competes through recombinant factor specialization, while CSL Ltd anchors plasma-derived portfolios with vertical integration into fractionation facilities.
Blood clotting accelerants comprise biologically active proteins and peptide formulations, typically thrombin or fibrinogen concentrates with specific international unit potency per milligram, designed to catalyze fibrin formation and achieve hemostasis within seconds to minutes of topical or intravenous application. Recombinant factors represent the fastest-growing product category as biotechnology yields higher purity and reduced immunogenicity compared with plasma-derived alternatives. Surgical procedures generate the largest application volume, though trauma care commands premium pricing due to time-critical efficacy requirements and military procurement standards.
FDA biologics licensing requirements and EMA's advanced therapy medicinal products framework govern recombinant factor approvals, while ISO 13485 quality management standards shape manufacturing compliance for hemostatic device-drug combinations. These regulatory layers extend development timelines but also create durable barriers against commoditization. Stakeholders must monitor emerging biosimilar pathways and evolving military procurement specifications as dual-use demand reshapes competitive positioning.
Market Dynamics
Recombinant biotechnology is compressing development timelines while fragmenting the supplier base between plasma-dependent incumbents and biotech entrants. Military procurement specifications for rapid hemostasis are simultaneously elevating efficacy standards and shortening vendor qualification cycles.
Growth Catalysts
- Battlefield medicine protocols:US military trauma networks mandate 3-minute hemostasis benchmarks, creating procurement pull for next-generation thrombin formulations in combat support hospitals.
- EMA advanced therapy medicinal products framework:Accelerated pathways for recombinant factors reduce regulatory friction for European biotech developers seeking orphan drug designation.
- Civilian mass-casualty preparedness:Urban trauma centers in high-threat metropolitan areas stockpile rapid-acting hemostatics under federal disaster readiness grants.
Market Restraints
- Plasma supply concentration:Fractionation-grade plasma concentrates in US and European collection networks, exposing manufacturers to donor pool volatility and viral screening cost spikes.
- FDA biologics licensing complexity:Immunogenicity testing requirements extend recombinant thrombin approval timelines by 18-24 months versus small-molecule benchmarks.
- Autologous blood salvage systems:Intraoperative cell salvage technology reduces allogeneic clotting factor dependence in elective cardiac and orthopedic procedures.
Strategic Opportunities
- Pre-hospital emergency medicine:Underpenetrated ambulance and tactical combat casualty care segments present white space for freeze-dried, room-temperature stable formulations.
- Japan PMDA regenerative medicine framework:Expedited review pathways for combination hemostat-device products attract developers seeking Asian market entry.
- Point-of-care diagnostic convergence:Integration with viscoelastic coagulation analyzers enables algorithmic dosing and outcome-based reimbursement models.
Industry Challenges
- Bioprocess engineering talent scarcity:Mammalian cell culture expertise for recombinant factor production concentrates in Boston and Basel clusters, constraining scale-up capacity.
- ISO 13485 device-drug combination compliance:Dual quality system requirements for hemostatic matrices with embedded thrombin extend certification timelines and audit costs.
- Cold chain integrity:Lyophilized product stability advantages are offset by reconstitution complexity in field conditions without sterile water access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Clotting Accelerant Market |
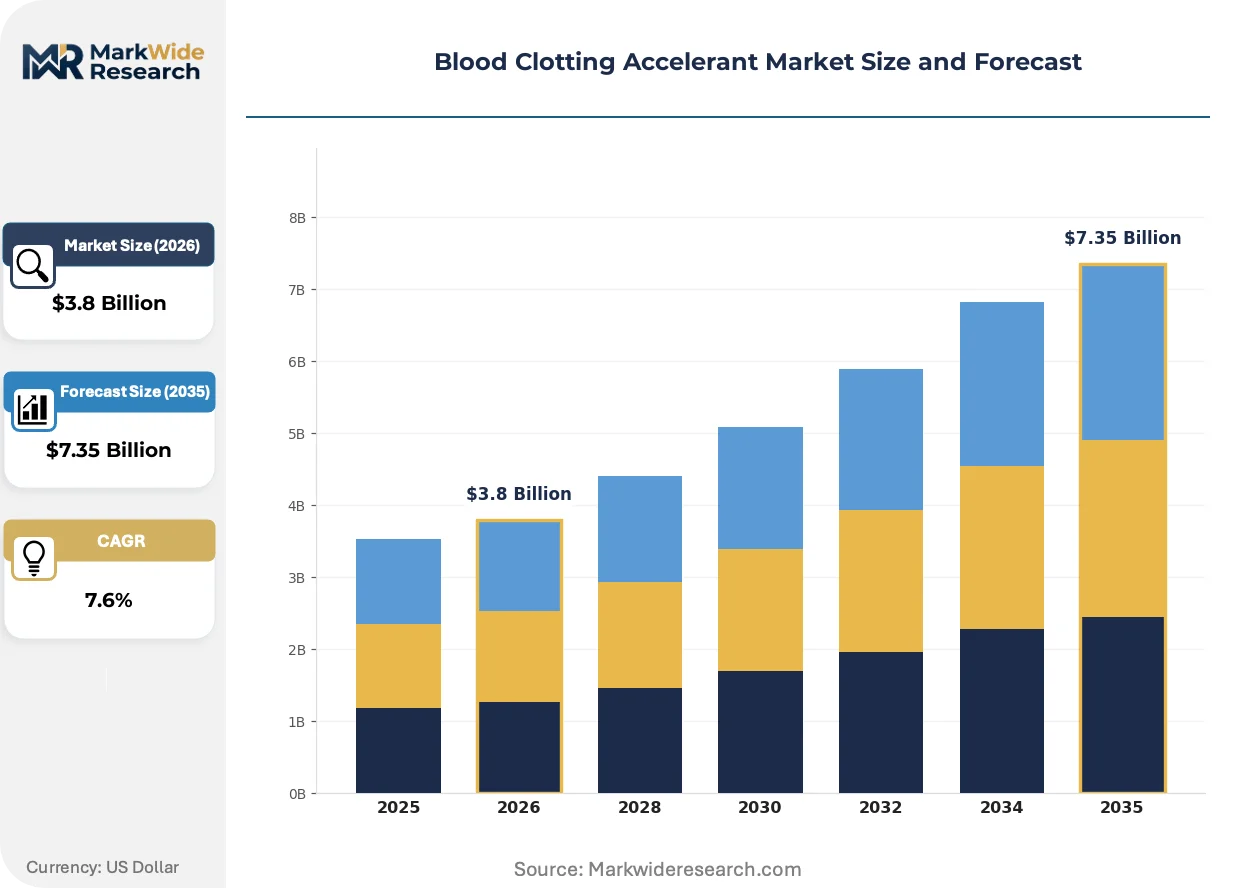
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thrombin, Fibrinogen, Platelet Concentrate, Recombinant Factors End User: Hospitals, Surgeries, Emergency Medical Services, Clinics Application: Trauma Care, Surgical Procedures, Hematological Disorders, Postoperative Recovery Technology: Biotechnology, Synthesized Products, Natural Extracts, Delivery Systems |
| Companies Covered | Merck KGaA, Baxter International Inc, CSL Ltd, Grifols, Kedrion S.P.A., Novo Nordisk A/S, Johnson & Johnson Services, Inc., Pfizer Inc., B. Braun SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Clotting Accelerant Market Strategic Shifts
Biotechnology platforms are redefining product architecture while regulatory frameworks race to accommodate novel mechanisms. The convergence of synthetic biology and military medical requirements is compressing traditional development paradigms.
Recombinant human thrombin produced in Chinese hamster ovary cells is electrifying the competitive landscape by eliminating plasma-derived viral inactivation steps and enabling consistent international unit potency. Tertiary hospital trauma units are adopting these formulations for massive transfusion protocols despite premium positioning. The technology is electrifying margin structures as biotech specialists capture value previously retained by plasma fractionators.
EU Medical Device Regulation reclassification of hemostatic sprays as class III devices imposes clinical evidence requirements that favor well-capitalized developers with existing surgical trial infrastructure. European trauma networks are consolidating vendor lists to reduce qualification burden, compressing mid-tier supplier access. German and French university hospitals are piloting EUDAMED-compliant traceability systems ahead of full enforcement.
Hospital purchasing cooperatives are consolidating hemostatic procurement under standardized formularies that privilege dual-source supply security over single-vendor loyalty. Group purchasing organizations are unbundling device-drug combinations for separate negotiation, pressuring bundled pricing models. This behavior is most visible in US civilian trauma centers responding to CMS price transparency mandates and 340B drug pricing program pressures.
Blood Clotting Accelerant Market Segmentation
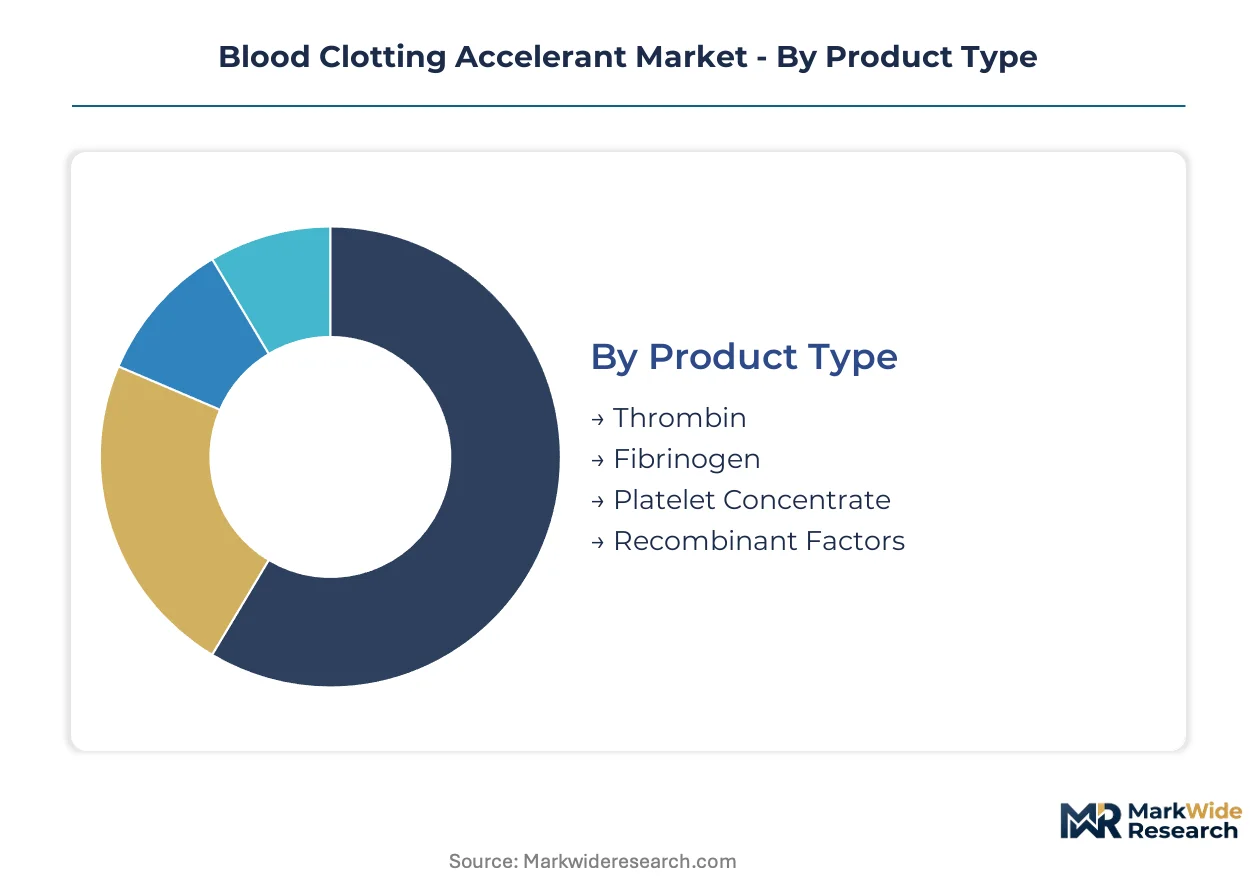
Segmentation in blood clotting accelerants reveals how product architecture, care setting, and application urgency create distinct commercial pockets. Each dimension carries different margin profiles, regulatory pathways, and procurement dynamics that reshape vendor strategy.
Product Type:
Standalone thrombin formulations dominate direct application scenarios, while recombinant factors increasingly embed into integrated hemostatic systems requiring bioprocess sophistication.
- Thrombin:Purified serine protease enzyme derived from bovine or human plasma, standardized to specific international unit potency per milligram. Demand concentrates in US military combat support hospitals where 3-minute hemostasis benchmarks mandate rapid-acting catalytic agents.
- Recombinant Factors:Biotechnology-produced coagulation proteins manufactured in Chinese hamster ovary cell lines, eliminating plasma-derived viral inactivation requirements. German and French university hospitals are piloting these formulations for massive transfusion protocols despite premium positioning, driven by EMA advanced therapy medicinal products framework incentives.
- Fibrinogen:Plasma-derived or recombinant glycoprotein concentrates enabling clot stabilization through fibrin polymerization.
- Platelet Concentrate:Autologous or allogeneic platelet-rich preparations supporting primary hemostasis in bleeding disorders.
Thrombin leads volumes today; recombinant factors are climbing the fastest as purity advantages displace legacy plasma dependence.
End User:
Procurement authority and reimbursement frameworks diverge sharply between institutional purchasers with centralized formularies versus distributed care settings with constrained cold chain infrastructure.
- Hospitals:Tertiary medical centers with trauma designation and surgical volume. US civilian trauma centers responding to CMS price transparency mandates are consolidating hemostatic procurement under standardized formularies that privilege dual-source supply security.
- Emergency Medical Services:Pre-hospital tactical combat casualty care and ambulance networks. Underpenetrated segments present white space for freeze-dried, room-temperature stable formulations where sterile water access remains problematic in field conditions.
- Surgeries:Ambulatory surgical centers and specialty procedure suites with defined case mix.
- Clinics:Outpatient settings managing chronic hematological conditions with lower acuity intervention needs.
Hospitals command the largest procurement volumes; emergency medical services represent the steepest expansion trajectory as pre-hospital protocols mature.
Application:
Urgency gradients determine pricing power, with time-critical trauma applications capturing premium multiples over scheduled surgical deployment.
- Trauma Care:Massive hemorrhage protocols in combat and civilian mass-casualty scenarios. Urban trauma centers in high-threat US metropolitan areas stockpile rapid-acting hemostatics under federal disaster readiness grants, creating concentrated demand spikes.
- Surgical Procedures:Elective cardiac, orthopedic, and general surgical hemostasis. Autologous blood salvage systems are reducing allogeneic clotting factor dependence in these scheduled procedures, constraining volume growth.
- Hematological Disorders:Congenital factor deficiencies and acquired coagulopathies requiring chronic management.
- Postoperative Recovery:Bleeding risk mitigation in surgical aftermath with extended monitoring windows.
Surgical procedures generate baseline volumes; trauma care captures the highest margin expansion as military procurement standards elevate efficacy benchmarks.
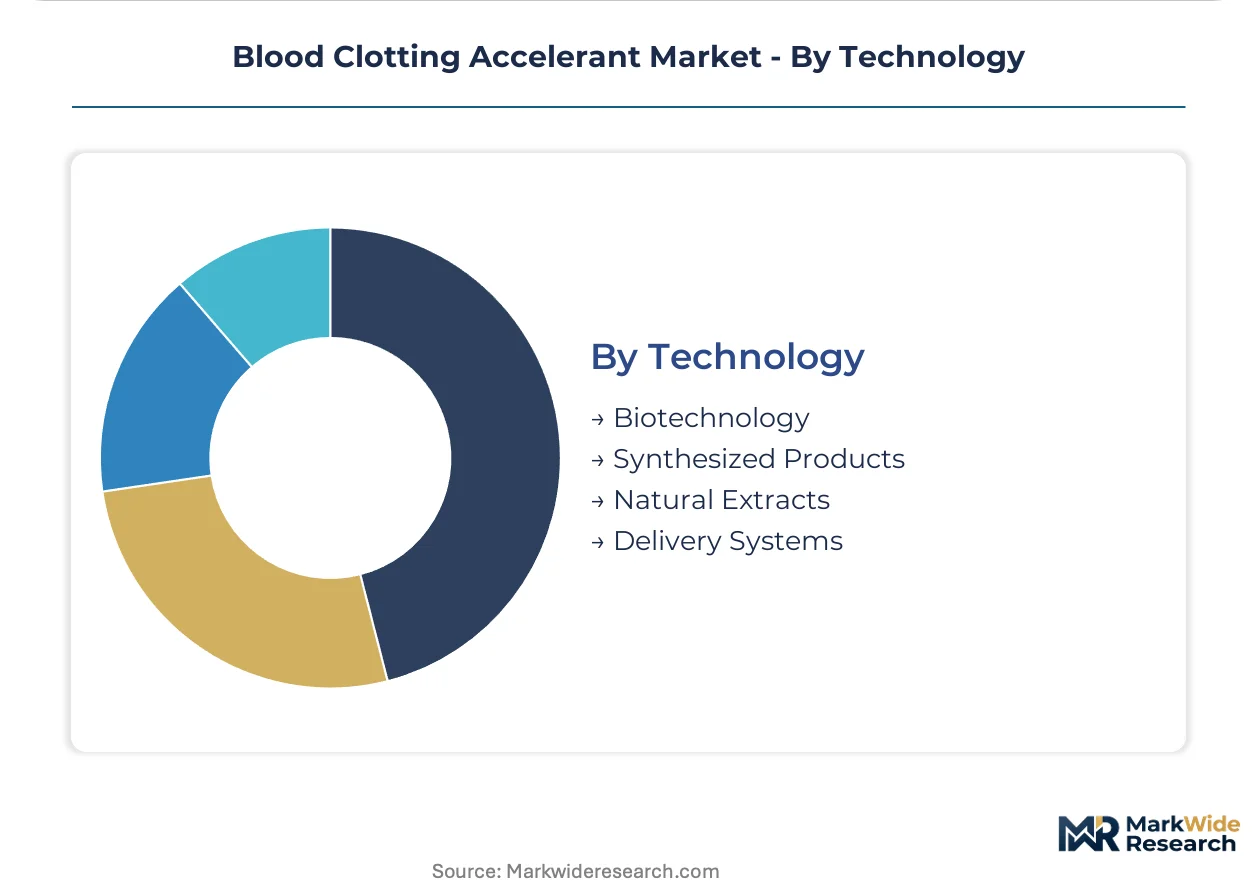
Technology:
Manufacturing maturity and regulatory complexity stratify the supplier base between established plasma fractionation and emerging biotech platforms.
- Biotechnology:Mammalian cell culture and recombinant protein engineering. Boston and Basel clusters concentrate the scarce bioprocess engineering talent required for recombinant factor scale-up, constraining new entrant capacity.
- Synthesized Products:Chemically modified or engineered peptide formulations with defined molecular architecture.
- Natural Extracts:Marine, plant, or animal-derived bioactive compounds with hemostatic properties.
- Delivery Systems:Device-drug combinations including hemostatic sprays, matrices, and flowable carriers. EU Medical Device Regulation reclassification as class III devices imposes clinical evidence requirements favoring well-capitalized developers with existing surgical trial infrastructure.
Biotechnology anchors premium positioning; delivery systems are expanding most quickly as device-drug convergence accelerates regulatory complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as biotech developers migrate toward jurisdictions offering accelerated licensing pathways for recombinant factors. Compliance cost differentials between FDA and EMA frameworks are influencing where mammalian cell culture capacity concentrates.
United States
Military medical research commands procurement intensity through combat support hospital networks mandating rapid hemostasis benchmarks. FDA biologics licensing requirements extend recombinant thrombin approval timelines, yet Boston's bioprocess engineering cluster anchors recombinant factor scale-up capacity for domestic developers.
Germany
University hospitals in Munich and Heidelberg pilot EMA advanced therapy medicinal products framework pathways for massive transfusion protocols. EUDAMED-compliant traceability systems are consolidating vendor lists ahead of full EU Medical Device Regulation enforcement, compressing mid-tier supplier access across German trauma networks.
Japan
PMDA's regenerative medicine framework attracts developers seeking expedited review for combination hemostat-device products. Tokyo and Osaka medical centers are evaluating room-temperature stable formulations for pre-hospital emergency medicine segments where cold chain infrastructure remains constrained.
Switzerland
Swissmedic oversight of plasma-derived products reinforces Basel's concentration of bioprocess engineering talent for recombinant factor manufacturing. The country's fractionation heritage supports vertical integration strategies as developers seek captive supply security amid donor pool volatility.
India
CDSCO regulatory evolution is drawing contract manufacturing investment for lyophilized hemostatic formulations targeting price-sensitive hospital procurement. Maharashtra's pharmaceutical corridor near Mumbai is emerging as a production hub for freeze-dried products requiring sterile reconstitution protocols.
Blood Clotting Accelerant Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with plasma fractionation incumbents defending position through backward integration into collection networks while biotech entrants capture premium recombinant positioning. The supplier base stratifies between scale-driven fractionators, mammalian cell culture specialists, and device-drug combination developers. Dominant competitive moves include capacity expansion in Basel and Boston bioprocess clusters alongside strategic partnerships bridging plasma-dependent and recombinant technology platforms.
Among diversified healthcare conglomerates, Baxter International Inc and Pfizer Inc exemplify contrasting strategic archetypes, with the former anchoring hospital distribution control and the latter representing recombinant factor specialization. CSL Ltd occupies a position within plasma-derived portfolio defenders leveraging captive fractionation infrastructure. These three entities illustrate how vertical integration depth, biotechnology platform access, and channel reach define competitive positioning in procurement environments favoring dual-source supply security.
| Leading Market Players |
|---|
| Merck KGaA |
| Baxter International Inc |
| CSL Ltd |
| Grifols |
| Kedrion S.P.A. |
| Novo Nordisk A/S |
| Johnson & Johnson Services, Inc. |
| Pfizer Inc. |
| B. Braun SE |
| Others |
Value Chain & Pricing Dynamics
Recombinant biotechnology migration from plasma-dependent to mammalian cell culture production is compressing manufacturing cost curves while fragmenting supplier power between legacy fractionators and biotech specialists. This technology shift concentrates high-value production in Boston and Basel bioprocess clusters, elevating pricing power for recombinant thrombin formulations while pressuring margins on commodity plasma-derived alternatives.
Pricing Analysis
Distributor margins on hemostatic device-drug combinations compress under group purchasing organization unbundling pressures, particularly in US civilian trauma centers responding to CMS price transparency mandates. Three-tier pricing structure across premium recombinant factors, standard plasma-derived concentrates, and economy-grade bovine thrombin reflects immunogenicity risk profiles and FDA biologics licensing tier. Cost compression in standard-grade segments is intensifying because autologous blood salvage systems reduce allogeneic dependence in elective procedures. Emergency medical services buyers exhibit highest price sensitivity due to constrained pre-hospital budgets, while military procurement networks prioritize efficacy benchmarks over unit cost.
Supply Chain Analysis
Direct-to-hospital channels handle trauma center demand through specialized distributor networks, while group purchasing organizations consolidate procurement for tertiary surgical volumes. Supply concentrates in the United States, Germany, and Switzerland, with fractionation-grade plasma drawing from US and European collection networks. Mammalian cell culture capacity rests on recombinant protein engineering inputs, Chinese hamster ovary cell lines, and sterile lyophilization infrastructure. Single-source vulnerability in Boston and Basel bioprocess engineering talent clusters constrains scale-up capacity for new entrants. Distribution runs through hospital purchasing cooperatives, military medical logistics networks, and emergency medical service suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recombinant factor premiumization is expanding addressable margins as biotechnology yields displace legacy plasma dependence, with cost-down drivers anchored in mammalian cell culture yield improvements and reduced viral inactivation overhead.
For Market Incumbents: Acquire bioprocess engineering talent clusters in Boston and Basel to secure recombinant scale-up capacity against emerging biotech entrants. Backward integration into fractionation-grade plasma collection networks defends supply security amid donor pool volatility. Invest in ISO 13485 device-drug combination certification to maintain access as EU Medical Device Regulation enforcement consolidates vendor lists across German and French trauma networks. For New Entrants and Emerging Players: Begin with freeze-dried, room-temperature stable formulations targeting underpenetrated emergency medical services and tactical combat casualty care segments where sterile water access constraints exclude incumbent liquid reconstitution products. Japan PMDA's regenerative medicine framework offers expedited pathway entry for combination hemostat-device developers seeking Asian market establishment. Partner with viscoelastic coagulation analyzer manufacturers for algorithmic dosing integration. For Investors and Strategic Acquirers: Roll-up economics work for mammalian cell culture specialists because bioprocess engineering talent scarcity in Boston and Basel clusters creates captive value in scale-up capability. Long-term viability favors platforms with dual-source supply security credentials and military procurement qualification. Watch for biosimilar pathway clarity as inflection indicator for recombinant factor commoditization risk.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Biologics Licensing Submission | Recombinant thrombin approvals extend timelines but create durable competitive moats against plasma-derived alternatives. |
| EMA Advanced Therapy Designation | Orphan drug pathways in Germany and France accelerate European market entry for next-generation hemostatics. |
| Hospital System Partnership | Direct formulary placement with US civilian trauma centers secures volume under CMS price transparency compliance. |
| Manufacturing Scale-Up in Basel | Swiss bioprocess clusters concentrate scarce mammalian cell culture expertise for recombinant factor production. |
| Pre-Hospital Formulation Development | Freeze-dried stability enables ambulance and tactical combat casualty care penetration where cold chain fails. |
Study Parameters
Coverage spans the United States, Germany, Japan, Switzerland, and India, with primary inputs from each market's stakeholder ecosystem. Primary interviews with hospital procurement managers, trauma surgeons, regulatory affairs leads at biotech developers, and military medical logistics officers combined with secondary validation from FDA biologics licensing databases, EMA advanced therapy submissions, hospital GPO contract repositories, and ISO 13485 certification records. Bottom-up demand modeling across trauma care units, surgical procedure volumes, and hematological disorder prevalence triangulated with top-down plasma fractionation capacity and recombinant bioprocess throughput estimates.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by product type, end user procurement authority, application urgency gradient, and manufacturing technology maturity. Modeled dimensions include thrombin versus recombinant factor versus fibrinogen architecture, tertiary hospital versus emergency medical service versus ambulatory surgical center purchasing, trauma care versus surgical procedure versus chronic hematological application, and biotechnology versus plasma-derived versus synthesized production method. CAGRs derive from procedure volume elasticity to hemostatic adoption rates, military procurement specification evolution, and regulatory pathway timeline compression.
Several conditions sit outside the modeled scope, including geopolitical disruption to plasma collection networks, novel anticoagulant therapeutic advances reducing procedural hemostatic dependence, and breakthrough synthetic biology platforms bypassing mammalian cell culture entirely. Forecasts reflect assumptions regarding EMA framework stability, FDA immunogenicity testing consistency, and military 3-minute hemostasis benchmark maintenance. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global DPT Vaccine Market
Pharmaceuticals
Australia Schizophrenia Drugs Market
Pharmaceuticals
Drug Designing Tools Market
Pharmaceuticals
Medicinal Fungi Market
Pharmaceuticals
Calcineurin Inhibitor Drugs Market
Pharmaceuticals
Carglumic Acid Market
Pharmaceuticals
Controlled Substance Market
Pharmaceuticals
Global Human Vaccines Market
Pharmaceuticals
Depression Drugs Market
Pharmaceuticals
Vitiligo Drugs Market
Pharmaceuticals
Gardasil (HPV Vaccine) Market
Pharmaceuticals
Antidepressants Market
Pharmaceuticals
Enteric Empty Capsules Sales Market
Pharmaceuticals
Dipeptidyl Peptidase-4 (DPP-4) Inhibitors Market
Pharmaceuticals
Placental Protein Market
Pharmaceuticals
Steroid-Free Nasal Sprays Market