
 Radioligand Therapy (RLT) Market | 2026-2036
Radioligand Therapy (RLT) Market Size, Share, and Industry Trends Forecast 2026-2036
Radioligand Therapy (RLT) Market Analytics
Lutetium-177 is repositioning product economics in radioligand therapy by displacing older beta-emitter formulations with higher therapeutic indices and more favorable dosimetry profiles. Novartis leverages its vertically integrated radiopharmaceutical network to secure isotope supply and manufacturing capacity across multiple continents. Bayer anchors its position through deep R&D investment in targeted alpha therapy platforms. Telix Pharmaceuticals competes by specializing in theranostic pairing strategies that link diagnostic imaging agents to companion therapeutic products.
Radioligand therapy employs tumor-targeting molecules conjugated to radioactive isotopes to deliver localized cytotoxic radiation, with lutetium-177 and actinium-225 serving as the primary therapeutic payloads bound to prostate-specific membrane antigen or somatostatin receptor ligands. The treatment modality functions by exploiting molecular recognition to concentrate radiation dose within malignant tissue while sparing adjacent healthy structures. Beta emitters currently dominate commercial volume due to established manufacturing infrastructure and broader reimbursement coverage, though alpha emitters represent the fastest-growing category as clinicians pursue higher linear energy transfer for resistant micrometastases. Oncology commands the largest application share, while neurology applications are emerging as a concentrated margin pool for developers addressing neuroendocrine tumors.
FDA oversight through its Center for Drug Evaluation and Research governs radiopharmaceutical approval pathways, while EMA's Committee for Medicinal Products for Human Use coordinates centralized European authorization requiring compliance with Good Manufacturing Practice for sterile radioactive products. The Nuclear Regulatory Commission and comparable national atomic energy agencies impose additional layer controls on isotope handling, transport, and administration that directly shape site certification requirements and treatment capacity expansion. Stakeholders must monitor evolving reimbursement frameworks for theranostic procedures and build supply chain resilience against isotope production disruptions at aging reactor facilities.
Market Dynamics
Isotope supply concentration at aging reactor facilities is constraining treatment capacity expansion and forcing radiopharmaceutical developers to secure captive production arrangements or alternative sourcing routes. This structural bottleneck shapes competitive positioning more than product differentiation.
Growth Catalysts
- PSMA-targeted agent approvals:FDA and EMA authorizations of prostate-specific membrane antigen therapeutics are accelerating clinical access and expanding reimbursable indications.
- Germany:Nuclear medicine infrastructure concentration in German academic medical centers is driving theranostic program adoption and physician training pipeline expansion.
- Lutetium-177 manufacturing:Higher therapeutic indices and favorable dosimetry profiles of lutetium-based formulations are displacing older beta-emitter standards in clinical protocols.
Market Restraints
- Reactor concentration risk:Molybdenum-99 and lutetium-177 production depends on five aging research reactors in Canada, Netherlands, Belgium, South Africa, and Australia.
- Good Manufacturing Practice compliance:EMA sterile radioactive product requirements impose capital-intensive facility upgrades that exclude smaller contract manufacturers.
- Alpha-emitter infrastructure gaps:Actinium-225 handling requires specialized shielding and containment systems absent at most community oncology sites.
Strategic Opportunities
- Japan:Underdeveloped theranostic penetration relative to Germany and the United States creates first-mover advantage for site certification and physician education investments.
- Neuroendocrine tumor applications:Somatostatin receptor-targeted therapies represent concentrated margin pools with less competitive saturation than prostate indications.
- Targeted alpha therapy convergence:Pairing actinium-225 payloads with established ligand platforms enables higher linear energy transfer for resistant micrometastases.
Industry Challenges
- Radiopharmacist scarcity:Compounding sterile radioactive doses requires specialized certification programs with limited enrollment capacity at accredited training institutions.
- Nuclear Regulatory Commission licensing:Site certification timelines for isotope handling and administration create multi-year barriers to treatment capacity expansion.
- Cold chain integrity:Short half-lives of therapeutic isotopes demand precision logistics coordination between production facilities and administration sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radioligand Therapy (RLT) Market |
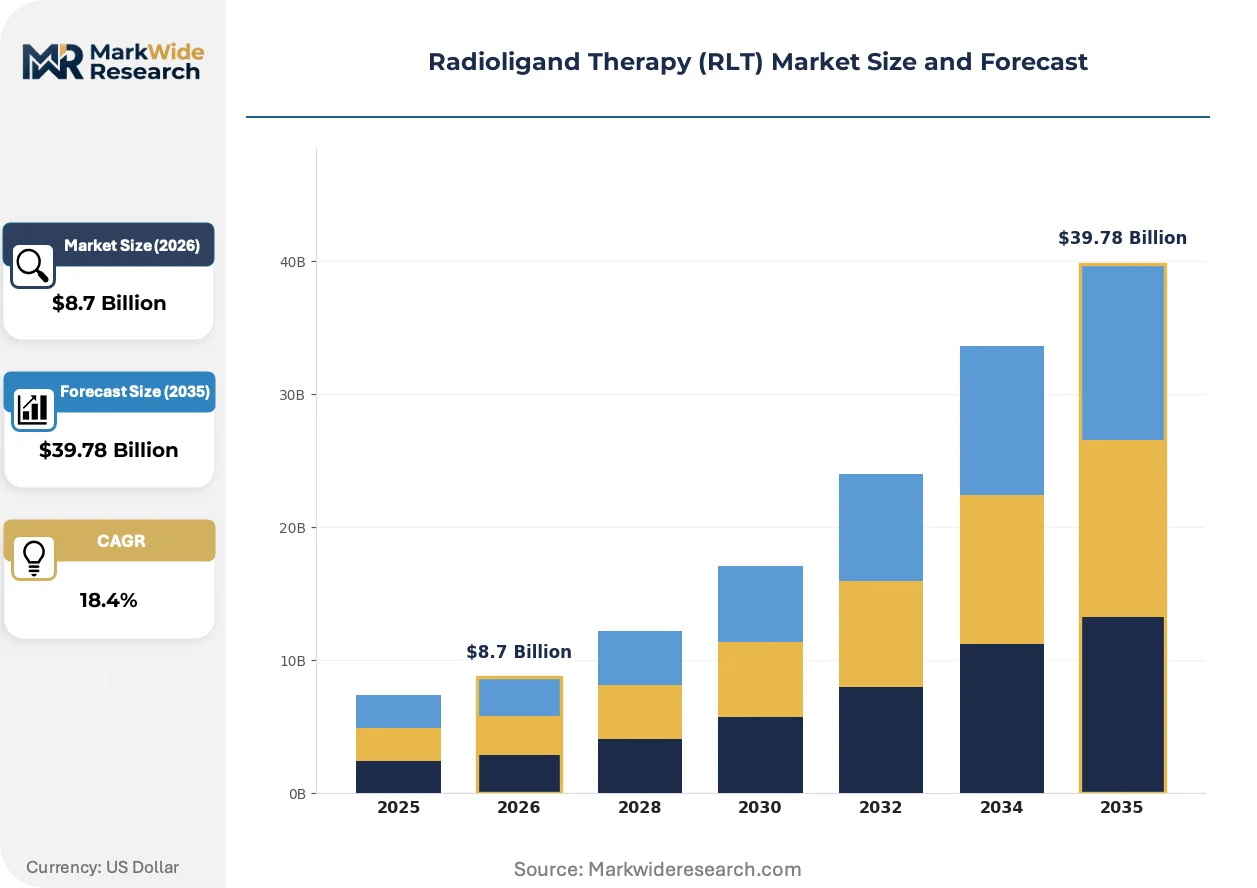
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alpha Emitters, Beta Emitters, Combined Therapeutics, Radiopharmaceuticals Application: Oncology, Neurology, Cardiovascular, Endocrinology Technology: Single Photon Emission Computed Tomography, Positron Emission Tomography, Targeted Radiotherapy, Radioimmunotherapy End User: Hospitals, Clinics, Research Institutions, Diagnostic Centers |
| Companies Covered | Fusion Pharmaceuticals, Lantheus Holdings, Novartis, ITM Isotope Technologies Munich SE, Curium Pharma, Bayer, Telix Pharmaceuticals, Orano Med, POINT Biopharma Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radioligand Therapy (RLT) Market Evolving Landscape
Technological convergence between diagnostic imaging and therapeutic delivery is compressing development cycles and reshaping how pharmaceutical firms structure radiopharmaceutical portfolios. This theranostic integration demands synchronized regulatory strategies and manufacturing investments.
Actinium-225 is expanding into clinical protocols for resistant metastatic disease. Academic medical centers in Germany and the United States are adopting alpha-emitter trials at accelerating pace. The technology is expanding into micrometastatic indications where beta-emitter efficacy plateaus, creating new addressable patient segments.
EMA's Committee for Medicinal Products for Human Use has streamlined centralized authorization pathways for radiopharmaceuticals with companion diagnostic requirements. This regulatory convergence reduces duplicative filings across member states. European oncology networks are responding by consolidating theranostic procurement at hub-and-spoke nuclear medicine centers.
Hospital systems are unbundling diagnostic imaging from therapeutic administration to optimize asset utilization across distributed networks. Community oncology practices in the United States are losing referral volume to centralized academic hubs with captive cyclotron or reactor sourcing. This geographic consolidation is most visible in prostate cancer care pathways where PSMA-PET availability determines treatment site selection.
Radioligand Therapy (RLT) Market Segmentation
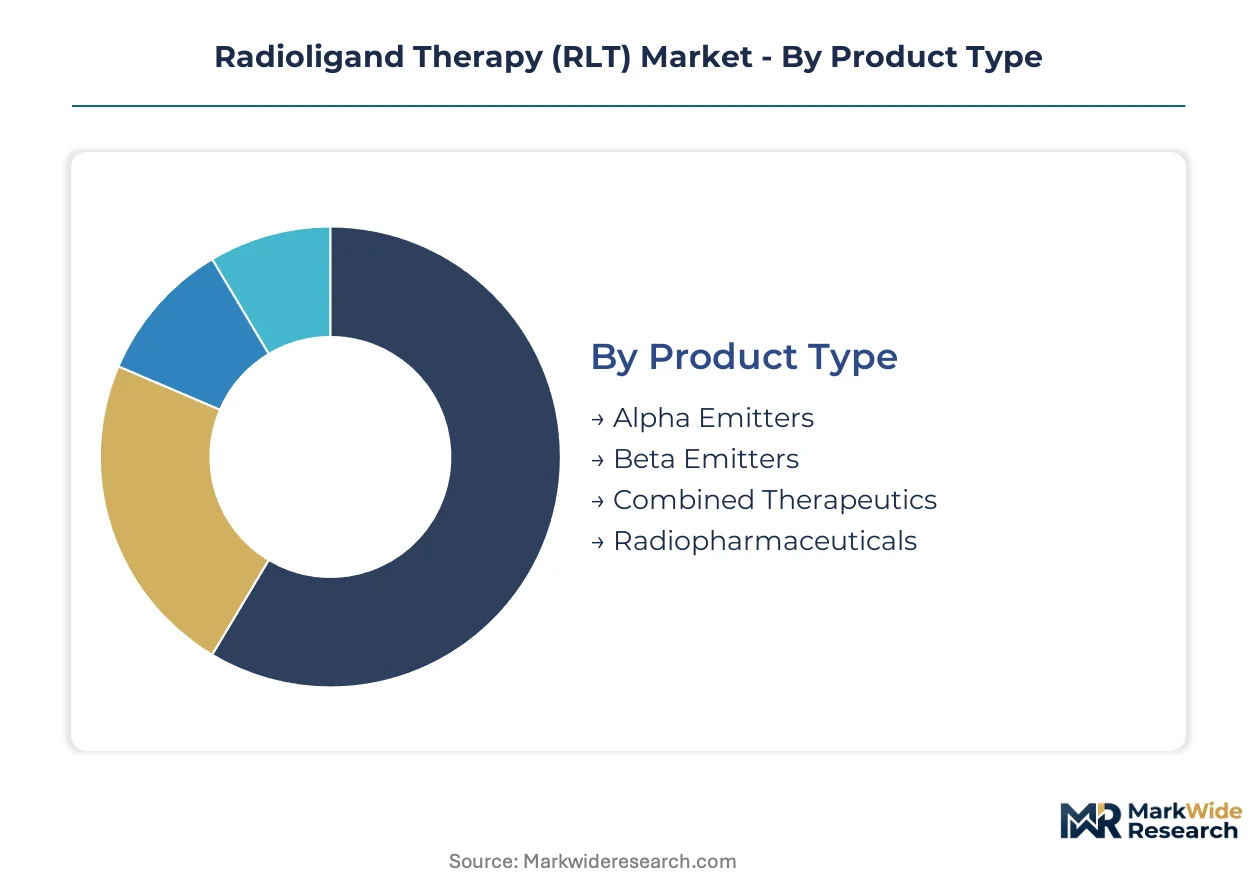
Radioligand therapy segmentation reflects the modality's dual nature as both diagnostic and therapeutic. Isotope half-life characteristics and ligand specificity determine clinical utility across tumor types. Each segmentation axis carries distinct regulatory, reimbursement, and infrastructure implications for market participants.
Product Type:
Beta-emitting isotopes currently anchor commercial volume due to manufacturing maturity and broader site certification, while alpha emitters are gaining protocol share for resistant micrometastatic disease.
- Beta Emitters:Lutetium-177 formulations dominate current treatment protocols with established cyclotron production networks and favorable reimbursement codes. Demand concentrates in prostate and neuroendocrine indications at German and United States academic centers where nuclear medicine infrastructure is most developed.
- Alpha Emitters:Actinium-225 delivers higher linear energy transfer for resistant micrometastases but requires specialized shielding infrastructure absent at community sites. Clinical adoption is accelerating at Mayo Clinic, Heidelberg University Hospital, and Memorial Sloan Kettering for patients who have exhausted beta-emitter options.
- Radiopharmaceuticals:Commercially manufactured dose units with standardized specific activity reduce compounding variability.
- Combined Therapeutics:Sequential or concurrent alpha-beta protocols under investigation at select European centers.
Beta emitters lead on scale; alpha emitters lead on momentum.
Application:
Oncology commands revenue concentration while neurology applications are expanding into addressable patient pools with less competitive saturation.
- Oncology:Prostate-specific membrane antigen targeting and somatostatin receptor ligands constitute the primary revenue base. FDA and EMA approvals have expanded reimbursable indications to earlier treatment lines.
- Neurology:Neuroendocrine tumor applications represent concentrated margin pools with favorable pricing power. Demand is materializing at specialized centers in Germany, the United States, and Japan.
- Endocrinology:Thyroid and parathyroid applications leverage established iodine isotope infrastructure.
- Cardiovascular:Amyloid and inflammation imaging protocols are emerging as off-label therapeutic exploration areas.
Oncology leads on scale; neurology leads on momentum.
Technology:
Imaging modality selection determines ligand development priorities and cyclotron investment requirements for radiopharmaceutical developers.
- Targeted Radiotherapy:Tumor-directed isotope delivery with companion diagnostic pairing constitutes the core therapeutic value proposition. German and United States academic centers are consolidating theranostic procurement at hub-and-spoke nuclear medicine networks.
- Positron Emission Tomography:Gallium-68 and fluorine-18 diagnostics enable patient selection and response monitoring. Production requires on-site or regional cyclotron infrastructure with EMA Good Manufacturing Practice compliance.
- Radioimmunotherapy:Antibody-isotope conjugates for hematologic malignancies.
- Single Photon Emission Computed Tomography:Technetium-based diagnostics with established generator supply chains.
Targeted radiotherapy leads on scale; positron emission tomography leads on momentum.
End User:
Site certification requirements and isotope handling infrastructure create sharp segmentation between centralized academic hubs and distributed community settings.
- Hospitals:Academic medical centers with captive cyclotron or reactor sourcing are consolidating referral volume. Nuclear Regulatory Commission licensing timelines create multi-year barriers that protect incumbent positions.
- Research Institutions:Early-phase trials and alpha-emitter protocol development concentrate at Heidelberg, MD Anderson, and Osaka University where specialized containment systems are operational.
- Clinics:Community oncology practices are losing prostate cancer referrals to centralized hubs with PSMA-PET availability.
- Diagnostic Centers:Imaging-only facilities without therapeutic administration licenses.
Hospitals lead on scale; research institutions lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German academic medical centers anchor radioligand therapy infrastructure development, with Heidelberg University Hospital and Munich's university hospitals operating theranostic programs that integrate diagnostic imaging and therapeutic delivery. Regional expansion patterns reflect isotope production geography, regulatory pathway efficiency, and nuclear medicine training capacity.
United States
PSMA-targeted agent demand concentrates at Mayo Clinic, Memorial Sloan Kettering, and MD Anderson where specialized containment systems enable alpha-emitter protocols. FDA oversight through CDER governs radiopharmaceutical approvals while the Nuclear Regulatory Commission imposes multi-year licensing timelines for isotope handling. The Southwest and Northeast corridor academic hubs are consolidating prostate cancer referrals through captive cyclotron networks.
Germany
EMA centralized authorization pathways accelerate market access for theranostic products with companion diagnostic requirements. The country's national pharmaceutical regulator maintains stringent Good Manufacturing Practice standards for sterile radioactive products that exclude smaller contract manufacturers. Bavaria and North Rhine-Westphalia host the densest concentration of nuclear medicine departments, with Heidelberg and Munich driving physician training pipeline expansion.
Japan
PMDA review timelines for radiopharmaceuticals are compressing as METI prioritizes nuclear medicine infrastructure investment. Underdeveloped theranostic penetration relative to Germany and the United States creates first-mover advantage for site certification investments. Osaka University and Tokyo metropolitan academic centers are adopting lutetium-177 protocols at accelerating pace, with specialized shielding requirements limiting community site participation.
Australia
TGA authorization pathways for radioactive medicinal products align with EMA standards, reducing regulatory friction for European developers. The country's national pharmaceutical regulator emphasizes supply chain traceability for short half-life isotopes. Sydney and Melbourne nuclear medicine centers are expanding theranostic procurement through hub-and-spoke networks that concentrate production at centralized cyclotron facilities.
Switzerland
Swissmedic maintains autonomous authorization pathways for radiopharmaceuticals while recognizing EMA centralized procedures for parallel submissions. The country's national pharmaceutical regulator imposes stringent transport documentation for radioactive materials crossing alpine logistics corridors. Basel and Zurich academic medical centers leverage proximity to German isotope production facilities, with specialized courier networks maintaining cold chain integrity across mountainous terrain.
Radioligand Therapy (RLT) Market Competitive Landscape
Global majors compete with regional champions across isotope supply security and manufacturing capacity. The market structure consolidates around vertically integrated radiopharmaceutical networks that control production from reactor sourcing through dose compounding. Three archetypes dominate: diversified pharmaceutical conglomerates with captive isotope arrangements, specialized radiopharmaceutical developers focused on theranostic pairing, and contract manufacturing organizations with EMA GMP certification. Competitive positioning hinges on backward integration into reactor partnerships and geographic licensing velocity.
Among diversified pharmaceutical conglomerates, Novartis and Bayer occupy positions that exemplify scale-driven radiopharmaceutical strategies. Telix Pharmaceuticals represents the specialized developer archetype with theranostic-focused portfolio construction. ITM Isotope Technologies Munich SE anchors the European isotope production tier through reactor sourcing arrangements and GMP manufacturing infrastructure.
| Leading Market Players |
|---|
| Fusion Pharmaceuticals |
| Lantheus Holdings |
| Novartis |
| ITM Isotope Technologies Munich SE |
| Curium Pharma |
| Bayer |
| Telix Pharmaceuticals |
| Orano Med |
| POINT Biopharma Global |
| Others |
Value Network & Pricing Analysis
Lutetium-177 spot pricing volatility at European reactor facilities cascades through radiopharmaceutical manufacturing into tiered patient-access structures. Academic medical centers with captive isotope contracts command premium pricing power while community oncology sites absorb higher procurement costs from distributor markups.
Pricing Analysis
Input-cost pass-through from reactor production fees drives pricing stratification across beta-emitter and alpha-emitter tiers. Specific-activity certification grade and site-licensing tier (Nuclear Regulatory Commission Category 1 versus Category 2) differentiate contract rates. Pricing pressure stems from reactor maintenance shutdowns concentrating supply at fewer production nodes. Community oncology practices exhibit highest price sensitivity due to uncompensated cold-chain logistics, while academic centers with integrated cyclotron infrastructure maintain cost absorption capacity.
Supply Chain Analysis
Reverse-logistics flows for unused radiopharmaceutical doses require specialized courier networks returning partially decayed product to centralized waste processing. Supply concentrates in Canada, the Netherlands, and Belgium where aging research reactors produce medical isotopes. Raw material dependencies include highly enriched uranium targets, specialized chemical separation resins, and sterile vial assemblies. Single-source vulnerability at BR-2 and HFR reactors creates supply interruption risk. Distribution runs through hub-and-spoke nuclear pharmacy networks radiating from production facilities to administration sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radioligand therapy functions as a stable compounder anchored by irreversible demographic shifts in prostate cancer incidence and expanding reimbursable indications. Recurring treatment protocols generate predictable revenue streams resistant to cyclical pharmaceutical pricing pressure.
For Market Incumbents: Extend manufacturing capacity through reactor partnership arrangements in Germany and Japan before competitor site certification accelerates. Secure backward integration into lutetium-177 production through long-term offtake agreements with BR-2 and HFR operators. Alpha-emitter infrastructure investments at Mayo Clinic and Heidelberg University Hospital represent defensive positioning against beta-emitter commoditization. For New Entrants and Emerging Players: The premium-to-economy pricing gap in neuroendocrine tumor therapeutics offers white-space entry below Novartis and Bayer prostate-focused portfolios. Target Japan's underdeveloped theranostic penetration where PMDA review timelines are compressing and METI infrastructure investment creates first-mover site certification opportunities. Pursue specialized radiopharmacist training partnerships with Osaka University and Tokyo metropolitan academic centers as differentiated go-to-market foundation. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized radiopharmaceutical developers possessing theranostic pairing capabilities and EMA GMP-certified manufacturing infrastructure. Five-to-ten-year viability hinges on alpha-emitter protocol adoption velocity and reactor diversification progress. Monitor FDA breakthrough therapy designations for actinium-225 candidates as inflection indicator for platform valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Reactor Partnership Arrangement | Secures lutetium-177 supply continuity against BR-2 and HFR maintenance shutdowns. |
| Alpha-Emitter Infrastructure Investment | Enables actinium-225 protocols at Memorial Sloan Kettering and Heidelberg University Hospital. |
| Theranostic Regulatory Convergence | Streamlines EMA centralized authorization for companion diagnostic-therapeutic pairings. |
| Radiopharmacist Training Pipeline | Addresses Nuclear Regulatory Commission licensing bottlenecks limiting site expansion. |
| Japan Site Certification Program | Captures first-mover advantage in METI-prioritized nuclear medicine infrastructure buildout. |
Research Methodology
Multiple input streams — primary interviews with nuclear medicine department heads, regulatory affairs specialists at EMA and FDA, and GPO contracts managers — were reconciled against secondary validation from ClinicalTrials.gov entries, CMS Medicare reimbursement databases, and SEC 10-K radiopharmaceutical segment disclosures. Bottom-up treatment volume estimates from German, United States, and Japanese academic medical centers were triangulated against top-down market sizing from isotope production capacity declarations.
Data-stream reconciliation applied treatment-line segmentation across beta-emitter and alpha-emitter categories, with regional regulatory cluster differentiation for FDA, EMA, and PMDA approval pathways. CAGRs were derived from patient-flow modeling through prostate and neuroendocrine cancer care pathways, incorporating isotope half-life decay mathematics and reactor production scheduling constraints.
Caveats apply where reactor unscheduled maintenance, PMDA regulatory delays, or alpha-emitter shielding infrastructure cost overruns could materially shift the outlook. Practitioners should monitor BR-2 and HFR reactor operational status, FDA breakthrough therapy designation announcements for actinium-225 candidates, and METI nuclear medicine infrastructure budget allocations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Anticancer Drugs Market
Pharmaceuticals
Global Angina Pectoris Drugs Market
Pharmaceuticals
Metoprolol Tartrate Market
Pharmaceuticals
Global Zika Vaccines Market
Pharmaceuticals
Global Central Nervous System (CNS) Stimulant Drugs Market
Pharmaceuticals
Injectable Targeted Therapy Market
Pharmaceuticals
Hydroxychloroquine Market
Pharmaceuticals
Global Diphenhydramine Market
Pharmaceuticals
Multiple Sclerosis Drugs Market
Pharmaceuticals
US Over the Counter Drugs Market
Pharmaceuticals
Live Vaccines Market
Pharmaceuticals
Short-Acting Insulin Market
Pharmaceuticals
Anti-Obesity Drugs Market
Pharmaceuticals
Antidepressant Drugs Market
Pharmaceuticals
Calcitriol Capsules Market
Pharmaceuticals
Global Narcolepsy Drugs Market