
 Indobufen API Market | 2026-2036
Indobufen API Market Size, Share, and Industry Trends Forecast 2026-2036
Indobufen API Market Insights
Hospital procurement for antiplatelet therapies is consolidating as health systems centralize formularies under single-source contracts. Fuan Pharmaceutical leverages backward integration into key starting materials to protect margin structures. Olon S.p.A sustains European manufacturing scale for high-purity batches. Dr Reddy's Laboratories Ltd anchors Indian export capacity toward regulated markets.
Indobufen API is a phenylbutyric acid derivative antiplatelet agent, synthesized through acylation and cyclization routes with strict control over residual solvent limits and polymorph purity. It inhibits platelet aggregation by reversible cyclooxygenase blockade, serving primarily as an alternative to aspirin in post-surgical thrombosis prevention. Oral tablets dominate prescription volumes among product type segments, while injectable solutions capture premium positioning in perioperative care settings. Hospital end users concentrate the largest procurement pools, though pharmacy channels extend reach into chronic outpatient management.
China's NMPA enforces updated ICH Q3D elemental impurity guidelines for antiplatelet APIs, while India's CDSCO mandates enhanced stability data for export registration. The US FDA maintains active pharmaceutical ingredient GMP inspections through risk-based scheduling, shaping supplier qualification timelines. Stakeholders must monitor evolving pharmacopeial monograph revisions and bioequivalence study design changes that could alter API specification requirements.
Market Dynamics
Hospital formulary consolidation is compressing supplier margins while China's NMPA impurity enforcement raises batch rejection rates, forcing API manufacturers to absorb compliance costs or cede share to vertically integrated competitors.
Growth Catalysts
- Perioperative antiplatelet protocols:Surgical departments in tertiary hospitals are expanding indobufen use for patients with aspirin intolerance, driving API procurement volumes through centralized purchasing agreements.
- ICH Q3D elemental impurity guidelines:China's NMPA adoption of international standards is filtering out subscale producers, concentrating qualified supply among GMP-certified manufacturers with validated impurity profiling capabilities.
- Reversible COX inhibition mechanism:The pharmacological profile enables perioperative management without bleeding risk escalation, supporting uptake in orthopedic and cardiovascular surgery settings where rapid platelet function recovery matters.
Market Restraints
- Starting material cost volatility:Phenylbutyric acid derivatives face pricing pressure from petroleum feedstock fluctuations, squeezing margin structures for non-integrated API producers.
- Single-source KSM dependency:European and Indian manufacturers rely on Chinese suppliers for cyclization intermediates, exposing production schedules to export license delays and geopolitical friction.
- Generic aspirin substitution:Ultra-low-cost acetylsalicylic acid formulations dominate chronic thrombosis prophylaxis, limiting indobufen penetration in price-sensitive outpatient markets.
Strategic Opportunities
- Injectable formulation expansion:Perioperative care units in German and French hospitals are requesting sterile indobufen solutions, opening premium pricing tiers for aseptic manufacturing specialists.
- CDSCO export registration pathways:India's enhanced stability data requirements, once satisfied, unlock accelerated access to regulated markets with abbreviated inspection timelines.
- Continuous flow synthesis adoption:Integration of flow chemistry with real-time release testing is reducing solvent consumption and batch cycle times for manufacturers retrofitting legacy batch plants.
Industry Challenges
- Analytical method transfer complexity:Validating polymorph-specific assays across contract laboratories delays ANDA submissions and extends time-to-revenue for generic developers.
- Multipurpose equipment cleaning validation:Shared synthesis trains require extensive residue testing between antiplatelet and anticoagulant campaigns, constraining capacity utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indobufen API Market |
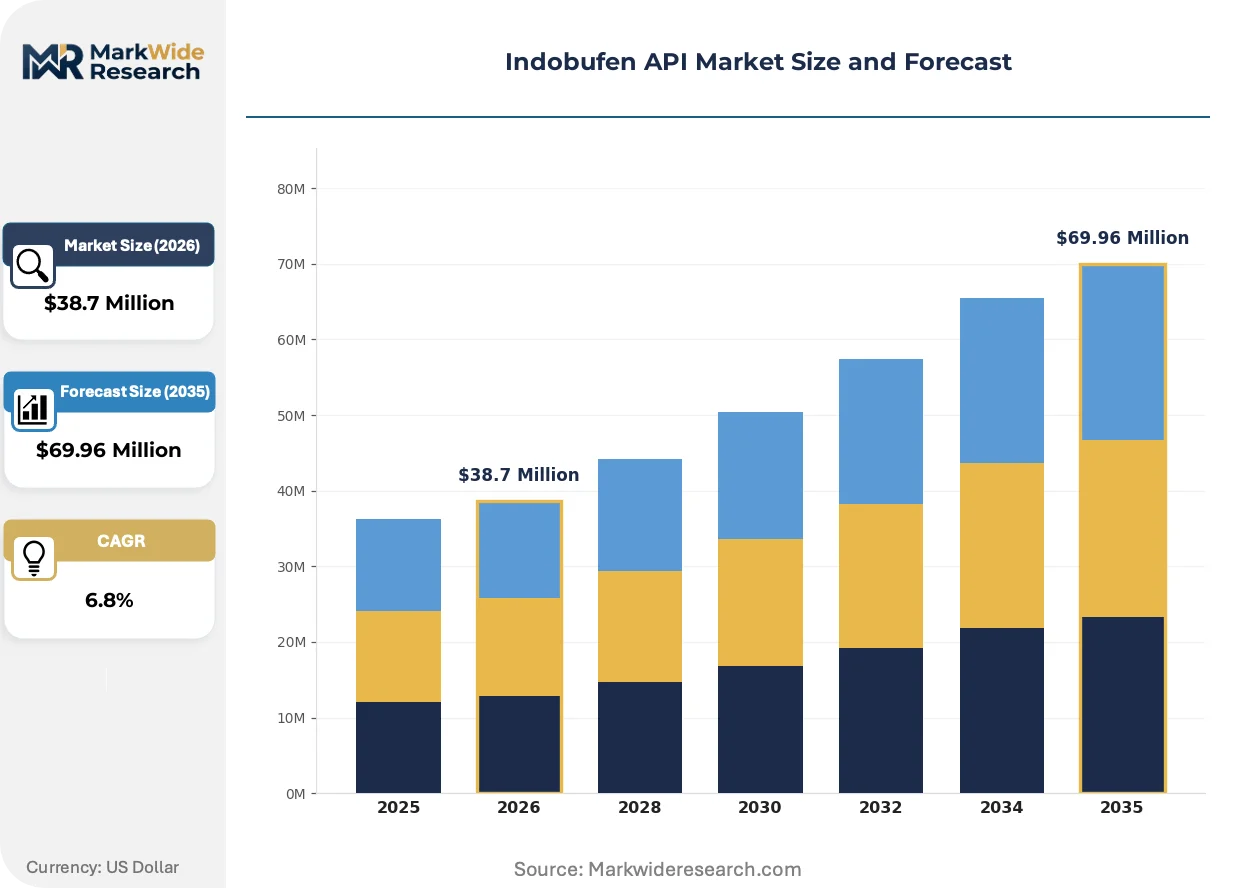
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $69.96 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Tablets, Injectable Solutions, Powder for Injection, Oral Suspension End User: Hospitals, Pharmacies, Clinics, Research Institutions Packaging Type: Blister Packs, Vials, Bottles, Ampoules Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Beijing Fukangren Biopharmaceutical, Fuan Pharmaceutical, Olon S.p.A, Suzhou Ryway Biotech, Boehringer Ingelheim, Teva Pharmaceutical Industries Ltd, Dr Reddy's Laboratories Ltd, IOL Chemicals and Pharmaceuticals Limited, Solara Active Pharma Sciences Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indobufen API Market Trends and Innovations
Process analytical technology and real-time release paradigms are displacing end-point testing in API manufacturing, while regulatory convergence around ICH guidelines is harmonizing specification requirements across import jurisdictions.
Continuous manufacturing platforms are expanding into antiplatelet API production, replacing conventional batch reactors with modular flow systems that maintain tighter temperature and mixing control. German and Swiss CDMOs are retrofitting pilot plants with these configurations to serve high-value perioperative injectable contracts. The technology is expanding into markets previously dominated by commodity-scale batch producers, compressing cost structures for qualified supply.
China's NMPA is enforcing updated elemental impurity thresholds aligned with ICH Q3D, requiring manufacturers to demonstrate control over catalyst residues and environmental contaminants in final API lots. This regulatory tightening is accelerating facility upgrades among domestic producers while raising barriers for exporters seeking Chinese market access. European and Indian suppliers are responding by qualifying dedicated manufacturing trains with closed-system containment.
Hospital purchasing coalitions are consolidating antiplatelet API procurement under multi-year sole-source agreements, displacing spot-market transactions and fragmenting demand among fewer qualified vendors. Group purchasing organizations in the United States are extracting volume commitments in exchange for formulary exclusivity, compressing supplier margins. This concentration is most visible in cardiovascular service line contracts where therapeutic interchange protocols favor single-agent standardization.
Indobufen API Market Segmentation
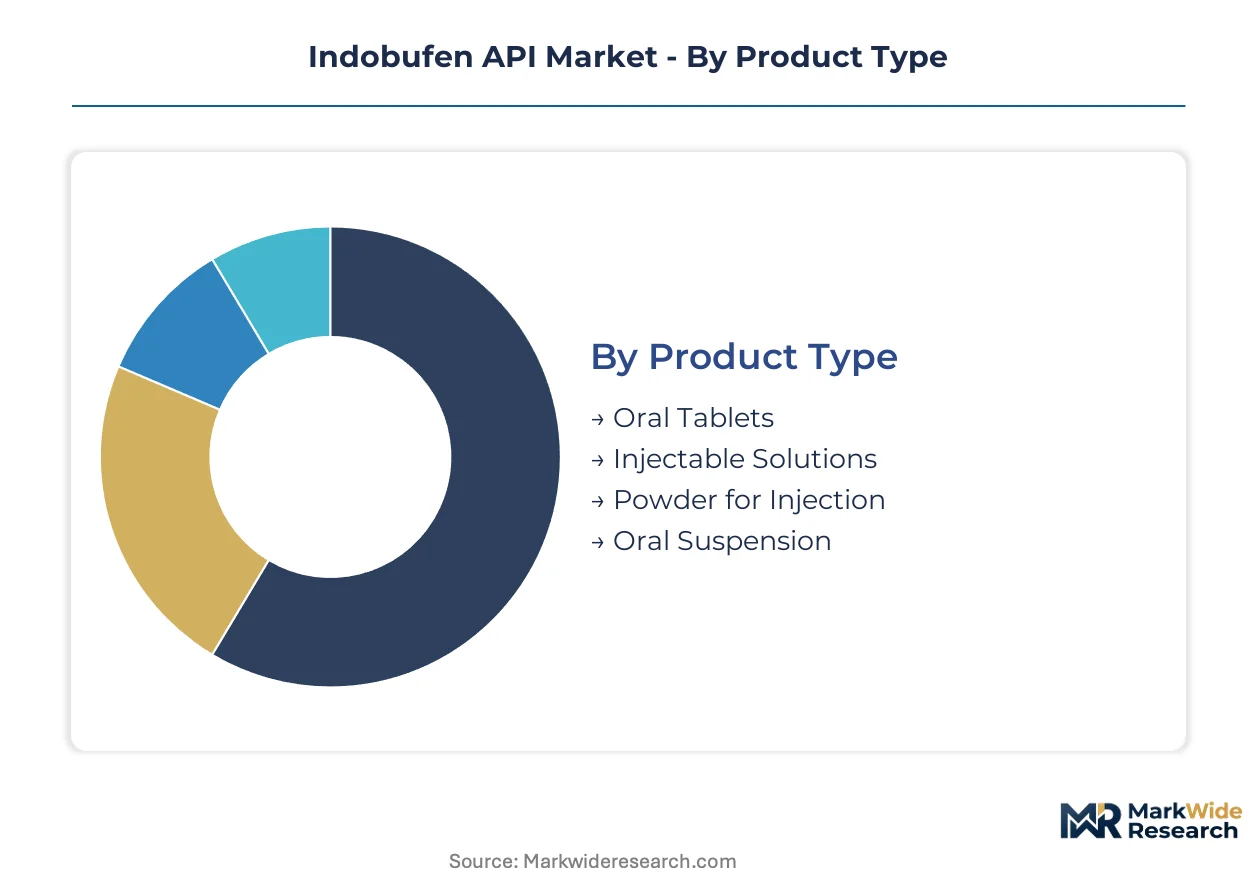
Indobufen API demand fragments across formulation technologies, procurement channels, and clinical settings. Each segment carries distinct specification requirements, regulatory pathways, and margin structures that shape supplier positioning.
Product Type:
Solid-state engineering and sterile manufacturing capabilities define competitive differentiation across dosage forms.
- Oral Tablets:Compressed dosage forms with defined dissolution profiles dominate chronic outpatient prescriptions. German and Italian formulators concentrate procurement for 200mg strength tablets under hospital formulary contracts.
- Injectable Solutions:Sterile liquid formulations requiring aseptic processing command premium positioning in perioperative care. French tertiary hospitals are expanding centralized compounding unit adoption for cardiovascular surgery protocols.
- Powder for Injection:Lyophilized presentations enable extended shelf stability for emergency stockpiles. Cold chain infrastructure requirements limit distribution to institutional purchasers with validated storage capacity.
- Oral Suspension:Liquid alternatives serve pediatric and geriatric populations with swallowing difficulties. Niche demand concentrates in specialized compounding pharmacies serving long-term care facilities.
Mature deployment sits with Oral Tablets. Newer deployment is concentrated in Injectable Solutions.
End User:
Procurement scale and regulatory sophistication vary sharply across institutional settings.
- Hospitals:Centralized purchasing departments negotiate multi-year API supply agreements for cardiovascular service lines. US group purchasing organizations extract volume commitments in exchange for therapeutic interchange protocols favoring indobufen over aspirin alternatives.
- Pharmacies:Retail and specialty dispensers extend reach into chronic antiplatelet management. Outpatient prescription volumes climb fastest in markets with established generic substitution incentives.
- Clinics:Ambulatory surgical centers source smaller batch sizes for limited perioperative protocols. Margin compression from wholesaler markups constrains API specification flexibility.
- Research Institutions:Academic medical centers procure reference standards and investigational lots for bioequivalence studies. CDSCO and FDA inspection readiness requirements extend qualification timelines for this segment.
Procurement concentration sits with Hospitals. Volume expansion is climbing fastest in Pharmacies.
Packaging Type:
Containment specifications align with stability requirements and administration settings.
- Blister Packs:Unit-dose aluminum-polymer laminates protect against moisture ingress for oral solid doses. European hospital pharmacies favor this format for automated dispensing cabinet compatibility.
- Vials:Borosilicate glass containers with rubber stoppers house sterile solutions for multi-dose withdrawal. Aseptic filling validation and container closure integrity testing dominate supplier qualification.
- Bottles:High-density polyethylene containers with desiccant caps serve bulk oral suspension and tablet packaging. Child-resistant closure mandates from the FDA and EMA shape design specifications.
- Ampoules:Single-use glass containers eliminate preservative requirements for injectable presentations. German CDMOs specialize in ampoule forming and sterilization for perioperative contract manufacturing.
Standard deployment sits with Vials. Specialized deployment is expanding most quickly in Blister Packs.
Distribution Channel:
Channel selection reflects order scale, regulatory documentation needs, and geographic reach requirements.
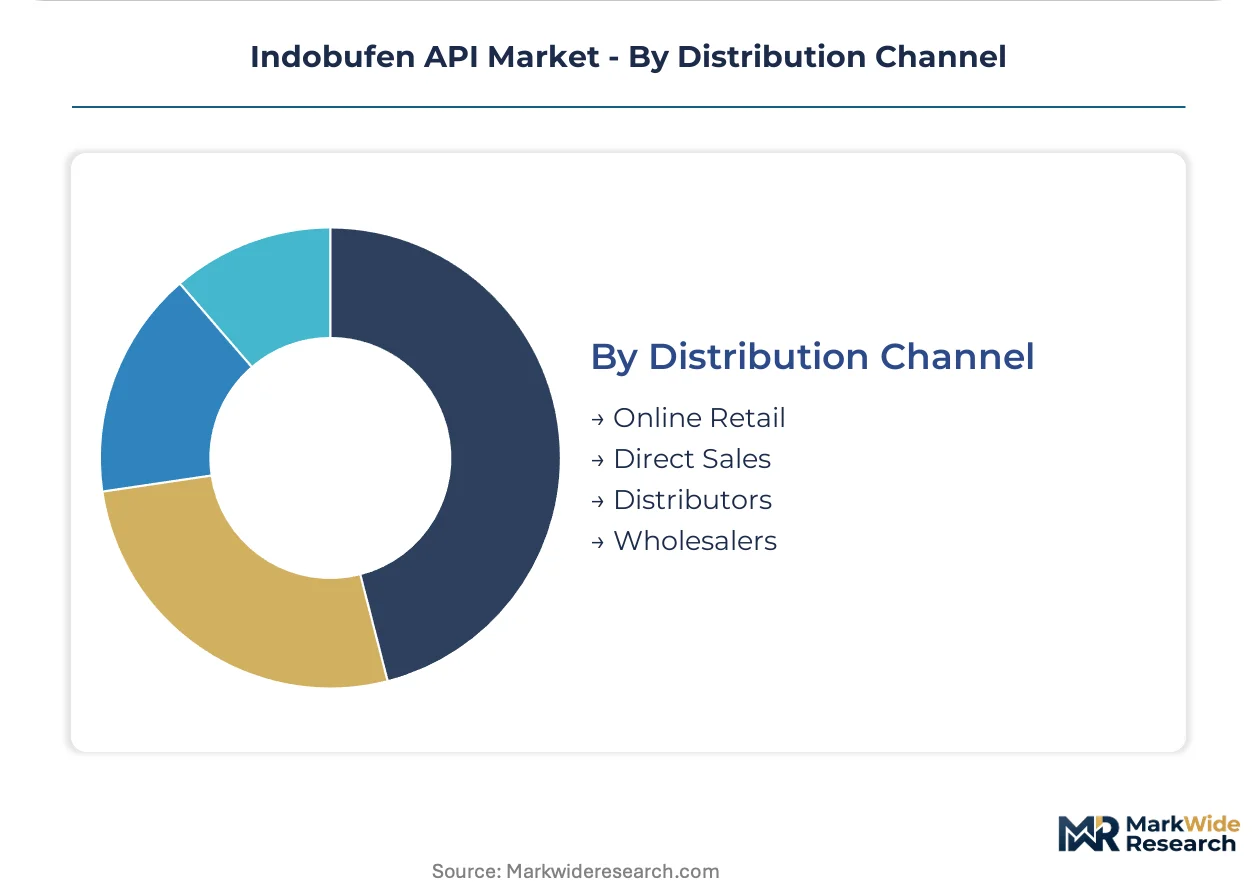
- Direct Sales:API manufacturers ship bulk active pharmaceutical ingredient directly to formulators with established GMP audits. Long-term supply agreements with Indian and Chinese finished dose producers anchor this channel.
- Distributors:Regional intermediaries aggregate demand from smaller formulators lacking direct supplier relationships. Inventory holding and documentation translation services justify margin capture.
- Wholesalers:Large-scale logistics providers manage temperature-controlled storage and just-in-time delivery for hospital networks. US pharmaceutical wholesalers extend payment terms that shape working capital requirements.
- Online Retail:Digital procurement platforms serve research institutions and specialty compounders with small-lot requirements. Certificate of analysis verification and chain-of-custody documentation remain friction points.
Established volume sits with Direct Sales. Channel diversification is gaining share fastest in Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phenylbutyric acid derivative production clusters in eastern China anchor raw-material supply chains for indobufen API synthesis. Hospital procurement networks in North America and Europe drive finished-dose demand through centralized cardiovascular formularies. Regulatory divergence across FDA, EMA, and NMPA jurisdictions shapes qualification timelines for cross-border suppliers.
United States
Group purchasing organizations consolidate antiplatelet API procurement under multi-year therapeutic interchange agreements. FDA risk-based GMP inspection scheduling extends supplier qualification cycles for ANDA filers. New Jersey and North Carolina pharmaceutical corridors concentrate sterile manufacturing capacity for perioperative injectable formulations.
Germany
Tertiary hospital cardiovascular service lines expand perioperative indobufen protocols for aspirin-intolerant surgical patients. EMA pharmacovigilance requirements mandate enhanced batch traceability for antiplatelet APIs. Bavarian and Baden-Württemberg CDMO clusters retrofit flow chemistry platforms for high-purity antiplatelet production.
China
NMPA ICH Q3D elemental impurity enforcement filters subscale producers from qualified supplier pools. Zhejiang and Jiangsu province chemical parks integrate backward into phenylbutyric acid starting materials for captive API supply. Domestic hospital procurement centralization under volume-based purchasing compresses margins for non-integrated manufacturers.
India
CDSCO enhanced stability data requirements for export registration unlock abbreviated inspection timelines to regulated markets. Maharashtra and Gujarat API corridors anchor generic formulator supply relationships with US and European customers. Hyderabad and Mumbai regulatory consulting clusters specialize in ANDA documentation for antiplatelet filings.
Italy
Lombardy pharmaceutical manufacturing districts sustain European-scale batch production for high-purity antiplatelet APIs. Swissmedic-aligned quality systems enable seamless cross-Alpine supply to German and French hospital networks. Milan-area analytical service providers validate polymorph-specific assays for generic developer submissions.
Indobufen API Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue continuous manufacturing specialization and aseptic injectable capacity. The supplier base concentrates among GMP-certified manufacturers with validated impurity profiling and dedicated antiplatelet production trains. Three archetypes dominate: vertically integrated Chinese producers with captive starting-material supply, European CDMOs with sterile processing expertise, and Indian export specialists with ANDA-track regulatory capabilities. Competitive dynamics center on backward integration into cyclization intermediates and qualification of real-time release testing platforms.
Within the integrated-manufacturer tier, Fuan Pharmaceutical and Dr Reddy's Laboratories Ltd exemplify archetypes spanning captive raw-material control and regulated-market export specialization respectively. Olon S.p.A occupies a position among European sterile-processing specialists serving perioperative injectable demand. These three anchors illustrate how geographic and capability positioning—not scale alone—determines access to hospital formulary contracts and premium pricing tiers for high-purity batches.
| Leading Market Players |
|---|
| Beijing Fukangren Biopharmaceutical |
| Fuan Pharmaceutical |
| Olon S.p.A |
| Suzhou Ryway Biotech |
| Boehringer Ingelheim |
| Teva Pharmaceutical Industries Ltd |
| Dr Reddy's Laboratories Ltd |
| IOL Chemicals and Pharmaceuticals Limited |
| Solara Active Pharma Sciences Limited |
| Others |
Pricing and Supply Chain Analysis
Hospital group purchasing organizations concentrate procurement volumes under multi-year sole-source agreements, anchoring contract-based long-term offtake as the dominant pricing model for indobufen API. This buyer concentration compresses margin structures for non-integrated suppliers while rewarding manufacturers with validated impurity profiling and dedicated production trains.
Pricing Analysis
High-volume hospital contracts trade margin for security, while low-volume research and specialty compounder segments retain pricing power. Price differentiation rests on GMP certification tier and volume scale, with FDA-inspected facilities commanding premiums over regional-standard suppliers. Cost compression in the oral tablet tier is intensifying because China's NMPA impurity enforcement raises rejection rates. Outpatient pharmacy channels exhibit the highest price sensitivity due to generic aspirin substitution pressure, whereas perioperative injectable buyers prioritize supply assurance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese suppliers of phenylbutyric acid cyclization intermediates that European and Indian API manufacturers draw from. Raw material dependencies include petroleum-derived phenylbutyric acid derivatives, palladium catalysts for hydrogenation steps, and specialized solvents for polymorph control. Tariff exposure on Chinese intermediate exports threatens production schedules for non-integrated formulators. Distribution runs through direct sales to GMP-audited finished dose producers, with regional distributors serving smaller compounders lacking qualification bandwidth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified GMP manufacturing capacity for antiplatelet APIs runs below hospital procurement demand, propping pricing power among validated suppliers. This supply-constrained structure favors incumbents with backward integration and regulatory track records.
For Market Incumbents: Anchor hospital formulary position through multi-year volume commitments to US group purchasing organizations. Invest in continuous flow synthesis retrofitting to reduce solvent consumption and batch cycle times. Defend against emerging Chinese producers with captive starting-material supply by accelerating real-time release testing qualification. For New Entrants and Emerging Players: Launch via contract manufacturing partnerships with German and French CDMOs specializing in perioperative injectable aseptic processing. Target the lyophilized powder-for-injection segment where cold chain infrastructure requirements limit incumbent competition. Pursue CDSCO export registration to unlock abbreviated FDA inspection timelines for regulated market access. For Investors and Strategic Acquirers: The window for entry favors European sterile-processing specialists with EMA-aligned quality systems and existing hospital network relationships. Over a multi-year horizon, consolidation pressure will concentrate value among manufacturers with closed-system containment and dedicated antiplatelet trains. Watch NMPA enforcement consistency as the signal indicating whether Chinese integrated producers gain or lose qualification momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cyclization Intermediates | Captive supply of phenylbutyric acid derivatives insulates margin structures from petroleum feedstock volatility. |
| Continuous Flow Synthesis Adoption | Real-time release testing integration reduces solvent consumption and accelerates batch cycle times for legacy plants. |
| CDSCO Export Registration Pathway | Enhanced stability data requirements unlock abbreviated inspection timelines to FDA and EMA regulated markets. |
| Injectable Formulation Capacity Expansion | Aseptic processing qualification opens premium pricing tiers in German and French perioperative care units. |
| Polymorph-Specific Assay Validation | Milan-area analytical service partnerships accelerate ANDA submission timelines for generic developers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with API manufacturing executives, regulatory affairs specialists, hospital procurement managers, and CDSCO registration consultants combined with FDA 483 observation databases, EMA inspection reports, and NMPA GMP certificates. Bottom-up volume estimates from dosage-form production data triangulated against top-down therapeutic class expenditure trends.
Segment-level modeling tracked oral tablets, injectable solutions, powder for injection, and oral suspensions across hospital, pharmacy, clinic, and research institution end users. Regional regulatory clusters captured FDA, EMA, NMPA, CDSCO, and Swissmedic jurisdiction differences in impurity thresholds and inspection protocols. CAGRs derived from weighted average of historical volume trends and procurement contract visibility, with continuous manufacturing adoption rates and hospital formulary consolidation pace as key sensitivity inputs.
The model assumes a particular technology adoption path; alternative pathways for continuous flow synthesis would alter the outlook if batch reactor retrofits stall due to capital constraints. Forecasts reflect assumptions regarding NMPA enforcement consistency, petroleum feedstock price bands, and hospital procurement centralization momentum. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Anticoagulant Reversal Drugs Market
Pharmaceuticals
Unit Dose Manufacturing Market
Pharmaceuticals
Hydroxycarbamide Market
Pharmaceuticals
Meningococcal Vaccines Market
Pharmaceuticals
India Nicotine Replacement Therapy Market
Pharmaceuticals
Myasthenia Gravis Therapeutics Market
Pharmaceuticals
Zoldonat Injection Market
Pharmaceuticals
Global Rotavirus Vaccine Market
Pharmaceuticals
Contraceptive Drugs Market
Pharmaceuticals
Tapentadol Market
Pharmaceuticals
Antiglaucoma Drugs Market
Pharmaceuticals
Global Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
Propofol Market
Pharmaceuticals
Ginkgo Leaf Extract and Dipyridamole Injection Market
Pharmaceuticals
Bladder Cancer Treatment Drugs Market
Pharmaceuticals
B7-H3 Antibody Market