
 Asset Management System Market | 2026-2036
Asset Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Asset Management System Market Analysis
Modular bundling of RFID hardware with cloud analytics dashboards is broadening buyer choice across mid-market enterprises. Zebra Technologies leverages its end-to-end barcode and RFID portfolio to anchor enterprise deployments in warehousing and logistics. Honeywell International competes through ruggedized mobile computers that extend field asset visibility for utilities and energy operators. Siemens AG specializes in industrial IoT integrations that dominate manufacturing plant floor implementations.
An asset management system comprises software platforms and connected hardware infrastructure that track, value, and optimize physical and financial asset portfolios through real-time data ingestion, depreciation algorithms, and lifecycle analytics. These systems integrate RFID tags, GPS modules, and ERP connectors to automate inventory reconciliation, reduce ghost asset rates, and enforce maintenance schedules across distributed operations. Cloud-based deployment now leads adoption as financial institutions and government agencies migrate from legacy on-premises installations to reduce capital expenditure and enable remote accessibility. Portfolio management functionality captures the largest margin pool among functionality segments, while compliance monitoring grows fastest as ESG reporting obligations intensify across corporate and non-profit end users.
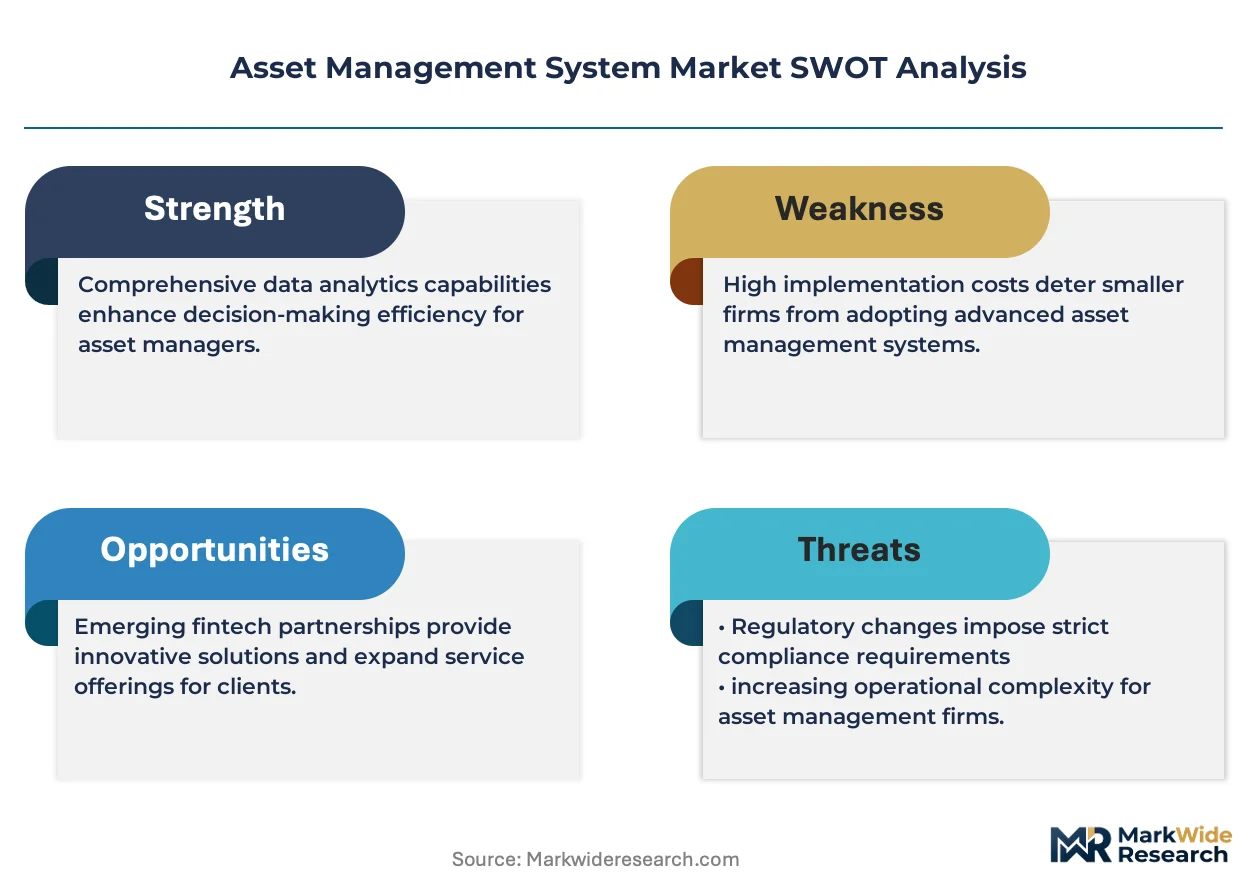
The SEC mandates climate risk disclosures that force asset managers to trace carbon exposure across real estate and fixed income holdings. EU regulators enforce CSRD and GDPR requirements that reshape how European financial institutions store asset-level data and report sustainability metrics. ISO 55000 standards provide the asset management framework that governs certification pathways for infrastructure operators and public sector entities. Stakeholders must monitor how evolving ESG disclosure rules in North America and Europe will redefine data architecture requirements and vendor qualification criteria.
Market Dynamics
The SEC's climate disclosure mandate is forcing asset managers to rebuild data infrastructure around carbon tracking, triggering wholesale replacement of legacy portfolio accounting systems that cannot tag emissions at the holding level.
Growth Catalysts
- RFID hardware convergence:Passive UHF tags combined with cloud analytics platforms are cutting deployment costs for mid-market manufacturers tracking tooling and work-in-process inventory.
- EU CSRD compliance deadlines:European fund managers must report asset-level sustainability metrics by 2026, accelerating replacement of spreadsheet-based ESG tracking with automated disclosure engines.
- Pension fund modernization:US public retirement systems in California, Texas, and New York are consolidating legacy mainframe installations into unified SaaS platforms.
Market Restraints
- Semiconductor supply concentration:RFID chip fabrication concentrates in Taiwan and South Korea, exposing hardware vendors to geopolitical disruption and allocation delays.
- ISO 55000 certification complexity:Infrastructure operators face 18-24 month audit timelines that slow procurement decisions and extend sales cycles.
- Open-source ERP substitutes:Odoo and ERPNext community editions are capturing price-sensitive municipal and educational buyers who would otherwise license commercial asset modules.
Strategic Opportunities
- India manufacturing digitization:PLI scheme beneficiaries in electronics and pharmaceuticals are deploying asset tracking to meet export traceability requirements.
- Digital twin convergence:Integration of RFID location data with Siemens MindSphere and GE Digital platforms enables predictive maintenance for rotating equipment.
- Subscription pricing penetration:Per-asset monthly billing models are unlocking municipal utilities and school districts previously blocked by capex approval thresholds.
Industry Challenges
- OT-IT integration complexity:Manufacturing customers struggle to bridge plant-floor SCADA systems with corporate ERP asset registers without custom middleware development.
- Cybersecurity skill scarcity:Utilities and energy operators lack personnel to harden field-deployed GPS and cellular gateways against remote access exploits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asset Management System Market |
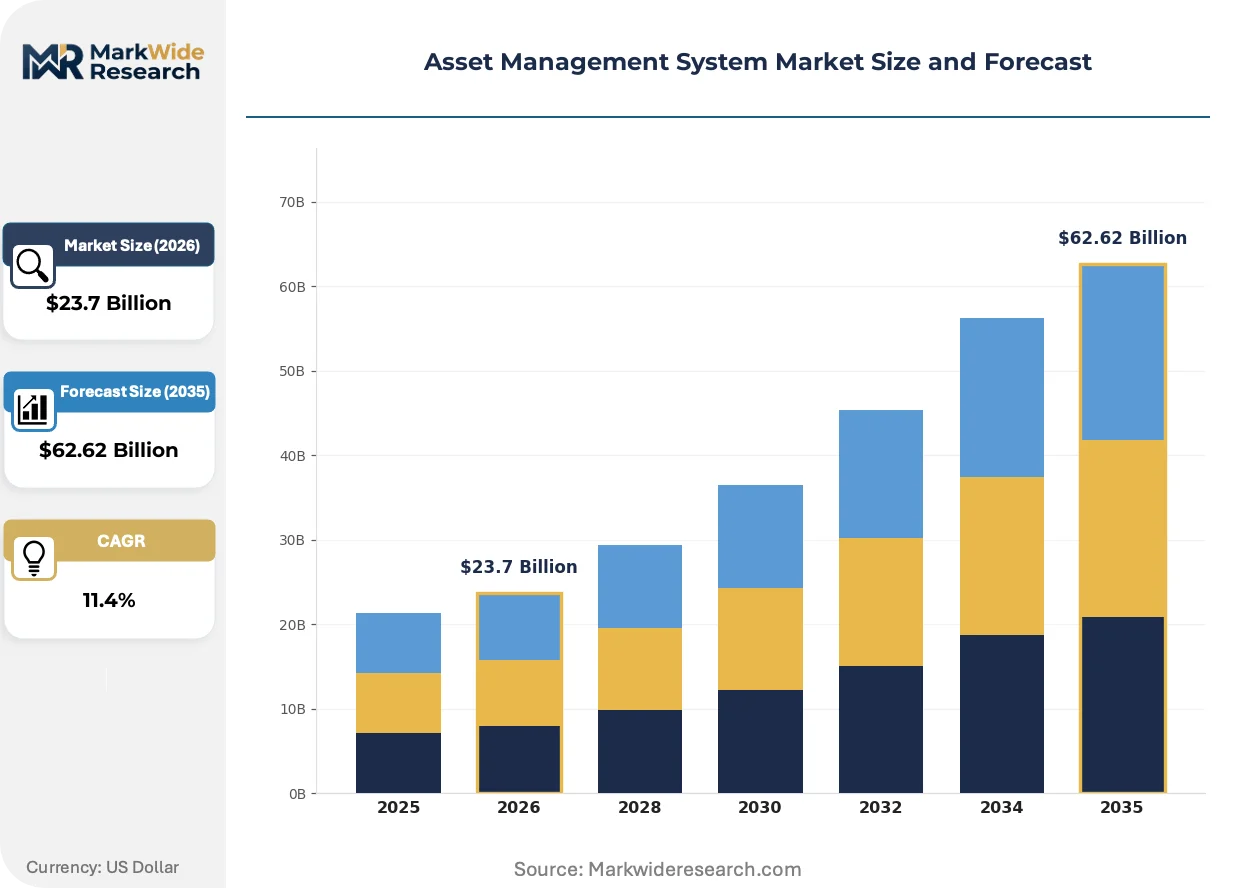
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Corporate, Government, Financial Institutions, Non-Profit Organizations Functionality: Portfolio Management, Risk Management, Performance Tracking, Compliance Monitoring Asset Type: Real Estate, Equities, Fixed Income, Commodities |
| Companies Covered | Zebra Technologies Corporation, Honeywell International, Trimble Inc., Impinj, Datalogic S.p.A., Siemens AG, Motorola Solutions, Stanley Black and Decker, Topcon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asset Management System Market Emerging Trajectories
Cloud-native architectures are dismantling the installed base of on-premises asset registries, while regulatory pressure fuses sustainability reporting directly into core financial systems rather than bolt-on modules.
Passive RFID with RAIN protocol compatibility is overtaking active beacon systems for indoor asset location in warehousing and healthcare facilities. Retail distribution centers are deploying item-level tagging at pallet scale to eliminate cycle-count labor. The shift is compressing hardware margins while expanding recurring software attach rates.
EU CSRD and SEC climate disclosure rules are mandating granular carbon attribution across fixed income and real estate portfolios. Asset managers must trace emissions through supply chains to the underlying facility or project level. European insurers and US pension fiduciaries are prioritizing vendors with pre-built emissions calculation engines and audit-ready data lineage.
Buyers are unbundling implementation services from software licenses, contracting specialized systems integrators for data migration while negotiating direct SaaS terms. This disintermediation pressures vendor professional services margins and shifts relationship ownership to regional implementation partners. The pattern is most pronounced in Germany and the Netherlands where mid-size industrials favor local integrators over vendor captive teams.
Asset Management System Market Segmentation
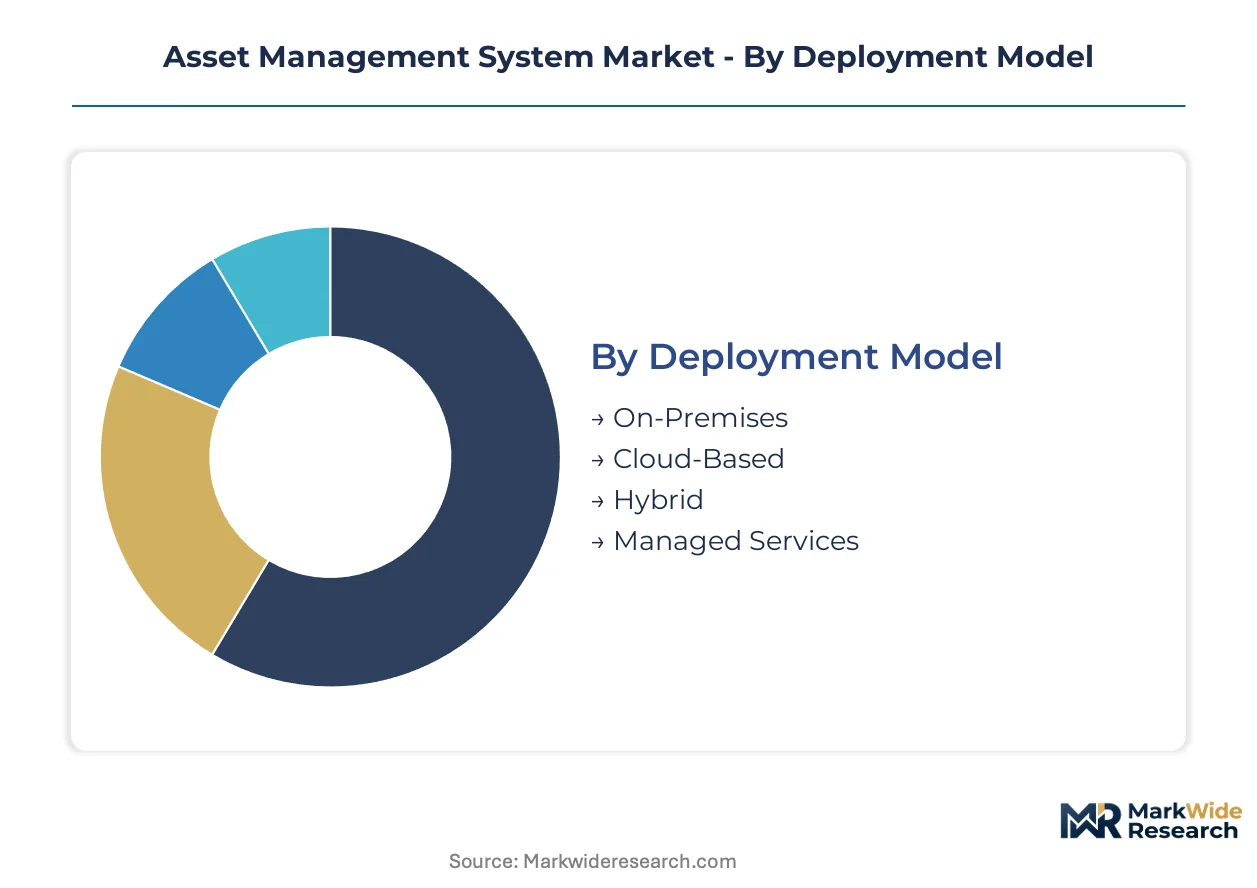
Asset management systems fragment across deployment architecture, user sophistication, and regulatory exposure. Procurement patterns diverge sharply between legacy infrastructure replacement and greenfield cloud adoption, with compliance functionality commanding premium pricing.
Deployment Model:
Replacement cycles for legacy on-premises installations are shortening as hybrid architectures bridge capital constraints with scalability demands.
- Cloud-Based:Multi-tenant SaaS architectures with API-first design enable pension funds and sovereign wealth vehicles to consolidate fragmented legacy installations. California and New York public retirement systems are migrating mainframe asset registries to cloud-native platforms to reduce operational expenditure and enable remote fiduciary access.
- Hybrid:Split deployments maintain sensitive portfolio data on-premises while pushing analytics workloads to public cloud infrastructure. German and Dutch mid-size industrials favor this model to satisfy GDPR data residency requirements without sacrificing computational elasticity.
- On-Premises:Single-tenant installations persist among defense contractors and intelligence-adjacent entities with air-gapped security mandates.
- Managed Services:Outsourced infrastructure operations with vendor-managed patching and backup recovery appeal to municipal utilities lacking internal IT capacity.
Cloud-Based sits at the top of the volume ranking, with Hybrid climbing the fastest.
End User:
Customer procurement sophistication separates price-sensitive municipal buyers from institutional investors with dedicated technology evaluation committees.
- Financial Institutions:Asset managers, insurance underwriters, and pension fiduciaries require real-time portfolio reconciliation across multi-asset class holdings. SEC climate disclosure mandates are forcing wholesale replacement of spreadsheet-based ESG tracking with automated disclosure engines that trace carbon exposure to facility level.
- Government:Federal, state, and municipal agencies track physical infrastructure from military equipment to transit rolling stock. ISO 55000 certification requirements extend procurement timelines to 18-24 months for infrastructure operators.
- Corporate:Industrial conglomerates and real estate investment trusts manage depreciating physical assets alongside financial portfolios.
- Non-Profit Organizations:Endowments and foundations with restricted gift instruments face simplified compliance burdens but limited implementation budgets.
Financial Institutions capture the dominant revenue share, while Government expands most quickly under infrastructure modernization programs.
Functionality:
Margin concentration follows regulatory complexity rather than transaction volume, with compliance modules achieving pricing leverage unavailable to core accounting functions.
- Portfolio Management:Core position-keeping, performance attribution, and rebalancing engines constitute the foundational software layer. Real-time data ingestion from prime brokers and custodians differentiates institutional-grade platforms from mid-market alternatives.
- Compliance Monitoring:Automated rule engines track regulatory limits, ESG thresholds, and fiduciary constraints across distributed decision-makers. EU CSRD deadlines are accelerating replacement of manual disclosure processes with audit-ready data lineage systems.
- Risk Management:Stress testing and scenario analysis modules quantify exposure across interest rate, credit, and liquidity dimensions.
- Performance Tracking:Benchmark comparison and attribution analytics separate alpha generation from market beta for investor reporting.
Portfolio Management retains the largest installed base, though Compliance Monitoring gains share fastest under disclosure rule proliferation.
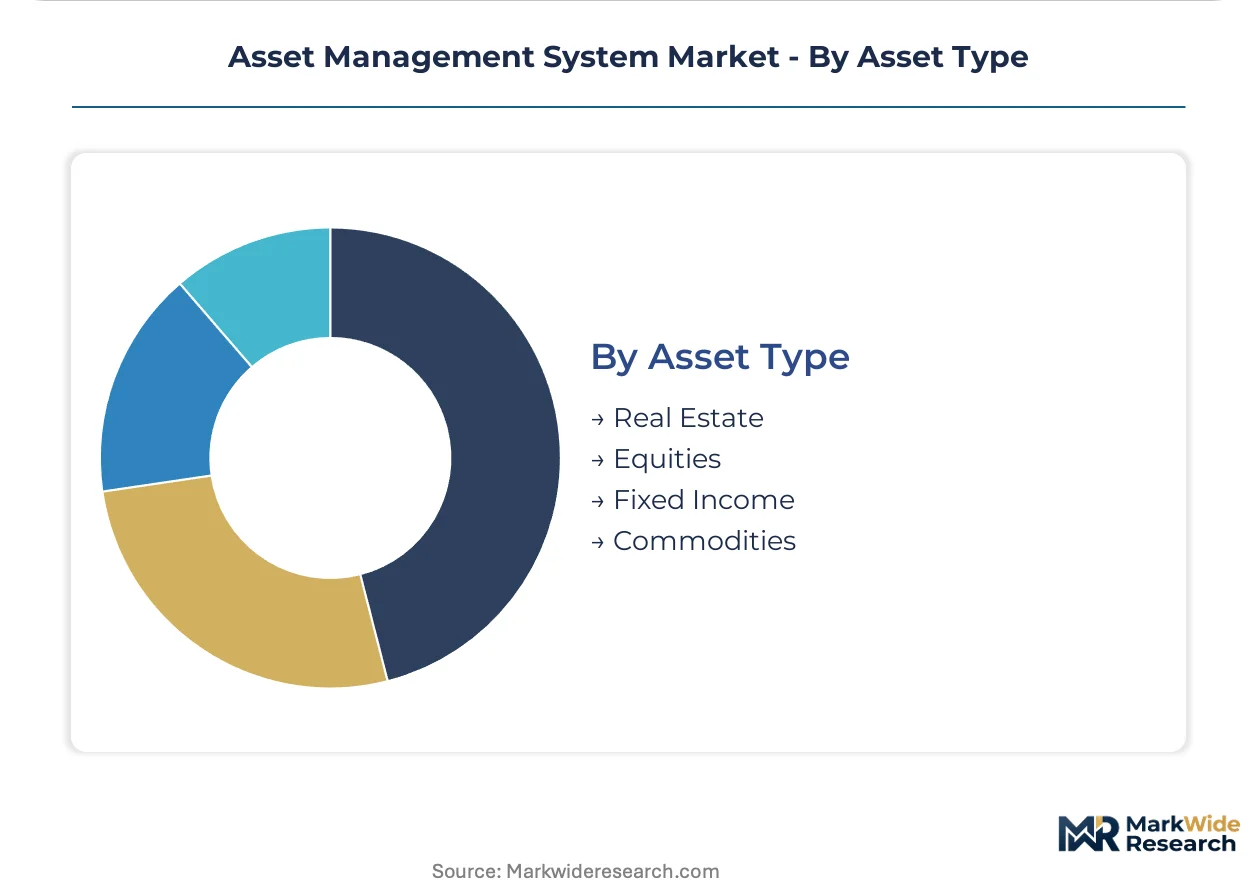
Asset Type:
Data granularity requirements separate liquid securities with standardized identifiers from illiquid physical assets requiring custom valuation methodologies.
- Fixed Income:Bond portfolios demand cash flow modeling, duration analysis, and credit surveillance across sovereign, municipal, and corporate issuers. SEC climate rules now require tracing emissions through supply chains to underlying project or facility level for green bond verification.
- Real Estate:Property-level asset management integrates lease administration, capital planning, and sustainability metrics for institutional portfolios. European insurers and US pension fiduciaries prioritize vendors with pre-built emissions calculation engines for building-level carbon attribution.
- Equities:Public equity holdings require real-time pricing feeds and corporate action processing with minimal latency.
- Commodities:Physical and derivative commodity exposure demands location-specific storage tracking and contango/backwardation analytics.
Fixed Income leads by revenue contribution, with Real Estate showing the steepest expansion trajectory as ESG integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The asset management system industry traces its commercial origins to United States enterprise software development in the 1990s, when pension funds and institutional investors first digitized portfolio accounting. From this North American foundation, adoption patterns now diverge across regulatory jurisdictions and industrial digitization timelines.
United States
California and New York public retirement systems are consolidating legacy mainframe installations into unified cloud platforms. SEC climate disclosure mandates are forcing asset managers to rebuild data infrastructure around carbon tracking capabilities. The Texas energy corridor drives demand for ruggedized field asset visibility solutions across utilities and pipeline operators.
Germany
Mid-size industrials in Baden-Württemberg and North Rhine-Westphalia favor hybrid deployment models to satisfy GDPR data residency requirements. EU CSRD compliance deadlines are accelerating replacement of manual ESG disclosure processes with automated engines. The Eindhoven-adjacent logistics cluster in western Germany deploys RAIN protocol RFID at pallet scale to eliminate cycle-count labor.
China
Manufacturing digitization in the Yangtze River Delta and Pearl River Delta is driving RFID-enabled asset tracking for export traceability. MIIT industrial internet policies encourage integration of plant-floor SCADA systems with corporate asset registers. Shenzhen-based electronics assemblers deploy item-level tagging to meet dual carbon goals and supply chain visibility mandates.
India
PLI scheme beneficiaries in Maharashtra and Gujarat are deploying asset tracking to meet pharmaceutical and electronics export requirements. SEBI regulations for mutual fund disclosure are modernizing back-office infrastructure at Mumbai-headquartered asset managers. The Bangalore software corridor hosts implementation partners serving mid-market enterprises migrating from spreadsheet-based tracking.
Japan
METI industrial efficiency standards are accelerating RFID adoption in Nagoya-area automotive component manufacturing. Pension funds in Tokyo are replacing legacy portfolio accounting systems with cloud-native platforms enabling remote fiduciary access. Osaka-based industrial conglomerates integrate asset management with predictive maintenance platforms for rotating equipment.
Asset Management System Market Vendor Landscape
The competitive structure tilts toward diversified industrial technology conglomerates with established barcode and RFID hardware portfolios. Market concentration remains moderate, with no single vendor commanding dominant share across both financial portfolio management and physical asset tracking segments. Two strategic archetypes predominate: end-to-end platform providers bundling hardware with cloud analytics, and specialized component suppliers focusing on RFID chips or ruggedized mobile computers. Competitive moves center on vertical integration into semiconductor fabrication and strategic partnerships with systems integrators to capture implementation services revenue.
Within the diversified technology tier, Zebra Technologies Corporation and Honeywell International occupy positions exemplifying end-to-end platform breadth. Siemens AG anchors the industrial IoT integration archetype, representing vendors that dominate manufacturing plant floor implementations through SCADA and ERP connectivity. Among RFID component specialists, Impinj sits within the pure-play semiconductor tier, while Motorola Solutions exemplifies the ruggedized field hardware positioning targeting utilities and public safety operators.
| Leading Market Players |
|---|
| Zebra Technologies Corporation |
| Honeywell International |
| Trimble Inc. |
| Impinj |
| Datalogic S.p.A. |
| Siemens AG |
| Motorola Solutions |
| Stanley Black and Decker |
| Topcon Corporation |
| Others |
Supply Flow & Price Mechanics
Backward integration into RFID semiconductor fabrication anchors supply security and pricing power for hardware vendors serving asset-intensive industries. Zebra Technologies and Honeywell International leverage captive chip sourcing from Taiwan and South Korea to buffer against allocation volatility while commanding premium positioning in enterprise warehousing deployments.
Pricing Analysis
Subscription-based SaaS tiers with per-asset monthly billing dominate software revenue streams, separating enterprise-grade compliance modules from mid-market tracking dashboards. Price differentiation hinges on ISO 55000 certification support and ESG disclosure engine sophistication. Cost compression in mid-market RFID hardware is intensifying because passive UHF tag commoditization compresses margins. Municipal utilities and school districts exhibit highest price sensitivity due to capex approval constraints, while pension funds demonstrate lowest sensitivity given fiduciary mandates for audit-ready data lineage.
Supply Chain Analysis
Reverse logistics flows for RFID reader refurbishment and mobile computer remanufacturing extend hardware lifecycle value across utility and energy operator fleets. Semiconductor fabrication concentrates in Taiwan, South Korea, and mainland China, exposing vendors to geopolitical disruption and foundry allocation delays. Raw material dependencies span silicon wafers, lithium-ion cells for field gateways, and rare earth elements for antenna substrates. Single-source vulnerability in Taiwan-based RFID chip production represents the dominant structural risk. Distribution runs through authorized systems integrators in Germany and the Netherlands, with direct SaaS contracting accelerating in North American pension fund verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The asset management system market functions as a regulatory compounder where SEC climate disclosure mandates and EU CSRD deadlines are forcing wholesale infrastructure replacement across institutional portfolios.
For Market Incumbents: Cement market position by deepening captive semiconductor supply relationships with Taiwan-based foundries to insulate against allocation volatility. Invest in pre-built emissions calculation engines to capture ESG disclosure premiums from European insurers and US pension fiduciaries. Defend against open-source ERP substitutes by embedding compliance automation that spreadsheet-based tracking cannot replicate. For New Entrants and Emerging Players: Cloud-native SaaS delivery models unlock municipal utilities and school districts previously blocked by on-premises capex thresholds. Target mid-market manufacturers in India's PLI scheme corridors with RFID-enabled export traceability bundles. Lead with subscription pricing that bypasses procurement committee approval cycles and accelerates land-and-expand adoption. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 55000 certification complexity extends sales cycles beyond eighteen months and strains smaller vendor cash conversion. Long-term viability favors platforms with dual strength in financial portfolio management and physical asset tracking segments. Monitor CSRD implementation velocity across European fund managers as inflection indicator for compliance module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| RFID Semiconductor Backward Integration | Captive chip supply from Taiwan foundries insulates Zebra and Honeywell against geopolitical allocation disruption. |
| Cloud-Native SaaS Platform Launch | Per-asset monthly billing unlocks municipal utilities blocked by traditional capex approval thresholds. |
| ESG Disclosure Engine Development | Pre-built emissions calculation capabilities capture premium pricing from SEC and CSRD-mandated pension fiduciaries. |
| Systems Integrator Partnership Expansion | German and Dutch regional integrators disintermediate vendor professional services and own customer relationships. |
| Digital Twin Platform Integration | Siemens MindSphere connectivity enables predictive maintenance premiums for rotating equipment in Japanese automotive plants. |
Methodological Framework
Multiple input streams — primary interviews with asset management software executives, RFID hardware procurement leads, and pension fund technology committees — were reconciled against secondary validation from SEC climate disclosure filings, EU CSRD regulatory texts, and ISO 55000 certification databases. Bottom-up triangulation across vendor revenue disclosures and top-down cross-reference against industrial IoT deployment statistics anchored market sizing.
Historical trend analysis against expert panel input shaped the projection framework across deployment architecture, end-user sophistication tiers, and regulatory exposure segments. CAGRs were derived from segment-level growth rate reconciliation across the analysis window. RFID hardware volume assumptions fed from Taiwan Semiconductor Industry Association trade data, while SaaS adoption curves incorporated California and New York public retirement system migration timelines.
Geopolitical disruption in Taiwan and South Korea semiconductor supply, CSRD implementation delays across European fund managers, and open-source ERP substitution acceleration in municipal verticals are the dominant revision risks to modeled outputs. Practitioners should monitor foundry allocation announcements, EU regulatory guidance updates, and Odoo community edition feature expansion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
Capital Expenditure Market
Asset Management
Equity Management Tool Market
Asset Management
Mutual Fund Assets Market
Asset Management
Canada Pension Fund Market
Asset Management
India Mutual Fund Market
Asset Management
US Pension Funds Market
Asset Management
Fund Management Fee Market
Asset Management
Healthcare Asset Management Market
Asset Management
India AMC Industry Market
Asset Management
Asia-Pacific Utilities Asset Management Market
Asset Management
Global Asset Performance Management Market
Asset Management
Asset and Wealth Management Market
Asset Management
India Asset Management Market
Asset Management
US Healthcare Assets Management Market
Asset Management
Smart Asset Management Market
Asset Management
Canada Asset Management Market