
 India Private Equity Market | 2026-2036
India Private Equity Market Size, Share, and Industry Trends Forecast 2026-2036
India Private Equity Market Outlook
Institutional-grade fund governance is reorganizing capital formation across Indian private markets. Warburg Pincus leverages its healthcare and financial services specialization to anchor large-cap buyout transactions. Sequoia Capital India sustains early-stage dominance through concentrated bets on SaaS and consumer technology. Blackstone Group competes on scale, controlling one of the largest real estate and infrastructure portfolios in the country.
Private equity denotes negotiated capital commitments into unlisted companies, typically structured through limited partnership agreements with ten-to-twelve-year horizons and carried-interest compensation for general partners. The asset class serves as a critical bridge between long-dated institutional liabilities and high-growth enterprises lacking public market access. Expansion-stage deployment leads by volume, as companies seek pre-IPO capital to scale operations without immediate listing pressure. Closed-end fund structures concentrate the bulk of committed capital, matching illiquid underlying assets with locked-in investor timelines. Sovereign wealth funds represent the fastest-growing investor category, channeling Abu Dhabi and Singaporean capital into Indian infrastructure and technology platforms.
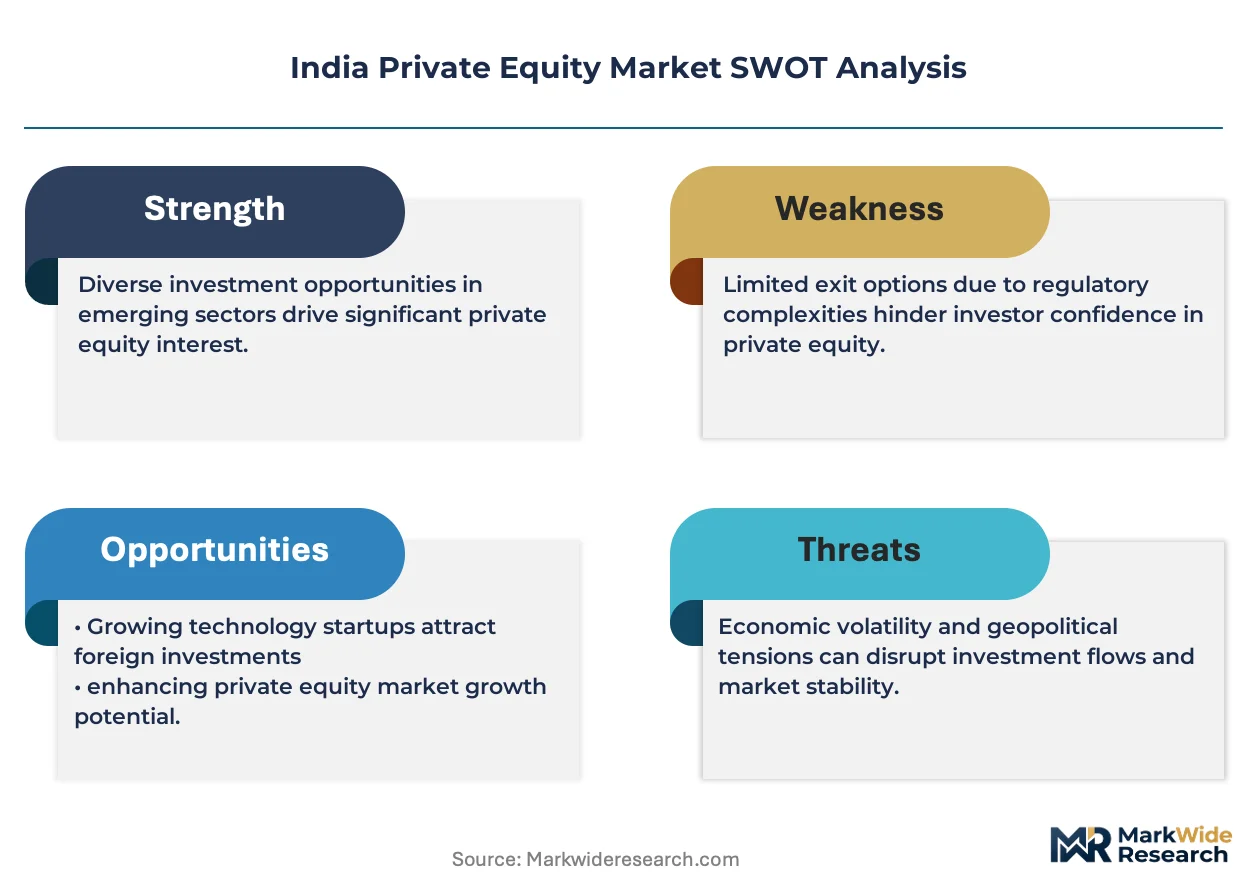
SEBI's Alternative Investment Fund regulations mandate quarterly disclosures and restrict leverage, shaping how domestic and offshore managers structure India-dedicated vehicles. RBI oversees foreign portfolio and direct investment routes, with FEMA provisions determining currency convertibility and repatriation terms for offshore limited partners. The PLI scheme and DPIIT startup recognition framework create qualified deal pipelines by subsidizing capital-intensive sectors. Stakeholders must monitor SEBI's evolving AIF classification criteria and RBI's foreign investment threshold adjustments to preserve capital deployment efficiency.
Market Dynamics
SEBI's tightening of AIF disclosure standards is compressing fundraising timelines and forcing domestic managers to restructure carry terms, while offshore capital from Abu Dhabi and Singaporean sovereign vehicles is reshaping LP composition in India-dedicated vehicles.
Growth Catalysts
- Production-Linked Incentive Scheme:The PLI framework channels institutional capital into domestic manufacturing by subsidizing capital-intensive sectors including semiconductors and renewable energy components, creating qualified deal pipelines for growth equity.
- Startup India Recognition:DPIIT certification unlocks tax holidays and simplified compliance for venture-backed companies, accelerating early-stage formation in Bengaluru and Hyderabad technology corridors.
- Real Estate Investment Trust Liberalization:SEBI's REIT regulations permit fractional ownership structures that attract retail participation, expanding the investor base beyond traditional institutional LPs for infrastructure and commercial assets.
Market Restraints
- Foreign Exchange Management Act Friction:RBI's FEMA provisions impose currency convertibility restrictions and repatriation timelines that extend exit horizons for offshore limited partners, compressing IRR targets.
- Valuation Input Volatility:Rupee-dollar fluctuations and domestic interest rate movements distort comparable company analysis, forcing general partners to maintain wider bid-ask spreads during negotiations.
- Domestic Banking Concentration:Debt financing for buyout transactions relies heavily on public sector banks with conservative collateral requirements, limiting leverage capacity relative to developed markets.
Strategic Opportunities
- Tier-II City Penetration:Jaipur, Indore, and Kochi present undercapitalized consumer and logistics platforms where operating metrics trail Mumbai and Delhi benchmarks by 40-60 percent, offering multiple expansion potential.
- Climate Technology Convergence:Battery storage and green hydrogen production create intersection points between industrial buyout expertise and venture growth capital, requiring hybrid fund structures.
- Insurance Sector Distribution:Bancassurance partnerships and direct-to-customer channels are displacing traditional agent networks, creating carve-out opportunities for financial services specialists.
Industry Challenges
- Fund Administration Talent Scarcity:Experienced CFOs and compliance officers capable of navigating SEBI's quarterly disclosure requirements command premium compensation, inflating operating expense ratios.
- Legacy Portfolio Company Integration:Buyout targets with founder-operated governance structures require extensive management overlay to professionalize financial reporting and board composition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Private Equity Market |
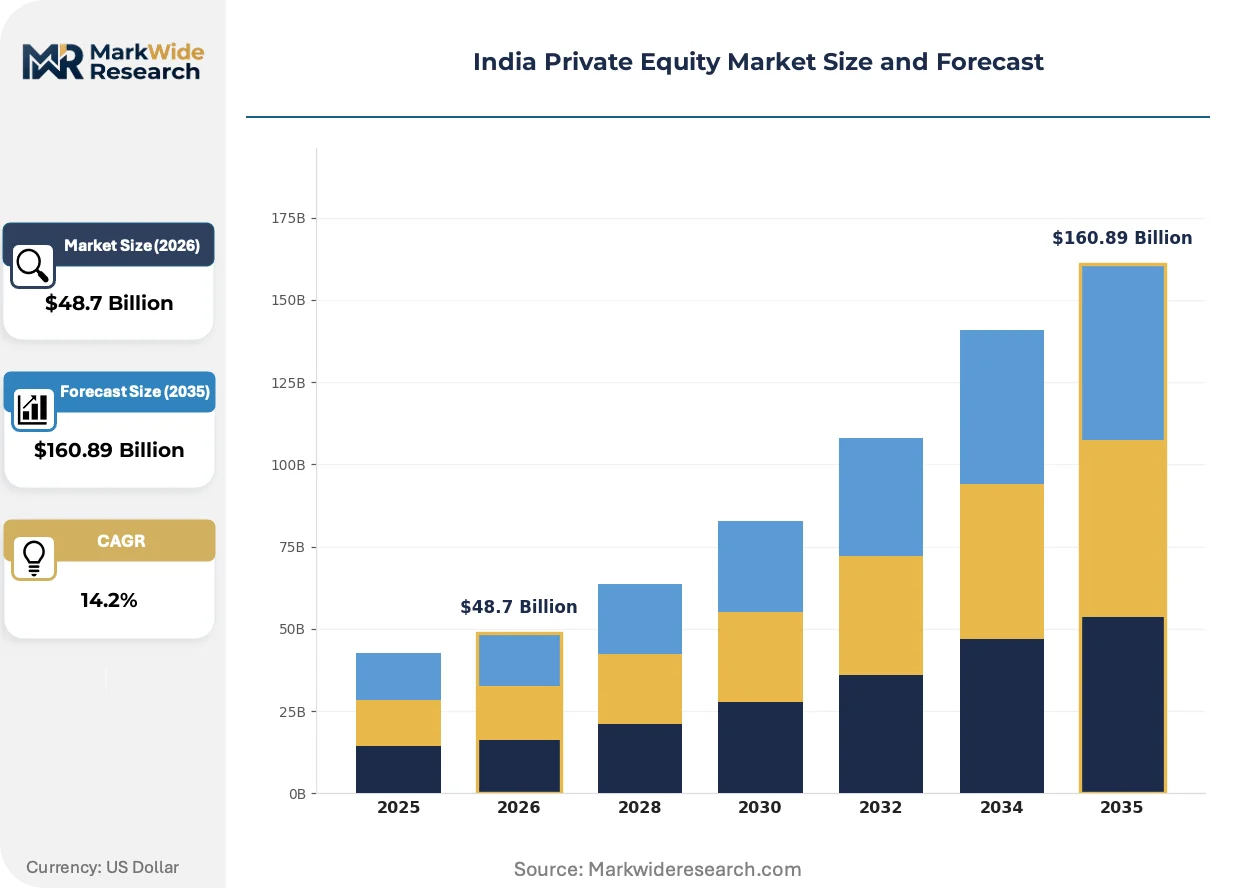
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $160.89 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Stage: Seed, Early Growth, Expansion, Late Stage Fund Structure: Closed-end, Open-end, Fund of Funds, Mezzanine Asset Class: Equity, Debt, Real Estate, Infrastructure Investor Type: Pension Funds, Family Offices, Sovereign Wealth Funds, Others |
| Companies Covered | Warburg Pincus, ICICI Venture, Blackstone Group, Accel Partners, Sequoia Capital India, KKR & Co., Bain Capital, General Atlantic, Carlyle Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Private Equity Market Strategic Shifts
Technology platforms are fragmenting traditional intermediation layers across Indian private markets, compressing information asymmetries while creating new data infrastructure requirements for due diligence and portfolio monitoring.
Artificial intelligence-driven due diligence tools are decomposing the traditional reliance on manual financial statement analysis. Growth equity and venture capital managers in Mumbai and Delhi are deploying natural language processing to screen regulatory filings and news sentiment at seed and Series A stages. This compression of initial screening timelines is enabling smaller teams to evaluate larger opportunity sets without proportional headcount expansion.
SEBI's 2024 amendments to AIF Category II and III regulations mandate granular portfolio-level disclosures on leverage and concentration limits. Domestic fund managers must now report derivative exposures and related-party transactions quarterly, increasing compliance overhead. Offshore managers structuring India-dedicated vehicles are responding by segregating domestic and international LP classes to preserve confidentiality for non-Indian investors.
Family offices and high-net-worth individuals are displacing traditional fund-of-funds as the primary capital source for first-time managers. Direct co-investment rights and separately managed accounts are replacing standard limited partnership commitments in Mumbai and Gujarat wealth channels. This behavioral shift is most visible in technology and healthcare verticals where operational expertise substitutes for track record requirements.
India Private Equity Market Segmentation
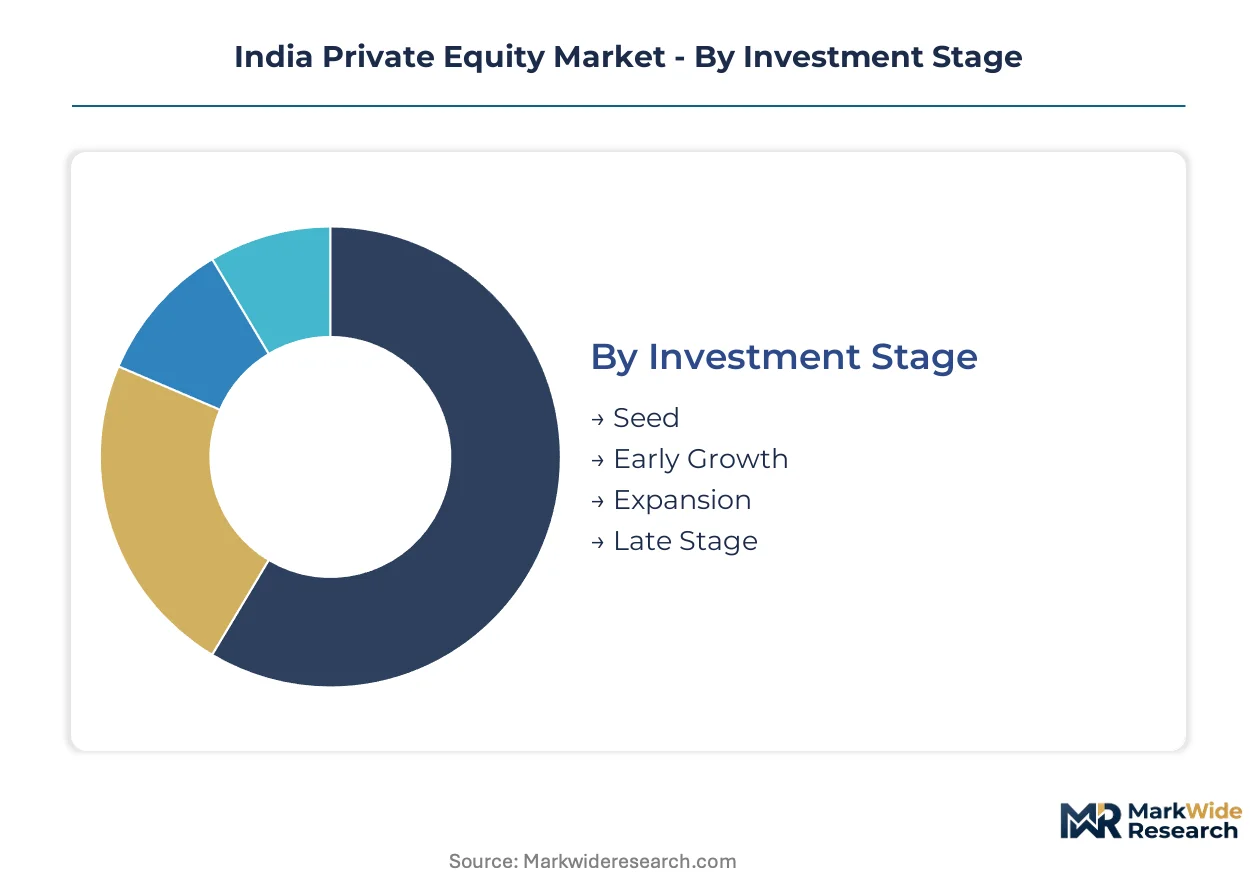
India's private equity landscape fragments across four distinct dimensions that determine capital deployment velocity, regulatory treatment, and return profile. Each segmentation axis reveals how fund managers match liability structures with underlying asset liquidity and growth trajectories.
Investment Stage:
Later-stage segments face intensifying substitution pressure from public market alternatives and structured credit products, compressing risk-adjusted return premiums for growth equity relative to early-stage venture.
- Seed:Initial capital injections into pre-revenue enterprises, typically deployed through convertible instruments or SAFE structures. Concentrated demand in Bengaluru and Hyderabad SaaS corridors, driven by SEBI's relaxed AIF Category I norms for startup-focused vehicles.
- Early Growth:Series A and B rounds financing product-market expansion and team scaling. Mumbai and Delhi NCR absorb the majority of commitments, with DPIIT certification unlocking tax holidays that improve net IRR calculations for offshore LPs.
- Expansion:Pre-IPO capital for revenue-positive companies seeking geographic or vertical diversification without immediate listing pressure. Deployment volumes concentrate in consumer technology and financial services platforms where unit economics have stabilized.
- Late Stage:Structured equity and pre-IPO secondary transactions providing liquidity to early investors while delaying public market entry. SEBI's tightening disclosure timelines for AIF Category II vehicles are compressing fundraising windows for this segment.
Expansion-stage deployment retains volume leadership; Seed holds the steepest expansion curve as first-time managers proliferate.
Fund Structure:
Cost-tier differentiation separates institutional-grade vehicles with dedicated compliance infrastructure from lean structures targeting high-net-worth capital pools.
- Closed-end:Ten-to-twelve-year limited partnership agreements with defined investment and harvest periods. Locked-in timelines match illiquid underlying assets, dominating buyout and growth equity mandates where exit certainty remains uncertain.
- Open-end:Evergreen structures permitting periodic subscriptions and redemptions, more common in real estate and infrastructure where cash-flowing assets support NAV-based liquidity. SEBI's quarterly disclosure mandates increase operating overhead for domestic open-end vehicles.
- Fund of Funds:Diversified exposure across multiple underlying managers, historically prominent among pension allocations with limited India-dedicated internal resources.
- Mezzanine:Subordinated debt with equity participation rights, filling leverage gaps where domestic banking concentration limits senior debt availability for buyout transactions.
Closed-end structures command the capital commitment majority; Mezzanine is climbing the fastest as leverage constraints intensify.
Asset Class:
Application-driven segmentation separates yield-focused institutional mandates from capital appreciation strategies targeting operational value creation.
- Equity:Common and preferred share acquisitions with board representation rights, forming the core of buyout and growth equity deployment. Mumbai and Delhi house the majority of control transactions in financial services and healthcare verticals.
- Debt:Direct lending and distressed credit strategies filling gaps left by public sector bank conservatism. Concentrated demand from real estate developers and mid-market manufacturers unable to access traditional working capital facilities.
- Real Estate:Commercial, residential, and logistics asset acquisitions benefiting from SEBI's REIT liberalization enabling fractional retail participation. Bengaluru and Hyderabad technology corridor office assets absorb significant institutional allocation.
- Infrastructure:Long-duration capital for renewable energy, transportation, and digital backbone assets. Sovereign wealth funds from Abu Dhabi and Singapore anchor the largest commitments, matching liability durations with contracted revenue streams.
Equity retains deployment volume leadership; Infrastructure is gaining share fastest on sovereign capital inflows.
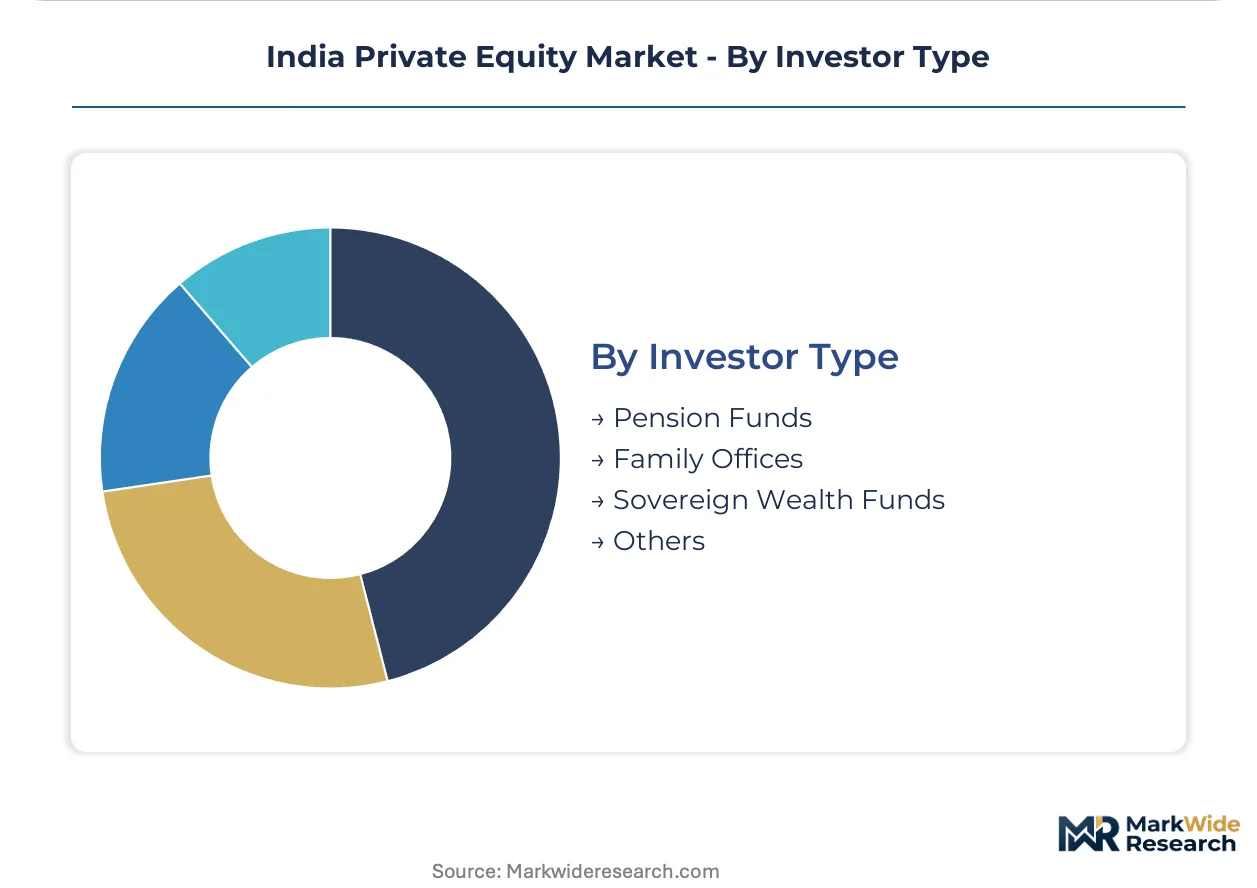
Investor Type:
Customer-type concentration is displacing traditional fund-of-funds intermediation as direct relationships substitute for layered fee structures.
- Pension Funds:Long-horizon institutional capital from domestic and offshore defined-benefit schemes. Allocation growth constrained by conservative investment committee thresholds and FEMA repatriation timeline uncertainties.
- Family Offices:Mumbai and Gujarat wealth channels increasingly preferring direct co-investment rights and separately managed accounts over standard LP commitments. Operational expertise substitutes for formal track record requirements in technology verticals.
- Sovereign Wealth Funds:Abu Dhabi and Singaporean vehicles representing the most rapidly expanding capital source, channeling concentrated commitments into infrastructure and technology platforms with national strategic alignment.
- Others:Corporate balance sheet deployment, endowment capital, and high-net-worth individual aggregators through private banking channels.
Sovereign wealth funds retain the steepest allocation growth trajectory; Family offices hold expanding share of first-time manager fundraising.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Abu Dhabi and Singaporean sovereign wealth vehicles channel concentrated capital into Indian infrastructure and technology platforms, while domestic family offices in Mumbai and Gujarat reshape fundraising channels for first-time managers.
Maharashtra
Mumbai anchors control transactions in financial services and healthcare verticals, with the Reserve Bank of India's FEMA provisions governing currency convertibility for offshore limited partners. SEBI's quarterly AIF disclosure mandates compress fundraising timelines for domestic managers operating from the city's central business district.
Karnataka
Bengaluru's SaaS corridors absorb seed and Series A commitments through DPIIT-certified vehicles unlocking tax holidays. The state's startup recognition framework accelerates early-stage formation, with Sequoia Capital India and Accel Partners maintaining concentrated early-stage dominance.
Telangana
Hyderabad's technology corridor draws expansion-stage capital for revenue-positive companies delaying IPO entry. State-level IT policy incentives complement central PLI scheme benefits, creating qualified deal pipelines for growth equity managers targeting enterprise software platforms.
Gujarat
Ahmedabad and Surat family offices displace traditional fund-of-funds through direct co-investment rights and separately managed accounts. The region's wealth channels prefer operational expertise over formal track records, particularly in healthcare and consumer technology verticals.
Delhi-NCR
Gurugram and Noida house buyout targets requiring management overlay to professionalize founder-operated governance structures. SEBI's AIF Category II regulations mandate granular portfolio disclosures on leverage, increasing compliance overhead for domestic vehicles headquartered in the National Capital Region.
India Private Equity Market Competitive Environment
Listed leaders compete with private specialists across fund structure and investor access channels. The vendor base organizes around three tiers: global buyout giants with healthcare and infrastructure specializations, domestic venture platforms with early-stage concentration, and sovereign-backed vehicles with long-duration liability matching. Strategic consolidation manifests through carve-out acquisitions of founder-operated targets and hybrid fund structures spanning climate technology convergence points.
Within the global buyout tier, Warburg Pincus and Blackstone Group exemplify scale-driven positioning through large-cap transaction anchoring and real estate portfolio concentration. Sequoia Capital India occupies the early-stage specialist position, sustaining dominance through concentrated SaaS and consumer technology bets. ICICI Venture represents the domestic hybrid archetype, bridging growth equity deployment with local regulatory navigation.
| Leading Market Players |
|---|
| Warburg Pincus |
| ICICI Venture |
| Blackstone Group |
| Accel Partners |
| Sequoia Capital India |
| KKR & Co. |
| Bain Capital |
| General Atlantic |
| Carlyle Group |
| Others |
Value Chain & Pricing Dynamics
Offshore capital substitution for domestic banking channels is simultaneously redrawing fund formation geography and compressing management fee economics across Indian private equity structures. Sovereign wealth vehicles from Abu Dhabi and Singapore now anchor the largest commitments, displacing traditional fund-of-funds intermediaries and forcing fee compression at the top of the capital stack.
Pricing Analysis
First-generation fund structures with ten-to-twelve-year locked horizons command premium carry terms against next-generation evergreen vehicles with NAV-based liquidity mechanics. Three-tier pricing structure across premium, standard, and economy levels separates institutional-grade vehicles with dedicated compliance infrastructure from lean structures targeting high-net-worth capital pools. Pricing pressure stems from family office direct co-investment rights that bypass layered fee structures entirely. Domestic pension funds exhibit highest price sensitivity due to conservative investment committee thresholds, while sovereign wealth funds prioritize strategic alignment over fee minimization.
Supply Chain Analysis
Strategic stockpiling of regulatory expertise dominates over just-in-time compliance adaptation as SEBI's quarterly disclosure mandates intensify operating overhead. Fund administration talent concentrates in Mumbai, Delhi NCR, and Bengaluru, with experienced CFOs and compliance officers commanding premium compensation that inflates operating expense ratios. Raw material dependencies include legal advisory services, audit and assurance functions, and technology infrastructure for portfolio monitoring. Single-source vulnerability sits with concentrated domestic banking channels where public sector collateral requirements limit leverage capacity. Distribution runs through limited partnership agreements with defined investor classes and separately managed accounts for direct relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indian private equity is navigating a cyclical recovery anchored to sovereign capital inflows from Abu Dhabi and Singaporean vehicles, which are reshaping LP composition and extending fund deployment timelines.
For Market Incumbents: Fortify governance infrastructure to meet SEBI's tightening AIF disclosure standards while restructuring carry terms to retain domestic LP relationships under compressed fundraising windows. Vertical integration into proprietary deal sourcing networks in Tier-II cities creates defensive moats against emerging first-time managers. Certification investment in DPIIT-compliant vehicles preserves tax-advantaged access to early-stage technology corridors.
For New Entrants and Emerging Players: Anchor in undercapitalized consumer and logistics platforms across Jaipur, Indore, and Kochi where operating metrics trail Mumbai and Delhi benchmarks by substantial margins. Climate technology convergence points between battery storage and green hydrogen production present the most penetrable white-space for hybrid fund structures. Go-to-market execution should emphasize operational expertise substitution for formal track record requirements in direct co-investment negotiations.
For Investors and Strategic Acquirers: Capital is best deployed toward founder-operated buyout targets requiring management overlay to professionalize financial reporting and board composition. Long-term viability over the next decade hinges on matching liability durations with contracted revenue streams in infrastructure and real estate assets. The signal to watch is RBI's foreign investment threshold adjustments, which would compress or extend exit horizons for offshore limited partners.
| Strategic Initiative | Industry Significance |
|---|---|
| Fund Administration Outsourcing | Reduces compliance overhead burden from SEBI's quarterly AIF disclosure mandates for domestic vehicles. |
| Hybrid Fund Structure Launch | Captures climate technology convergence between industrial buyout expertise and venture growth capital deployment. |
| Tier-II City Deal Sourcing Network | Unlocks multiple expansion potential in undercapitalized consumer platforms across Jaipur, Indore, and Kochi. |
| Direct Co-Investment Platform | Bypasses layered fee structures to access Mumbai and Gujarat family office capital channels directly. |
| SEBI Category II Certification | Preserves capital deployment efficiency under evolving AIF classification criteria and regulatory thresholds. |
Study Parameters
A standing panel of fund formation attorneys, institutional LP allocation officers, SEBI compliance consultants, and portfolio company CFOs provided ongoing calibration across primary interview rounds and secondary validation. Primary sources included general partners at India-dedicated vehicles, sovereign wealth fund investment committees, domestic family office principals, and regulatory affairs specialists. Secondary data sources encompassed SEBI AIF disclosure filings, RBI FEMA circulars, DPIIT startup recognition databases, and closed-end fund offering memoranda. Bottom-up deal flow analysis triangulated against top-down capital commitment tracking across investor categories.
Consistency checks validated volume and value outputs against external benchmarks including sovereign wealth fund allocation disclosures and regulatory filing aggregates. The analytical framework modeled deployment across investment stage, fund structure, asset class, and investor type dimensions throughout the forecast period. CAGRs were derived from historical commitment trajectories and projected capital formation velocity. Industry-specific forecast inputs incorporated PLI scheme subsidy pipelines, REIT liberalization participation rates, and FEMA repatriation timeline assumptions.
Decision-makers should treat outputs as directional under stable regulatory enforcement and sustained sovereign capital inflow assumptions; material deviation in SEBI disclosure timelines or RBI foreign investment thresholds would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Investment Analysis and Financial Strategies
North America Mobile Payments Market
Investment Analysis and Financial Strategies
Retail Banking Market
Investment Analysis and Financial Strategies
Pension Fund Management Software Market
Investment Analysis and Financial Strategies
NFT Analytics Tools Market
Investment Analysis and Financial Strategies
Southeast Asia Commercial Banking Market
Investment Analysis and Financial Strategies
Smart Finance Services Market
Investment Analysis and Financial Strategies
Certificates Market
Investment Analysis and Financial Strategies
Middle East Data Analytics in Banking Market
Investment Analysis and Financial Strategies
Blockchain Distributed Ledger Market
Investment Analysis and Financial Strategies
Slovenia Point of Sale (POS) Terminal Market
Investment Analysis and Financial Strategies
Japan Virtual Cards Market
Investment Analysis and Financial Strategies
Latin America Subscription and Billing Management Market
Investment Analysis and Financial Strategies
Retail POS Terminals Market
Investment Analysis and Financial Strategies
Global AI in Asset Management Market
Investment Analysis and Financial Strategies
Saudi Arabia Motor Insurance Market
Investment Analysis and Financial Strategies
Master Recharge API Market