
 Saudi Arabia Sealants Market | 2026-2036
Saudi Arabia Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Sealants Market Analytics
Commercial construction buyers is collapsing into a narrower set of large-scale developers and EPC contractors with giga-project pipelines, while residential and maintenance segments fragment across smaller applicators. Sika AG leverages its position in high-rise concrete protection and expansion joint systems to anchor premium specification channels. H.B. Fuller Company sustains adhesive-sealant cross-selling through direct technical service teams embedded with major contractors. Dow competes on silicone chemistry breadth, extending its architectural glazing portfolio into Saudi Arabia's specialized desert climate requirements.
Sealants are elastomeric compounds formulated from silicone, polyurethane, acrylic, or butyl polymers that cure to flexible solids with specified movement accommodation of 25% to 50% joint width, engineered to prevent air, moisture, and contaminant ingress across dynamic building or assembly interfaces. Silicone dominates architectural glazing and weathersealing applications where UV stability and temperature cycling resistance command specification priority, while polyurethane captures structural bonding and expansion joint work where modulus and adhesion to porous substrates matter. Acrylic occupies cost-sensitive interior sealing, and butyl remains entrenched in preformed tape applications for HVAC and metal building assemblies where low permeability and immediate tack are valued over movement capacity.
SFDA and SASO frameworks govern construction chemical import registration and local conformity assessment, while the Saudi Building Code mandates third-party testing for structural sealant applications in curtain wall systems. MOMRA permitting processes for commercial towers increasingly require submitted sealant compatibility data with specified framing and glazing materials. Stakeholders must monitor how giga-project master developers consolidate supplier lists around pre-approved material schedules, as this determines which formulation platforms achieve specification lock-in across the kingdom's largest construction pipelines.
Market Dynamics
Giga-project master developers are consolidating supplier lists around pre-approved material schedules, creating specification lock-in that determines which formulation platforms capture volume across Riyadh and the Red Sea coastal corridor.
Growth Catalysts
- Saudi Building Code enforcement:SASO mandates third-party testing for structural sealants in curtain wall systems, elevating certified products into specification priority for commercial tower developers.
- Megaproject construction acceleration:NEOM, Red Sea Global, and Qiddiya developments generate concentrated demand for high-performance silicone and polyurethane formulations in building envelope applications.
- Silicone chemistry advancement:UV-stable formulations engineered for desert climate extremes now command specification priority in architectural glazing across the kingdom's high-rise pipeline.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane sealant producers face margin pressure from MDI and polyol price swings tied to regional refinery output fluctuations.
- Import registration bottlenecks:SFDA and SASO conformity assessment timelines extend 4-8 months, delaying new formulation launches for international suppliers.
- Acrylic substitution in interiors:Cost-sensitive residential and maintenance segments default to lower-performance acrylics where movement accommodation requirements are minimal.
Strategic Opportunities
- Maintenance and retrofit expansion:Existing building stock across Jeddah and Dammam creates aftermarket volume for weathersealing replacement as envelope performance degrades.
- Hybrid silicone-polyurethane convergence:Formulations combining silicone weathering resistance with polyurethane structural adhesion open specification pathways in expansion joint applications.
- Direct contractor embedding:Technical service teams stationed with major EPC contractors capture specification influence before material schedules finalize.
Industry Challenges
- Applicator certification gaps:Shortage of SASO-certified installation technicians delays project timelines and triggers warranty disputes on structural glazing contracts.
- Compatibility testing complexity:MOMRA permitting requires submitted sealant-framing-glazing compatibility data that extends pre-construction phases by 6-12 weeks.
- Master developer list access:Pre-approved material schedule inclusion demands 18-24 month qualification cycles with giga-project procurement committees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Sealants Market |
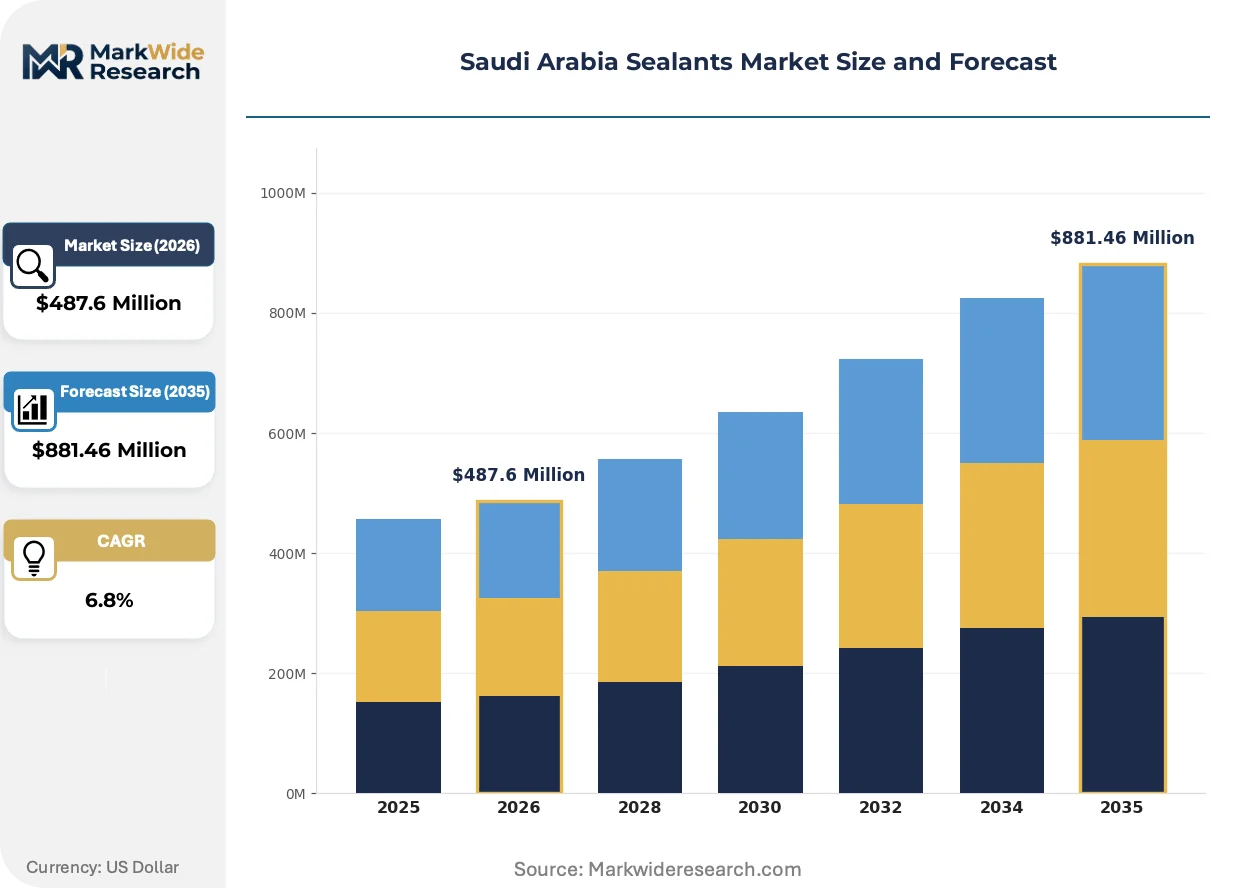
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Silicone, Butyl End User: Construction, Automotive, Electronics, Aerospace Application: Sealing, Bonding, Insulation, Soundproofing Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Soudal Holding N.V., H.B. Fuller Company, Dow, Arkema Group, 3M, Henkel AG & Co. KGaA, The Industrial Group Ltd., MAPEI S.p.A., Sika AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Sealants Market Evolving Landscape
Formulation chemistry and procurement protocols are evolving in parallel as desert climate performance requirements intersect with consolidated buyer power among megaproject developers.
Low-modulus silicone formulations with enhanced movement accommodation are supplanting conventional medium-modulus grades in structural glazing specifications. Curtain wall engineers at Riyadh commercial tower projects specify these materials for 50% joint width tolerance under thermal cycling stress. This chemistry shift compresses competitive positioning around modulus customization capabilities rather than commodity volume.
SASO's tightened enforcement of Saudi Building Code structural sealant provisions is elevating third-party test documentation into bid prerequisites. International suppliers now maintain permanent conformity assessment liaisons in Riyadh to compress registration timelines. The policy consequence concentrates specification authority among suppliers with established local testing relationships and SASO-notified body partnerships.
Buyer concentration among giga-project master developers is compressing material selection into pre-approved schedules before EPC contractors engage. Major developers at NEOM and Red Sea Global now issue locked material lists that exclude non-prequalified sealant brands. This behavioral shift fragments residual demand across smaller residential and maintenance contractors who lack schedule influence.
Saudi Arabia Sealants Market Segmentation
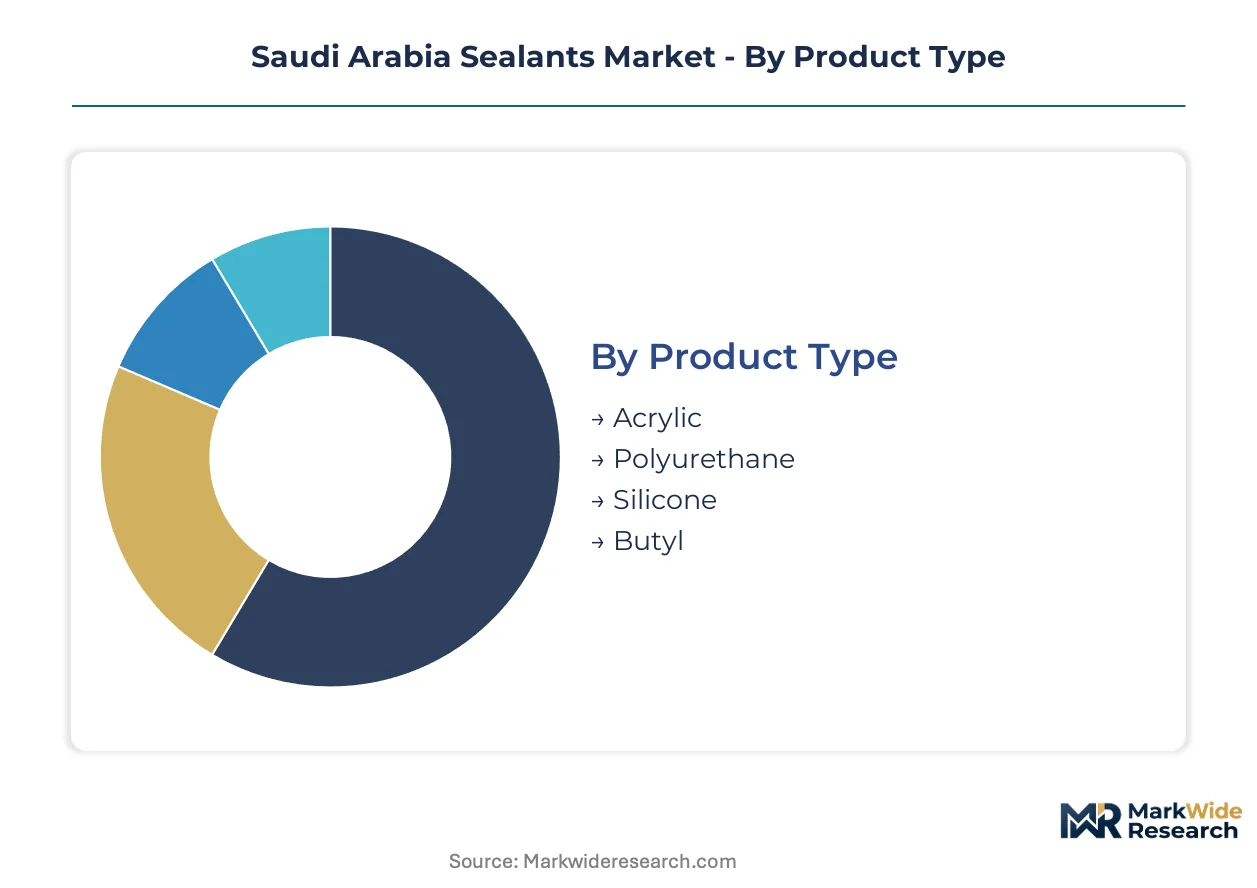
Segmentation clarity determines specification capture in Saudi Arabia's sealants market, where giga-project procurement committees filter suppliers through pre-approved material schedules. Understanding how product chemistry, end-use concentration, and channel access intersect reveals which formulation platforms achieve volume lock-in across Riyadh and Red Sea coastal developments.
Product Type:
Acrylic sealants face the most acute substitution pressure from hybrid formulations in interior applications, while silicone and polyurethane defend premium positioning through performance differentiation.
- Silicone:UV-stable formulations with 50% joint movement accommodation dominate architectural glazing and weathersealing across Riyadh's high-rise commercial pipeline. NEOM and Red Sea Global developers specify these materials for curtain wall systems exposed to desert thermal cycling.
- Polyurethane:High-modulus structural bonding compounds capture expansion joint work and concrete protection where adhesion to porous substrates matters. Megaproject concrete infrastructure generates concentrated demand for these formulations in Qiddiya and Diriyah developments.
- Acrylic:Cost-sensitive interior sealing in residential maintenance segments where minimal movement tolerance suffices.
- Butyl:Preformed tape applications for HVAC and metal building assemblies prioritizing low permeability over joint flexibility.
Silicone anchors the volume base while polyurethane gains share at the steepest rate through structural bonding specification expansion.
End User:
Cost tier stratification separates giga-project construction from fragmented maintenance demand, with automotive and electronics representing import-dependent niche volumes.
- Construction:Megaproject developers at NEOM, Red Sea Global, and Qiddiya consolidate procurement around pre-approved material schedules. SASO-certified structural sealants achieve specification priority for commercial tower curtain walls under tightened Saudi Building Code enforcement.
- Automotive:Assembly plant sealant procurement concentrates around Jeddah and Dammam manufacturing clusters with OEM-tier supplier qualification requirements.
- Electronics:Specialized conformal coating and potting compound demand from Riyadh-based assembly operations.
- Aerospace:Maintenance, repair, and overhaul applications at King Abdulaziz International Airport and smaller regional facilities.
Construction commands absolute volume dominance while automotive climbs fastest through localization incentives in vehicle assembly.
Application:
Application maturity varies sharply, with sealing and bonding representing established specification categories while insulation and soundproofing emerge from building code evolution.
- Sealing:Weathersealing and waterproofing applications across building envelopes represent the most penetrated category. Riyadh commercial towers and Red Sea coastal resorts generate recurring demand for high-performance perimeter sealing systems.
- Bonding:Structural glazing and expansion joint adhesion where load-bearing capacity intersects with movement accommodation. MOMRA permitting processes require submitted compatibility data extending pre-construction phases.
- Insulation:Thermal break and energy efficiency applications gaining traction through Saudi Green Building Forum guidance.
- Soundproofing:Acoustic sealant specification in hospitality and entertainment venues at Qiddiya and Red Sea Global developments.
Sealing retains volume leadership while bonding expands most quickly through structural glazing specification depth.
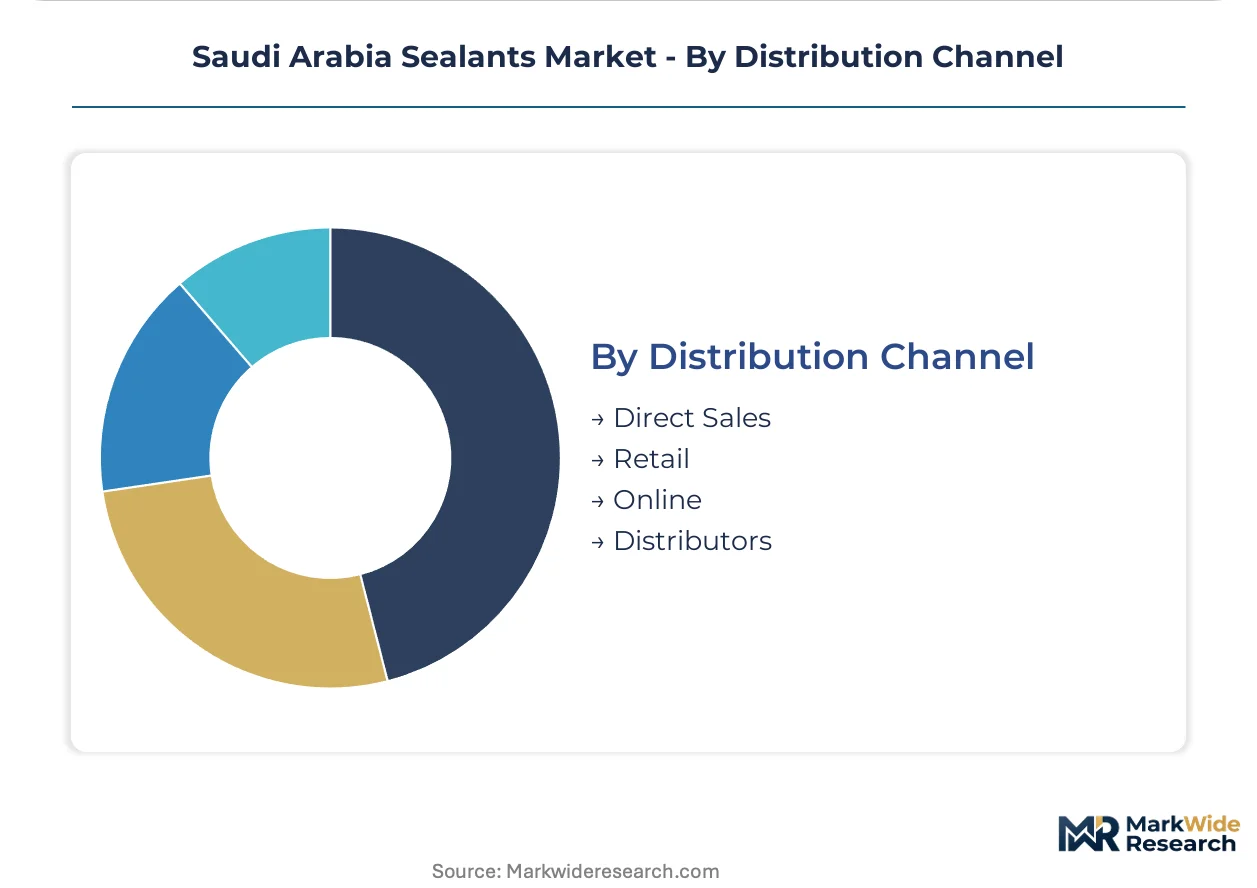
Distribution Channel:
Channel configuration reflects customer scale concentration, with direct sales capturing giga-project volume and retail fragments across residential maintenance.
- Direct Sales:Technical service teams embedded with major EPC contractors capture specification influence before material schedules finalize. Sika AG and H.B. Fuller deploy direct coverage for NEOM and Red Sea Global master developer relationships.
- Distributors:Regional stocking points in Riyadh, Jeddah, and Dammam serve mid-tier contractors outside pre-approved schedules.
- Retail:Hardware and construction supply outlets fragment across residential applicators and small maintenance contractors.
- Online:Emerging procurement pathway for standardized interior sealants with documented SASO conformity.
Direct sales anchors volume concentration while distributor relationships gain operational scale through contractor network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sealant demand concentrates in Riyadh and the Red Sea coastal corridor where giga-project construction is most active. Eastern Province industrial zones and Western Region urban centers generate secondary volume through maintenance and automotive assembly. Sub-regional differentiation reflects procurement consolidation patterns among megaproject developers.
Riyadh
Commercial tower construction and Diriyah Gate development drive specification-grade silicone demand. SASO enforces Saudi Building Code structural sealant testing for curtain wall systems. King Abdullah Financial District and Riyadh Metro extensions anchor high-performance building envelope procurement.
Eastern Province
Petrochemical facility maintenance and Dammam automotive assembly plants sustain industrial sealant consumption. SFDA import registration requirements govern construction chemical conformity assessment. Jubail Industrial City generates recurring demand for expansion joint compounds in concrete infrastructure.
Western Region
Jeddah high-rise construction and Makkah hospitality developments command weathersealing formulations. MOMRA permitting processes require submitted sealant compatibility documentation. King Abdulaziz International Airport expansion triggers specification activity for structural glazing systems.
NEOM Northwest
THE LINE and Oxagon developments consolidate procurement around pre-approved material schedules. Giga-project master developers exclude non-qualified sealant brands from EPC contractor bidding. NEOM Bay and Sindalah island resorts prioritize UV-stable silicone for coastal exposure conditions.
Saudi Arabia Sealants Market Competitive Landscape
Concentration sits with multinational chemical conglomerates and specialized construction chemical manufacturers. The vendor base splits between premium specification players with direct technical service capabilities and volume distributors serving fragmented residential maintenance. Two strategic archetypes dominate: integrated adhesive-sealant suppliers leveraging cross-selling relationships, and silicone chemistry specialists competing on formulation breadth. Competitive moves center on pre-approved material schedule inclusion with giga-project developers and SASO conformity assessment partnership establishment.
Among multinational chemical conglomerates, Dow and Arkema Group exemplify silicone chemistry specialization, while Henkel AG & Co. KGaA and H.B. Fuller Company represent integrated adhesive-sealant suppliers with embedded technical service models. Sika AG occupies a position at the intersection of concrete protection systems and expansion joint solutions. These companies anchor competitive dynamics through specification influence at NEOM, Red Sea Global, and Qiddiya master developer procurement committees.
| Leading Market Players |
|---|
| Soudal Holding N.V. |
| H.B. Fuller Company |
| Dow |
| Arkema Group |
| 3M |
| Henkel AG & Co. KGaA |
| The Industrial Group Ltd. |
| MAPEI S.p.A. |
| Sika AG |
| Others |
Value Network & Pricing Analysis
Acrylic substitution in interior sealing applications simultaneously compresses supply geography toward regional blending facilities and erodes pricing economics for commodity-grade formulations across Saudi Arabia's residential maintenance segments. This displacement dynamic concentrates premium silicone and polyurethane sourcing around certified import channels while fragmenting low-value acrylic procurement across domestic distributors.
Pricing Analysis
Volume-discount tiering structures separate giga-project master developers from fragmented residential applicators across Saudi Arabia's sealants market. Three-tier pricing stratifies across SASO-certified structural grades, commercial-standard weathersealing, and economy interior acrylics. Cost compression in the economy tier intensifies as regional blending facilities expand captive acrylic production. Giga-project procurement committees demonstrate lowest price sensitivity due to performance guarantees and warranty requirements, while small maintenance contractors exhibit acute sensitivity to per-unit differentials.
Supply Chain Analysis
Germany, Switzerland, and the United States anchor high-performance silicone and polyurethane formulation supply for Saudi Arabia's construction chemical imports. MDI and polyol feedstocks draw from European and Asian petrochemical complexes, while fumed silica and specialty catalysts rest on German and Japanese specialty chemical production. Single-source vulnerability concentrates around MDI supply disruptions from regional refinery output fluctuations. Distribution runs through Jeddah and Dammam port complexes into Riyadh-stocked distributor networks and direct technical service channels embedded with major EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Giga-project master developer consolidation has shifted buyer power toward pre-approved material schedule gatekeepers, compressing supplier access and elevating certification barriers for non-qualified brands across Saudi Arabia's sealants procurement landscape.
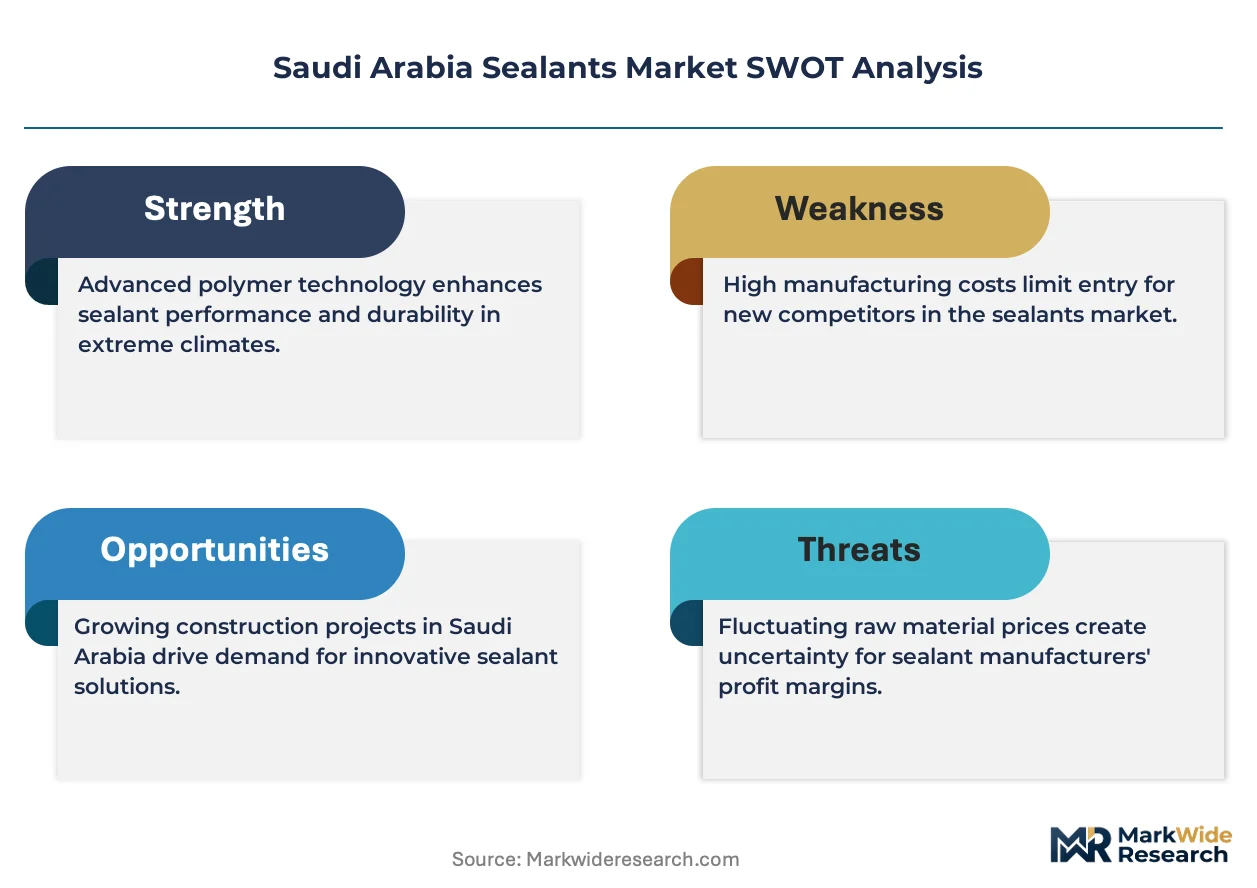
For Market Incumbents: Secure pre-approved material schedule lock-in with NEOM and Red Sea Global procurement committees before EPC contractor engagement phases. Deepen backward integration into silicone polymer production to defend margin position against MDI feedstock volatility. Channel control through embedded technical service teams represents the critical lever for specification influence. For New Entrants and Emerging Players: SASO conformity assessment fast-tracks offer the most penetrable pathway for international suppliers lacking giga-project relationships. Target the maintenance and retrofit segment across Jeddah and Dammam where applicator certification gaps delay incumbent response times. Direct contractor embedding with mid-tier EPC firms outside pre-approved schedules provides viable go-to-market traction. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized construction chemical manufacturers with established SASO testing relationships and giga-project procurement access. Long-term viability hinges on specification platform breadth across silicone chemistry and hybrid formulation development. The signal to watch is master developer schedule expansion or contraction announcements at NEOM and Qiddiya.| Strategic Initiative | Industry Significance |
|---|---|
| SASO Certification Investment | Permanent conformity assessment liaisons in Riyadh compress registration timelines for structural sealant launches. |
| Technical Service Team Expansion | Direct embedding with EPC contractors captures specification influence before material schedules finalize at giga-projects. |
| Hybrid Formulation Development | Silicone-polyurethane convergence opens specification pathways in expansion joint applications with desert climate performance. |
| Maintenance Channel Partnership | Regional distributor relationships in Jeddah and Dammam build aftermarket volume for weathersealing replacement demand. |
| Backward Integration into Feedstocks | In-house MDI and polyol sourcing buffers margin pressure from regional petrochemical output volatility. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with EPC contractor procurement managers, giga-project technical specification leads, SASO conformity assessment officers, distributor inventory planners, and sealant applicator certification trainers. Secondary validation drew from Saudi Building Code enforcement bulletins, SASO technical regulation updates, MOMRA permitting documentation, customs import registration databases, and construction chemical trade flow records. Bottom-up volume estimates from project-level material takeoffs triangulated against top-down market sizing from regional production and import data.
Across the analysis window, forecasts reflect segmented modeling across product chemistry tiers, end-use construction categories, application types, and distribution channel configurations. Growth trajectory derivation incorporated Saudi Building Code enforcement intensity, giga-project construction phase sequencing, and silicone chemistry advancement cycles. Forecast inputs included master developer pre-approval schedule expansion rates and SASO certification timeline compression initiatives.
Underlying assumptions cover sustained giga-project construction commitment, stable petrochemical feedstock availability, and consistent regulatory enforcement intensity, with deviation risk concentrated in applicator certification capacity constraints and master developer procurement committee composition shifts. Recalibration cycles align with material shifts in Saudi Building Code amendment schedules and giga-project phase transition announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Italy Adhesives Market
Adhesives & Sealants
Electric Vehicle Adhesives and Sealants Market
Adhesives & Sealants
Global Engineering Adhesives Market
Adhesives & Sealants
US Adhesives and Sealants Market
Adhesives & Sealants
Thailand Adhesives Market
Adhesives & Sealants
Asia-Pacific Bone Glue Market
Adhesives & Sealants
Mirror Adhesive Market
Adhesives & Sealants
Moisture Curing Adhesives Market
Adhesives & Sealants
Dibutyl Maleate (DBM) Market
Adhesives & Sealants
South America Construction Adhesives Market
Adhesives & Sealants
Elastomeric Adhesive Market
Adhesives & Sealants
Global Hygiene Adhesives Market
Adhesives & Sealants
South America Adhesives and Sealants Market
Adhesives & Sealants
Spray Glue Market
Adhesives & Sealants
Europe Hot-Melt Adhesives Market
Adhesives & Sealants
Global Bonding Varnish Market