
 Adhesives and Sealants for Handheld Devices Market | 2026-2036
Adhesives and Sealants for Handheld Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Adhesives and Sealants for Handheld Devices Market Analysis
Smartphone assembly is expanding its share of adhesive consumption as foldable and waterproof designs multiply bonding points per unit. Henkel leverages its electronics materials portfolio to dominate European supply channels for high-reliability formulations. Dow anchors North American demand through silicone sealant expertise in moisture protection. Bostik competes on acrylic hot-melt systems tailored to fast-cycling Asian OEM lines.
Adhesives and sealants for handheld devices are specialty bonding materials formulated from acrylic, epoxy, silicone, or UV-reactive chemistries, applied in micrometer-scale layers to secure displays, batteries, and environmental seals without adding structural weight. Their primary purpose is to maintain device integrity through thermal cycling, drop stress, and liquid ingress while enabling disassembly for repair. UV-curable adhesives lead the product type segment due to instant cure speeds that match takt-time requirements in automated assembly. Epoxy adhesives occupy the highest-margin tier where structural bonding of glass-to-metal frames demands shear strength above 15 MPa. Pressure-sensitive adhesives sustain volume growth in tablet and wearable applications where re-workability protects delicate flex circuits.
REACH in Europe restricts volatile organic compound content in consumer electronics adhesives, pushing reformulation toward solvent-free UV and hot-melt platforms. EPA chemical safety reviews under the Toxic Substances Control Act shape US market access for new adhesive chemistries, particularly fluorinated sealants. China's GB standards for electronic product environmental protection add testing layers for imported formulations. Stakeholders must monitor regulatory divergence between these jurisdictions to avoid stranded inventory and redundant certification costs.
Market Dynamics
UV-curable adhesive platforms are compressing cure cycles from minutes to seconds, forcing reformulation investments across supplier networks while Shenzhen's manufacturing cluster concentrates procurement leverage.
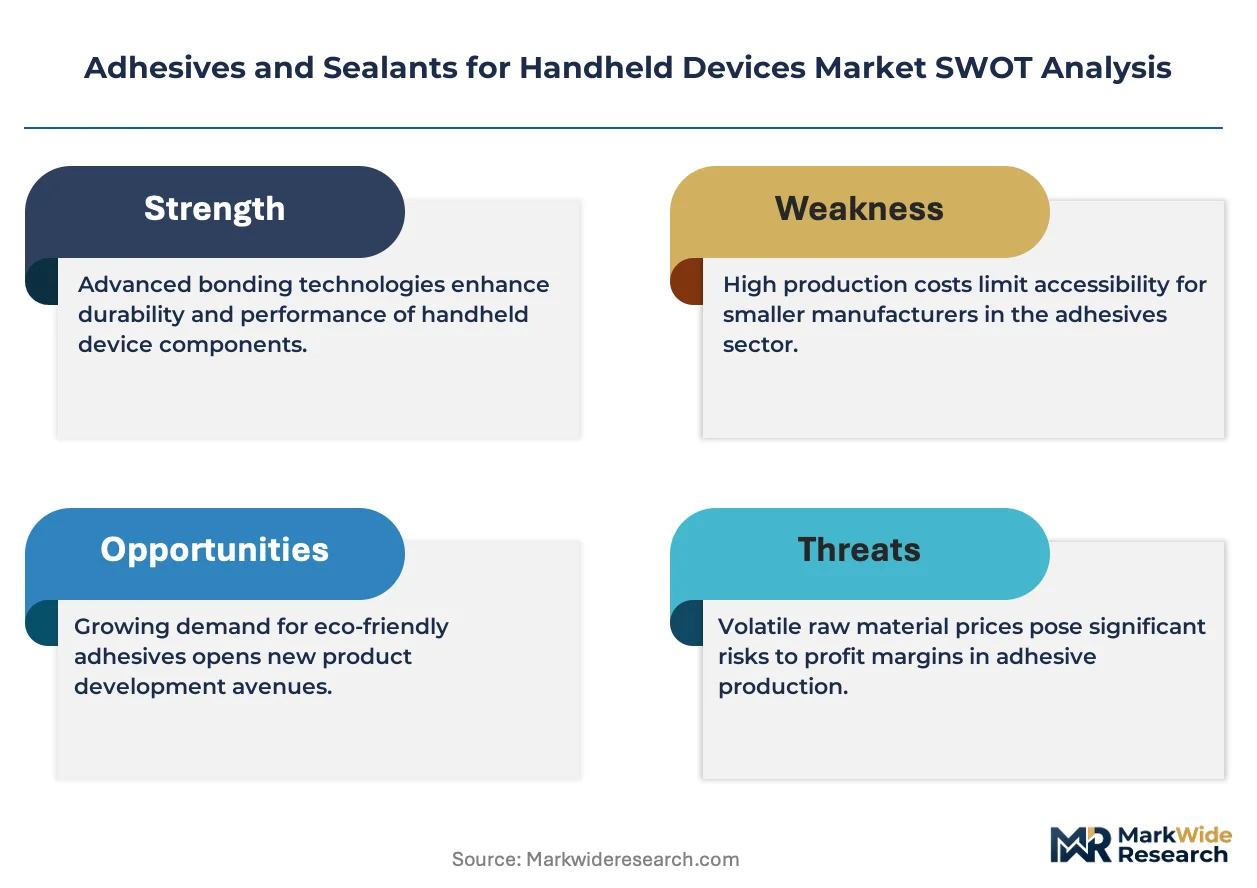
Growth Catalysts
- REACH solvent restrictions:European VOC limits are accelerating solvent-free UV and hot-melt platform adoption, redirecting R&D budgets toward instant-cure chemistries.
- Foldable display architectures:Multi-layer bonding requirements in bendable smartphones are expanding adhesive surface area per unit by three to five times.
- Shenzhen cluster procurement:Concentrated electronics manufacturing in China's Pearl River Delta is consolidating specification-setting power among three dominant OEMs.
Market Restraints
- Photoinitiator cost volatility:UV-curable systems depend on benzoin ether derivatives subject to petrochemical feedstock swings.
- Japanese silicone supply concentration:Shin-Etsu and Dow Toray control over seventy percent of high-purity electronics-grade silicone precursors.
- Epoxy brittleness ceiling:Glass-to-metal frame bonding demands shear strength above fifteen megapascals, but conventional epoxies crack under drop stress below minus forty degrees Celsius.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for mobile phone assembly are attracting Foxconn and Dixon Technologies to establish captive adhesive qualification programs.
- Thermally conductive interfaces:5G chipset thermal management is creating demand for adhesives with thermal conductivity above two watts per meter-kelvin.
- EU Green Deal circularity mandates:Right-to-repair regulations are favoring pressure-sensitive and debondable formulations over permanent structural bonds.
Industry Challenges
- Cleanroom-grade formulation expertise:Particulate contamination control in sub-ten-micrometer adhesive layers requires chemists with semiconductor process backgrounds.
- Dual-cure certification timelines:UV-thermal hybrid systems must pass separate IEC and UL testing tracks, extending qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adhesives and Sealants for Handheld Devices Market |
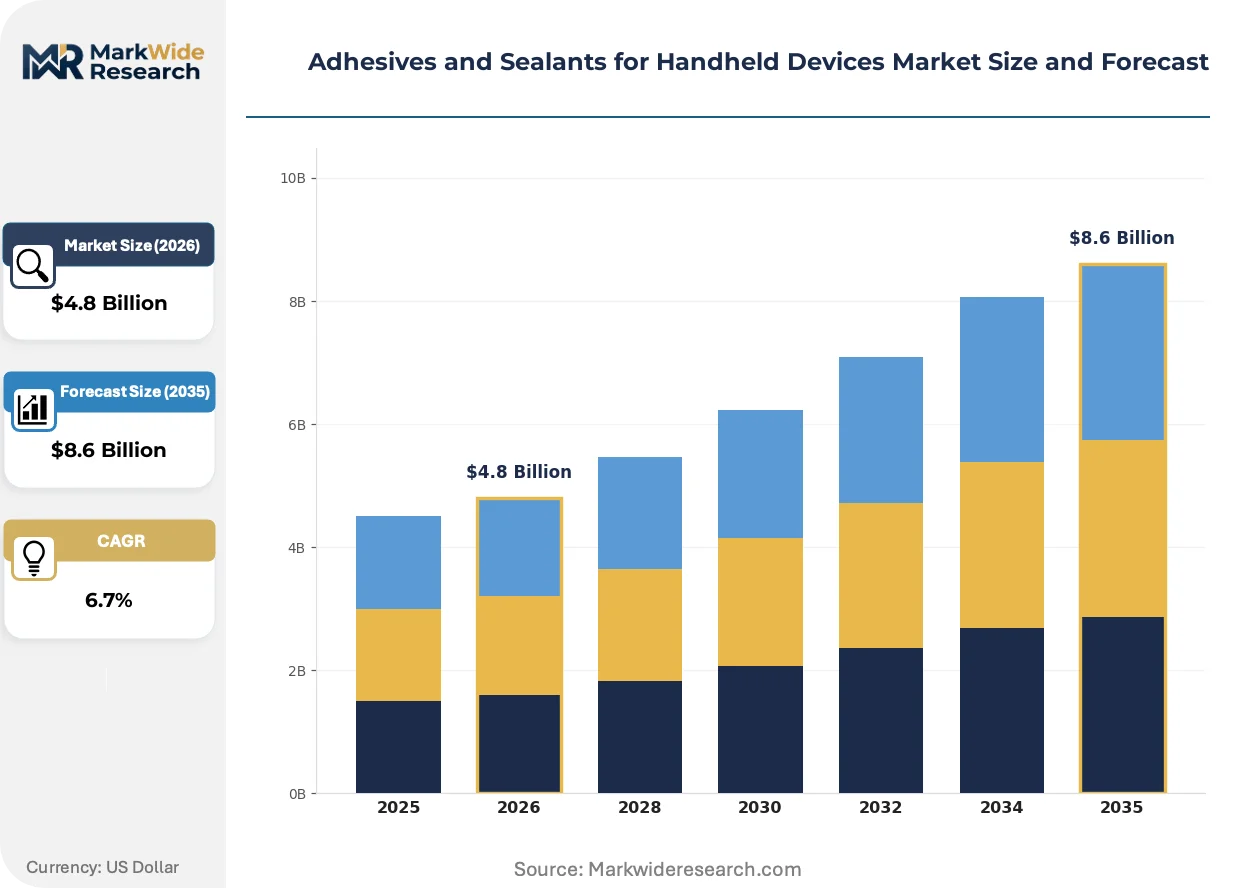
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Sensitive Adhesives, Epoxy Adhesives, Silicone Sealants, UV-Curable Adhesives End User: Manufacturers, Repair Shops, Retailers, Distributors Application: Smartphones, Tablets, Wearable Devices, Audio Devices Technology: Hot Melt Adhesive, Liquid Adhesive, Acrylic Adhesive, Biocompatible Adhesive |
| Companies Covered | H.B. Fuller, Bostik, Henkel, ITW, Arkema, 3M, Dow, RPM International, Sika, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adhesives and Sealants for Handheld Devices Market Emerging Trajectories
Adhesive functionality is migrating from passive mechanical fixation to active thermal and electromagnetic management, rewiring supplier value propositions toward materials science partnerships.
Dual-cure adhesive systems combining UV snap-cure with thermal post-cure are rewriting assembly line economics for waterproof smartphone sealing. Foxconn and Luxshare are deploying these platforms across Shenzhen and Kunshan facilities to eliminate clamping stations. The technology is compressing work-in-process inventory cycles from hours to minutes while maintaining IP68 ingress protection ratings.
REACH Annex XVII restrictions on organotin catalysts in polyurethane sealants are forcing reformulation toward bismuth and zinc alternatives. German and French adhesive formulators are absorbing six to nine month requalification costs ahead of 2025 enforcement deadlines. Medical-grade wearable devices face the steepest compliance burden, as skin-contact biocompatibility testing must repeat for every catalyst substitution.
Direct OEM qualification of adhesive suppliers is displacing tier-two distributor relationships in high-volume smartphone programs. Samsung and Xiaomi procurement teams in Seoul and Beijing are establishing approved vendor lists with single-source accountability for lot traceability. This pattern is most pronounced in battery bonding applications where thermal runaway liability demands material certificates of analysis for every production batch.
Adhesives and Sealants for Handheld Devices Market Segmentation
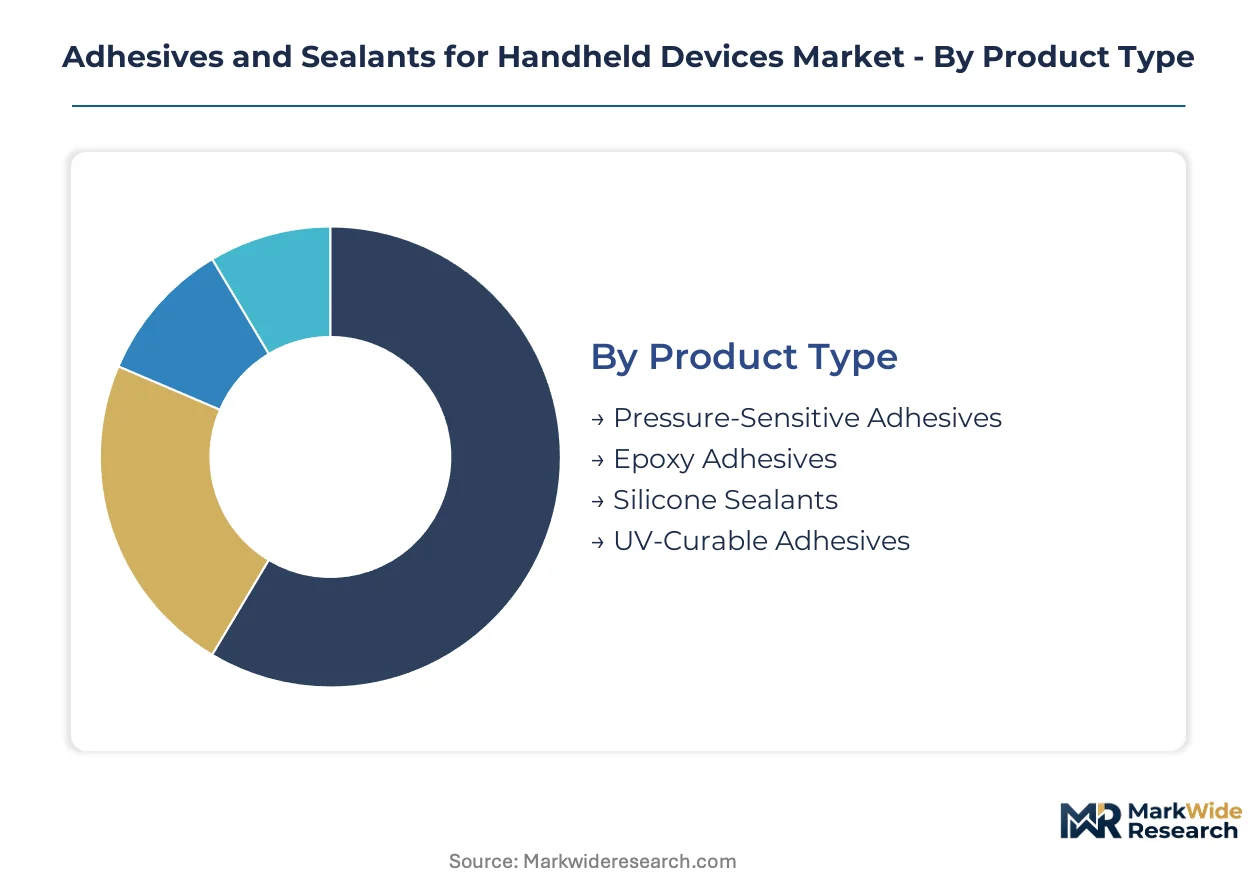
Adhesive selection in handheld devices hinges on cure speed, environmental resistance, and assembly automation compatibility. Each segment category reflects distinct procurement logics across OEM assembly lines, aftermarket channels, and specialized device architectures.
Product Type:
Volume production favors instant-cure platforms, while premium margins concentrate in structural formulations.
- UV-Curable Adhesives:Photoinitiator-activated systems cure in seconds under 365-405 nm LED arrays. Shenzhen assembly lines specify these for display bonding to match 15-second takt times.
- Epoxy Adhesives:Two-part thermoset formulations deliver shear strength exceeding 15 MPa for glass-to-metal frame bonding. Demand concentrates in flagship smartphone programs where drop-test certification requirements are most stringent.
- Pressure-Sensitive Adhesives:Tackified acrylic or rubber-based films enable repositioning during flex circuit assembly in tablets and wearables.
- Silicone Sealants:Platinum-catalyzed systems provide IP68 moisture protection with thermal stability from -40°C to 150°C.
Today's leader: UV-Curable Adhesives. Tomorrow's challenger: Epoxy Adhesives.
End User:
Specification authority shifts upstream as OEMs tighten material traceability requirements.
- Manufacturers:Foxconn, Luxshare, and Dixon Technologies operate captive adhesive qualification labs with batch-level certificates of analysis. Their procurement teams enforce single-source accountability for thermal runaway liability coverage.
- Distributors:Avnet and Arrow Electronics aggregate fragmented demand from mid-tier EMS providers across India's PLI-subsidized assembly corridors.
- Repair Shops:Independent service providers source debondable pressure-sensitive films to comply with EU right-to-repair mandates.
- Retailers:Consumer-facing channels move small-volume DIY repair kits with pre-cut adhesive templates.
Procurement gravity centers on Manufacturers. Channel expansion opportunity: Repair Shops.
Application:
Device architecture complexity determines adhesive layer count and precision requirements.
- Smartphones:Foldable designs multiply bonding points three to five times per unit versus rigid counterparts. Multi-layer display stacks demand UV-curable optical clear adhesives with sub-10-micrometer thickness control.
- Tablets:Larger display areas increase thermal cycling stress on adhesive joints, favoring silicone sealants with elongation above 300%.
- Wearable Devices:Skin-contact biocompatibility testing per ISO 10993 restricts catalyst selection in polyurethane and silicone platforms.
- Audio Devices:Miniaturized true wireless earbuds require micro-dispensed epoxy for driver-to-housing fixation.
Smartphones generate current volume dominance. Wearable Devices offer the steepest expansion trajectory.
Technology:
Formulation chemistry determines compatibility with cleanroom environments and automated dispensing.
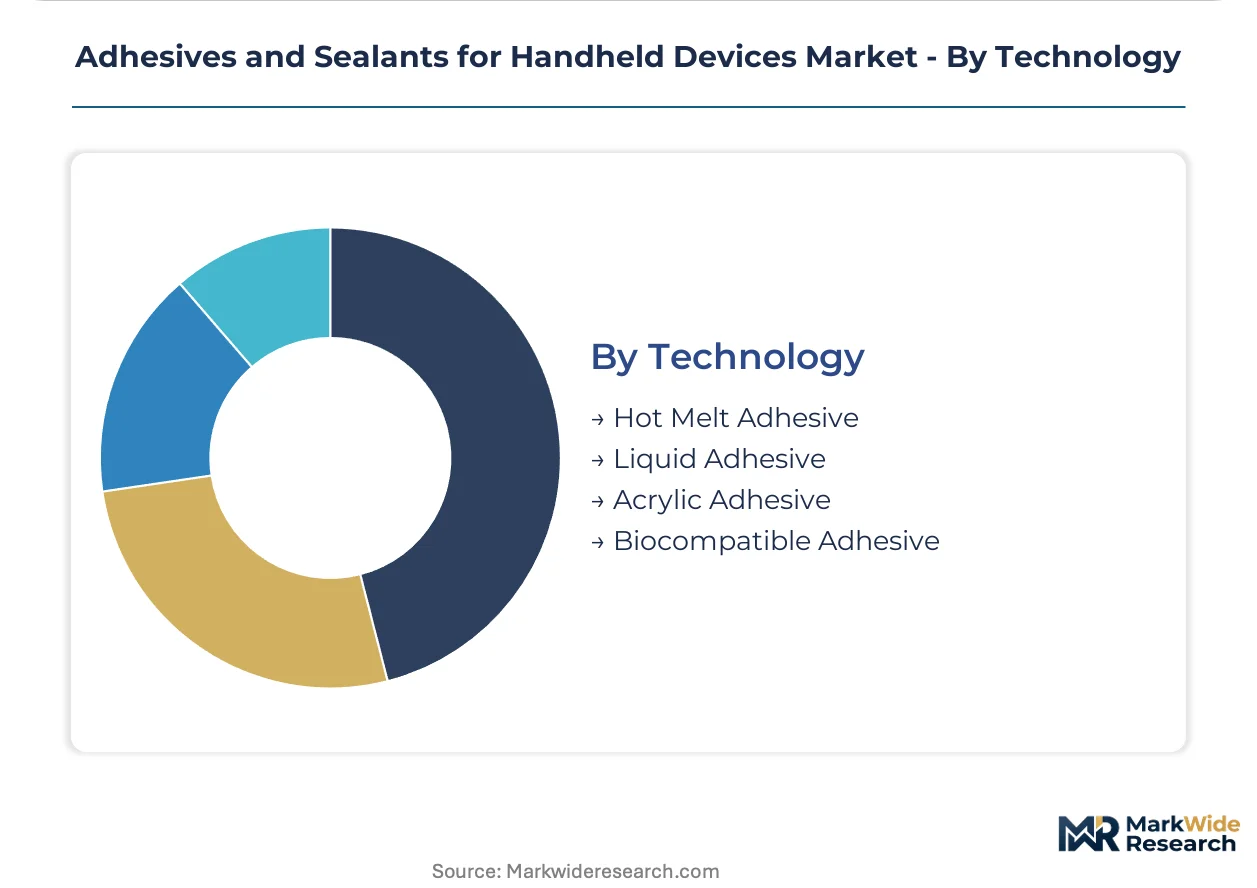
- Hot Melt Adhesive:Reactive polyurethane systems activate at 120-150°C for immediate handling strength. Asian OEM lines favor these for battery bonding where UV shadow areas prevent light-cure.
- Liquid Adhesive:Low-viscosity epoxies and acrylates suit capillary-flow applications in waterproof sealing gaskets.
- Acrylic Adhesive:Solvent-free UV platforms dominate European supply channels under REACH VOC restrictions.
- Biocompatible Adhesive:Cyanoacrylate and light-cure silicone variants pass ISO 10993-5 cytotoxicity testing for wearable skin contact.
Hot Melt Adhesive anchors high-volume throughput. Biocompatible Adhesive represents the emerging specification frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing migration patterns follow divergent regulatory compliance costs, with assembly lines relocating to jurisdictions offering streamlined chemical safety approvals while formulation R&D clusters in regions with stringent environmental standards.
United States
Domestic smartphone assembly expansion in Texas and Arizona drives precision adhesive demand from EMS providers. EPA chemical safety reviews under the Toxic Substances Control Act create qualification bottlenecks for new fluorinated sealant chemistries. Austin's emerging semiconductor-adjacent manufacturing corridor attracts adhesive distributors establishing technical service centers for Southwestern OEM lines.
Germany
Automotive electronics crossover applications sustain high-margin epoxy demand for industrial-grade handheld devices. REACH Annex XVII solvent restrictions force reformulation toward UV-curable platforms with six-to-nine month requalification cycles. Baden-Württemberg's precision engineering cluster hosts adhesive formulators developing semiconductor-process-compatible cleanroom grades.
China
Shenzhen's Pearl River Delta electronics manufacturing cluster concentrates global volume procurement of micrometer-scale bonding materials. GB standards for electronic product environmental protection add testing layers for imported formulations, favoring domestic suppliers. Foxconn and Luxshare qualification labs in Kunshan enforce batch-level certificates of analysis for battery bonding applications.
India
Production-linked incentive schemes for mobile phone assembly attract Foxconn and Dixon Technologies to establish captive adhesive qualification programs. BIS certification requirements for imported chemicals create domestic formulation partnerships. Tamil Nadu and Karnataka assembly corridors drive distributor consolidation as Avnet and Arrow Electronics aggregate fragmented EMS demand.
South Korea
Seoul-based OEM procurement teams establish approved vendor lists with single-source accountability for thermal runaway liability coverage. MFDS biocompatibility testing requirements restrict catalyst selection in wearable device applications. Suwon and Gumi manufacturing hubs specify dual-cure adhesive systems for waterproof flagship smartphone sealing.
Adhesives and Sealants for Handheld Devices Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation expertise consolidating among European and North American chemical conglomerates while Asian distributors capture volume procurement leverage. The vendor base organizes around three archetypes: integrated materials science conglomerates with electronics portfolios, regional adhesive specialists serving single geography OEM clusters, and captive formulation operations within tier-one EMS providers. Competitive moves center on dual-cure technology licensing partnerships and backward integration into photoinitiator supply chains to offset petrochemical feedstock volatility.
Among diversified materials conglomerates, Henkel AG represents the integrated portfolio archetype spanning European high-reliability supply channels. Dow anchors North American positioning through silicone sealant expertise. Bostik occupies a distinct tier serving fast-cycling Asian OEM lines with acrylic hot-melt systems. These three entities exemplify how geographic R&D clustering aligns with regional regulatory specialization.
| Leading Market Players |
|---|
| H.B. Fuller |
| Bostik |
| Henkel |
| ITW |
| Arkema |
| 3M |
| Dow |
| RPM International |
| Sika |
| Others |
Supply Flow & Price Mechanics
Captive integration into photoinitiator supply chains anchors both cost predictability and pricing power for UV-curable adhesive formulators facing benzoin ether derivative volatility. This backward control separates Henkel and Dow from distributors exposed to spot-market petrochemical swings.
Pricing Analysis
Distributor margin compression runs through Asian OEM channels as Foxconn and Luxshare consolidate procurement leverage across Shenzhen assembly lines. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade biocompatible formulations from commodity display bonding grades. Price differentiation centers on REACH certification tier and thermal conductivity specification. Pricing pressure stems from Indian PLI scheme subsidies attracting volume production away from Chinese cost bases. Mid-tier EMS providers exhibit highest price sensitivity; flagship smartphone OEMs prioritize lot traceability over unit cost.
Supply Chain Analysis
Freight cost escalation from Japanese silicone precursor shipments feeds into sealant pricing for moisture-protection applications. Supply concentration rests on China for photoinitiator synthesis, Japan for high-purity electronics-grade silicone, and Germany for epoxy resin specialty grades. Raw material dependencies include benzoin ether derivatives, platinum catalysts, and acrylic monomers. Single-source vulnerability concentrates in Shin-Etsu and Dow Toray silicone precursor control. Distribution runs through direct OEM qualification programs displacing tier-two distributor relationships in battery bonding applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-compliant European formulation premiums and Indian PLI-subsidized assembly cost advantages.
For Market Incumbents: Deepen captive qualification lab partnerships with Foxconn and Dixon Technologies to lock in batch-level certificate-of-analysis requirements. Invest in bismuth catalyst R&D ahead of REACH Annex XVII organotin enforcement. Vertical integration into photoinitiator synthesis hedges benzoin ether feedstock volatility threatening margin stability.
For New Entrants and Emerging Players: E-commerce platform routes into independent repair shop channels bypass established OEM vendor list barriers. Target EU right-to-repair compliance segments with debondable pressure-sensitive film formulations where incumbents lack repositionable adhesive portfolios. White-space concentration sits in wearable biocompatibility testing services adjacent to adhesive supply.
For Investors and Strategic Acquirers: Roll-up economics work for regional adhesive specialists with cleanroom-grade formulation expertise because semiconductor-process backgrounds remain scarce outside Baden-Württemberg and Austin corridors. Five-to-ten year viability favors targets with dual-cure technology licensing partnerships. Monitor Indian BIS certification timeline acceleration as inflection signal for domestic formulation partnership valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Supply | Captive benzoin ether production insulates Henkel from petrochemical feedstock swings. |
| Dual-Cure Technology Licensing Partnership | Foxconn deployment across Kunshan facilities validates UV-thermal hybrid platform economics. |
| Biocompatibility Testing Service Expansion | ISO 10993-5 cytotoxicity certification opens wearable skin-contact adhesive specifications. |
| Indian PLI Scheme Qualification Program | Dixon Technologies captive labs secure BIS certification for imported chemical alternatives. |
| REACH Annex XVII Reformulation Investment | Bismuth catalyst substitution ahead of 2025 enforcement preserves European market access. |
Methodological Framework
Bottom-up smartphone and wearable modeling reconciled against top-down adhesive supplier production tracking forms the analytical core. Primary interviews with adhesive formulators, EMS procurement leads, cleanroom process engineers, and regulatory compliance officers combined with secondary validation from ECHA REACH filings, EPA TSCA chemical safety reviews, and SEC 10-K disclosures from listed materials conglomerates. Triangulation across these sources anchored volume estimates against Foxconn and Luxshare qualification lab throughput indicators.
Historical trendline analysis of UV-curable adoption rates across Shenzhen assembly lines established baseline growth patterns. Segmentation dimensions modeled include cure mechanism, device architecture complexity, thermal conductivity tier, and regional regulatory cluster. CAGRs derived from supply-side capacity announcements and demand-side OEM content-per-unit trajectories. Forecast inputs incorporated foldable display bonding surface area multipliers and 5G chipset thermal management specification shifts.
The model assumes a particular technology adoption path; alternative pathways for solvent-free hot-melt platforms would alter the outlook if REACH enforcement accelerates beyond current timelines. Forecasts reflect documented assumptions about photoinitiator cost stability and Japanese silicone supply continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Contact Adhesives Market
Adhesives & Sealants
Tile and Stone Adhesive Market
Adhesives & Sealants
Asia-Pacific Acrylic Adhesives Market
Adhesives & Sealants
Europe Construction Adhesives and Sealants Market
Adhesives & Sealants
Adhesives and Sealants Distribution Market
Adhesives & Sealants
Mexico Sealants Market
Adhesives & Sealants
Global Adhesion Barrier Market
Adhesives & Sealants
Thailand Adhesives Market
Adhesives & Sealants
APAC Polyurethane Hot-Melt Adhesives Market
Adhesives & Sealants
Global Emulsion Adhesives Market
Adhesives & Sealants
Global Electrically Conductive Adhesives Market
Adhesives & Sealants
Middle East and Africa Human Fibrin Glue Market
Adhesives & Sealants
South America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Fabric Adhesive Market
Adhesives & Sealants
Acetate Silicone Sealant Market
Adhesives & Sealants
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market