
 Butyl Adhesive Market | 2026-2036
Butyl Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Butyl Adhesive Market Analysis
Formulation chemistry is tilting toward low-VOC and hot-melt systems as OEMs redesign assembly lines for cleaner bonding operations. Henkel Corporation leverages its European R&D footprint to specialize in automotive-grade butyl tapes with enhanced temperature stability. H.B. Fuller Company anchors its position through backward integration into polymer modification, controlling raw material consistency across regional plants. Sika competes by extending its construction adhesive portfolio into waterproofing membranes where butyl's impermeability dominates specification sheets.
Butyl adhesive comprises synthetic elastomer formulations derived from isobutylene-isoprene copolymerization, typically exhibiting gas impermeability, UV resistance, and service temperatures from minus forty to plus one hundred twenty degrees Celsius; manufacturers extrude or calender these compositions into tapes, sealants, and liquid coatings for bonding, sealing, and damping applications across industrial and consumer end-uses. Hot melt butyl adhesives command the largest production volume due to their elimination of solvent recovery systems and compatibility with automated dispensing equipment in automotive final assembly. Water-based formulations are gaining specification share in construction applications where contractors face jobsite VOC exposure limits, though cure speed constraints restrict their use in high-throughput manufacturing. Pressure-sensitive butyl tapes occupy premium positioning in electronics and medical packaging where clean-room application and repositionability justify higher material costs.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based butyl adhesive production in US manufacturing facilities, while REACH registration requirements in Europe force reformulation of legacy products containing restricted phthalate plasticizers. China's MEE enforces progressively stricter VOC content limits on adhesive products sold into construction and automotive sectors, compelling domestic and multinational producers to relocate formulation capacity toward compliant polymer systems. Stakeholders must monitor divergence between regional chemical control frameworks and assess whether centralized production can satisfy incompatible compliance regimes without redundant plant investment.
Market Dynamics
Automotive electrification is compressing specification cycles for butyl adhesive formulations as OEMs redesign battery enclosures to manage thermal runaway risks, forcing suppliers to validate new chemistries against stricter flammability standards within truncated development windows.
Growth Catalysts
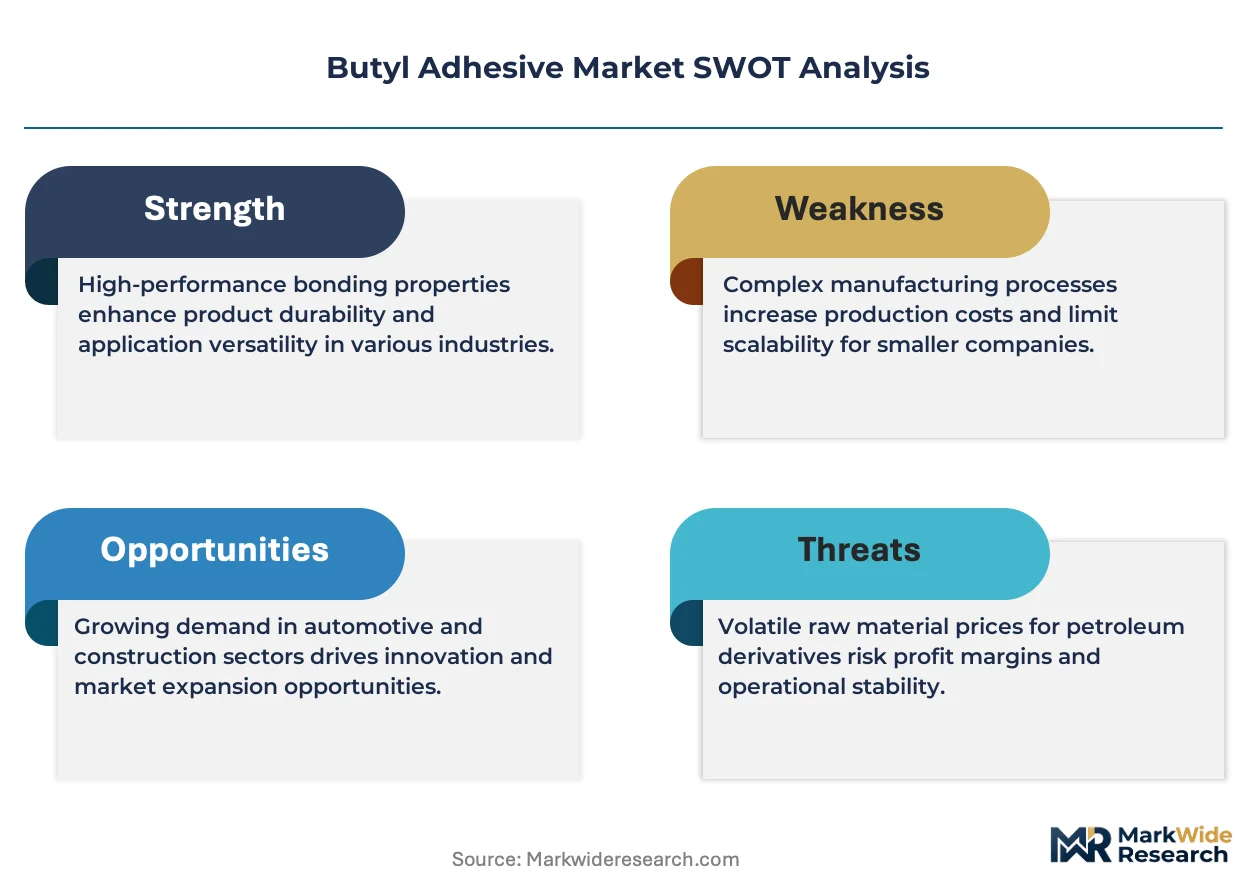
- EV Battery Sealing Mandates:Automotive OEMs in Germany and South Korea now specify butyl-based barrier tapes for lithium-ion cell isolation, creating pull-through demand for high-temperature grades.
- REACH SVHC Restrictions:ECHA's expanded candidate list is phasing out legacy phthalate plasticizers, advantaging reformulated butyl systems with compliant polymer architecture.
- China's Infrastructure Pipeline:MEE enforcement of GB standards for building envelope waterproofing is specifying butyl membrane adhesives in state-funded transit and data center projects.
Market Restraints
- Isobutylene Feedstock Concentration:Four petrochemical complexes in the US Gulf Coast and Singapore control over sixty percent of polymer-grade feedstock, exposing formulators to coordinated supply disruptions.
- Cure Speed Limitations:Water-based butyl systems require eight to twelve hour ambient cure cycles, disqualifying them from automotive final assembly lines running ninety-second takt times.
- Silicone Substitution in Medical:Platinum-cured silicone adhesives are capturing share in implantable device sealing where US FDA biocompatibility requirements exceed butyl certification boundaries.
Strategic Opportunities
- India Construction Formalization:BIS certification requirements for commercial building membranes are creating first-mover advantage for butyl tape suppliers establishing local compounding partnerships.
- Agrivoltaic Waterproofing:Dual-use solar installations over irrigation reservoirs in Spain and Italy are specifying butyl-backed EPDM membranes for twenty-five year service life guarantees.
- Hot-Melt Automation Convergence:Integration of robotic dispensing systems with infrared cure monitoring is opening precision electronics assembly to butyl formulations previously excluded by viscosity constraints.
Industry Challenges
- Polymer Rheology Expertise Gap:Formulation chemists capable of tuning butyl molecular weight distributions for automated extrusion are concentrated at three European technical centers, constraining regional plant expansion.
- Multi-Jurisdiction Registration Burden:Separate dossier requirements for EPA PMN notification, REACH registration, and China MEE new chemical notification are extending product launch timelines by fourteen to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butyl Adhesive Market |
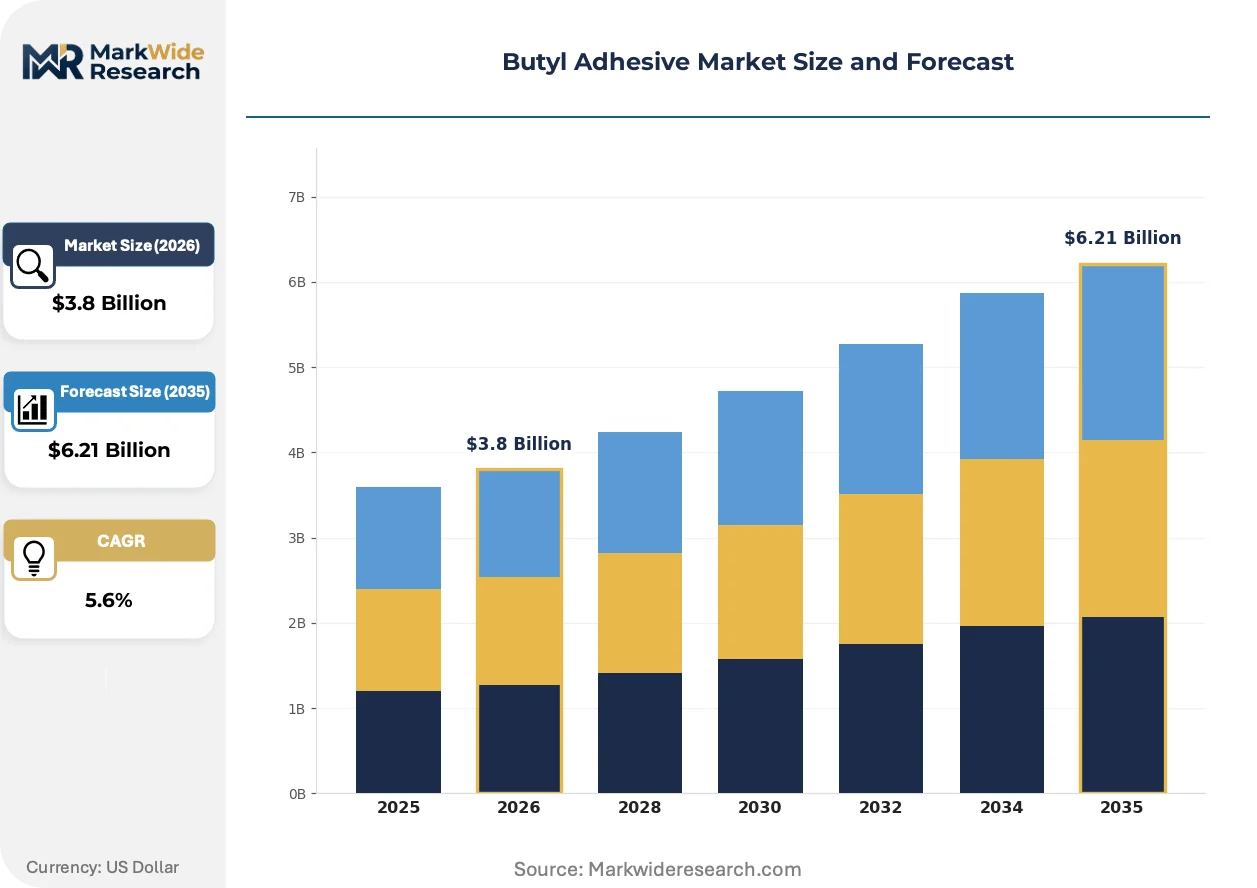
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Melt, Water-Based, Solvent-Based, Pressure-Sensitive Application: Automotive, Construction, Electronics, Packaging End User: Manufacturers, DIY Consumers, Contractors, Distributors Form: Liquid, Film, Tape, Granules |
| Companies Covered | Henkel Corporation, H.B. Fuller Company, Bostik, 3M, Sika, Nitto Denko Corporation, General Sealants, RENOLIT SE, L'ISOLANTE K-FLEX S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butyl Adhesive Market Emerging Trajectories
Formulation science is pivoting toward reactive hot-melt architectures that combine application speed with structural performance, while regulatory divergence between major economies is fragmenting product portfolios into geography-specific SKUs.
Reactive polyurethane-butyl hybrid adhesives are rendering obsolete conventional solvent-based seam sealers in automotive body-in-white construction. Tier-1 suppliers in Stuttgart and Detroit are validating these systems for crash-durable bonding. The technology is compressing the supplier base by disqualifying formulators lacking reactive chemistry expertise.
EPA's National Emission Standards for Hazardous Air Pollutants are constraining solvent recovery capacity expansions at US manufacturing facilities. Formulators are redirecting capital toward hot-melt compounding lines with nitrogen-blanketed reactors. Construction-grade butyl sealants face the steepest reformulation costs as architectural specifications lag automotive in accepting non-solvent alternatives.
Consolidated procurement desks at European automotive OEMs are unbundling adhesive supply from full-service sealing system contracts. Buyers now source butyl tapes directly while outsourcing application engineering to equipment integrators. This disintermediation is most advanced in Bavaria and Lower Saxony, where Volkswagen and BMW procurement organizations have established separate adhesive category managers.
Butyl Adhesive Market Segmentation
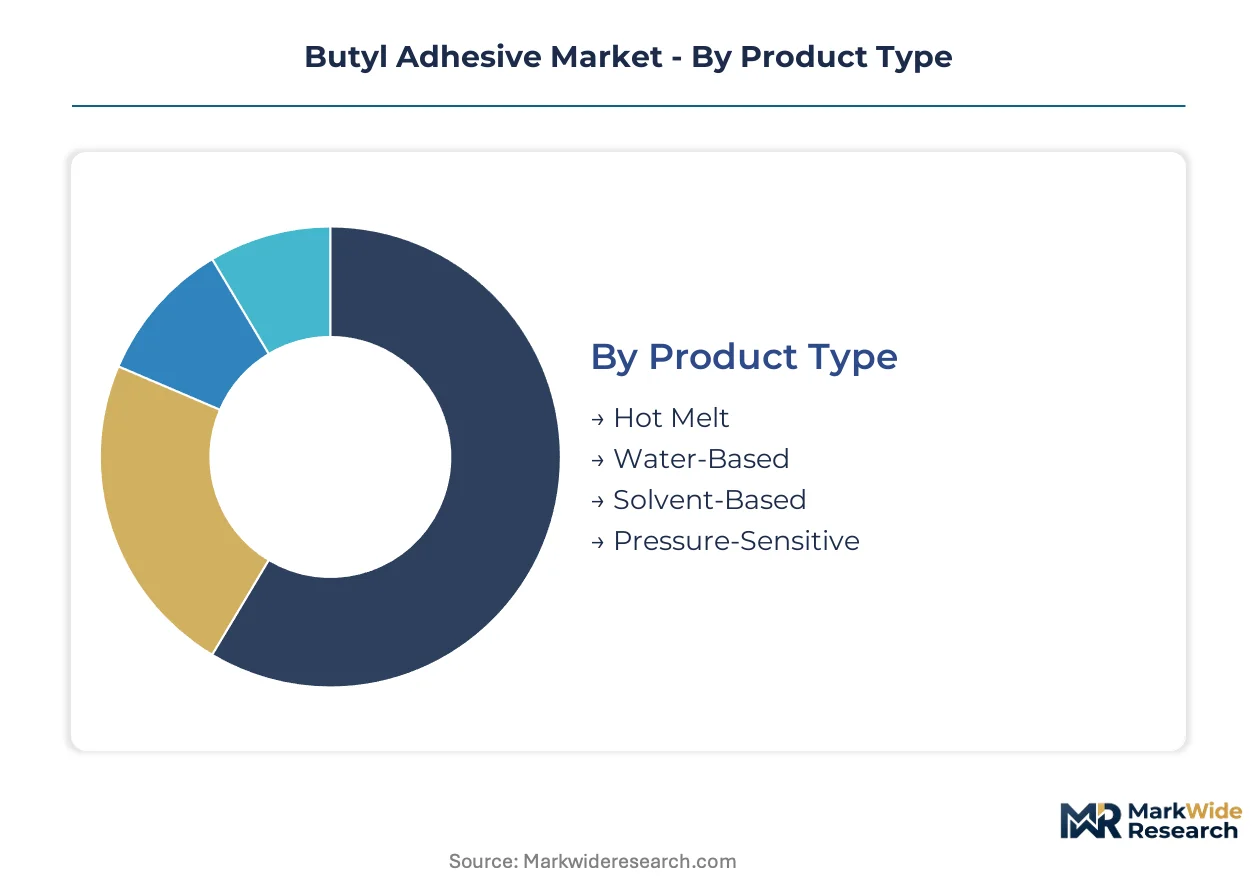
Butyl adhesive procurement patterns diverge sharply across formulation chemistry and physical form, with automotive OEMs prioritizing hot-melt automation compatibility while construction contractors weigh cure speed against jobsite VOC limits. Understanding these segment boundaries clarifies where formulation R&D investments concentrate versus where commoditization pressures dominate.
Product Type:
Cost tier stratification separates solvent-based legacy formulations from capital-intensive hot-melt systems and compliance-driven water-based alternatives.
- Hot Melt:These formulations eliminate solvent recovery infrastructure and integrate directly with robotic dispensing equipment in automotive final assembly. German OEMs in Stuttgart and Wolfsburg specify these grades for battery enclosure sealing where ninety-second takt times permit no ambient cure delays.
- Water-Based:Emulsion systems carry lower VOC burdens but require eight to twelve hour ambient cure cycles. Demand concentrates in European construction where REACH enforcement and contractor exposure limits override speed requirements.
- Solvent-Based:Legacy formulations still dominate architectural membrane specifications in markets with lagging regulatory enforcement.
- Pressure-Sensitive:Clean-room compatible tapes command premium positioning in electronics assembly and medical packaging where repositionability justifies material cost multiples.
Hot Melt holds installed capacity. Water-Based is rotating up the share rankings.
Application:
End-use maturity varies from electrification-driven automotive redesigns to formalizing construction markets in South Asia.
- Automotive:EV battery sealing mandates are compressing specification cycles as OEMs validate barrier tapes against thermal runaway protocols. Korean and German manufacturers now require high-temperature grades for lithium-ion cell isolation.
- Construction:Waterproofing membranes exploit butyl's gas impermeability for building envelope applications. China's state-funded transit and data center projects are pulling volume toward MEE-compliant membrane adhesives.
- Electronics:Precision assembly applications favor low-outgassing formulations with clean-room compatibility.
- Packaging:Medical and pharmaceutical blister sealing drives demand for grades meeting FDA biocompatibility thresholds.
Automotive commands specification intensity. Construction is climbing the fastest as infrastructure formalization spreads.
End User:
Customer type determines whether procurement flows through consolidated OEM desks or fragmented distributor networks.
- Manufacturers:Integrated automotive and electronics producers source directly through category managers, unbundling adhesive supply from full-service sealing contracts in Bavaria and Lower Saxony.
- DIY Consumers:Retail channels move standardized tape formats for home repair and weatherization.
- Contractors:Jobsite procurement favors pre-cut tape dimensions and compatible primer systems that minimize application training.
- Distributors:Regional stocking points buffer construction demand volatility and provide technical support for specification translation.
Manufacturers anchor volume concentration. Contractors are gaining procurement sophistication fastest.
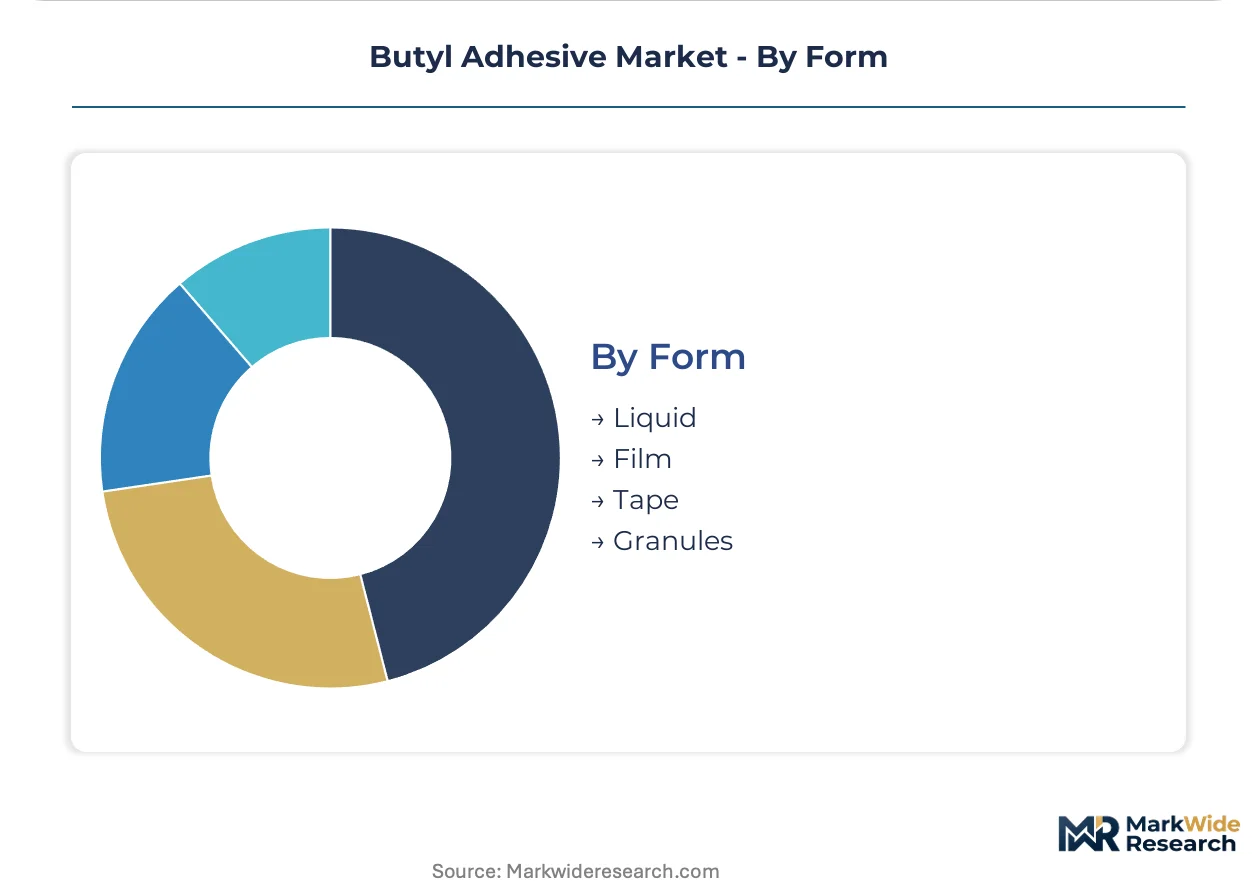
Form:
Physical configuration dictates equipment compatibility and labor skill requirements across installation environments.
- Tape:Calendered rolls dominate automotive body-in-white sealing and construction membrane overlaps where consistent thickness enables automated application.
- Liquid:Brush or spray-applied sealants serve complex geometries in aftermarket repair and custom fabrication.
- Film:Thin-gauge unsupported membranes integrate into multi-layer barrier systems for electronics and medical packaging.
- Granules:Solid feedstock forms supply hot-melt compounding operations and custom formulation houses.
Tape holds manufacturing scale. Film is expanding most quickly in precision barrier applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs in Stuttgart and Wolfsburg anchor premium-grade procurement, while construction contractors in Shanghai and Beijing drive volume for waterproofing membranes. Distributor networks in Mumbai and São Paulo intermediate fragmented demand from smaller fabricators and repair specialists.
United States
EPA's National Emission Standards for Hazardous Air Pollutants constrain solvent-based production at Gulf Coast manufacturing facilities. Formulators redirect capital toward hot-melt compounding lines with nitrogen-blanketed reactors. Detroit-area automotive plants specify high-temperature barrier tapes for EV battery enclosure sealing.
Germany
REACH SVHC restrictions phase legacy phthalate plasticizers from construction-grade formulations. ECHA's expanded candidate list advantages compliant polymer architectures. Bavarian OEM procurement desks unbundle adhesive supply from full-service sealing contracts, establishing separate category managers.
China
MEE enforcement of GB standards for building envelope waterproofing specifies butyl membrane adhesives in state-funded transit projects. Domestic production of butyl rubber feedstock concentrates in Shandong and Zhejiang petrochemical clusters. Yangtze River Delta manufacturing plants serve both automotive and construction demand.
India
BIS certification requirements for commercial building membranes create first-mover advantage for tape suppliers establishing local compounding partnerships. Infrastructure formalization accelerates specification adoption in Maharashtra and Gujarat. Mumbai-based distributors buffer demand volatility for regional contractors.
South Korea
Korean automotive OEMs now specify butyl-based barrier tapes for lithium-ion cell isolation in battery pack assembly. MFDS-aligned quality protocols govern medical-grade pressure-sensitive formulations. Busan-Ulsan industrial corridor hosts integrated adhesive compounding and tape calendering operations.
Butyl Adhesive Market Vendor Landscape
Channel-controlling players compete with product-specialist players across formulation chemistry tiers. Consolidated procurement desks at European automotive OEMs compress supplier margins while fragmenting construction demand through regional distributor networks. Three archetypes dominate: vertically integrated polymer modifiers, construction-focused membrane specialists, and automotive-grade tape manufacturers. Capacity expansion and reactive chemistry licensing represent the dominant competitive moves as formulators race to validate hybrid systems against truncated EV development cycles.
Among the named players, Henkel Corporation and H.B. Fuller Company occupy positions on the premium-automotive vector, while Sika exemplifies the construction-specialist archetype with waterproofing membrane integration. These three anchors represent distinct strategic postures: European R&D footprint specialization, backward integration into polymer modification, and portfolio extension from structural adhesives into barrier systems.
| Leading Market Players |
|---|
| Henkel Corporation |
| H.B. Fuller Company |
| Bostik |
| 3M |
| Sika |
| Nitto Denko Corporation |
| General Sealants |
| RENOLIT SE |
| L'ISOLANTE K-FLEX S.p.A. |
| Others |
Supply Flow & Price Mechanics
Isobutylene feedstock concentration across four Gulf Coast and Singapore petrochemical complexes exposes formulators to coordinated supply disruptions that compress pricing tier spreads between premium automotive-grade formulations and commodity construction alternatives while forcing capital allocation toward captive polymer modification capabilities.
Pricing Analysis
Cost-plus contracts indexed to polymer-grade isobutylene spot benchmarks dominate procurement between feedstock suppliers and tier-1 formulators. Three-tier pricing structure across premium, standard, and economy levels separates hot-melt automotive grades with nitrogen-blanketed reactor certification from water-based construction alternatives and legacy solvent-based architectural formulations. Cost compression in standard-tier construction sealants intensifies because MEE-compliant reformulation adds raw material burden without specification premium recovery. Automotive OEMs through consolidated procurement desks exhibit lowest price sensitivity; fragmented contractor channels in emerging markets show highest elasticity.
Supply Chain Analysis
Upstream polymer-grade isobutylene production anchors in United States Gulf Coast, Singapore, and Shandong Province petrochemical clusters. Formulation draws from isobutylene-isoprene copolymer feedstock, phthalate-free plasticizer alternatives, and tackifying resin modifiers. Single-source vulnerability concentrates in Singapore complex outages that would cascade through Asia-Pacific automotive supply chains. Distribution runs through regional compounding plants serving OEM direct procurement in Germany and South Korea, with distributor networks buffering construction demand volatility in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Application engineering services and specification support contracts expand faster than base material volumes as OEM procurement desks unbundle adhesive supply from full-service sealing systems, creating recurring-revenue layers with superior margin stability.
For Market Incumbents: Entrench position through backward integration into polymer modification capabilities that secure feedstock consistency across regional plants, while accelerating reactive hot-melt chemistry validation to disqualify formulators lacking expertise in hybrid polyurethane-butyl systems. Silicone substitution in medical packaging and platinum-cure certification gaps threaten butyl's implantable device position; prioritize FDA biocompatibility pathway investment to defend specification share. For New Entrants and Emerging Players: Mid-market commercial building membranes in Maharashtra and Gujarat represent the most penetrable entry point as BIS certification requirements formalize procurement standards ahead of domestic supply capacity. Agrivoltaic waterproofing installations across Spain and Italy offer specification-led beachhead with twenty-five-year service guarantees that lock out commodity alternatives. Partner with regional EPC contractors on jobsite primer system compatibility to bypass distributor channel control. For Investors and Strategic Acquirers: Regional tape calendering specialists with established MEE-compliant formulation capabilities in Yangtze River Delta manufacturing clusters offer platform assets for automotive qualification expansion. Long-term viability hinges on reactive chemistry licensing portfolios that compress supplier bases in EV battery sealing applications. Monitor ECHA SVHC candidate list expansion velocity as inflection indicator for reformulation capex cycles and stranded legacy asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Reactive Hot-Melt Capacity Expansion | Nitrogen-blanketed reactor investment qualifies formulators for Stuttgart and Wolfsburg OEM battery enclosure specifications. |
| Backward Integration into Polymer Modification | Captive isobutylene-isoprene copolymer production insulates margin pressure from Singapore feedstock concentration. |
| MEE-Compliant Formulation Relocation | GB standards alignment opens state-funded transit and data center project participation in China. |
| Application Engineering Service Layer | Unbundled specification support contracts capture recurring revenue as OEM procurement desks separate adhesive from sealing system sourcing. |
| Agrivoltaic Waterproofing Partnership | Dual-use solar installation specifications in Mediterranean markets establish twenty-five-year membrane adhesive lock-in. |
Methodological Framework
Operator-level perspectives from adhesive formulation chemists, automotive Tier 1 procurement managers, construction membrane contractors, and MEE regulatory compliance officers anchored the qualitative base. Primary interview findings triangulated against secondary validation from SEC 10-K filings of listed chemical producers, Cefic and ACC industry reports, customs trade data on isobutylene derivative flows, and EPA NESHAP enforcement records. Bottom-up volume modeling across formulation chemistry tiers and top-down macro anchoring ensured cross-verification.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling spanning hot-melt, water-based, solvent-based, and pressure-sensitive formulation chemistry; automotive, construction, electronics, and packaging end-use applications; and tape, liquid, film, and granule physical forms. CAGRs derived from elasticity-adjusted demand curves incorporating EV battery sealing mandate trajectories and infrastructure formalization indices. Feedstock cost pass-through assumptions and regulatory compliance cost burdens informed margin compression scenarios.
Macroeconomic conditions sit as an overlay; deviation in construction spending cycles, automotive production schedules, or petrochemical feedstock pricing would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement timing and specification adoption curves. Cross-checking against IHS Markit vehicle production databases and national construction permit registries is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
High Strength Laminated Adhesives Market
Adhesives & Sealants
Adhesive Equipment Market
Adhesives & Sealants
Europe Human Fibrin Glue Market
Adhesives & Sealants
Asia-Pacific Adhesives Market
Adhesives & Sealants
Mirror Adhesive Market
Adhesives & Sealants
China Adhesives Market
Adhesives & Sealants
Water-Borne Adhesives Market
Adhesives & Sealants
Water Based Adhesive Market
Adhesives & Sealants
Spain Sealants Market
Adhesives & Sealants
UV-Curable Adhesives Market
Adhesives & Sealants
Polysulfide Sealants Market
Adhesives & Sealants
South America Contact Adhesives Market
Adhesives & Sealants
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market
Adhesives & Sealants
Asia-Pacific Epoxy Adhesive Market
Adhesives & Sealants
North America Acrylic Adhesives Market
Adhesives & Sealants
Global Cyanoacrylate Adhesives Market