
 North America Polyurethane (PU) Adhesives Market | 2026-2036
North America Polyurethane (PU) Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Polyurethane (PU) Adhesives Market Analytics
Mexico's expanding automotive assembly capacity is reshaping regional supply chain geography for PU adhesive producers. 3M leverages its Minnesota-based R&D campus to sustain technology leadership in structural bonding applications for electric vehicle battery packs. H.B. Fuller anchors its position through backward integration into polymer resin production, securing feedstock cost stability across North American operations.
North America polyurethane adhesives comprise isocyanate-cured polymer systems formulated with polyol backbones, typically achieving shear strengths of 15-35 MPa and operating across temperature ranges from -40°C to 120°C depending on crosslink density. These adhesives bond dissimilar substrates in load-bearing applications where flexibility and chemical resistance outweigh the cure-time limitations of faster-setting alternatives. Water-based formulations are gaining share fastest as EPA VOC regulations tighten, though reactive hot-melt technology dominates in automotive assembly where green-strength development within seconds prevents line stoppages. Low-VOC product lines now command premium positioning in California and Northeast construction markets where state-level air quality standards exceed federal baselines.
EPA enforcement of National Ambient Air Quality Standards limits solvent-borne adhesive use in non-attainment zones, while OSHA Permissible Exposure Limits for isocyanates mandate engineering controls in manufacturing facilities. Health Canada aligns with US EPA thresholds under the Canada-United States Air Quality Agreement, creating cross-border regulatory consistency for formulations. Stakeholders must monitor state-level HAPS rulemaking in Texas and Louisiana, where petrochemical production clusters face escalating emission scrutiny that could redirect capital toward water-based capacity expansion.
Market Dynamics
Automotive lightweighting mandates across Michigan and Ohio assembly plants are forcing adhesive specification changes at a pace faster than formulation pipelines can accommodate. This pressure concentrates demand for solvent-free systems that bond multi-material substrates while meeting EPA emission thresholds.
Growth Catalysts
- Clean Air Act enforcement:EPA VOC emission limits in non-attainment zones compel manufacturers to abandon solvent-borne formulations for water-based alternatives, expanding addressable market for compliant suppliers.
- Electric vehicle battery pack assembly:Structural bonding requirements for thermal management modules in EV powertrains pull high-shear PU systems into new specification tiers.
- US Gulf Coast petrochemical corridor:Proximity to isocyanate feedstock production enables integrated adhesive manufacturing with captive raw material security.
Market Restraints
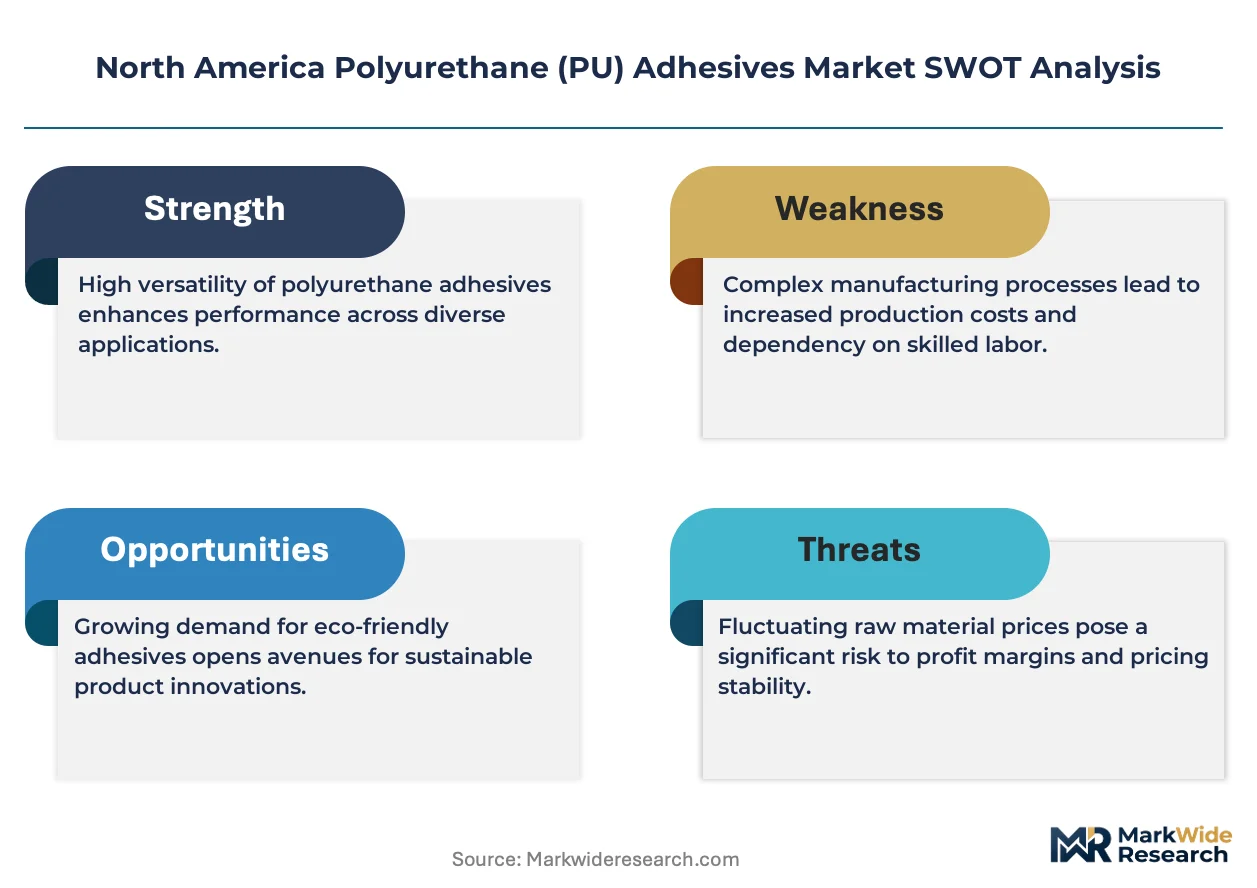
- Isocyanate price volatility:Feedstock costs tied to crude oil and natural gas benchmarks create margin compression that water-based R&D investments cannot offset immediately.
- Reactive hot-melt equipment lock-in:Automotive assembly lines in Detroit and Windsor carry sunk capital in dispensing systems that slow adoption of next-generation curable technologies.
- Cyanoacrylate and epoxy substitution:Faster-curing alternatives capture applications where flexibility requirements have loosened, particularly in consumer electronics assembly.
Strategic Opportunities
- Mexico automotive capacity expansion:New assembly plants in Guanajuato and Nuevo León create greenfield specification opportunities without legacy adhesive entrenchment.
- California Title 24 building standards:State-level low-VOC mandates for commercial construction create premium positioning for compliant formulations ahead of federal adoption.
- Reactive hot-melt and UV-cure convergence:Hybrid systems combining snap-cure speed with structural durability open specification windows in appliance and furniture manufacturing.
Industry Challenges
- Formulation chemist scarcity:Expertise in isocyanate-polyol stoichiometry and rheology control concentrates among aging specialists in Minnesota and New Jersey industrial corridors.
- OSHA isocyanate exposure compliance:Permissible Exposure Limits mandate engineering controls that add capital intensity to facility expansions in Texas and Louisiana.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Polyurethane (PU) Adhesives Market |
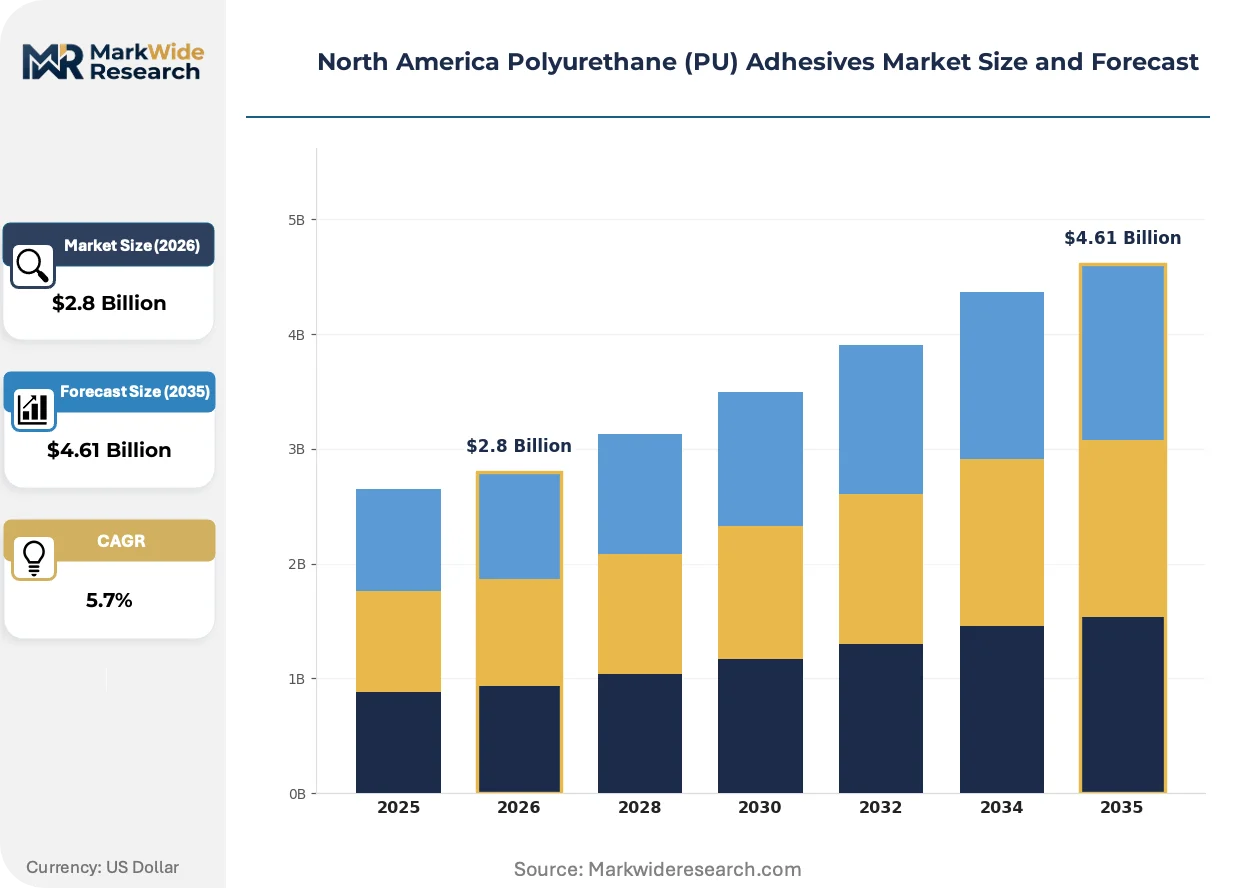
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible, Rigid, Low-VOC, Water-Based End User: Construction, Automotive, Furniture, Aerospace Application: Packaging, Footwear, Coatings, Bonding Technology: Reactive, Hot Melt, Pressure Sensitive, Thermoplastic |
| Companies Covered | 3M, H.B. Fuller, Henkel AG & Co. KGaA, Dow, Arkema Group, Sika AG, Huntsman International LLC, BASF, Avery Dennison, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Polyurethane (PU) Adhesives Market Evolving Landscape
Formulation chemistry is pivoting toward systems that eliminate cure-time penalties previously accepted as trade-offs for structural performance. This shift redefines competitive advantage around process compatibility rather than bond strength alone.
Bio-based polyol feedstocks derived from soy and castor oil are rendering obsolete the petroleum-origin assumption in premium adhesive positioning. Tier-1 automotive suppliers in Ontario and Michigan specify renewable content thresholds in RFQs. This requirement compresses cost premiums for bio-based systems while disqualifying conventional formulations from new platform bids.
EPA enforcement of National Ambient Air Quality Standards tightens solvent-borne adhesive eligibility in Texas and California non-attainment zones. Manufacturers respond by accelerating water-based capacity builds in Louisiana petrochemical corridors. Construction adhesive segments in the Northeast face parallel pressure from state-level HAPS rulemaking that exceeds federal baselines.
Direct specification relationships between adhesive formulators and automotive OEM engineering teams are displacing distributor-mediated procurement in EV battery bonding applications. Tier-2 suppliers in Ohio and Michigan now require technical service co-location with assembly plants. This pattern concentrates contract value among formulators with dedicated application engineering resources.
North America Polyurethane (PU) Adhesives Market Segmentation
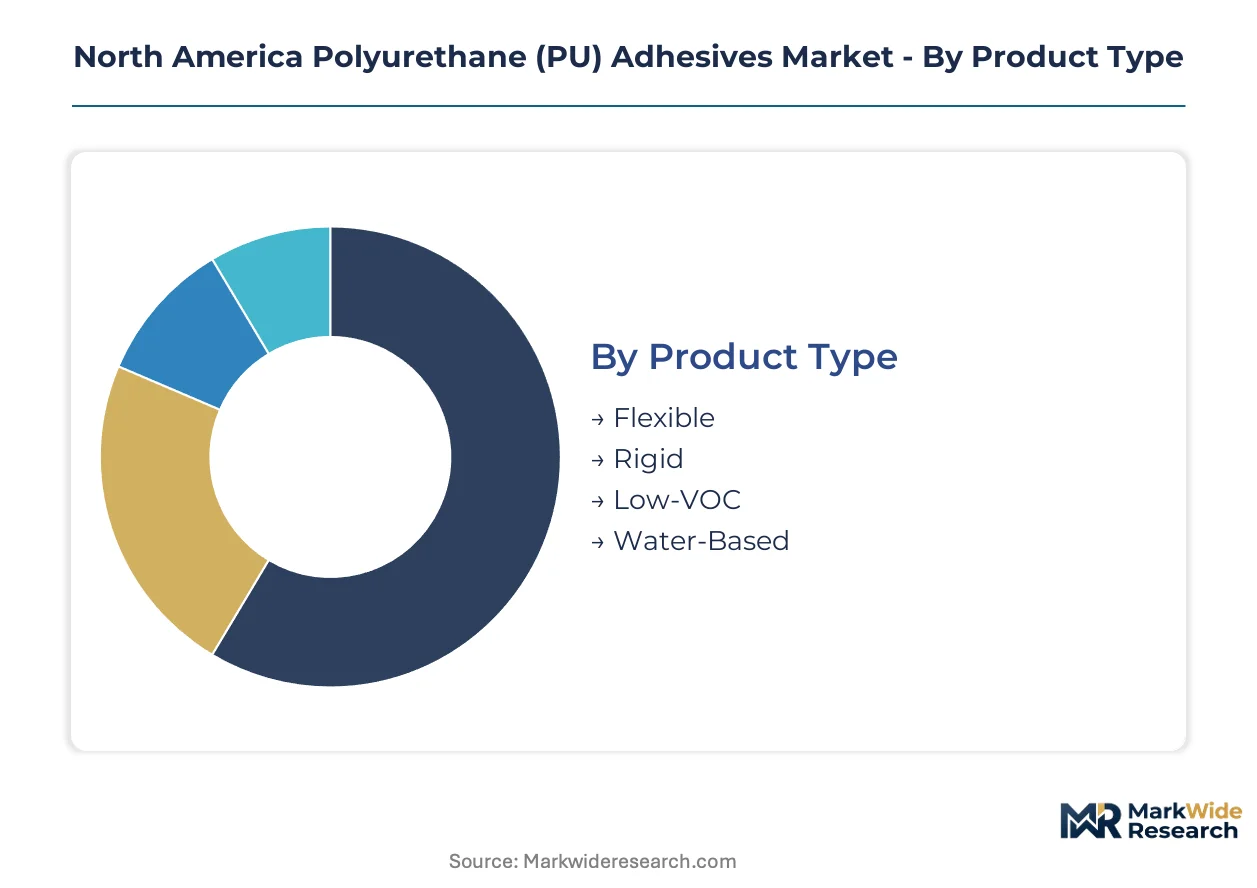
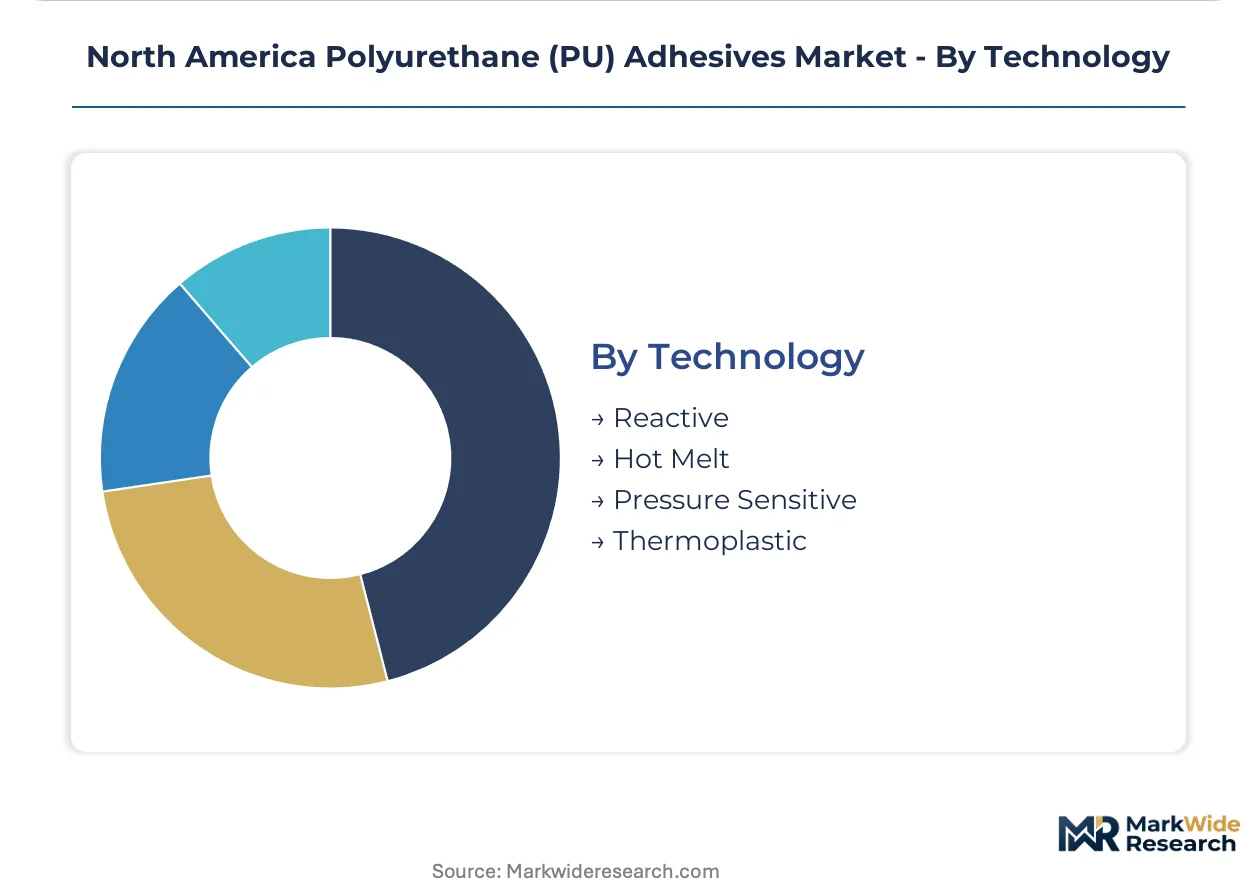
Polyurethane adhesive segmentation in North America reflects divergent maturity curves across formulation chemistry and end-use specifications. Product type and technology categories show the widest spread between established solvent-borne systems and emerging water-based alternatives, while end-user concentration in automotive and construction creates specification bottlenecks.
Product Type:
Mature rigid formulations coexist with emerging low-VOC systems as regulatory pressure reshapes the maturity spectrum.
- Flexible:Elastomeric formulations with Shore A hardness ratings of 40-70 dominate automotive interior assembly and furniture cushioning applications. Michigan and Ohio OEMs specify these systems for dashboard laminates and seat foam bonding where vibration damping exceeds structural load requirements.
- Low-VOC:Formulations meeting California SCAQMD Rule 1168 and EPA VOC limits concentrate demand in Northeast commercial construction and California residential retrofits. State-level air quality enforcement ahead of federal adoption creates premium positioning for compliant suppliers.
- Rigid:High-modulus systems with Shore D hardness above 70 serve structural composite bonding in wind turbine blade manufacturing and truck trailer assembly.
- Water-Based:Dispersion technology with 40-50% solids content penetrates packaging and woodworking segments where spray application compatibility matters.
Flexible formulations handle the majority of throughput; Low-VOC systems are gaining share fastest as regulatory deadlines approach.
End User:
Volume concentration in automotive and construction contrasts with margin concentration in aerospace specification tiers.
- Automotive:Structural bonding of aluminum-intensive body-in-white structures and EV battery pack thermal management modules pulls high-shear PU systems into new performance tiers. Detroit and Windsor assembly plants specify reactive hot-melt systems with green-strength development under 30 seconds.
- Construction:Commercial roofing membrane attachment and insulated panel lamination drive bulk consumption in the US Gulf Coast and California. Title 24 building standards in California and New York State low-VOC mandates exceed federal baselines, filtering specification eligibility.
- Furniture:Mattress and upholstered seating manufacturers in North Carolina and Mississippi specify water-based systems for foam-to-fabric bonding where flammability standards add formulation complexity.
- Aerospace:FAA-certified structural films for composite primary structures command 10-15x pricing multiples over industrial grades, with qualification timelines spanning 18-36 months.
Automotive absorbs the dominant share of high-performance formulations; Construction shows the steepest expansion trajectory in absolute volume terms.
Application:
Process compatibility requirements fragment the application landscape between speed-critical assembly and durability-critical bonding.
- Bonding:Multi-substrate structural assembly in transportation and industrial equipment represents the core value proposition for PU chemistry. Load-bearing applications with cyclic stress exposure favor PU flexibility over epoxy brittleness.
- Packaging:Flexible film lamination for food and medical packaging demands FDA 21 CFR 175.105 compliance, with water-based systems displacing solvent-borne in California and Northeast facilities.
- Footwear:Outsole attachment and upper construction in Mexican and Dominican Republic manufacturing supply US brands, with reactive systems dominating athletic footwear.
- Coatings:Protective and decorative finishes leverage PU toughness for abrasion resistance in flooring and industrial maintenance applications.
Bonding commands the premium specification tier; Packaging is expanding most quickly as water-based technology crosses performance thresholds.
Technology:
Reactive chemistry anchors high-value applications while thermoplastic systems serve cost-sensitive segments.
- Reactive:Two-component systems with pot lives of 2-10 minutes and full cure in 24 hours dominate structural applications where bond line durability spans 15-20 year service lives. Automotive OEMs in Michigan and Ohio specify these for crash-critical joints.
- Hot Melt:Moisture-curing reactive hot-melts combine snap-set speed with structural performance, locking in automotive assembly line specifications despite equipment capital intensity.
- Pressure Sensitive:Permanent and removable tackified formulations serve label and tape applications where repositionability or clean removal matters.
- Thermoplastic:Linear polymers without crosslinking enable heat-reversible bonding in textile and temporary assembly applications where rework capability outweighs ultimate strength.
Reactive technology captures the majority of value; Hot Melt systems are climbing the fastest on adoption curves in EV battery assembly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement of National Ambient Air Quality Standards anchors regional demand dynamics across the United States, Canada, and Mexico. Clean Air Act compliance deadlines are redrawing procurement patterns for adhesive formulators serving automotive and construction end-users.
United States
Automotive lightweighting mandates in Michigan and Ohio assembly plants are forcing specification changes toward solvent-free PU systems. EPA VOC emission limits in non-attainment zones compel manufacturers to abandon solvent-borne formulations for water-based alternatives. The US Gulf Coast petrochemical corridor concentrates integrated adhesive production near isocyanate feedstock sources in Texas and Louisiana.
Canada
Health Canada aligns with US EPA thresholds under the Canada-United States Air Quality Agreement, creating cross-border regulatory consistency for formulations. Ontario's Tier-1 automotive suppliers specify renewable content thresholds in RFQs for bio-based polyol systems. Windsor assembly plants mirror Detroit specifications for reactive hot-melt systems with green-strength development under 30 seconds.
Mexico
Expanding automotive assembly capacity in Guanajuato and Nuevo León creates greenfield specification opportunities without legacy adhesive entrenchment. Mexican manufacturing supply chains for US footwear brands drive reactive system demand in athletic footwear production. Direct specification relationships between formulators and OEM engineering teams are displacing distributor-mediated procurement in new plant constructions.
North America Polyurethane (PU) Adhesives Market Competitive Landscape
Vertically integrated multinational chemical conglomerates and specialized adhesive formulators split the market between feedstock security and application engineering depth. The vendor base concentrates around players with captive isocyanate access or dedicated automotive technical service capabilities. Three archetypes dominate: petrochemical-backed integrated producers, construction-specialist formulators with regional distribution density, and automotive-focused application engineers co-located with assembly plants. Competitive moves center on backward integration into polymer resin production and dedicated R&D campus investments near OEM engineering centers.
Among Minnesota-based technology leaders, 3M exemplifies the application-engineering archetype through structural bonding specialization for electric vehicle battery packs. H.B. Fuller anchors the integrated formulator position through captive polymer resin production securing feedstock cost stability. Henkel AG & Co. KGaA occupies a position bridging automotive specification depth with construction market presence across the regional footprint.
| Leading Market Players |
|---|
| 3M |
| H.B. Fuller |
| Henkel AG & Co. KGaA |
| Dow |
| Arkema Group |
| Sika AG |
| Huntsman International LLC |
| BASF |
| Avery Dennison |
| Others |
Value Network & Pricing Analysis
Isocyanate production clustering along the US Gulf Coast petrochemical corridor concentrates feedstock pricing power among integrated producers with captive MDI and TDI supply. This upstream concentration funnels margin capture toward backward-integrated formulators while forcing non-integrated competitors to absorb volatile aromatic feedstock costs passed through from Texas and Louisiana refiners.
Pricing Analysis
California and Northeast markets command 15-25% premiums over Gulf Coast pricing for low-VOC formulations meeting state-level air quality standards. Three-tier pricing structure across premium, standard, and economy levels separates SCAQMD-compliant systems from federal-baseline products and commodity solvent-borne grades. Pricing pressure stems from isocyanate feedstock volatility tied to natural gas benchmarks, with automotive OEM procurement teams in Michigan and Ohio extracting volume concessions on reactive hot-melt contracts. Construction distributors in California show highest price sensitivity due to project-based bidding, while aerospace specification tiers remain least sensitive given 18-36 month qualification barriers.
Supply Chain Analysis
Export-control scrutiny on advanced polymer catalyst technologies limits flow of certain organometallic curing systems from European suppliers to North American formulators. Supply concentrates in the United States, Germany, and Japan for high-purity isocyanate monomers and specialty polyol intermediates. Raw material dependencies center on crude oil-derived aromatics, natural gas-based propylene oxide, and bio-based soybean oil feedstocks for renewable polyol streams. Single-source vulnerability runs through specialized catalyst suppliers in the Rhine-Ruhr industrial basin. Distribution runs through direct specification relationships with automotive OEM engineering teams, bypassing traditional chemical distributor networks in EV battery bonding applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America polyurethane adhesives sit in early-cycle expansion as EPA enforcement timelines force solvent-borne displacement faster than incumbent capacity can pivot. Water-based and reactive hot-melt penetration in automotive and construction end-uses remains below saturation thresholds despite regulatory tailwinds.
For Market Incumbents: Insulate specification positions in EV battery thermal management modules through co-located application engineering in Michigan and Ohio assembly corridors. Deepen backward integration into polymer resin production to neutralize isocyanate feedstock volatility eroding margins on non-captive formulations. Secure long-term offtake agreements with Gulf Coast petrochemical producers before capacity expansion cycles tighten MDI availability. For New Entrants and Emerging Players: Establish a beachhead in Mexico's Guanajuato and Nuevo León automotive greenfield plants where legacy adhesive specifications have not yet entrenched. Target water-based construction adhesives in California Title 24 compliance tiers where state mandates exceed federal baselines and create premium positioning windows. Lead with technical service co-location models that mirror 3M's OEM engineering partnership structure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive adhesive specialists in Ontario and Michigan lacking captive feedstock security. Five-to-ten year viability hinges on water-based formulation patent estates and EPA compliance certification timelines. Watch for isocyanate price spikes forcing distressed consolidation among non-integrated formulators as the signal for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Production | H.B. Fuller's captive supply strategy neutralizes feedstock volatility eroding competitor margins across North American operations. |
| Water-Based Capacity Expansion | Louisiana petrochemical corridor builds position formulators ahead of EPA non-attainment zone enforcement deadlines in Texas and California. |
| Technical Service Co-Location | 3M's Minnesota R&D campus sustains direct OEM specification relationships displacing distributor-mediated procurement in EV battery bonding. |
| Bio-Based Polyol Certification | Renewable content thresholds in Ontario and Michigan Tier-1 RFQs disqualify conventional petroleum-origin formulations from new platform bids. |
| Reactive Hot-Melt Equipment Partnerships | Henkel's dispensing system alliances lock in automotive assembly line specifications despite sunk capital slowing technology transitions. |
Research Methodology
A standing panel of adhesive formulator R&D directors, automotive OEM procurement managers, construction distributor category buyers, and EPA regulatory compliance officers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with plant managers at Gulf Coast petrochemical facilities and technical directors at Minnesota and New Jersey industrial corridor formulators. Secondary validation drew from EPA enforcement action databases, ACC chemical trade flow reports, SEC 10-K disclosures from listed adhesive producers, and Health Canada PMRA registration filings. Bottom-up volume modeling triangulated against top-down petrochemical consumption benchmarks.
Scenario-bracketing anchored the analytical framework around regulatory enforcement intensity and automotive lightweighting adoption curves across the projection horizon. Segmentation dimensions modeled include formulation chemistry tier, end-use industry concentration, technology type, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating isocyanate price volatility and OEM specification cycle timing. Industry-specific inputs encompassed EV battery pack thermal management module attachment rates and California Title 24 building standard adoption trajectories.
Sensitivities concentrate around EPA enforcement acceleration in Texas and Louisiana non-attainment zones and isocyanate feedstock disruption from Gulf Coast weather events. Forecasts reflect assumptions on regulatory timeline adherence and automotive platform standardization patterns. Material shifts in Clean Air Act implementation schedules or MDI supply consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Aqueous Acrylic Binders Market
Adhesives & Sealants
Corrosion Protection Tapes Market
Adhesives & Sealants
Europe Epoxy Adhesive Market
Adhesives & Sealants
Timber Laminating Adhesives Market
Adhesives & Sealants
Russia Adhesives Market
Adhesives & Sealants
Germany Sealants Market
Adhesives & Sealants
Light Curing Adhesives Market
Adhesives & Sealants
Asia-Pacific Waterproofing Products Market
Adhesives & Sealants
Hybrid Silane-Terminated Polymer Adhesives for EV Battery Pack Assembly Market
Adhesives & Sealants
Floor Tile Adhesive Market
Adhesives & Sealants
Electric Vehicle Adhesives and Sealants Market
Adhesives & Sealants
Middle East & Africa Construction Adhesives & Sealants Market
Adhesives & Sealants
Asia-Pacific Waterborne Adhesives Market
Adhesives & Sealants
United States Adhesives Market
Adhesives & Sealants
Global Underfill Material Market
Adhesives & Sealants
2K Epoxy Adhesives Market