
 Europe EVA Adhesives Market | 2026-2036
Europe EVA Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe EVA Adhesives Market Foresight
Buyer concentration among European packaging converters is hardening as multinational food brands consolidate supplier panels. Henkel AG & Co. KGaA leverages its hot-melt technology leadership to anchor long-term contracts with these scaled buyers. Dow competes through backward integration into ethylene-vinyl acetate resin production, securing feedstock cost advantages. Sika AG specializes in construction-grade EVA adhesives, dominating renovation and flooring installation channels across the continent.
Ethylene-vinyl acetate adhesives are thermoplastic polymer systems formulated with 18-40% vinyl acetate content, polymerized through high-pressure bulk processes to achieve melt indices between 2-500 g/10min for precise open-time control in automated bonding lines. Hot melt formulations command the largest volume share due to their instant green strength and compatibility with high-speed packaging lines, while water-based systems are capturing share in food-contact applications where regulatory scrutiny of residual monomers intensifies. Reactive EVA adhesives occupy the premium tier, serving automotive interior lamination where heat and plasticizer resistance justify elevated pricing.
REACH registration requirements and the EU Green Deal's decarbonization mandates are forcing reformulation of solvent-based grades, redirecting R&D investment toward bio-based vinyl acetate feedstocks. ECHA's restrictions on persistent organic pollutants further constrain legacy additive packages, elevating compliance costs for smaller compounders. Stakeholders must monitor the EU Packaging and Packaging Waste Regulation's recycled content targets, as these will determine whether adhesive recyclability becomes a specification gate for supplier qualification.
Market Dynamics
REACH compliance deadlines and the EU Green Deal's VOC reduction mandates are forcing wholesale reformulation of solvent-based EVA grades, concentrating R&D investment among compounders with captive resin capabilities.
Growth Catalysts
- Flexible food packaging expansion:German and French packaging converters are commissioning bonded-laminate capacity to serve multinational food brands consolidating supplier panels.
- Automotive interior lamination demand:Germany's automotive corridor is specifying reactive EVA adhesives for heat-resistant dashboard and trim bonding as cabin quality specifications tighten.
- EU Green Deal decarbonization:The framework's industrial emissions targets are redirecting public and private capital toward bio-based vinyl acetate feedstock development.
Market Restraints
- Ethylene feedstock volatility:Naphtha-cracker economics in the ARA hub expose compounders to margin compression when oil prices spike.
- ECHA additive restrictions:Persistent organic pollutant limitations are disqualifying legacy stabilizer packages, forcing expensive reformulation for smaller producers without dedicated compliance teams.
- Polyurethane substitution in construction:Sika AG and construction specialists face pressure from moisture-cure PUR systems in flooring installation where open-time flexibility is valued over instant green strength.
Strategic Opportunities
- Northern Italy furniture belt:Panel lamination demand from Milan-Turin manufacturers remains underpenetrated by EVA hot-melt specialists relative to PUR dominance.
- EU Packaging and Packaging Waste Regulation:Recycled content mandates will create specification gates favoring adhesives with demonstrated recyclability and compatibility with mechanical recycling streams.
- Water-based EVA convergence with digital printing:Food-contact compliant aqueous systems paired with inkjet-decorated flexible packaging lines offer a path to solvent-free converter operations.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise in vinyl acetate copolymer architecture is concentrating at major resin producers, constraining independent compounder innovation capacity.
- Multi-standard certification timelines:Simultaneous EU 10/2011 food-contact, German BfR, and French DGCCRF approvals extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe EVA Adhesives Market |
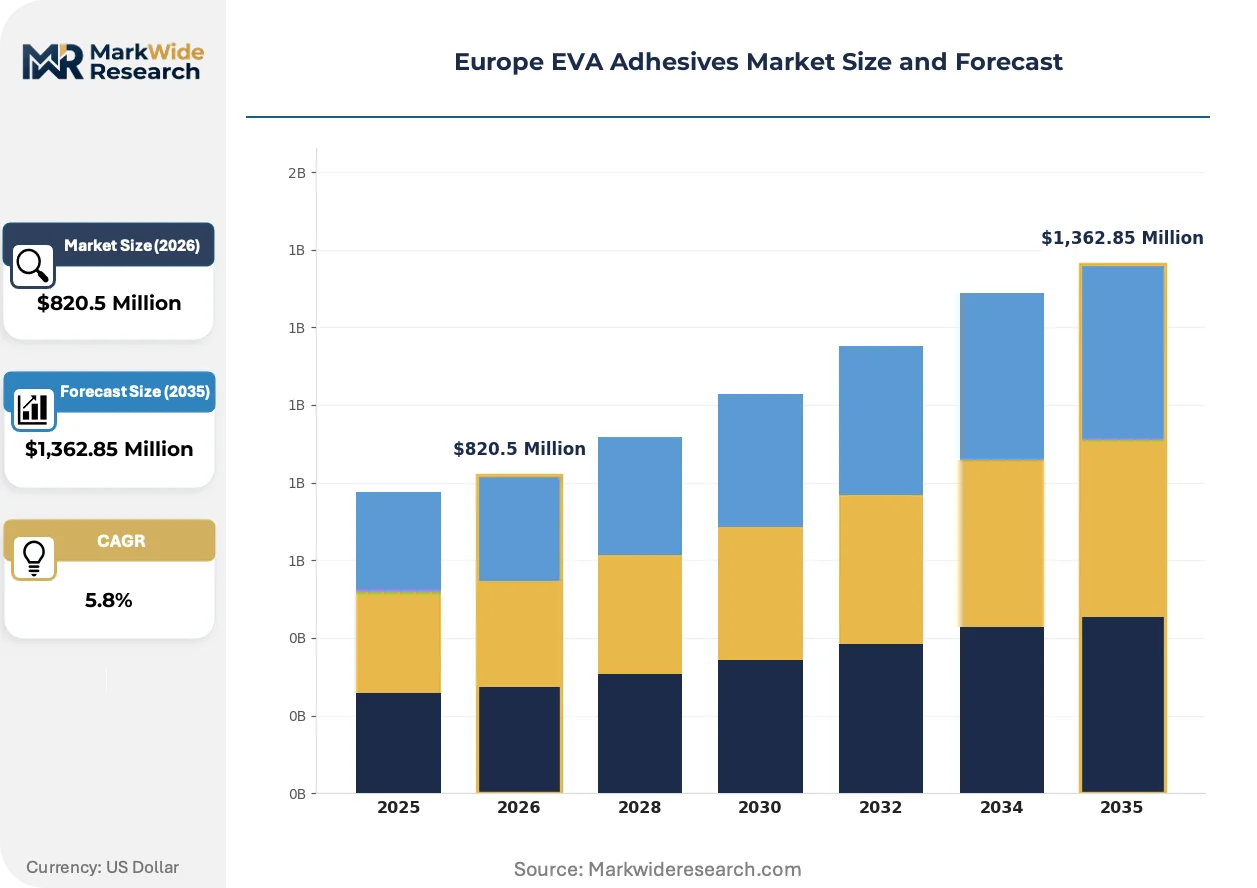
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,362.85 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Melt, Water-Based, Solvent-Based, Reactive End Use Industry: Automotive, Packaging, Construction, Footwear Application: Bonding, Lamination, Coating, Assembly Form: Granules, Emulsions, Films, Blocks |
| Companies Covered | Arkema Group, Beardow Adams, Dow, Henkel AG & Co. KGaA, Jowat SE, H.B. Fuller Company, Sika AG, 3M Company, Wacker Chemie AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe EVA Adhesives Market Shifts & Advancements
Reformulation chemistry and adhesive recyclability are converging as the primary axes of competitive differentiation, with regulatory pressure compressing development timelines and favoring integrated resin-to-formulation players.
Bio-based vinyl acetate feedstocks derived from biomass gasification and ethanol dehydration are absorbing capital allocation from European chemical majors. Automotive interior laminators in Stuttgart and Wolfsburg are piloting these grades for dashboard bonding where odor and emission specifications are most stringent. The technology is absorbing share from petroleum-derived equivalents in premium vehicle platforms where sustainability credentials command supplier qualification priority.
REACH registration renewal deadlines for 2024-2027 are accelerating substitution of boron-based crosslinkers in reactive EVA formulations. Compounders serving construction and automotive channels are reformulating with organometallic catalysts to maintain shelf stability and heat resistance profiles. Northern European markets are responding fastest, with German flooring installers already specifying next-generation grades for heated-substrate applications.
Specification-driven procurement is consolidating converter relationships around adhesive suppliers with integrated testing and certification support. French and Italian flexible packaging buyers are unbundling technical service from material supply, contracting separate formulation development from toll manufacturers while sourcing base polymers directly. This pattern is most visible in the Benelux corridor, where co-manufacturing networks allow mid-size converters to access custom EVA grades without captive R&D infrastructure.
Europe EVA Adhesives Market Segmentation
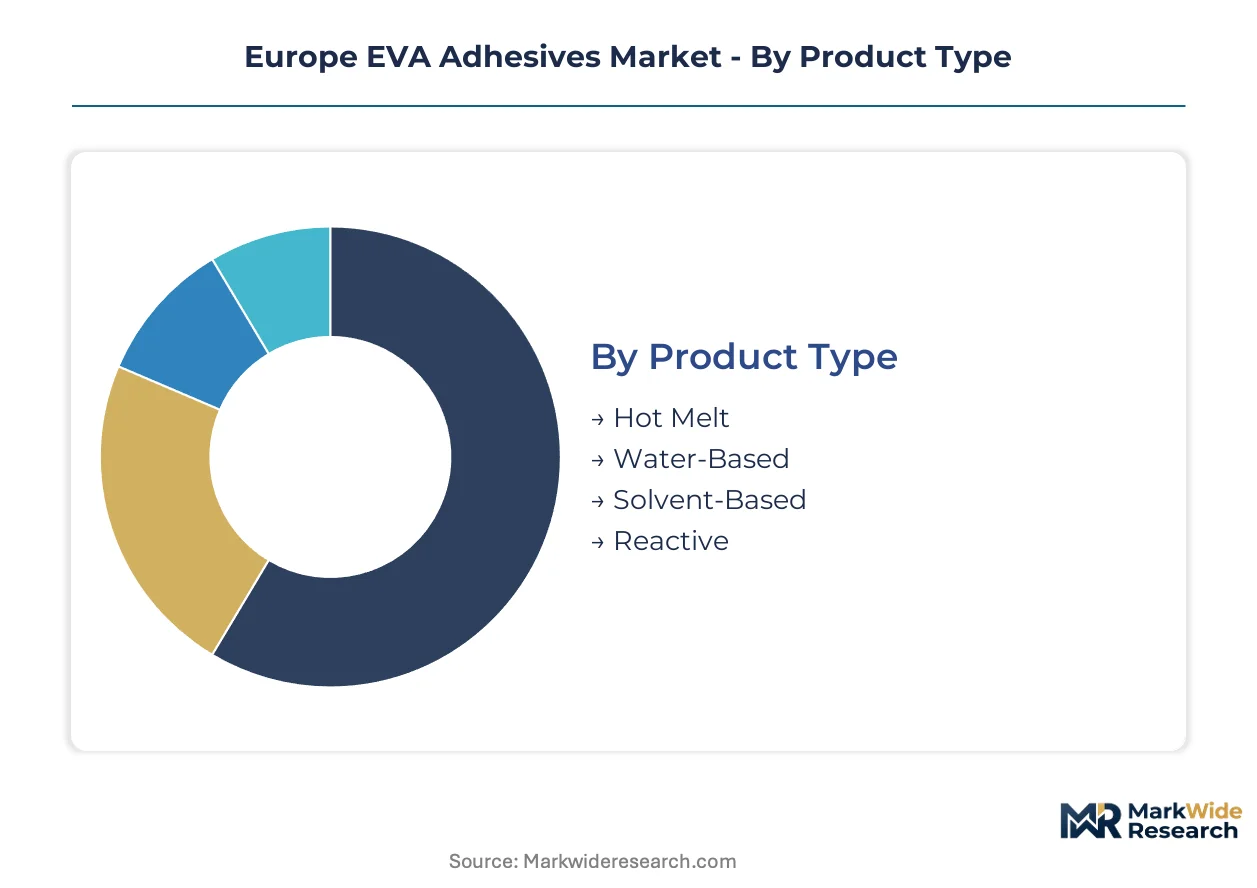
Europe's EVA adhesives market fragments along formulation chemistry and physical delivery formats, with regulatory pressure on VOC emissions and food-contact safety reshaping specification priorities across converter operations. Buyers segment procurement by open-time requirements, substrate compatibility, and compliance certification burdens rather than commodity polymer sourcing alone.
Product Type:
Formulation chemistry determines processing infrastructure investment and regulatory exposure for compounders serving European manufacturing clusters.
- Hot Melt:Thermoplastic formulations with 18-40% vinyl acetate content deliver instant green strength for high-speed packaging lines in Germany's Ruhr industrial belt. REACH-compliant stabilizer packages are displacing legacy boron-based crosslinkers as ECHA renewal deadlines approach.
- Water-Based:Aqueous emulsion systems capture specification share in French and Italian food-contact flexible packaging where residual monomer scrutiny under EU 10/2011 intensifies. Converter investment in drying infrastructure limits penetration to scaled operations with captive lamination capacity.
- Solvent-Based:Solution formulations face structural decline as EU Green Deal VOC thresholds tighten and ethyl acetate recovery costs escalate.
- Reactive:Crosslinked systems command premium positioning for automotive interior lamination in Stuttgart and Wolfsburg where dashboard heat resistance specifications justify elevated pricing.
Hot melt leads on scale across European converter procurement; water-based leads on momentum as food-contact compliance hardens.
End Use Industry:
Demand concentration tracks manufacturing geography and specification stringency across the continent's industrial corridors.
- Automotive:Germany's automotive corridor specifies reactive and high-performance hot-melt grades for cabin trim bonding where odor and emission protocols from OEMs exceed regulatory baselines. Stuttgart-based laminators pilot bio-based vinyl acetate feedstocks for premium platform qualification.
- Packaging:German and French flexible food packaging converters commission bonded-laminate capacity to serve multinational brand supplier consolidation, concentrating procurement among compounders with integrated EFSA compliance documentation.
- Construction:Flooring installation demand concentrates in Northern Europe where heated-substrate applications favor reformulated grades with organometallic catalysts replacing restricted additives.
- Footwear:Assembly operations in Portugal and Romania source hot-melt granules for sole bonding where open-time flexibility balances production line speed with bond durability requirements.
Packaging anchors volume procurement; automotive commands margin premiums.
Application:
Functional use case determines adhesive specification hierarchy and converter technical service requirements.
- Bonding:General assembly applications in furniture manufacturing across Northern Italy's Milan-Turin belt favor hot-melt granules for panel edgebanding where instant handling strength accelerates throughput.
- Lamination:Multi-layer substrate bonding for flexible packaging demands precise open-time control and food-contact certification under German BfR and French DGCCRF parallel approval pathways.
- Coating:Surface treatment applications in technical textiles and protective films require emulsion stability and film-forming consistency.
- Assembly:Component joining in automotive and electronics manufacturing specifies reactive grades where load-bearing and thermal cycling resistance justify formulation complexity.
Lamination concentrates R&D investment; bonding maintains broadest geographic penetration.
Form:
Physical delivery format aligns with converter processing equipment and supply chain integration depth.
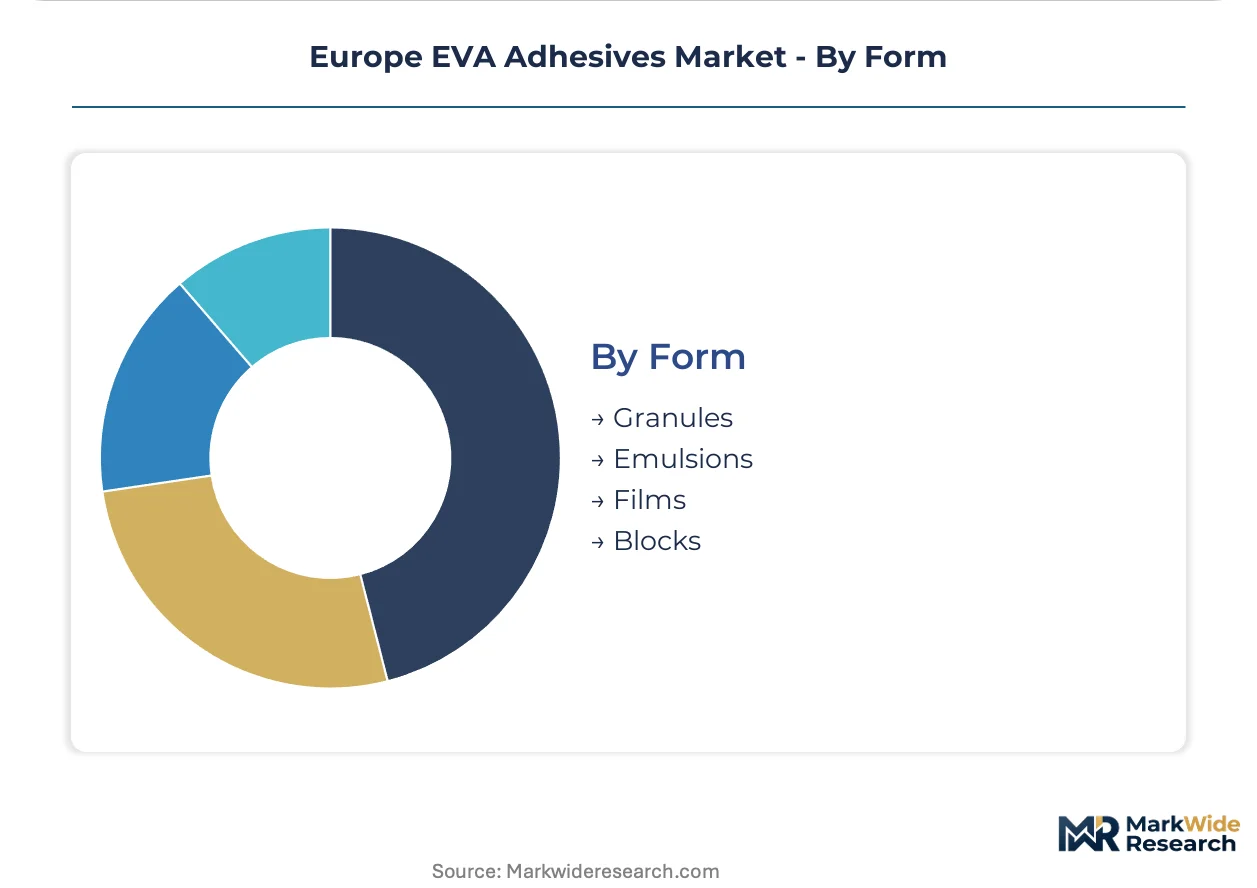
- Granules:Solid pellet supply dominates hot-melt consumption across high-speed packaging and woodworking lines where bulk pneumatic conveying and automated hopper feeding minimize labor content.
- Emulsions:Liquid aqueous systems serve coating and some lamination applications where dilution control and pump transfer compatibility reduce solvent handling infrastructure.
- Films:Pre-formed adhesive sheets target specialized electronics and automotive applications requiring precise thickness control and clean-room processing compatibility.
- Blocks:Solid mass formats persist in smaller-scale footwear and handicraft operations where manual melting and brush application predominate over automated systems.
Granules lead on procurement scale; emulsions gain share fastest as water-based formulation investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the highest EVA adhesive consumption intensity across Europe, while France pursues parallel growth through packaging converter consolidation rather than automotive dominance.
Germany
Stuttgart and Wolfsburg automotive clusters specify reactive EVA grades for dashboard lamination where OEM odor protocols exceed REACH baselines. The EU Green Deal's industrial emissions targets accelerate bio-based vinyl acetate pilot programs among compounders serving premium vehicle platforms. Bavarian resin producers anchor captive supply chains for hot-melt formulations across the Ruhr packaging belt.
France
Flexible food packaging converters in the Île-de-France region commission bonded-laminate capacity to serve multinational brand supplier panel consolidation. DGCCRF parallel approval pathways with German BfR extend certification timelines for water-based emulsion systems. Lyon-based toll manufacturers enable mid-size converters to access custom grades without captive R&D infrastructure.
Italy
The Milan-Turin furniture manufacturing belt favors polyurethane systems for panel lamination, leaving underpenetrated opportunity for EVA hot-melt specialists in edgebanding applications. ECHA restrictions on boron-based crosslinkers force reformulation of construction-grade adhesives used in Northern Italian flooring installation. Emilia-Romagna packaging converters invest in aqueous system drying infrastructure to capture food-contact specification share.
Netherlands
Rotterdam-ARA naphtha-cracker economics expose compounders to ethylene feedstock volatility that compresses margins during oil price spikes. The country's central logistics position supports distribution of granule and emulsion formats across Benelux converter networks. Amsterdam-based co-manufacturing networks allow specification-driven procurement unbundling of technical service from base polymer supply.
United Kingdom
Post-Brexit regulatory divergence from EU 10/2011 food-contact standards creates parallel certification burdens for adhesive suppliers serving UK flexible packaging converters. Midlands-based automotive component laminators adopt reactive grades for electric vehicle interior bonding where thermal cycling resistance specifications intensify. London-headquartered multinational food brands drive supplier panel consolidation that concentrates procurement among compounders with integrated EFSA documentation capabilities.
Europe EVA Adhesives Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry boundaries, creating a tiered structure where captive resin capabilities determine pricing power. Three archetypes dominate: integrated chemical majors with backward control over ethylene-vinyl acetate polymerization, independent compounders reliant on merchant resin supply, and construction-specialized adhesive formulators with channel-locked distribution. Competitive moves concentrate on M&A to secure formulation expertise and capacity expansion in high-speed packaging corridors.
Among integrated chemical majors, Dow and Arkema Group exemplify archetypes built on captive resin production. Henkel AG & Co. KGaA occupies a position representing diversified adhesive conglomerates with technology leadership in hot-melt systems. Sika AG anchors the construction-specialized tier with channel dominance in flooring and renovation applications across Northern Europe.
| Leading Market Players |
|---|
| Arkema Group |
| Beardow Adams |
| Dow |
| Henkel AG & Co. KGaA |
| Jowat SE |
| H.B. Fuller Company |
| Sika AG |
| 3M Company |
| Wacker Chemie AG |
| Others |
Supply & Pricing Matrix
Polymer chemist scarcity in the Rhine-Ruhr corridor widens pricing-tier spreads between integrated resin producers and formulation-dependent compounders, as labor-cost differentials compound feedstock advantages for backward-integrated majors.
Pricing Analysis
Capacity additions in Germany's Ruhr packaging belt are reshaping price floors for hot-melt granules, compressing margins for merchant-resin compounders. Three-tier pricing structure across premium reactive grades, standard hot-melt formulations, and economy solvent-based tiers tracks certification burden and captive resin access. Pricing pressure stems from REACH compliance cost inflation disqualifying smaller producers. Volume-scale buyers in French flexible packaging exhibit highest price sensitivity; automotive OEMs in Stuttgart accept premium positioning for emission-compliant grades.
Supply Chain Analysis
Single-source vulnerability sits with ARA hub naphtha crackers supplying ethylene feedstock to Northwestern European compounders. Manufacturing concentrates in Germany, France, and the Netherlands, with resin polymerization anchored in Bavaria and the Rotterdam corridor. Feedstock draws from petroleum-derived naphtha and pilot-scale bio-based ethanol dehydration routes. Tariff exposure on imported vinyl acetate monomer elevates cost unpredictability. Distribution runs through co-manufacturing networks in Benelux and direct mill-to-converter relationships in Germany's automotive corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA's persistent organic pollutant restrictions and REACH renewal deadlines are accelerating demand for reformulated, compliance-documented grades.
For Market Incumbents: Anchor long-term contracts with multinational food brands consolidating supplier panels by investing in integrated EFSA and BfR certification documentation. Deepen backward integration into bio-based vinyl acetate feedstocks to defend margin position against ethylene cost volatility. Prioritize organometallic catalyst R&D to preempt ECHA additive restrictions disqualifying legacy crosslinker packages. For New Entrants and Emerging Players: The 40-60% price-point gap between premium reactive automotive grades and economy solvent-based construction tiers opens white-space opportunity in Northern Italy's underpenetrated furniture edgebanding segment. Target water-based emulsion supply to Emilia-Romagna packaging converters investing in drying infrastructure. Pursue toll-manufacturing partnerships with Lyon-based technical service providers to bypass captive R&D requirements. For Investors and Strategic Acquirers: Construction-specialized adhesive formulators with channel-locked Northern European flooring distribution are the most active acquirer category in this space. Five-to-ten year viability favors compounders with demonstrated recyclability credentials ahead of EU Packaging and Packaging Waste Regulation recycled content mandates. Monitor bio-based vinyl acetate pilot program scale-up at Stuttgart automotive laminators as inflection signal for feedstock transition economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | Captive supply of biomass-derived vinyl acetate secures OEM qualification for premium automotive platforms ahead of EU Green Deal targets. |
| REACH-compliant Stabilizer Reformulation | Organometallic catalyst substitution maintains shelf stability while preempting ECHA restrictions on boron-based crosslinkers. |
| Co-manufacturing Network Expansion | Benelux toll partnerships enable mid-size French and Italian converters to access custom grades without captive R&D infrastructure. |
| Integrated Certification Documentation | Parallel BfR and DGCCRF approval capabilities shorten product launch cycles for water-based food-contact formulations. |
| Recyclability Compatibility Investment | Adhesive grades demonstrating mechanical recycling stream compatibility position suppliers for EU Packaging and Packaging Waste Regulation specification gates. |
Research Methodology
Direct dialogue with polymer chemists at major resin producers, procurement leads at German and French packaging converters, technical R&D directors at automotive laminators, and flooring installation contractors across Northern Europe grounded qualitative assessment. Secondary validation drew from ECHA restriction documentation, EU Packaging and Packaging Waste Regulation drafts, Cefic chemical industry reports, and customs trade data on ethylene-vinyl acetate resin flows. Bottom-up volume modeling triangulated against top-down macroeconomic indicators.
Segmented projections across formulation chemistry, physical delivery format, end-use industry, and regional manufacturing cluster generated volume and value outputs over the analysis window. CAGRs derived from regression analysis against automotive production forecasts, packaging converter capacity expansion announcements, and furniture manufacturing output indices. Modeled inputs included REACH compliance cost inflation curves and bio-based feedstock pilot program commercialization timelines.
Caveats apply where ECHA additive restriction enforcement intensity, ethylene feedstock price spikes, or polyurethane substitution rates in construction could materially shift the outlook. Forecasts embed assumptions on regulatory timeline adherence and OEM sustainability qualification pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Glue Pen Market
Adhesives & Sealants
Global Spray Adhesive Market
Adhesives & Sealants
2-Octyl Cyanoacrylate Adhesives Market
Adhesives & Sealants
Textile Binders Market
Adhesives & Sealants
Middle-East and Africa Cyanoacrylate Adhesives Market
Adhesives & Sealants
Acrylic Flooring Adhesives Market
Adhesives & Sealants
Amine Curing Agents Market
Adhesives & Sealants
Construction Repair and Rehabilitation Chemicals Market
Adhesives & Sealants
Skin Adhesives Market
Adhesives & Sealants
Global Vascular Sealant Market
Adhesives & Sealants
Adhesives and Sealants Distribution Market
Adhesives & Sealants
Italy Adhesives Market
Adhesives & Sealants
Middle East and Africa Bone Glue Market
Adhesives & Sealants
United States Adhesives Market
Adhesives & Sealants
Middle East & Africa Automotive Adhesives & Sealants Market
Adhesives & Sealants
Asia-Pacific Automotive Adhesives and Sealants Market